
 Acne Vulgaris Market | 2026-2036
Acne Vulgaris Market Size, Share, and Industry Trends Forecast 2026-2036
Acne Vulgaris Market Analysis
Multi-source API procurement is expanding across the acne vulgaris supply chain as manufacturers diversify away from single-source dependencies on Chinese and Indian raw material suppliers. Galderma leverages its vertically integrated manufacturing footprint to sustain cost advantages in topical retinoid production. Sun Pharmaceutical anchors its position through backward integration into active pharmaceutical ingredient synthesis. Johnson & Johnson competes on brand equity and pharmacy shelf presence across over-the-counter benzoyl peroxide segments.
Acne vulgaris denotes a chronic inflammatory dermatological condition of the pilosebaceous unit characterized by comedones, papules, pustules, and nodules, with severity graded by lesion count and inflammatory burden. Topical treatments dominate prescription volumes, though oral medications capture higher per-patient value in moderate-to-severe cases. Light therapy segments are gaining traction in dermatology clinics seeking non-pharmacological alternatives for antibiotic-resistant populations. Home care channels are expanding fastest among delivery modes, driven by direct-to-consumer subscription models and telemedicine prescribing.
FDA oversight of topical retinoid teratogenicity labeling and EPA manufacturing discharge standards shape formulation and production site decisions for US-market suppliers. The EMA's Pharmacovigilance Risk Assessment Committee periodically reviews systemic isotretinoin risk management protocols, influencing prescriber behavior across European markets. Stakeholders must monitor evolving antibiotic stewardship guidelines from WHO and national regulators, as these will progressively restrict oral tetracycline and macrolide use in acne protocols.
Market Dynamics
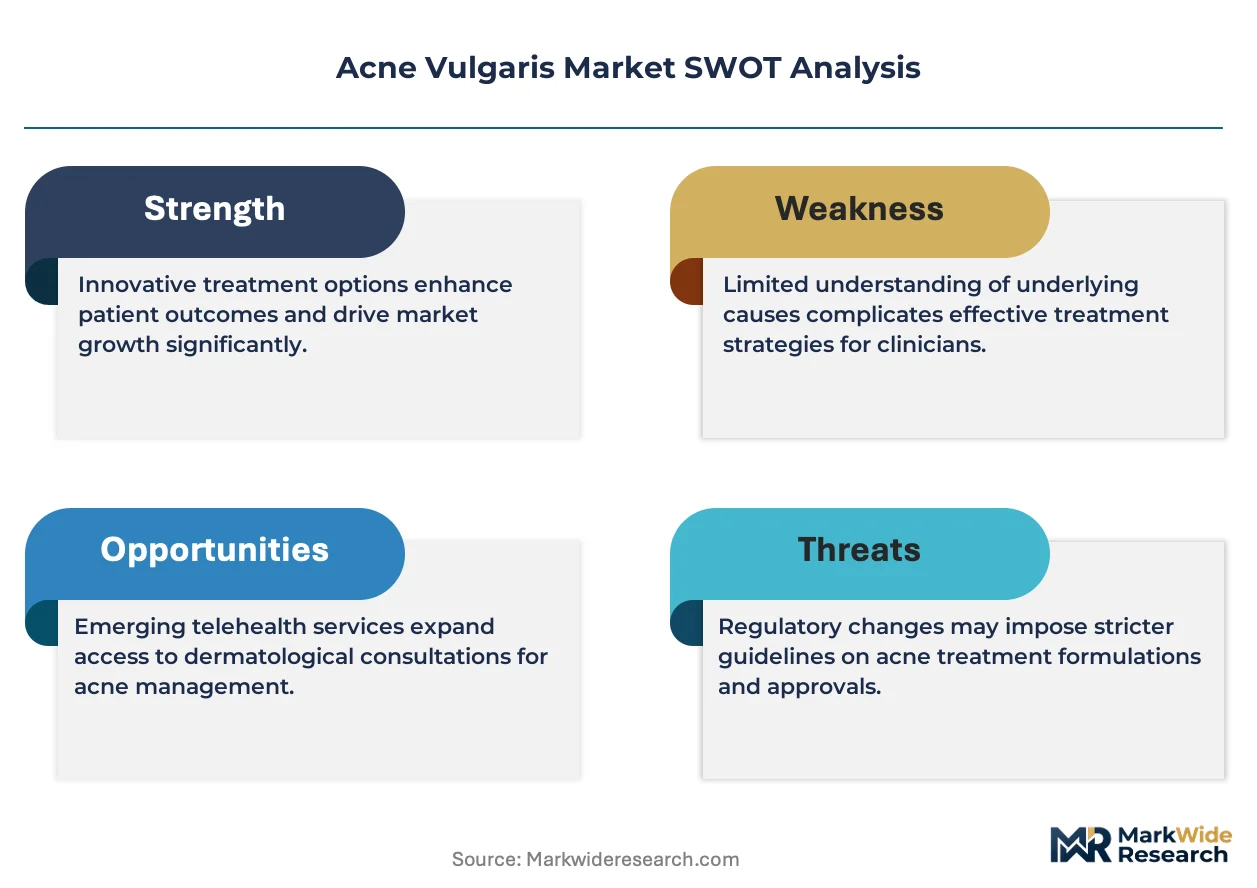
Antibiotic stewardship mandates from WHO and national regulators are compressing oral tetracycline prescribing volumes and forcing manufacturers to accelerate non-antibiotic topical development programs.
Growth Catalysts
- FDA Label Modernization:The agency's streamlined review pathways for combination topical products accelerate time-to-market for fixed-dose retinoid-antimicrobial formulations.
- Telemedicine Prescribing:Dermatology platforms in the United States now generate substantial prescription volumes through asynchronous consultation models, expanding addressable patient pools beyond traditional clinic footprints.
- Photodynamic Therapy:Blue and red light devices for home use gain reimbursement traction in Germany, creating parallel demand channels alongside pharmaceutical interventions.
Market Restraints
- Isotretinoin Teratogenicity Controls:The FDA's iPLEDGE risk management program imposes burdensome prescriber and pharmacy certification requirements that limit prescriber willingness to initiate therapy.
- API Concentration Risk:Bulk retinoid and benzoyl peroxide active pharmaceutical ingredient production concentrates in select Indian and Chinese manufacturing clusters, exposing formulators to geopolitical supply interruptions.
- Generic Substitution Pressure:Patent expirations on branded topical retinoids enable pharmacy-level therapeutic substitution that compresses realized prices for originator products.
Strategic Opportunities
- Microbiome-Targeted Therapeutics:Emerging platforms that modulate C. acnes strain populations without broad-spectrum antibiotic activity address unmet need in recalcitrant inflammatory acne.
- Subscription Direct-to-Consumer Channels:Telehealth-integrated delivery models in the United States bypass traditional pharmacy distribution and capture patient lifetime value through recurring revenue structures.
- EMA Orphan Designation Pathways:Severe nodulocystic acne subpopulations may qualify for expedited regulatory review and pricing flexibility under European rare disease frameworks.
Industry Challenges
- Formulation Stability Expertise:Retinoid oxidation sensitivity and benzoyl peroxide decomposition kinetics require specialized chemistry talent that commands premium compensation in competitive labor markets.
- Multi-Jurisdiction Label Harmonization:Divergent teratogenicity warning requirements across FDA, EMA, and PMDA jurisdictions complicate global product registration strategies and delay market entry timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acne Vulgaris Market |
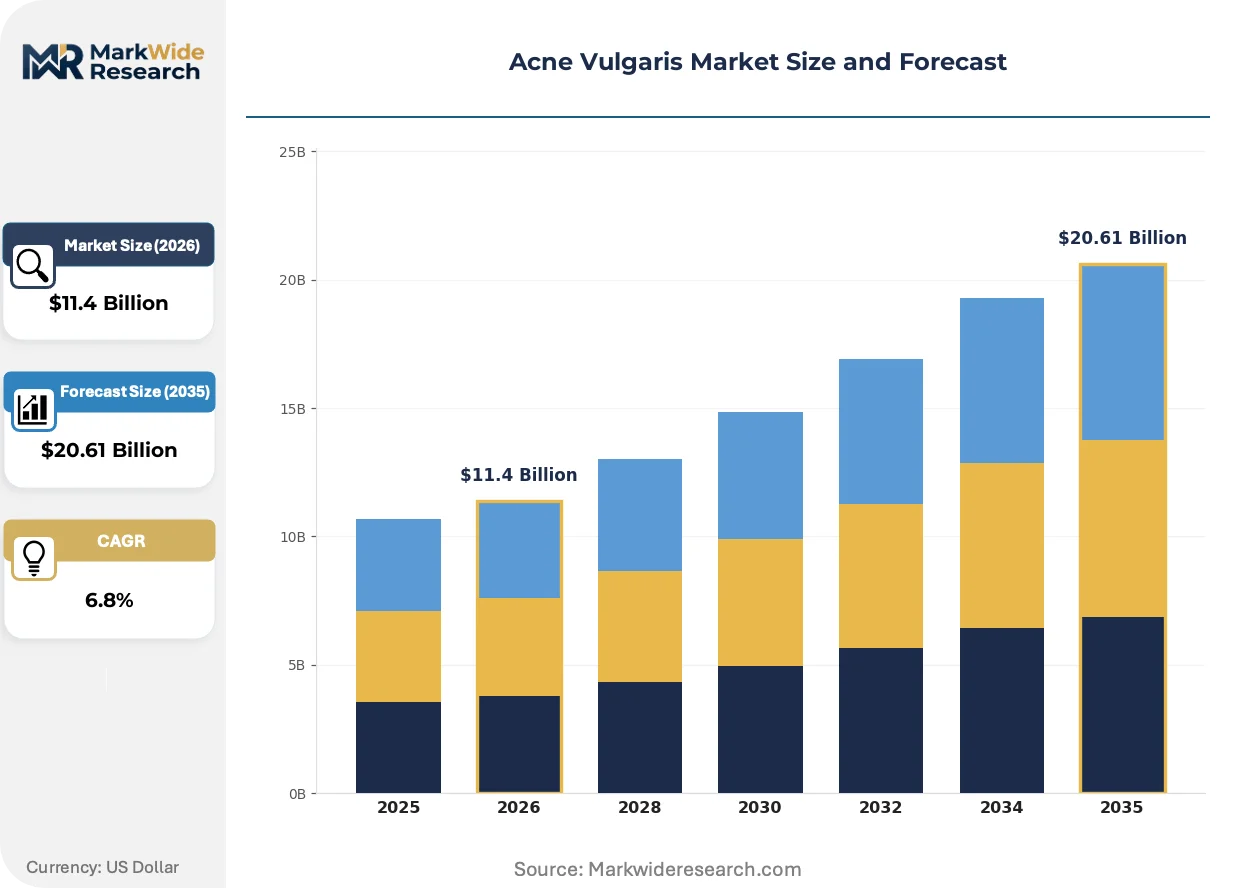
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Treatments, Oral Medications, Light Therapy, Chemical Peels End User: Dermatology Clinics, Hospitals, Home Care, Pharmacies Application: Adult Acne, Adolescent Acne, Scarring Treatment, Prevention Delivery Mode: Prescription, Over-the-Counter, Salon Treatments, Online Sales |
| Companies Covered | Allergan, GlaxoSmithKline, Galderma, Sun Pharmaceutical Industries Ltd., Almirall, Johnson & Johnson, Pfizer Inc., Eli Lilly and Company, Bausch Health Companies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acne Vulgaris Market Emerging Trajectories
Formulation science and delivery mechanism innovation are displacing conventional cream and gel vehicles, while regulatory pressure on antibiotic use accelerates investment in alternative anti-inflammatory modalities.
Microencapsulated retinoid delivery systems is decentralizing potency distribution across epidermal layers, reducing irritation profiles that historically limited patient adherence. Dermatology practices in the United States and South Korea are adopting these vehicles for sensitive-skin patient populations. The technology is decentralizing the historical trade-off between efficacy and tolerability that constrained prescription retention rates.
The EPA's manufacturing discharge standards for pharmaceutical active ingredients are forcing production site relocations and capital upgrades at US-based topical formulation facilities. These environmental compliance costs disproportionately affect mid-scale generic manufacturers without captive API synthesis capabilities. Contract manufacturing organizations with integrated waste treatment infrastructure are capturing volume from repositioning brand owners.
Patient-initiated switching between over-the-counter and prescription channels is compressing brand loyalty cycles and elevating price transparency. Pharmacy benefit managers in the United States are unbundling acne therapies from broader dermatology formularies, enabling granular prior authorization controls. This behavioral shift is most pronounced among adult female acne patients aged 25-40 who maintain active engagement with digital health platforms.
Acne Vulgaris Market Segmentation
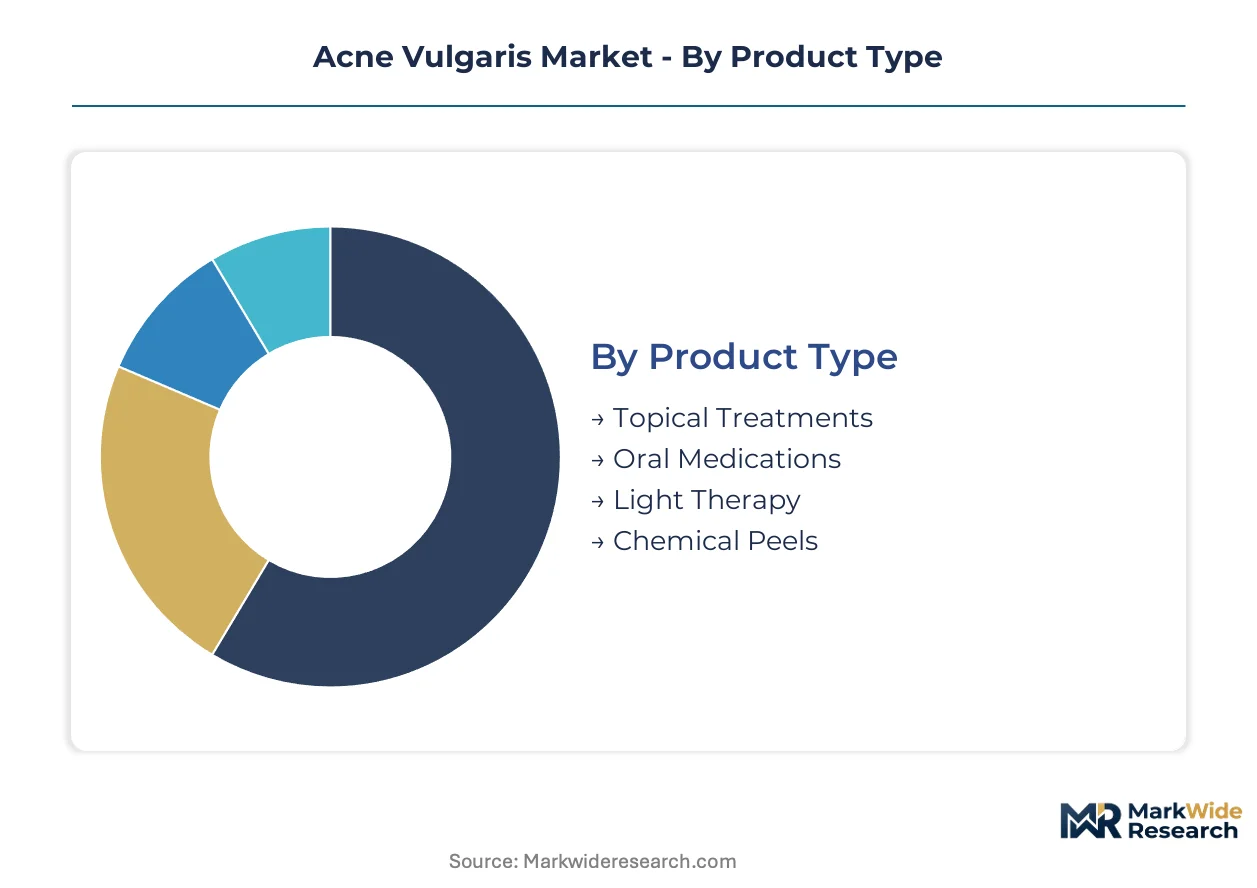
Acne vulgaris treatment modalities fragment across pharmacological and non-pharmacological pathways, with each segment commanding distinct reimbursement codes and prescriber workflows. Understanding these divisions reveals where manufacturers capture margin versus where volume concentrates.
Product Type:
Topical formulations dominate prescription volumes while oral therapies command premium pricing per patient course.
- Topical Treatments:Retinoid, benzoyl peroxide, and combination creams/gels constitute the first-line standard across mild-to-moderate cases. Demand clusters in the United States where pharmacy benefit managers maintain broad formulary access for generic adapalene and clindamycin-benzoyl peroxide combinations.
- Oral Medications:Systemic isotretinoin, tetracyclines, and hormonal therapies target moderate-to-severe inflammatory or treatment-resistant populations. Germany's statutory health insurance funds restrict tetracycline reimbursement to documented failure of topical protocols, compressing volumes despite higher per-prescription value.
- Light Therapy:Blue and red LED devices for clinic and home deployment address antibiotic stewardship concerns.
- Chemical Peels:Glycolic, salicylic, and trichloroacetic acid procedures for comedonal clearance and post-inflammatory hyperpigmentation.
Today's leader: Topical Treatments. Tomorrow's challenger: Light Therapy.
End User:
Channel fragmentation accelerates as telemedicine platforms disintermediate traditional clinic relationships.
- Dermatology Clinics:Specialist practices in the United States and South Korea deploy combination protocols and device-based adjuncts. Patient throughput constraints limit capacity expansion despite reimbursement advantages for procedural add-ons.
- Hospitals:Academic medical centers manage severe nodulocystic cases and isotretinoin risk management programs. France's hospital-based dermatology departments anchor regional referral networks for iPLEDGE-equivalent pregnancy prevention protocols.
- Home Care:Direct-to-consumer subscription services and telehealth-integrated prescribing expand fastest among delivery channels.
- Pharmacies:Community and mail-order dispensing face margin compression from generic substitution mandates.
Home Care channels are climbing the fastest as asynchronous dermatology platforms scale patient acquisition.
Application:
Patient demographics split between adolescent volume and adult premium-seeking behavior.
- Adult Acne:Persistent or late-onset cases in patients aged 25-40 drive demand for cosmetic-compatible formulations. The United Kingdom's National Health Service excludes adult acne from routine commissioning in many clinical commissioning groups, pushing patients toward private-pay channels.
- Adolescent Acne:Pubertal onset cases generate highest absolute patient volumes globally. Pediatric dermatology referral backlogs in Canada extend wait times for moderate cases beyond six months in Ontario and British Columbia.
- Scarring Treatment:Laser resurfacing, microneedling, and filler interventions for atrophic and hypertrophic sequelae.
- Prevention:Maintenance regimens and pre-emptive topical protocols for high-risk populations.
Adolescent Acne retains volume dominance. Adult Acne offers steepest expansion trajectory as cosmetic dermatology spending rises.
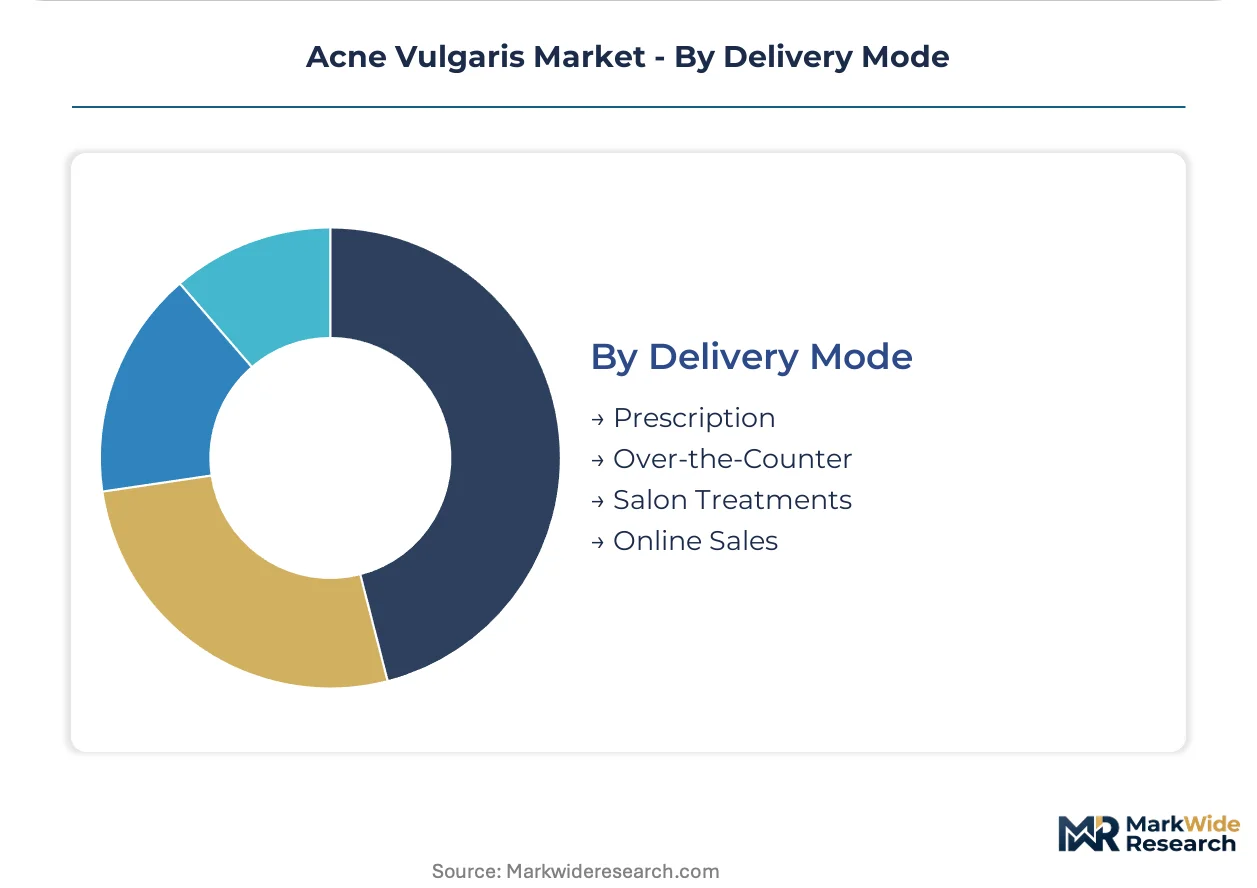
Delivery Mode:
Regulatory classification determines distribution infrastructure and marketing investment requirements.
- Prescription:Physician-controlled access for retinoids, isotretinoin, and oral antibiotics. Japan's PMDA maintains distinct approval pathways for fixed-dose combination topicals that delay market entry versus single-agent alternatives.
- Over-the-Counter:Benzoyl peroxide and salicylic acid formulations for self-directed mild case management. Shelf space competition at US mass retailers drives promotional spending cycles that erode manufacturer margins.
- Salon Treatments:Aesthetic clinic-administered peels and extractions operating outside medical reimbursement.
- Online Sales:Direct-to-consumer platforms bypass pharmacy distribution entirely.
Prescription channels defend value capture. Online Sales are gaining share fastest as regulatory arbitrage enables cross-border fulfillment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating topical formulation capacity to jurisdictions with streamlined environmental compliance, exploiting cost-of-compliance gaps between EPA-regulated US facilities and emerging production zones with less stringent discharge protocols.
United States
Adolescent and adult patient volumes sustain the world's highest prescription density for topical retinoids and combination therapies. The FDA's iPLEDGE risk management program for isotretinoin imposes certification burdens that limit prescriber participation and push moderate cases toward topical alternatives. New Jersey and North Carolina host concentrated formulation manufacturing for US-market benzoyl peroxide and retinoid products.
Germany
Statutory health insurance funds restrict oral tetracycline reimbursement to documented topical failure, compressing antibiotic volumes despite strong patient demand. The EMA's Pharmacovigilance Risk Assessment Committee periodically reviews systemic isotretinoin protocols, influencing prescriber behavior across German dermatology practices. The Rhine-Ruhr corridor anchors production of photodynamic therapy devices gaining home-use reimbursement traction.
India
Domestic API synthesis capabilities supply global formulators with bulk retinoid and benzoyl peroxide intermediates at cost-advantaged scale. The CDSCO's accelerated approval pathways for fixed-dose combination topicals attract multinational licensing activity. Gujarat and Maharashtra host concentrated active pharmaceutical ingredient manufacturing clusters serving North American and European markets.
South Korea
Cosmetic-compatible formulation expertise supports premium positioning for adult female acne patients aged 25-40. The MFDS maintains distinct stability testing requirements for microencapsulated retinoid vehicles that delay market entry versus conventional formulations. Seoul's Gangnam district concentrates aesthetic dermatology clinics deploying advanced delivery systems for sensitive-skin populations.
United Kingdom
National Health Service commissioning exclusions for adult acne push patients toward private-pay channels and direct-to-consumer platforms. MHRA post-Brexit divergence from EMA labeling standards complicates pan-European registration strategies for UK-based formulators. The Southeast England corridor hosts telehealth-integrated prescribing platforms scaling asynchronous dermatology consultations.
Acne Vulgaris Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue microbiome-targeted modalities and direct-to-consumer subscription channels outside traditional pharmacy distribution. The market structures around three archetypes: vertically integrated API-to-formulation operators, brand-equity-dependent over-the-counter marketers, and telehealth-integrated direct dispensing platforms. Consolidation pressure concentrates among mid-scale generic manufacturers lacking captive synthesis capabilities. Competitive moves center on backward integration into active pharmaceutical ingredient production and geographic relocation of formulation capacity to lower-compliance-cost jurisdictions.
Among Swiss-anchored dermatology specialists, Galderma exemplifies the vertically integrated archetype through in-house retinoid manufacturing. Sun Pharmaceutical Industries Ltd. occupies a position representing Indian API-to-formulation integration. Johnson & Johnson anchors the brand-equity tier across mass-market benzoyl peroxide segments. These three entities collectively illustrate the competitive vectors reshaping supply chain configuration and channel access.
| Leading Market Players |
|---|
| Allergan |
| GlaxoSmithKline |
| Galderma |
| Sun Pharmaceutical Industries Ltd. |
| Almirall |
| Johnson & Johnson |
| Pfizer Inc. |
| Eli Lilly and Company |
| Bausch Health Companies Inc. |
| Others |
Supply Flow & Price Mechanics
Pharmacy benefit manager formulary unbundling in the United States is forcing manufacturers to absorb distribution margin compression or relocate formulation capacity to lower-compliance-cost jurisdictions, reshaping where value capture concentrates across the supply chain.
Pricing Analysis
Input-cost pass-through from EPA discharge compliance upgrades and retinoid oxidation-sensitive handling requirements sustains premium pricing for microencapsulated formulations versus commodity gels. Three-tier pricing structure across premium, standard, and economy levels separates patent-protected combination vehicles from authorized generics and mass-market benzoyl peroxide. Cost compression in the generic topical segment is intensifying because of pharmacy substitution mandates and direct-to-consumer subscription erosion. Adolescent patient populations through Medicaid channels exhibit highest price sensitivity; adult cosmetic-seeking patients aged 25-40 show lowest sensitivity.
Supply Chain Analysis
Certification gating through FDA cGMP, EMA GMP, and MFDS stability testing requirements limits qualified formulation sites for US and European market supply. Active pharmaceutical ingredient production concentrates in India, China, and selected US facilities for retinoid and benzoyl peroxide intermediates. Finished formulation draws from India, Germany, and the United States for high-compliance markets. Single-source vulnerability in Chinese benzoyl peroxide precursor supply exposes formulators to geopolitical interruption. Distribution runs through pharmacy benefit manager networks, direct-to-consumer platforms, and hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities in acne therapeutics rest on microbiome-targeted platform premiums and telehealth-integrated dispensing models that bypass traditional pharmacy margin stacking.
For Market Incumbents: Anchor formulation competitiveness through backward integration into retinoid API synthesis and captive production of oxidation-stable microencapsulated vehicles. Defend against generic substitution pressure by securing exclusive pharmacy benefit manager placement for combination therapies. Prioritize certification maintenance across FDA, EMA, and MFDS jurisdictions to preserve high-value market access. For New Entrants and Emerging Players: The premium-to-economy price gap in adult cosmetic-compatible segments offers white-space entry for mid-tier players with sensitive-skin formulation expertise. Target direct-to-consumer subscription channels in the United Kingdom and United States where National Health Service exclusions and asynchronous telemedicine platforms bypass traditional gatekeepers. Pursue licensing partnerships with Indian API manufacturers to compress development timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with microbiome-targeted therapeutic platforms addressing antibiotic stewardship restrictions. Long-term viability favors assets with demonstrated C. acnes strain selectivity and regulatory progress toward non-antibiotic mechanisms. Watch FDA iPLEDGE program modifications as the inflection signal for isotretinoin market restructuring and topical alternative demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Microbiome Platform Development | Non-antibiotic C. acnes modulation addresses WHO stewardship mandates and recalcitrant patient populations. |
| Telehealth-Integrated Dispensing | Direct-to-consumer subscription models bypass pharmacy benefit manager margin extraction in the United States. |
| API Backward Integration | In-house retinoid synthesis insulates against Indian and Chinese supply concentration risks. |
| EMA Orphan Pathway Pursuit | Severe nodulocystic acne designation unlocks expedited review and pricing flexibility in European markets. |
| Microencapsulation Scale-Up | Advanced delivery vehicle production captures sensitive-skin premium segments in South Korea and the United States. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement with dermatology practice managers, formulary directors at pharmacy benefit managers, regulatory affairs leads at topical formulation manufacturers, and procurement officers at contract manufacturing organizations grounded the supply chain assessment. Secondary validation drew from FDA 483 inspection observations, EMA Pharmacovigilance Risk Assessment Committee minutes, CDSCO accelerated approval announcements, and ClinicalTrials.gov protocol registries. Bottom-up patient volume modeling and top-down manufacturer revenue triangulation anchored market sizing.
Historical reference periods spanning pre-pandemic, pandemic-disrupted, and recovery-phase intervals anchored the forecast window calibration. The analytical framework segmented across treatment modality, delivery channel, patient demographic, and regional regulatory cluster dimensions. CAGRs were derived from fitted growth curves applied to normalized baseline values. Forecast inputs incorporated antibiotic stewardship policy trajectory, telemedicine platform scaling rates, and EPA manufacturing discharge standard evolution.
The model assumes a particular technology adoption path; alternative pathways for at-home photodynamic therapy device reimbursement would alter the outlook. Forecasts reflect documented assumptions regarding iPLEDGE program stability and WHO antibiotic guideline implementation timing. Deviation in FDA topical retinoid labeling requirements or EMA isotretinoin risk management protocol modifications would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Dermabrasion and Micro Needling Market
Dermatology
Europe Scar Treatment Market
Dermatology
Scar Treatment Oils Market
Dermatology
Common Warts Market
Dermatology
Homecare Dermatology Energy-Based Devices Market
Dermatology
Telogen Effluvium Treatment Market
Dermatology
Lichen Sclerosus Treatment Market
Dermatology
Psoriasis Treatment Market
Dermatology
Atopic Dermatitis Therapeutics Market
Dermatology
Acne Vulgaris Treatment Market
Dermatology
Japan Scar Treatment Market
Dermatology
Dermatological Products Market
Dermatology
Dermatology Devices Market
Dermatology
Porokeratosis Treatment Market
Dermatology
Global Dermatological OTC Drugs Market
Dermatology
Global Dermatitis Herpetiformis Market