
 Pigmented Lesion Treatment Market | 2026-2036
Pigmented Lesion Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Pigmented Lesion Treatment Market Outlook
Capital-intensity divergence between integrated device manufacturers and pure-play service providers is unwinding competitive dynamics across the pigmented lesion treatment landscape. Alma Lasers Ltd. leverages in-house laser source production to sustain margin control across multiple wavelength platforms. Cynosure, Inc. anchors its position through proprietary picosecond technology that dominates premium clinic segments. Lumenis Ltd. competes on installed-base scale, extending service revenue through long-term maintenance contracts in hospital systems.
Pigmented lesion treatment encompasses medical and aesthetic interventions targeting melanocytic nevi, solar lentigines, and post-inflammatory hyperpigmentation through selective photothermolysis, cryonecrosis, or chemoexfoliation, with laser devices typically operating at 532 nm, 755 nm, or 1064 nm wavelengths depending on lesion depth and melanin concentration. Laser Devices command the largest revenue pool due to capital equipment replacement cycles and consumable handpiece attach rates, while Topical Agents gain traction in homecare settings where patient compliance and cost sensitivity reshape prescribing patterns. Dermatology Clinics absorb the majority of procedural volume as physician-owned practices consolidate purchasing power and negotiate preferred vendor tiers.
FDA 510(k) clearance pathways and CE marking under the EU MDR govern commercial access for laser and energy-based devices, with both frameworks demanding clinical evidence for pigment-specific indications that extends development timelines. The EPA regulates mercury-containing lamps in older IPL systems, accelerating xenon flashlamp replacement demand. Solta Medical Inc. and Lutronic Corporation navigate these requirements through dedicated regulatory affairs teams that prevalidate documentation for multi-jurisdiction submissions. Stakeholders must monitor how FDA draft guidance on software-as-a-medical-device applies to AI-enabled lesion mapping features now appearing in next-generation platforms.
Market Dynamics
Picosecond laser platforms are compressing treatment protocols from multiple sessions to single-visit outcomes, forcing capital equipment refresh cycles and reshaping clinic purchasing priorities toward wavelength versatility and handpiece interchangeability.
Growth Catalysts
- Outpatient migration:Physician-owned dermatology practices in the United States and Germany are consolidating purchasing power through group procurement organizations, negotiating preferred vendor tiers that accelerate device replacement cycles.
- EU MDR alignment:CE marking under the EU Medical Device Regulation is elevating clinical evidence standards for pigment-specific indications, filtering marginal competitors and concentrating market share among established manufacturers with dedicated regulatory affairs infrastructure.
- Homecare topical expansion:Patient compliance patterns in South Korea are shifting prescription behavior toward chemoexfoliation agents for maintenance between procedural interventions, expanding the addressable patient base beyond clinic walls.
Market Restraints
- Xenon flashlamp supply concentration:EPA regulations on mercury-containing lamps in legacy IPL systems have concentrated qualified lamp sourcing to three Japanese and German suppliers, creating input bottlenecks for mid-tier device manufacturers.
- Technical depth limitation:532 nm wavelength platforms cannot safely treat Fitzpatrick skin types V-VI due to competing hemoglobin absorption and epidermal injury risk, excluding substantial patient populations across India and Brazil.
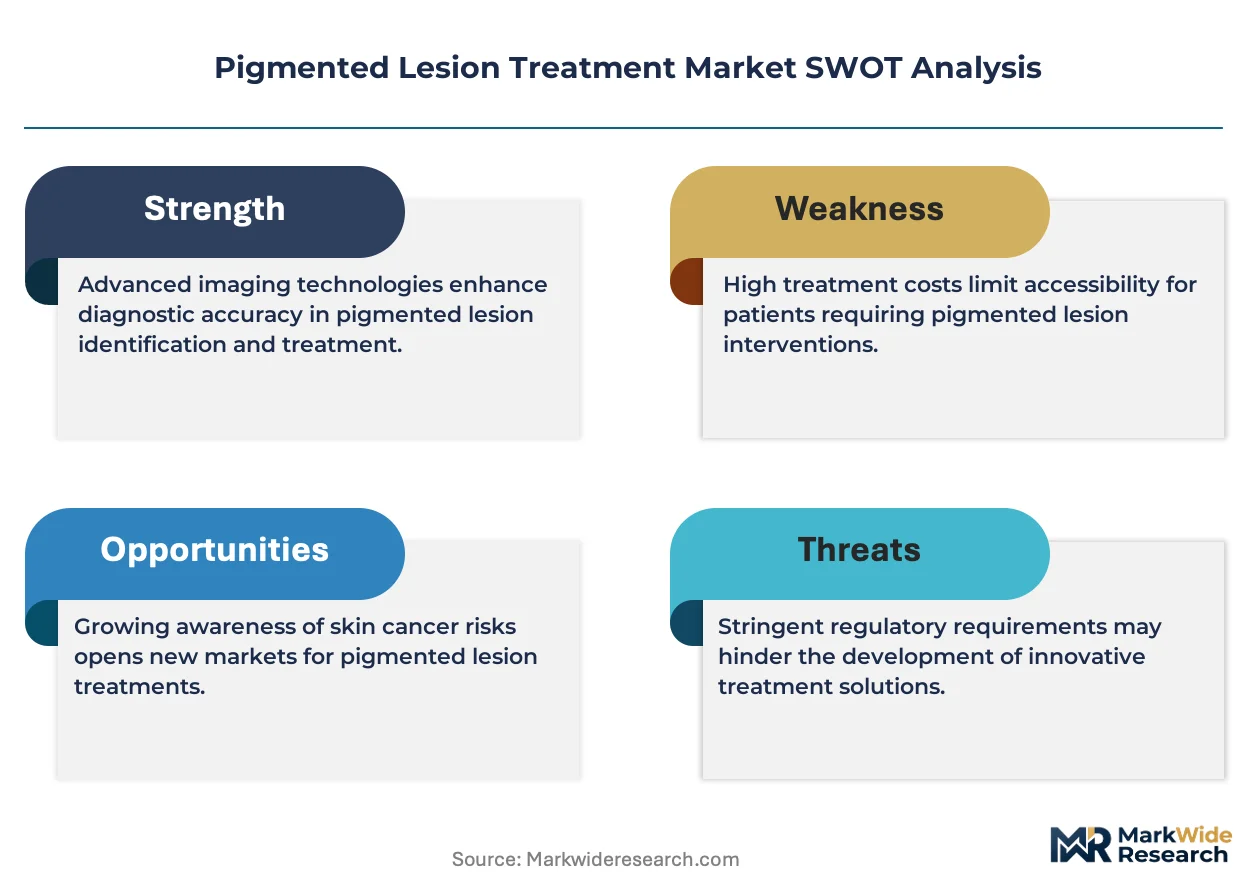
- Reimbursement fragmentation:Cosmetic classification of solar lentigines and benign nevi removal blocks insurance coverage in most national health systems, restricting volume to discretionary out-of-pocket expenditure.
Strategic Opportunities
- AI-enabled lesion mapping:Software-as-a-medical-device frameworks under FDA draft guidance are creating regulatory pathways for automated melanin concentration assessment, enabling personalized wavelength selection algorithms.
- Middle East clinic expansion:Dubai and Riyadh are witnessing medical tourism infrastructure investment that positions pigmented lesion treatment as adjunctive service to broader aesthetic medicine packages.
- Combination protocol adoption:Sequential laser-cryotherapy approaches for resistant melasma are gaining protocol validation in South Korean university hospital settings, opening bundled service revenue models.
Industry Challenges
- Laser physicist talent scarcity:Device manufacturers face recruitment competition from semiconductor and defense sectors for specialists capable of optimizing Nd:YAG cavity designs and beam delivery optics.
- 510(k) timeline extension:FDA demands for pigment-specific clinical endpoints have stretched premarket notification review periods, compressing product launch windows against competitive refresh cycles.
- Legacy system integration:Hospital systems with decade-old IPL installations require costly electrical infrastructure upgrades to accommodate picosecond platform power demands and cooling requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pigmented Lesion Treatment Market |
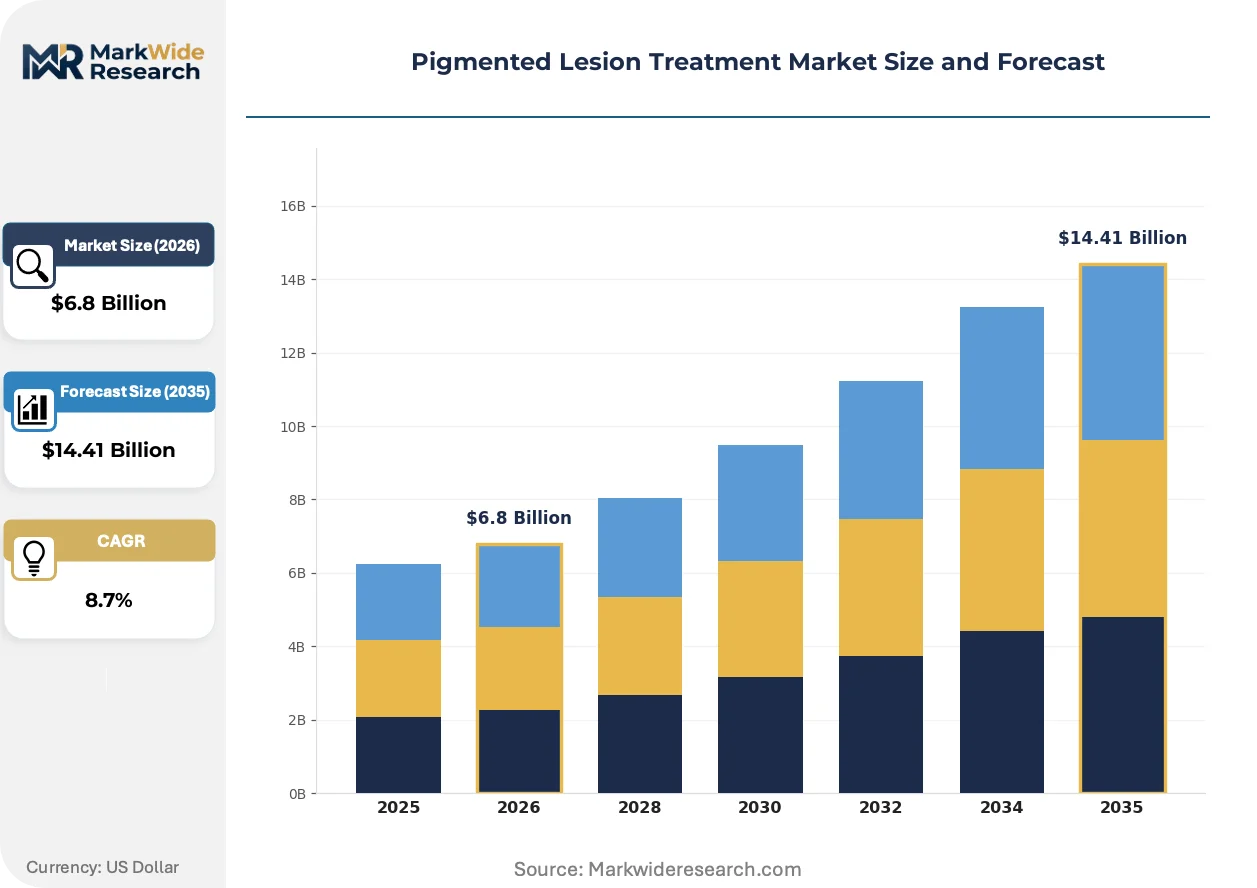
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Agents, Laser Devices, Photodynamic Therapy, Surgical Removal End User: Dermatology Clinics, Hospitals, Homecare Settings, Research Facilities Treatment Technology: Laser Therapy, Cryotherapy, Chemical Peels, Electrosurgery Age Group: Pediatric, Adult, Geriatric, Elderly |
| Companies Covered | Alma Lasers Ltd., Cynosure, Inc., Lumenis Ltd., Cutera Inc., Solta Medical Inc., Strata Skin Sciences Inc., Lutronic Corporation, Lynton Lasers Ltd., Syneron Medical Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pigmented Lesion Treatment Market Strategic Shifts
Device architecture is fragmenting around divergent clinical workflows, with premium platforms pursuing artificial intelligence integration while value-tier manufacturers optimize for single-wavelength reliability and reduced service intervals.
Picosecond pulse duration technology is bifurcating treatment economics across the dermatology clinic segment. Ultra-short pulse platforms operating at 755 nm and 1064 nm enable photoacoustic melanin disruption with reduced thermal diffusion, supporting single-session clearance for solar lentigines. High-volume clinic chains in the United States and Germany are prioritizing these systems for throughput optimization, while independent practices defer capital commitment pending outcome durability data. The technology is bifurcating market tiering between premium picosecond installations and discounted nanosecond legacy trade-ins.
EU MDR technical documentation requirements are extending development timelines for laser-based devices seeking CE marking. The regulation mandates clinical evaluation reports with pigment-specific safety and performance endpoints, forcing manufacturers to sponsor prospective trials rather than relying on predicate device equivalence. Class IIa and IIb device categories face notified body capacity constraints, with queue times stretching submission-to-certification intervals. German and French manufacturers with established quality management systems are absorbing these costs more readily than smaller competitors.
After-sales service contracts are unbundling from capital equipment sales in hospital system procurement. Purchasing departments in the United States are negotiating maintenance agreements separately from device acquisition, comparing multi-vendor service offerings against manufacturer-captive programs. This disintermediation pressures original equipment manufacturers to demonstrate response time guarantees and parts availability commitments. The pattern is most visible in integrated delivery networks consolidating dermatology service lines across multiple states.
Pigmented Lesion Treatment Market Segmentation
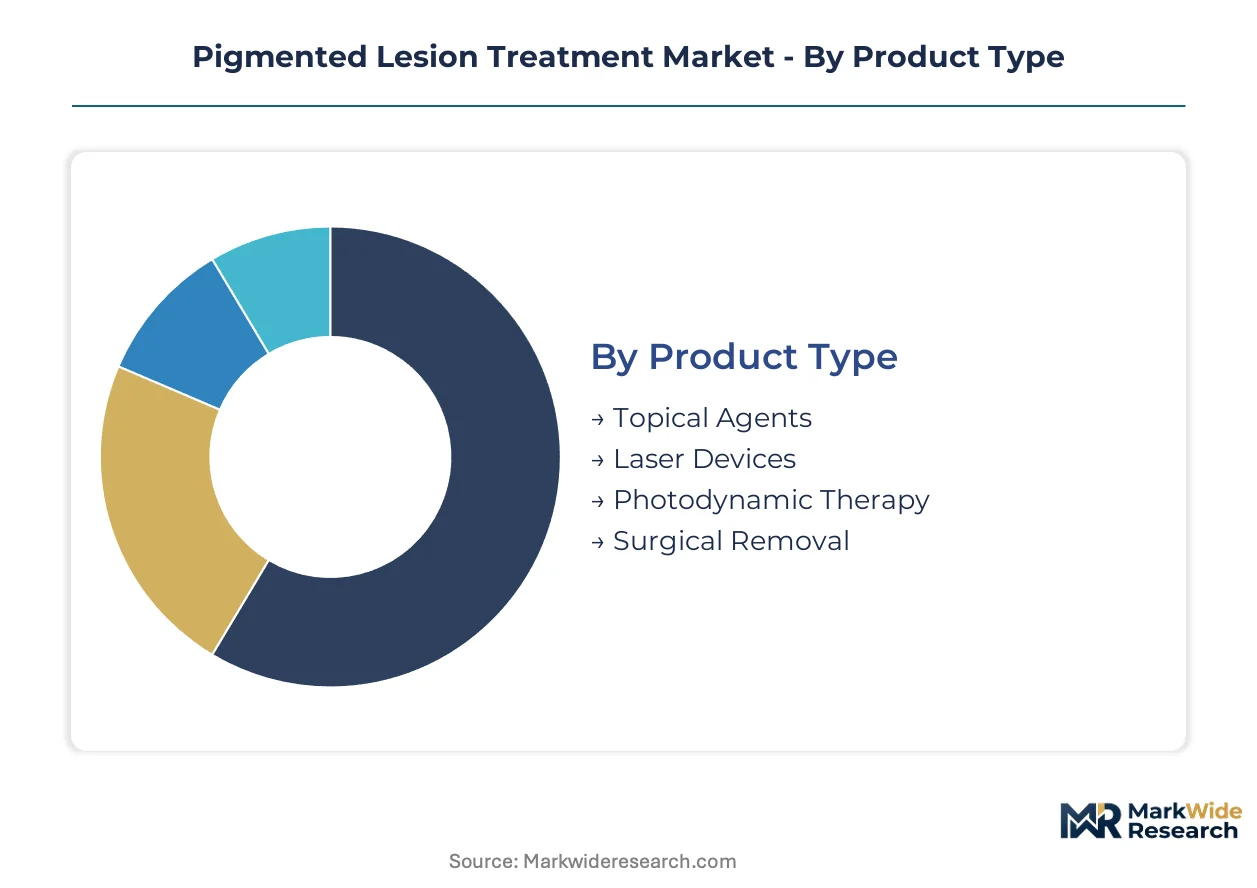
Segmentation in pigmented lesion treatment reveals divergent margin architectures across hardware, consumables, and service delivery. Product type determines capital intensity and recurring revenue attach rates, while end-user channel selection governs pricing power and procurement negotiation dynamics.
Product Type:
Margin pools concentrate in capital equipment with captive consumable streams, though homecare topicals are capturing recurring revenue at lower per-unit economics.
- Laser Devices:Capital platforms operating at 532 nm, 755 nm, or 1064 nm wavelengths dominate procedural revenue through equipment replacement cycles and handpiece attach rates. Demand clusters in United States and German dermatology clinics where physician-owned practices consolidate purchasing power through group procurement organizations.
- Topical Agents:Chemoexfoliation formulations for maintenance between procedural interventions are gaining prescription traction in South Korean homecare settings where patient compliance patterns reshape prescribing behavior. Cost sensitivity and convenience drivers expand the addressable patient base beyond clinic walls.
- Photodynamic Therapy:Photosensitizer-activated protocols for resistant lesions occupy niche positioning in hospital-based dermatology departments.
- Surgical Removal:Excisional approaches for suspicious or deep dermal lesions retain utility in pathology-requiring cases within hospital systems.
Laser Devices hold installed capacity. Topical Agents is rotating up the share rankings.
End User:
Channel selection dictates reimbursement access and capital deployment cycles, with outpatient migration reshaping volume distribution.
- Dermatology Clinics:Physician-owned practices absorb the majority of procedural volume as aesthetic medicine shifts toward outpatient settings. Consolidated purchasing power enables preferred vendor tier negotiations that accelerate device refresh cycles in United States and German markets.
- Hospitals:Integrated delivery networks maintain legacy IPL installations requiring electrical infrastructure upgrades to accommodate picosecond platform power demands. Service revenue unbundling from capital sales pressures original equipment manufacturers on response time guarantees.
- Homecare Settings:Prescription topical maintenance protocols between clinic visits are expanding in South Korea where patient compliance patterns favor convenience.
- Research Facilities:Academic medical centers sponsor prospective trials for EU MDR clinical evaluation reports with pigment-specific endpoints.
Dermatology Clinics command volume leadership. Homecare Settings is climbing the fastest.
Treatment Technology:
Technology selection correlates with lesion depth, melanin concentration, and Fitzpatrick skin type safety profiles.
- Laser Therapy:Selective photothermolysis at wavelength-specific depths enables targeted melanin disruption. Picosecond pulse durations compress treatment protocols from multiple sessions to single-visit outcomes, forcing capital equipment refresh cycles toward wavelength versatility.
- Cryotherapy:Liquid nitrogen-based cryonecrosis retains cost advantage for superficial lesions in value-tier clinic segments.
- Chemical Peels:Acid-based chemoexfoliation supports maintenance protocols and combination approaches for resistant melasma in South Korean university hospital settings.
- Electrosurgery:High-frequency current applications for lesion destruction persist in resource-constrained settings.
Laser Therapy holds installed capacity. Cryotherapy is rotating up the share rankings.
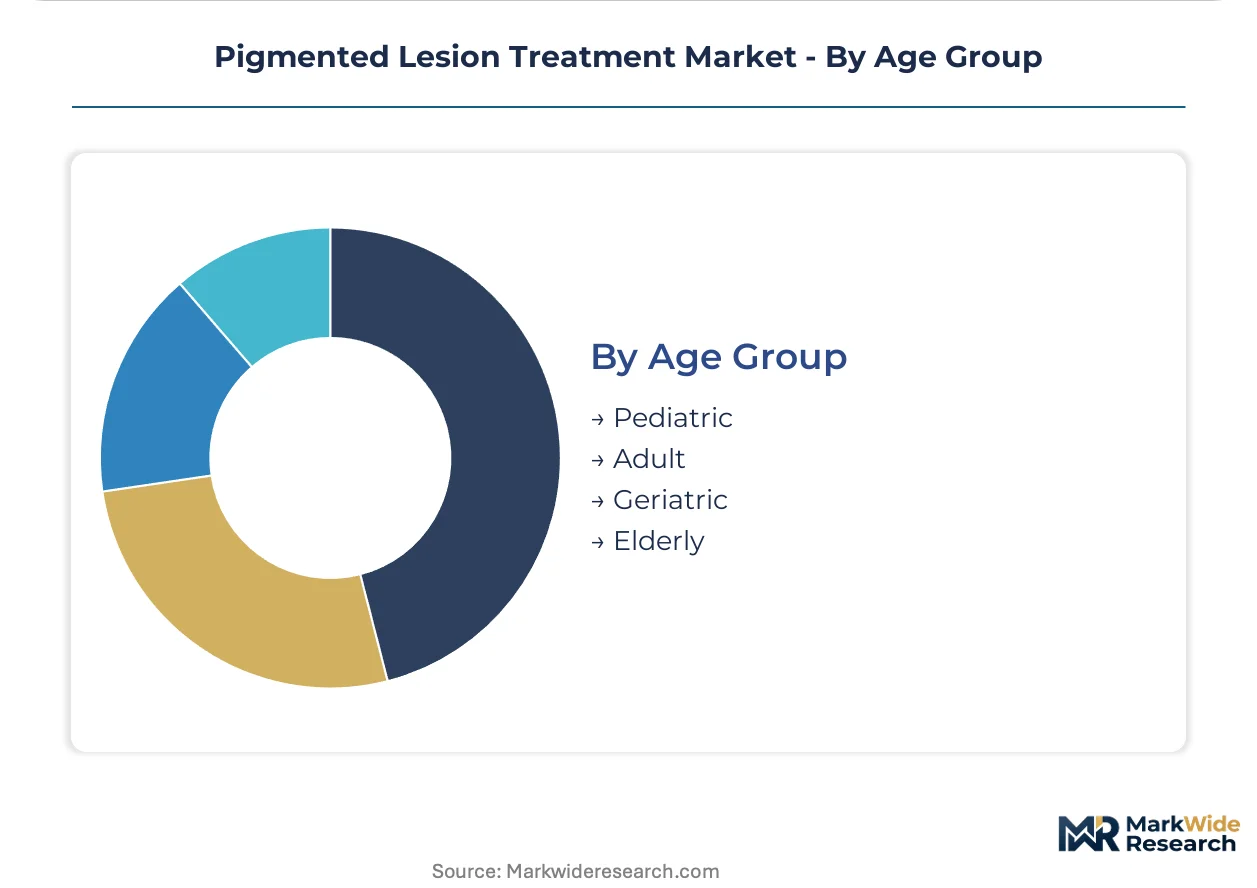
Age Group:
Demographic targeting aligns with lesion etiology and aesthetic concern prevalence.
- Adult:Solar lentigines and post-inflammatory hyperpigmentation drive procedural volume in working-age populations with discretionary expenditure capacity.
- Geriatric:Cumulative UV exposure lesions concentrate demand in aging populations across developed markets.
- Pediatric:Congenital melanocytic nevi indications occupy specialized pediatric dermatology referral pathways.
- Elderly:Benign nevi removal for comfort or cosmetic reasons persists in long-term care-integrated settings.
Adult holds installed capacity. Geriatric is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Patients in South Korea and Germany absorb premium pricing for picosecond platforms with minimal reimbursement support. Buyers in Brazil and India face acute cost constraints where 532 nm wavelength limitations exclude darker skin types from standard protocols.
United States
Physician-owned dermatology practices consolidate purchasing power through group procurement organizations. FDA 510(k) clearance pathways for laser devices demand pigment-specific clinical endpoints that extend premarket timelines. Miami and Los Angeles clinic chains drive picosecond platform adoption for single-visit solar lentigines clearance.
Germany
EU MDR technical documentation requirements elevate clinical evidence standards for CE marking. Notified body capacity constraints stretch submission-to-certification intervals for Class IIb laser devices. Munich and Frankfurt hospital systems unbundle after-sales service contracts from capital equipment procurement.
South Korea
Patient compliance patterns reshape prescribing behavior toward chemoexfoliation agents for homecare maintenance. MFDS regulates laser devices under medical device classification with stringent post-market surveillance. Seoul university hospitals validate sequential laser-cryotherapy protocols for resistant melasma.
Brazil
Technical depth limitations of 532 nm platforms exclude Fitzpatrick skin types V-VI from safe treatment. ANVISA governs commercial access for energy-based devices with import licensing requirements. São Paulo aesthetic medicine clinics absorb mid-tier nanosecond laser volume discounted from premium picosecond trade-ins.
United Arab Emirates
Medical tourism infrastructure investment positions pigmented lesion treatment as adjunctive service to broader aesthetic packages. MOHAP regulates device registration with parallel import restrictions protecting authorized distributor margins. Dubai clinic operators negotiate multi-device vendor tiers for wavelength versatility.
Pigmented Lesion Treatment Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes. Integrated device manufacturers with in-house laser source production sustain margin control across wavelength platforms. Pure-play service providers compete on installed-base scale and long-term maintenance contract penetration. The market structure concentrates around three strategic archetypes: vertically integrated hardware specialists, picosecond technology premiumizers, and service revenue optimizers. Dominant competitive moves include M&A for regulatory affairs infrastructure and strategic partnerships for multi-jurisdiction distribution.
Among Israeli-integrated device manufacturers, Alma Lasers Ltd. and Lumenis Ltd. exemplify the vertically integrated archetype with captive laser source production. Cynosure, Inc. anchors the picosecond premium tier through proprietary ultra-short pulse platforms. These three entities represent divergent margin architectures across hardware, consumables, and service delivery.
| Leading Market Players |
|---|
| Alma Lasers Ltd. |
| Cynosure, Inc. |
| Lumenis Ltd. |
| Cutera Inc. |
| Solta Medical Inc. |
| Strata Skin Sciences Inc. |
| Lutronic Corporation |
| Lynton Lasers Ltd. |
| Syneron Medical Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term service contracts with captive parts provisioning lock in both xenon flashlamp supply access and maintenance revenue visibility for laser device manufacturers negotiating with United States hospital systems. These agreements insulate original equipment manufacturers from spot-market volatility while embedding pricing power through response-time guarantees and handpiece replacement schedules.
Pricing Analysis
After-sales service tiers including preventive maintenance and extended warranty contracts drive lifetime value for capital equipment vendors. Three-tier pricing structure across premium picosecond platforms, standard nanosecond systems, and economy IPL trade-ins reflects wavelength versatility and pulse duration specifications. Cost compression in mid-tier segments intensifies as South Korean and German clinics consolidate purchasing through group procurement organizations. Independent dermatology practices exhibit highest price sensitivity, while integrated delivery networks absorb premium pricing for throughput-optimized platforms.
Supply Chain Analysis
Xenon flashlamp sourcing concentrates among three qualified Japanese and German suppliers, creating a chokepoint for mid-tier device manufacturers dependent on EPA-compliant mercury-free replacements. Nd:YAG laser crystals draw from synthetic crystal growers in the United States and Russia, while precision optical coatings hinge on German and Japanese thin-film deposition specialists. Single-source vulnerability in flashlamp qualification exposes manufacturers to extended lead times. Distribution runs through authorized dealer networks with parallel import restrictions protecting margins in Middle East medical tourism markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laser physicist recruitment competition from semiconductor and defense sectors constrains device optimization capabilities across the industry. This talent scarcity elevates the strategic value of captive R&D teams and university partnerships for cavity design and beam delivery engineering.
For Market Incumbents: Shield installed-base revenue by embedding multi-year service contracts with guaranteed handpiece availability before competitors can displace legacy IPL systems. Deepen upstream control over laser source production to defend margin architecture against pure-play service providers consolidating through group purchasing negotiations. Prioritize regulatory affairs infrastructure investment to navigate EU MDR clinical evidence requirements that filter marginal competitors. For New Entrants and Emerging Players: Maintenance protocol standardization for decade-old hospital IPL installations represents a service-layer gap where incumbents under-serve electrical infrastructure upgrade requirements. Target Brazil and India with 1064 nm wavelength platforms specifically validated for Fitzpatrick skin types V-VI, penetrating segments excluded by 532 nm safety limitations. Lead with combination laser-cryotherapy training programs to differentiate against capital-only vendors. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated device manufacturers with in-house laser source production and established notified body relationships for EU MDR certification. Long-term viability favors entities with regulatory affairs infrastructure spanning FDA 510(k) and CE marking pathways. Watch FDA draft guidance finalization on software-as-a-medical-device for AI-enabled lesion mapping as an inflection signal for next-generation platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evaluation Sponsorship | Prospective trials with pigment-specific endpoints satisfy notified body requirements for Class IIb laser devices. |
| AI-Enabled Lesion Mapping Development | FDA SaMD pathways for automated melanin assessment enable personalized wavelength selection algorithms. |
| Group Procurement Organization Partnership | Preferred vendor tier status with United States dermatology clinic chains accelerates picosecond platform refresh cycles. |
| Xenon Flashlamp Supply Diversification | Dual-sourcing from Japanese and German qualified suppliers mitigates EPA-driven input bottlenecks. |
| Sequential Protocol Validation | South Korean university hospital trials for laser-cryotherapy combinations open bundled service revenue models. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, EU MDR notified body guidance documents, and hospital procurement contract filings. Interviews with dermatology clinic operators, biomedical engineers, GPO contracts managers, and regulatory affairs specialists informed demand and pricing assumptions. Secondary validation drew from CMS Medicare reimbursement data, MFDS post-market surveillance reports, and customs records for laser device trade flows. Bottom-up equipment shipment analysis triangulates against top-down addressable patient population estimates.
Segmentation dimensions modeled include product type, end-user channel, treatment technology, and age group across the projection horizon. CAGRs derive from equipment replacement cycle analysis, consumable attach rate trends, and procedural volume elasticity to pricing. Forecast inputs incorporate wavelength-specific safety profiles by Fitzpatrick skin type and reimbursement pathway development in cosmetic dermatology.
Forecasts assume regulatory continuity in FDA 510(k) pathways and EU MDR notified body capacity; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as EPA mercury lamp restrictions and AI-enabled device classification guidance evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
US and Canada Skin Cancer Dermatology Market
Dermatology
Lentigo Maligna Melanoma Therapeutic Market
Dermatology
Common Warts Market
Dermatology
Alopecia Treatment (Hair Loss) Market
Dermatology
Global Dermatology Cro Market
Dermatology
Seborrheic Dermatitis Treatment Market
Dermatology
Seborrheic Keratosis Treatment Market
Dermatology
Scleroderma Treatment Market
Dermatology
Rosacea Treatment Market
Dermatology
Darier Disease Drugs Market
Dermatology
Dermatology Drugs Market
Dermatology
Skin Hyperpigmentation Treatment Market
Dermatology
Erythema Treatment Market
Dermatology
Radiation Dermatitis Market
Dermatology
Dermal Facial Fillers Market
Dermatology
Global Dermatological OTC Drugs Market