
 Inflammatory Skin Diseases Treatment Market | 2026-2036
Inflammatory Skin Diseases Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Inflammatory Skin Diseases Treatment Market Analytics
ISO 14155 (clinical investigation of medical devices for human subjects) is reorganizing how dermatology biologic trials are structured, particularly for interleukin-targeting therapies. Novartis leverages its integrated dermatology franchise to sustain global reach in psoriasis and atopic dermatitis indications. AbbVie anchors its position through deep immunology expertise and an established injectable portfolio. Eli Lilly and Company differentiates via rapid IL-23 and IL-17 pipeline progression.
Inflammatory skin diseases treatment encompasses pharmacologic and phototherapeutic interventions designed to modulate immune-mediated cutaneous inflammation, including biologics targeting TNF-alpha, IL-17, IL-23, and JAK-STAT pathways with specified dosing regimens and cold-chain distribution requirements. The primary purpose is to achieve disease clearance or minimal disease activity in chronic conditions such as psoriasis, atopic dermatitis, and hidradenitis suppurativa. Corticosteroids and calcineurin inhibitors within the product type dimension represent mature margin pools with generic erosion, while biologic injectables command premium positioning. The delivery mode segment shows systemic and injectable routes capturing disproportionate value growth as biologics displace conventional topicals in moderate-to-severe disease.
The FDA, EMA, and WHO collectively shape market access through divergent biosimilar interchangeability rules, dermatology-specific efficacy endpoints, and prequalification standards for combination therapies. These frameworks determine trial design costs, labeling claims, and reimbursement eligibility across markets. Stakeholders must monitor evolving IL-targeting competitive dynamics and regulatory differentiation for biosimilar substitution policies.
Market Dynamics
The FDA's accelerated approval pathways for dermatology biologics are compressing competitive entry timelines while specialty pharmacy networks concentrate dispensing power around high-value injectable therapies. This regulatory-commercial convergence is restructuring how interleukin-targeting therapies reach moderate-to-severe disease patients.
Growth Catalysts
- IL-23 pathway expansion:Novel biologics targeting this cytokine axis are unlocking superior disease clearance rates in psoriasis and psoriatic arthritis, pulling patients from conventional systemic therapy.
- EMA's dermatology-specific efficacy endpoints:Harmonized PASI and EASI scoring frameworks are streamlining cross-border trial design and accelerating European market access for biologic developers.
- Prior authorization infrastructure maturation:United States specialty pharmacy networks have built automated approval workflows that reduce time-to-therapy initiation for TNF-alpha and IL-17 inhibitors.
Market Restraints
- Cold-chain distribution costs:Biologic injectables requiring 2-8°C controlled logistics impose infrastructure investments that limit dispensing site density in rural United States markets.
- EMA biosimilar interchangeability friction:Divergent substitution rules across EU member states create pricing uncertainty and delay volume migration from originator molecules.
- Topical corticosteroid generic saturation:Mature margin pools in mild-to-moderate disease segments face continuous price erosion from multi-source competition.
Strategic Opportunities
- Japan's aging dermatology patient base:METI reimbursement reforms are expanding biologic coverage for elderly psoriasis populations previously managed with phototherapy alone.
- JAK-STAT oral convergence:Small-molecule inhibitors targeting shared downstream pathways offer patient-administered alternatives to injectable biologics in atopic dermatitis.
- Direct-to-patient pharmacy channels:Home infusion and self-injection training programs are bypassing traditional clinic-based administration in United States commercial plans.
Industry Challenges
- Immunology-specialized clinical trial workforce scarcity:Recruitment of investigators experienced in IL-targeting protocol design lags behind pipeline expansion, extending study startup timelines.
- ISO 14155 compliance complexity:Medical device trial restructuring requirements for combination biologic-delivery systems impose documentation burdens on dermatology sponsors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inflammatory Skin Diseases Treatment Market |
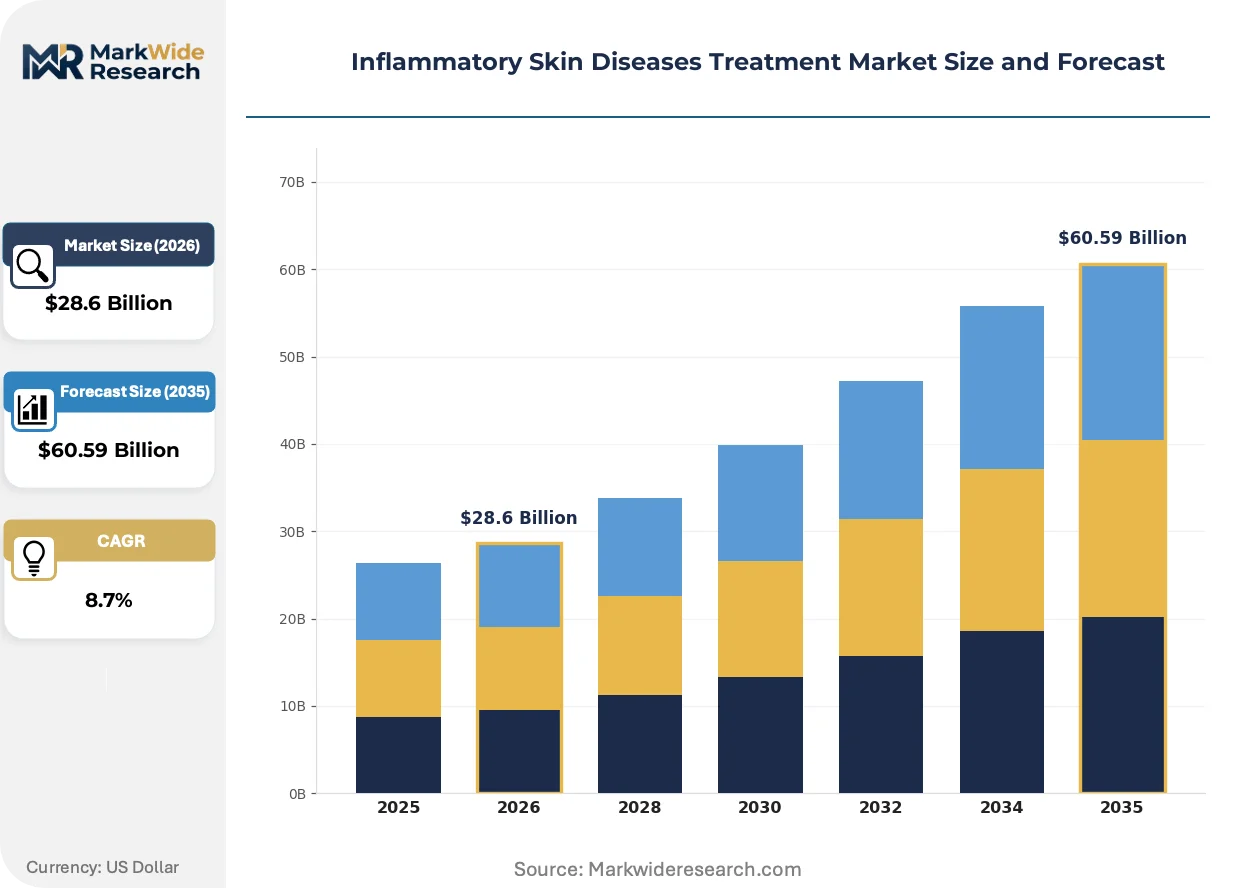
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Topical Retinoids, Calcineurin Inhibitors, Phototherapy Delivery Mode: Topical, Systemic, Injectable, Oral End User: Hospitals, Dermatology Clinics, Home Care, Pharmacies Indication: Eczema, Psoriasis, Dermatitis, Rosacea |
| Companies Covered | Novartis, LEO Pharma, AbbVie, Johnson & Johnson, Pfizer, Sanofi, Eli Lilly and Company, Regeneron Pharmaceuticals, Amgen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inflammatory Skin Diseases Treatment Market Evolving Landscape
Biologics targeting discrete interleukin pathways are fragmenting the inflammatory skin disease treatment landscape, displacing the historical TNF-alpha dominance with more precise immunomodulation. This molecular precision is reshaping trial endpoints, reimbursement criteria, and prescriber education requirements across major markets.
Next-generation IL-17 and IL-23 inhibitors are fragmenting the biologic competitive set, offering rapid onset and durable maintenance dosing that compresses treatment intervals. Dermatology clinics in Germany and the United States are prioritizing these agents for biologic-naïve patients, forcing earlier-generation therapies into later-line positioning. The result is a tiered access hierarchy where mechanism-of-choice drives formulary placement.
EMA's evolving biosimilar interchangeability guidance is fragmenting substitution policy consistency across European markets, creating parallel access pathways that diverge from FDA automatic substitution rules. Manufacturers must now navigate member-state-specific pharmacy-level substitution permissions and physician notification requirements. This regulatory fragmentation favors originator portfolio defenders with localized market access capabilities.
Patient-driven channel preferences are fragmenting traditional site-of-care models, with United States commercial plans expanding home administration benefits for self-injectable biologics. Specialty pharmacies are capturing dispensing volume from hospital outpatient departments by integrating nurse training and adherence monitoring into direct distribution. This channel shift compresses institutional pharmacy margins while elevating cold-chain logistics requirements for home delivery networks.
Inflammatory Skin Diseases Treatment Market Segmentation
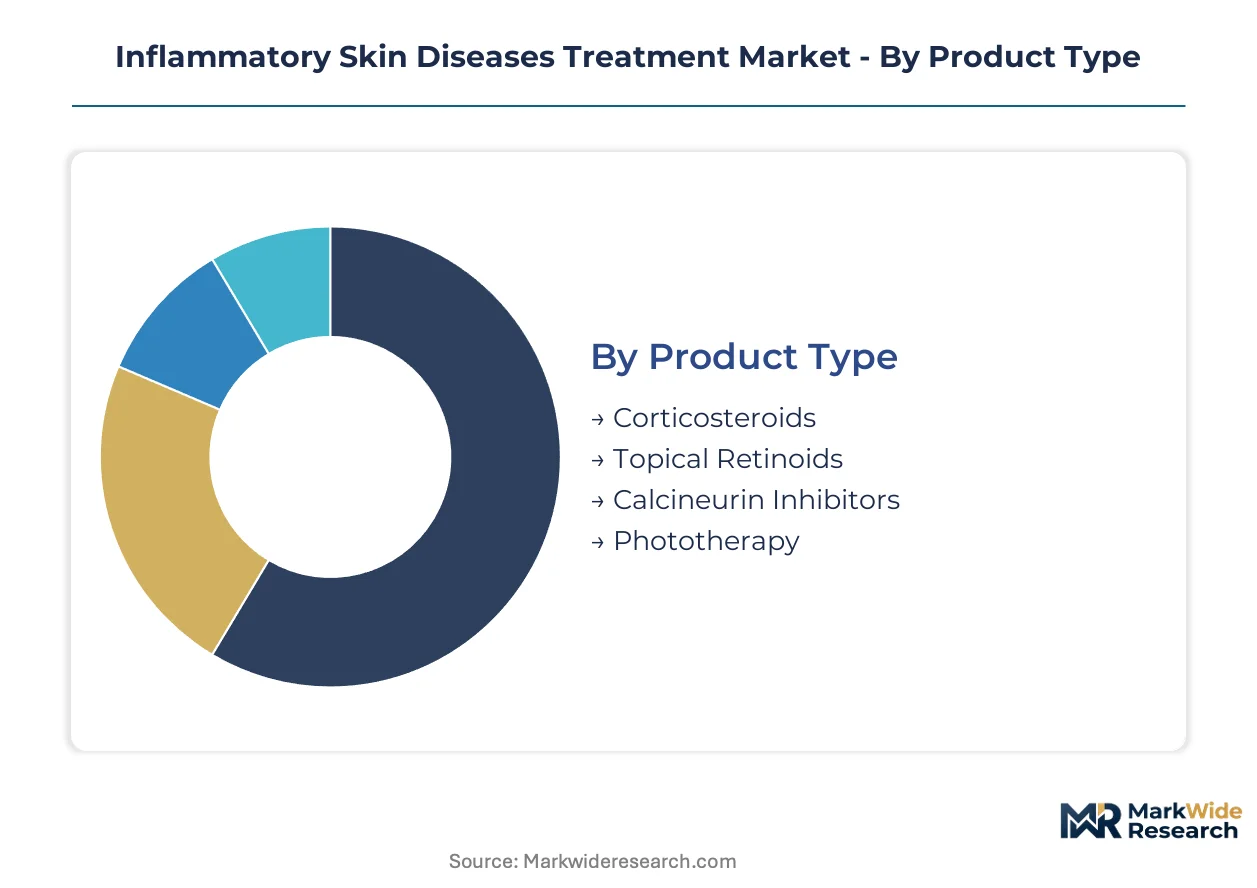
Segmentation in the inflammatory skin disease treatment market reveals how therapeutic modality, administration route, and care setting interact to determine patient access and commercial viability. Understanding these dimensions exposes where biologic innovation concentrates versus where generic commoditization erodes returns.
Product Type:
Domestic formulation capabilities dominate corticosteroid and retinoid supply, while calcineurin inhibitors and advanced phototherapy systems flow through specialized import channels.
- Corticosteroids:Hydrocortisone, betamethasone, and clobetasol formulations constitute the foundational anti-inflammatory arsenal for mild-to-moderate disease. Demand concentrates in United States retail pharmacies and Indian hospital formularies where cost-containment protocols prioritize generic substitution.
- Topical Retinoids:Tazarotene and adapalene derivatives modulate keratinocyte proliferation and inflammation in psoriasis and acneiform presentations. Prescription volumes are climbing fastest in German dermatology clinics adopting combination protocols with biologic maintenance therapy.
- Calcineurin Inhibitors:Tacrolimus and pimecrolimus macrolactams serve steroid-sparing roles in facial and intertriginous atopic dermatitis.
- Phototherapy:Narrowband UVB and excimer laser systems deliver targeted immunosuppression without systemic exposure.
Corticosteroids command the established base. The steepest expansion runs through calcineurin inhibitors.
Delivery Mode:
Cost tier stratification separates premium biologic injectables from commoditized topical and oral alternatives, with systemic routes occupying a contracting middle ground.
- Topical:Creams, ointments, gels, and foams deliver active agents directly to affected skin with minimal systemic absorption. Patient-administered application in United States home care settings drives volume, though adherence monitoring gaps limit outcomes in chronic plaque psoriasis.
- Injectable:Subcutaneous and intravenous biologics targeting IL-17, IL-23, and TNF-alpha achieve superior disease clearance in moderate-to-severe cohorts. Japanese and United States specialty pharmacy networks capture dispensing value through cold-chain logistics and nurse training programs.
- Systemic:Oral methotrexate, cyclosporine, and acitretin retain niche positioning for biologic-ineligible patients.
- Oral:Small-molecule JAK inhibitors and apremilast offer patient-preferred alternatives to injection in atopic dermatitis and psoriatic arthritis.
Topical formulations anchor volume across mild disease. Injectable biologics are gaining share fastest in moderate-to-severe segments.
End User:
Volume concentration varies sharply by therapy complexity, with biologic initiation restricted to sites possessing infusion infrastructure and prior authorization expertise.
- Dermatology Clinics:Dedicated cutaneous disease centers in Germany and the United States concentrate biologic prescribing, phototherapy administration, and clinical trial enrollment. Staffing shortages in rural United States markets limit expansion despite patient demand.
- Hospitals:Academic medical centers manage complex cases with comorbid psoriatic arthritis or erythrodermic crisis requiring multidisciplinary coordination.
- Home Care:Self-injection training programs and direct-to-patient pharmacy distribution are displacing clinic-based administration in United States commercial plans.
- Pharmacies:Retail and specialty pharmacy networks handle topical dispensing and oral systemic fulfillment.
Dermatology clinics capture the highest-value patient flows. Home care channels are expanding most quickly.
Indication:
Maturity gradients separate well-established psoriasis biologic markets from underpenetrated atopic dermatitis and rosacea segments where pipeline assets are reshaping standards of care.
- Psoriasis:Plaque, guttate, and pustular variants drive the majority of biologic utilization, with PASI 90/100 endpoints now standard for IL-23 and IL-17 inhibitors. United States and German prescribing concentrates in dermatology clinics with phototherapy backup.
- Eczema:Atopic dermatitis in pediatric and adult populations represents the fastest-expanding biologic indication as dupilumab and tralokinumab penetrate previously topical-managed cohorts.
- Dermatitis:Contact and seborrheic variants remain predominantly topical-managed with limited biologic penetration.
- Rosacea:Papulopustular and erythematotelangiectatic subtypes lack approved biologic options, constraining treatment to oral tetracyclines and topical agents.
Psoriasis commands the established biologic base. Eczema is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty pharmacy networks and dermatology clinic density concentrate biologic prescribing power in markets with mature prior authorization infrastructure and cold-chain logistics capabilities.
United States
Commercial insurance plans and Medicare Part D drive biologic utilization through specialty pharmacy networks in urban corridors. FDA accelerated approval pathways compress entry timelines for interleukin-targeting therapies. Boston and New York Metro dermatology clusters concentrate clinical trial enrollment for IL-23 and IL-17 inhibitors.
Germany
Dermatology clinic chains and statutory health insurance funds anchor biologic prescribing in psoriasis and atopic dermatitis. EMA dermatology-specific efficacy endpoints streamline PASI-based reimbursement decisions. The Rhine-Ruhr and Bavarian medical centers prioritize phototherapy-biologic combination protocols.
Japan
An aging psoriasis patient base and METI reimbursement reforms expand biologic coverage beyond phototherapy-managed cohorts. PMDA consultation pathways accelerate IL-targeting therapy reviews for moderate-to-severe disease. Tokyo and Osaka dermatology departments concentrate biologic-naïve patient recruitment.
United Kingdom
NICE technology appraisals and NHS England commissioning frameworks gate biologic access through severity-weighted criteria. MHRA post-Brexit regulatory autonomy enables divergence from EMA labeling timelines. London and Manchester academic medical centers anchor biologic initiation for complex psoriatic arthritis cases.
India
CDSCO biosimilar approvals and domestic manufacturing capabilities expand access to TNF-alpha and IL-17 alternatives at reduced cost points. Government hospital formularies prioritize corticosteroid and calcineurin inhibitor procurement. Mumbai and Hyderabad dermatology centers concentrate biologic trial activity for tropical phenotype adaptations.
Inflammatory Skin Diseases Treatment Market Competitive Landscape
Player mix skews toward integrated immunology specialists with established injectable portfolios and dermatology-focused biotech developers with rapid interleukin pathway progression. The competitive set fragments across originator biologics, biosimilar challengers, and oral small-molecule entrants targeting JAK-STAT signaling. Two strategic archetypes dominate: diversified pharmaceutical conglomerates leveraging cross-indication immunology platforms, and targeted biologic developers with concentrated dermatology pipelines. Competitive moves concentrate on mechanism-of-choice positioning for biologic-naïve patients and direct-to-patient pharmacy channel expansion.
Within the integrated immunology tier, Novartis and AbbVie exemplify portfolio breadth across psoriasis, atopic dermatitis, and psoriatic arthritis indications. Eli Lilly and Company occupies a position on the rapid pipeline progression vector, with IL-23 and IL-17 assets capturing biologic-naïve prescribing in United States and German dermatology clinics.
| Leading Market Players |
|---|
| Novartis |
| LEO Pharma |
| AbbVie |
| Johnson & Johnson |
| Pfizer |
| Sanofi |
| Eli Lilly and Company |
| Regeneron Pharmaceuticals |
| Amgen |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day cold-chain inventory cycles in biologic injectables concentrate pricing power with United States specialty pharmacy networks that control prior authorization workflows and patient onboarding. This lead-time band ties directly to EMA biosimilar interchangeability friction, where divergent substitution rules fragment European pricing while FDA accelerated approval compresses originator premium windows.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient indexation dominate biologic procurement between United States payers and specialty pharmacy networks. Three-tier pricing structure across premium biologics, authorized biosimilars, and multi-source small molecules reflects mechanism-of-choice positioning and cold-chain service bundling. Price erosion runs through mature corticosteroid tiers as Indian and Chinese generic manufacturers expand hospital formulary penetration. Biologic-naïve patient segments show lowest price sensitivity, while topical-managed mild-to-moderate cohorts drive volume through retail pharmacy substitution protocols.
Supply Chain Analysis
Strategic stockpiling of IL-targeting biologics prevails among United States specialty pharmacies managing prior authorization delays, while German dermatology clinics prefer just-in-time delivery synchronized with patient appointment scheduling. Active pharmaceutical ingredient production concentrates in India, China, and Switzerland for small-molecule corticosteroids and calcineurin inhibitors, with fill-finish biologic capacity centered in United States, Germany, and Japan. Supply chain risk rests on single-source vulnerability for monoclonal antibody cell lines and EMA regulatory divergence blocking automatic substitution. Distribution runs through cold-chain validated specialty pharmacy networks with direct-to-patient home delivery expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biologic-delivery system interoperability and specialty pharmacy platform consolidation are shifting competitive advantage toward ecosystem orchestrators that control patient data flows and reimbursement navigation.
For Market Incumbents: Shield IL-23 and IL-17 franchise value by deepening formulary exclusivity through real-world evidence generation and prior authorization automation partnerships with United States specialty pharmacy networks. Accelerate backward integration into fill-finish manufacturing to reduce dependency on contract manufacturing organization capacity constraints. Defensive patent estate fortification around subcutaneous delivery devices blocks biosimilar automatic substitution pathways.
For New Entrants and Emerging Players: Lead with JAK-STAT oral alternatives in atopic dermatitis, where patient preference for non-injectable administration creates white-space positioning against established biologic incumbents. Target Japan's aging psoriasis population and METI reimbursement expansion as the most penetrable geography for biologic-naïve conversion. Direct-to-patient pharmacy channel partnerships bypass dermatology clinic gatekeeper concentration in United States urban corridors.
For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because specialty pharmacy networks and patient data infrastructure determine prescription capture more than molecule innovation alone. Acquisition targets should concentrate on dermatology-focused biotech developers with rapid IL-targeting pipelines and established United States prior authorization relationships. Watch FDA biosimilar interchangeability determinations as the signal indicating originator pricing power inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| IL-23 Pathway Expansion | Captures biologic-naïve prescribing in United States and German dermatology clinics through superior PASI 90/100 endpoints. |
| Prior Authorization Automation | Reduces time-to-therapy initiation for TNF-alpha and IL-17 inhibitors through United States specialty pharmacy workflow integration. |
| Direct-to-Patient Pharmacy Channel | Bypasses clinic-based administration by integrating nurse training and cold-chain home delivery into commercial plan benefits. |
| Biosimilar Interchangeability Defense | Navigates EMA member-state substitution divergence through localized market access capabilities and physician notification systems. |
| JAK-STAT Oral Development | Addresses patient preference for non-injectable alternatives in atopic dermatitis through small-molecule downstream pathway targeting. |
Research Methodology
Initial hypotheses were tested against primary input from dermatology clinic directors, specialty pharmacy network executives, regulatory affairs leads at biologic developers, and United States payer formulary managers, then refined through secondary validation. FDA accelerated approval pathway documentation, EMA dermatology-specific efficacy endpoint guidance, ClinicalTrials.gov protocol registries, and formulary database audits supplied triangulation anchors. Bottom-up patient flow modeling and top-down revenue reconciliation across product type, delivery mode, and end user dimensions ensured segmentation integrity.
Variance decomposition across treatment line, administration route, patient severity tier, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from patient population epidemiology, biologic penetration rate trajectories, and pricing elasticity assumptions by therapy class. Forecast inputs incorporated ISO 14155 trial restructuring cost impacts and cold-chain logistics capacity expansion timelines.
Underlying assumptions cover EMA biosimilar interchangeability progression, United States specialty pharmacy network consolidation, and IL-targeting pipeline approval velocities, with deviation risk concentrated in regulatory substitution policy divergence and immunology-specialized investigator recruitment bottlenecks. Revision becomes warranted when FDA automatic substitution determinations for dermatology biologics cross thresholds that alter originator pricing power calculations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Alopecia Treatment (Hair Loss) Market
Dermatology
Global Dermatitis Herpetiformis Market
Dermatology
Dermatology Cryosurgery Units Market
Dermatology
UK Scar Treatment Market
Dermatology
Global Online Dermatology Consultation Market
Dermatology
Seborrheic Keratosis Treatment Market
Dermatology
Acne Scar Treatment Market
Dermatology
Chronic Spontaneous Urticaria Market
Dermatology
Atopic Dermatitis Therapeutics Market
Dermatology
Global Onychomycosis Market
Dermatology
Darier Disease Drugs Market
Dermatology
Immunodermatology Market
Dermatology
Erythema Treatment Market
Dermatology
Scar Treatment Oils Market
Dermatology
Rosacea Treatment Market
Dermatology
Dermatophytic Onychomycosis Treatment Market