
 Medicinal Mushrooms Market | 2026-2036
Medicinal Mushrooms Market Size, Share, and Industry Trends Forecast 2026-2036
Medicinal Mushrooms Market Outlook
China is reconfiguring global supply dynamics through large-scale Ganoderma lucidum cultivation zones in Fujian and Zhejiang provinces. Four Sigmatic leverages Nordic branding and direct-to-consumer channels to sustain premium positioning in functional beverages. Fungi Perfecti anchors Pacific Northwest production with Paul Stamets-founded mycology expertise and organic certification depth. Om Mushroom Superfood competes through whole-food powder formulations and broad retail distribution across North American mass-market channels.
Medicinal mushrooms comprise fungal fruiting bodies and mycelial biomass standardized for bioactive compounds including beta-glucans, triterpenoids, and erinacines, cultivated via solid-state fermentation or hardwood log inoculation for therapeutic and wellness applications. Reishi and Lion's Mane extracts command the highest margin pools in the product type dimension due to cognitive and adaptogenic positioning in premium supplement lines. Powder and capsule forms dominate volume throughput, though tincture formats are capturing fastest growth in specialty wellness retail and practitioner channels where bioavailability claims differentiate positioning. Health supplements and functional foods represent the twin demand pillars, with cosmetics applications emerging through mycelium-derived ferment filtrates in Korean and French skincare formulations.
FDA Current Good Manufacturing Practice regulations and EFSA novel food authorization pathways shape ingredient compliance costs and market access timelines for new entrants. USDA organic certification and EU organic regulation standards create tiered supply segmentation between conventional and certified organic material streams. Stakeholders must monitor evolving pharmacovigilance requirements from Health Canada and Australia's TGA as these regulators expand post-market surveillance frameworks for adaptogenic and nootropic mushroom claims.
Market Dynamics
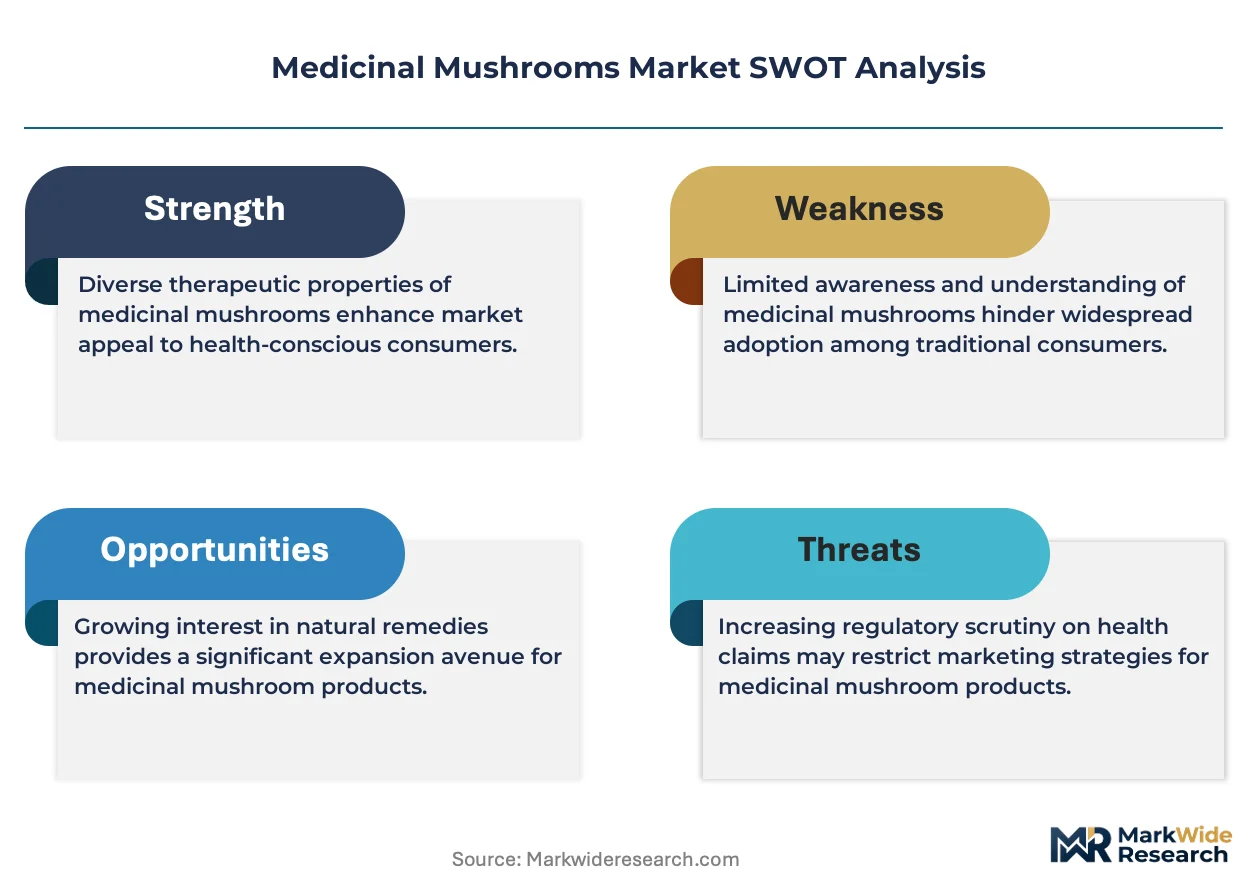
Certification requirements from FDA and EFSA are compressing supplier margins while concentrating procurement among vertically integrated cultivators with in-house extraction capabilities.
Growth Catalysts
- EFSA Novel Food Pathways:Streamlined authorization for mycelial biomass ingredients accelerates European market entry for fermented mushroom products.
- Cognitive Wellness Positioning:Lion's Mane extracts penetrate practitioner and specialty retail channels through bioavailability-focused tincture formats.
- Pacific Northwest Cultivation Clusters:Integrated hardwood log inoculation and processing infrastructure in Oregon and Washington supply premium organic grades to domestic nutraceutical manufacturers.
Market Restraints
- Hardwood Substrate Volatility:Oak and maple log availability fluctuates with North American timber harvest cycles and competing biomass demand.
- Fujian-Zhejiang Supply Concentration:Ganoderma lucidum cultivation zones in coastal China control upstream raw material pricing for global Reishi extract supply.
- Dual Extraction Cost Structure:Separate hot water and ethanol processing steps for beta-glucan and triterpenoid standardization elevate unit economics above single-extract alternatives.
Strategic Opportunities
- Korean and French Cosmetics Integration:Mycelium-derived ferment filtrates penetrate premium skincare formulations through adaptogenic and anti-aging positioning.
- USDA Organic Certification Tier:Certified organic material streams command 15-30% price premiums over conventional extracts in North American supplement channels.
- Direct-to-Consumer Functional Beverages:Mushroom-infused coffee and cacao formats bypass traditional retail markups through subscription and e-commerce models.
Industry Challenges
- Mycology Expertise Scarcity:Cultivation science and solid-state fermentation engineering talent pools remain shallow relative to scaling production targets.
- Health Canada Pharmacovigilance Expansion:Post-market surveillance frameworks for adaptogenic claims extend compliance timelines and documentation burdens.
- Bioactive Standardization Complexity:Beta-glucan content variability across fruiting body harvests complicates batch consistency for pharmaceutical-grade applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medicinal Mushrooms Market |
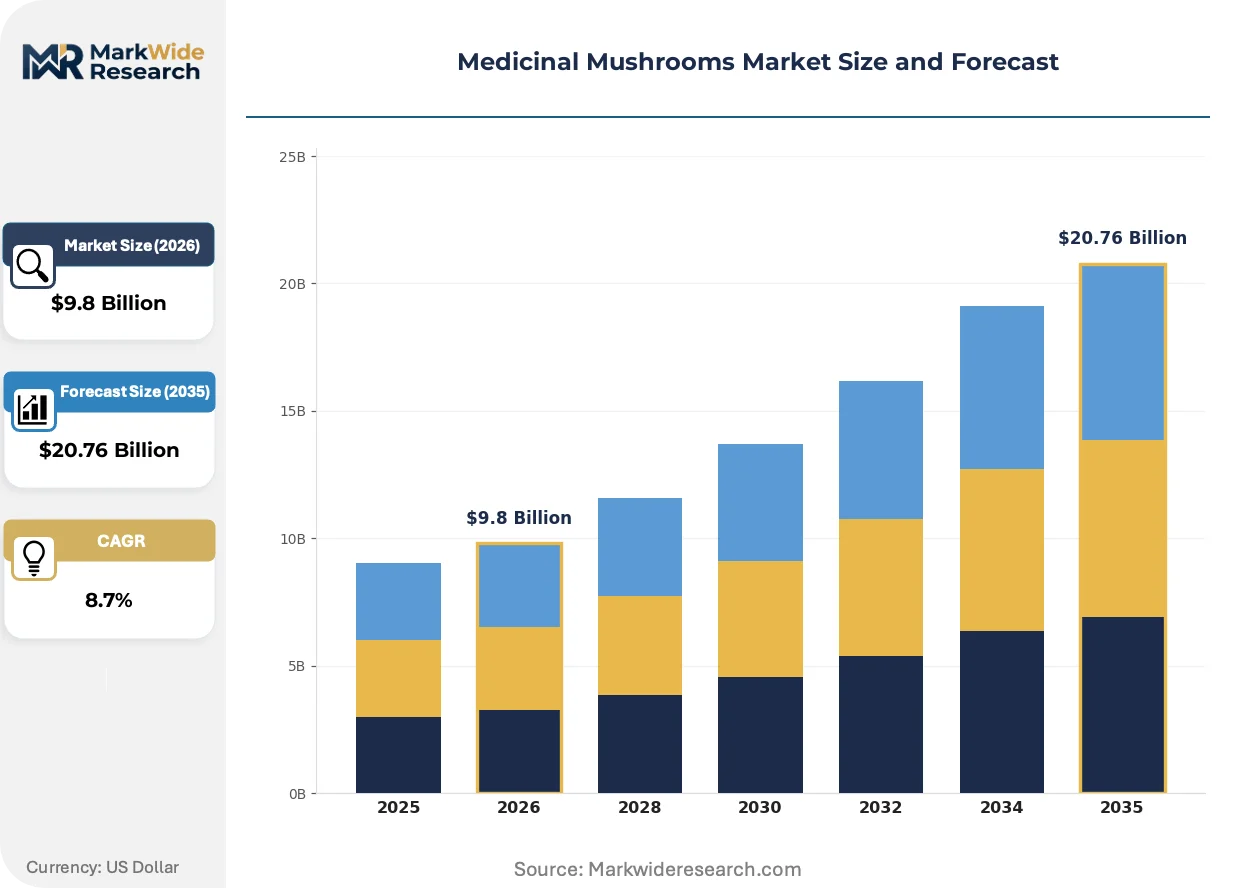
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.76 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reishi, Chaga, Lion's Mane, Shiitake Form: Powder, Capsule, Extract, Tincture Application: Health Supplements, Functional Foods, Cosmetics, Beverages Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Supermarkets |
| Companies Covered | Four Sigmatic, Fungi Perfecti, Om Mushroom Superfood, Real Mushrooms, Nammex, Host Defense, Mushroom Wisdom, DXN Holdings Bhd, Life Cykel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medicinal Mushrooms Market Strategic Shifts
Extraction technology and regulatory science are converging to reshape product formats and compliance architectures across the value chain.
Ultrasonic-assisted extraction is migrating from laboratory-scale R&D to commercial production lines, reducing solvent volumes and processing times while preserving heat-sensitive erinacines and triterpenoids. Premium supplement manufacturers in Germany and the United States adopt these systems to support bioavailability claims in practitioner-channel positioning. The technology is compressing cost structures for dual-extract products previously confined to artisanal production scales.
EFSA's evolving novel food assessments for fungal mycelium establish precedent for biomass-based ingredients distinct from traditional fruiting body extracts. The regulatory friction creates tiered compliance pathways where mycelial products face extended safety evaluation timelines. European manufacturers respond by segregating R&D pipelines and building dedicated fermentation facilities to isolate novel food dossier preparation from conventional extract operations.
Practitioner-channel purchasing is consolidating around third-party tested, certificate-of-analysis-backed supply relationships that displace commodity spot buying. Functional medicine clinics and integrative health practitioners in the Pacific United States and German-speaking Europe now require chromatographic verification of beta-glucan content and heavy metal screening. This behavioral shift elevates supplier qualification costs while compressing margins for undifferentiated bulk extract distributors.
Medicinal Mushrooms Market Segmentation
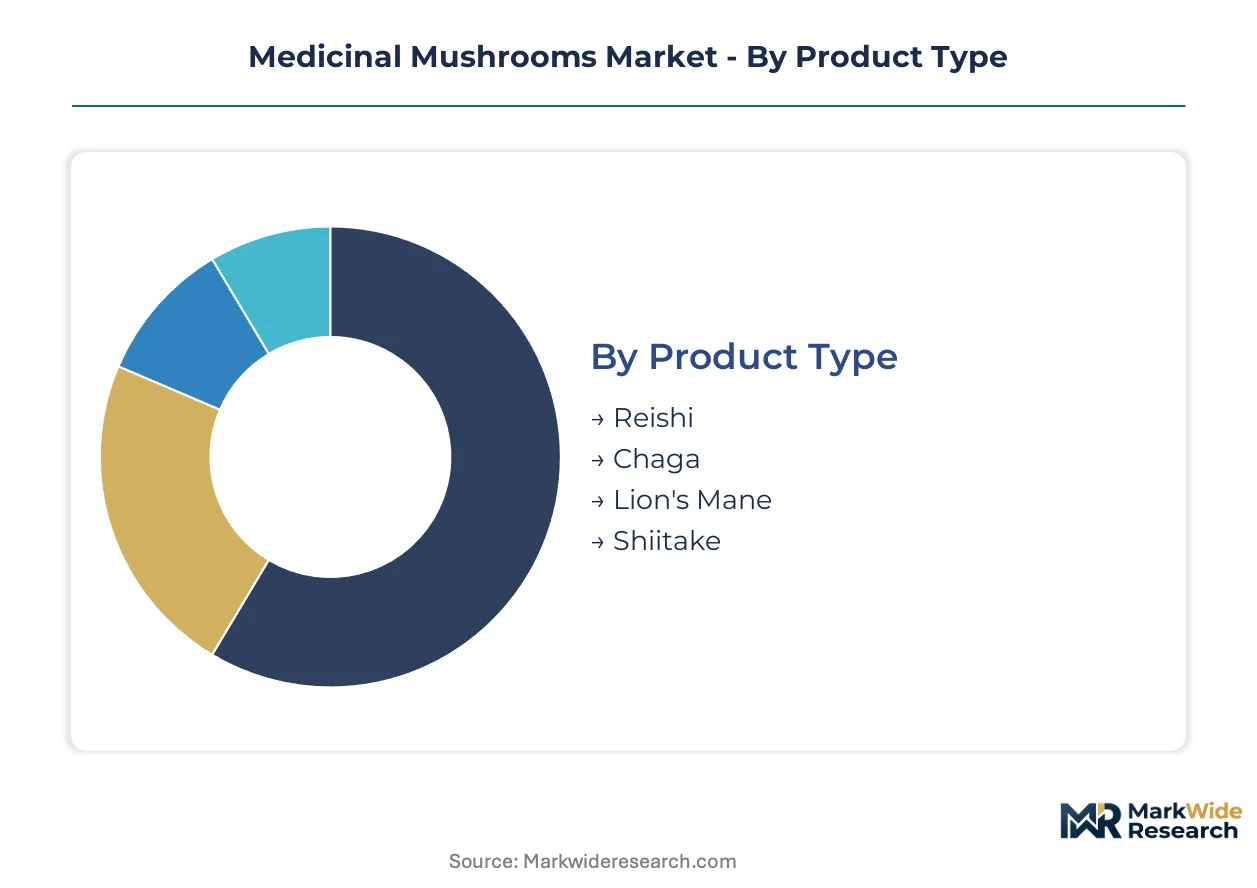
Medicinal mushroom segmentation reflects divergent supply chain configurations and compliance architectures across therapeutic applications. Each dimension carries distinct margin structures and regulatory burdens that reshape procurement patterns among nutraceutical manufacturers.
Product Type:
Species selection determines extraction methodology, bioactive standardization targets, and geographic sourcing concentration for downstream formulations.
- Reishi:Ganoderma lucidum fruiting bodies and mycelial biomass supply triterpenoid and beta-glucan fractions for adaptogenic positioning. Fujian and Zhejiang cultivation zones in China control upstream raw material pricing for global extract supply, creating procurement concentration risk for European and North American manufacturers.
- Lion's Mane:Hericium erinaceus delivers erinacines and hericenones for cognitive wellness applications in practitioner channels. Pacific Northwest hardwood log inoculation clusters in Oregon and Washington supply premium organic grades to domestic nutraceutical formulators seeking chromatographic verification of bioactive content.
- Chaga:Inonotus obliquus sclerotium harvested from birch forests in Nordic and Russian boreal zones provides antioxidant-rich extracts for specialty wellness retail.
- Shiitake:Lentinula edodes cultivated via solid-state fermentation yields lentinan-standardized fractions for immune-support formulations in East Asian and North American supplement channels.
The dominant share belongs to Reishi, while Lion's Mane is closing the gap fastest.
Form:
Processing intensity and bioavailability claims segment manufacturing investment and channel access requirements.
- Extract:Dual-processed hot water and ethanol fractions achieve beta-glucan and triterpenoid standardization for pharmaceutical-grade applications. German and United States nutraceutical manufacturers expand procurement of certified organic grades for immune-support formulations, though unit economics exceed single-process alternatives.
- Tincture:Alcohol-based suspensions target practitioner and specialty wellness channels where bioavailability claims differentiate positioning. Ultrasonic-assisted extraction technology is compressing cost structures for premium tincture production previously confined to artisanal scales.
- Powder:Whole-food and milled fruiting body formats serve mass-market supplement channels with lower processing overhead.
- Capsule:Encapsulated powders and standardized extracts dominate volume throughput in retail pharmacy and supermarket placements.
Extract formats command the highest margin tier, with tincture gaining share most steeply in practitioner channels.
Application:
End-use specifications drive divergent purity standards and regulatory pathway requirements across the value chain.
- Health Supplements:Standardized extracts in capsule and powder formats dominate revenue concentration. FDA Current Good Manufacturing Practice regulations and EFSA novel food authorization pathways shape ingredient compliance costs and market access timelines for new entrants.
- Cosmetics:Mycelium-derived ferment filtrates penetrate Korean and French skincare formulations through adaptogenic and anti-aging positioning. EFSA's evolving novel food assessments for fungal mycelium establish precedent for biomass-based ingredients distinct from traditional fruiting body extracts.
- Functional Foods:Mushroom-infused coffee and cacao formats bypass traditional retail markups through subscription and direct-to-consumer e-commerce models.
- Beverages:Ready-to-drink functional formulations leverage Nordic branding and direct-to-consumer channels to sustain premium positioning.
Health Supplements retains the largest application share, while Cosmetics is expanding most quickly through ferment filtrate innovation.
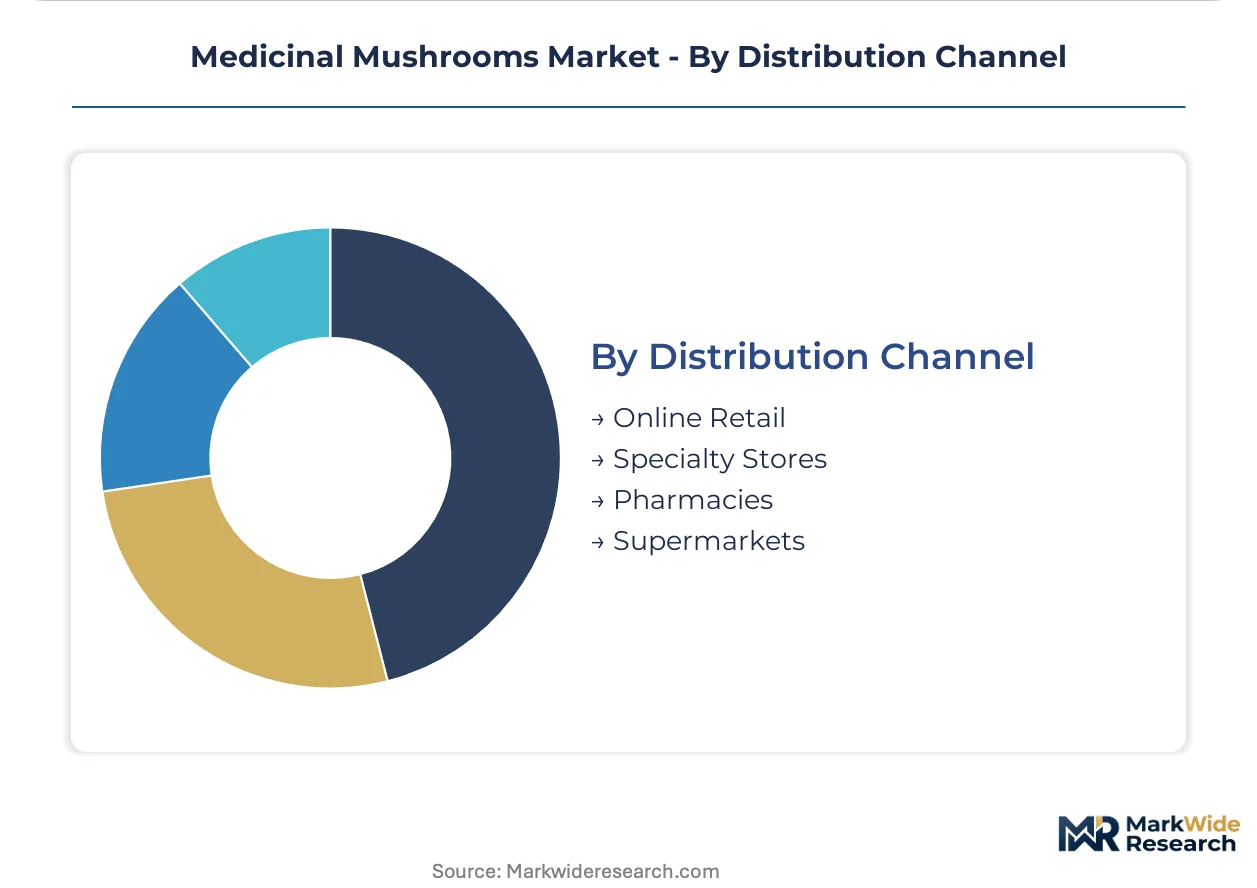
Distribution Channel:
Channel selection determines qualification depth, margin retention, and customer relationship architecture.
- Specialty Stores:Practitioner-channel purchasing consolidates around third-party tested, certificate-of-analysis-backed supply relationships that displace commodity spot buying. Functional medicine clinics in the Pacific United States and German-speaking Europe require chromatographic verification and heavy metal screening.
- Online Retail:Direct-to-consumer functional beverage subscriptions and e-commerce platforms bypass traditional retail markups. USDA organic certification tiers command price premiums over conventional extracts in North American supplement channels.
- Pharmacies:Over-the-counter capsule and extract placements serve mainstream wellness consumers with established brand recognition.
- Supermarkets:Mass-market powder and functional food placements compete on shelf price with limited bioactive standardization claims.
Specialty Stores hold the leading position, with Online Retail climbing the fastest through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. German and United States buyers prioritize certified organic extracts for practitioner-channel formulations, while Chinese procurement concentrates on bulk Ganoderma lucidum biomass for domestic processing and re-export.
United States
Pacific Northwest cultivation clusters in Oregon and Washington supply premium organic grades to domestic nutraceutical manufacturers. FDA Current Good Manufacturing Practice regulations compress supplier margins while concentrating procurement among vertically integrated cultivators. Hardwood log inoculation infrastructure anchors upstream supply for Lion's Mane and Reishi extract production.
Germany
German nutraceutical manufacturers expand procurement of certified organic mushroom extracts for immune-support formulations. EFSA novel food authorization pathways shape ingredient compliance costs and extend market access timelines for new entrants. Ultrasonic-assisted extraction technology adoption is compressing cost structures for dual-extract products in Baden-Württemberg processing facilities.
China
Fujian and Zhejiang provinces control upstream raw material pricing for global Reishi extract supply through large-scale Ganoderma lucidum cultivation zones. NMPA dietary supplement guidelines and dual carbon goals are tightening purity and environmental standards across coastal processing hubs. Solid-state fermentation capacity concentrates in these zones for domestic and export biomass production.
Canada
Health Canada pharmacovigilance expansion extends compliance timelines for adaptogenic and nootropic mushroom claims in the practitioner channel. British Columbia and Ontario host specialty wellness retail consolidation around third-party tested supply relationships. Chromatographic verification requirements are displacing commodity spot buying among functional medicine clinics.
Australia
TGA post-market surveillance frameworks for adaptogenic claims elevate documentation burdens for imported extract suppliers. Practitioner-channel purchasing concentrates in Sydney and Melbourne metro areas around certificate-of-analysis-backed supply relationships. Korean and French cosmetics integration is creating export demand for mycelium-derived ferment filtrates from Australian cultivators.
Medicinal Mushrooms Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. Vertically integrated cultivators with in-house extraction capabilities capture premium-tier procurement from German and United States nutraceutical manufacturers, while bulk biomass traders serve commodity extract processors in coastal China. Three archetypes dominate: Pacific Northwest organic-certified cultivators, Nordic direct-to-consumer functional beverage brands, and Fujian-Zhejiang biomass aggregators. Competitive moves center on backward integration into hardwood substrate cultivation and ultrasonic-assisted extraction technology licensing.
Within the premium organic tier, Fungi Perfecti anchors Pacific Northwest production with Paul Stamets-founded mycology expertise and organic certification depth. Four Sigmatic exemplifies Nordic branding and direct-to-consumer channel strategy in functional beverages. Om Mushroom Superfood occupies a position in whole-food powder formulations and broad retail distribution across North American mass-market channels.
| Leading Market Players |
|---|
| Four Sigmatic |
| Fungi Perfecti |
| Om Mushroom Superfood |
| Real Mushrooms |
| Nammex |
| Host Defense |
| Mushroom Wisdom |
| DXN Holdings Bhd |
| Life Cykel |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Fujian-Zhejiang Reishi biomass concentrates procurement leverage among Chinese cultivators while simultaneously compressing margin pools for North American and European extract processors, forcing a bifurcated pricing architecture that rewards captive hardwood log cultivation in the Pacific Northwest and penalizes spot-market biomass buyers.
Pricing Analysis
Geographic price spreads between Fujian-Zhejiang bulk biomass and Pacific Northwest certified organic extracts reach 40-60% at the ingredient level, with three-tier pricing structure across premium, standard, and economy levels anchored by USDA organic certification depth, chromatographic verification, and dual-extraction processing intensity. Price differentiation separates certified organic grades from conventional material streams, with subscription-based direct-to-consumer functional beverages capturing margin retention advantages over mass-market powder distributors. Cost compression in conventional extract tiers is intensifying because EFSA novel food dossier preparation extends compliance timelines and elevates documentation burdens. Mass-market supermarket buyers exhibit highest price sensitivity, while practitioner-channel clinics in German-speaking Europe and the Pacific United States demonstrate lowest sensitivity due to certificate-of-analysis requirements.
Supply Chain Analysis
Hardwood substrate availability from North American timber harvests draws from oak and maple log cycles in Oregon and Washington, birch forests in Nordic zones, and competing biomass demand from construction and bioenergy sectors. Raw material dependencies center on Ganoderma lucidum fruiting bodies from Fujian-Zhejiang cultivation zones, Hericium erinaceus mycelial biomass from Pacific Northwest solid-state fermentation facilities, and Inonotus obliquus sclerotium from Russian and Nordic boreal harvests. Single-source vulnerability concentrates in Chinese Reishi supply, where NMPA dietary supplement guidelines and dual carbon goals are tightening environmental standards across coastal processing hubs. Distribution runs through vertically integrated cultivators with in-house extraction capabilities serving German and United States nutraceutical manufacturers, supplemented by bulk biomass traders supplying commodity extract processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase driven by post-pandemic practitioner-channel consolidation around third-party tested supply relationships, with procurement patterns normalizing toward pre-disruption qualification depths after temporary commodity spot-buying spikes.
For Market Incumbents: Build regulatory moat depth through preemptive EFSA novel food dossier submission for mycelial biomass ingredients, isolating fermentation operations from conventional extract production to streamline compliance pathways. Anchor backward integration into Pacific Northwest hardwood log cultivation to secure organic-certified substrate supply against timber harvest volatility. Defend against ultrasonic-assisted extraction technology licensing competition by accelerating in-house adoption in Baden-Württemberg and Oregon processing facilities.
For New Entrants and Emerging Players: Build out white-space presence in Korean and French cosmetics channels through mycelium-derived ferment filtrate supply relationships, where adaptogenic skincare positioning remains underpenetrated relative to supplement saturation. Target practitioner-channel tincture formats in German-speaking Europe as the most penetrable segment, leveraging bioavailability claims and chromatographic verification to displace commodity bulk distributors. Pursue direct-to-consumer subscription models for functional beverages as the primary go-to-market angle, bypassing traditional retail markup structures.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated mid-cap specialists with captive organic certification and in-house dual-extraction capabilities over pure-play biomass traders. Long-term viability across the projection horizon rests on regulatory science depth and cultivation science talent retention rather than commodity scale. Prioritize acquisition targets combining Pacific Northwest hardwood log infrastructure with Paul Stamets-tier mycology expertise. Monitor Health Canada pharmacovigilance expansion timelines as the critical inflection signal for practitioner-channel compliance cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| USDA Organic Certification Investment | Certified organic material streams command sustained price premiums in North American supplement channels. |
| Ultrasonic-Assisted Extraction Licensing | German and United States manufacturers adopt these systems to support bioavailability claims in practitioner positioning. |
| EFSA Novel Food Dossier Preparation | Streamlined authorization for mycelial biomass ingredients accelerates European market entry timelines. |
| Hardwood Log Cultivation Expansion | Pacific Northwest clusters in Oregon and Washington supply premium organic grades to domestic nutraceutical formulators. |
| Direct-to-Consumer Subscription Launch | Mushroom-infused coffee and cacao formats bypass traditional retail markups through e-commerce models. |
Study Parameters
A spread of perspectives from cultivation science directors, nutraceutical procurement leads, regulatory affairs specialists at EFSA and FDA, functional medicine clinic purchasing managers, and cosmetics R&D formulators converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against USDA organic certification databases, EFSA novel food submission records, FDA dietary supplement enforcement reports, and customs trade data for Ganoderma lucidum and Hericium erinaceus biomass flows. Bottom-up triangulation across species-level production estimates and top-down reconciliation against end-use formulation demand anchored volume and value outputs.
Demand-supply balance modeling across the analysis window integrated species segmentation by bioactive compound profile, form factor processing intensity, application purity requirements, and channel qualification depth. CAGRs were derived from regression analysis of historical procurement patterns and forward projection of practitioner-channel consolidation trends, with specific incorporation of hardwood substrate harvest cycle variability and ultrasonic-assisted extraction technology adoption curves as industry-specific forecast inputs.
Stress conditions across EFSA novel food authorization delays, Pacific Northwest timber harvest disruptions, and Health Canada pharmacovigilance expansion severity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding organic certification penetration rates and dual-extraction cost compression trajectories. Cross-checking against NMPA dietary supplement guideline enforcement intensity and dual carbon goal implementation pace is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Coenzyme Q10 Market
Nutraceuticals
Multifunctional Health Pot Market
Nutraceuticals
Eye Health Ingredients Market
Nutraceuticals
North America Collagen Market
Nutraceuticals
Europe Nutricosmetics Market
Nutraceuticals
Levocarnitine Market
Nutraceuticals
Fish-Oil Based Drugs Market
Nutraceuticals
Cordyceps Sinensis and Militaris Market
Nutraceuticals
South America Pet Nutraceuticals Market
Nutraceuticals
Anti-Inflammatory Peptides Market
Nutraceuticals
Global 5-Hydroxytryptophan (5-HTP) Market
Nutraceuticals
Nootropics Market
Nutraceuticals
Europe Collagen Peptide Products Market
Nutraceuticals
Cissus Quadrangularis Market
Nutraceuticals
Cognitive Health Ingredients Market
Nutraceuticals
Ayurvedic Products Market