
 Global Dermatology Cro Market | 2026-2036
Global Dermatology Cro Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dermatology Cro Market Foresight
Market Context
Biologics-grade cold-chain logistics is decoupling high-value dermatology trials from traditional small-molecule distribution economics, allowing sponsors to run multi-site inflammatory skin disease studies without temperature-excursion risk. IQVIA Holdings Inc. leverages its global site network to dominate patient access for psoriasis and atopic dermatitis protocols across North America and Europe. Charles River Laboratories International, Inc. anchors its dermatology position through integrated non-clinical toxicology services that bridge preclinical skin models to first-in-human filings.
Technical Definition and Segment Structure
A dermatology contract research organization delivers outsourced clinical trial management, regulatory strategy, and bioanalytical testing specifically for skin, hair, and nail disease therapeutics, encompassing ICH-GCP-compliant site monitoring, dermatology-specific endpoint validation such as PASI and EASI scoring, and topical formulation bioequivalence assessment. Clinical studies remains the largest service type by revenue commitment, while bioanalytical services generates the fastest expansion as pharmacokinetic validation for novel topical delivery systems grows more complex. Phase II trials command disproportionate margin pools because proof-of-concept studies in psoriasis and eczema require specialized investigator networks and rapid adaptive design execution that few full-service CROs can deliver.
Regulatory Environment and Outlook
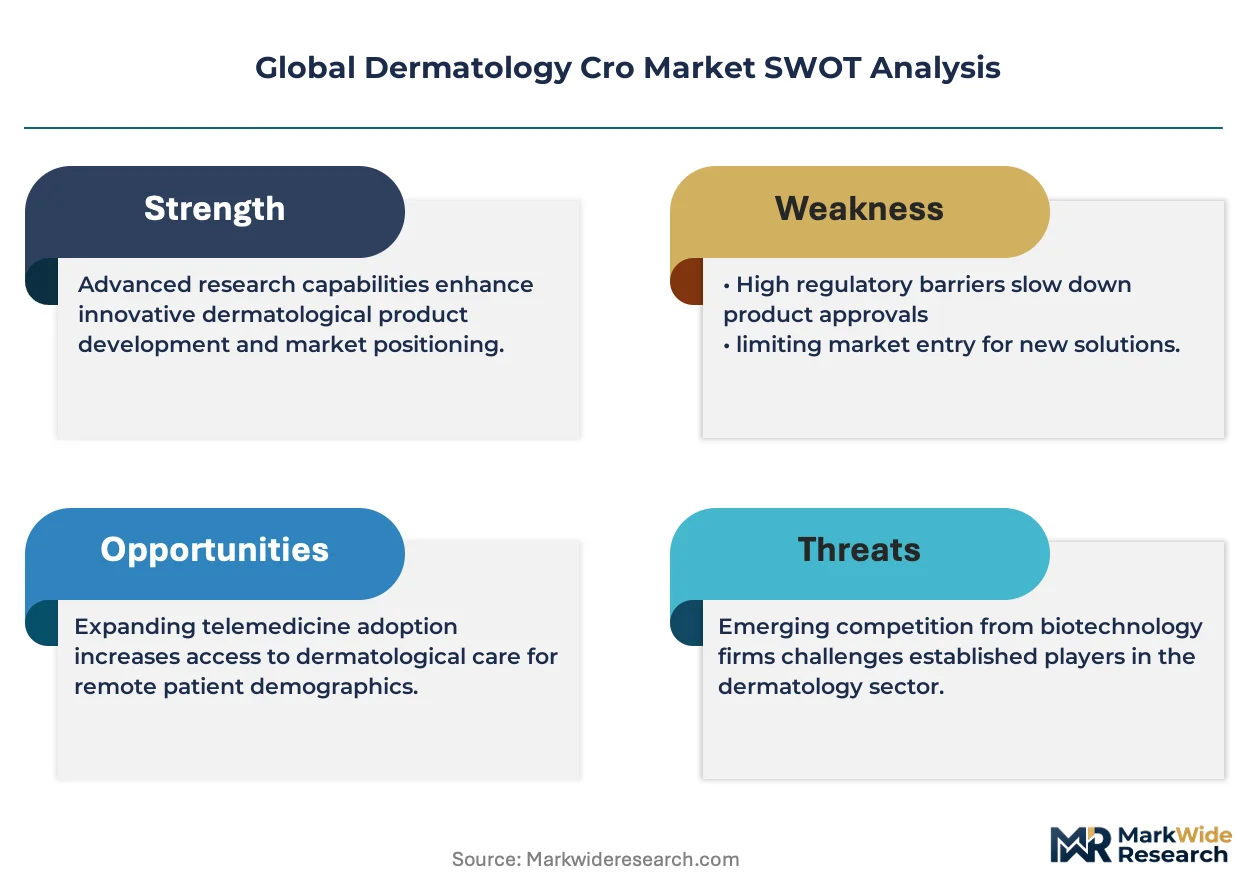
FDA guidance on topical bioequivalence, EMA's evolving standards for biosimilar dermatology indications, and ICH E6(R2) Good Clinical Practice requirements collectively elevate compliance costs and favor CROs with proven regulatory track records across multiple jurisdictions. The EU AI Act and FDA's emerging framework for digital endpoints in atopic dermatitis trials are introducing new validation burdens for ePRO and teledermatology data capture. Stakeholders must monitor how decentralized trial technologies reshape site selection criteria and whether regulatory convergence on patient-reported outcome measures creates first-mover advantages for CROs with validated digital infrastructure.
Market Dynamics
Adaptive trial designs and decentralized patient monitoring are compressing study timelines for inflammatory skin disease protocols, forcing CROs to restructure site networks around real-time data capture capabilities rather than traditional brick-and-mortar investigator relationships.
Growth Catalysts
- FDA Topical Bioequivalence Guidance:Updated standards for pharmacokinetic validation of dermatologic formulations are expanding bioanalytical service contracts as sponsors require specialized CRO expertise to navigate complex waiver pathways and in vitro permeation testing.
- Biotech Outsourcing Surge:Venture-backed dermatology developers lack internal clinical operations infrastructure, creating sustained demand for full-service CROs capable of executing Phase II proof-of-concept studies in psoriasis and atopic dermatitis without sponsor-side oversight.
- Cold-Chain Logistics Maturation:Temperature-controlled distribution networks for biologics-grade therapeutics now support multi-site inflammatory skin disease trials across dispersed geographies without excursion risk, enabling patient access in secondary and tertiary markets.
Market Restraints
- Specialized Investigator Scarcity:Dermatology trial networks concentrate among academic medical centers in the United States, Germany, and Japan, creating recruitment bottlenecks when multiple sponsors compete simultaneously for limited principal investigator capacity.
- Regulatory Divergence Costs:EMA's evolving biosimilar dermatology standards and FDA's distinct topical bioequivalence frameworks force CROs to maintain parallel compliance infrastructures, elevating fixed costs for multi-jurisdictional studies.
- Endpoint Validation Burden:ICH-GCP requirements for PASI and EASI scoring standardization demand rater training programs and inter-rater reliability monitoring that extend study startup timelines and inflate monitoring budgets.
Strategic Opportunities
- Latin America Site Expansion:Brazil's ANVISA regulatory alignment with ICH standards and Argentina's dense dermatology patient populations offer underutilized recruitment pools for inflammatory skin disease trials at lower per-patient costs than United States or Western European sites.
- Digital Endpoint Integration:FDA's emerging framework for teledermatology and ePRO validation in atopic dermatitis creates first-mover advantages for CROs building proprietary digital infrastructure ahead of formal guidance finalization.
- Teledermatology Platform Convergence:Remote lesion photography and AI-assisted severity scoring are compressing site visit requirements, enabling CROs to expand patient access into rural geographies previously excluded from dermatology trial participation.
Industry Challenges
- Adaptive Design Expertise Gap:Few clinical operations teams possess statistical programming capabilities to execute seamless protocol amendments mid-study, forcing sponsors to either accept timeline delays or pay premium rates for specialized biostatistics contractors.
- Legacy System Integration Friction:Electronic data capture platforms at established dermatology sites often lack API compatibility with newer decentralized trial technologies, requiring costly middleware development or manual data reconciliation processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dermatology Cro Market |
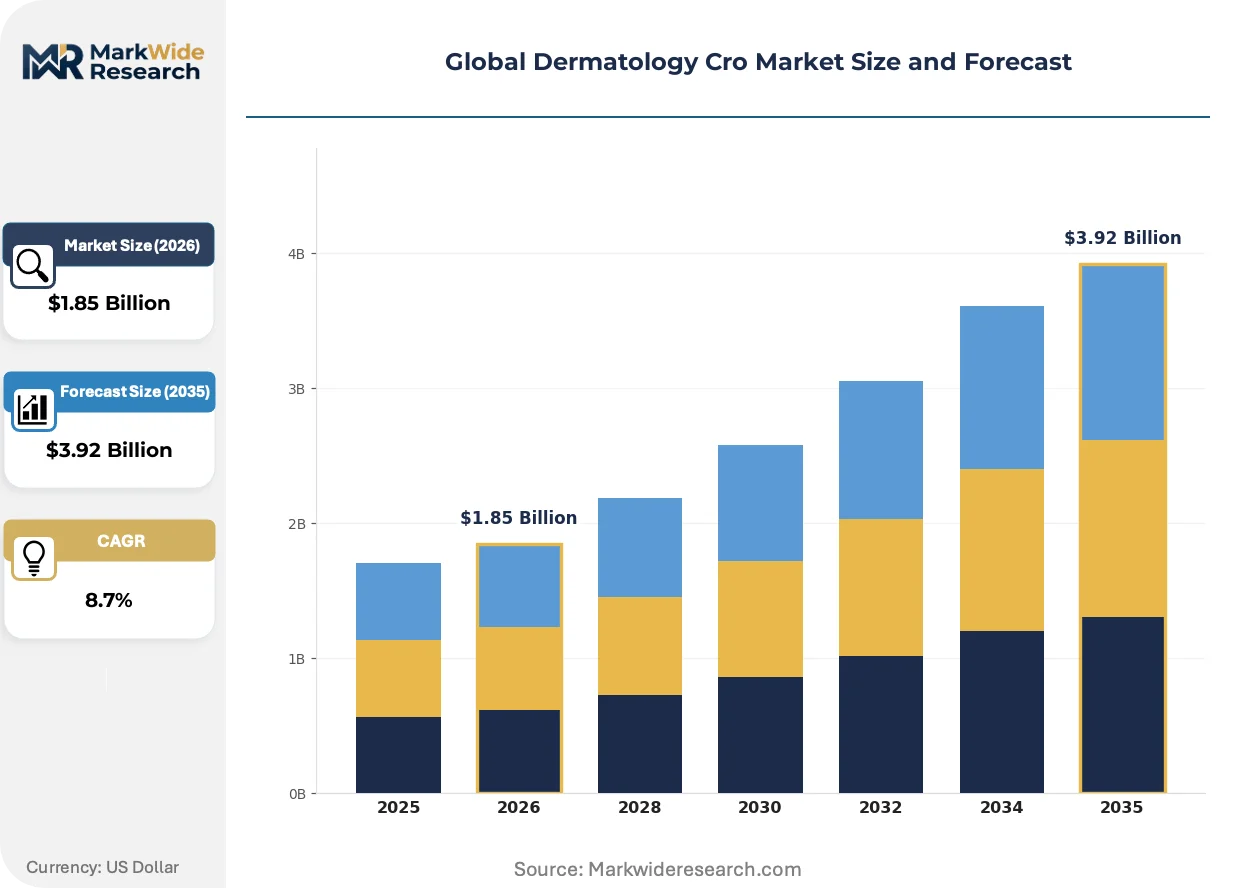
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Clinical Studies, Formulation Development, Regulatory Affairs, Bioanalytical Services, Post-Marketing Surveillance Therapy Area: Psoriasis, Eczema, Acne Vulgaris, Rosacea, Vitiligo End User: Pharmaceutical Companies, Biotech Firms, Contract Manufacturing Organizations, Research Institutions Study Phase: Phase I, Phase II, Phase III, Phase IV, Bioequivalence Trials |
| Companies Covered | IQVIA Holdings Inc., Charles River Laboratories International, Inc., ICON plc, Parexel International Corporation, Syneos Health Inc., Pharmaceutical Product Development, LLC (PPD), Indero (formerly Innovaderm), Medpace Holdings, Inc., WuXi AppTec Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dermatology Cro Market Shifts & Advancements
Real-world evidence capture and patient-centric trial designs are displacing traditional site-dependent models, with technology vendors and CROs racing to deploy integrated platforms that unify remote monitoring, digital endpoints, and direct-to-patient logistics.
Teledermatology platforms incorporating AI-assisted lesion classification and standardized photography protocols are unifying remote patient assessment with central rater adjudication. Mid-size biotech sponsors are adopting these tools at accelerating pace to reduce site visit burden in atopic dermatitis and psoriasis trials. This convergence is compressing geographic constraints on patient recruitment, enabling CROs to access dispersed populations without traditional site infrastructure investments.
EMA's Medical Device Regulation and FDA's draft guidance on software as a medical device are imposing new validation requirements on digital health technologies used for dermatology endpoint capture. CROs must now document algorithm performance and data integrity for AI-assisted severity scoring tools alongside traditional clinical outcomes. European sponsors are responding by front-loading regulatory strategy engagements to avoid protocol amendments during active enrollment.
Sponsor procurement of dermatology CRO services is gravitating toward integrated functional service provider arrangements that bundle clinical operations, bioanalytical testing, and regulatory consulting under unified governance. This displaces the historical model of fragmented vendor management across specialized providers. United States-based biotech firms are driving this shift most visibly, seeking single-accountability structures for complex Phase II inflammatory skin disease programs.
Global Dermatology Cro Market Segmentation
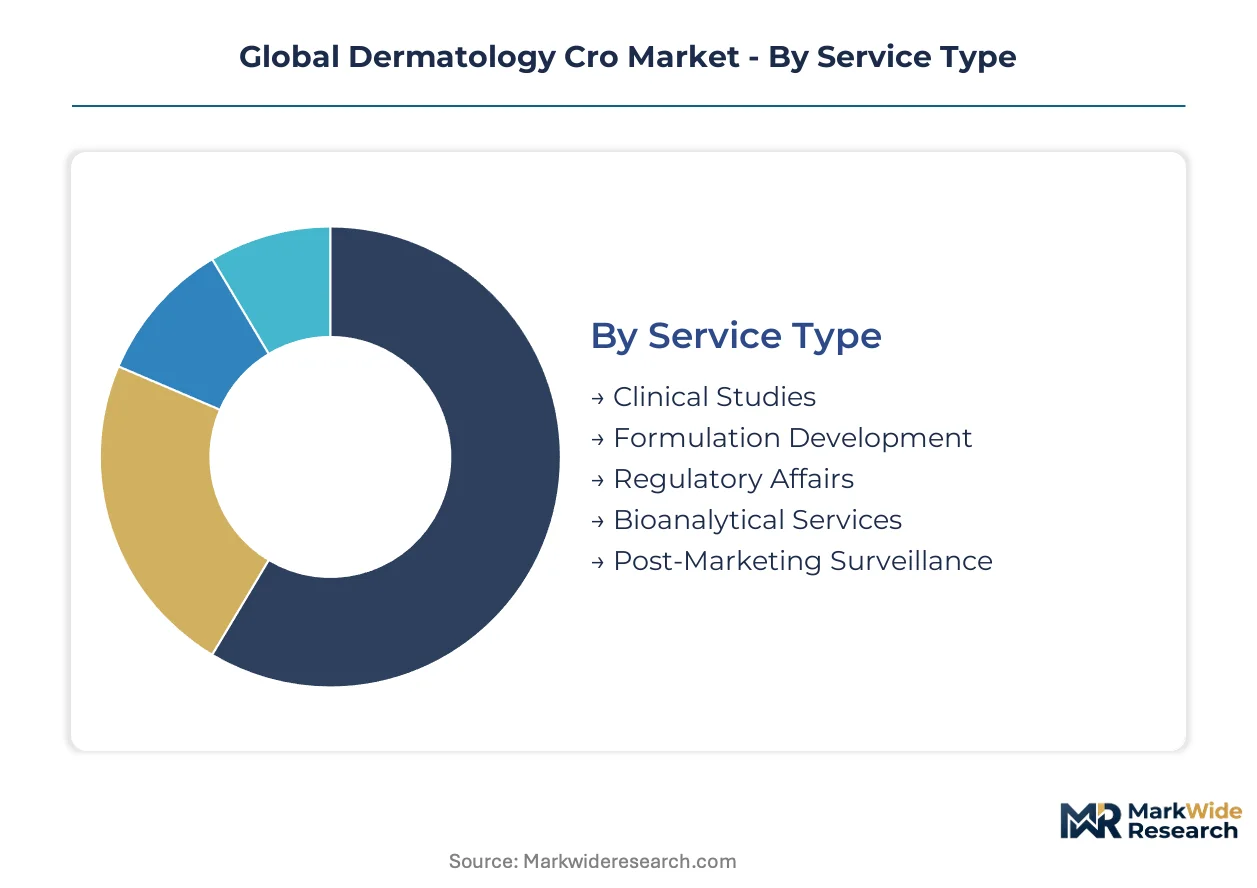
Segmentation in dermatology CRO services reveals how sponsor priorities diverge across development complexity, therapeutic specialization, and outsourcing maturity. Understanding these fault lines clarifies why certain service bundles command premium pricing while others face commoditization pressure.
Service Type:
Buyers in this category separate by internal capability gaps—sponsors with robust clinical operations seek point solutions, while emerging biotechs demand full integration.
- Clinical Studies:Dominant revenue category encompassing site selection, patient recruitment, and ICH-GCP monitoring for inflammatory skin disease protocols. Demand concentrates among United States biotech sponsors running Phase II psoriasis trials, where specialized investigator networks prove decisive for enrollment velocity.
- Bioanalytical Services:Pharmacokinetic validation, biomarker quantification, and topical permeation testing for novel dermatologic formulations. European sponsors expanding into biosimilar dermatology indications drive fastest growth here, requiring CROs with EMA-aligned analytical method transfer capabilities.
- Formulation Development:Preclinical optimization of topical delivery systems and stability testing for semi-solid dosage forms.
- Regulatory Affairs:FDA 505(b)(2) pathway navigation, EMA scientific advice preparation, and global dossier assembly for skin disease therapeutics.
- Post-Marketing Surveillance:Real-world evidence collection and pharmacovigilance for approved dermatology products across dispersed patient populations.
Clinical Studies leads volumes today; Bioanalytical Services is climbing the fastest as topical formulation complexity escalates.
Therapy Area:
Segment boundaries here reflect regulatory pathway differentiation and endpoint validation burden rather than disease prevalence alone.
- Psoriasis:Established proof-of-concept infrastructure with validated PASI scoring and extensive biologics experience. United States academic medical centers anchor demand, where competition for principal investigator slots intensifies during peak enrollment windows.
- Atopic Dermatitis:Rapidly expanding indication driven by pediatric trial requirements and EASI endpoint adoption. Japanese sponsors increasingly outsource here, leveraging CROs with PMDA-aligned pediatric study design expertise.
- Acne Vulgaris:Large patient pools and straightforward lesion counting sustain high-volume, lower-margin trial execution.
- Rosacea:Smaller indication with IGA-based endpoints and limited validated biomarker infrastructure.
- Vitiligo:Emerging therapeutic interest with evolving repigmentation assessment standards and dispersed patient geography.
Psoriasis retains the largest committed revenue base; Atopic Dermatitis shows the steepest expansion trajectory as pediatric indications multiply.
End User:
Organizational scale and capital structure determine procurement patterns—venture-backed entities prioritize speed and single-accountability, while large pharmas optimize for cost and risk distribution.
- Biotech Firms:Fastest-expanding buyer segment, typically outsourcing entire clinical operations for Phase II proof-of-concept studies. These sponsors lack internal infrastructure and demand CROs capable of autonomous execution in psoriasis and atopic dermatitis without sponsor-side oversight.
- Pharmaceutical Companies:Established dermatology portfolios with selective outsourcing for geographic expansion or specialized bioanalytical needs. German and Swiss sponsors dominate this tier, leveraging CRO relationships for EMA parallel-track filings.
- Contract Manufacturing Organizations:Vertically integrated players seeking clinical capabilities to complement formulation and manufacturing services.
- Research Institutions:Academic sponsors with constrained budgets and complex grant-compliance requirements.
Pharmaceutical Companies commit the largest absolute contract values; Biotech Firms are expanding their share most rapidly.
Study Phase:
Margin structure varies sharply here—early-phase work rewards specialized expertise, while late-phase volume favors operational scale.
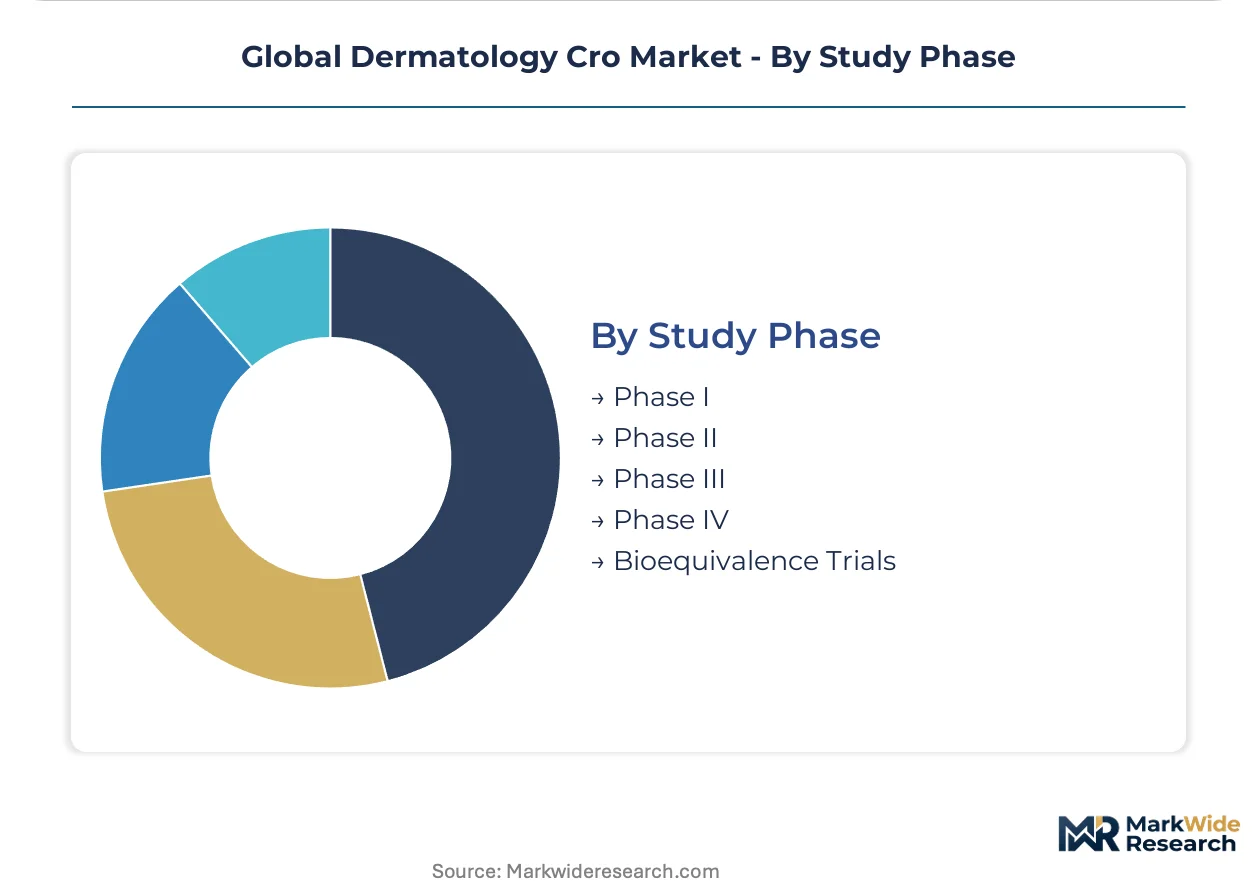
- Phase II:Disproportionate margin concentration due to adaptive design complexity and rapid enrollment demands. Sponsors running proof-of-concept studies in inflammatory skin disease pay premium rates for CROs with proven investigator networks and seamless protocol amendment capabilities.
- Phase III:Largest absolute revenue pool driven by multi-regional registration trials requiring extensive site footprint. Demand clusters in the United States and Germany, where regulatory-grade data packages carry global acceptance weight.
- Phase I:First-in-human and bioavailability studies for novel topical formulations, often conducted at specialized units.
- Phase IV:Post-approval safety and real-world effectiveness studies with dispersed patient monitoring requirements.
- Bioequivalence Trials:Generic dermatology product development with FDA topical bioequivalence guidance compliance.
Phase III commands the greatest revenue commitment; Phase II delivers the highest margin density per contract dollar.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States academic medical centers anchor dermatology CRO demand through dense concentrations of specialized investigator networks and FDA-aligned regulatory infrastructure that accelerates inflammatory skin disease trial enrollment.
United States
Biotech sponsors concentrate Phase II psoriasis and atopic dermatitis outsourcing among Boston, New York, and Philadelphia metropolitan research clusters. FDA guidance on topical bioequivalence and adaptive trial designs shapes service procurement patterns. The Northeast Corridor houses the deepest pool of dermatology principal investigators with validated PASI and EASI scoring credentials.
Germany
EMA parallel-track filing requirements drive demand for CROs with integrated regulatory consulting and bioanalytical method transfer capabilities. The country's national pharmaceutical regulator enforces stringent ICH-GCP compliance standards for multi-jurisdictional studies. Munich and Frankfurt host specialized site networks serving biosimilar dermatology development programs.
Japan
PMDA-aligned pediatric study design expertise attracts outsourcing from domestic sponsors expanding atopic dermatitis indications. The regulator's evolving framework for digital endpoints creates validation partnerships with CROs building teledermatology infrastructure. Tokyo and Osaka academic centers concentrate investigator capacity for inflammatory skin disease protocols.
Brazil
ANVISA regulatory alignment with ICH standards opens underutilized recruitment pools for inflammatory skin disease trials at lower per-patient costs than United States or Western European alternatives. São Paulo and Rio de Janeiro dermatology clinics serve as anchor sites for Latin American expansion strategies. Dense patient populations and established clinical research infrastructure attract mid-size biotech sponsors seeking geographic diversification.
United Kingdom
NHS research networks and MHRA regulatory pathways support streamlined dermatology trial execution for sponsors targeting European approval. London and Cambridge academic medical centers maintain specialized investigator pools for psoriasis and eczema protocols. Post-Brexit regulatory positioning creates competitive tension with EMA-aligned CRO service offerings.
Global Dermatology Cro Market Competitive Landscape
Global majors compete with regional champions across patient access networks and regulatory expertise depth, producing a tiered structure where scale-driven full-service providers coexist with specialized dermatology boutiques. Market concentration favors CROs with validated investigator relationships in United States academic centers and proven EMA filing track records. Three archetypes dominate: integrated global networks, therapeutic-area specialists, and emerging Asia-Pacific scale players. Competitive moves center on M&A to acquire site networks and strategic partnerships to build digital endpoint capabilities.
Within the integrated global network tier, IQVIA Holdings Inc. and Charles River Laboratories International, Inc. occupy positions defined by geographic reach and service breadth rather than dermatology-specific focus. IQVIA exemplifies the patient-access archetype through its global site network dominance, while Charles River represents the preclinical-to-clinical bridge model with toxicology services anchoring dermatology positioning. ICON plc sits within the same tier as a scale-driven competitor with cross-therapeutic execution capabilities.
| Leading Market Players |
|---|
| IQVIA Holdings Inc. |
| Charles River Laboratories International, Inc. |
| ICON plc |
| Parexel International Corporation |
| Syneos Health Inc. |
| Pharmaceutical Product Development, LLC (PPD) |
| Indero (formerly Innovaderm) |
| Medpace Holdings, Inc. |
| WuXi AppTec Co., Ltd. |
| Others |
Supply & Pricing Matrix
Biologics-grade cold-chain infrastructure expansion is simultaneously compressing per-patient logistics costs and concentrating supply leverage among CROs with validated temperature-controlled networks across multiple jurisdictions. This dual effect reshapes competitive economics as sponsors weigh premium service bundling against point-solution procurement.
Pricing Analysis
Input-cost pass-through from specialized investigator training and rater certification programs flows directly into Phase II study premiums. Project-based contracting dominates, with price differentiation hinging on EMA/FDA dual-filing capability and geographic site density. Pricing pressure stems from biotech sponsor procurement consolidation favoring integrated functional service providers over fragmented vendor management. Emerging biotech firms exhibit highest price sensitivity, while large pharmaceutical sponsors prioritize regulatory risk mitigation over unit cost.
Supply Chain Analysis
Freight cost volatility for temperature-sensitive biologics shipments is forcing CROs to regionalize depot networks and secure redundant carrier agreements. Supply concentration centers on the United States, Germany, and Japan for specialized dermatology investigator access. Raw material dependencies include validated PASI/EASI scoring tools, AI-assisted lesion classification software, and ICH-GCP-compliant electronic data capture platforms. Single-source vulnerability in principal investigator networks at United States academic medical centers poses structural risk. Distribution runs through sponsor-direct contracting with site networks rather than intermediary channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where per-patient recruitment costs in Brazil and Argentina undercut United States and Western European rates by substantial margins while maintaining ICH-GCP compliance standards.
For Market Incumbents: Hedge against biotech sponsor consolidation by deepening proprietary digital endpoint infrastructure ahead of FDA teledermatology guidance finalization. Secure exclusive investigator network agreements at United States academic medical centers before competitor saturation peaks. Backward integration into AI-assisted severity scoring algorithms reduces reliance on third-party software vendors.
For New Entrants and Emerging Players: Teledermatology platform partnerships offer lower-capital entry paths than brick-and-mortar site network buildouts. Target pediatric atopic dermatitis trials in Japan where PMDA-aligned study design expertise remains scarce. White-space availability concentrates in Latin American site expansion and real-world evidence capture services for post-marketing surveillance.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-size CROs with dermatology-specialized investigator networks but limited digital infrastructure. Long-term viability favors entities bridging preclinical toxicology through Phase II execution with regulatory consulting depth. Monitor FDA topical bioequivalence guidance implementation timing as inflection signal for bioanalytical service demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Endpoint Infrastructure Buildout | Positions CROs for FDA teledermatology framework adoption ahead of formal guidance. |
| Latin American Site Network Expansion | Captures cost arbitrage from ANVISA-aligned regulatory pathways and dense patient pools. |
| AI-Assisted Severity Scoring Integration | Compresses central rater adjudication timelines while satisfying EMA Medical Device Regulation validation. |
| Integrated Functional Service Provider Arrangements | Consolidates procurement leverage for biotech sponsors seeking single-accountability governance. |
| Preclinical-to-Clinical Bridge Services | Charles River Laboratories anchors positioning through toxicology-to-first-in-human continuity. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, clinical operations directors, and dermatology principal investigators with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov protocols, and ICH-GCP guidance documents. Bottom-up service-type demand modeling and top-down end-user spending analysis were triangulated for consistency.
Segment-weighting approaches applied differential growth assumptions across service types, therapy areas, end-user archetypes, and study phases. The analytical framework incorporated pharmacokinetic validation complexity, pediatric indication expansion rates, and decentralized trial technology adoption curves across the projection horizon. CAGRs were derived from regression analysis of historical outsourcing intensity and forward-looking sponsor pipeline commitments.
Regulatory guidance delays, investigator recruitment bottlenecks, and digital endpoint validation failures are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions about sponsor outsourcing propensity and CRO capacity expansion plans. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Dermatology Drugs Market
Dermatology
Acne Vulgaris Market
Dermatology
Pigmented Lesion Treatment Market
Dermatology
Global Hirsutism Market
Dermatology
Athletes Foot (Tinea Pedis) Treatment Market
Dermatology
Keloid Treatment Market
Dermatology
Seborrheic Dermatitis Treatment Market
Dermatology
Skin Hyperpigmentation Treatment Market
Dermatology
Seborrheic Keratosis Market
Dermatology
Global Rosacea Market
Dermatology
China Scar Treatment Market
Dermatology
Acne Vulgaris Treatment Market
Dermatology
Keratoacanthoma Market
Dermatology
Folliculitis Treatment Market
Dermatology
Homecare Dermatology Energy-Based Devices Market
Dermatology
Androgenetic Alopecia Market