
 Dermabrasion and Micro Needling Market | 2026-2036
Dermabrasion and Micro Needling Market Size, Share, and Industry Trends Forecast 2026-2036
Dermabrasion and Micro Needling Market Analysis
Medical spas are repositioning as the dominant channel for advanced microneedling services, overtaking traditional dermatology clinics in volume for elective procedures. Crown Aesthetics leverages its specialized pen-based systems to anchor the professional segment, while Lumenis Be Ltd competes through laser-integrated platforms that extend treatment versatility. Koninklijke Philips N.V. dominates consumer-grade dermaroller sales through mass retail channel control.
Dermabrasion and micro needling encompass mechanical and percutaneous collagen induction techniques that ablate or puncture the stratum corneum at controlled depths, typically 0.25–2.5 millimeters for microneedling devices, to trigger wound-healing cascades and dermal remodeling. These procedures serve primarily cosmetic and dermatological therapeutic purposes, addressing acne scarring, photoaging, and alopecia through collagen neogenesis and angiogenesis stimulation. Electric dermabrasion systems command the highest margin pools due to capital equipment pricing and consumable attachment revenue, while microneedling pens represent the fastest-growing device category as practitioners seek precision depth control and reduced patient downtime. Scar treatment applications sustain the largest revenue share, though skin rejuvenation procedures are narrowing the gap as younger demographics pursue preventive aesthetic interventions.
FDA 510(k) clearance requirements govern device safety and efficacy claims for US market access, while the EU MDR and CE marking processes impose strengthened clinical evidence standards on manufacturers seeking European distribution. These frameworks elevate barriers for new entrants but reinforce demand for validated, professionally administered treatments over unregulated home alternatives. Stakeholders must monitor evolving reimbursement policies for medically indicated procedures versus purely cosmetic applications, as this boundary increasingly determines volume allocation across clinical and retail channels.
Market Dynamics
Medical spa chains are consolidating procurement power through franchise-standardized device specifications, forcing manufacturers to abandon fragmented clinic sales models in favor of volume-based contract structures with centralized purchasing committees.
Growth Catalysts
- Minimally Invasive Preference:Consumer demand for reduced-downtime aesthetic procedures accelerates microneedling pen adoption over ablative laser alternatives in dermatology practices.
- FDA 510(k) Pathway Clarity:Streamlined clearance processes for predicate device submissions shorten time-to-market for next-generation needle cartridge systems.
- Collagen Induction Science:Published clinical evidence on percutaneous wound-healing cascades validates professional treatments against unregulated home dermarollers.
Market Restraints
- Single-Use Consumable Costs:Sterile needle cartridge pricing creates margin pressure for independent practitioners operating outside franchise networks.
- EU MDR Compliance Burden:Strengthened clinical evidence requirements for CE marking extend product development timelines and elevate documentation costs for European market entry.
- Home Device Substitution:Unregulated consumer-grade dermarollers available through mass retail channels capture price-sensitive segments seeking preventive maintenance.
Strategic Opportunities
- Preventive Aesthetic Demographics:Millennial and Gen-Z patient segments in the United States pursue early-intervention skin rejuvenation before visible photoaging manifests.
- Combination Therapy Protocols:Microneedling paired with radiofrequency or biologic topicals commands premium positioning in medical spa service menus.
- Reimbursement Boundary Expansion:Medically indicated scar revision procedures qualify for insurance coverage in select dermatology clinic settings, diverting volume from purely cosmetic channels.
Industry Challenges
- Practitioner Certification Variance:Inconsistent state-level training requirements for microneedling administration create liability exposure and service quality fragmentation.
- Capital Equipment Refresh Cycles:Electric dermabrasion system depreciation schedules compress replacement demand as clinics extend legacy device utilization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dermabrasion and Micro Needling Market |
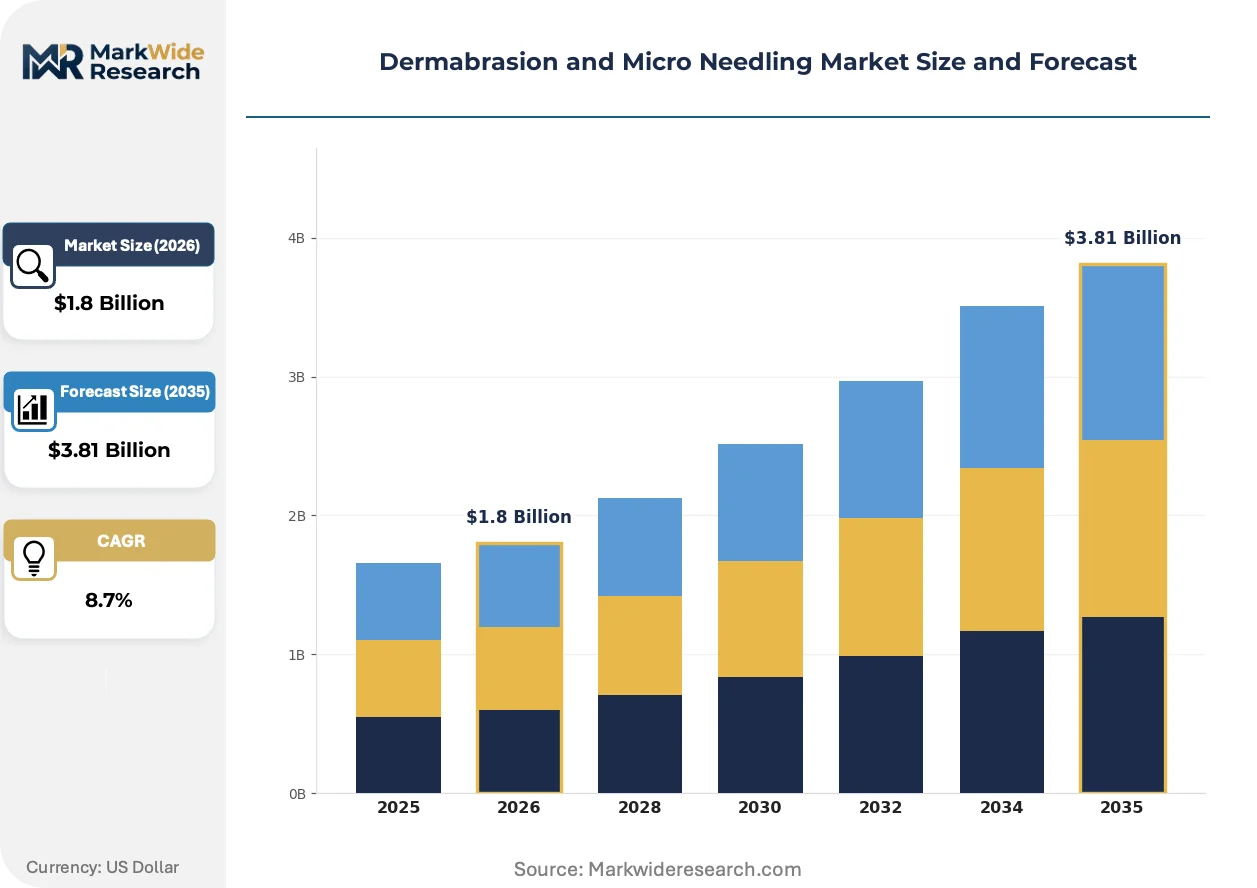
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Electric Dermabrasion, Manual Dermabrasion, Microneedling Pen, Dermaroller Application: Scar Treatment, Skin Rejuvenation, Hair Restoration, Anti-Aging End User: Dermatology Clinics, Beauty Salons, Home Users, Medical Spas Pricing Model: Premium, Mid-Range, Budget, Subscription |
| Companies Covered | Crown Aesthetics, Lumenis Be Ltd, Candela Corporation, INMODE, Cynosure, Koninklijke Philips N.V., Trophy Skin, Suneva Medical, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dermabrasion and Micro Needling Market Emerging Trajectories
Precision depth control and automated needle advancement are displacing manual technique dependency, while regulatory frameworks on both sides of the Atlantic recalibrate competitive access barriers.
Radiofrequency-integrated microneedling platforms is consolidating the high-end professional segment by combining thermal coagulation with mechanical collagen induction in single-treatment sessions. Medical spa franchises in California and Florida are standardizing these systems across multi-location networks. The technology is consolidating capital equipment purchasing around hybrid platforms that reduce per-procedure device switching.
EU MDR clinical evidence requirements are elevating barriers for smaller manufacturers seeking European distribution, concentrating CE-marked device supply among established players with dedicated regulatory affairs infrastructure. Notified body capacity constraints extend review timelines. Scar treatment applications face the most stringent documentation demands, prompting some suppliers to prioritize skin rejuvenation indications for initial market access.
Subscription-based consumable replenishment models are replacing transactional needle cartridge purchasing in high-volume dermatology clinic chains. This procurement evolution locks practitioners into single-supplier ecosystems through predictive inventory algorithms and bundled pricing tiers. The United States exhibits the most advanced adoption of these arrangements, particularly among multi-site aesthetic medicine groups.
Dermabrasion and Micro Needling Market Segmentation
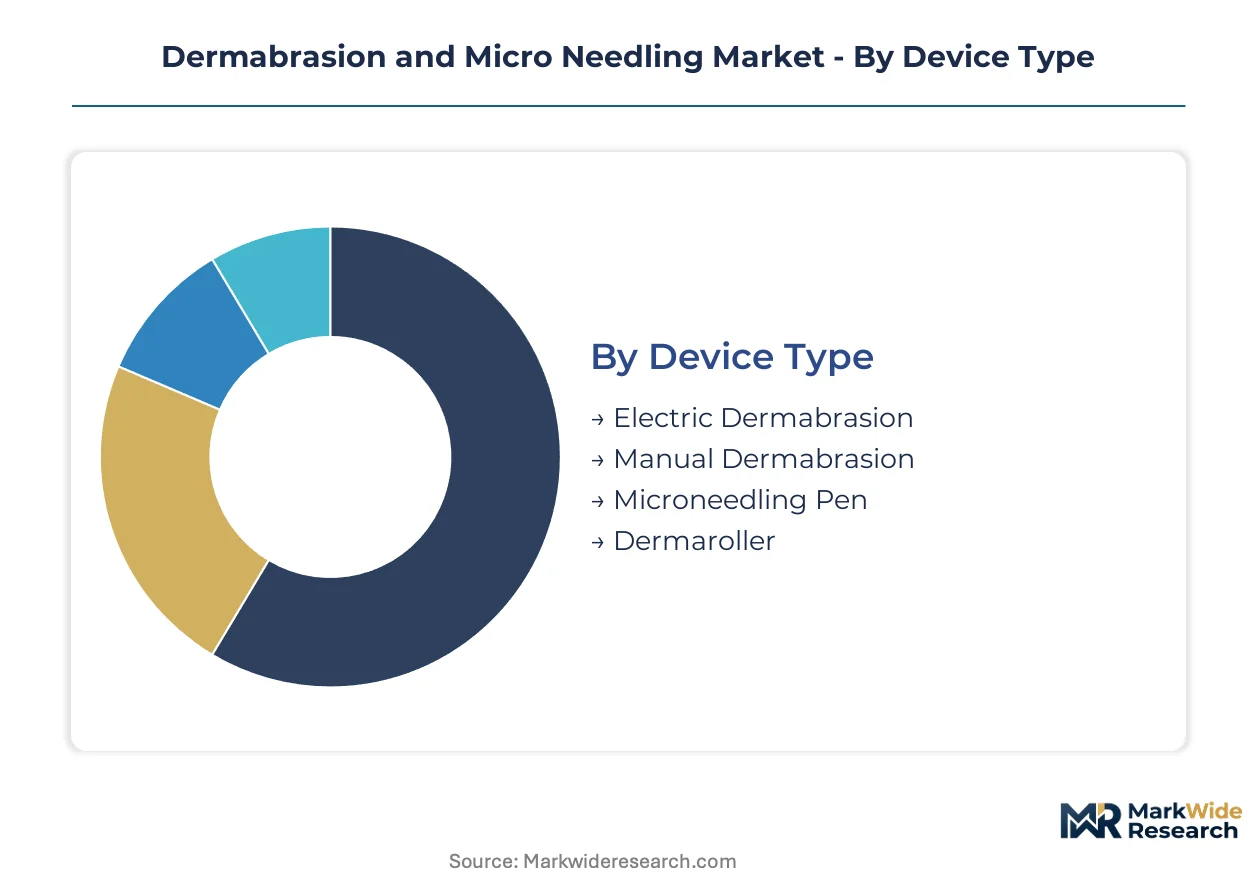
Device taxonomy determines margin architecture and regulatory pathway complexity across the dermabrasion and micro needling landscape. Segmentation by application and end user reveals divergent growth trajectories between medically indicated procedures and elective aesthetic services.
Device Type:
Electric systems capture premium pricing pools while microneedling pens drive volume expansion through reduced patient downtime.
- Electric Dermabrasion:Motorized abrasive systems with diamond or crystal tips enable controlled epidermal ablation at depths up to 1.5 millimeters. Dermatology clinic chains in the United States favor these platforms for scar revision protocols where insurance reimbursement applies.
- Microneedling Pen:Automated needle cartridges with adjustable depth settings (0.25–2.5mm) dominate medical spa procurement through precision collagen induction and faster recovery windows. California and Florida franchise networks standardize these devices across multi-location service menus.
- Manual Dermabrasion:Hand-held abrasive tools with rotating brushes or wire loops serve budget-conscious independent practitioners.
- Dermaroller:Cylindrical drums with fixed needle arrays populate consumer retail channels and beauty salon back-bar inventories.
Today's leader: Electric Dermabrasion. Tomorrow's challenger: Microneedling Pen.
Application:
Medically necessary indications anchor reimbursement-eligible revenue streams while preventive aesthetic applications expand addressable patient demographics.
- Scar Treatment:Acne and surgical scar revision protocols command the largest professional segment through validated clinical outcomes and partial insurance coverage in US dermatology settings.
- Skin Rejuvenation:Preventive collagen induction for photoaging prevention attracts millennial and Gen-Z patient segments seeking early intervention before visible damage manifests.
- Hair Restoration:Scalp microneedling combined with topical biologics addresses androgenetic alopecia through follicular stimulation.
- Anti-Aging:Fine line reduction and texture improvement procedures concentrate in medical spa channels with premium service positioning.
Scar Treatment retains installed base dominance. Skin Rejuvenation climbs the fastest toward parity.
End User:
Channel structure fragments between clinically regulated environments and retail-accessible service tiers.
- Medical Spas:Hybrid clinical-aesthetic facilities with physician oversight now drive majority volume for elective microneedling procedures through franchise-standardized protocols.
- Dermatology Clinics:Board-certified practices concentrate medically indicated scar treatments and complex case referrals with FDA 510(k)-cleared device requirements.
- Beauty Salons:Non-medical aesthetic venues utilize manual dermabrasion and superficial microneedling where state regulations permit.
- Home Users:Consumer-grade dermaroller purchases through mass retail channels capture maintenance-oriented segments outside professional supervision.
Medical Spas consolidate elective volume. Dermatology Clinics defend medically indicated territory.
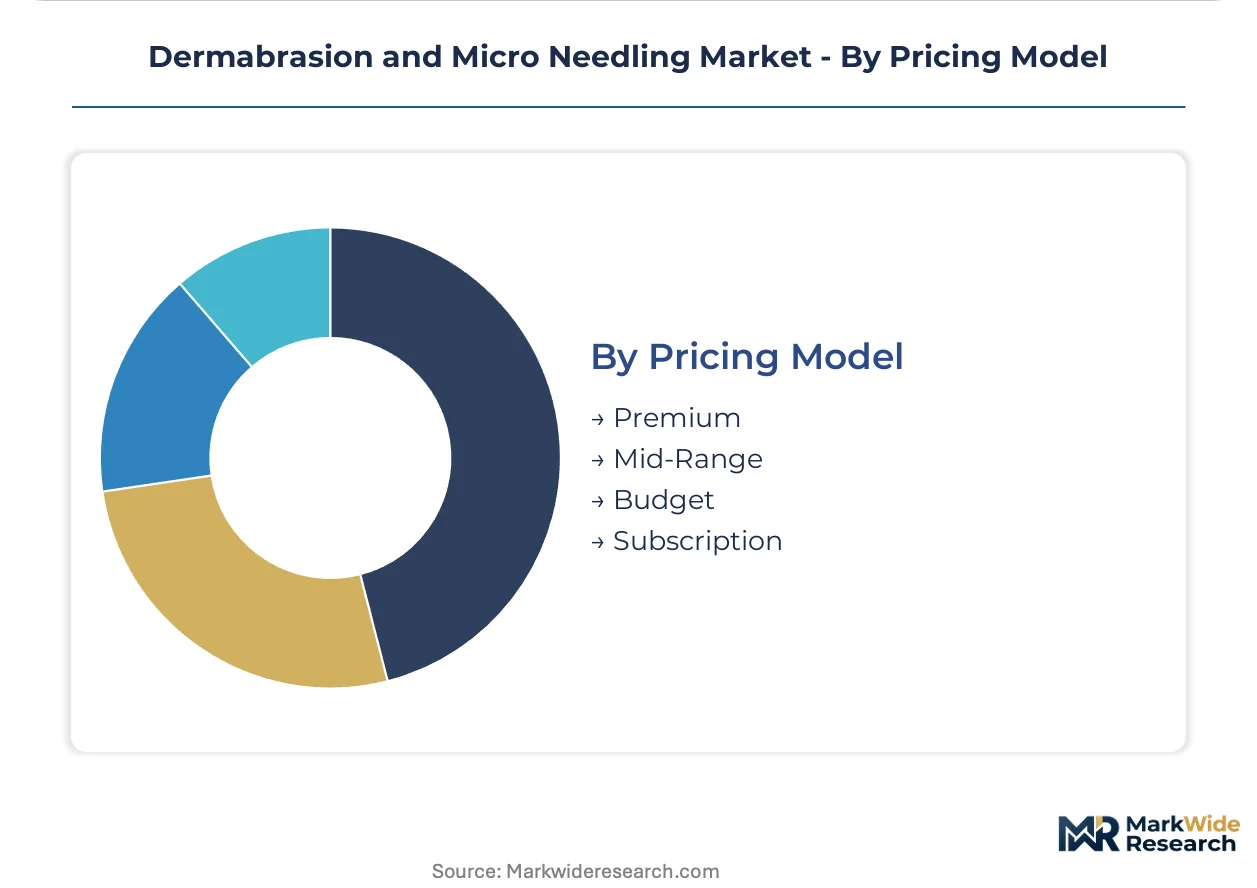
Pricing Model:
Procurement economics diverge between capital equipment ownership and recurring consumable commitments.
- Premium:RF-integrated platforms and laser-dermabrasion hybrids command equipment investments exceeding $50,000 with proprietary cartridge lock-in.
- Subscription:Predictive needle cartridge replenishment with bundled pricing tiers now dominates high-volume US clinic chain procurement.
- Mid-Range:Standalone microneedling pens with disposable tips serve independent practitioners outside franchise networks.
- Budget:Manual tools and consumer dermarollers compete on acquisition cost alone with minimal consumable attachment.
Subscription models gain share fastest among organized buyers. Premium positioning defends margin pools in integrated platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical spa franchise networks in California anchor procurement volume for precision microneedling systems. FDA 510(k) clearance pathways and EU MDR compliance requirements reshape competitive access across major markets. Device manufacturers concentrate regulatory affairs infrastructure in jurisdictions with streamlined predicate device submissions.
United States
Dermatology clinic chains in Texas and Florida drive electric dermabrasion adoption for scar revision protocols. FDA 510(k) clearance requirements govern safety and efficacy claims for professional-grade devices. Medical spa franchises in Los Angeles and Miami standardize automated microneedling pens across multi-location service menus.
Germany
Notified body capacity constraints extend CE marking timelines for scar treatment device categories. EU MDR clinical evidence standards elevate documentation burdens for European market entry. Aesthetic medicine clusters in Munich and Hamburg concentrate procurement of RF-integrated platforms for combination therapy protocols.
United Kingdom
Private dermatology practices in London prioritize FDA-cleared devices for premium service positioning. MHRA recognition of FDA 510(k) clearances accelerates parallel market access for US-manufactured systems. Harley Street medical aesthetic clinics anchor demand for subscription-based consumable replenishment models.
South Korea
MFDS regulatory pathways support domestic device innovation for percutaneous collagen induction systems. Seoul-based aesthetic clinic chains integrate microneedling with topical biologics for hair restoration applications. Gangnam district medical spas command premium positioning through technology-forward treatment protocols.
Australia
TGA approval requirements align with FDA predicate device standards for streamlined market entry. Sydney and Melbourne dermatology practices concentrate volume for medically indicated scar treatments. Subscription procurement models gain traction among multi-site aesthetic medicine groups in southeastern metropolitan corridors.
Dermabrasion and Micro Needling Market Vendor Landscape
Strategic partnerships dominate the current landscape as manufacturers seek regulatory expertise and distribution scale. The vendor base concentrates around three tiers: diversified medical device conglomerates with aesthetic divisions, specialized energy-based platform developers, and professional-grade consumable suppliers. Two archetypes anchor competitive positioning: laser-integrated platform developers competing on treatment versatility, and pen-based system specialists competing on precision depth control. M&A activity and technology licensing agreements represent the dominant competitive moves as firms seek CE marking infrastructure and US sales channel access.
Within the specialized energy-platform tier, Lumenis Be Ltd and Candela Corporation exemplify archetypes competing through multi-modality device portfolios. Among diversified medical technology conglomerates, Koninklijke Philips N.V. occupies a position spanning professional and consumer-grade segments. Crown Aesthetics anchors the precision-pen specialist category with focused professional segment positioning. These three company types represent distinct strategic postures: capital equipment breadth, vertical integration across price tiers, and segment-specific depth.
| Leading Market Players |
|---|
| Crown Aesthetics |
| Lumenis Be Ltd |
| Candela Corporation |
| INMODE |
| Cynosure |
| Koninklijke Philips N.V. |
| Trophy Skin |
| Suneva Medical |
| 3M |
| Others |
Supply Flow & Price Mechanics
Medical-grade stainless steel pricing indices cascade through needle cartridge manufacturing into tiered equipment economics, compressing margins at the budget tier while RF-integrated platforms sustain premium positioning through proprietary consumable lock-in.
Pricing Analysis
Input-cost pass-through from precision-machined needle arrays and biocompatible polymers stratifies pricing across three tiers. Subscription-based consumable replenishment dominates high-volume US clinic chains, while independent practitioners face acute sensitivity to single-use cartridge costs. FDA 510(k) certification tier and after-sales service bundling drive differentiation between premium and mid-range positioning. Pricing pressure stems from home device substitution in the consumer segment.
Supply Chain Analysis
EU MDR local-content documentation requirements are reshaping sourcing toward notified-body-proximate manufacturing. Component supply concentrates in Germany, Switzerland, and the United States for precision drive systems and medical-grade metals. Raw material dependencies include surgical stainless steel, biocompatible polymers, and RF generator subassemblies. Single-source vulnerability runs through specialized needle array suppliers. Distribution runs through medical device distributors and direct-to-clinic sales forces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dermabrasion and micro needling market functions as a geographic-arbitrage play where EU MDR compliance costs in Europe diverge sharply from FDA 510(k) pathway efficiency in the United States, creating divergent capital allocation returns.
For Market Incumbents: Cement regulatory affairs infrastructure as the primary defensive moat by deepening CE marking expertise and securing notified body relationships ahead of capacity constraints. Prioritize backward integration into needle cartridge manufacturing to offset consumable cost pressure from franchise purchasing committees. Channel control through exclusive distributor agreements defends against emerging pen-based specialists.
For New Entrants and Emerging Players: The mid-range price-point gap between Lumenis-tier RF platforms and budget manual tools offers white-space entry through subscription-compatible standalone pens. Target Australian and South Korean markets where TGA and MFDS pathways align with streamlined predicate device standards. Pursue GPO contracts with multi-site aesthetic medicine groups as the primary go-to-market angle.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized consumable suppliers possessing CE marking infrastructure and US distribution relationships. Long-term viability centers on recurring revenue attachment rates rather than capital equipment refresh cycles. Monitor FDA 510(k) clearance velocity for microneedling-RF hybrids as the inflection signal for platform consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements concentrate supply among established regulatory affairs infrastructure holders. |
| Hospital System Partnership | Dermatology clinic chains in Texas and Florida anchor reimbursement-eligible scar revision volume. |
| Software Companion Development | Predictive inventory algorithms lock practitioners into single-supplier subscription ecosystems. |
| Reimbursement Strategy | Medically indicated scar treatment qualification diverts volume from purely cosmetic medical spa channels. |
| FDA Submission | Streamlined predicate device pathways accelerate time-to-market for next-generation needle cartridge systems. |
Methodological Framework
Direct dialogue with medical spa franchise operators, dermatology clinic purchasing managers, biomedical engineers at device manufacturers, and regulatory affairs specialists at notified bodies grounded qualitative findings. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation summaries, hospital procurement databases, and GPO contract disclosures. Bottom-up and top-down triangulation cross-checked installed base estimates against consumable replenishment velocity.
Bottom-up modeling aggregated procedure volume by device type, application, and end-user channel across the projection horizon. Segmentation dimensions included device technology tier, clinical versus cosmetic indication, and procurement model ownership structure. CAGRs were derived from regression analysis against demographic penetration curves and capital equipment replacement cycles. Forecast inputs incorporated medical spa franchise expansion rates and FDA clearance timeline distributions.
Caveats apply where reimbursement policy shifts or notified body capacity constraints could materially shift the outlook for European market entry timelines. Forecasts reflect assumptions regarding regulatory pathway stability and practitioner certification standardization trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Global Veterinary Dermatology Drugs Market
Dermatology
Hyperpigmentation Treatment Market
Dermatology
Global Hirsutism Market
Dermatology
Acne Vulgaris Treatment Market
Dermatology
Europe Scar Treatment Market
Dermatology
Dermabrasion Market
Dermatology
Folliculitis Treatment Market
Dermatology
Folliculitis Market
Dermatology
China Scar Treatment Market
Dermatology
Pigmented Lesion Treatment Market
Dermatology
Dermatological Products Market
Dermatology
Global Radiodermatitis Market
Dermatology
US and Canada Skin Cancer Dermatology Market
Dermatology
Lentigo Maligna Melanoma Therapeutic Market
Dermatology
Scar Treatment Market
Dermatology
Hyperpigmentation Disorder Treatment Market