
 Hyperpigmentation Treatment Market | 2026-2036
Hyperpigmentation Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hyperpigmentation Treatment Market Foresight
Topical delivery technology is fragmenting into nano-encapsulation, liposomal carriers, and transdermal penetration enhancers. L'Oréal S.A. leverages its dermatological research network to sustain pipeline depth across prescription and cosmetic channels. Galderma S.A. anchors its position through physician-dispensed platforms that compete directly with mass-market alternatives. AbbVie Inc. differentiates via specialty pharmacy distribution controls that limit counterfeiting exposure.
Hyperpigmentation treatment encompasses therapeutic and cosmetic interventions designed to reduce melanin accumulation through tyrosinase inhibition, melanocyte suppression, or epidermal renewal, with hydroquinone formulations typically restricted to 2% over-the-counter and 4% prescription concentrations in regulated markets. The primary commercial purpose spans post-inflammatory hyperpigmentation correction, melasma management, and photodamage reversal across outpatient dermatology and retail skincare settings. Topical creams dominate volume due to lower per-unit pricing and broader pharmacy access, while laser therapy commands premium positioning in skincare clinics where treatment protocols bundle multiple modalities. Azelaic acid formulations are gaining fastest in prescription channels as dermatologists shift from hydroquinone amid regulatory scrutiny.
FDA oversees over-the-counter monograph compliance and prescription labeling for depigmenting agents, while EMA's REACH framework governs cosmetic ingredient safety across European formulation imports. The EU Green Deal chemical sustainability targets are forcing reformulation timelines for kojic acid and retinoid suppliers serving European skincare clinics. Stakeholders must monitor pending FDA hydroquinone concentration limits and emerging state-level cosmetic ingredient disclosure laws that could reshape channel economics for online retailers and dermatology practices alike.
Market Dynamics
Regulatory pressure on hydroquinone concentrations is fragmenting formulation strategies across dermatology clinics and retail channels, forcing suppliers to rebuild active ingredient portfolios around azelaic acid, kojic acid derivatives, and peptide-based melanin inhibitors.
Growth Catalysts
- REACH chemical sustainability targets:ECHA's tightening cosmetic ingredient standards are accelerating reformulation investment among European suppliers, creating first-mover advantages for azelaic acid and tranexamic acid platforms.
- Dermatology clinic consolidation:Outpatient skincare centers in Brazil and South Korea are bundling laser therapy with prescription topicals, expanding addressable patient volumes beyond traditional retail pharmacy channels.
- Nano-encapsulation penetration:Liposomal delivery systems are improving bioavailability of unstable actives, enabling lower-concentration formulations that satisfy FDA safety thresholds while maintaining efficacy.
Market Restraints
- Hydroquinone regulatory friction:Pending FDA concentration limits and state-level disclosure mandates in California and New York are compressing formulation timelines and raising compliance costs for legacy product lines.
- Active ingredient supply concentration:Kojic acid production clusters in East Asian fermentation facilities expose formulators to shipping volatility and customs processing delays.
- Substitution threat from cosmetic alternatives:Niacinamide and vitamin C serums at mass-market price points are capturing mild hyperpigmentation cases that previously sought prescription intervention.
Strategic Opportunities
- Underpenetrated Indian dermatology:Rising disposable income in Mumbai and Bangalore outpatient clinics is creating demand for physician-dispensed combination therapies that bypass traditional pharmacy distribution.
- Transdermal penetration enhancer convergence:Microneedle patch technology paired with tyrosinase inhibitors is opening at-home treatment segments previously reserved for clinical laser protocols.
- EU Green Deal biopreferred procurement:Bio-based retinoid alternatives qualify for preferential purchasing in European skincare clinics, rewarding suppliers with certified sustainable supply chains.
Industry Challenges
- Formulation chemist talent scarcity:Specialized expertise in melanocyte biology and stability testing for photo-sensitive actives is concentrating among a limited pool of contract research organizations.
- Clinical trial timeline compression:FDA's evolving safety standards for depigmenting agents are extending Phase III study durations, delaying product launches and freezing pipeline capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyperpigmentation Treatment Market |
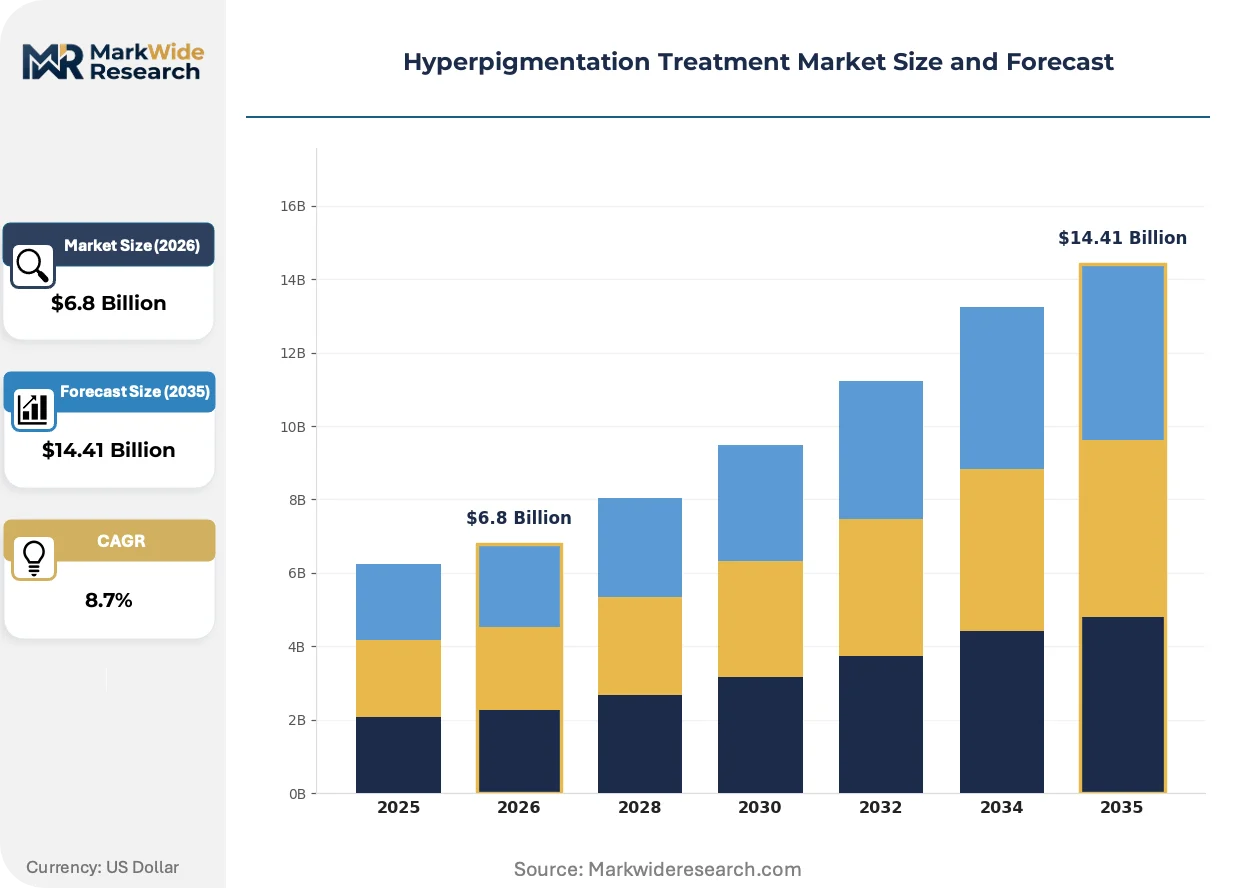
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Creams, Chemical Peels, Laser Therapy, Microdermabrasion Active Ingredient: Hydroquinone, Kojic Acid, Azelaic Acid, Retinoids Customer Type: Dermatologists, Skincare Clinics, Pharmacies, Online Retailers Formulation: Gels, Serums, Lotions, Emulsions |
| Companies Covered | Obagi Cosmeceuticals LLC, Unilever plc, Galderma S.A., Candela Medical, Beiersdorf AG, L’Oréal S.A., Johnson & Johnson, Pierre Fabre Dermo-Cosmétique, AbbVie Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyperpigmentation Treatment Market Shifts & Advancements
Delivery system architecture is diverging from conventional emulsion bases toward engineered carriers that protect unstable actives from oxidation while targeting melanocyte activity with precision. This shift is compressing the gap between cosmetic and therapeutic efficacy claims.
Liposomal encapsulation technology is migrating from high-end cosmetic serums into prescription-grade hyperpigmentation treatments. Dermatology clinics in Seoul and São Paulo are adopting these platforms to reduce irritation incidence in melasma patients with sensitive skin. The technology is migrating from premium positioning into mid-market physician-dispensed channels, eroding price premiums that once separated cosmetic from medical-grade formulations.
EMA's REACH framework amendments are forcing kojic acid suppliers to submit updated safety dossiers by tightened deadlines, triggering reformulation costs that disproportionately burden small European skincare clinics dependent on imported Asian raw materials. German and French formulators are responding by accelerating domestic fermentation capacity investments and diversifying toward azelaic acid sourced from European oleochemical feedstocks.
Patient acquisition through tele-dermatology platforms is compressing the traditional clinic referral funnel, with direct-to-consumer prescription services in the United States capturing post-inflammatory hyperpigmentation cases that previously required in-person consultation. This channel shift is most visible among millennial demographics in urban coastal markets, where convenience prioritization overrides established physician relationships and drives preference for subscription-based topical regimens.
Hyperpigmentation Treatment Market Segmentation
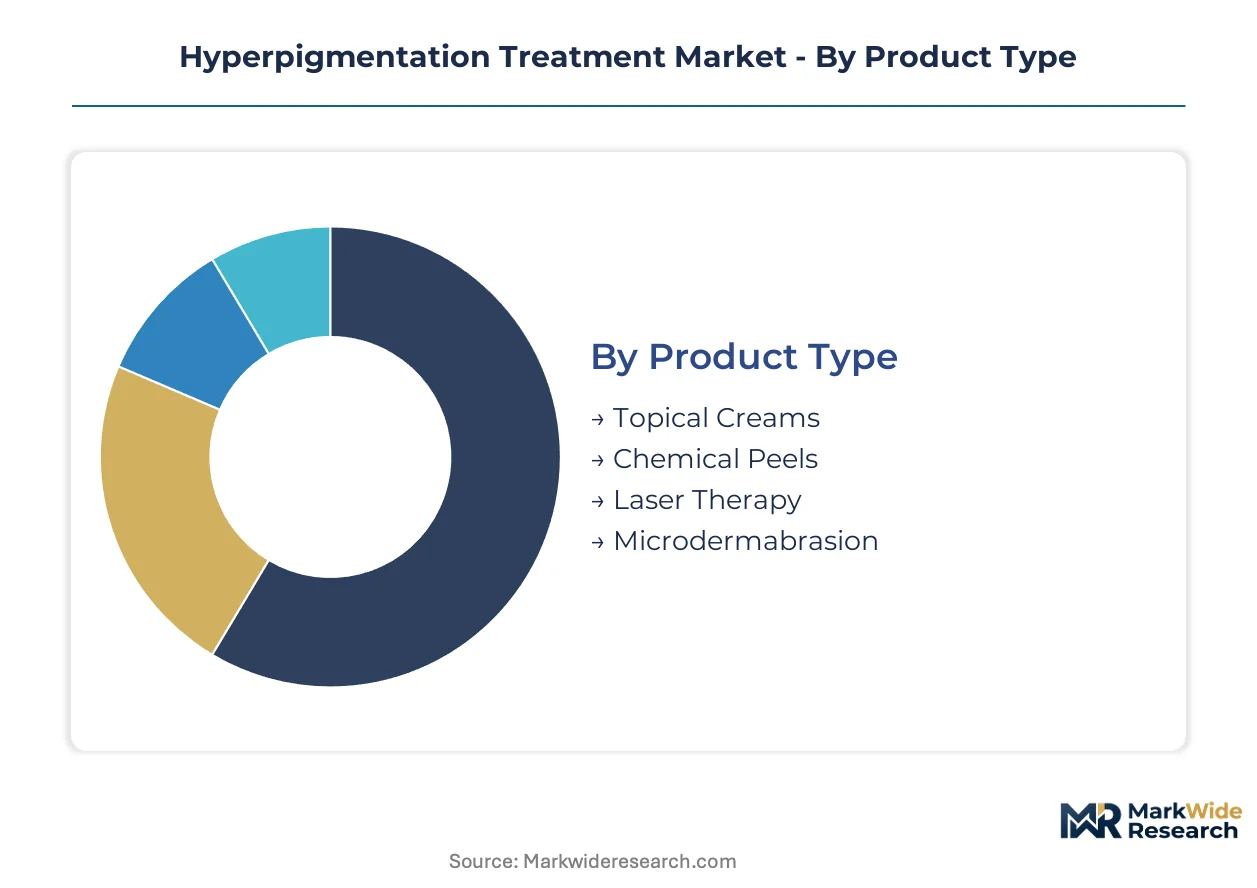
Hyperpigmentation treatment segmentation reveals divergent margin profiles across delivery modalities and regulatory risk exposure among active ingredient portfolios. Channel fragmentation between physician-dispensed and retail access tiers reshapes pricing power and patient acquisition economics for suppliers.
Product Type:
Mature topical formats dominate volume while emerging energy-based modalities capture premium positioning in consolidated clinic networks.
- Topical Creams:Emulsion-based vehicles incorporating tyrosinase inhibitors or retinoids serve as first-line intervention for post-inflammatory hyperpigmentation. Demand concentrates in United States retail pharmacy chains where FDA 2% hydroquinone OTC thresholds enable broad access without prescription friction.
- Laser Therapy:Q-switched and fractional laser platforms target dermal melanin deposits resistant to topical penetration. Skincare clinics in São Paulo and Seoul bundle these protocols with prescription topicals, expanding per-patient revenue beyond single-modality treatment.
- Chemical Peels:Glycolic acid and trichloroacetic acid formulations accelerate epidermal turnover. Physician-administered applications in Brazilian outpatient centers address melasma with deeper penetration than home-use alternatives.
- Microdermabrasion:Mechanical exfoliation systems prepare skin for active ingredient absorption. Aesthetic practices in South Korea integrate these into multi-step brightening protocols.
Topical creams retain volume leadership; laser therapy holds the steepest expansion curve.
Active Ingredient:
Regulatory pressure on legacy compounds is fragmenting R&D investment toward alternatives with cleaner safety profiles and REACH compliance pathways.
- Hydroquinone:Tyrosinase inhibitor with established efficacy at 2% OTC and 4% prescription concentrations. FDA safety reviews and California disclosure mandates are compressing formulation timelines for legacy product lines dependent on this active.
- Azelaic Acid:Dicarboxylic acid derived from cereal grains with dual anti-inflammatory and melanin-inhibiting properties. Prescription channels in Germany and France are shifting toward this compound as ECHA tightening accelerates kojic acid substitution.
- Kojic Acid:Fungal fermentation product with melanin suppression activity. East Asian production concentration exposes European formulators to supply volatility amid REACH dossier resubmission requirements.
- Retinoids:Vitamin A derivatives accelerating cell turnover and dispersing melanin granules. Bio-based alternatives qualify for EU Green Deal preferential procurement in sustainable supply chain certifications.
Hydroquinone retains volume leadership; azelaic acid holds the steepest expansion curve.
Customer Type:
Channel economics diverge sharply between controlled distribution preserving margin and open retail sacrificing price for volume reach.
- Dermatologists:Physician prescribers managing complex melasma and post-inflammatory cases. United States specialty pharmacy controls limit counterfeiting exposure for high-value prescription formulations.
- Skincare Clinics:Outpatient facilities bundling device-based and topical interventions. Brazilian and South Korean clinic consolidation is expanding addressable patient volumes beyond traditional pharmacy channels.
- Pharmacies:Retail dispensaries handling OTC concentrations and prescription fulfillment. Mass-market niacinamide and vitamin C serums at these outlets capture mild hyperpigmentation cases.
- Online Retailers:Direct-to-consumer platforms compressing traditional clinic referral funnels. United States tele-dermatology services capture millennial demographics prioritizing convenience over established physician relationships.
Pharmacies retain volume leadership; skincare clinics hold the steepest expansion curve.
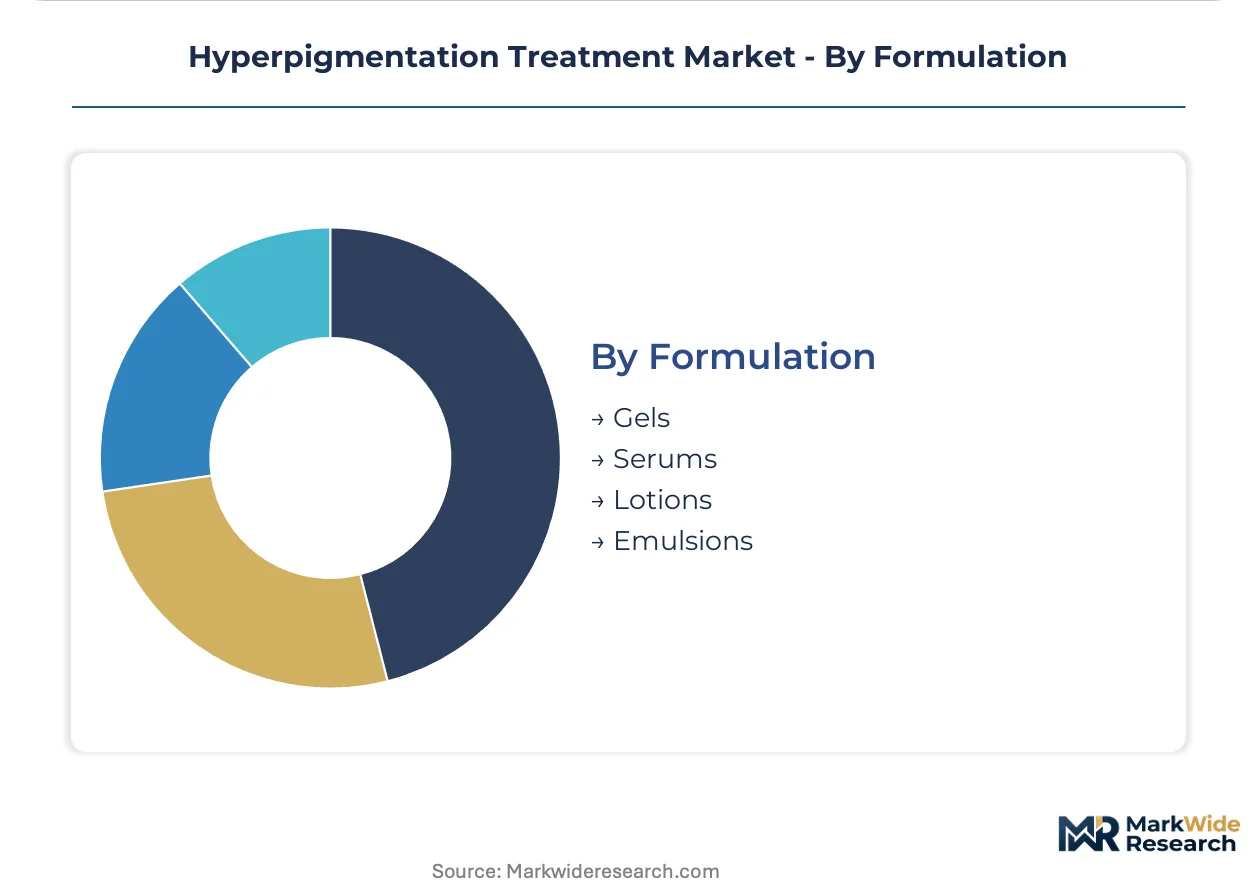
Formulation:
Delivery system architecture determines active stability, penetration depth, and sensory acceptance across patient compliance profiles.
- Serums:Low-viscosity vehicles with high active concentration and rapid absorption. Liposomal encapsulation technology is migrating from premium cosmetic positioning into prescription-grade treatments in Seoul dermatology practices.
- Gels:Aqueous-based systems preferred for oily skin types and humid climates. Brazilian outpatient clinics favor these for post-inflammatory hyperpigmentation in acne-prone patients.
- Lotions:Higher water content formulations balancing spreadability with occlusion. Mass-market channels in the United States deploy these for broader demographic accessibility.
- Emulsions:Oil-in-water or water-in-oil systems stabilizing photo-sensitive actives. Nano-encapsulation penetration enhancers are improving bioavailability in these bases for FDA-compliant lower-concentration efficacy.
Lotions retain volume leadership; serums hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dermatology clinics and retail pharmacy networks concentrate demand across distinct geographic clusters, with regulatory frameworks and disposable income levels determining channel access patterns for prescription and over-the-counter formulations.
United States
Specialty pharmacy distribution and tele-dermatology platforms drive prescription volume in urban coastal markets. FDA oversight of hydroquinone concentration limits shapes formulation strategies for legacy product lines. Miami and Los Angeles outpatient centers bundle laser protocols with physician-dispensed topicals, capturing post-inflammatory hyperpigmentation cases from diverse patient demographics.
Brazil
Consolidating skincare clinic networks in São Paulo and Rio de Janeiro expand per-patient revenue through multi-modality treatment bundling. ANVISA registration requirements for imported active ingredients create compliance timelines that favor domestic formulators. The Southeast region anchors national demand, with physician-administered chemical peels addressing melasma prevalence in sun-exposed populations.
South Korea
Seoul Capital Area dermatology practices adopt liposomal delivery systems for sensitive-skin patient segments. MFDS cosmetic ingredient standards exceed baseline international thresholds, accelerating nano-encapsulation investment among domestic suppliers. Busan-Ulsan aesthetic centers integrate microdermabrasion into standardized brightening protocols for medical tourism clientele.
Germany
EMA REACH framework amendments force kojic acid suppliers toward updated safety dossiers, triggering reformulation costs for European skincare clinics. Azelaic acid sourced from domestic oleochemical feedstocks gains prescription channel share as dermatologists shift from hydroquinone. Bavarian and North Rhine-Westphalian formulators invest in fermentation capacity to reduce East Asian supply dependence.
India
Rising disposable income in Mumbai and Bangalore outpatient clinics creates demand for physician-dispensed combination therapies. CDSCO import regulations for cosmetic actives compress timeline flexibility for multinational suppliers. Maharashtra and Karnataka dermatology networks bypass traditional pharmacy distribution through direct clinic dispensing models.
Hyperpigmentation Treatment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tiering that separates mass-market retail access from controlled physician dispensing. The vendor base spans multinational dermatological conglomerates, cosmetic science platforms, and device manufacturers with bundled service offerings. Strategic archetypes include prescription-access defenders, cosmetic-brand extenders, and clinic-network integrators. Competitive moves concentrate on M&A for dermatology clinic networks and licensing agreements for nano-encapsulation delivery patents.
Among multinational dermatological conglomerates, L'Oréal S.A. and Galderma S.A. occupy positions that bridge cosmetic and therapeutic channels. AbbVie Inc. anchors the specialty pharmacy-controlled segment. These three entities exemplify divergent strategic postures: cosmetic-brand extension leveraging research networks, physician-dispensed platform competition with mass-market alternatives, and distribution control limiting counterfeiting exposure respectively.
| Leading Market Players |
|---|
| Obagi Cosmeceuticals LLC |
| Unilever plc |
| Galderma S.A. |
| Candela Medical |
| Beiersdorf AG |
| L’Oréal S.A. |
| Johnson & Johnson |
| Pierre Fabre Dermo-Cosmétique |
| AbbVie Inc. |
| Others |
Supply & Pricing Matrix
East Asian fermentation clusters anchor global kojic acid supply, and their capacity utilization rates transmit directly into formulation pricing power for European skincare clinics navigating REACH compliance deadlines. Brazilian oleochemical processors meanwhile leverage domestic feedstock access to undercut import-dependent competitors on azelaic acid contract terms.
Pricing Analysis
Cost-plus contracts with oleochemical price indexation dominate active ingredient procurement between Brazilian formulators and domestic grain processors. Three-tier pricing structure across premium liposomal serums, standard emulsion creams, and economy lotion formats separates physician-dispensed channels from mass-market retail. Pricing pressure stems from niacinamide substitution at mass-market price points capturing mild hyperpigmentation cases. Retail pharmacy buyers exhibit highest price sensitivity; dermatology clinics purchasing bundled device-protocol packages show lowest.
Supply Chain Analysis
Upstream oleochemical feedstocks from Brazilian and German cereal grain processors feed azelaic acid fermentation capacity, while East Asian fungal fermentation facilities concentrate kojic acid output. Active ingredient supply draws from fermentation-derived tyrosinase inhibitors, synthetic retinoid precursors, and peptide-based melanin suppressors. Single-source vulnerability concentrates in East Asian kojic acid clusters exposed to customs processing volatility. Distribution runs through specialty pharmacy controls in the United States, physician-dispensed platforms in Brazil and South Korea, and direct-to-consumer tele-dermatology channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: FDA and EMA safety reviews of hydroquinone concentrations create compliance barriers that favor established players with reformulation expertise and dossier resubmission capabilities.
For Market Incumbents: Insulate prescription channel positioning through captive supply of azelaic acid from Brazilian oleochemical partnerships, while accelerating nano-encapsulation patent licensing to block generic liposomal entrants. Regulatory friction on hydroquinone concentration limits threatens legacy product lines; vertical integration into domestic fermentation capacity reduces East Asian supply exposure. For New Entrants and Emerging Players: Physician-dispensed combination therapies in Mumbai and Bangalore outpatient clinics represent the most penetrable entry point, bypassing CDSCO import friction through local formulation partnerships. Microneedle patch technology paired with tyrosinase inhibitors opens at-home treatment segments previously reserved for clinical laser protocols; direct-to-consumer tele-dermatology subscription models capture convenience-prioritizing millennial demographics. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors clinic-network integrators with bundled device-topical service capabilities over pure-play topical formulators. Long-term viability across the projection horizon rests on regulatory navigation expertise and delivery system patent estates. Acquisition targets should demonstrate REACH-compliant active ingredient portfolios and liposomal encapsulation capabilities. The signal to watch is FDA hydroquinone concentration limit finalization timing.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Investment | EMA REACH dossier resubmission capabilities differentiate European suppliers amid kojic acid scrutiny. |
| Nano-Encapsulation Patent Licensing | Liposomal delivery system patents protect premium positioning against generic serum entrants. |
| Clinic Network Acquisition | Bundled device-topical protocols in São Paulo and Seoul expand per-patient revenue capture. |
| Domestic Fermentation Capacity Buildout | Bavarian and North Rhine-Westphalian oleochemical investments reduce East Asian supply dependence. |
| Tele-Dermatology Platform Integration | Direct-to-consumer prescription services compress traditional clinic referral funnels in coastal US markets. |
Research Methodology
A spread of perspectives from dermatology clinic operators, pharmaceutical formulation chemists, regulatory affairs specialists, and specialty pharmacy procurement managers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through FDA 510(k) filings, EMA marketing authorization applications, ClinicalTrials.gov protocol registries, and ANVISA import registration databases. Bottom-up patient volume modeling and top-down market sizing triangulated on segment-level estimates.
Demand-supply balance framing anchored the analytical framework across the analysis window, with segmentation modeling spanning product type, active ingredient class, customer channel, and formulation architecture. CAGRs derived from patient population growth, treatment protocol adoption curves, and pricing trajectory assumptions. Forecast inputs incorporated dermatology clinic consolidation rates in Brazil and South Korea, and tele-dermatology platform penetration in United States urban coastal markets.
Practitioners should monitor FDA hydroquinone concentration limit finalization, EMA REACH dossier deadline extensions, and East Asian fermentation facility shipping volatility for early signals requiring forecast revision. Cross-checking against IMS Health prescription audit data and Circana retail skincare tracking is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Scar Treatment Oils Market
Dermatology
Impetigo Treatment Market
Dermatology
Dermabrasion and Micro Needling Market
Dermatology
Seborrheic Dermatitis Treatment Market
Dermatology
Global Dermatitis Herpetiformis Market
Dermatology
Global Hirsutism Market
Dermatology
US and Canada Skin Cancer Dermatology Market
Dermatology
Derma Rollers Market
Dermatology
Microdermabrasion Market
Dermatology
Atopic Dermatitis Treatment Market
Dermatology
Atopic Dermatitis Therapeutics Market
Dermatology
Global Dermatology Cro Market
Dermatology
Microneedling Market
Dermatology
Athletes Foot (Tinea Pedis) Treatment Market
Dermatology
Skin Cancer Market
Dermatology
Dermatology Devices Market