
 Japan Scar Treatment Market | 2026-2036
Japan Scar Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Scar Treatment Market Insights
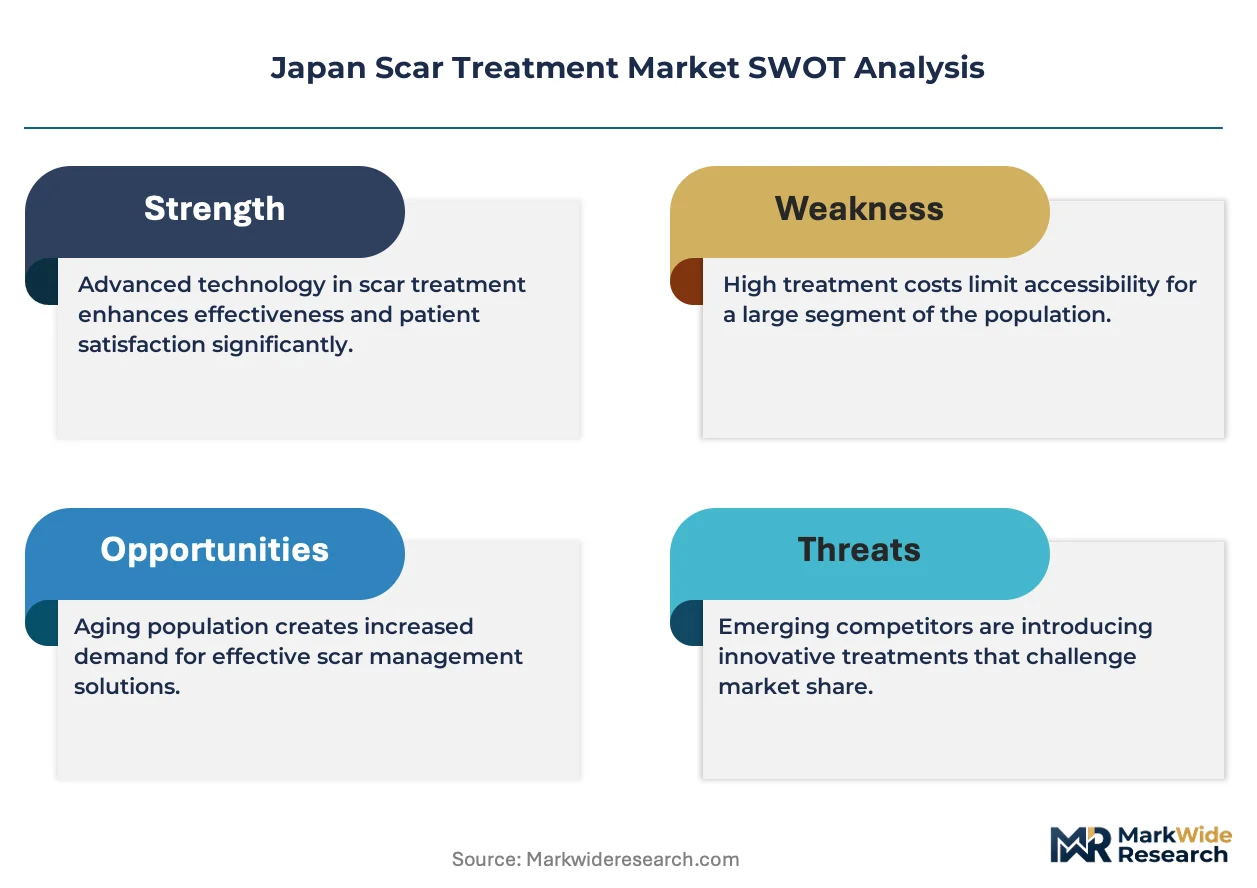
PMDA medical device certification cycles for laser and energy-based scar treatment systems is collapsing from historical norms, compressing market access timelines for domestic and imported equipment. Rohto Pharmaceutical Co., Ltd. leverages its pharmacy channel dominance to sustain over-the-counter gel and cream distribution across Japan's 60,000-plus drugstores. Mandom Corporation competes through specialized silicone sheet formulations that anchor its position in post-surgical patient kits supplied to major hospital chains. Kao Corporation differentiates via dermatological R&D pipelines that extend its consumer skincare credibility into clinical-adjacent scar management products.
Japan scar treatment encompasses topical formulations, occlusive dressings, and energy-based modalities designed to modulate collagen remodeling and reduce fibrous tissue visibility following dermal injury. Silicone-based products function through hydration occlusion and static pressure mechanisms, while fractional laser devices operate at 1,540 nm to 2,940 nm wavelengths targeting scar collagen thermal disruption without full epidermal ablation. Cream and gel segments maintain volume leadership through pharmacy and homecare accessibility, yet laser devices capture disproportionate value pools as clinic-based procedural revenue per treatment exceeds topical alternatives by an order of magnitude. Post-surgical applications structurally dominate procedure volumes given Japan's elevated cesarean section rates and aging-related surgical interventions, though acne scar revision represents the fastest-expanding application as younger demographics seek fractional laser and microneedling protocols.
METI administers Japan's medical device quality management system registration aligned with Ministerial Ordinance No. 169, while PMDA conducts premarket reviews that determine reimbursement eligibility under MHLW fee schedules. This regulatory architecture shapes competitive dynamics by favoring manufacturers with established Japanese subsidiary infrastructure and clinical trial capabilities, effectively filtering market participants based on compliance investment capacity. Stakeholders must monitor MHLW biennial fee schedule revisions and PMDA real-world evidence guidance evolution, as these mechanisms determine whether advanced energy-based scar modalities achieve sustainable clinic reimbursement or remain confined to elective cash-pay channels.
Market Dynamics
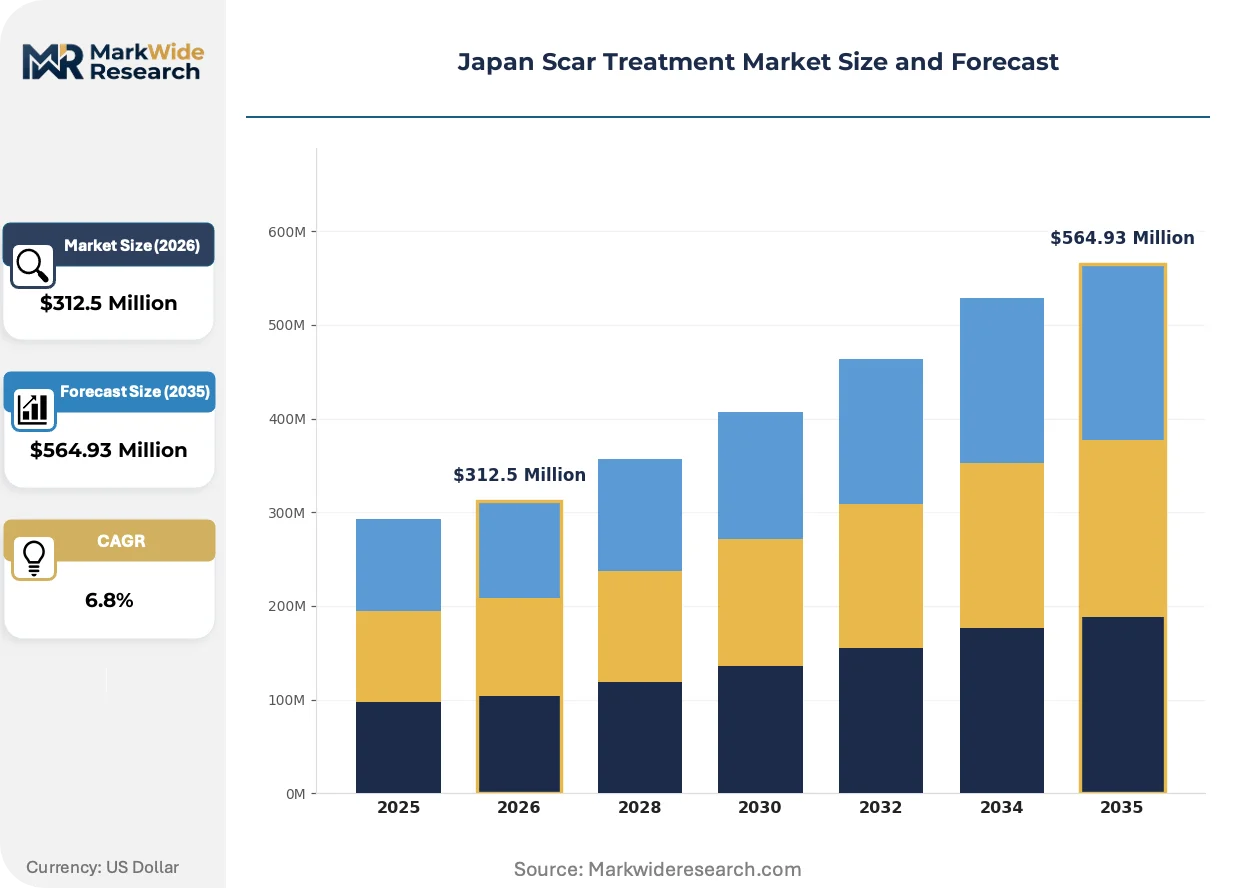
Japan's scar treatment market is being reshaped by the collapse of PMDA medical device certification cycles, which is compressing market access timelines for both domestic manufacturers and imported energy-based equipment while simultaneously accelerating clinic-level capital deployment.
Growth Catalysts
- Reimbursement Expansion:MHLW biennial fee schedule revisions for outpatient dermatological procedures are accelerating investment in laser and energy-based devices across Tokyo and Osaka clinic networks.
- Post-Surgical Volume:Elevated cesarean section rates and aging-related surgical interventions in Japan's hospital system structurally dominate procedure volumes for scar revision services.
- Fractional Laser Adoption:Devices operating at 1,540 nm to 2,940 nm wavelengths targeting scar collagen thermal disruption without full epidermal ablation are expanding dermatology center service menus.
Market Restraints
- Input Cost Volatility:Medical-grade silicone raw material prices fluctuate with petrochemical feedstock markets, squeezing margins for occlusive dressing manufacturers supplying hospital chains.
- Regulatory Friction:METI Ministerial Ordinance No. 169 quality management system registration requirements favor established Japanese subsidiary infrastructure, filtering market participants by compliance investment capacity.
- Substitution Threat:Over-the-counter gel and cream formulations distributed through Japan's 60,000-plus drugstores capture patient preference for homecare accessibility over clinic-based procedural alternatives.
Strategic Opportunities
- Kanto Region Concentration:Aesthetic medicine density and patient willingness to pay for cosmetic outcomes in Tokyo prefecture outpace other Japanese regions, creating premium service expansion potential.
- Acne Scar Applications:Younger demographics seeking fractional laser and microneedling protocols represent the fastest-expanding application segment within Japan's dermatology market.
- Channel Innovation:Pharmacy channel dominance enables over-the-counter scar management products to reach post-surgical patients through retail distribution networks adjacent to hospital discharge pathways.
Industry Challenges
- Certification Timeline Compression:PMDA premarket review acceleration demands enhanced clinical trial capabilities from manufacturers seeking reimbursement eligibility under MHLW fee schedules.
- Reimbursement Sustainability Risk:Advanced energy-based scar modalities face uncertainty over whether MHLW will assign sustainable clinic reimbursement codes or confine treatments to elective cash-pay channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Scar Treatment Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Gels, Silicone Sheets, Laser Devices Application: Post-Surgical, Burns, Acne, Trauma End User: Hospitals, Clinics, Homecare, Dermatology Centers Distribution Channel: Online Stores, Pharmacies, Supermarkets, Direct Sales |
| Companies Covered | Rohto Pharmaceutical Co., Ltd., Mandom Corporation, Kao Corporation, Smith & Nephew PLC, Lumenis Be Ltd., Merz Pharma GmbH & Co. KGaA, Molnlycke Health Care AB, Sonoma Pharmaceuticals, Inc., Newmedical Technology Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Scar Treatment Market Trends and Innovations
Technology convergence and regulatory acceleration are fundamentally altering competitive positioning in Japan's scar treatment landscape, with energy-based modalities capturing disproportionate value pools despite topical formulations maintaining volume leadership.
Fractional laser technology is bifurcating the scar treatment market by creating distinct tiers between high-value clinic-based procedures and accessible homecare alternatives. Dermatology centers in Tokyo and Osaka are expanding service menus for laser-based scar revision at accelerating pace. This technology is compressing revenue per patient for traditional occlusive dressing manufacturers while expanding procedural revenue pools for equipped clinics.
PMDA medical device certification cycles are collapsing from historical norms under evolving real-world evidence guidance, reshaping competitive dynamics for imported equipment. Domestic and foreign manufacturers with established Japanese subsidiary infrastructure capture accelerated market access timelines. Energy-based device segments are responding by prioritizing clinical trial investment and local regulatory affairs capabilities over pure technology differentiation.
Patient preference patterns are rotating toward cosmetic outcomes in younger demographics, disrupting traditional post-surgical scar management pathways. Acne scar revision demand is displacing purely functional recovery protocols in Kanto region dermatology practices. This behavioral shift is most visible in Tokyo prefecture, where aesthetic medicine density supports premium pricing for fractional laser and microneedling protocols outside standard reimbursement frameworks.
Japan Scar Treatment Market Segmentation
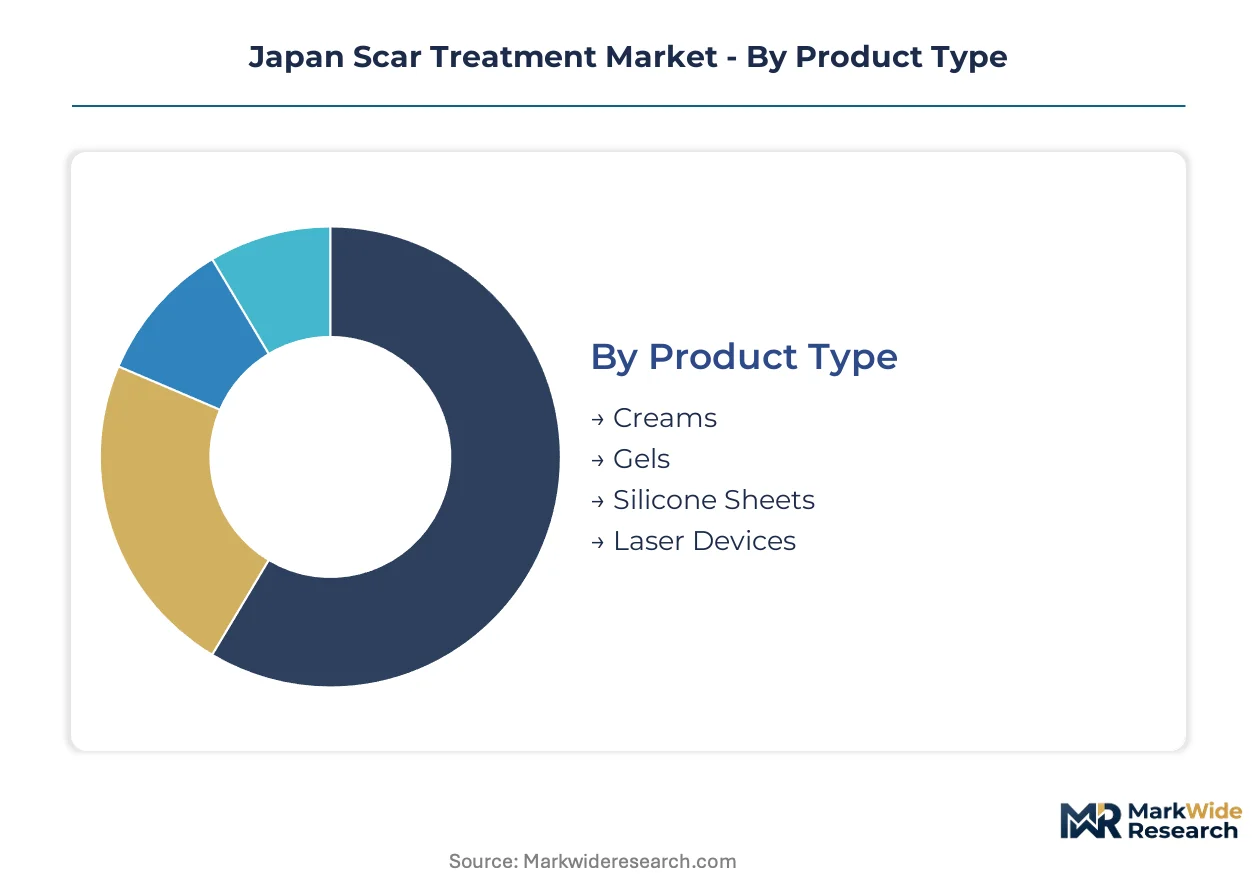
Scar treatment products in Japan traverse distinct commercial pathways determined by regulatory classification and patient access patterns. Channel economics fundamentally shape how manufacturers prioritize segment development and resource allocation across the value chain.
Product Type:
Pharmacy shelves capture high-velocity topical formats while clinic networks concentrate value-intensive energy-based systems.
- Creams:Emulsion-based formulations containing onion extract, allantoin, or vitamin E derivatives hydrate superficial scar tissue. Kanto region drugstores move the highest unit volumes as post-surgical patients seek homecare convenience following hospital discharge.
- Gels:Silicone gel variants deliver occlusive hydration through transparent, cosmetically acceptable films that accommodate facial application. Younger demographics in Tokyo and Osaka prefectures favor gels for acne scar management due to daytime wearability under makeup.
- Silicone Sheets:Medical-grade polymer dressings apply sustained pressure and hydration to hypertrophic and keloid formations. Hospital procurement channels dominate volume as surgical discharge kits incorporate standardized sheet protocols.
- Laser Devices:Fractional and ablative systems operating at 1,540-2,940 nm wavelengths target collagen remodeling through controlled thermal injury. Dermatology centers in metropolitan clusters capture disproportionate revenue per procedure despite lower treatment frequency.
By volume, creams lead. By growth pace, laser devices are expanding most quickly.
Application:
Procedure origin determines reimbursement eligibility and channels patient flow between institutional and retail purchasing environments.
- Post-Surgical:Cesarean sections, orthopedic interventions, and cardiac procedures generate structured scar management protocols within Japan's hospital system. MHLW fee schedule coverage for outpatient dermatological follow-up accelerates clinic investment in revision services.
- Burns:Thermal and chemical injuries requiring specialized pressure garment and sheet combinations concentrate demand at burn centers and rehabilitation facilities. Scar contracture prevention drives long-term silicone product utilization.
- Acne:Atrophic and hypertrophic facial scarring among younger demographics fuels fractional laser and microneedling demand. Kanto region dermatology practices report steepest patient volume acceleration for cosmetic-motivated revision outside standard reimbursement.
- Trauma:Accident-related lacerations and abrasions create episodic demand patterns tied to emergency department volumes and subsequent specialist referral pathways.
Post-surgical applications anchor volume baselines. Acne revision climbs the fastest as aesthetic medicine density deepens in urban prefectures.
End User:
Institutional purchasing power contrasts with fragmented homecare decision-making across Japan's scar treatment landscape.
- Hospitals:Acute care facilities standardize silicone sheet protocols for surgical discharge kits and maintain referral relationships with dermatology specialists for complex revision cases.
- Clinics:Outpatient dermatology and plastic surgery practices in Tokyo and Osaka are expanding laser device fleets following MHLW reimbursement revisions for energy-based procedures.
- Homecare:Self-directed topical application dominates total patient encounters as pharmacy accessibility and over-the-counter marketing sustain cream and gel preference.
- Dermatology Centers:Specialized facilities concentrate fractional laser and microneedling capacity, capturing premium pricing for cosmetic outcomes in Kanto region aesthetic medicine clusters.
Homecare commands treatment frequency leadership. Dermatology centers gain share fastest on procedural revenue expansion.
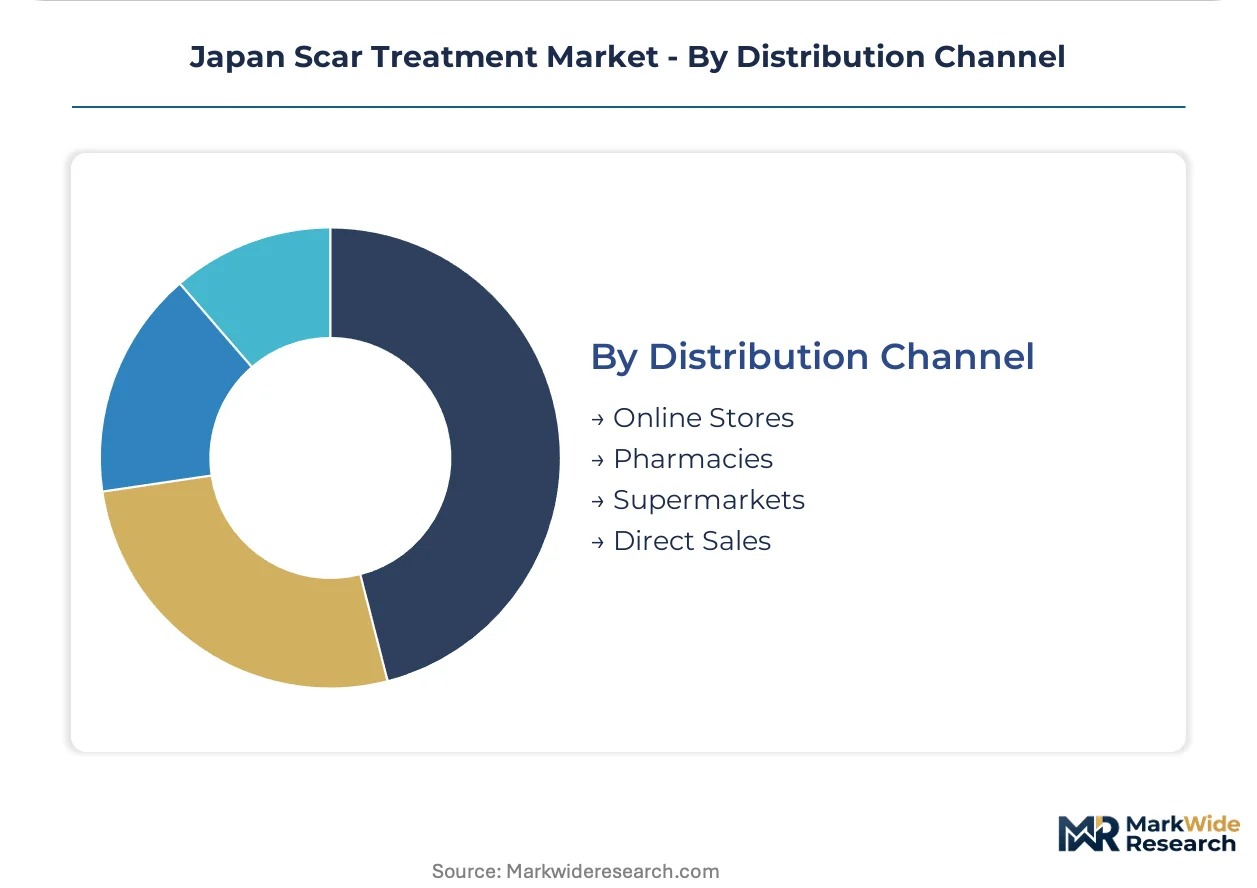
Distribution Channel:
Physical retail maintains dominance for topical formats while device procurement flows through specialized sales infrastructure.
- Online Stores:E-commerce platforms aggregate niche silicone sheet brands and discounted topical formulations, capturing price-sensitive patients outside major metropolitan pharmacy networks.
- Pharmacies:Japan's 60,000-plus drugstores anchor cream and gel distribution through pharmacist recommendation and prominent shelf placement adjacent to wound care categories.
- Supermarkets:Mass retail channels stock entry-price topical variants for impulse and convenience purchasing, though professional credibility lags pharmacy positioning.
- Direct Sales:Laser device manufacturers deploy specialized clinical specialists to dermatology centers and hospital procurement departments, supporting capital equipment evaluation and PMDA compliance navigation.
Pharmacies lead by transaction volume. Online stores are gaining share fastest as digital purchasing habits deepen among younger demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's scar treatment demand concentrates in metropolitan hospital networks and aesthetic medicine clusters where surgical volume and discretionary spending intersect. Patient archetypes span post-surgical discharge cohorts seeking homecare solutions and younger demographics pursuing cosmetic revision outside reimbursement frameworks.
Kanto/Tokyo
Tokyo prefecture dermatology centers command Japan's highest procedural revenue per scar revision treatment. MHLW outpatient dermatological fee schedule revisions accelerate clinic investment in fractional laser fleets across the capital region. Aesthetic medicine density in Shibuya and Ginza districts supports premium cash-pay positioning for energy-based modalities.
Kansai/Osaka
Osaka's hospital chains standardize silicone sheet protocols for post-surgical discharge kits following cesarean and orthopedic interventions. PMDA medical device certification timeline compression enables faster market access for imported laser equipment in Kansai clinic networks. The Osaka-Kobe corridor concentrates manufacturing distribution nodes serving western Japan pharmacy channels.
Chubu/Nagoya
Nagoya's aging demographic profile elevates surgical intervention rates and subsequent scar management demand. METI Ministerial Ordinance No. 169 quality management compliance requirements filter device manufacturer participation in Chubu procurement. Regional medical device distributors maintain inventory hubs supplying Aichi and Gifu prefecture clinics.
Kyushu
Fukuoka's burn centers and rehabilitation facilities drive specialized pressure garment and sheet utilization for thermal injury protocols. MHLW biennial fee schedule uncertainty constrains clinic investment in advanced energy-based modalities relative to Kanto benchmarks. Pharmaceutical wholesalers extend pharmacy channel coverage across Kyushu's island geography.
Hokkaido
Sapporo's dispersed population geography favors homecare topical formats over clinic-dependent procedural alternatives. Cold climate conditions extend wound healing timelines and amplify silicone occlusion demand for hypertrophic scar prevention. Regional drugstore chains anchor cream and gel distribution outside major hospital procurement networks.
Japan Scar Treatment Market Competitive Landscape
Player mix skews toward diversified pharmaceutical conglomerates with pharmacy channel dominance alongside specialized dermatological device manufacturers. Market structure exhibits tiered consolidation where consumer healthcare divisions of large chemical conglomerates control topical volume, while mid-cap device specialists capture procedural value pools. Strategic archetypes span pharmacy-centric consumer health operators, hospital-contract silicone suppliers, and clinic-focused energy-based equipment vendors. Competitive moves concentrate on PMDA certification acceleration and MHLW reimbursement code pursuit.
Within the pharmaceutical conglomerate tier, Rohto Pharmaceutical Co., Ltd., Mandom Corporation, and Kao Corporation exemplify divergent channel strategies. Rohto Pharmaceutical anchors pharmacy shelf presence across Japan's drugstore network. Mandom Corporation occupies a position within hospital-contract supply chains. Kao Corporation represents consumer skincare credibility extension into clinical-adjacent positioning.
| Leading Market Players |
|---|
| Rohto Pharmaceutical Co., Ltd. |
| Mandom Corporation |
| Kao Corporation |
| Smith & Nephew PLC |
| Lumenis Be Ltd. |
| Merz Pharma GmbH & Co. KGaA |
| Molnlycke Health Care AB |
| Sonoma Pharmaceuticals, Inc. |
| Newmedical Technology Inc. |
| Others |
Pricing and Supply Chain Analysis
Silicone polymer production scale in Japan's petrochemical corridor establishes minimum efficient scale thresholds that concentrate supply among three domestic compounders and directly anchor price floors for medical-grade sheet formulations. MHLW reimbursement revisions for outpatient dermatological procedures compress clinic equipment payback periods, accelerating capital deployment into fractional laser fleets while squeezing margin buffers for topical manufacturers competing through pharmacy channel volume.
Pricing Analysis
Cost-plus contracts with quarterly medical-grade silicone indexation to naphtha feedstock benchmarks dominate hospital procurement agreements for occlusive dressing supply. Three-tier pricing structure across premium laser systems, standard energy-based devices, and economy topical formats separates clinic-based procedural revenue from homecare accessibility tiers. Cost compression in silicone gel segments is intensifying because petrochemical volatility transfers directly to compounder margins. Hospital procurement committees exhibit lowest price sensitivity for PMDA-certified laser equipment, while pharmacy channel consumers drive volume through promotional elasticity for cream and gel alternatives.
Supply Chain Analysis
Japan and Germany anchor precision laser source manufacturing for dermatological applications, while South Korea supplies fractional handpiece assemblies and optical components. Medical-grade silicone feedstock draws from Nagoya petrochemical complexes and imported polymer resins, with specialized coating substrates sourced from Taiwanese film manufacturers. Single-source vulnerability concentrates in 1,540-2,940 nm laser diode supply from specific German and Japanese foundries. Distribution runs through hospital procurement consortia and GPO contracts for institutional segments, pharmacy wholesale networks for retail topical formats, and direct clinical specialist engagement for capital equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's scar treatment market sits at a platform-economics inflection where PMDA certification data interoperability between device manufacturers and clinic networks is reshaping competitive moats around real-world evidence generation and reimbursement code capture.
For Market Incumbents: Secure MHLW reimbursement code permanence through sustained clinical trial investment in fractional laser outcomes data, insulating procedural revenue from cash-pay channel migration. Deepen backward integration into medical-grade silicone compounding to defend margin position against petrochemical feedstock volatility and emerging Korean supplier encroachment.
For New Entrants and Emerging Players: Lead with acne scar revision protocols targeting Tokyo and Osaka dermatology centers outside standard reimbursement frameworks, where aesthetic medicine density supports premium cash-pay positioning. Exploit PMDA certification timeline compression by establishing Japanese subsidiary infrastructure and local clinical affairs capabilities ahead of imported equipment competitors.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among clinic-focused energy-based device vendors with installed base service contracts and consumable attachment rates. Long-term viability centers on manufacturers bridging pharmaceutical distribution credibility with procedural technology platforms. Monitor MHLW biennial fee schedule revision timing as the critical inflection signal for sustainable reimbursement code assignment versus elective channel confinement.
| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Certification Acceleration | Compressed review timelines under evolving real-world evidence guidance reshape market access for imported laser systems. |
| MHLW Reimbursement Strategy | Fee schedule code pursuit determines whether energy-based modalities achieve sustainable clinic coverage or remain cash-pay. |
| Hospital System Partnership | Standardized silicone sheet protocols in surgical discharge kits anchor volume baselines for post-surgical applications. |
| Pharmacy Channel Expansion | Rohto's drugstore network dominance enables over-the-counter topical reach across Japan's 60,000-plus retail points. |
| Software Companion Development | Digital treatment planning platforms differentiate clinic-based laser services and support outcome documentation for reimbursement. |
Research Methodology
Initial hypotheses were tested against primary input from dermatology clinic operators, hospital procurement managers, medical device regulatory affairs specialists, and pharmaceutical channel sales directors, and refined through secondary validation against PMDA premarket review databases, MHLW fee schedule documentation, METI Ministerial Ordinance No. 169 compliance filings, and hospital procurement consortium contract disclosures. Bottom-up demand modeling across product type, application, and end-user segments was triangulated with top-down market sizing from equipment import statistics and pharmacy distribution audit data.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects within each segmentation dimension, with analytical framework incorporating product format, procedural application, institutional purchaser type, and regional regulatory cluster. CAGRs were derived from segment-level growth trajectory convergence, incorporating PMDA certification cycle dynamics, MHLW reimbursement revision patterns, and petrochemical feedstock cost pass-through assumptions specific to silicone-based product manufacturing.
The analysis sits within stated boundaries; outcomes outside sustained MHLW outpatient dermatological fee schedule support or accelerated PMDA real-world evidence guidance adoption would require recalibration. Forecasts reflect documented assumptions regarding reimbursement code permanence, clinic capital deployment cycles, and pharmacy channel promotional intensity. Recalibration cycles align with material shifts in MHLW biennial fee schedule revisions, PMDA guidance evolution, and medical-grade silicone polymer supply contract renegotiations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Androgenetic Alopecia Market
Dermatology
Hyperpigmentation Treatment Market
Dermatology
Dermatophytic Onychomycosis Treatment Market
Dermatology
Psoriasis Treatment Market
Dermatology
Dermatological Products Market
Dermatology
Europe Scar Treatment Market
Dermatology
Dermatology Diagnostic Devices and Therapeutics Market
Dermatology
Acne Scar Treatment Market
Dermatology
Pigmented Lesion Treatment Market
Dermatology
Dermatology Drugs Market
Dermatology
China Scar Treatment Market
Dermatology
Skin Hyperpigmentation Treatment Market
Dermatology
Atopic Dermatitis Treatment Market
Dermatology
Skin Excision Market
Dermatology
Keloid Treatment Market
Dermatology
Acne Vulgaris Treatment Market