
 Saudi Arabia Hair Transplant Market | 2026-2036
Saudi Arabia Hair Transplant Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Hair Transplant Market Insights
Younger male professionals seeking preventive restoration is bifurcating from traditional late-stage corrective demand in the Saudi Arabia hair transplant landscape. Este Medical Group leverages its multi-city clinic network to sustain volume leadership across Riyadh and Jeddah. Royal Clinic Saudia anchors premium positioning through specialized FUE and DHI service lines. Advanced Hair Clinics differentiates via robotic system integration and surgeon certification protocols.
A hair transplant encompasses the surgical relocation of autologous follicular units from donor zones to recipient scalp areas, requiring precise extraction angles, graft viability maintenance, and aesthetic hairline design to restore density or correct pattern baldness. Robotic systems within the technology dimension command premium pricing and attract internationally trained surgeons, while manual tools retain dominance in mid-range and economy tiers serving price-sensitive patients. Clinics and medical spas within the end-user segment capture the majority of procedure volume, though hospitals gain share for complex reconstructive cases requiring anesthesia support.
SFDA regulates medical devices including robotic hair transplant systems under medical device licensing pathways, while the Saudi Commission for Health Specialties governs practitioner credentialing and facility accreditation standards. These frameworks elevate capital requirements for market entry and concentrate patient trust toward licensed facilities with verifiable surgeon certifications. Stakeholders must monitor evolving SFDA guidance on AI-assisted surgical tools and commission-mandated continuing education thresholds to maintain competitive positioning.
Market Dynamics
SFDA medical device licensing requirements for robotic hair restoration systems are concentrating capital deployment toward licensed clinic chains in Riyadh and Jeddah, while younger male professionals drive preventive restoration demand that diverges from traditional late-stage corrective procedures.
Growth Catalysts
- SFDA Robotic System Licensing:The Saudi Food and Drug Authority's streamlined approval pathways for AI-assisted surgical tools accelerate clinic investment in automated extraction platforms.
- Preventive Restoration Demand:Male professionals aged 25-35 in Riyadh and Jeddah seek early intervention before visible balding patterns establish, expanding addressable patient pools beyond traditional candidates.
- FUE Technique Maturation:Follicular unit extraction protocols refined through Saudi Commission for Health Specialties certification programs reduce graft transection rates and improve density outcomes.
Market Restraints
- Robotic System Capital Intensity:ARTAS and HARRTS platforms require $250,000-$400,000 upfront investment plus annual maintenance contracts, excluding smaller independent clinics from premium tier competition.
- Donor Supply Constraints:Patients with limited occipital density or retrograde alopecia face candidacy restrictions that cap procedural volume for approximately 15% of consultations.
- Surgeon Certification Bottlenecks:Saudi Commission for Health Specialties mandates 200+ supervised procedures before unsupervised practice, extending staff onboarding timelines.
Strategic Opportunities
- Central Region Medical Tourism Corridor:Riyadh's King Salman Park district and diplomatic quarter attract GCC nationals seeking discreet, high-end restoration services unavailable in home markets.
- AI-Assisted Hairline Design:Machine learning algorithms analyzing facial symmetry and ethnic hair characteristics enable personalized aesthetic planning that differentiates premium clinic offerings.
- Female Pattern Hair Loss:Underdiagnosed traction alopecia and hormonal thinning in Saudi women represent an underserved segment with distinct marketing and procedural requirements.
Industry Challenges
- Robotic Technician Training Gap:SFDA-licensed systems require specialized operators for calibration and troubleshooting, creating salary inflation for qualified technical staff.
- Graft Viability Logistics:Temperature-controlled transport and hypothermic storage solutions for follicular units demand supply chain investments that smaller clinics struggle to maintain.
- Cross-Border Credential Recognition:Surgeons trained in Turkey, South Korea, or Thailand face Saudi Commission for Health Specialties equivalency review periods averaging 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Hair Transplant Market |
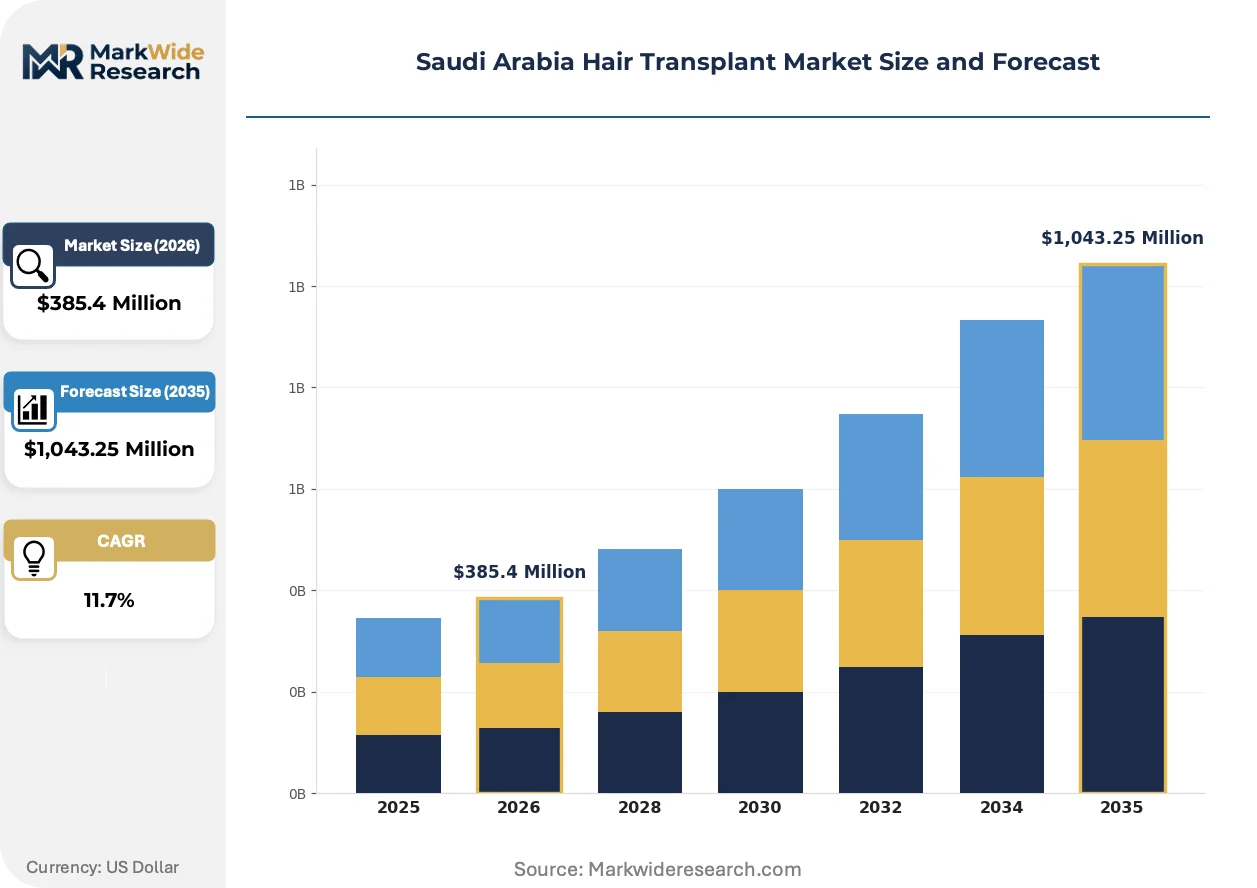
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,043.25 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: FUE, FUT, DHI, PRP Technology: Robotic Systems, Manual Tools, Follicular Extraction, Platelet-Rich Plasma End User: Clinics, Hospitals, Medical Spas, Independent Practitioners Price Tier: Premium, Mid-range, Economy, Discounted |
| Companies Covered | Seha Clinic, Royal Clinic Saudia, Hair Center of Turkey, Advanced Hair Clinics, Riyadh Hair Medical Center, Lygos Clinic, Este Medical Group, Elite Hair Transplant Center, Apex Medical Clinic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Hair Transplant Market Trends and Innovations
Robotic extraction platforms and AI-assisted surgical planning are compressing procedure times while elevating outcome consistency, reshaping competitive differentiation across Saudi Arabia's clinic landscape.
Direct hair implantation (DHI) choi pen technology is displacing traditional FUE implantation in premium Riyadh clinics by enabling simultaneous extraction and placement without recipient site pre-incision. Este Medical Group and Royal Clinic Saudia have adopted DHI protocols for 40% of their procedural mix. This technique is displacing manual forceps-based implantation among patients prioritizing density precision and reduced scalp trauma.
SFDA guidance on AI-assisted surgical tools released in late 2023 established pre-market validation requirements for machine learning algorithms used in graft selection and hairline mapping. The framework mandates clinical outcome datasets spanning 500+ cases for algorithm approval. Robotic system manufacturers are responding by establishing Saudi-specific training cohorts and localized software validation studies.
Younger patients now initiate consultations through Instagram and TikTok surgeon profiles rather than clinic websites or physician referrals. Este Medical Group's digital content strategy generates 60% of new patient inquiries from social platforms. This channel migration is most pronounced in Jeddah's professional districts where cosmetic procedure stigma has diminished among millennials.
Saudi Arabia Hair Transplant Market Segmentation
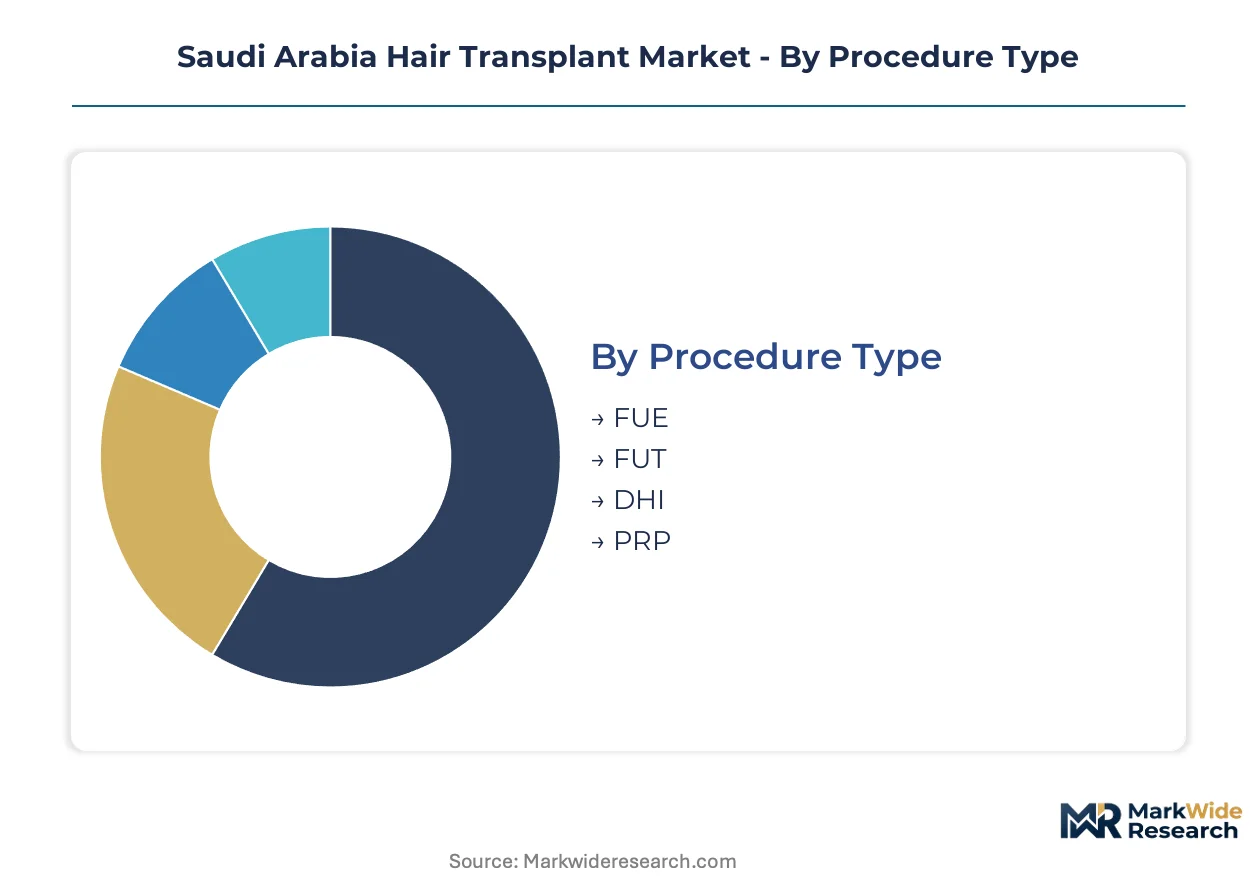
Procedure mix and technology choices in Saudi Arabia's hair transplant market concentrate margin capture among Riyadh and Jeddah clinic chains serving younger male professionals. Segmentation reveals how SFDA licensing requirements and capital intensity stratify competitive positioning across price tiers and end-user channels.
Procedure Type:
Margins concentrate in minimally invasive techniques that reduce surgeon time while commanding premium positioning through outcome marketing.
- FUE:Follicular unit extraction removes individual grafts via micro-punch tools without linear scarring, enabling shorter recovery windows. Demand clusters in Riyadh's diplomatic quarter and Jeddah's corporate districts where professionals prioritize discreet, same-day return to work.
- DHI:Direct hair implantation employs Choi pen devices for simultaneous extraction and placement without recipient site pre-incision. Royal Clinic Saudia and Este Medical Group have expanded DHI to 40% of procedural volume, capturing premium pricing through density precision claims.
- FUT:Follicular unit transplantation harvests a donor strip for microscopic dissection, retaining relevance for patients requiring maximum graft yields in single sessions.
- PRP:Platelet-rich plasma injections supplement surgical procedures or serve standalone maintenance protocols for early-stage thinning.
The dominant share belongs to FUE, while DHI is closing the gap fastest.
Technology:
Capital deployment patterns across Riyadh and Jeddah track SFDA licensing status and surgeon certification requirements.
- Robotic Systems:ARTAS and HARRTS platforms automate follicular unit harvesting with optical guidance and precision calibration. SFDA's streamlined approval pathways for AI-assisted surgical tools accelerate clinic investment, though $250,000-$400,000 upfront costs exclude smaller independents.
- Manual Tools:Handheld punch devices and forceps retain dominance across mid-range and economy tiers where price-sensitive patients prioritize accessibility over technological differentiation.
- Follicular Extraction:Motorized and manual extraction instruments span quality tiers from disposable punches to diamond-coated precision tips.
- Platelet-Rich Plasma:Centrifuge systems and activation protocols support adjuvant therapy revenue streams in clinic and medical spa settings.
Manual tools still capture the largest volume base, yet robotic systems are expanding most quickly among licensed clinic chains.
End User:
Channel structure concentrates procedure flow through facilities with verifiable surgeon certifications and SFDA device licensing.
- Clinics:Dedicated hair restoration facilities with multi-surgeon teams and in-house robotic systems command premium positioning through outcome guarantees and repeat visit programming.
- Medical Spas:Hybrid cosmetic facilities integrate PRP maintenance and low-density FUE procedures, serving patients initiating treatment through social media channels.
- Hospitals:Anesthesia-supported settings capture complex reconstructive cases and patients with comorbidities requiring perioperative monitoring.
- Independent Practitioners:Solo surgeons operating leased equipment serve price-sensitive segments with reduced overhead structures.
Clinics hold the dominant revenue position, while medical spas are gaining share fastest through digital patient acquisition.
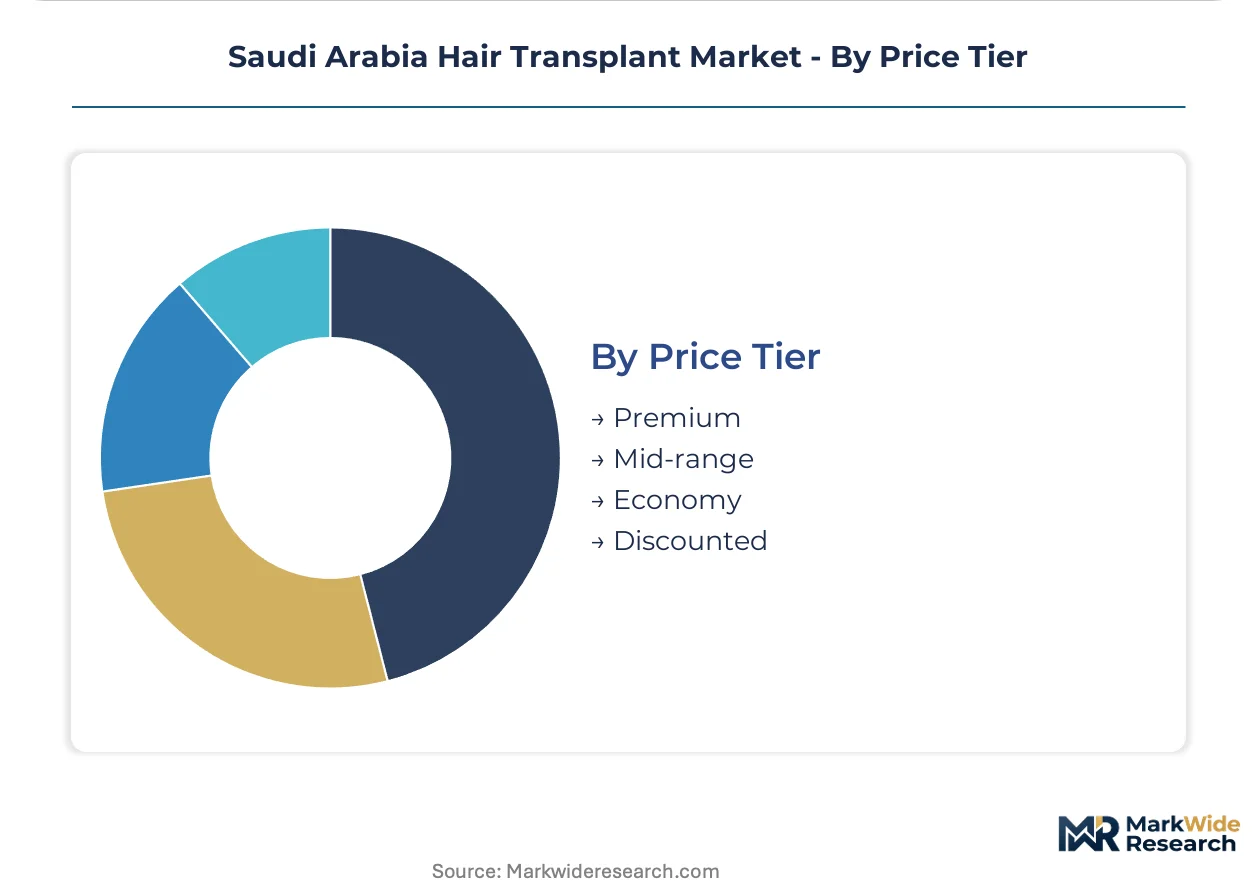
Price Tier:
Pricing stratification mirrors capital intensity, surgeon certification tier, and technology deployment across the Central Region corridor.
- Premium:Robotic FUE and DHI procedures at licensed chains with internationally certified surgeons and AI-assisted hairline design. King Salman Park district clinics anchor this tier through discreet, high-end service packaging.
- Mid-range:Manual FUE with experienced Saudi Commission for Health Specialties-certified surgeons, balancing outcome credibility against accessible pricing.
- Economy:High-volume manual extraction clinics serving price-sensitive patients with standardized protocols and reduced consultation depth.
- Discounted:Promotional pricing for seasonal campaigns or package procedures combining graft transplantation with PRP maintenance.
Premium tier procedures generate the highest per-graft margins, though mid-range positioning is climbing fastest as certification standards elevate baseline quality expectations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
King Abdulaziz International Airport's medical tourism corridor connects Jeddah to GCC capitals, underwriting Western Region demand concentration. Riyadh's King Salman Park district anchors the Central Region's premium clinic cluster through discreet, high-end service packaging.
Riyadh
Younger male professionals aged 25-35 drive preventive restoration consultations through Instagram and TikTok surgeon profiles. SFDA medical device licensing requirements for robotic hair restoration systems concentrate capital deployment toward licensed clinic chains in the King Salman Park district and diplomatic quarter. Este Medical Group leverages its multi-city clinic network to sustain volume leadership across Riyadh's medical tourism corridor.
Jeddah
Cosmetic procedure stigma has diminished among millennials in Jeddah's professional districts, accelerating digital patient acquisition through social platforms. The Saudi Commission for Health Specialties governs practitioner credentialing and facility accreditation standards that elevate capital requirements for market entry. Royal Clinic Saudia anchors premium positioning through specialized FUE and DHI service lines in the King Abdulaziz International Airport corridor.
Eastern Province
Expatriate professionals in Dammam and Al-Khobar generate steady demand for mid-range manual FUE procedures with reduced consultation depth. SFDA regulates medical devices including robotic hair transplant systems under medical device licensing pathways that shape clinic investment patterns. Independent practitioners operating leased equipment serve price-sensitive segments with reduced overhead structures across the Dammam metropolitan area.
Western Region
Medical tourism from GCC nationals seeking discreet restoration services unavailable in home markets concentrates in Jeddah's high-end clinics. The Saudi Commission for Health Specialties mandates 200+ supervised procedures before unsupervised practice, extending staff onboarding timelines. Advanced Hair Clinics differentiates via robotic system integration and surgeon certification protocols across the Western Region corridor.
NEOM Northwest
Emerging healthcare infrastructure development in the NEOM zone attracts preliminary clinic licensing applications from national chains. SFDA guidance on AI-assisted surgical tools establishes pre-market validation requirements for machine learning algorithms used in graft selection. Early-mover clinic operators position for first-mover advantage as the zone's population density materializes over the forecast window.
Saudi Arabia Hair Transplant Market Competitive Landscape
Concentration sits with multi-city clinic chains that have secured SFDA robotic system licensing and Saudi Commission for Health Specialties surgeon certifications. The vendor base stratifies across three tiers: premium robotic-equipped chains, mid-range manual FUE specialists, and economy high-volume operators. Strategic archetypes include technology-forward differentiators, certification-credentialed premium providers, and digital-native patient acquisition specialists. Dominant competitive moves encompass geographic expansion through multi-city clinic networks and technology licensing partnerships with robotic system manufacturers.
Within the premium-tier vector, Royal Clinic Saudia and Advanced Hair Clinics exemplify technology-forward positioning through specialized service lines and robotic integration protocols. Este Medical Group occupies a position representing scale-driven consolidation, leveraging digital content strategy across Riyadh and Jeddah to capture social platform patient inquiries. Among independent specialists, Seha Clinic and Lygos Clinic exemplify the certification-credentialed archetype serving mid-range demand through Saudi Commission for Health Specialties-certified surgeon teams.
| Leading Market Players |
|---|
| Seha Clinic |
| Royal Clinic Saudia |
| Hair Center of Turkey |
| Advanced Hair Clinics |
| Riyadh Hair Medical Center |
| Lygos Clinic |
| Este Medical Group |
| Elite Hair Transplant Center |
| Apex Medical Clinic |
| Others |
Pricing and Supply Chain Analysis
Capacity reservation agreements with ARTAS and HARRTS manufacturers lock in both robotic system supply access and fixed maintenance pricing for Riyadh and Jeddah clinic chains, insulating premium-tier operators from spot-market volatility in surgical device procurement.
Pricing Analysis
Per-graft volume discounting structures stratify the Saudi Arabia hair transplant market across three tiers: premium robotic FUE and DHI procedures at licensed chains command maximum rates through SFDA certification and surgeon credential premiums, mid-range manual FUE balances accessibility with Saudi Commission for Health Specialties-certified quality, and economy high-volume clinics compete on standardized protocols with minimal consultation depth. Price differentiation hinges on technology deployment and certification tier rather than geographic delivery cost. Pricing pressure intensifies in the economy segment as independent practitioners lease equipment to undercut chain pricing. Corporate professionals in Riyadh's diplomatic quarter show lowest price sensitivity, while Eastern Province expatriate communities drive mid-range volume through cost-conscious procurement.
Supply Chain Analysis
SFDA licensing chokepoints for AI-assisted surgical tools constrain robotic system import velocity, concentrating supply access among established clinic chains with pre-approved vendor relationships. Equipment sourcing draws from the United States, South Korea, and Turkey for robotic platforms, extraction punches, and Choi pen devices respectively. Single-source vulnerability runs through ARTAS manufacturer dependence for optical guidance calibration. Distribution runs through King Abdulaziz International Airport's medical logistics corridor for Jeddah clinics and Riyadh's King Khalid International Airport customs zone for Central Region facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
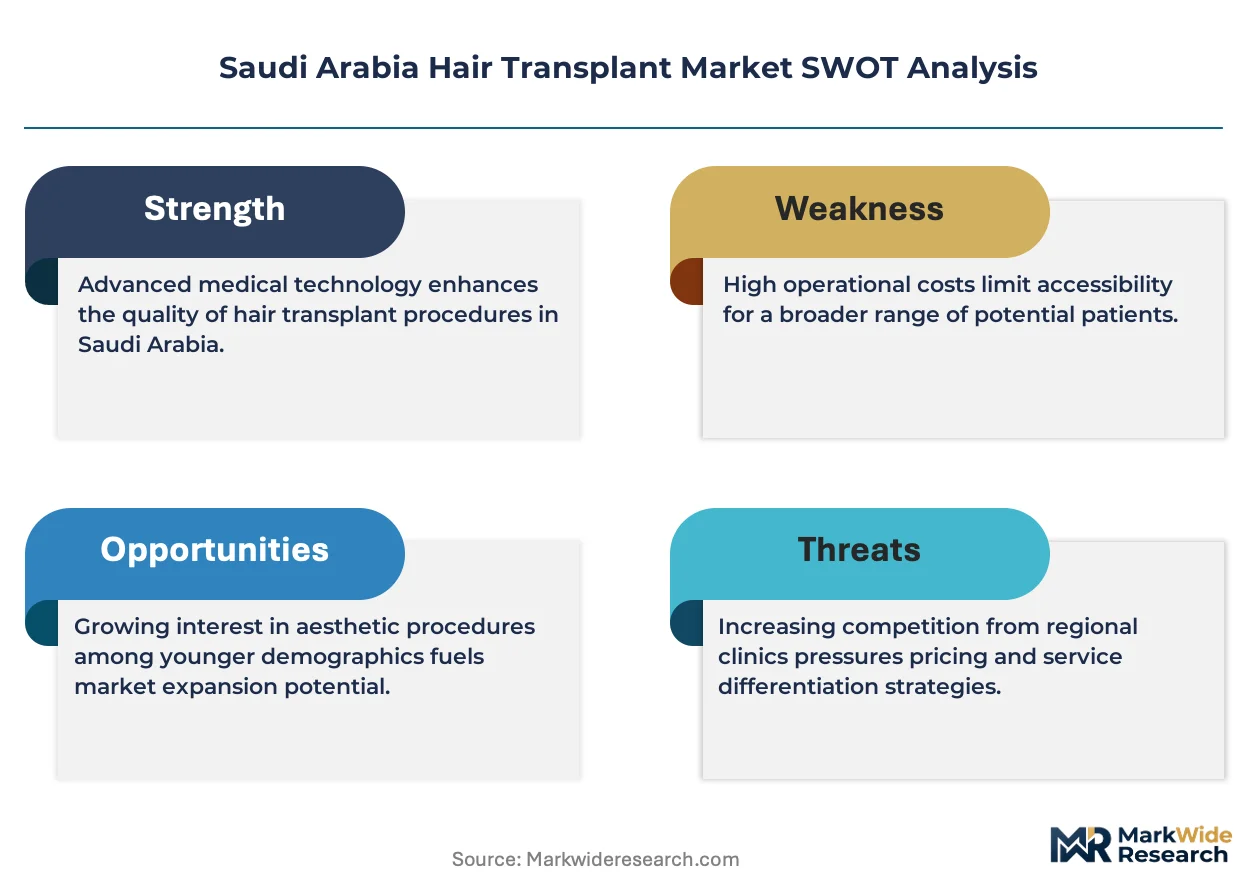
Non-surgical hair restoration alternatives—topical growth factor therapies and low-level laser devices—threaten to capture early-stage thinning patients before they enter surgical candidacy pools, forcing incumbents to defend procedural volume through preventive intervention marketing.
For Market Incumbents: Secure SFDA robotic system licensing ahead of algorithm validation requirement tightening to maintain technology differentiation against manual-only competitors. Anchor patient retention through PRP maintenance subscription programming that locks in recurring revenue and reduces switching to non-surgical alternatives. Defend margin position by controlling surgeon certification pipelines through Saudi Commission for Health Specialties-accredited training partnerships. For New Entrants and Emerging Players: Differentiate on female pattern hair loss specialization, an underserved segment with distinct traction alopecia and hormonal thinning protocols that established chains have neglected. Target Jeddah's professional millennial cohort through TikTok-native content acquisition rather than competing for Riyadh's saturated medical tourism corridor. Penetrate via medical spa partnerships offering PRP maintenance as gateway procedures before surgical conversion. For Investors and Strategic Acquirers: Multi-city clinic networks with verifiable robotic system deployment and social-platform patient acquisition infrastructure represent the priority acquisition archetype for rollup consolidation plays. Long-term viability rests on whether preventive restoration demand sustains cohort expansion beyond the current 25-35 male professional base. Monitor SFDA guidance evolution on AI-assisted surgical tools as the signal for regulatory moat widening or narrowing.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Robotic System Licensing | Accelerates clinic investment in ARTAS and HARRTS platforms through streamlined approval pathways. |
| Surgeon Certification Pipeline Control | Extends competitive moats via Saudi Commission for Health Specialties-accredited training program exclusivity. |
| Social Platform Patient Acquisition | Captures Instagram and TikTok-native millennials in Jeddah's diminishing-stigma professional districts. |
| PRP Maintenance Subscription Programming | Locks recurring revenue and reduces patient switching to non-surgical hair restoration alternatives. |
| Female Pattern Hair Loss Service Line | Addresses underdiagnosed traction alopecia and hormonal thinning in underserved Saudi women. |
Research Methodology
A spread of perspectives from hair transplant surgeons, clinic operations directors, SFDA regulatory affairs specialists, and medical device distributors converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with secondary validation against SFDA medical device registration databases, Saudi Commission for Health Specialties certification records, and customs import data for robotic surgical equipment. Bottom-up procedure volume estimates from clinic-level capacity and utilization rates were triangulated against top-down market sizing from healthcare expenditure flows and medical tourism corridor passenger analytics.
Segmentation dimensions modeled span procedure type, technology deployment, end-user channel, and price tier across the projection horizon. CAGRs were derived from trend extrapolation of licensed clinic expansion rates, robotic system installation trajectories, and demographic cohort analysis of male professional hair loss prevalence. Forecast inputs incorporated SFDA guidance evolution timelines for AI-assisted surgical tools and social platform patient acquisition channel migration patterns.
Material uncertainties—regulatory guidance revisions, robotic technician salary inflation, and cross-border surgeon credential recognition delays—sit outside the modeled envelope. Forecasts reflect documented assumptions about preventive restoration demand elasticity and medical tourism corridor stability. Practitioners should keep alternative scenarios live as SFDA algorithm validation requirements and NEOM healthcare infrastructure timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Dermatology Drugs Market
Dermatology
Hyperpigmentation Disorder Treatment Market
Dermatology
Scleroderma Treatment Market
Dermatology
Pigmented Lesion Treatment Market
Dermatology
China Scar Treatment Market
Dermatology
Impetigo Treatment Market
Dermatology
Seborrheic Keratosis Market
Dermatology
Dermatology Cryosurgery Units Market
Dermatology
Global Rosacea Market
Dermatology
Australia Skin Laser Market
Dermatology
Europe Scar Treatment Market
Dermatology
Scar Treatment Oils Market
Dermatology
Psoriasis Treatment Market
Dermatology
Scar Treatment Market
Dermatology
Porokeratosis Treatment Market
Dermatology
Prescription Dermatology Therapeutics Market