
 Global Rosacea Market | 2026-2036
Global Rosacea Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rosacea Market Foresight
The capability gap between biologics-focused and dermatology-specialist portfolios is rotating competitive capital toward inflammatory skin disease platforms. AbbVie leverages its immunology infrastructure to sustain pipeline momentum in advanced rosacea therapeutics. Galderma anchors its position through dedicated dermatology channel control across European and North American markets. Almirall differentiates by concentrating manufacturing scale on topical formulation expertise.
Rosacea constitutes a chronic inflammatory dermatological condition characterized by facial erythema, telangiectasia, and papulopustular lesions, with topical metronidazole, azelaic acid, and ivermectin formulations serving as first-line interventions to modulate cutaneous immune response and Demodex mite density. The therapy area dimension shows inflammatory rosacea commanding the largest patient pool due to its symptomatic visibility and treatment-seeking behavior, while vascular rosacea segments attract premium device-based interventions. Oral antibiotics occupy a mature position with generic erosion, whereas laser therapy devices represent the fastest-growing margin pool as aesthetic dermatology clinics expand service menus.
The FDA regulates topical rosacea therapies under its dermatological drug approval framework, while the EMA's centralized procedure governs market access across EU member states and REACH compliance shapes excipient sourcing standards for European manufacturers. The EU MDR intensifies clinical evidence requirements for laser therapy devices, redirecting development budgets toward pivotal trial execution. Stakeholders must monitor reimbursement negotiations for device-based procedures against pharmaceutical benefit categories.
Market Dynamics
The FDA's streamlined dermatological approval pathway is compressing commercialization timelines for topical rosacea therapies, redirecting R&D capital toward inflammatory skin disease platforms and accelerating competitive entry.
Growth Catalysts
- EMA Centralized Procedure:The European Medicines Agency's unified market access framework reduces regulatory duplication across EU member states, enabling faster scaling for topical formulation launches.
- Aesthetic Dermatology Clinics:Device-based service expansion in Germany, France, and the United States creates pull-through demand for combination pharmaceutical-device protocols.
- Cutaneous Microbiome Research:Advances in Demodex mite biology and skin barrier dysfunction are validating novel therapeutic targets beyond traditional anti-inflammatory mechanisms.
Market Restraints
- Generic Erosion in Oral Antibiotics:Doxycycline and minocycline commoditization eliminates pricing power for mature systemic rosacea therapies, constraining revenue pools.
- EU MDR Clinical Evidence Requirements:The Medical Device Regulation intensifies pivotal trial obligations for laser and light-based devices, extending development cycles and capital lock-up periods.
- Substitute Procedures:Cosmetic camouflage and over-the-counter skincare routines capture mild rosacea cases before medical intervention, narrowing addressable patient populations.
Strategic Opportunities
- Japan's Aging Dermatology Patient Base:METI-supported aesthetic medicine infrastructure and PMDA's dermatology review experience create favorable conditions for premium device entry.
- Biologics-Dermatology Convergence:IL-17 and IL-23 pathway inhibitors validated in psoriasis are being repurposed for severe inflammatory rosacea subtypes.
- Direct-to-Patient Subscription Models:Telemedicine platforms bypass traditional dermatology referral bottlenecks, capturing diagnosis-avoidant patients in the United States and United Kingdom.
Industry Challenges
- Specialist Recruitment Bottlenecks:Dermatology residency program capacity constraints in the United States and Germany limit clinical trial site activation and post-launch prescriber education.
- Legacy Formulation Integration:New topical actives must demonstrate compatibility with established metronidazole and azelaic acid regimens, complicating protocol design and payer positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rosacea Market |
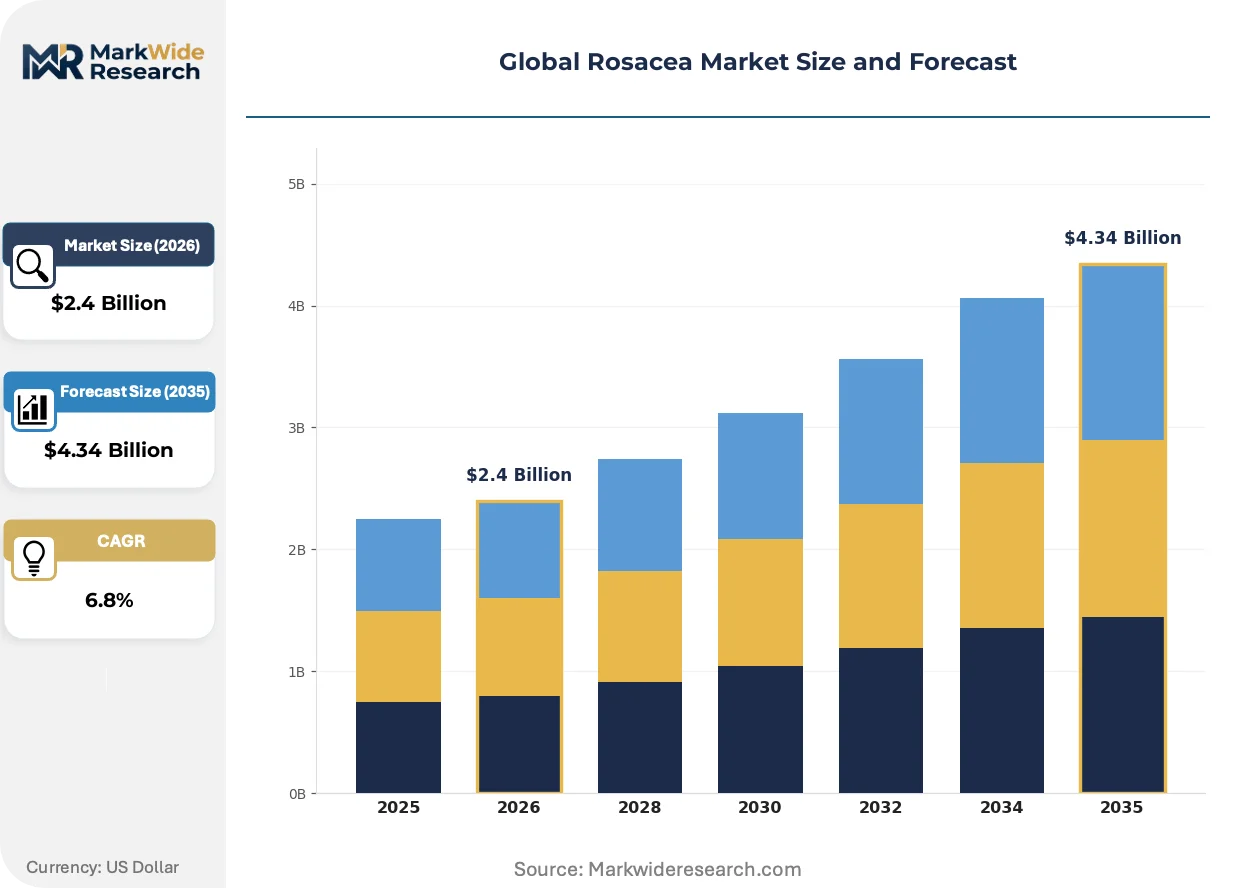
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Creams, Oral Antibiotics, Laser Therapy Devices, Moisturizers, Cleansers Therapy Area: Vascular Rosacea, Inflammatory Rosacea, Rhinophyma, Ocular Rosacea End User: Dermatology Clinics, Specialty Hospitals, Ambulatory Surgical Centers, Pharmacies Distribution Channel: Online Pharmacies, Retail Pharmacies, Hospitals & Clinics, Direct Sales |
| Companies Covered | AbbVie, Mayne Pharma Group Limited, Galderma, Sol-Gel Technologies Ltd., Journey Medical Corporation, Bausch Health, Almirall, Teva Pharmaceutical Industries Ltd., LEO Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rosacea Market Shifts & Advancements
Device-therapy combination protocols are displacing monotherapy as the standard of care, while regulatory frameworks on both sides of the Atlantic reshape competitive positioning and capital allocation priorities.
Microbiome-targeted topical formulations are fragmenting the first-line therapy landscape. These products modulate cutaneous bacterial and mite populations rather than suppressing inflammation directly. Aesthetic dermatology chains in the United States and South Korea are piloting these protocols for treatment-resistant patients. The technology is fragmenting prescriber loyalty toward established metronidazole and azelaic acid franchises.
REACH compliance for excipient sourcing is tightening supply chain requirements for European manufacturers. The regulation mandates full chemical substance registration and safety documentation for formulation components. Topical producers are consolidating supplier relationships and investing in in-house analytical capabilities. Germany and France-based manufacturers face the steepest adaptation costs.
Patient-driven diagnosis through telemedicine platforms is compressing the traditional specialist referral pathway. Smartphone-based symptom assessment tools and asynchronous dermatologist consultations are capturing mild-to-moderate cases. United States and United Kingdom health systems are integrating these channels into reimbursement frameworks. This shift is most visible among working-age patients in urban markets where specialist appointment availability is constrained.
Global Rosacea Market Segmentation
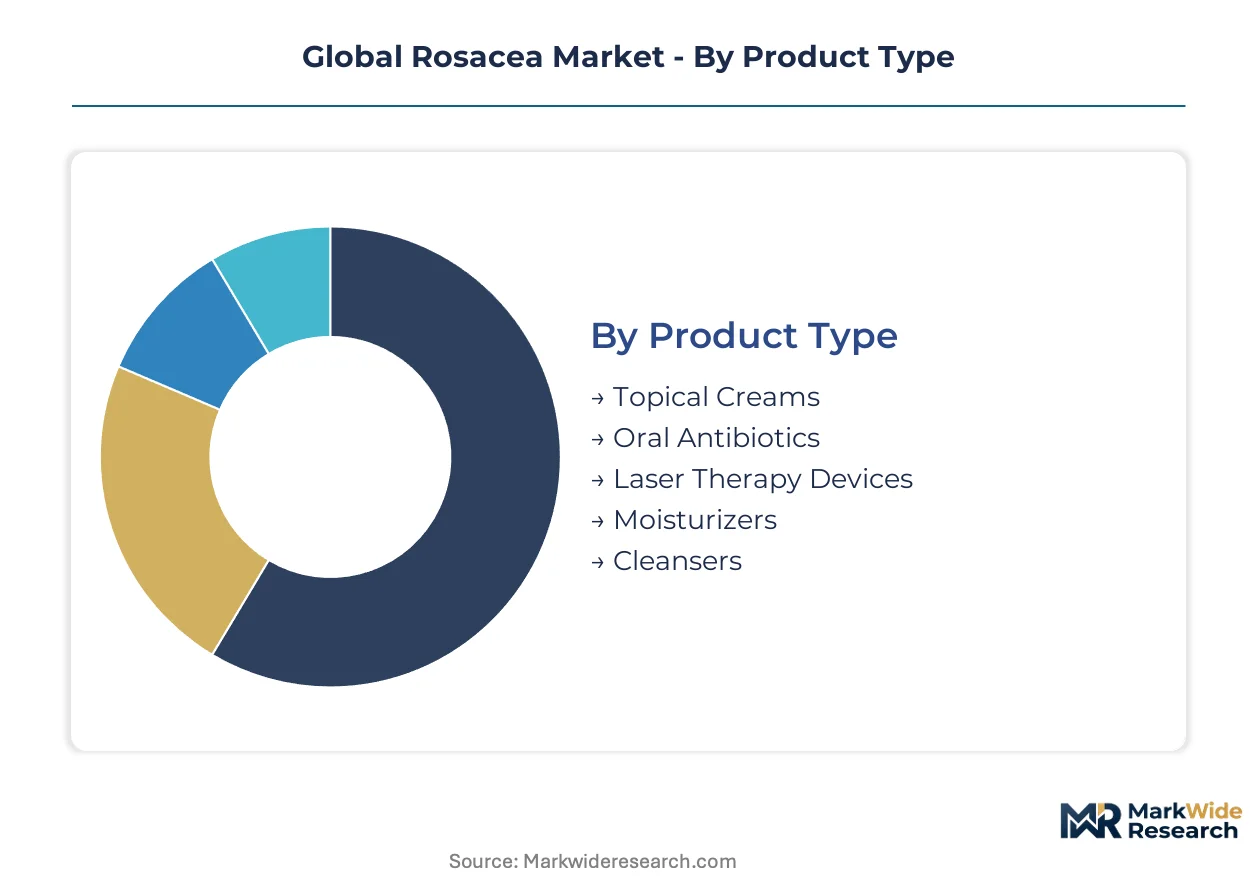
Rosacea treatment selection varies sharply by disease severity and patient access pathways. Segmentation reveals how topical formulations dominate primary care channels while device-based interventions concentrate in aesthetic dermatology settings.
Product Type:
Domestic manufacturing clusters in Germany and the United States supply topical creams to regional markets, whereas laser therapy devices flow through export-led supply chains centered on South Korean and Israeli production hubs.
- Topical Creams:Metronidazole, azelaic acid, and ivermectin formulations modulate cutaneous immune response and Demodex mite density. Demand concentrates in United States retail pharmacies where patient awareness campaigns and high dermatologist density drive first-line prescribing. The FDA's streamlined dermatological approval pathway accelerates generic substitution pressures.
- Laser Therapy Devices:Pulsed dye and Nd:YAG systems target vascular lesions through selective photothermolysis. Aesthetic dermatology chains in Germany, France, and South Korea are expanding service menus, creating pull-through demand for combination pharmaceutical-device protocols. EU MDR compliance requirements extend development cycles for new device entrants.
- Oral Antibiotics:Doxycycline and minocycline address moderate-to-severe inflammatory subtypes through anti-inflammatory mechanisms at sub-antimicrobial doses.
- Moisturizers:Barrier-repair formulations containing ceramides and niacinamide support adjunctive care in European pharmacy channels.
- Cleansers:pH-balanced, non-foaming preparations reduce irritation triggers for sensitive skin populations.
Topical creams command the established base. The steepest expansion runs through laser therapy devices.
Therapy Area:
Cost-tier stratification separates premium device-treatable vascular presentations from commodity-managed inflammatory variants, with ocular and phymatous subtypes occupying niche reimbursement categories.
- Inflammatory Rosacea:Papulopustular lesions drive the largest patient pool due to symptomatic visibility and treatment-seeking behavior. United States dermatology clinics capture high volumes through established topical protocols, though generic erosion in oral antibiotics constrains systemic therapy revenue pools.
- Vascular Rosacea:Persistent erythema and telangiectasia respond to laser and light-based interventions. Aesthetic medicine infrastructure in Japan and South Korea supports premium device penetration, with METI-supported reimbursement frameworks enabling clinic investment.
- Rhinophyma:Sebaceous hyperplasia of the nose requires surgical or laser resurfacing intervention in tertiary referral centers.
- Ocular Rosacea:Blepharitis and meibomian gland dysfunction demand ophthalmology-dermatology co-management in specialty hospital settings.
Inflammatory presentations anchor prescription volume. Vascular subtypes are climbing the fastest through aesthetic channel expansion.
End User:
Customer-type fragmentation splits volume-driven pharmacy dispensing from high-margin clinic-administered procedures, with ambulatory surgical centers capturing device-based interventions.
- Dermatology Clinics:Private practice and aesthetic chains in the United States, Germany, and United Kingdom combine pharmaceutical prescribing with laser service delivery. Telemedicine platforms are compressing referral bottlenecks through direct-to-patient subscription models.
- Specialty Hospitals:Academic medical centers manage severe or refractory cases with biologics access and multidisciplinary ocular rosacea protocols.
- Ambulatory Surgical Centers:Outpatient facilities in France and South Korea perform laser resurfacing and rhinophyma correction under regional anesthesia.
- Pharmacies:Community and hospital pharmacies dispense first-line topicals and oral antibiotics across European reimbursement systems.
Dermatology clinics capture the margin concentration. Ambulatory surgical centers are expanding capacity fastest for device-based procedures.
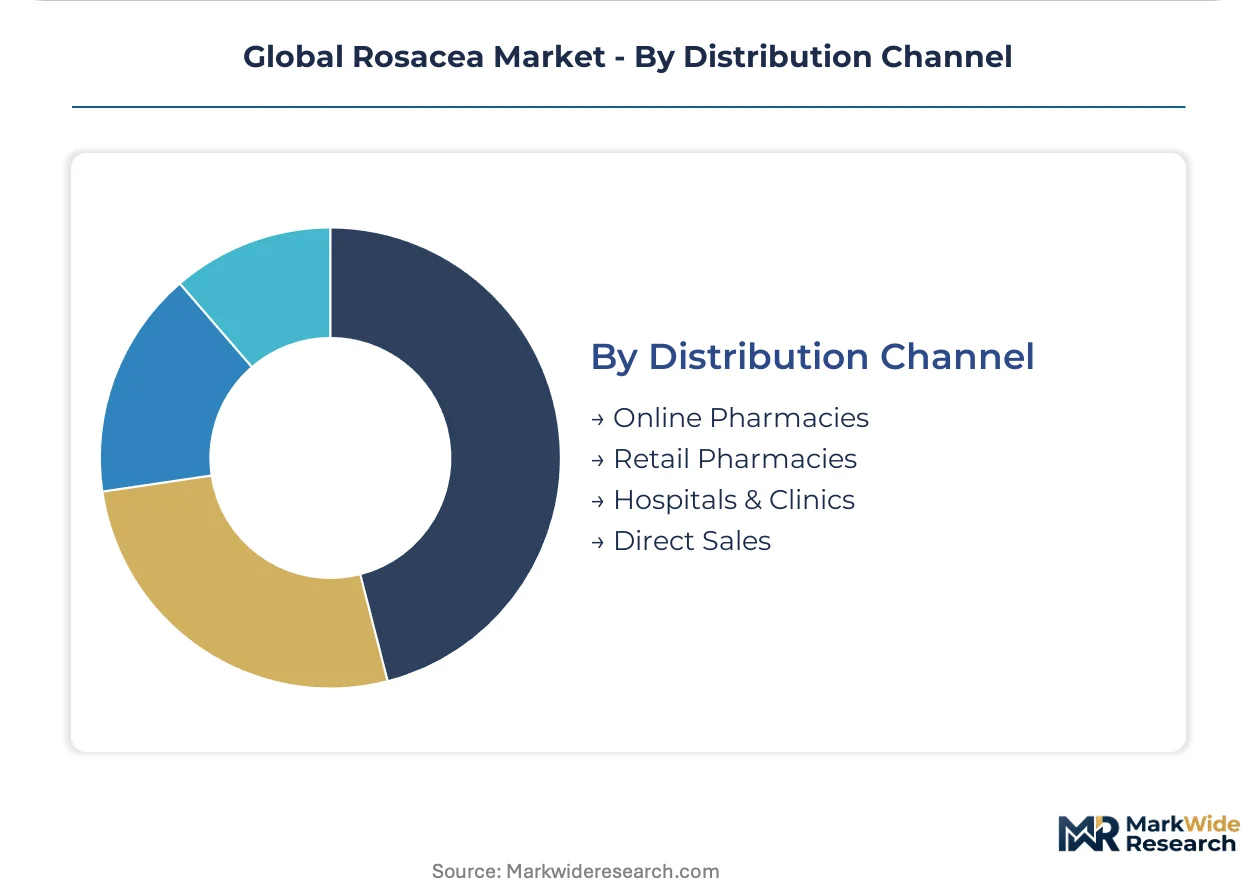
Distribution Channel:
Supply concentration in direct sales relationships for high-value laser equipment contrasts with fragmented online and retail pharmacy networks for recurring topical purchases.
- Online Pharmacies:Asynchronous dermatologist consultations and smartphone-based symptom assessment tools capture mild-to-moderate cases in United States and United Kingdom urban markets where specialist appointment availability is constrained.
- Retail Pharmacies:Brick-and-mortar chains in Germany and France maintain formulary control over established metronidazole and azelaic acid franchises.
- Hospitals & Clinics:Institutional procurement governs biologics access and device placement in academic medical centers.
- Direct Sales:Manufacturer field service organizations install and maintain laser systems in aesthetic dermatology chains.
Retail pharmacies hold the volume base. Online pharmacies are gaining share fastest through telemedicine integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. United States patients demonstrate low sensitivity to premium device-based interventions, while European pharmacy markets face intense generic substitution pressure. Japanese buyers occupy a middle tier, accepting premium positioning for technology-validated outcomes.
United States
Patient awareness campaigns and high dermatologist density drive first-line topical prescribing. FDA's streamlined dermatological approval pathway accelerates generic substitution pressures. Aesthetic dermatology chains in California and New York expand laser service menus, creating pull-through demand for combination protocols.
Germany
Retail pharmacy chains maintain formulary control over established metronidazole and azelaic acid franchises. REACH compliance mandates full chemical substance registration for formulation components, tightening supply chain requirements. Manufacturers in Bavaria and North Rhine-Westphalia consolidate supplier relationships and invest in in-house analytical capabilities.
Japan
METI-supported aesthetic medicine infrastructure enables premium device penetration for vascular rosacea subtypes. PMDA's dermatology review experience creates favorable conditions for laser therapy entry. Tokyo and Osaka-based clinics anchor demand for combination pharmaceutical-device protocols.
South Korea
Aesthetic dermatology chains pilot microbiome-targeted topical formulations for treatment-resistant patients. MFDS regulates device safety through post-market surveillance frameworks. Seoul Capital Area production hubs supply laser systems to export markets across Asia-Pacific.
United Kingdom
Telemedicine platforms bypass traditional dermatology referral bottlenecks through direct-to-patient subscription models. MHRA aligns with EMA centralized procedures for topical formulation approvals. London and Southeast England urban markets show fastest adoption of smartphone-based symptom assessment tools.
Global Rosacea Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the rosacea treatment spectrum. The market structure splits between biologics-focused immunology platforms and dermatology-specialist topical formulators. Three archetypes dominate: multinational pharmaceutical conglomerates with immunology infrastructure, pure-play dermatology companies with channel control, and generic manufacturers competing on oral antibiotic commoditization. Competitive moves concentrate on M&A for inflammatory skin disease platforms and strategic partnerships for device-therapy combination protocols.
Within the dermatology-specialist tier, Galderma and Almirall exemplify channel-centric positioning. AbbVie represents the immunology-platform archetype, leveraging infrastructure validated in adjacent inflammatory indications. Mayne Pharma Group Limited occupies a position among manufacturers addressing generic erosion dynamics in mature systemic therapies.
| Leading Market Players |
|---|
| AbbVie |
| Mayne Pharma Group Limited |
| Galderma |
| Sol-Gel Technologies Ltd. |
| Journey Medical Corporation |
| Bausch Health |
| Almirall |
| Teva Pharmaceutical Industries Ltd. |
| LEO Pharma |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts between German topical manufacturers and Bavarian excipient suppliers lock in both supply security and price visibility across the EU REACH compliance cycle. These arrangements insulate formulation producers from raw material volatility while constraining flexibility for spot-market purchasing.
Pricing Analysis
After-sales service contracts for laser therapy devices drive lifetime value through maintenance agreements and software upgrade subscriptions. Three-tier pricing structure across premium, standard, and economy levels separates academic medical centers from aesthetic chains and individual dermatology practices. Pricing pressure stems from generic erosion in oral antibiotics, with doxycycline commoditization eliminating brand premium capture. Retail pharmacy buyers in Germany demonstrate highest price sensitivity, while United States aesthetic clinics accept premium positioning for device-based outcomes.
Supply Chain Analysis
Inventory lead times for topical active pharmaceutical ingredients have extended following REACH-mandated excipient documentation requirements. Supply concentrates in Germany, the United States, and France for cream formulations, while South Korea and Israel anchor laser device production. Raw material dependencies center on azelaic acid precursors, metronidazole API, and Nd:YAG laser crystals. Single-source vulnerability for specialized optical components creates chokepoint exposure. Distribution runs through direct sales organizations for high-value equipment and wholesale pharmacy networks for recurring topical purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's streamlined dermatological approval pathway constitutes a regulatory inflection accelerating competitive entry and compressing commercialization timelines for inflammatory skin disease platforms.
For Market Incumbents: Fortify channel control through exclusive distribution agreements with expanding aesthetic dermatology chains in California and New York. Deepen backward integration into azelaic acid precursor manufacturing to offset REACH compliance cost inflation. Biologics-focused competitors threaten topical franchise erosion through IL-17 pathway repositioning. For New Entrants and Emerging Players: Anchor in telemedicine-integrated subscription models targeting United Kingdom and United States urban markets where specialist appointment scarcity drives patient self-diagnosis. The mild-to-moderate inflammatory segment offers lowest competitive density. Partner with smartphone-based symptom assessment platforms to bypass traditional referral bottlenecks. For Investors and Strategic Acquirers: Dermatology-specialist topical formulators with established EMA centralized procedure experience represent priority acquisition targets. Long-term viability hinges on device-therapy combination protocol leadership rather than monotherapy positioning. Watch for PMDA approval decisions on vascular rosacea laser indications as inflection signals for Asia-Pacific premium device adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA's streamlined dermatological framework accelerates topical commercialization timelines for inflammatory indications. |
| Manufacturing Scale-Up | REACH-compliant excipient sourcing investments secure European market access for German and French producers. |
| Strategic Partnership | Device-therapy combination protocols with aesthetic chains create pull-through demand for pharmaceutical-device bundles. |
| Pipeline Diversification | Microbiome-targeted topical formulations fragment prescriber loyalty toward established metronidazole franchises. |
| Geographic Expansion | METI-supported aesthetic infrastructure in Japan enables premium laser penetration for vascular rosacea subtypes. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with dermatology practice administrators, regulatory affairs specialists at topical manufacturers, hospital formulary directors, and aesthetic clinic procurement managers; and secondary validation through FDA 510(k) filings, EMA centralized procedure documentation, ClinicalTrials.gov rosacea intervention records, and EU MDR device registration databases. Bottom-up patient population estimates triangulated against top-down pharmaceutical sales audit data.
Across the analysis window, the forecasting framework modeled therapy area segmentation, product type differentiation, end-user channel dynamics, and regional regulatory cluster variations. CAGRs derived from growth driver quantification and constraint boundary analysis. Forecast inputs incorporated dermatologist density projections, telemedicine platform penetration curves, and aesthetic clinic capital expenditure patterns.
Material uncertainties — reimbursement negotiation outcomes for device-based procedures, EU MDR clinical evidence requirement evolution, and generic substitution rates in oral antibiotics — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory pathway stability and patient awareness campaign effectiveness. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Dermatology Drugs Market
Dermatology
Porokeratosis Treatment Market
Dermatology
Alopecia Treatment (Hair Loss) Market
Dermatology
Scleroderma Treatment Market
Dermatology
Dermabrasion Market
Dermatology
Global Online Dermatology Consultation Market
Dermatology
Global Dermatology Excimer Laser Market
Dermatology
Chronic Spontaneous Urticaria Market
Dermatology
UK Scar Treatment Market
Dermatology
Global Dermatology Cro Market
Dermatology
Australia Skin Treatment Market
Dermatology
Seborrheic Keratosis Treatment Market
Dermatology
Cutaneous Squamous Cell Carcinoma Market
Dermatology
Seborrheic Keratosis Market
Dermatology
Global Radiodermatitis Market
Dermatology
Skin Hyperpigmentation Treatment Market