
 Radiation Dermatitis Market | 2026-2036
Radiation Dermatitis Market Size, Share, and Industry Trends Forecast 2026-2036
Radiation Dermatitis Market Outlook
Clinical-grade prophylactic formulations is redrawing competitive boundaries in radiation dermatitis care. 3M leverages its adhesive and barrier film expertise to dominate hospital formulary access. Smith & Nephew plc anchors its position through advanced wound care portfolios that extend into oncology settings. Stratpharma AG specializes in silicone-based topical therapies that compete on scar prevention and skin barrier restoration metrics.
Radiation dermatitis encompasses the cutaneous inflammatory response triggered by ionizing radiation exposure, characterized by erythema, desquamation, and epidermal barrier disruption measured through RTOG toxicity grading scales. The condition demands interventions that modulate cytokine cascades while maintaining epidermal hydration integrity during fractionated radiotherapy regimens. Topical agents command the largest revenue pool among product types due to their direct application convenience and established reimbursement pathways. Home care settings represent the fastest-expanding end user segment as ambulatory oncology models shift post-radiation monitoring away from institutional facilities. Therapeutic devices remain a concentrated margin pocket where electromagnetic field and light-based modalities justify premium positioning through mechanistic differentiation.
The FDA oversees radiation dermatitis product approvals through its dermatologic and radiological health division, while the EPA regulates any antimicrobial claims embedded in skin care formulations. ISO 13485 quality management standards govern device manufacturers seeking entry into regulated markets, creating compliance moats that favor established operators. Stakeholders must monitor how CMS reimbursement policy evolution for prophylactic versus reactive dermatitis interventions reshapes prescribing economics across care settings.
Market Dynamics
The radiation dermatitis market is experiencing structural compression as prophylactic skin care protocols displace reactive treatment models across oncology care settings. This shift from episodic intervention to integrated prevention is reshaping product development priorities and reimbursement negotiations simultaneously.
Growth Catalysts
- CMS reimbursement expansion:The Centers for Medicare & Medicaid Services is broadening coverage for prophylactic dermatitis interventions, incentivizing integrated cancer centers to adopt standardized prevention protocols ahead of radiotherapy initiation.
- Fractionated radiotherapy protocols:Extended treatment courses for head, neck, and breast malignancies generate sustained demand for barrier-preserving topical agents throughout multi-week regimens.
- Silicone-based barrier films:Advanced polymer formulations demonstrate superior moisture retention and cytokine modulation compared to traditional petrolatum-based emollients, driving formulary upgrades.
Market Restraints
- Medical-grade silicone supply concentration:Specialty silicone feedstock production clusters in Germany and Japan, exposing formulation manufacturers to geopolitical logistics disruptions and input cost volatility.
- Clinical evidence thresholds:FDA's elevating requirements for randomized controlled trial data in radiation-induced skin injury indications extends development timelines and capital requirements for novel entrants.
- Petrolatum commodity substitution:Low-cost mineral oil-based emollients retain preference in cost-constrained ambulatory settings, limiting premium formulation penetration in price-sensitive segments.
Strategic Opportunities
- Home care channel expansion:Direct-to-patient distribution models bypass institutional procurement bottlenecks, capturing margin from ambulatory oncology's decentralization.
- Light-based therapeutic devices:Photobiomodulation and low-level laser technologies converge with topical delivery systems, creating combination therapy protocols for grade 2-3 dermatitis management.
- India's oncology infrastructure buildout:Tata Memorial Centre and regional cancer networks are establishing radiotherapy capacity in tier-2 cities, opening underpenetrated demand for prophylactic skin care protocols.
Industry Challenges
- ISO 13485 certification complexity:Device manufacturers face extended quality management system audits and documentation requirements, compressing time-to-market for electromagnetic field and light-based modalities.
- Interoperability with electronic health records:RTOG toxicity grading data capture requires customized integration with oncology information systems, fragmenting implementation across health system IT environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiation Dermatitis Market |
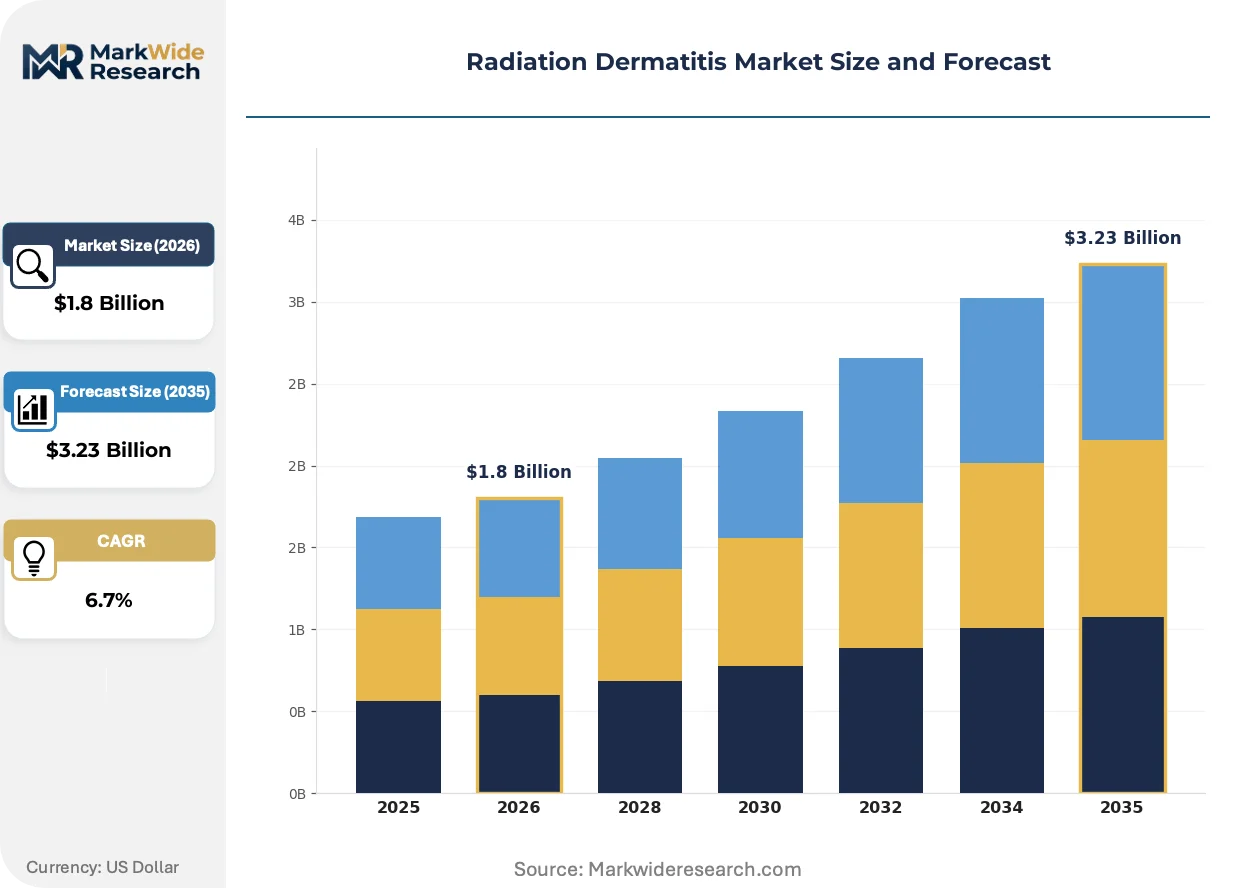
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Agents, Oral Medications, Skin Care Products, Therapeutic Devices Delivery Mode: Intravenous, Oral, Topical, Injectable End User: Hospitals, Home Care Settings, Oncology Clinics, Rehabilitation Centers Treatment Stage: Acute Phase, Chronic Phase, Prophylactic Care, Palliative Care |
| Companies Covered | Stratpharma AG, Smith & Nephew plc, 3M, Mölnlycke Health Care, ConvaTec Group Plc, Lutris Pharma, Integra LifeSciences, Bausch Health Companies, KeraNetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiation Dermatitis Market Strategic Shifts
Active pharmaceutical ingredient delivery mechanisms are undergoing functional transformation as nanostructured lipid carriers enable targeted cytokine modulation at irradiated tissue sites. This technological pivot is compressing the efficacy gap between prescription and over-the-counter categories.
Hyaluronic acid microsphere formulations is supplanting conventional hydrogel matrices in premium prophylactic segments. Major academic medical centers in the United States are adopting these carriers for breast and head-and-neck radiotherapy protocols. The technology is compressing reimbursement negotiations by demonstrating measurable reductions in grade 2+ dermatitis incidence against standard-of-care comparators.
REACH regulation amendments in the European Union are tightening disclosure requirements for silicone-based medical device constituents, compelling manufacturers to requalify supply chains and reformulate legacy products. Industrial consequence includes accelerated migration toward pharmaceutical-grade silicone certifications and third-party toxicological assessments. The medical device segment bears disproportionate compliance burden, with mid-tier manufacturers pursuing CE marking extensions under MDR transitional provisions.
Ambulatory oncology centers are unbundling skin care protocols from bundled radiotherapy payments, creating standalone reimbursement codes for prophylactic interventions. This purchasing pattern shift displaces traditional hospital pharmacy procurement with direct manufacturer contracting. The United States exhibits the most pronounced channel transformation, where integrated cancer networks negotiate multi-year supply agreements bypassing group purchasing organizations.
Radiation Dermatitis Market Segmentation
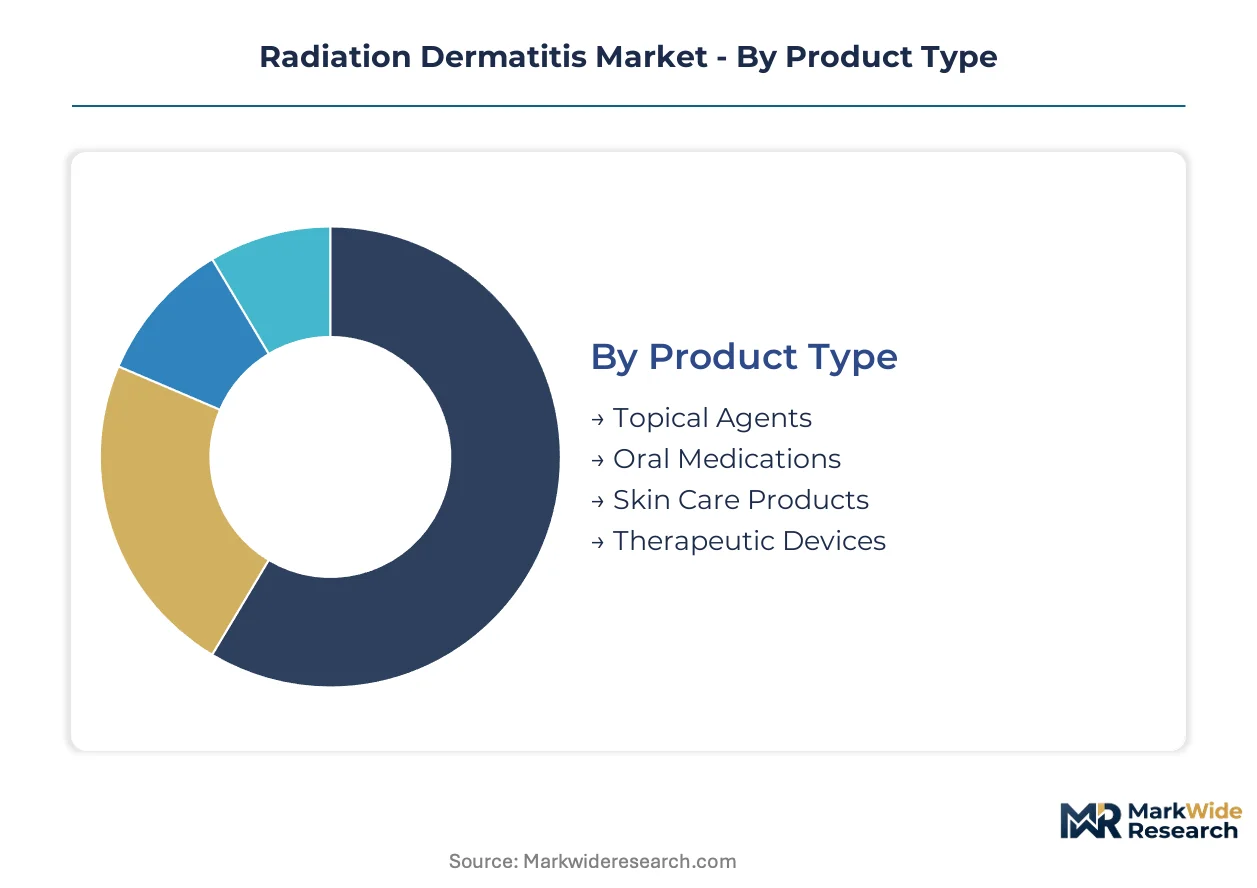
Radiation dermatitis interventions fragment across four distinct taxonomies. Product type determines reimbursement pathways and clinical evidence requirements. Delivery mode shapes patient compliance profiles. End user concentration dictates channel strategy. Treatment stage governs whether prophylactic or reactive protocols dominate purchasing decisions.
Product Type:
FDA's Center for Drug Evaluation and Research applies distinct approval standards to each category, creating divergent competitive moats.
- Topical Agents:Barrier films, hydrogels, and silicone-based emollients form the revenue core. Academic medical centers in the United States prioritize formulations demonstrating RTOG grade reduction in head-and-neck protocols. Petrolatum commodity substitution limits premium penetration in cost-constrained settings.
- Therapeutic Devices:Photobiomodulation and electromagnetic field modalities command concentrated margins through mechanistic differentiation. ISO 13485 certification requirements compress time-to-market for novel entrants.
- Oral Medications:Systemic cytokine modulators and antioxidant compounds address refractory cases.
- Skin Care Products:Moisturizers and cleansers support daily protocol adherence.
Established volume favors Topical Agents; emerging adoption favors Therapeutic Devices.
Delivery Mode:
Patient self-administration capacity drives cost tier stratification across acute versus extended care settings.
- Topical:Direct application convenience anchors formulary placement in ambulatory oncology. Home care distribution models capture margin from decentralization of post-radiation monitoring.
- Oral:Capsule and tablet formulations enable patient-managed prophylaxis throughout fractionated regimens. Compliance tracking integrates with oncology information systems.
- Intravenous:Hospital-administered antioxidant protocols serve grade 3-4 dermatitis cases.
- Injectable:Cytokine modulators delivered via subcutaneous routes address systemic inflammation.
Institutional procurement concentrates on Intravenous; patient-directed models favor Oral.
End User:
Channel configuration determines whether group purchasing organization contracts or direct manufacturer agreements govern supply relationships.
- Home Care Settings:Ambulatory oncology's shift away from institutional monitoring creates standalone reimbursement codes. Direct-to-patient distribution bypasses pharmacy procurement bottlenecks entirely.
- Oncology Clinics:Integrated cancer centers negotiate multi-year supply agreements for standardized prevention protocols. Unbundling of skin care from radiotherapy bundles enables discrete contracting.
- Hospitals:Inpatient grade 3-4 management requires acute intervention capabilities.
- Rehabilitation Centers:Post-tissue recovery protocols address fibrosis and scar management.
Margin concentration sits with Home Care Settings; volume concentration remains with Oncology Clinics.
Treatment Stage:
Clinical evidence requirements escalate from prophylactic prevention through palliative intervention, reshaping development economics.
- Prophylactic Care:Pre-radiation barrier application demonstrates superior cost-effectiveness in CMS reimbursement analyses. Hyaluronic acid microsphere formulations compress negotiations through measurable grade 2+ reduction.
- Acute Phase:Erythema and desquamation management demands cytokine-modulating interventions during active fractionated courses. RTOG toxicity grading data capture requires EHR integration.
- Chronic Phase:Persistent fibrosis and atrophy protocols extend months beyond radiotherapy completion.
- Palliative Care:Comfort-focused interventions address end-stage symptom burden.
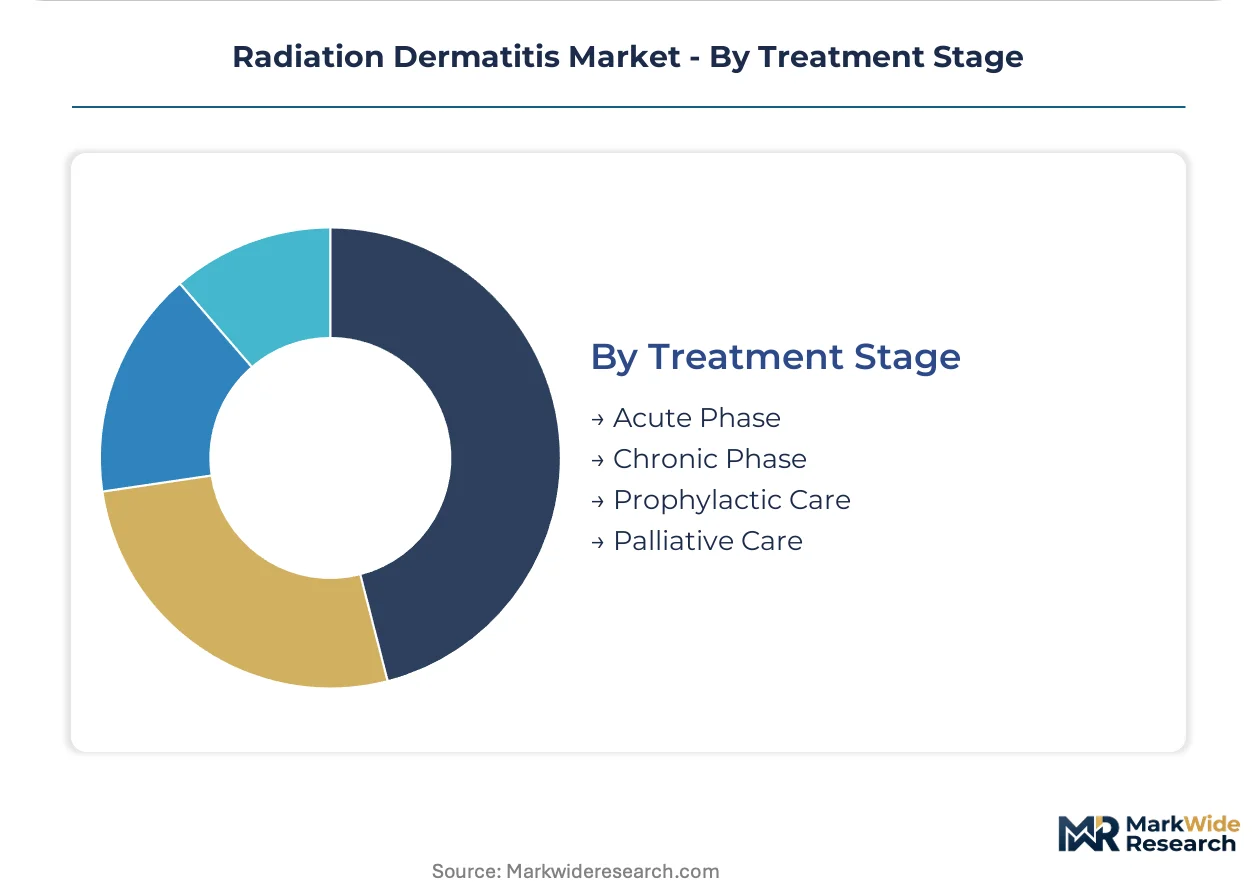
Reimbursement expansion favors Prophylactic Care; evidence intensity peaks in Acute Phase.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in radiation dermatitis products skew toward developed oncology infrastructure, with the United States importing advanced silicone formulations from European specialty chemical producers while exporting photobiomodulation devices to Asian markets.
United States
Integrated cancer centers in Houston and Boston drive prophylactic protocol adoption ahead of radiotherapy initiation. FDA's Center for Drug Evaluation and Research elevates clinical evidence requirements for barrier film approvals. The Mayo Clinic network in Rochester, Minnesota, pilots hyaluronic acid microsphere regimens for head-and-neck protocols.
Germany
Specialty silicone feedstock production clusters in Leverkusen and Wesseling supply formulation manufacturers globally. ECHA's REACH amendments tighten disclosure requirements for medical device constituents, compelling supply chain requalification. Heidelberg's National Center for Tumor Diseases establishes standardized prevention protocols for fractionated breast radiotherapy.
Japan
PMDA's evolving guidance on radiation-induced skin injury prompts manufacturers to elevate randomized controlled trial data packages. METI subsidizes domestic production of pharmaceutical-grade silicone to reduce import dependency. Osaka's cancer centers adopt light-based therapeutic devices for grade 2-3 dermatitis management.
India
Tata Memorial Centre in Mumbai and regional cancer networks build radiotherapy capacity in tier-2 cities, opening underpenetrated demand. CDSCO streamlines approval pathways for topical agents with established US or EU registrations. Hyderabad's pharmaceutical formulation cluster attracts contract manufacturing for silicone-based barrier films.
Australia
TGA's alignment with FDA evidence standards accelerates market entry for devices with prior US approval. Public hospital procurement concentrates volume in Sydney and Melbourne oncology units. The Peter MacCallum Cancer Centre in Melbourne leads protocol development for ambulatory skin care regimens.
Radiation Dermatitis Market Competitive Environment
Listed leaders compete with private specialists across formulation and device segments, creating a tiered structure where scale advantages in hospital formulary access coexist with niche positioning in silicone chemistry. The vendor base separates into three strategic archetypes: diversified healthcare conglomerates leveraging cross-category procurement relationships, wound care specialists extending oncology adjacencies, and polymer technology pure-plays competing on barrier performance metrics. Dominant competitive moves include multi-year supply agreements with integrated cancer networks and backward integration into pharmaceutical-grade silicone feedstock.
Within the diversified healthcare tier, 3M and Smith & Nephew plc exemplify scale-driven formulary penetration, with the former representing adhesive and barrier film expertise and the latter anchoring advanced wound care portfolios that extend into institutional oncology settings. Stratpharma AG occupies a position among silicone-based topical specialists, competing on scar prevention and skin barrier restoration metrics in premium prophylactic segments.
| Leading Market Players |
|---|
| Stratpharma AG |
| Smith & Nephew plc |
| 3M |
| Mölnlycke Health Care |
| ConvaTec Group Plc |
| Lutris Pharma |
| Integra LifeSciences |
| Bausch Health Companies |
| KeraNetics |
| Others |
Value Chain & Pricing Dynamics
Multi-year supply agreements with integrated cancer networks lock in both pharmaceutical-grade silicone feedstock access and predictable unit economics for barrier film manufacturers. These contracts insulate formulation specialists from spot market volatility in Germany and Japan while committing oncology clinics to standardized prophylactic protocols.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in radiation dermatitis care. Premium hyaluronic acid microsphere formulations command formulary placement through FDA-tier clinical evidence and measurable RTOG grade reduction, while petrolatum-based commodities compete on procurement cost in ambulatory settings. Cost compression in standard-tier silicone emollients is intensifying because CDSCO fast-track approvals for Indian contract manufacturers expand supply alternatives. Price-sensitive buyers concentrate in tier-2 oncology centers across India and Southeast Asia, whereas academic medical centers in the United States exhibit lowest sensitivity due to bundled reimbursement codes.
Supply Chain Analysis
Germany and Japan anchor pharmaceutical-grade silicone production for barrier film formulations, with Leverkusen and Wesseling clusters supplying specialty polymer feedstock globally. Formulation manufacturing draws from medical-grade silicone, hyaluronic acid raw material, and nanostructured lipid carrier inputs. Single-source vulnerability concentrates in German specialty chemical producers exposed to ECHA REACH amendment compliance costs. Distribution runs through direct manufacturer contracting with integrated cancer networks, displacing traditional group purchasing organization channels in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CMS reimbursement expansion for prophylactic interventions creates a high-growth disruption window as integrated cancer centers unbundle skin care from radiotherapy bundles ahead of institutional protocol standardization.
For Market Incumbents: Secure captive supply of pharmaceutical-grade silicone through backward integration into German or Japanese feedstock producers to defend against emerging polymer technology pure-plays. Lock in multi-year formulary access at academic medical centers piloting hyaluronic acid microsphere protocols before competitive entrants achieve comparable clinical evidence packages. For New Entrants and Emerging Players: FDA 510(k) fast-track for topical agents with established EU MDR documentation creates entry pathway into United States ambulatory oncology. Target India's tier-2 city cancer networks building first-time radiotherapy capacity, where CDSCO streamlined approvals and unmet prophylactic protocol demand coexist. Lead with direct-to-patient distribution models that bypass entrenched hospital pharmacy procurement at Tata Memorial Centre regional affiliates. For Investors and Strategic Acquirers: Capital is best deployed toward silicone chemistry specialists with ISO 13485 certification and existing CE marking under MDR transitional provisions, positioned for FDA submission leverage. Long-term viability hinges on consolidation of formulation capabilities as REACH compliance costs force mid-tier manufacturer exit. Watch for CMS reimbursement code expansion for combination therapy protocols pairing topical agents with photobiomodulation devices as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Feedstock | Captive supply from German producers insulates margin from ECHA REACH compliance cost pass-through. |
| CE Marking Pathway under MDR Transitional Provisions | Accelerated EU market entry enables FDA 510(k) predicate device claims for topical barrier films. |
| Hospital System Partnership | Direct contracting with Mayo Clinic network pilots bypasses group purchasing organization intermediaries. |
| Reimbursement Strategy | Unbundled CMS codes for prophylactic care shift procurement economics toward standalone skin care protocols. |
| Software Companion Development | RTOG toxicity grading data capture integration with oncology information systems differentiates device offerings. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across the radiation dermatitis value chain, including oncology clinic procurement directors, formulary pharmacists at integrated cancer networks, biomedical engineers specifying therapeutic devices, and regulatory affairs leads navigating FDA Center for Drug Evaluation and Research pathways. Secondary validation drew from FDA 510(k) filings, EMA MDR submission databases, CMS Medicare reimbursement code updates, and hospital procurement contract disclosures. Bottom-up patient volume modeling and top-down pharmaceutical spending allocation were triangulated to cross-verify segment sizing.
Across the analysis window, forecasts applied treatment stage progression modeling linking prophylactic adoption rates to fractionated radiotherapy protocol expansion in head-and-neck and breast malignancies. Segmentation dimensions included product type, delivery mode, end user channel configuration, and geographic regulatory cluster. CAGRs were derived from elasticity-adjusted volume projections and pricing tier migration assumptions. Forecast inputs incorporated silicone feedstock cost trajectories and CMS reimbursement policy evolution scenarios.
Underlying assumptions cover stable REACH regulatory implementation timelines and continued CMS prophylactic coverage expansion, with deviation risk concentrated in FDA evidence requirement elevation for radiation-induced skin injury indications. Recalibration cycles align with material shifts in reimbursement coding decisions and specialty silicone supply disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Homecare Dermatology Energy-Based Devices Market
Dermatology
Seborrheic Keratosis Market
Dermatology
Japan Scar Treatment Market
Dermatology
Hyperpigmentation Disorder Treatment Market
Dermatology
Dermatology Devices Market
Dermatology
Dermabrasion Market
Dermatology
Global Veterinary Dermatology Drugs Market
Dermatology
China Scar Treatment Market
Dermatology
Telogen Effluvium Treatment Market
Dermatology
Acne Vulgaris Treatment Market
Dermatology
Scleroderma Treatment Market
Dermatology
Athletes Foot (Tinea Pedis) Treatment Market
Dermatology
Porokeratosis Treatment Market
Dermatology
Folliculitis Market
Dermatology
Skin Excision Market
Dermatology
Scar Treatment Market