
 Global Lightweight Aggregate Concrete Market | 2026-2036
Global Lightweight Aggregate Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lightweight Aggregate Concrete Market Foresight
Aftermarket technical consulting and mix-design optimization services is reshaping margin distribution across the value chain. Heidelberg Materials leverages its vertically integrated expanded clay production network to control raw material quality from quarry to batch plant. Arcosa Lightweight anchors its competitive position through specialized shale aggregate operations concentrated in the southeastern United States. Cemex differentiates by operating ready-mix concrete plants with dedicated lightweight aggregate silo infrastructure across multiple metropolitan markets.
Lightweight aggregate concrete incorporates porous mineral aggregates such as expanded clay, shale, or pumice to achieve dry densities between 300 and 1,840 kg per cubic meter while maintaining structural compressive strength above 17 MPa. This engineered material reduces dead loads in structural elements, enabling longer spans and smaller foundation footprints in commercial and infrastructure applications. Expanded clay products command the dominant share of product-type revenue due to proven performance in freeze-thaw environments and established supply chains across Europe and North America. Precast elements represent the fastest-expanding application segment as offsite manufacturing gains traction among contractors seeking schedule compression and quality control. Marine structures applications sustain premium pricing power where corrosion-resistant, low-permeability concrete specifications dominate port and coastal infrastructure tenders.
The European Commission's Construction Products Regulation and REACH chemical compliance protocols govern aggregate sourcing and admixture disclosure across member states, while the EPA's National Emission Standards for Hazardous Air Pollutants shape kiln operations for expanded shale and clay manufacturers in the United States. China's GB standards for structural lightweight concrete establish minimum performance benchmarks that influence export-oriented production from Asian suppliers. Stakeholders must monitor evolving embodied carbon accounting methodologies and building code amendments that will determine specification eligibility for lightweight alternatives in public infrastructure procurement.
Market Dynamics
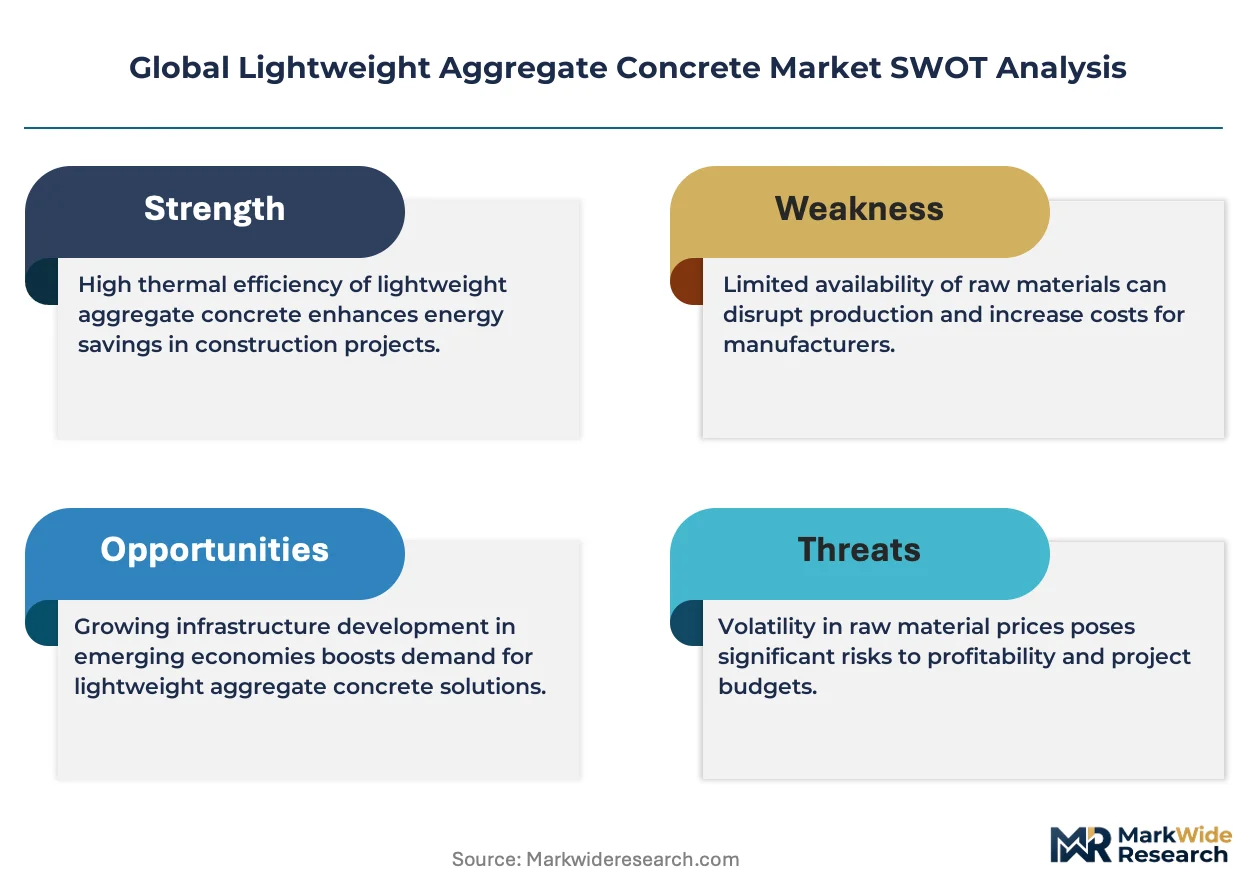
EU Green Deal embodied carbon thresholds are redirecting specification decisions toward lower-density structural materials, compressing traditional concrete's share in public infrastructure tenders across seismic zones and high-rise corridors.
Growth Catalysts
- Seismic Resilience Mandates:Japan's Building Standards Act revisions and California's seismic retrofit programs are expanding procurement of lightweight aggregate concrete for high-rise construction in fault-line corridors.
- REACH Chemical Compliance:ECHA disclosure protocols for admixture composition are accelerating substitution toward mineral-based lightweight aggregates with transparent supply chains.
- Offsite Manufacturing:Precast concrete producers in Germany and the Netherlands are capturing schedule compression premiums through standardized lightweight element fabrication.
Market Restraints
- Natural Gas Price Volatility:Expanded clay and shale kiln operations in Germany and the US Gulf Coast face margin compression from feedstock cost swings.
- Quarry Concentration Risk:Pumice aggregate supply clusters around volcanic deposits in Italy and Iceland, creating single-source vulnerability for Mediterranean marine structure projects.
- Compressive Strength Ceiling:Structural lightweight concrete formulations above 40 MPa require proprietary binder systems that lock buyers into sole-source admixture dependencies.
Strategic Opportunities
- India Urban Corridor Buildout:Smart Cities Mission infrastructure tenders in Mumbai and Bangalore corridors specify thermally efficient envelope systems where expanded clay block systems remain underpenetrated.
- GB Standard Harmonization:China's structural lightweight concrete performance benchmarks are creating export certification pathways for Asian precast producers serving Belt and Road port projects.
- Carbon Accounting Integration:ISO 14067-compliant Environmental Product Declarations are opening specification eligibility in French and Dutch public procurement where embodied carbon scoring determines bid rankings.
Industry Challenges
- Mix Design Specialization Gap:Qualified lightweight aggregate concrete technicians are concentrated in Western European and Japanese technical institutes, constraining project execution capacity in emerging markets.
- Kiln Emissions Compliance:EPA National Emission Standards for Hazardous Air Pollutants and EU Industrial Emissions Directive monitoring requirements are extending commissioning timelines for expanded aggregate production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lightweight Aggregate Concrete Market |
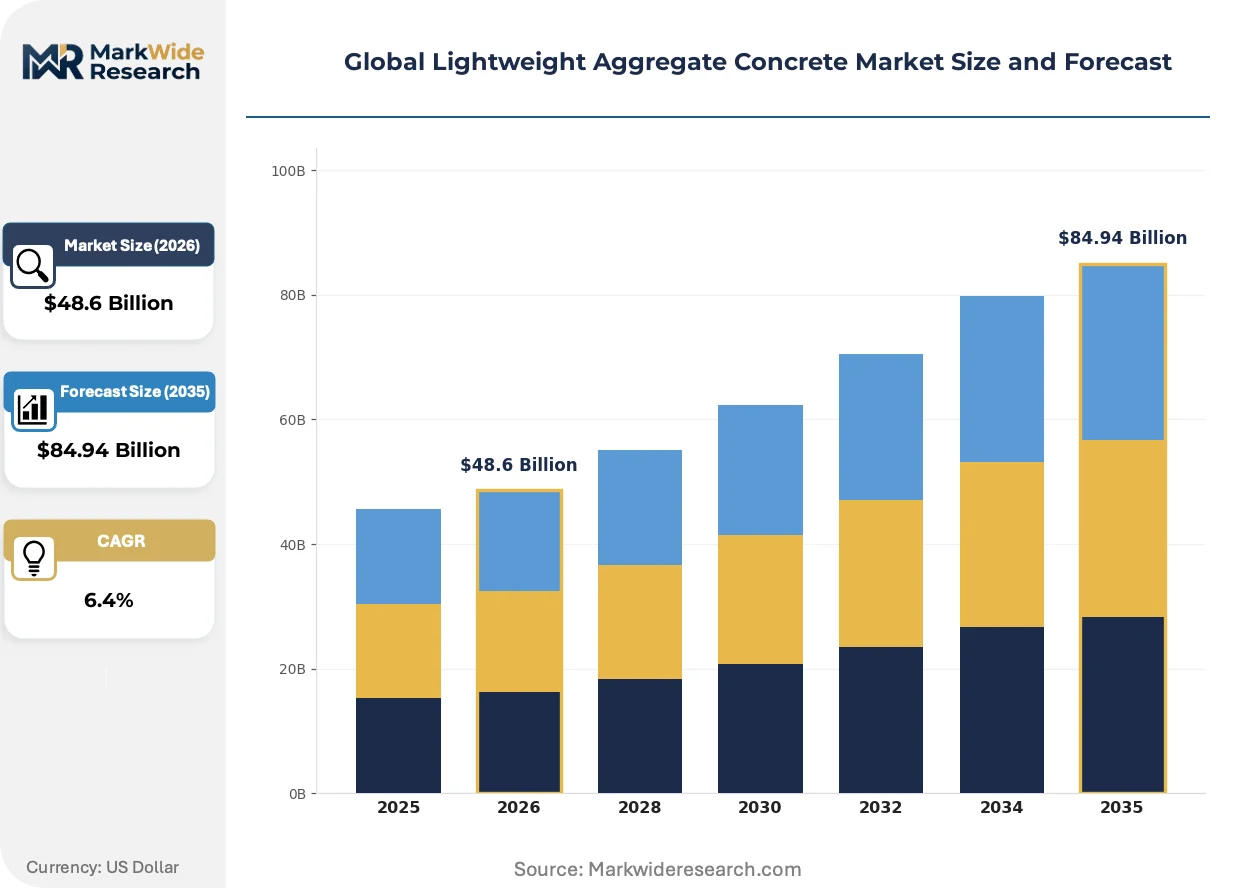
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $84.94 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Expanded Clay, Shale Aggregate, Pumice, Slag Aggregate, Perlite, Vermiculite Application: Bridges, High-Rise Buildings, Pavements, Marine Structures, Precast Elements, Sound Barriers End User: Construction Contractors, Infrastructure Developers, Civil Engineers, Real Estate Firms, Public Works Departments Deployment: Ready-Mix Concrete Plants, On-Site Mix, Precast Concrete Plants, Batch Mix Plants |
| Companies Covered | Heidelberg Materials, Lafarge, Arcosa Lightweight, Votorantim Cimentos, Buzzi Unicem, Cemex, Holcim, SCG, CRH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lightweight Aggregate Concrete Market Shifts & Advancements
Active R&D pipelines are compressing the performance gap between lightweight and conventional concrete while digital fabrication methods are rewriting precast production economics across three distinct vectors.
Geopolymer binder systems incorporating fly ash and slag are collapsing the embodied carbon differential between structural lightweight concrete and Portland cement-based alternatives. Scandinavian bridge contractors are specifying these formulations for coastal exposure zones where chloride resistance determines service life. The technology is collapsing traditional material selection hierarchies in marine infrastructure procurement.
EU Construction Products Regulation harmonized testing protocols are mandating third-party certification for freeze-thaw performance claims across expanded clay and shale aggregate categories. Italian and Spanish producers are consolidating testing laboratory partnerships to secure CE marking validity. Precast facade element manufacturers face the steepest compliance cost escalation as facade thermal performance declarations tighten.
Contractor procurement teams are unbundling mix-design optimization from material supply contracts, creating standalone technical consulting revenue streams. German and Austrian infrastructure developers now retain independent concrete technologists for batch-plant audit protocols. This pattern is most visible in federal highway tenders where performance-based specifications override prescriptive recipes.
Global Lightweight Aggregate Concrete Market Segmentation
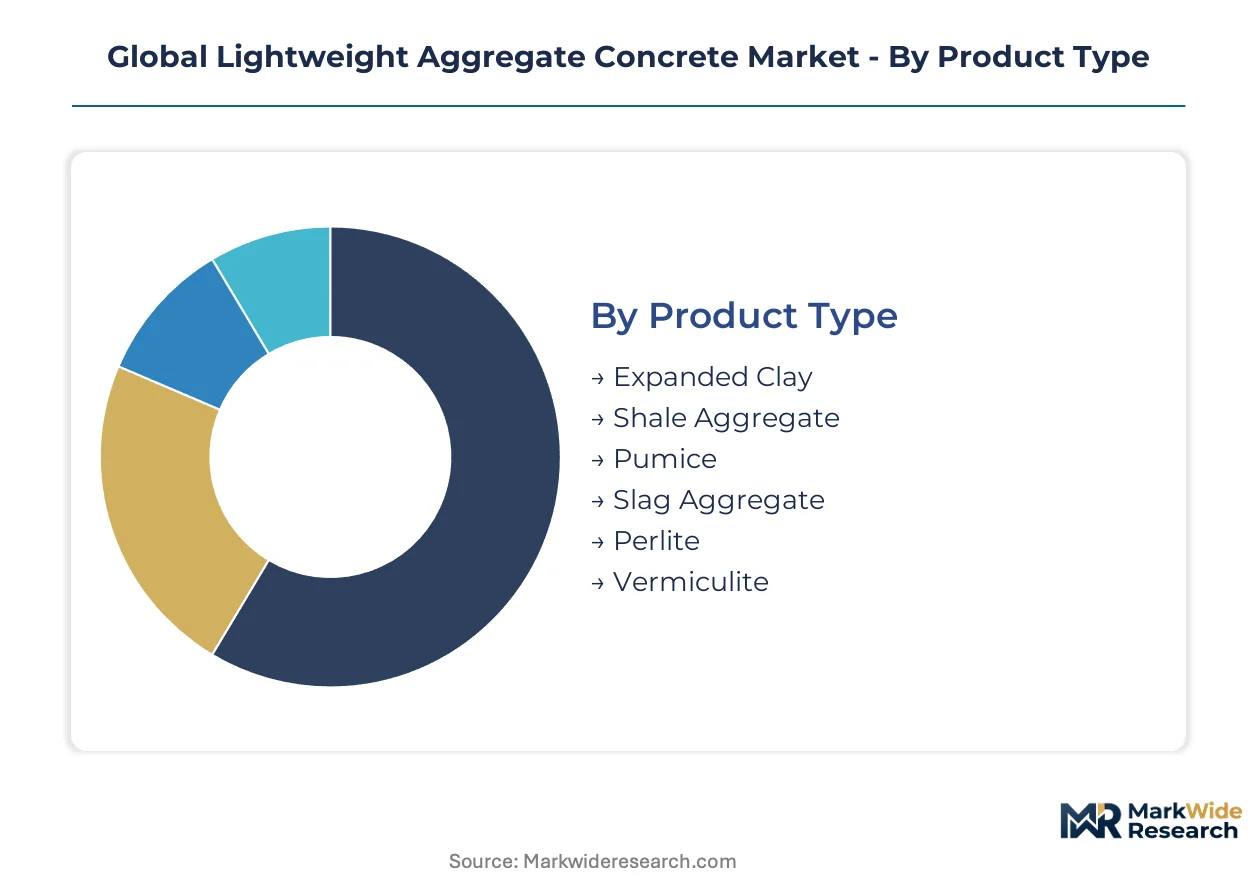
Segmentation in lightweight aggregate concrete tracks how material density, supply chain configuration, and project delivery methods reshape procurement economics. Product type selection determines thermal performance and seismic resilience specifications. Application and deployment choices reflect contractor preferences for offsite manufacturing versus traditional pour-in-place construction.
Product Type:
Expanded clay products turn inventory fastest due to standardized kiln production and established European supply chains, while pumice and vermiculite move slowest owing to quarry concentration and specialty handling requirements.
- Expanded Clay:Manufactured from rotary kiln-fired clay pellets achieving 300-600 kg per cubic meter dry density with proven freeze-thaw resistance. German federal building codes and Dutch public procurement tenders concentrate demand for thermally efficient envelope systems where expanded clay block systems dominate specification shortlists.
- Shale Aggregate:Produced from expanded sedimentary rock with higher crushing strength than clay alternatives, suited for structural elements exceeding 25 MPa design requirements. Arcosa Lightweight's southeastern US operations and similar regional producers anchor supply for California seismic retrofit programs and Gulf Coast infrastructure corridors.
- Pumice:Volcanic-origin porous stone with natural low density, sourced primarily from Italian and Icelandic deposits for Mediterranean marine applications.
- Slag Aggregate:Industrial byproduct from metallurgical processes offering embodied carbon advantages under EU Green Deal accounting protocols.
- Perlite:Expanded volcanic glass used primarily for insulating concrete overlays and roof deck applications requiring extreme lightness.
- Vermiculite:Hydrated laminar mineral providing fire-resistant properties for specialty commercial building specifications.
Expanded clay anchors the volume base while precast element applications of shale aggregate gain share at the steepest rate.
Application:
Cost tier stratification separates premium marine specifications from standardized pavement and sound barrier deployments where material substitution pressures intensify.
- Precast Elements:Offsite-manufactured wall panels, beams, and facade systems fabricated under controlled conditions enabling schedule compression and quality standardization. German and Dutch producers capture premium pricing through ISO 14067-compliant Environmental Product Declarations that satisfy French and Dutch public procurement embodied carbon scoring requirements.
- Marine Structures:Port infrastructure, coastal defense, and submerged elements demanding chloride resistance and low permeability specifications. Scandinavian bridge contractors specify geopolymer-bound lightweight formulations for coastal exposure zones where service life determines total cost of ownership calculations.
- High-Rise Buildings:Structural frames and floor systems in seismic zones where dead load reduction enables smaller foundation footprints and longer span capabilities.
- Bridges:Deck replacements and new span construction prioritizing weight reduction for substructure economy.
- Pavements:Road surfaces and airport runways where thermal insulation properties reduce frost heave damage.
- Sound Barriers:Highway noise walls leveraging porous aggregate acoustic absorption characteristics.
Marine structures command the steepest price premiums while precast elements expand most quickly through offsite manufacturing adoption.
End User:
Customer type determines specification authority and technical consulting engagement depth, with infrastructure developers and public works departments driving standardization versus contractor-driven project-level optimization.
- Infrastructure Developers:Long-horizon project sponsors integrating embodied carbon accounting into material selection criteria for federal highway and port authority tenders.
- Construction Contractors:Volume purchasers balancing material cost against placement productivity and schedule risk.
- Civil Engineers:Design-phase specification holders retaining independent concrete technologists for batch-plant audit protocols on performance-based federal highway projects.
- Real Estate Firms:Commercial building owners prioritizing thermal envelope efficiency for operational energy cost reduction.
- Public Works Departments:Municipal procurement authorities subject to EU Green Deal and domestic green public procurement mandates.
Infrastructure developers anchor the volume base while civil engineering consultancies gain procurement influence at the steepest rate through performance-based specification adoption.
Deployment:
Supply concentration varies dramatically by deployment mode, with ready-mix networks requiring metropolitan silo infrastructure versus precast plant captive integration.
- Ready-Mix Concrete Plants:Metropolitan batch facilities with dedicated lightweight aggregate silo infrastructure enabling just-in-time delivery to construction sites.
- Precast Concrete Plants:Captive manufacturing facilities controlling mix design, curing, and quality certification for standardized element production.
- On-Site Mix:Project-specific batching for remote or large-scale infrastructure where transportation economies favor field production.
- Batch Mix Plants:Regional centralized facilities serving dispersed construction corridors with bulk delivery logistics.
Ready-mix plants anchor the volume base while precast concrete plants gain share at the steepest rate through manufacturing consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes lightweight aggregate concrete primarily for thermally efficient envelope systems, while Japan deploys it for seismic resilience in high-rise cores—a consumption-mix differential that shapes specification priorities across major markets.
United States
California seismic retrofit programs and Gulf Coast infrastructure corridors drive shale aggregate procurement. EPA National Emission Standards for Hazardous Air Pollutants govern expanded aggregate kiln operations nationwide. Arcosa Lightweight anchors southeastern US supply for structural elements exceeding 25 MPa design requirements.
Germany
Federal building codes incentivize thermally efficient envelope systems in federal highway and port authority tenders. EU Green Deal embodied carbon thresholds redirect specification decisions toward lower-density structural materials. Heidelberg Materials leverages vertically integrated expanded clay production from quarry to batch plant across its domestic network.
China
GB standards for structural lightweight concrete establish minimum performance benchmarks influencing export-oriented production. Belt and Road port projects in coastal provinces specify precast elements with standardized lightweight fabrication. Asian suppliers concentrate production in eastern manufacturing corridors serving international certification pathways.
Japan
Building Standards Act revisions expand procurement for high-rise construction in fault-line corridors. METI oversees industrial emissions compliance for expanded aggregate production facilities. Technical institutes in Kanto and Kansai regions concentrate qualified lightweight aggregate concrete technicians for project execution.
India
Smart Cities Mission infrastructure tenders in Mumbai and Bangalore corridors specify thermally efficient envelope systems. Bureau of Indian Standards establishes performance benchmarks for structural lightweight concrete in urban corridor buildouts. Expanded clay block systems remain underpenetrated in western and southern state construction markets.
Global Lightweight Aggregate Concrete Market Competitive Landscape
Capability concentration sits with vertically integrated kiln operators; scale advantage sits with multinational ready-mix networks. The market structures around three archetypes: integrated aggregate-to-concrete producers controlling raw material quality, regional shale specialists anchoring seismic corridor supply, and metropolitan ready-mix operators with dedicated lightweight silo infrastructure. Dominant competitive moves include backward integration into captive aggregate production and capacity consolidation in precast manufacturing corridors.
Among European-based integrated producers, Heidelberg Materials exemplifies the kiln-to-batch-plant archetype through expanded clay network control. Arcosa Lightweight occupies a position within the regional shale specialist tier, while Cemex represents the metropolitan ready-mix model with dedicated lightweight aggregate silo infrastructure across multiple markets.
| Leading Market Players |
|---|
| Heidelberg Materials |
| Lafarge |
| Arcosa Lightweight |
| Votorantim Cimentos |
| Buzzi Unicem |
| Cemex |
| Holcim |
| SCG |
| CRH |
| Others |
Supply & Pricing Matrix
Single-source dependency on Italian and Icelandic volcanic deposits for pumice aggregate compresses pricing power for Mediterranean marine contractors while forcing supply chain redundancy investments. This concentration dynamic widens price spreads between premium chloride-resistant specifications and standardized expanded clay alternatives.
Pricing Analysis
Long-term offtake agreements dominate procurement for German federal highway and Dutch public infrastructure tenders, locking in volume commitments against natural gas price volatility. Pricing stratifies across premium, standard, and economy tiers based on freeze-thaw certification grade and embodied carbon disclosure depth. Cost compression in economy-grade expanded clay is intensifying because shale aggregate producers in the US Gulf Coast face feedstock margin pressure. Infrastructure developers show lowest price sensitivity due to lifecycle cost accounting, while volume construction contractors in India negotiate aggressively on material unit costs.
Supply Chain Analysis
EU dual-use export control regimes on kiln technology limit expanded aggregate production equipment flows to Asian markets, constraining capacity buildout outside established manufacturing corridors. Supply concentrates in Germany, the United States, and China, with raw material flows drawing from sedimentary shale basins, kaolin clay deposits, and metallurgical slag streams. Single-source vulnerability around volcanic pumice quarries creates procurement risk for Mediterranean port projects. Distribution runs through vertically integrated batch-plant networks in metropolitan corridors and captive precast manufacturing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal embodied carbon thresholds are reshaping material selection hierarchies, creating a high-growth disruption window for geopolymer-bound lightweight formulations that collapse the carbon differential against conventional concrete.
For Market Incumbents: Insulate margin position through backward integration into captive expanded clay kiln capacity and ISO 14067-compliant Environmental Product Declaration certification for French and Dutch public procurement eligibility. Natural gas price volatility and emerging geopolymer substitution threats demand supply chain control investments. For New Entrants and Emerging Players: Build out technical consulting capabilities for mix-design optimization services, targeting the underpenetrated Indian Smart Cities Mission corridor where qualified lightweight aggregate concrete technicians remain scarce. A performance-based specification go-to-market angle unlocks federal highway tender access. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated kiln-to-batch-plant operators with established European supply chain density. Long-term viability hinges on embodied carbon accounting integration into public procurement scoring. Watch for GB standard harmonization across Belt and Road port projects as the signal for Asian production capacity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Aggregate Production | Heidelberg Materials controls expanded clay quality from quarry to batch plant across its German network. |
| Geopolymer Binder System Development | Scandinavian bridge contractors specify fly ash formulations for coastal chloride resistance specifications. |
| ISO 14067-Compliant EPD Certification | Dutch and French public procurement tenders rank bids by embodied carbon scoring thresholds. |
| Technical Consulting Service Unbundling | German infrastructure developers retain independent concrete technologists for batch-plant audit protocols. |
| Smart Cities Mission Corridor Expansion | Mumbai and Bangalore infrastructure tenders specify thermally efficient envelope systems with limited local supply. |
Research Methodology
Desk research of trade customs data, EU Construction Products Regulation filings, and EPA National Emission Standards compliance records preceded structured interviews with expanded aggregate plant managers, ready-mix procurement leads, and civil engineering specification holders. Primary fieldwork with precast concrete producers and infrastructure developers was cross-referenced against SEC filings from publicly traded building materials groups and BIS performance benchmark publications. Bottom-up volume modeling triangulated against top-down construction spending forecasts across the analysis window.
Assumptions held fixed include EU Green Deal embodied carbon threshold enforcement timelines and GB standard harmonization pathways for Belt and Road certification, while natural gas price trajectories and seismic code revision schedules were stress-tested across scenarios. Segmentation modeling tracked product type density tiers, application delivery methods, and end-user specification authority. CAGRs were derived from production capacity expansion announcements and public infrastructure tender pipelines, with kiln commissioning timelines and REACH chemical compliance costs as industry-specific forecast inputs.
Stress conditions across natural gas feedstock pricing, volcanic quarry supply disruptions, and geopolymer binder technology maturation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions. Material shifts in EU Industrial Emissions Directive monitoring requirements or EPA NESHAP enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Canada Architectural Coatings Market
Building Materials
US Cement Tiles Market
Building Materials
West Africa Cement Market
Building Materials
Gravity Retaining Wall Market
Building Materials
Europe Exterior Sheathing Market
Building Materials
Spain Cement Market
Building Materials
Global Glass Fiber Reinforced Concrete Market
Building Materials
Drywall Joint Tape Market
Building Materials
East Africa Wall Putty Market
Building Materials
Glass Facade Market
Building Materials
Singapore Architectural Coatings Market
Building Materials
Construction Glass Market
Building Materials
Composite Decking and Railing Market
Building Materials
US Facade Market
Building Materials
Block Paving Market
Building Materials
Building and Construction Plastics Market