
 Residential Roofing Market | 2026-2036
Residential Roofing Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Roofing Market Outlook
F-Gas Regulation is rebalancing insulation-to-membrane cost ratios across European residential retrofits. Owens Corning leverages mineral wool integration to sustain margin depth in reroofing bundles. GAF Materials LLC anchors asphalt shingle volume through contractor loyalty programs and distribution density. CertainTeed Corporation differentiates via synthetic underlayment technology leadership in coastal wind zones.
Residential roofing encompasses weatherproof envelope systems installed on single-family and multi-family structures, typically comprising asphalt shingles, metal panels, clay or concrete tiles, or natural slate secured over underlayment and deck sheathing with pitches ranging from 2:12 to 12:12 for effective drainage. These assemblies protect structural integrity, regulate thermal transfer, and determine building energy performance across climates. Asphalt shingles still occupy the largest installed base in North America due to replacement cycle density and contractor familiarity, though metal roofing captures accelerated specification in hail-prone and wildfire-interface zones where insurers tighten coverage terms. Tile roofing retains premium positioning in Mediterranean and Spanish Colonial architectural markets, with clay sourcing from Mexico and Spain shaping landed cost structures.
US EPA Energy Star roofing specifications and California Title 24 cool roof requirements are tightening solar reflectance minimums, forcing reformulation of dark-pigmented materials and expanding white TPO and coated metal eligibility. IECC code cycles adopted across US states are pushing insulation R-value upgrades during roof replacement events, bundling structural and thermal improvements. Stakeholders must monitor how municipal electrification ordinances and utility rebate programs restructure the trade-off between incremental reroofing costs and long-term energy savings.
Market Dynamics
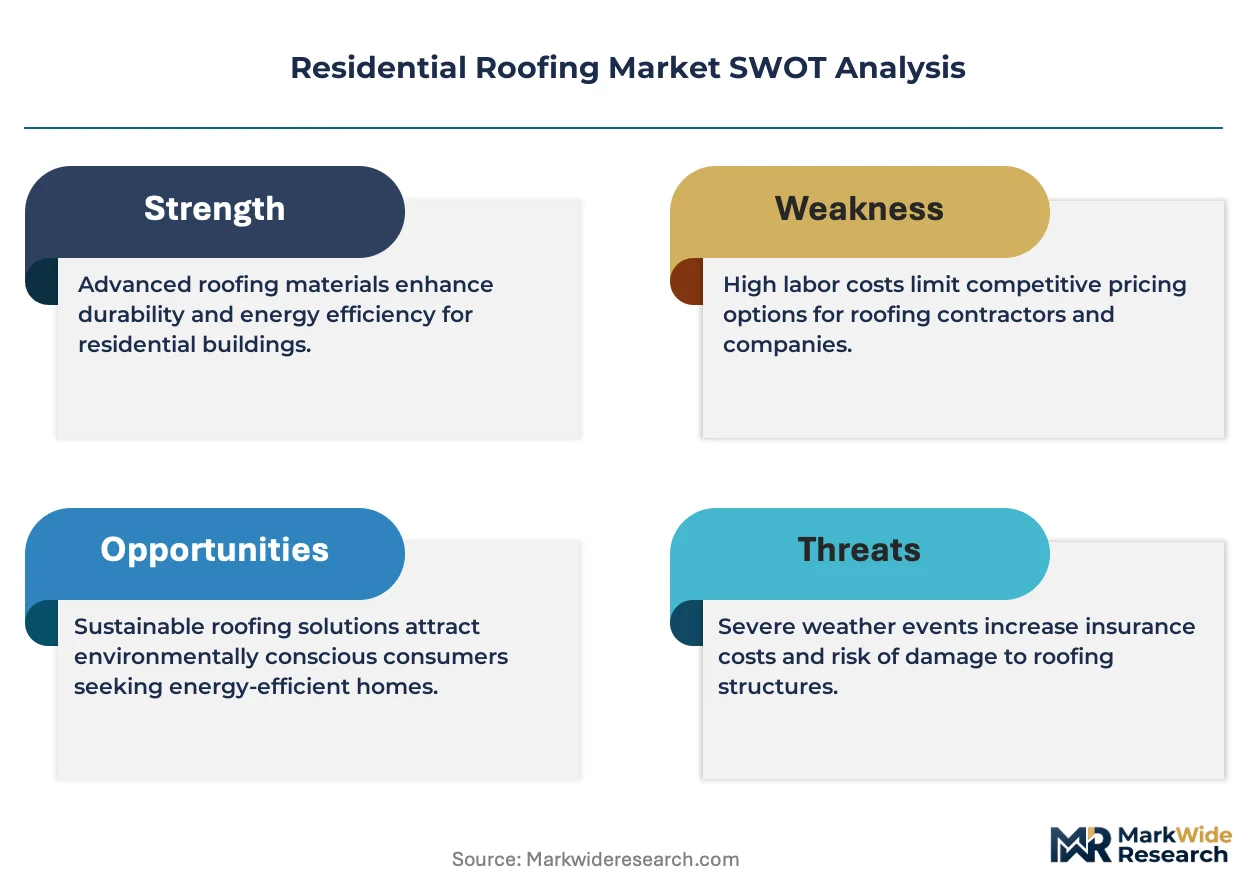
Cool roof mandates under California Title 24 are compressing traditional asphalt specification volumes while elevating reflective membrane and coated metal eligibility across reroofing events. This regulatory pressure is restructuring material cost trade-offs and contractor bundling strategies.
Growth Catalysts
- Title 24 Cool Roof Compliance:California's solar reflectance minimums are forcing reformulation of dark-pigmented materials and expanding white TPO eligibility in reroofing bundles.
- Wildfire-Interface Insurance Terms:Hail-prone and wildfire-adjacent zones are tightening coverage requirements, accelerating metal roofing specification among single-family developers.
- IECC Code Adoption Cycles:US states are pushing insulation R-value upgrades during roof replacement events, bundling structural and thermal improvements into single contracts.
Market Restraints
- Petroleum-Derived Binder Volatility:Asphalt shingle production remains exposed to crude oil price swings, compressing margin stability for volume producers.
- Clay Import Concentration:Mediterranean and Spanish Colonial tile sourcing depends on Mexico and Spain supply corridors, creating landed cost vulnerability.
- Dark Pigment Reformulation Limits:EPA Energy Star reflectance minimums are forcing material science investments that lag behind mandate timelines.
Strategic Opportunities
- Sun Belt Suburban Corridors:Florida through Texas and Arizona installation activity concentrates specification volume in high-replacement-cycle geographies.
- Electrification Ordinance Bundling:Municipal solar-ready roof requirements are creating integrated reroofing-plus-electrical-upgrade service packages.
- Synthetic Underlayment Convergence:Coastal wind zone performance standards are elevating polymer-based secondary barrier specification alongside primary roofing materials.
Industry Challenges
- Cool Roof Installer Certification:Title 24 compliance documentation requires trained crews capable of reflectance testing and rebate paperwork.
- Membrane-to-Insulation Integration:IECC thermal upgrade bundling demands cross-trade coordination between roofing and insulation contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Roofing Market |
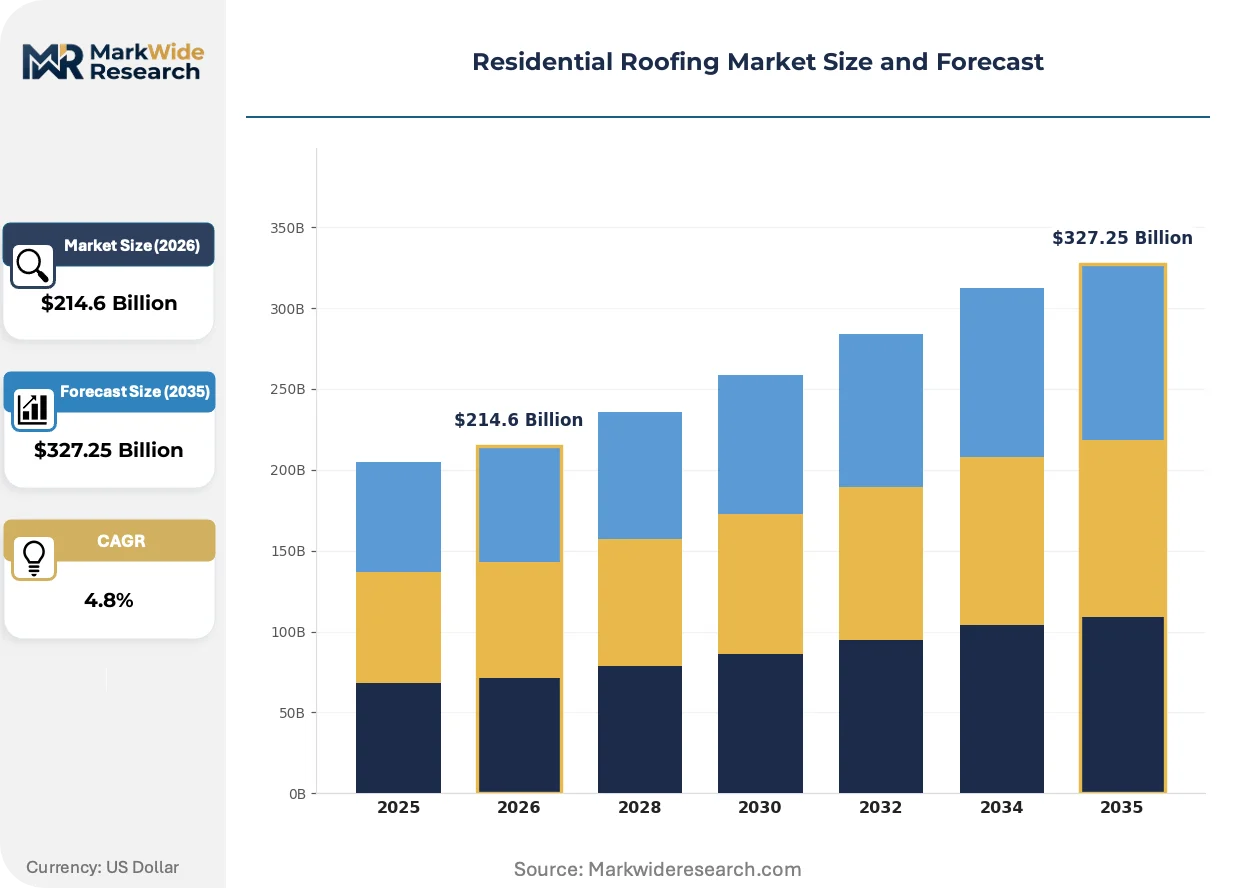
| Market Size in 2026 | $214.6 Billion |
| Market Size in 2035 | $327.25 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Asphalt Shingles, Metal Roofing, Tile Roofing, Slate Roofing Material: Fiberglass, Organic Asphalt, Steel, Aluminum Installation Type: New Construction, Roof Replacement, Repair Services, Retrofit Service Type: Design Services, Maintenance, Inspection, Installation |
| Companies Covered | GAF Materials LLC, Owens Corning, IKO Industries Ltd., TAMKO Building Products LLC, Atlas Roofing Corp., Carlisle Companies Inc., CertainTeed Corporation, Compagnie de Saint-Gobain SA, BEACON ROOFING SUPPLY INC., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Roofing Market Strategic Shifts
Material performance standards and procurement patterns are restructuring competitive positioning across residential roofing. Three distinct vectors are compressing traditional specification models.
Reflective membrane technology is overtaking dark asphalt shingle dominance in California reroofing markets. Single-family housing developers in suburban corridors are accelerating specification of white TPO and coated metal to meet Title 24 solar reflectance minimums. This shift is compressing petroleum-derived shingle volume while elevating polymer and coating chemistry capabilities among contractors.
EPA Energy Star roofing specifications are tightening solar reflectance thresholds across US states beyond California. Industrial consequence includes forced reformulation of traditional dark-pigmented materials and expanded eligibility for light-colored alternatives. Metal roofing and reflective membrane categories are capturing specification share in reroofing events where utility rebate programs offset incremental material costs.
Contractor loyalty programs are consolidating specification influence in suburban single-family markets. National distributors are bundling material supply with installation training and warranty administration, compressing independent contractor autonomy. This channel concentration is most visible in Texas and Florida Sun Belt corridors where replacement cycle density rewards scale-based procurement relationships.
Residential Roofing Market Segmentation
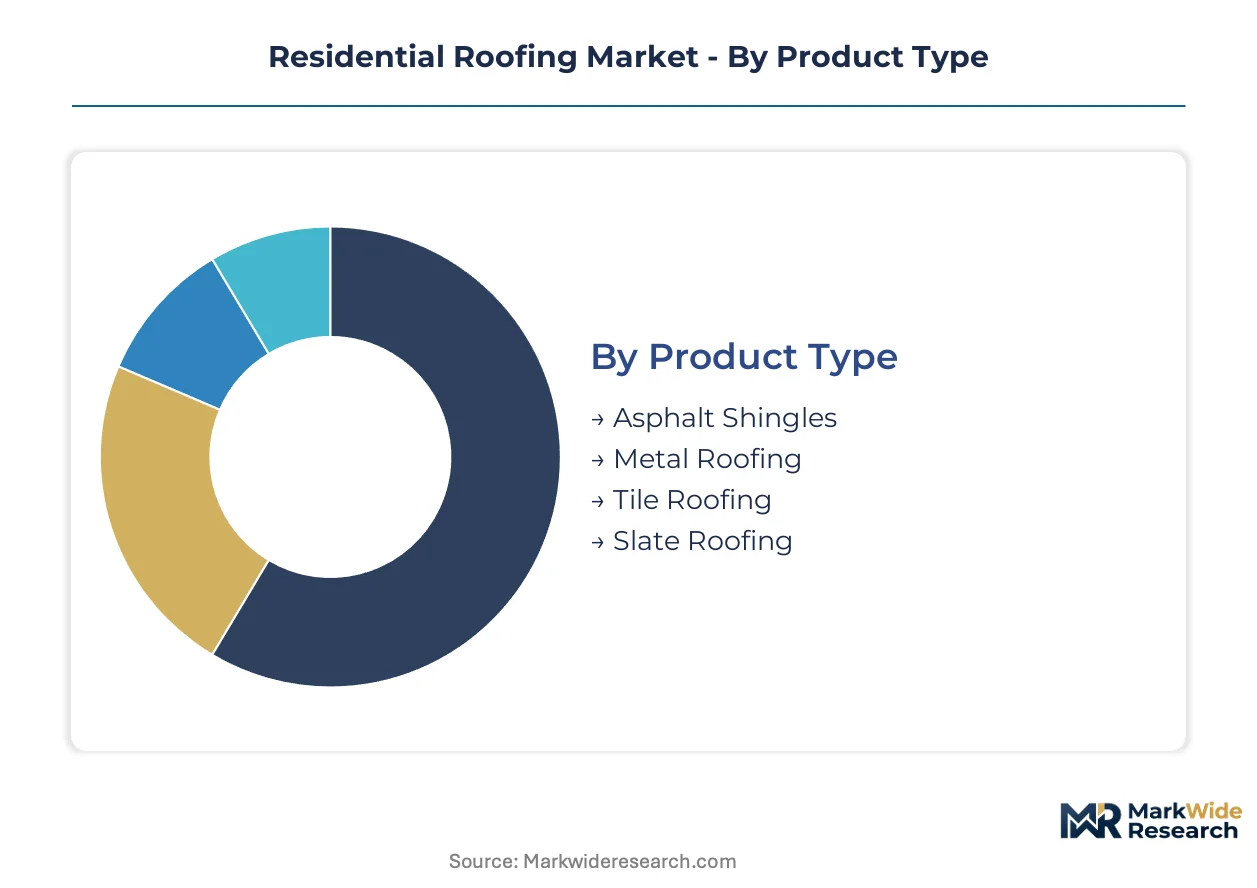
Residential roofing procurement patterns diverge sharply between standalone material supply and integrated system bundles. Understanding these structural splits reveals where margin pools concentrate and which specification pathways command installer loyalty across reroofing and new construction cycles.
Product Type:
Asphalt shingles function as standalone commodity purchases with minimal system integration, while metal and tile roofing increasingly embed within comprehensive envelope assemblies.
- Asphalt Shingles:Fiberglass-reinforced mats saturated with asphalt and surfaced with mineral granules dominate North American reroofing volumes. Suburban single-family corridors in Texas and Florida sustain replacement cycle density despite California Title 24 reflectance mandates compressing dark-pigmented specification.
- Metal Roofing:Standing seam and shingle-profile steel or aluminum panels integrate with synthetic underlayment and ventilation systems in wildfire-interface zones. Insurers in Colorado and California counties are tightening coverage terms, accelerating specification among custom homebuilders seeking Class A fire ratings.
- Tile Roofing:Clay and concrete profiles from Mexican and Spanish supply corridors serve Mediterranean architectural markets with limited system bundling.
- Slate Roofing:Natural stone from Vermont and Pennsylvania quarries occupies premium restoration segments with standalone procurement patterns.
Volume placements concentrate in Asphalt Shingles; the faster expansion belongs to Metal Roofing.
Material:
Material selection maps directly onto cost tier stratification, with fiberglass and organic asphalt anchoring economy segments while steel and aluminum capture premium specification.
- Fiberglass:Reinforced asphalt shingles with fiberglass mat cores deliver economy-tier performance across high-volume suburban reroofing markets. Texas and Florida installation contractors specify fiberglass as the default replacement material where insurance payouts prioritize cost containment over longevity.
- Steel:Galvanized and galvalume coil stock for metal roofing panels commands mid-to-premium pricing tiers. California Title 24 cool roof compliance is elevating white-coated steel specification in Sacramento and Central Valley reroofing events where solar reflectance minimums exclude traditional dark materials.
- Organic Asphalt:Felt-based shingle substrates retain niche specification in coastal humidity zones where fiberglass delamination risks concentrate.
- Aluminum:Lightweight coil stock dominates coastal Florida and Gulf Coast markets where salt corrosion resistance justifies material premium over steel alternatives.
Economy-tier procurement clusters on Fiberglass; premium specification is climbing fastest in Steel.
Installation Type:
Installation segmentation separates one-time capital events from recurring service relationships, with profound implications for contractor business model design and customer lifetime value.
- New Construction:Builder-grade specification tied to single-family housing permits concentrates volume in Sun Belt suburban corridors. National production homebuilders in Phoenix, Dallas-Fort Worth, and Tampa-St. Petersburg markets bundle roofing into fixed-price construction contracts with minimal homeowner involvement.
- Roof Replacement:Insurance-driven reroofing events following hail or wind damage dominate Midwest and Southern Plains revenue cycles. Independent contractors in Oklahoma and Kansas compete for adjuster referrals where claim settlement timelines compress material selection windows.
- Repair Services:Spot maintenance and leak remediation generates recurring revenue streams with higher margin profiles than full replacements.
- Retrofit:Cool roof and solar-ready upgrades integrate with IECC thermal improvement mandates in California and emerging municipal electrification ordinances.
Transaction density peaks in Roof Replacement; retrofit bundling with electrification upgrades is expanding most quickly.
Service Type:
Service segmentation distinguishes pure labor provision from knowledge-intensive advisory functions, with design and inspection services commanding premium positioning.
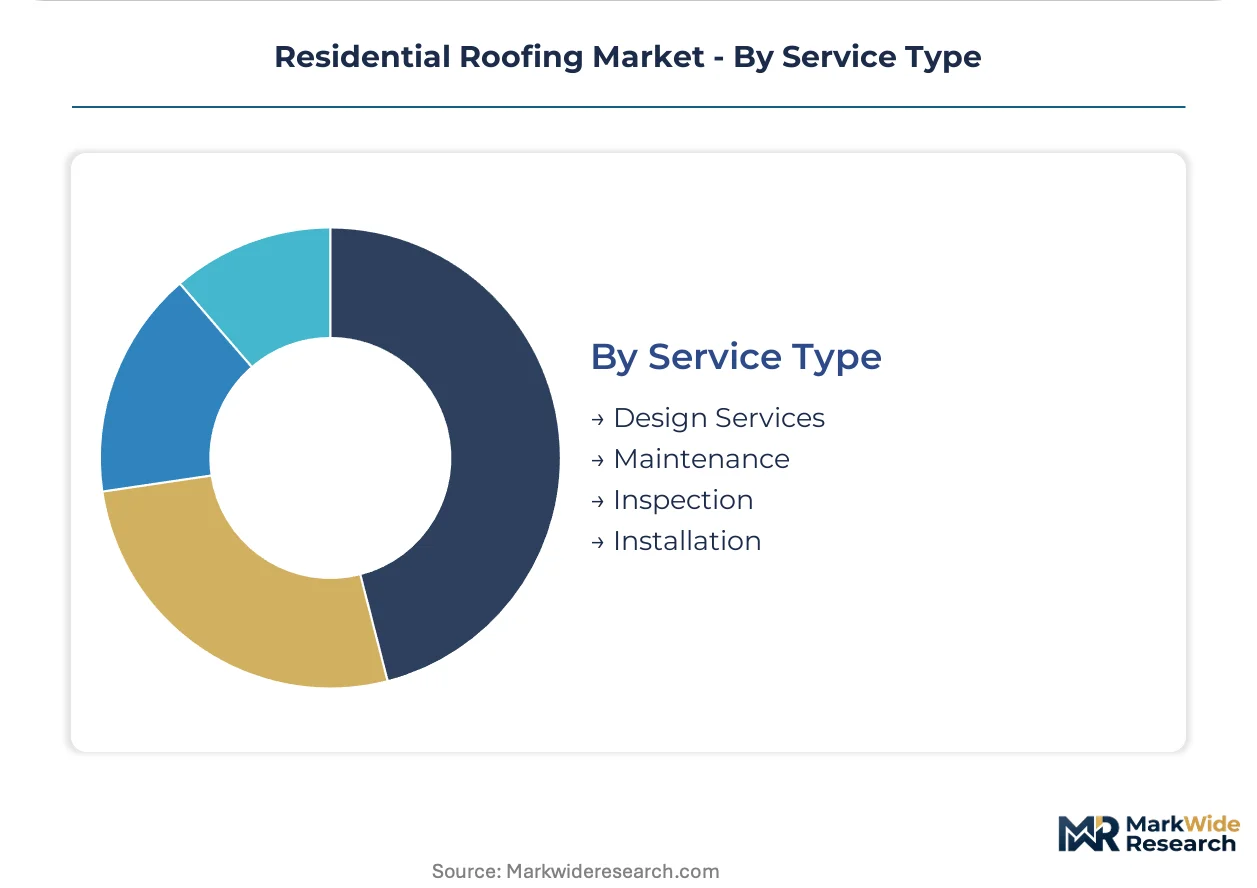
- Installation:Labor-only execution of material placement dominates contractor revenue models. Sun Belt roofing crews in Florida and Texas markets compete on speed and warranty administration rather than technical differentiation.
- Maintenance:Scheduled inspection and preventive repair programs build recurring revenue relationships. Commercial property management firms in Arizona and Nevada are adopting annual maintenance contracts to extend membrane system lifespans in extreme UV exposure climates.
- Design Services:Architectural specification support and energy modeling command fee-based positioning. California Title 24 compliance documentation requires trained designers capable of reflectance testing and rebate paperwork.
- Inspection:Third-party condition assessment and insurance claim documentation serves dispute resolution and pre-sale due diligence functions.
Labor volume concentrates in Installation; advisory services are gaining share fastest in Design Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Installation activity concentrates in suburban single-family corridors across the US Sun Belt, where replacement cycle density and insurance-driven reroofing events sustain volume. California Title 24 mandates are compressing traditional asphalt specification while elevating reflective membrane demand. Four countries anchor distinct demand patterns and regulatory frameworks.
United States
Texas and Florida suburban corridors drive replacement cycle density among single-family housing developers. EPA Energy Star roofing specifications tighten solar reflectance thresholds beyond California, forcing reformulation of dark-pigmented materials. Phoenix and Dallas-Fort Worth metro areas concentrate builder-grade specification tied to housing permit volumes.
Canada
Hail-prone Prairie Provinces accelerate metal roofing specification as insurers tighten coverage terms in Alberta and Saskatchewan. National building codes push thermal performance upgrades during roof replacement events. Toronto and Vancouver metropolitan areas concentrate design-service bundling for energy modeling compliance.
Mexico
Mediterranean architectural markets in Mexico City and Guadalajara sustain clay tile sourcing from domestic and Spanish supply corridors. Urban densification elevates multi-family roofing specifications. Monterrey industrial clusters anchor coated metal production for export markets.
Germany
F-Gas Regulation rebalances insulation-to-membrane cost ratios across residential retrofits in Bavaria and North Rhine-Westphalia. EU Green Deal thermal renovation targets compress traditional material specification windows. Stuttgart and Munich metropolitan areas concentrate synthetic underlayment specification for wind zone performance.
Australia
Extreme UV exposure climates in Queensland and Western Australia elevate annual maintenance contract adoption for membrane system lifespan extension. Building code thermal performance upgrades bundle structural and insulation improvements. Sydney and Melbourne coastal wind zones drive polymer-based secondary barrier specification.
Residential Roofing Market Competitive Environment
US producers anchor the volume-driven tier; European specialists hold premium-positioning corridors through material science differentiation. The vendor base fragments across three strategic tiers: integrated building materials conglomerates with mineral wool and insulation bundling capabilities; pure-play roofing manufacturers competing on contractor loyalty programs and distribution density; and regional specialists capturing architectural specification in tile and slate restoration segments. Dominant competitive moves include backward integration into mineral sourcing and cross-trade partnerships bundling roofing with electrical upgrades.
Within the integrated conglomerate tier, Owens Corning and CertainTeed Corporation exemplify multi-material platform strategies spanning insulation, underlayment, and primary roofing systems. GAF Materials LLC anchors the pure-play volume tier through contractor-facing distribution relationships. These three entities represent distinct archetypes: mineral wool integration for margin depth, synthetic underlayment technology leadership in coastal zones, and asphalt shingle volume defense through channel loyalty programs respectively.
| Leading Market Players |
|---|
| GAF Materials LLC |
| Owens Corning |
| IKO Industries Ltd. |
| TAMKO Building Products LLC |
| Atlas Roofing Corp. |
| Carlisle Companies Inc. |
| CertainTeed Corporation |
| Compagnie de Saint-Gobain SA |
| BEACON ROOFING SUPPLY INC. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between Title 24-compliant reflective systems and conventional dark-pigmented materials manifests in divergent pricing power and supply chain sourcing strategies across California and Sun Belt corridors. Premium white TPO and coated metal command material cost premiums while petroleum-derived asphalt shingles face margin compression from crude oil volatility and reformulation investments.
Pricing Analysis
Volume-versus-margin splits separate commodity asphalt shingle transactions from integrated system bundles. Three-tier pricing structure across premium, standard, and economy levels stratifies by thermal performance certification and fire rating, with California Title 24 compliance documentation adding service fees. Cost compression in dark-pigmented materials is intensifying because EPA Energy Star reflectance minimums demand material science investments. Insurance-driven reroofing events in Texas and Florida exhibit highest price sensitivity, while custom homebuilders in wildfire-interface zones accept material premiums for Class A ratings.
Supply Chain Analysis
Asphalt binder supply rests on Gulf Coast petroleum refining capacity and Canadian bitumen extraction, with clay tile sourcing anchored in Mexican and Spanish quarry operations. Raw material dependencies span petroleum derivatives for shingle saturation, galvanized steel coil from domestic mills, and mineral granules from regional aggregate processors. Single-source vulnerability concentrates in Mediterranean tile imports subject to trans-Atlantic logistics constraints. Distribution runs through national roofing distributors bundling material supply with contractor training and warranty administration in Florida and Texas suburban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Residential roofing is consolidating around scale-based procurement relationships and regulatory compliance capabilities, with California Title 24 mandates and IECC code cycles forcing smaller contractors into distributor-dependent arrangements.
For Market Incumbents: Cement specification influence through synthetic underlayment technology leadership in coastal wind zones and cool roof installer certification programs. Threats from emerging polymer membrane specialists and municipal electrification ordinance complexity demand cross-trade partnerships bundling roofing with electrical upgrades. Channel control through loyalty programs and distribution density remains the critical lever in Sun Belt suburban corridors.
For New Entrants and Emerging Players: Solar-ready roof retrofit bundling represents the most penetrable white-space target, particularly in California municipalities advancing electrification ordinances. Independent contractors seeking Title 24 compliance documentation support offer a secondary entry path. Go-to-market positioning should emphasize design-services capability for reflectance testing and rebate paperwork administration.
For Investors and Strategic Acquirers: Re-rating potential sits with mineral wool-integrated building materials platforms given IECC thermal upgrade bundling mandates across US states. Long-term viability favors entities with backward integration into mineral sourcing and cross-material envelope system capabilities. The signal to watch is municipal solar-ready roof requirement adoption velocity in Sun Belt metropolitan planning departments.
| Strategic Initiative | Industry Significance |
|---|---|
| Cool Roof Installer Certification Program | Title 24 compliance documentation requirements in California create trained crew scarcity. |
| Synthetic Underlayment Technology Partnership | Coastal wind zone performance standards elevate polymer-based secondary barrier specification. |
| Mineral Wool Integration Investment | IECC code cycles bundling insulation R-value upgrades with roof replacement events. |
| Solar-Ready Roof Retrofit Service Launch | Municipal electrification ordinances integrate reroofing with electrical infrastructure upgrades. |
| Contractor Loyalty Program Expansion | Texas and Florida replacement cycle density rewards scale-based procurement relationships. |
Study Parameters
Document review covered SEC filings from building materials conglomerates, EPA Energy Star certification databases, and California Title 24 compliance records, complemented by interviews with roofing contractors, distributor procurement managers, and municipal building code officials. Secondary validation drew from IECC adoption tracking, insurance industry coverage term disclosures, and customs data on clay tile imports. Bottom-up installation volume estimates triangulated against top-down construction spending allocations across the analysis window.
Historical permit data cross-referenced against panel input from single-family housing developers established baseline specification patterns. Segmentation dimensions modeled include product type, material grade tier, installation event category, and regional regulatory framework cluster. CAGRs derived from replacement cycle density projections and code mandate adoption timelines, with inputs from utility rebate program funding levels and insurer coverage term evolution.
Revisions become necessary when Title 24 mandate expansion accelerates beyond California, petroleum price volatility disrupts asphalt shingle production economics, or wildfire-interface zone designation expands geographically. A concentrated set of regulatory adoption triggers and commodity input cost movements warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
Italy Manufactured Homes Market
Residential Construction
Canada Residential Construction Market
Residential Construction
Swimming Pool Construction Market
Residential Construction
Europe Prefabricated Housing Market
Residential Construction
North America Bath Remodeling Market
Residential Construction
Germany Residential Construction Market
Residential Construction
Japan Residential Construction Market
Residential Construction
North America Prefabricated Housing Market
Residential Construction
Austria Prefabricated Housing Market
Residential Construction
Latin America Manufactured Homes Market
Residential Construction
Canada Manufactured Homes Market
Residential Construction
Europe Manufactured Homes Market
Residential Construction
Saudi Arabia Manufactured Homes Market
Residential Construction
North America Residential Construction Market
Residential Construction
UAE Manufactured Homes Market
Residential Construction
Saudi Arabia Residential Construction Market