
 Fiber Reinforced Concrete Market | 2026-2036
Fiber Reinforced Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Reinforced Concrete Market Analysis
Multi-source procurement for steel fiber is decoupling from traditional single-source relationships in North American infrastructure projects. Heidelberg Materials leverages captive cement production to secure downstream fiber-concrete blending capacity. Sika AG anchors its position through formulation chemistry that binds synthetic fibers to Portland cement matrices. Bekaert competes on drawn-wire fiber geometries optimized for crack-arrest performance in industrial slabs.
Fiber reinforced concrete composites disperse discrete filaments—steel, synthetic, glass, or natural—within a cementitious matrix to enhance post-crack tensile capacity and shrinkage control. Typical steel fiber dosages range from 25 to 60 kg per cubic meter depending on structural performance class specified. Synthetic fibers command expanding specification share in precast products where corrosion immunity and weight reduction outweigh premium material cost. Steel fibers retain margin concentration in industrial flooring applications where abrasion resistance and load-bearing duty cycles dominate design criteria.
ASTM C1116 governs fiber-reinforced concrete proportioning and testing protocols in the United States, while EN 14889 establishes European conformity benchmarks for steel and polymer fibers. The Federal Highway Administration pushes performance-based specifications that reward fiber-modified durability in bridge deck overlays. Stakeholders must monitor evolving embodied-carbon accounting rules that could reweight natural fiber competitiveness against synthetic alternatives.
Market Dynamics
Federal Highway Administration performance-based specifications are forcing specification upgrades across US bridge infrastructure, while Deutsche Bahn's track slab mandates in Germany create parallel demand pull for macro-synthetic fiber systems.
Growth Catalysts
- Infrastructure resilience mandates:The Federal Highway Administration requires fiber-modified durability in bridge deck overlays, accelerating adoption across state transportation departments.
- Railway concrete specifications:Deutsche Bahn's track slab programs in Germany mandate macro-synthetic fiber dosages, creating standardized procurement volumes.
- Corrosion immunity requirements:Synthetic fibers displace steel in precast products where chloride exposure and weight reduction drive material substitution.
Market Restraints
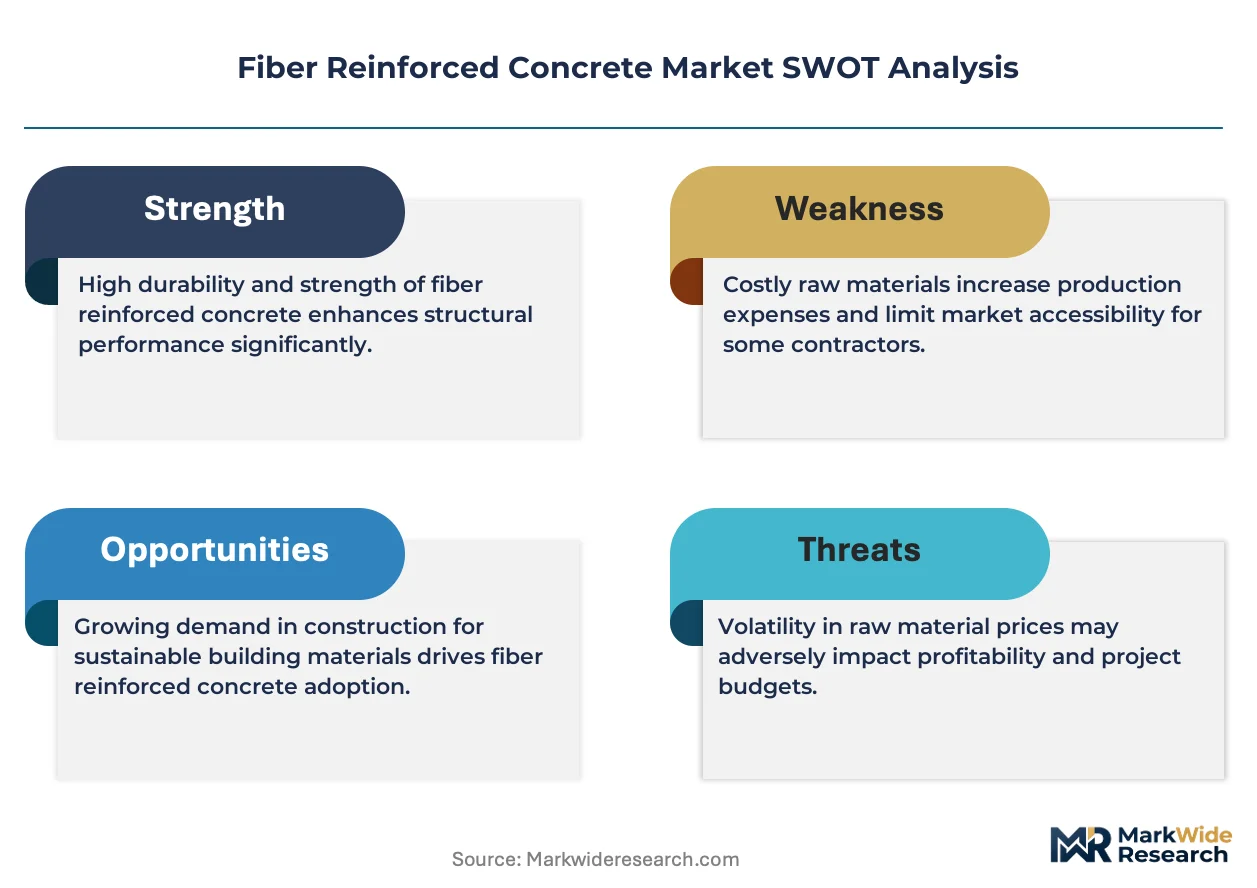
- Steel fiber supply concentration:North American infrastructure projects face decoupling risks from traditional single-source relationships for drawn-wire geometries.
- Premium material cost spreads:Synthetic fiber price premiums limit specification share in cost-sensitive municipal paving contracts.
- Embodied-carbon accounting uncertainty:Evolving lifecycle assessment rules create compliance friction for natural fiber alternatives against synthetic benchmarks.
Strategic Opportunities
- Industrial flooring specification gaps:Abrasion-resistant steel fiber formulations retain margin concentration in warehouse and manufacturing slab applications.
- CE marking harmonization:EN 14889 conformity benchmarks enable cross-border specification standardization across European Union member states.
- Natural fiber competitiveness:Carbon accounting rule evolution could reweight hemp and jute fiber economics against polypropylene alternatives.
Industry Challenges
- Formulation chemistry integration:Binding synthetic fibers to Portland cement matrices requires specialized technical expertise that constrains blending capacity expansion.
- Multi-standard compliance complexity:ASTM C1116 and EN 14889 testing protocol divergence forces dual certification investments for suppliers serving transatlantic projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Reinforced Concrete Market |
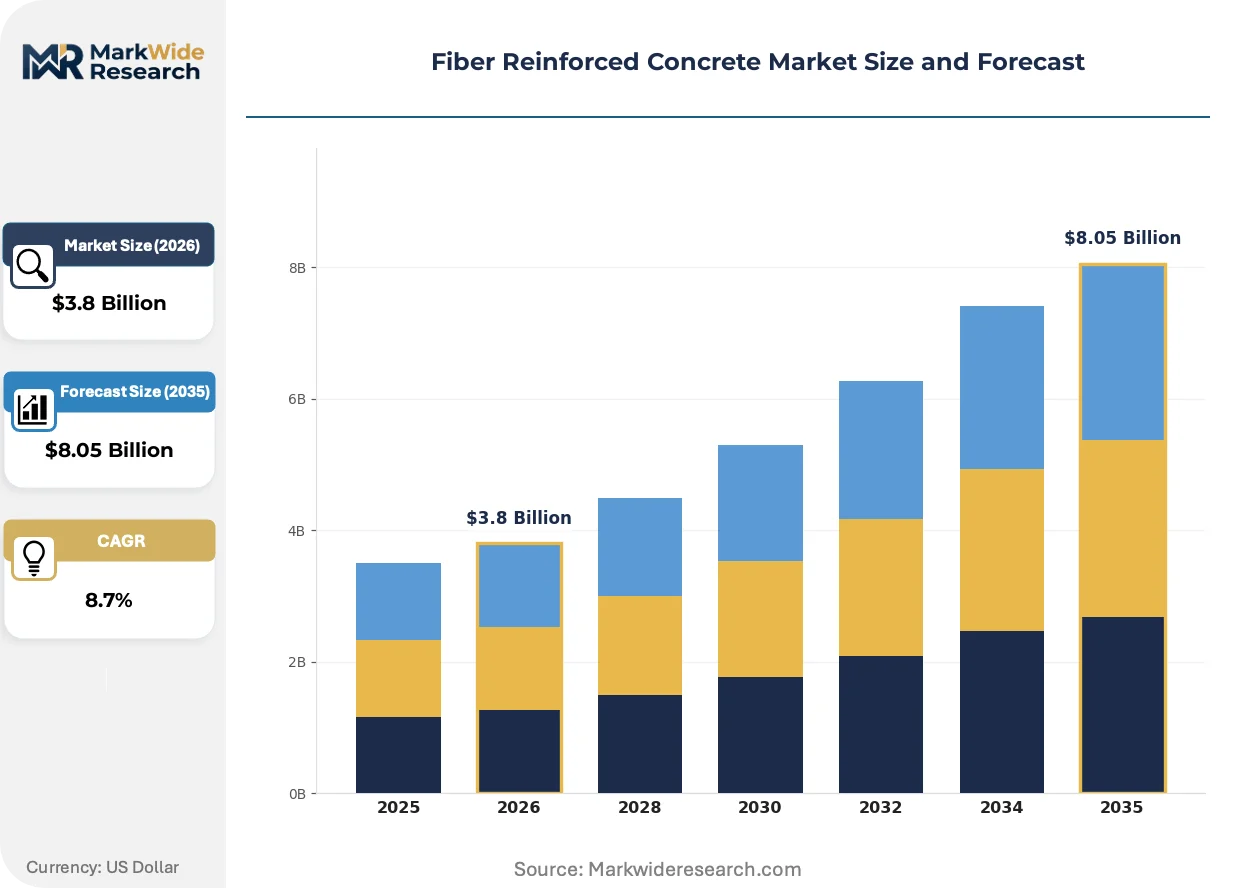
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Fibers, Steel Fibers, Glass Fibers, Natural Fibers Application: Commercial Construction, Residential Construction, Industrial Flooring, Precast Products End User: Contractors, Builders, Architects, Engineers Distribution Channel: Direct Sales, Online Sales, Retail Sales, Distributors |
| Companies Covered | Heidelberg Materials, Sika AG, Bekaert, Cemex, Owens Corning, BASF, Forta Corporation, Nycon Corporation, Holcim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Reinforced Concrete Market Emerging Trajectories
Specification chemistry and fiber geometry optimization are compressing the gap between performance tiers, while procurement decentralization reconfigures supplier relationships across infrastructure value chains.
Macro-synthetic fiber systems are consolidating specification share in precast tunnel segments and railway track beds. European railway authorities specify these formulations for corrosion immunity in electrified corridors. The technology is consolidating procurement volumes previously fragmented across steel fiber grades and welded wire mesh alternatives.
Performance-based specifications from the Federal Highway Administration reward post-crack tensile capacity metrics over prescriptive mix designs. State departments of transportation now qualify fiber-reinforced concrete through third-party durability testing. Bridge deck overlay programs in coastal states represent the most affected segment, with contractors adapting mix designs to meet equivalent service life calculations.
Multi-source procurement models now dominate North American infrastructure bidding, displacing sole-source steel fiber relationships that prevailed through 2020. General contractors aggregate volume across secondary suppliers to meet project-scale dosages. This pattern is most visible in Texas and California transportation contracts, where specification flexibility allows blended fiber strategies.
Fiber Reinforced Concrete Market Segmentation
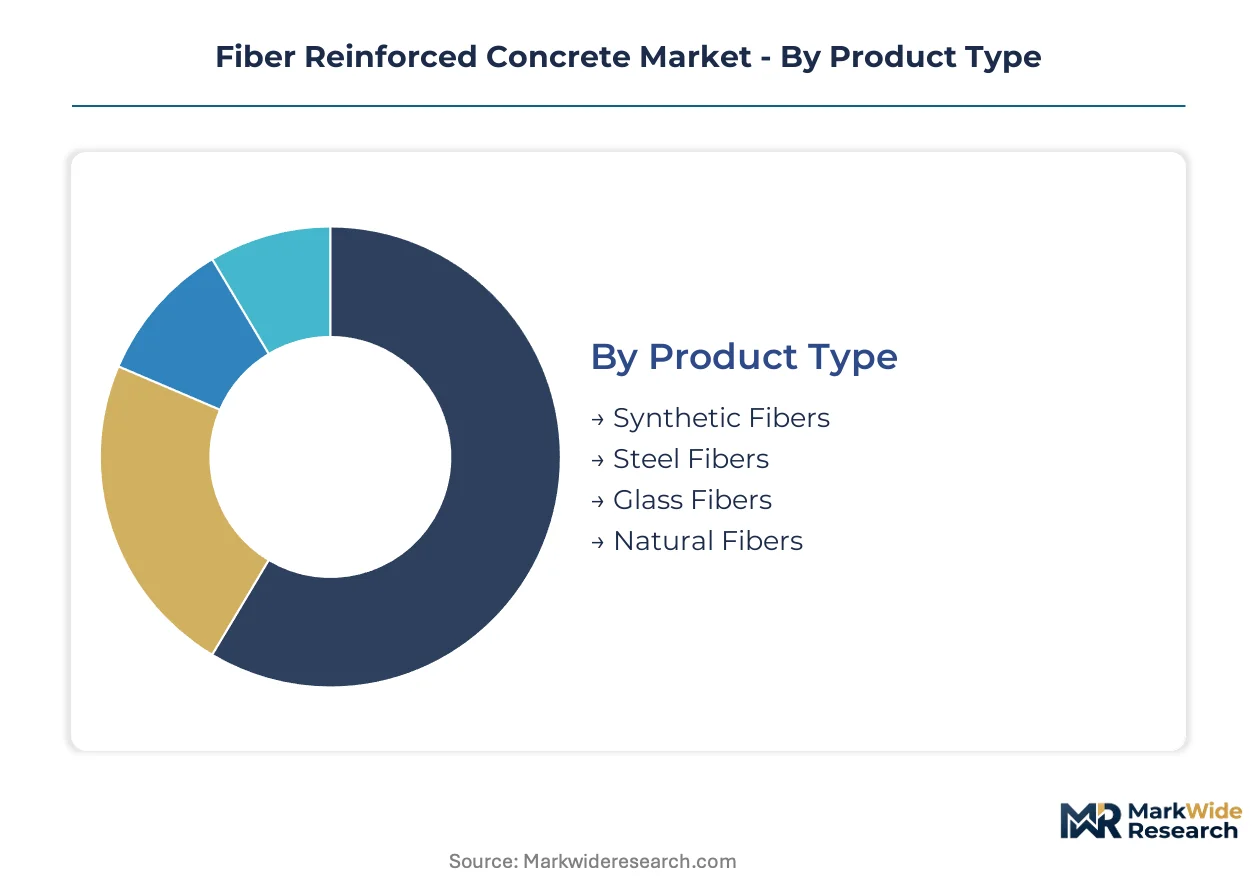
Fiber reinforced concrete procurement splits sharply between cost-driven volume applications and performance-critical premium specifications. Understanding where each segment commands pricing power versus commodity positioning shapes supplier strategy and investment allocation across the value chain.
Product Type:
Steel fibers dominate tonnage while synthetic fibers capture expanding specification share in corrosion-sensitive environments.
- Steel Fibers:Drawn-wire geometries deliver post-crack tensile capacity through mechanical anchoring in cement matrices. Industrial flooring in Germany's automotive manufacturing corridors specifies these formulations for load-bearing duty cycles exceeding 20 years.
- Synthetic Fibers:Polypropylene and polyolefin macro-fibers provide corrosion immunity and weight reduction in precast tunnel segments. Deutsche Bahn's track slab mandates across electrified railway corridors are consolidating procurement volumes previously fragmented across steel alternatives.
- Glass Fibers:Alkali-resistant formulations serve architectural cladding panels where surface finish quality outweighs structural fiber contribution.
- Natural Fibers:Hemp and jute variants face embodied-carbon accounting headwinds against synthetic benchmarks despite renewable sourcing credentials.
Today's leader: Steel Fibers. Tomorrow's challenger: Synthetic Fibers.
Application:
Specification intensity varies dramatically between structural load-bearing duty and aesthetic surface applications.
- Industrial Flooring:Abrasion-resistant steel fiber dosages from 40-60 kg per cubic meter anchor margin concentration in warehouse and manufacturing slab specifications. Texas and California transportation contracts now permit blended fiber strategies that aggregate volume across secondary suppliers.
- Precast Products:Macro-synthetic fiber systems displace welded wire mesh in tunnel segments and railway track beds where chloride exposure and weight reduction drive material substitution. European railway authorities specify these formulations for electrified corridor durability.
- Commercial Construction:High-visibility architectural applications prioritize crack control and surface finish over structural fiber loading.
- Residential Construction:Cost-sensitive municipal paving contracts limit synthetic fiber penetration despite performance advantages in shrinkage control.
Industrial Flooring commands current margin pools. Precast Products are climbing the fastest as railway infrastructure specifications harden.
End User:
Technical specification authority concentrates with design professionals while procurement execution sits with construction execution teams.
- Engineers:Structural engineers specify fiber dosages and performance classes in bridge deck overlays and tunnel linings. Federal Highway Administration performance-based specifications reward their post-crack tensile capacity calculations over prescriptive mix designs.
- Contractors:General contractors aggregate multi-source procurement volumes to meet project-scale dosages, displacing sole-source steel fiber relationships that prevailed through 2020.
- Architects:Surface finish and aesthetic integration drive fiber selection in exposed concrete applications.
- Builders:Production homebuilders prioritize cost minimization over fiber-modified durability in standard foundation specifications.
Engineers set technical standards. Contractors control procurement execution.
Distribution Channel:
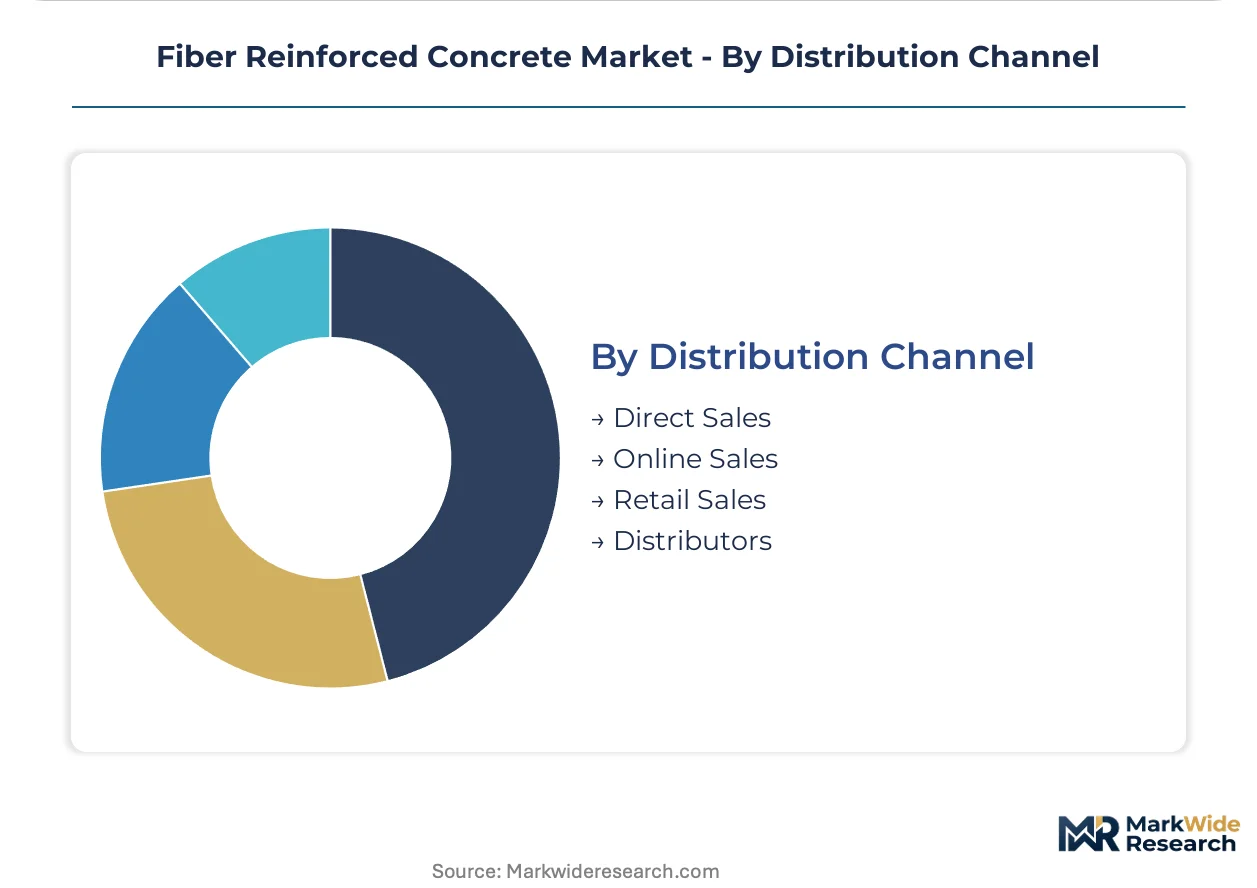
Channel selection tracks project scale and specification complexity rather than geographic coverage alone.
- Distributors:Regional construction supply networks aggregate fragmented contractor demand and provide technical support for mix design adaptation. Heidelberg Materials leverages captive cement production to secure downstream fiber-concrete blending capacity through these channels.
- Direct Sales:Large infrastructure projects specify fiber systems through direct manufacturer relationships that bypass distribution markups. Sika AG anchors its position through formulation chemistry support delivered directly to batch plant operators.
- Online Sales:Small-volume specialty fiber products for repair and renovation applications migrate to digital procurement platforms.
- Retail Sales:Consumer-grade fiber additives for minor concrete repair occupy limited shelf space at construction supply retailers.
Distributors own volume aggregation. Direct Sales capture specification influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr industrial corridor concentrates railway concrete specification authority through Deutsche Bahn's procurement standards. Federal mandates in the United States and centralized European railway planning drive divergent regional demand patterns for fiber-reinforced concrete systems.
United States
State transportation departments in Texas and California specify fiber-modified bridge deck overlays under Federal Highway Administration performance protocols. The FHA mandates post-crack tensile capacity testing that rewards synthetic and steel fiber blending strategies. Gulf Coast infrastructure corridors face chloride exposure pressures that accelerate specification upgrades in Florida and Louisiana port facilities.
Germany
Deutsche Bahn's track slab standardization mandates macro-synthetic fiber dosages across electrified railway corridors. The country's national transport regulator embeds durability requirements in federal infrastructure procurement rules. Bavarian automotive manufacturing clusters specify abrasion-resistant steel fiber formulations for plant flooring exceeding twenty-year duty cycles.
China
High-speed rail expansion programs generate standardized procurement volumes for macro-synthetic tunnel lining segments. The Ministry of Ecology and Environment's dual carbon goals shape embodied-carbon accounting preferences in coastal province infrastructure tenders. Yangtze River Delta megacity clusters specify fiber-reinforced concrete for flood-resilient underground transit systems.
India
National highway widening programs under the Ministry of Road Transport specify steel fiber overlays for heavy-vehicle corridors. The Bureau of Indian Standards drafts conformity protocols for synthetic fiber incorporation in precast drainage products. Gujarat industrial corridors adopt fiber-modified flooring for pharmaceutical manufacturing facilities requiring contamination control.
United Arab Emirates
NEOM and Red Sea Project developments specify corrosion-immune synthetic fibers for coastal infrastructure durability. The country's national building codes reference European EN standards for fiber conformity in megaproject concrete procurement. Dubai logistics hubs specify steel fiber industrial slabs for automated warehouse load-bearing requirements.
Fiber Reinforced Concrete Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized formulation chemistry and regional blending capacity. The market structures around three tiers: multinational construction material conglomerates with captive cement production, specialized fiber manufacturers with geometric optimization expertise, and regional blenders serving infrastructure procurement aggregators. Dominant competitive moves include backward integration into cement production and direct technical support relationships with batch plant operators.
Among European-based material specialists, Sika AG and Bekaert exemplify divergent archetype positioning. Sika AG represents the formulation chemistry tier, anchoring competitive position through technical integration with Portland cement matrices. Bekaert occupies the geometric optimization segment, with drawn-wire expertise translating into crack-arrest performance specifications. Heidelberg Materials demonstrates the conglomerate archetype, leveraging in-house cement production to secure downstream blending capacity in German and North American markets.
| Leading Market Players |
|---|
| Heidelberg Materials |
| Sika AG |
| Bekaert |
| Cemex |
| Owens Corning |
| BASF |
| Forta Corporation |
| Nycon Corporation |
| Holcim |
| Others |
Supply Flow & Price Mechanics
State transportation departments in Texas and California anchor procurement volume concentration, locking in contract-based long-term offtake pricing for fiber-reinforced concrete bridge deck overlays. This buyer archetype's specification authority under Federal Highway Administration mandates compresses margin negotiation space for suppliers competing on post-crack tensile capacity metrics.
Pricing Analysis
Input-cost pass-through from drawn-wire steel and polypropylene resin governs pricing dynamics across formulation tiers. Three-tier pricing structure across premium, standard, and economy levels separates certified EN 14889 conformity grades from uncertified commodity blends. Cost compression in synthetic fiber tiers is intensifying because polyolefin feedstock volatility outpaces cement price stability. Municipal paving contractors exhibit highest price sensitivity, while Deutsche Bahn's standardized procurement demonstrates lowest sensitivity due to durability mandates.
Supply Chain Analysis
Workforce availability constraints in Belgian wire-drawing facilities and German chemical synthesis plants tether production capacity to specialized labor pools. Supply concentrates in Belgium, Germany, and China for drawn-wire geometries and polymer fiber extrusion. Raw material dependencies span scrap steel feedstock, virgin polypropylene resin, and alkali-resistant glass rovings. Single-source vulnerability in North American drawn-wire supply creates procurement risk for infrastructure contractors. Distribution runs through regional construction supply networks that aggregate fragmented contractor demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fiber reinforced concrete has matured into a late-cycle quality story as Federal Highway Administration performance-based specifications displace prescriptive mix designs, rewarding suppliers with certified durability testing capabilities.
For Market Incumbents: Anticipate specification chemistry integration bottlenecks that constrain blending capacity expansion by securing captive technical expertise through direct batch plant operator relationships. Defend against multi-source procurement decentralization by anchoring sole-source positions in railway corridor mandates. Prioritize EN 14889 certification investments that enable cross-border specification standardization. For New Entrants and Emerging Players: Enter via natural fiber formulation gaps where evolving embodied-carbon accounting rules could reweight hemp and jute economics against polypropylene benchmarks. Target precast tunnel segment specifications in coastal infrastructure corridors where chloride exposure drives corrosion-immune material substitution. Pursue direct technical support relationships with state transportation department engineers as the primary go-to-market angle. For Investors and Strategic Acquirers: Construction material conglomerates with captive cement production are the most active acquirer in this space, seeking downstream blending capacity control. Long-term viability hinges on specification authority migration from contractors to design engineers. Acquisition target archetype: regional blenders with established batch plant technical support relationships. Monitor Federal Highway Administration rulemaking on lifecycle assessment integration as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cement Production | Heidelberg Materials leverages captive supply to secure downstream fiber-concrete blending capacity in German markets. |
| Formulation Chemistry Partnership | Sika AG anchors competitive position through technical integration with Portland cement matrices in batch plants. |
| Geometric Optimization Investment | Bekaert competes on drawn-wire fiber geometries optimized for crack-arrest performance in industrial slab specifications. |
| Multi-Source Procurement Aggregation | General contractors in Texas and California aggregate volume across secondary suppliers to meet project-scale dosages. |
| Performance-Based Specification Qualification | Third-party durability testing under ASTM C1116 protocols rewards post-crack tensile capacity over prescriptive designs. |
Methodological Framework
Multiple input streams — technical specification databases, procurement contract registries, and regulatory filing repositories — were reconciled to construct market estimates. Primary interviews with structural engineers, batch plant operators, state transportation procurement officers, and fiber manufacturer technical sales directors were validated against secondary sources including Federal Highway Administration specification bulletins, EN 14889 conformity assessment records, and SEC 10-K disclosures from listed construction material conglomerates. Bottom-up volume aggregation across application segments was cross-checked against top-down industry association estimates.
Historical shipment data was cross-referenced against expert panel inputs to establish baseline trajectories. The analytical framework modeled demand across product type, application intensity, end-user specification authority, and distribution channel structure throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation. Industry-specific forecast inputs included Deutsche Bahn track slab procurement schedules and Federal Highway Administration bridge deck overlay program allocations.
Inputs from state transportation department contract award databases and European railway authority procurement registries were available through the study window; gaps in real-time batch plant utilization rates introduce uncertainty bands around near-term volume estimates. Forecasts reflect documented assumptions on specification migration timelines and fiber substitution elasticity. Material deviation in Federal Highway Administration rulemaking pace or EN 14889 revision schedules warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
United Kingdom White Cement Market
Building Materials
Pre-Fabricated Glass Block Market
Building Materials
Africa Aluminum Door and Window Market
Building Materials
North America Dry-Mix Mortar Market
Building Materials
US Facade Market
Building Materials
Stone Adhesive Market
Building Materials
France Architectural Coatings Market
Building Materials
India Cement Market
Building Materials
Middle-East and Africa Buildings and Construction Sheets Market
Building Materials
East Africa Cement Market
Building Materials
Lightweight Cellular Concrete Market
Building Materials
United States Construction Materials Market
Building Materials
Bio-Based Structural Wood Adhesives for Modular Construction Market
Building Materials
Facade Gasket Market
Building Materials
Blind Bolts Market
Building Materials
US Cement Tiles Market