
 Roller Bearings Market | 2026-2036
Roller Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Roller Bearings Market Intelligence
A divergence in capital allocation toward specialized material science versus mass-production capacity is reorganizing competitive dynamics in the bearing industry. Schaeffler Technologies AG & Co. KG specializes in high-performance ceramic and specialty alloy bearings for demanding aerospace and e-mobility applications. SKF AB leverages its extensive global distribution network and condition monitoring services to serve diverse industrial end-users. JTEKT Corporation competes on manufacturing scale and cost-efficiency, particularly within the high-volume automotive sector.
Roller bearings are mechanical components that use rolling elements to reduce rotational friction and support loads between moving machine parts. These elements, such as cylinders, spheres, or tapers, are contained between two hardened steel rings, or races, to enable smooth, precise motion. Tapered roller bearings are prevalent in heavy-duty applications like railway equipment and commercial vehicles for their combined load-handling capabilities. The spherical roller segment is expanding, driven by its self-aligning properties suitable for systems with shaft deflection, such as those in wind turbines and mining conveyors.
International Organization for Standardization (ISO) standards define critical dimensions and tolerance classifications, ensuring global interchangeability. In Europe, the RoHS directive restricts hazardous substances in materials like chrome steel, influencing alloy selection for manufacturers. Stakeholders must now decide whether to invest in developing bearings for high-temperature electric vehicle applications or to optimize performance for existing industrial machinery.
Market Dynamics
The roller bearings market is being reorganized by dual pressures from energy transition mandates and advanced industrial automation. Demand for high-capacity, long-lifecycle components for wind turbines and electric vehicles is pulling capital toward material science innovation and specialized manufacturing.
Growth Catalysts
- Renewable Energy Mandates:Policies like the EU Green Deal are accelerating investments in wind energy projects, which require large-diameter spherical and tapered roller bearings capable of handling immense loads and offering extended operational life.
- Electric Vehicle Expansion:The automotive sector's shift to e-mobility creates demand for specialized bearings that can operate reliably at higher speeds and temperatures within electric motors and drivetrain systems.
- Industrial Modernization in China:Government-led initiatives in China to upgrade heavy industry and energy infrastructure concentrate significant demand for roller bearings used in everything from construction machinery to power generation equipment.
Market Restraints
- Input Material Volatility:Price fluctuations and supply constraints for high-purity chrome steel, specialty alloys, and ceramic materials create cost uncertainty and margin pressure for bearing manufacturers.
- Threat from Alternative Technologies:In niche high-speed, low-load applications, the development of advanced magnetic bearings and air bearings presents a long-term substitution risk for traditional rolling element components.
- Performance Limitations:Standard steel bearings face degradation in extreme temperature, high-vacuum, or corrosive environments found in chemical processing and certain aerospace applications, restricting their operational envelope.
Strategic Opportunities
- Smart Factory Automation:The proliferation of robotics and automated guided vehicles (AGVs) in logistics and manufacturing opens a new application frontier for compact, high-precision roller bearings.
- Integrated Sensor Technology:Embedding IoT sensors directly into bearing assemblies to create "smart bearings" for real-time condition monitoring and predictive maintenance represents a significant value-add opportunity. *Industrialization in Southeast Asia: Rapid industrial growth in nations like Vietnam and Indonesia provides an underpenetrated market for industrial bearings supporting new manufacturing plants, infrastructure, and energy projects.
Industry Challenges
- Complex Compliance Requirements:Manufacturers must navigate a dual challenge of adhering to global ISO standards for dimensional interchangeability while also meeting regional environmental rules like Europe's RoHS directive on hazardous substances.
- High Capital Expenditure:Producing high-tolerance bearings for demanding sectors such as aerospace and e-mobility requires substantial investment in precision grinding machines, heat treatment facilities, and clean-room assembly environments.
- Specialized Talent Scarcity:A shortage of material scientists and tribology experts capable of developing next-generation bearing alloys, coatings, and lubrication systems constrains the pace of innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roller Bearings Market |
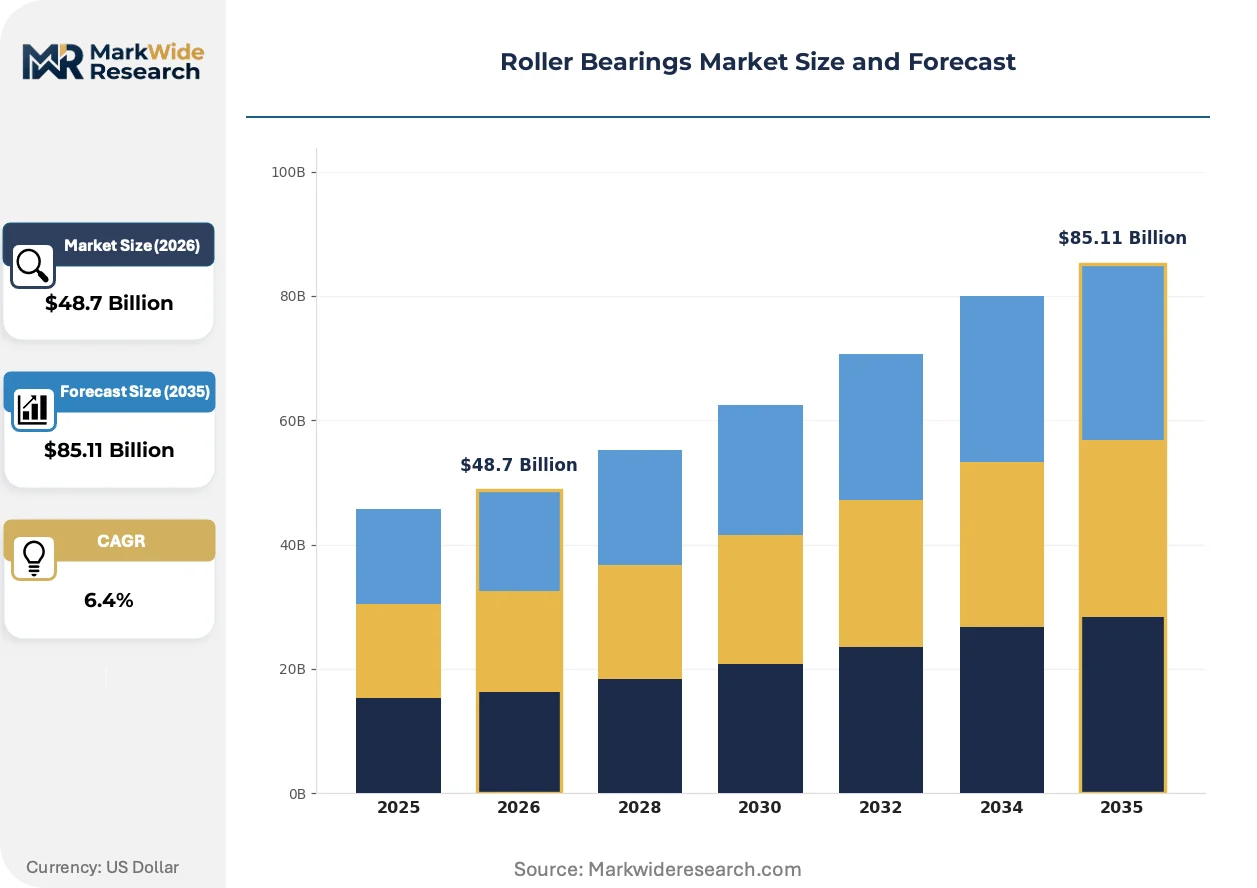
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $85.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Cylindrical Roller, Spherical Roller, Tapered Roller, Needle Roller, Thrust Roller Material: Chrome Steel, Stainless Steel, Ceramic, Plastic, Brass Application: Wind Turbines, Railway Equipment, Aerospace Systems, Machine Tools, Agricultural Equipment End User Industry: Energy Generation, Transportation, Aviation, Manufacturing, Farming |
| Companies Covered | The Timken Company, JTEKT Corporation, SKF AB, RBC Bearings Incorporated, Nachi-Fujikoshi Corp., Schaeffler Technologies AG & Co. KG, NTN Bearing Corporation, Wafangdian Bearing Group, NSK Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roller Bearings Market Strategic Shifts & Innovations
The market's trajectory is defined by a decisive shift toward application-specific performance and integrated systems over commoditized components. This evolution is driven by end-user demands for greater operational efficiency, extended asset life, and data-driven maintenance strategies in critical machinery.
Advanced material science, particularly the use of hybrid ceramic-steel compositions and proprietary alloys, delivers superior performance under extreme heat, speed, and load conditions. Aerospace and electric vehicle manufacturers are the primary adopters, seeking components that reduce friction and extend service intervals. This trend is bifurcating the competitive landscape into a segment for high-value, engineered solutions and another for mass-produced, standard industrial bearings.
Regulatory frameworks focused on sustainability are directly influencing bearing design and material selection. The EU Green Deal, for instance, promotes renewable energy sources, thereby increasing the technical requirements for components like wind turbine bearings to ensure longevity and reliability. This affects the wind energy segment most acutely, compelling manufacturers to validate longer service life through rigorous testing and advanced material engineering.
A fundamental shift in purchasing behavior sees end-users acquiring bearings as part of integrated condition monitoring and service packages. This model moves away from traditional transactional sales through distributors, favoring suppliers that offer embedded sensors and predictive analytics. The change is most prominent in capital-intensive industries like mining and paper production, where preventing unplanned equipment downtime is a primary operational goal.
Roller Bearings Market Segmentation
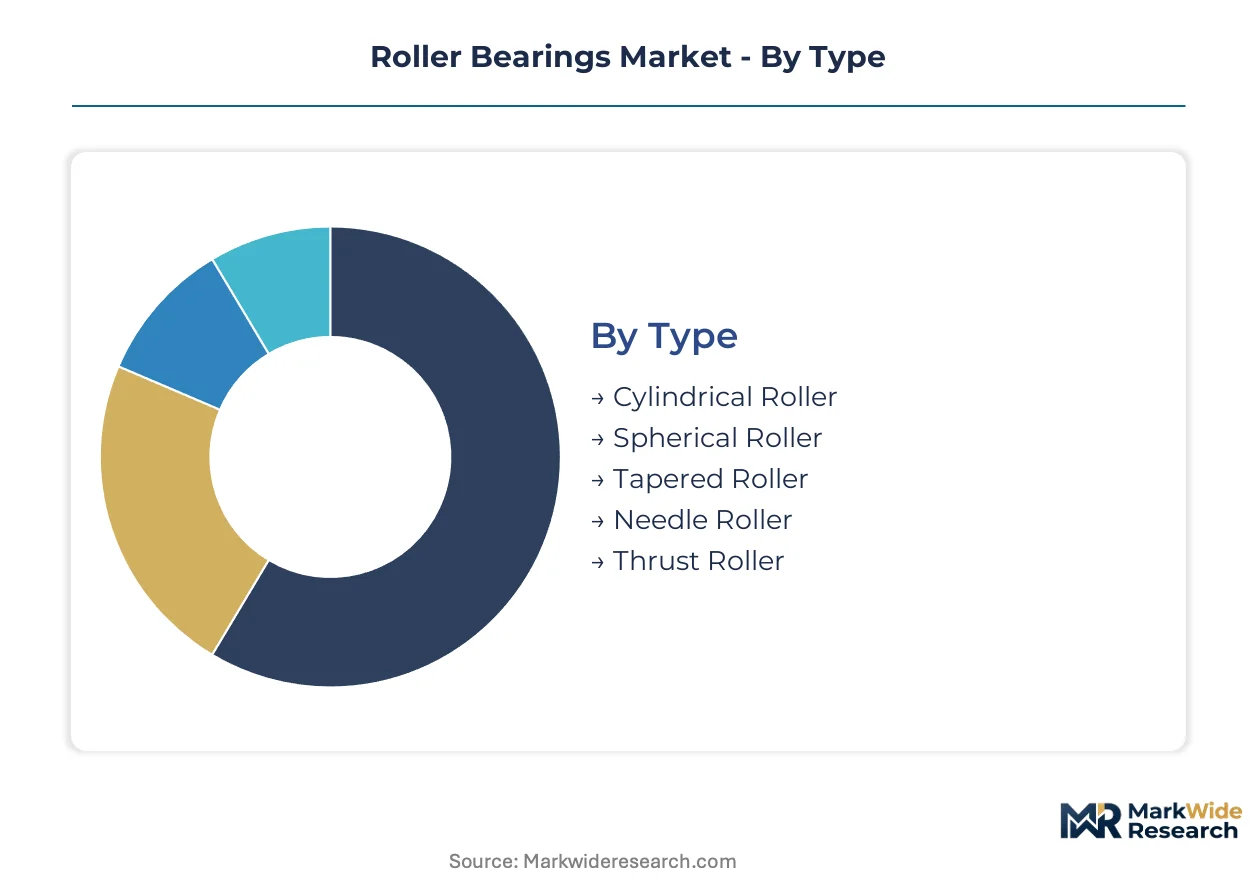
Understanding the segmentation of the roller bearings market is critical for stakeholders to align product development and market strategies with evolving industry demands. This granular analysis reveals where innovation is concentrated and which segments are experiencing the most dynamic shifts in demand.
Type:
Regulatory frameworks like the EU Green Deal are influencing the design and selection of roller bearing types, particularly for high-stress applications in renewable energy.
- Cylindrical Roller:These bearings feature cylindrical rollers, offering high radial load capacity and suitability for high-speed applications due to their line contact with raceways.
- Spherical Roller:Spherical roller bearings feature two rows of symmetrical rollers, a common spherical outer ring raceway, and two inner ring raceways inclined at an angle to the bearing axis. Demand for these self-aligning components is concentrating in wind turbines, driven by renewable energy mandates requiring long operational lifecycles.
- Tapered Roller:Tapered roller bearings incorporate conical rollers and raceways arranged so that the roller axes and raceway axes converge at a common point on the bearing axis. Heavy-duty applications like railway equipment and commercial vehicles in China concentrate demand for their combined radial and axial load handling capabilities.
- Needle Roller:Needle roller bearings utilize small diameter cylindrical rollers, providing high load capacity within a compact cross-section.
- Thrust Roller:Thrust roller bearings are designed to handle axial loads, often found in applications requiring high axial rigidity.
Cylindrical roller bearings handle the majority of throughput; spherical roller bearings are the fastest mover on share.
Material:
Material selection for roller bearings often reflects a trade-off between cost-efficiency and performance under extreme conditions.
- Chrome Steel:Chrome steel bearings are the industry standard, offering a balance of hardness, wear resistance, and cost-effectiveness for general industrial applications. Mass production lines in manufacturing facilities across Southeast Asia drive significant demand for these robust components.
- Stainless Steel:Stainless steel bearings provide corrosion resistance, making them suitable for environments with moisture or chemical exposure.
- Ceramic:Ceramic bearings utilize silicon nitride or zirconium oxide rolling elements for superior hardness, high-temperature resistance, and corrosion immunity. Aerospace systems and electric vehicle drivetrains are concentrating demand for their lightweight and high-speed capabilities.
- Plastic:Plastic bearings offer lightweight, non-magnetic, and corrosion-resistant properties for specific low-load, low-speed applications.
- Brass:Brass is primarily used for bearing cages due to its good machinability and low friction characteristics.
Chrome steel remains the foundational material for most industrial applications; ceramic materials are experiencing the most rapid expansion in high-performance niches.
Application:
The specific application environment dictates the precise design and performance requirements for roller bearings.
- Wind Turbines:Wind turbine applications require large-diameter spherical and tapered roller bearings capable of enduring immense loads and harsh environmental conditions. The EU Green Deal accelerates demand for these components, ensuring long-term reliability in renewable energy infrastructure.
- Railway Equipment:Railway equipment utilizes robust roller bearings for axles and gearboxes, demanding high reliability and resistance to heavy shock loads.
- Aerospace Systems:Aerospace systems require high-precision, lightweight bearings capable of operating under extreme temperatures and speeds with stringent safety standards.
- Machine Tools:Machine tool applications demand high-precision, stiff bearings to ensure accuracy and repeatability in manufacturing processes.
- Electric Vehicles:Electric vehicle drivetrains demand specialized bearings that operate reliably at higher speeds and temperatures compared to traditional internal combustion engines. The shift to e-mobility creates demand for low-friction, high-durability solutions within these advanced systems.
- Agricultural Equipment:Agricultural equipment uses durable bearings designed to withstand harsh outdoor conditions, dust, and heavy loads.
Industrial machinery applications consistently consume the largest volume of roller bearings; electric vehicle integration represents the steepest expansion trajectory.
End User Industry:
End-user industries define distinct operational environments and performance expectations for roller bearing integration.
- Energy Generation:The energy generation sector, particularly wind and hydropower, relies on robust roller bearings for turbines and generators to ensure continuous operation. Renewable energy mandates in Europe and Asia are driving demand for high-capacity, long-lifecycle components.
- Transportation:The transportation industry, encompassing rail, automotive, and commercial vehicles, requires durable bearings for axles, transmissions, and engine components. Industrial modernization initiatives in China significantly influence demand for heavy-duty transportation bearings.
- Aviation:The aviation industry demands ultra-reliable, high-performance bearings for aircraft engines, landing gear, and control systems.
- Manufacturing:The manufacturing sector uses roller bearings extensively in production machinery, robotics, and automation equipment.
- Farming:Farming equipment utilizes specialized bearings designed to operate reliably in challenging agricultural environments.
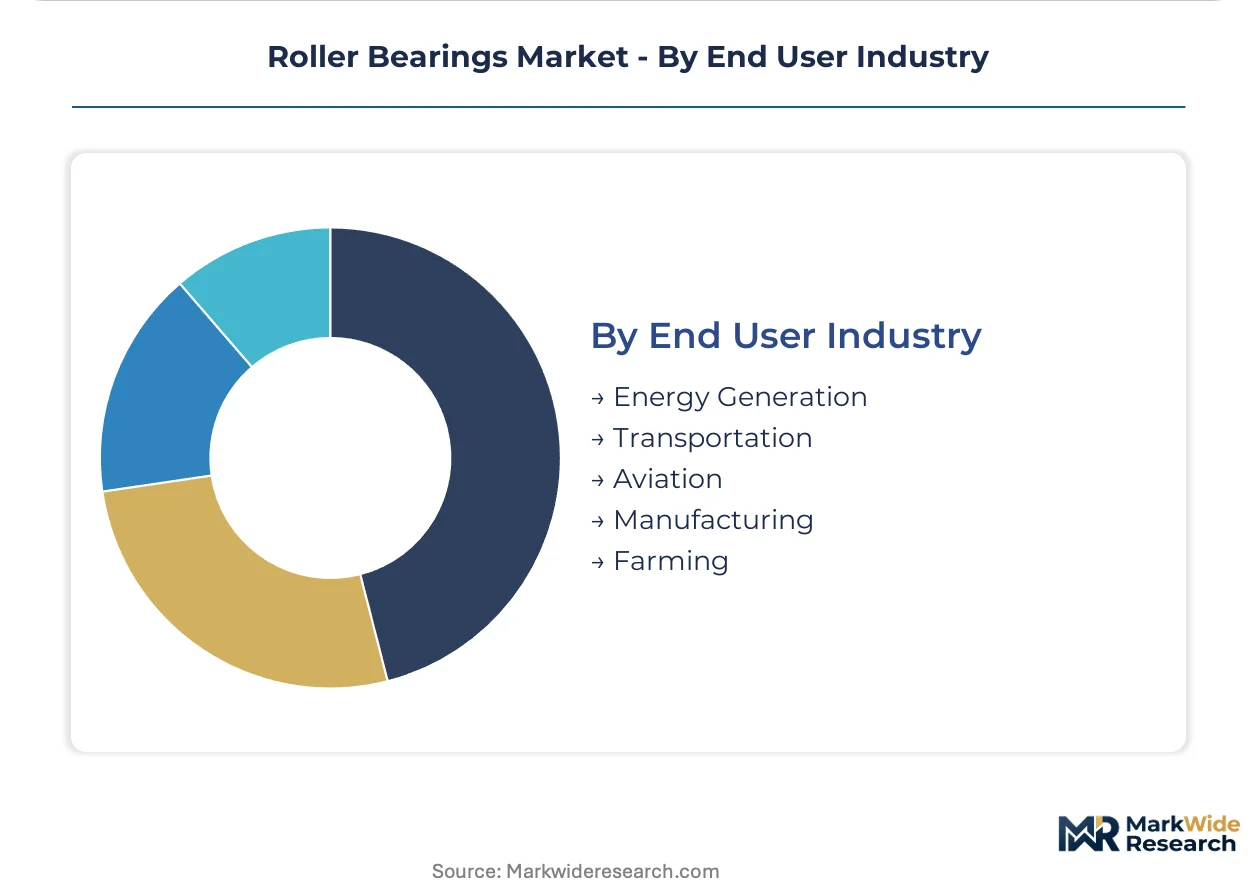
The manufacturing sector accounts for the largest installed base of roller bearings; energy generation is exhibiting the fastest growth in component demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The roller bearings market exhibits varying demand elasticity across global regions. Buyers in established industrial economies often prioritize specialized performance and long lifecycles, while emerging markets frequently focus on cost-efficiency and volume. This divergence influences capital allocation and product development strategies for manufacturers worldwide.
China
China's industrial modernization and extensive energy infrastructure projects drive significant demand for roller bearings. The nation's dual carbon goals accelerate investment in renewable energy, requiring high-capacity components for wind turbines. Manufacturing hubs in the Yangtze River Delta concentrate production and consumption of heavy-duty bearings.
Germany
German automotive manufacturing and high-precision machine tools create consistent demand for advanced roller bearings. The EU Green Deal and RoHS directive influence material selection, pushing manufacturers toward compliant alloys. Industrial clusters in Bavaria focus on developing and integrating specialized bearings for e-mobility systems.
United States
The United States aerospace sector and heavy industrial machinery applications generate substantial demand for high-performance roller bearings. The Inflation Reduction Act (IRA) supports domestic manufacturing and clean energy projects. Manufacturing centers across the Midwest concentrate on producing robust bearings for agricultural equipment and power generation.
India
India's rapid infrastructure development and expanding automotive production are significant drivers for roller bearing consumption. The PLI scheme encourages domestic manufacturing, stimulating local production of industrial components. Industrial zones in Maharashtra serve as key hubs for both bearing manufacturing and end-use in diverse machinery.
Japan
Japan's precision engineering and advanced robotics industries require high-accuracy and compact roller bearings. Adherence to JIS standards ensures quality and interchangeability for components in critical applications. The Kanto region hosts numerous research centers focused on next-generation bearing technologies for automation and high-speed systems.
Roller Bearings Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the roller bearings market. The industry exhibits a tiered structure, with a few large global players dominating high-performance segments and numerous regional manufacturers competing on volume and price. Strategic archetypes include specialized material science innovators, integrated service providers, and mass-production efficiency leaders. Companies primarily engage in strategic partnerships and capacity expansion to secure market share across varied applications.
Specialized material science innovators like Germany-based Schaeffler Technologies AG & Co. KG exemplify high-performance engineering for demanding applications. In contrast, Japan-based JTEKT Corporation occupies a position as a manufacturing scale and cost-efficiency leader, particularly for the high-volume automotive sector. Sweden-based SKF AB represents an integrated service provider, leveraging its extensive global distribution network and advanced condition monitoring services to serve diverse industrial end-users effectively.
| Leading Market Players |
|---|
| The Timken Company |
| JTEKT Corporation |
| SKF AB |
| RBC Bearings Incorporated |
| Nachi-Fujikoshi Corp. |
| Schaeffler Technologies AG & Co. KG |
| NTN Bearing Corporation |
| Wafangdian Bearing Group |
| NSK Ltd. |
| Others |
Cost & Logistics Intelligence
Days-of-inventory for high-performance ceramic bearings remain strategically high, reflecting the specialized manufacturing processes and long lead times, which in turn grants pricing power to technology leaders. This contrasts with the more commoditized chrome steel segments.
Pricing Analysis
After-sales service and condition monitoring services drive significant lifetime value for bearing manufacturers. Pricing for roller bearings often follows a contract-based long-term offtake model for major OEMs. Price differentiation stems from material science innovation, particularly for ceramic and specialty alloy components, and from adherence to critical ISO certification levels. Input material volatility for chrome steel creates pricing pressure in mass-market segments. Buyers in the aerospace and electric vehicle sectors exhibit lower price sensitivity compared to high-volume industrial machinery operators.
Supply Chain Analysis
Just-in-time inventory strategies are common for standard components, while specialized bearings require strategic stockpiles due to complex production. Geographic supply concentration for roller bearings centers on manufacturing hubs in China and Germany for diverse applications, alongside Japan for precision components. The industry draws from high-purity chrome steel, specialty alloys, and ceramic materials as key inputs. Supply chain risk primarily involves commodity price volatility for these raw materials, impacting cost structures. Distribution runs through extensive global networks for standard bearings, complemented by direct sales channels for specialized, high-performance solutions to OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The roller bearings market is in a cyclical recovery, driven by renewed investments in global industrial modernization and energy infrastructure projects. This resurgence creates opportunities across the value chain.
For Market Incumbents: Compound investment in material science R&D to develop next-generation alloys and ceramic composites. This strategy helps mitigate the threat from alternative technologies like magnetic bearings in niche applications. Consolidate market share by acquiring smaller specialized technology firms or expanding capacity in high-growth regions like Southeast Asia. Focus on enhancing existing global distribution networks to maintain channel control against emerging entrants.
For New Entrants and Emerging Players: Certification fast-track programs, particularly for environmental compliance like RoHS, offer a pathway into European markets. Target underpenetrated industrialization in Southeast Asia, focusing on compact, high-precision roller bearings for smart factory automation and AGVs. A go-to-market angle integrating IoT sensors for predictive maintenance presents a significant value-add opportunity. Focus on cost-efficient manufacturing for standard industrial bearings to compete on volume.
For Investors and Strategic Acquirers: Long-term, this sits as a foundational component play because roller bearings are indispensable across virtually all industrial and mobility applications. Seek acquisition targets among specialized material science innovators or integrated service providers offering robust condition monitoring platforms. The signal to watch is the sustained acceleration of electric vehicle production volumes and renewable energy project deployments, indicating continued high-performance demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Meets concentrated demand from China's industrial modernization and Southeast Asia's manufacturing growth. |
| Material Science R&D Investment | Develops high-performance alloys and ceramic composites for aerospace and e-mobility applications. |
| Strategic Partnerships for IoT Integration | Embeds smart bearing sensor technology with predictive maintenance platforms for end-user value. |
| Vertical Integration into Specialty Alloys | Secures supply of high-purity chrome steel and advanced materials, reducing input volatility. |
| Certification for Green Technologies | Ensures compliance with regulations like the EU Green Deal for wind turbine and EV components. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to triangulate market dynamics and validate quantitative models. Primary interviews included manufacturing plant managers, automotive engineers, wind turbine operators, and material scientists across key geographies. This primary research was cross-referenced with extensive secondary data from ISO standards documents, EU Green Deal policy papers, and national industrial statistics from China and the United States. A bottom-up and top-down approach ensured comprehensive market sizing.
The forecasting horizon extends across the analysis window, integrating quantitative models with qualitative insights. Segmentation dimensions modeled include bearing type, material, application, end-user industry, and regional economic growth trajectories. Compound annual growth rates were derived from historical performance and projected growth drivers, such as renewable energy investment trends and electric vehicle production forecasts. This framework accounts for market shifts driven by technological advancements.
Decision-makers should treat outputs as directional under current macroeconomic and regulatory assumptions; material deviation would warrant model refresh. Forecasts reflect these base assumptions, acknowledging that input material price volatility or geopolitical trade policies could significantly alter projections. Revision becomes warranted when key market conditions cross predefined thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Laboratory Vacuum Pumps Market
Industrial Equipment
CNC Tool Storage System Market
Industrial Equipment
Laser Marking Equipment Market
Industrial Equipment
Fiber Laser Coding System Market
Industrial Equipment
Dry Block Heaters Market
Industrial Equipment
Machine Tool Cooling System Market
Industrial Equipment
Magnetizing Equipment Market
Industrial Equipment
Global Flat Glass Tempering Machines Market
Industrial Equipment
Rotary Scroll Air Compressor Market
Industrial Equipment
Refrigeration Coolers Market
Industrial Equipment
Linear Motion (LM) Shaft Market
Industrial Equipment
Microwave Equipment Market
Industrial Equipment
Global Dicing Blades Market
Industrial Equipment
Magnetorheological Finishing (MRF) Machine Market
Industrial Equipment
Japan Ceramic Roller Bearings Market
Industrial Equipment
Above 300mm Cooling Fans Market