
 Magnetorheological Finishing (MRF) Machine Market | 2026-2036
Magnetorheological Finishing (MRF) Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetorheological Finishing (MRF) Machine Market Insights
Market Context
Software-defined process control is pivoting how MRF machine vendors monetize their installed base, shifting revenue from hardware sales toward recurring calibration and adaptive algorithm subscriptions. QED Technologies leverages its metrology heritage to bundle interferometric feedback loops with finishing contracts. Moore Nanotechnology Systems anchors North American demand through ultra-precision spindle integration that shortens setup cycles for freeform optics.
Technical Definition and Segments
Magnetorheological Finishing is a deterministic polishing process where a magnetically responsive fluid containing abrasive ferrous particles conforms to optical surfaces under controlled magnetic fields, achieving sub-nanometer surface roughness on aspheric and freeform substrates. CNC Finisher configurations command the premium tier due to five-axis correction capability for complex geometries, while Digital MRF is displacing conventional setups through real-time removal function adaptation. The Optics application segment dominates current volume, though Precision Machining for semiconductor wafer flattening represents the fastest margin expansion pool as node sizes shrink.
Regulatory and Forward Outlook
German KBA certification requirements for automotive LiDAR optics and FDA device-quality standards for medical imaging lenses shape MRF equipment specifications across export markets. China's GB standards for precision machine tools and REACH compliance for ferrofluid chemical constituents further constrain material sourcing and fluid disposal protocols. Stakeholders must monitor how EU AI Act documentation rules for autonomous process control will affect Digital MRF validation costs and time-to-market.
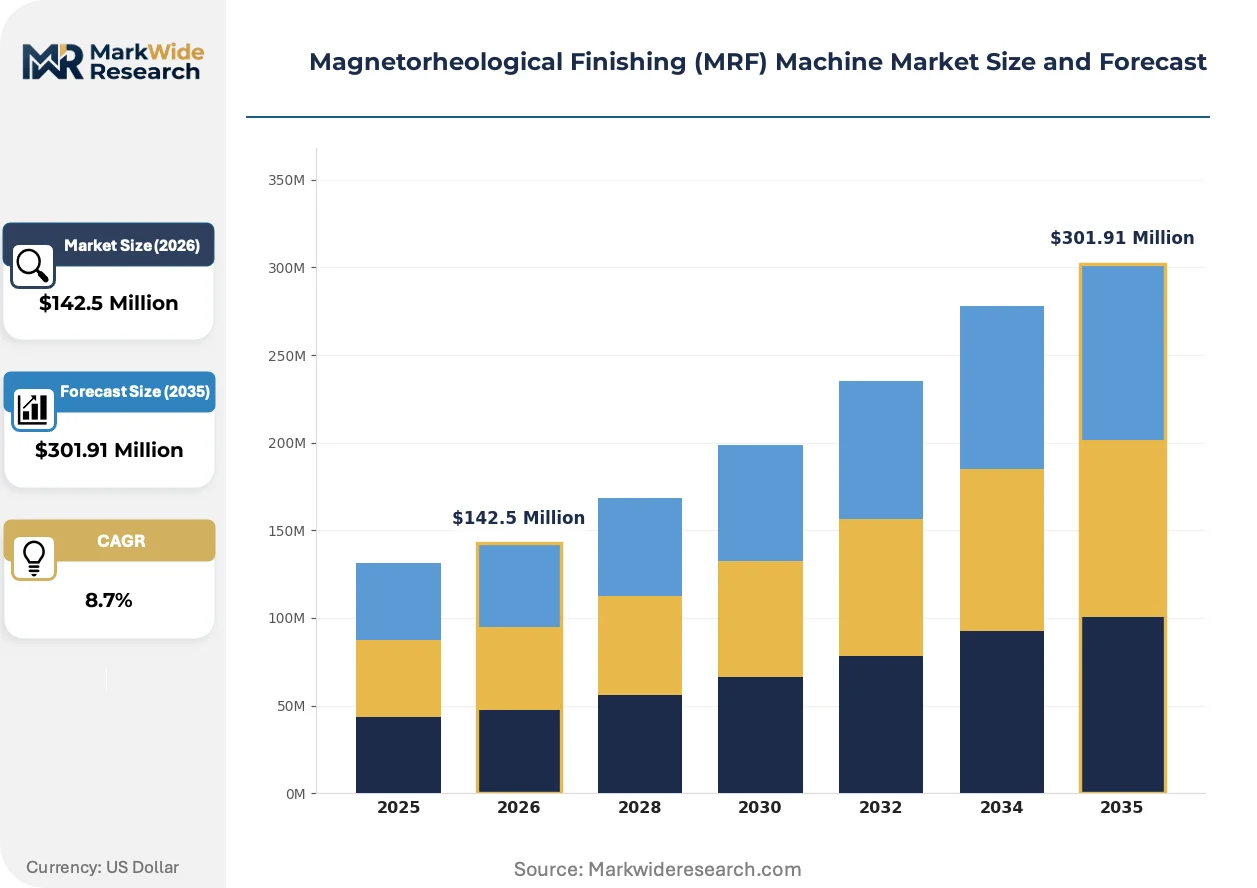
Market Dynamics
Software-defined process control is compressing hardware margins while expanding recurring revenue pools through algorithmic calibration subscriptions, fundamentally restructuring how MRF vendors capture value from their installed base.
Growth Catalysts
- Semiconductor node shrinkage:Sub-7nm lithography requirements for EUV mask blanks and wafer flatness specifications are pulling precision finishing demand from fabs in Taiwan and South Korea.
- REACH compliance protocols:ECHA restrictions on conventional polishing slurry chemistries are redirecting European optics manufacturers toward closed-loop ferrofluid systems with certified disposal chains.
- Freeform optics proliferation:Automotive LiDAR and AR/VR headset designs require non-rotationally symmetric surfaces that deterministic MRF correction uniquely enables.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium sourcing dependencies on Chinese processing facilities create input cost volatility and geopolitical exposure.
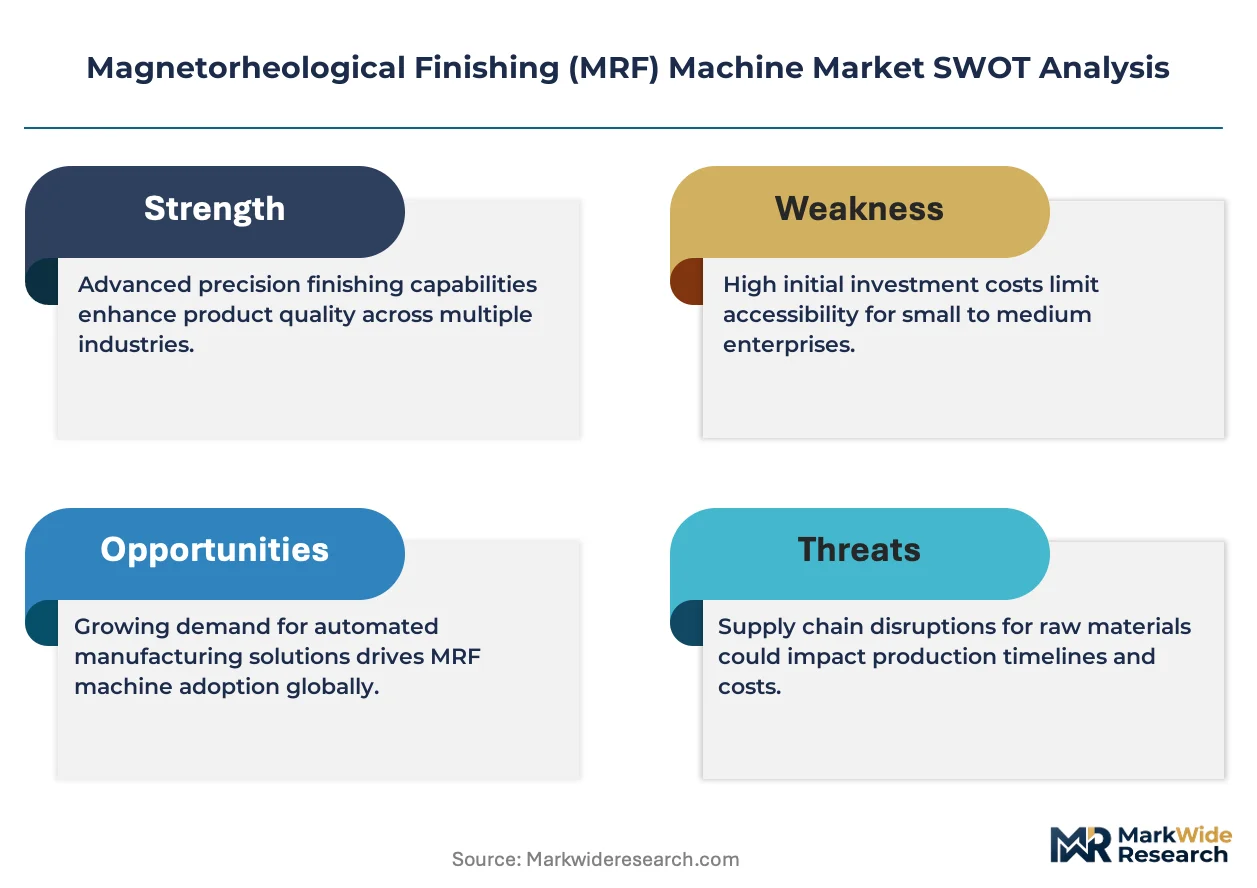
- Capital intensity barriers:Five-axis CNC MRF platforms require seven-figure equipment outlays that constrain adoption among mid-tier optical job shops.
- Ferrofluid disposal friction:EPA hazardous waste classifications for spent magnetorheological fluids in the United States impose compliance costs exceeding conventional slurry management by 40-60%.
Strategic Opportunities
- India precision manufacturing:PLI scheme incentives for semiconductor and defense optics are creating first-mover advantage windows for MRF service bureau establishment in Bangalore and Hyderabad clusters.
- Digital twin integration:Convergence of MRF removal function modeling with predictive metrology is enabling remote process optimization contracts that decouple revenue from physical machine shipments.
- EU AI Act documentation:Autonomous process control validation requirements are creating premium service tiers for algorithm audit trails and explainability packages.
Industry Challenges
- Interferometric metrology talent scarcity:Sub-nanometer surface characterization expertise resides in aging workforce pools across German and Japanese optical clusters.
- Legacy CNC retrofit complexity:Three-axis MRF installations require mechanical and control architecture overhauls to accommodate real-time adaptive correction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetorheological Finishing (MRF) Machine Market |
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $301.91 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Angle Polisher, Surface Grinder, Smart Polisher, CNC Finisher End User: Aerospace, Automotive OEMs, Electronics, Medical Devices Technology: Conventional MRF, Hybrid MRF, Digital MRF, Automated MRF Application: Optics, Precision Machining, Surface Treatment, Metal Forming |
| Companies Covered | Moore Nanotechnology Systems, Yuhuan CNC Machine Tool, QED Technologies, NBST, ZR Optics, Schneider Optical Machines, AMETEK Precitech, Changsha AFiSy Technology, Satisloh AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetorheological Finishing (MRF) Machine Market Trends and Innovations
Deterministic polishing is shedding its hardware-centric legacy as computational process models and service-based monetization architectures redefine competitive advantage in precision surface finishing.
Real-time removal function adaptation is converging with embedded interferometric feedback loops to enable autonomous correction cycles without operator intervention. Aerospace optics manufacturers in Germany and the United States are piloting these closed-loop configurations for aspheric mirror production. This convergence is compressing setup-to-delivery timelines from weeks to days while reducing skilled labor dependencies.
EU AI Act documentation requirements for autonomous manufacturing systems are mandating algorithmic audit trails and explainability protocols for Digital MRF platforms. Equipment vendors must now maintain version-controlled model repositories and decision-logging infrastructure. German LiDAR optics suppliers and French medical imaging lens manufacturers face the steepest compliance cost increases.
After-sales service unbundling is fragmenting traditional bundled maintenance contracts into discrete calibration, algorithm update, and consumable subscription tiers. Precision optics job shops in Japan and South Korea are resisting long-term service lock-ins. Equipment vendors are responding with usage-based pricing models tied to finished surface area rather than machine availability hours.
Magnetorheological Finishing (MRF) Machine Market Segmentation
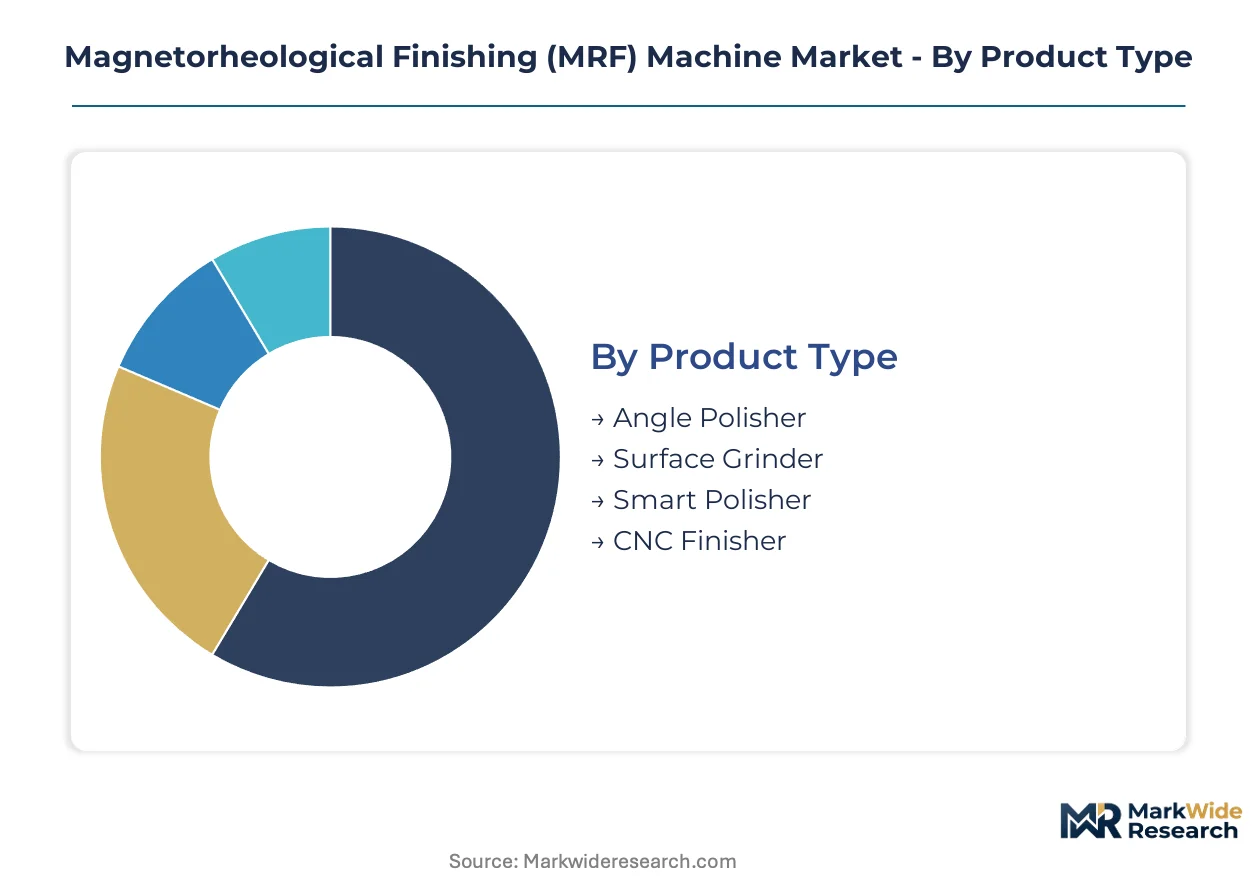
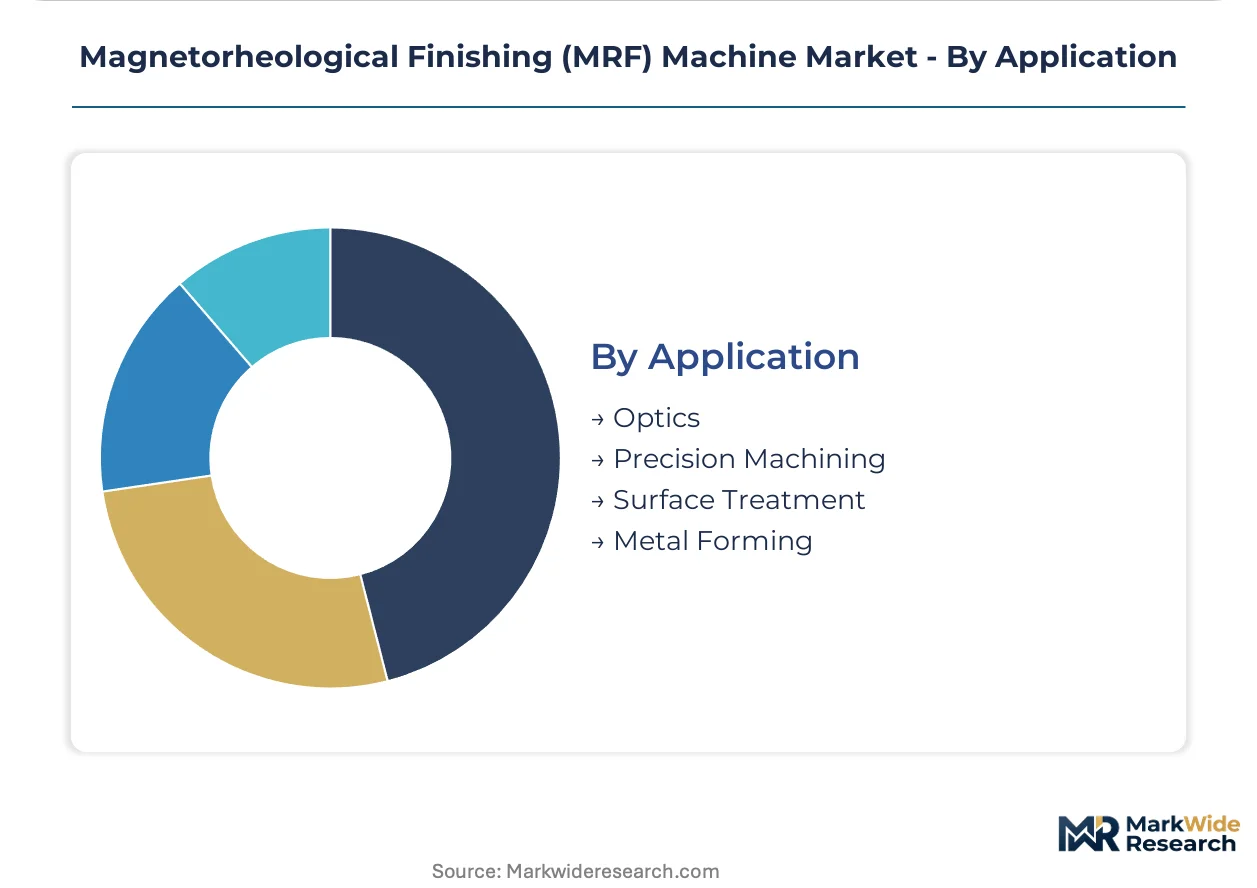
Segmentation in the MRF machine market reveals how capital deployment, technical complexity, and end-use certification requirements fragment procurement patterns across precision manufacturing verticals. Equipment specifications diverge sharply between job-shop service providers and captive fab operations.
Product Type:
Capital intensity escalates dramatically with axis complexity and software integration depth, creating tiered entry barriers that stratify the vendor landscape.
- CNC Finisher:Five-axis motion platforms with real-time magnetic field modulation command the highest upfront investment. Aerospace mirror manufacturers in Germany and the United States absorb these outlays for aspheric correction contracts where nanometer-level figure accuracy is mandatory.
- Smart Polisher:Embedded interferometric feedback loops and adaptive removal function algorithms reduce operator dependency. Electronics fabs in Taiwan and South Korea concentrate procurement here for EUV mask blank finishing where throughput consistency outweighs absolute flexibility.
- Angle Polisher:Specialized configurations for off-axis aspheric substrates with limited five-axis capability. Medical device lens suppliers in Switzerland deploy these for moderate-complexity geometries.
- Surface Grinder:Entry-level platforms for planarization tasks with fixed magnetic field geometries. Mid-tier optical job shops in India and Southeast Asia favor these for cost-containment.
CNC Finisher absorbs the bulk of installed capacity; Smart Polisher is expanding most quickly.
End User:
Certification stringency and volume scale create divergent purchasing logics across verticals, with automotive and medical applications imposing the most demanding validation protocols.
- Electronics:Semiconductor fabs and display panel manufacturers drive volume demand for wafer planarization and photomask finishing. Sub-7nm lithography roadmaps in Taiwan and South Korea pull precision specifications tighter.
- Medical Devices:FDA device-quality standards and ISO 13485 compliance requirements shape equipment specifications. German and French imaging lens manufacturers prioritize traceability and process documentation.
- Aerospace:Satellite mirror and telescope optic production with extreme stability requirements. NASA and ESA contractor facilities in the United States and Germany anchor demand.
- Automotive OEMs:LiDAR lens and head-up display component finishing with emerging KBA certification requirements for autonomous vehicle optics. German tier-one suppliers are expanding captive finishing capacity.
Electronics captures the largest share of annual shipments; Medical Devices is climbing the fastest as imaging modality miniaturization accelerates.
Technology:
Software-defined architectures are displacing hardware-centric platforms, restructuring how vendors monetize through recurring algorithm subscriptions rather than one-time equipment sales.
- Digital MRF:Real-time removal function adaptation with predictive metrology integration and autonomous correction cycles. EU AI Act documentation requirements for algorithm audit trails are raising validation costs for German and French adopters.
- Automated MRF:Robotic workpiece handling with limited adaptive capability but reduced labor dependency. Japanese precision optics job shops favor these for high-mix, low-volume production.
- Hybrid MRF:Combines deterministic polishing with conventional mechanical finishing for roughness reduction. Chinese domestic equipment vendors are developing these for cost-sensitive applications.
- Conventional MRF:Fixed-parameter operation with operator-driven process adjustment. Legacy installations in North American and European job shops face retrofit pressure.
Conventional MRF retains the largest installed base; Digital MRF is gaining share fastest as closed-loop control becomes standard for high-value optics.
Application:
Surface specification tolerances and substrate material diversity determine equipment configuration requirements, with optics commanding premium pricing and precision machining expanding through semiconductor demand.
- Optics:Aspheric and freeform lens and mirror finishing for imaging, laser, and photonics systems. German optical clusters around Jena and Upper Franconia concentrate demand for sub-nanometer roughness achievement.
- Precision Machining:Semiconductor wafer flattening, EUV mask blank preparation, and ceramic component finishing. Taiwan and South Korea fabs are pulling equipment specifications toward atomic-scale removal control.
- Surface Treatment:Functional surface modification for tribological or corrosion resistance properties. Aerospace component suppliers in the United States deploy these for mission-critical hardware.
- Metal Forming:Die and mold surface finishing with moderate precision requirements. General manufacturing applications in China and India dominate this tier.
Optics commands the steepest pricing and deepest technical integration; Precision Machining is expanding most quickly as node shrinkage accelerates finishing intensity per wafer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in German precision engineering clusters while consumption spreads across semiconductor fabrication centers in East Asia and aerospace optics facilities in North America.
Germany
Automotive LiDAR lens finishing and satellite mirror production drive equipment demand from Zeiss and Leica supply chains. KBA certification requirements for autonomous vehicle optics mandate traceable process documentation. The Jena and Upper Franconia optical clusters anchor European MRF machine deployment for sub-nanometer surface specifications.
United States
NASA and ESA contractor facilities sustain demand for extreme stability telescope optics and aerospace mirror finishing. EPA hazardous waste classifications for spent ferrofluids impose compliance costs exceeding conventional slurry management. Greater Rochester and Tucson optics corridors concentrate precision finishing capacity for defense and scientific instrumentation.
China
Domestic semiconductor equipment capability initiatives redirect procurement toward locally certified MRF platforms for EUV mask blank development. MIIT push for precision machine tool autonomy shapes GB standards compliance requirements. Shanghai and Hefei fabrication clusters are expanding captive finishing capacity for advanced lithography nodes.
South Korea
Sub-7nm lithography roadmaps at Samsung and SK Hynix pull precision wafer flatness specifications toward atomic-scale removal control. MFDS-equivalent process validation standards for semiconductor equipment shape procurement criteria. The Suwon and Pyeongtaek fab complexes concentrate demand for high-throughput deterministic polishing systems.
India
PLI scheme incentives for semiconductor and defense optics create first-mover advantage windows for MRF service bureau establishment. BIS precision machine tool standards and DGFT import substitution policies redirect capital toward domestic platforms. Bangalore and Hyderabad manufacturing clusters are attracting precision optics job shop investment.
Magnetorheological Finishing (MRF) Machine Market Competitive Landscape
Top-tier vendors anchor premium five-axis CNC configurations, while mid-tier specialists compete on regional service proximity and retrofit capability. The vendor base stratifies across integrated metrology-finishing bundlers, pure-play equipment fabricators, and emerging digital process control developers. Two dominant competitive moves are reshaping positioning: algorithmic service unbundling into subscription tiers, and strategic partnerships between MRF equipment vendors and interferometric metrology providers.
Among North American precision equipment developers, Moore Nanotechnology Systems and QED Technologies exemplify the integrated metrology-finishing archetype. Chinese fabricators including Yuhuan CNC Machine Tool and Changsha AFiSy Technology occupy positions within the cost-optimized equipment tier. European specialists Schneider Optical Machines and Satisloh AG represent the precision optics heritage segment. AMETEK Precitech and NBST sit within the diversified industrial technology conglomerate structure, while ZR Optics exemplifies regional specialist positioning.
| Leading Market Players |
|---|
| Moore Nanotechnology Systems |
| Yuhuan CNC Machine Tool |
| QED Technologies |
| NBST |
| ZR Optics |
| Schneider Optical Machines |
| AMETEK Precitech |
| Changsha AFiSy Technology |
| Satisloh AG |
| Others |
Pricing and Supply Chain Analysis
Neodymium oxide price volatility cascades through MRF machine manufacturing, compressing margins on five-axis CNC platforms while amplifying cost-down pressure on entry-level surface grinders. Equipment vendors absorb magnet sourcing premiums in premium tiers but pass through volatility to mid-market buyers.
Pricing Analysis
Margin tightening in mid-tier CNC configurations reflects rare earth magnet cost pass-through from Chinese processing facilities. Pricing stratifies across premium five-axis systems, adaptive Smart Polishers, and economy Surface Grinders based on axis complexity and software integration depth. Cost compression accelerates in the Surface Grinder tier as Indian and Southeast Asian job shops demand stripped-down configurations. Electronics fabs in Taiwan exhibit lowest price sensitivity for Smart Polisher procurement, while Indian precision manufacturing startups drive hardest bargain on entry-level platforms.
Supply Chain Analysis
Dual-sourcing mandates from German automotive LiDAR suppliers and South Korean semiconductor fabs force equipment vendors to qualify secondary magnet suppliers outside China. Neodymium and dysprosium draws from Chinese separation facilities, precision ball screws from Japan, and interferometric sensors from Germany. Single-source vulnerability concentrates in rare earth magnet processing. Distribution runs through direct OEM sales for captive fab installations and regional service bureaus for job-shop markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined monetization is consolidating vendor tiers, forcing pure-play hardware fabricators toward distressed exits as algorithmic service revenue pools concentrate with integrated metrology-finishing bundlers.
For Market Incumbents: Acquire interferometric metrology specialists to close feedback-loop integration gaps against QED Technologies and Moore Nanotechnology Systems. Lock in five-axis CNC capacity at Jena and Upper Franconia optical clusters before EU AI Act validation costs escalate. Certify disposal chains for REACH-compliant ferrofluid recovery to defend service contract renewals. For New Entrants and Emerging Players: Launch via precision manufacturing service bureau models in Bangalore and Hyderabad PLI corridors, avoiding capital-intensive equipment fabrication. Target medical device lens finishing for ISO 13485-compliant job shops in Switzerland and France where certification barriers deter hardware-centric competitors. Lead with Digital MRF remote optimization contracts decoupled from physical machine shipments. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier CNC retrofit specialists in North American optics corridors with aging three-axis installed bases. Five-to-ten year viability hinges on algorithmic audit trail infrastructure for EU AI Act compliance. Watch MFDS-equivalent validation adoption at Samsung and SK Hynix as inflection signal for South Korean market acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Sourcing | Secures neodymium supply chains against Chinese export licensing volatility for five-axis platform production. |
| Digital Twin Platform Launch | Enables remote MRF removal function optimization contracts for Taiwan semiconductor fabs without machine shipment. |
| EU AI Act Validation Certification | Creates algorithm audit trail premium tier for German LiDAR optics suppliers facing autonomous manufacturing compliance. |
| Precision Manufacturing Service Bureau Establishment | Captures PLI scheme incentives in Bangalore and Hyderabad for semiconductor and defense optics finishing. |
| REACH-Compliant Ferrofluid Disposal Chain Partnership | Locks in closed-loop recovery infrastructure for European optics manufacturers facing ECHA slurry chemistry restrictions. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with precision optics manufacturing directors, semiconductor fab equipment procurement managers, MRF aftermarket service heads, and interferometric metrology specialists combined with SEC 10-K disclosures, ECHA REACH registration databases, and MIIT equipment certification rosters. Bottom-up equipment shipment tallies triangulated against top-down precision manufacturing capex allocations across the analysis window.
Reconciliation of vendor shipment reports, fab equipment procurement databases, and optical cluster investment trackers informed the analytical framework. Segmentation dimensions spanned product type, end user vertical, technology architecture, and application substrate across the projection horizon. CAGRs derived from equipment replacement cycles, lithography node transition timelines, and autonomous vehicle LiDAR adoption curves. Rare earth magnet price indices and EU regulatory implementation schedules served as industry-specific forecast modifiers.
Semiconductor node transition delays, REACH enforcement variability, and rare earth export licensing shifts are the dominant revision risks. Deviation in EU AI Act documentation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
United States Fusion Splicer Market
Industrial Equipment
Roller Bearings Market
Industrial Equipment
Global Dicing Blades Market
Industrial Equipment
Global Thick Film Heater Market
Industrial Equipment
Global Servo Presses Market
Industrial Equipment
Laser Marking Market
Industrial Equipment
Coil Winding Machine Market
Industrial Equipment
Precision Dispensing Accessories Market
Industrial Equipment
Vertical Centrifugal Separator Market
Industrial Equipment
North America Industrial Embedded Systems Market
Industrial Equipment
Servo Drive Market
Industrial Equipment
Small Harmonic Reducer Market
Industrial Equipment
Snowrator Market
Industrial Equipment
Floor Scales Market
Industrial Equipment
Spot Curing System Market
Industrial Equipment
Linear Transfer System Market