
 Air Quality Monitoring System Market | 2026-2036
Air Quality Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Air Quality Monitoring System Market Analysis
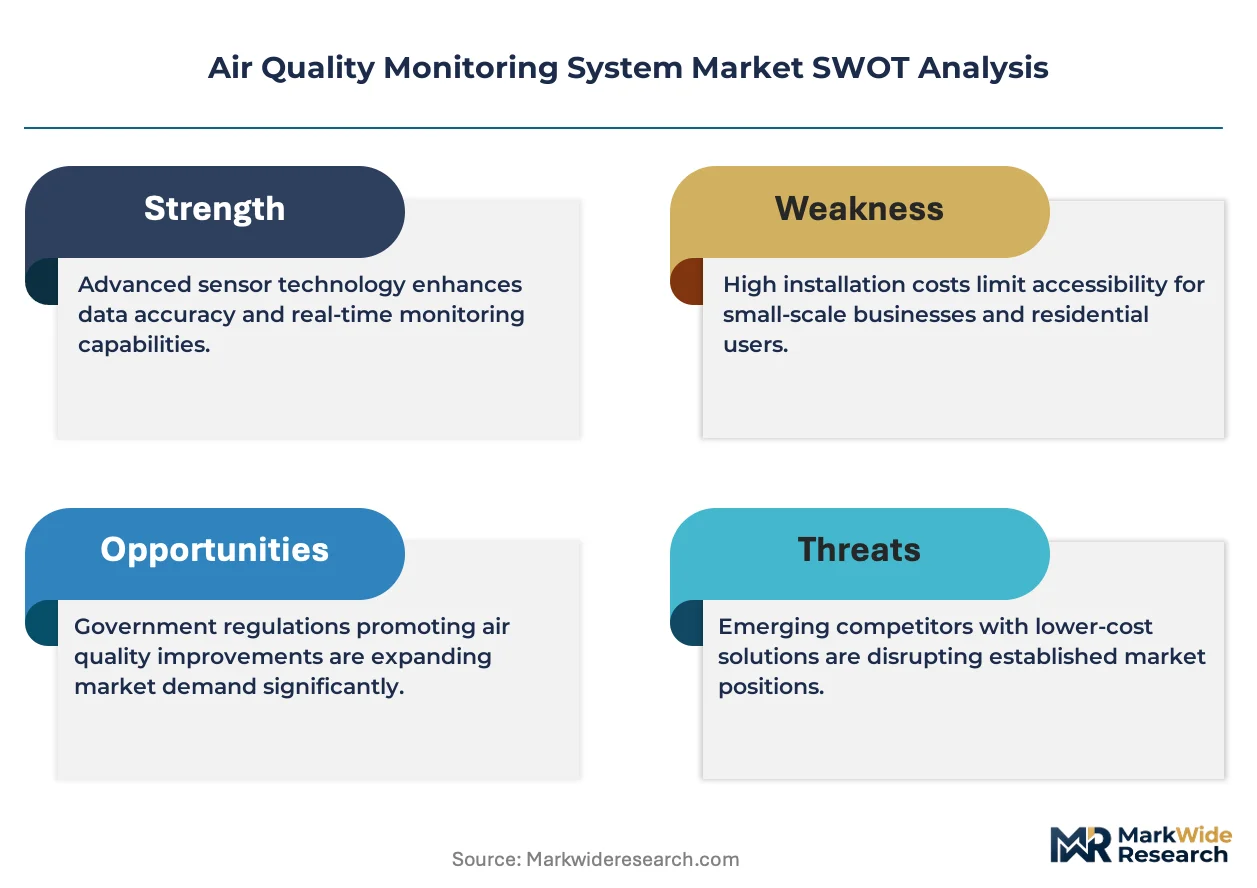
The divergence between premium reference-grade instrumentation and low-cost sensor networks is shifting procurement patterns across the installed base. Thermo Fisher Scientific leverages its analytical instrument heritage to dominate regulatory compliance applications requiring traceable measurement uncertainty. Aeroqual competes on modular hardware architectures that reduce total cost of ownership for dense urban sensor grids. Siemens anchors its position through integration with building management systems and industrial automation protocols.
An air quality monitoring system comprises electrochemical, optical, laser, or infrared sensing elements coupled with data acquisition, communication, and visualization subsystems designed to quantify concentrations of particulate matter, gaseous pollutants, and volatile organic compounds against defined performance criteria. Fixed monitors retain the largest installed base owing to regulatory mandate for continuous emissions and ambient network stations, while portable monitors represent the fastest-expanding category as field audit protocols multiply across industrial and workplace safety applications. Indoor monitors command premium pricing in commercial segments where LEED certification and wellness building standards drive specification.
The EPA enforces National Ambient Air Quality Standards that dictate monitor performance specifications and calibration frequencies for federal reference and equivalent methods. China's MEE mandates real-time data transparency from national air quality monitoring stations, creating demand for systems with tamper-proof data logging and public API connectivity. The EU's Ambient Air Quality Directive and associated EN standards shape product certification requirements across member states. Stakeholders must evaluate how emerging satellite validation requirements and machine learning-based sensor correction protocols will reshape competitive differentiation between hardware manufacturers and analytics platform providers.
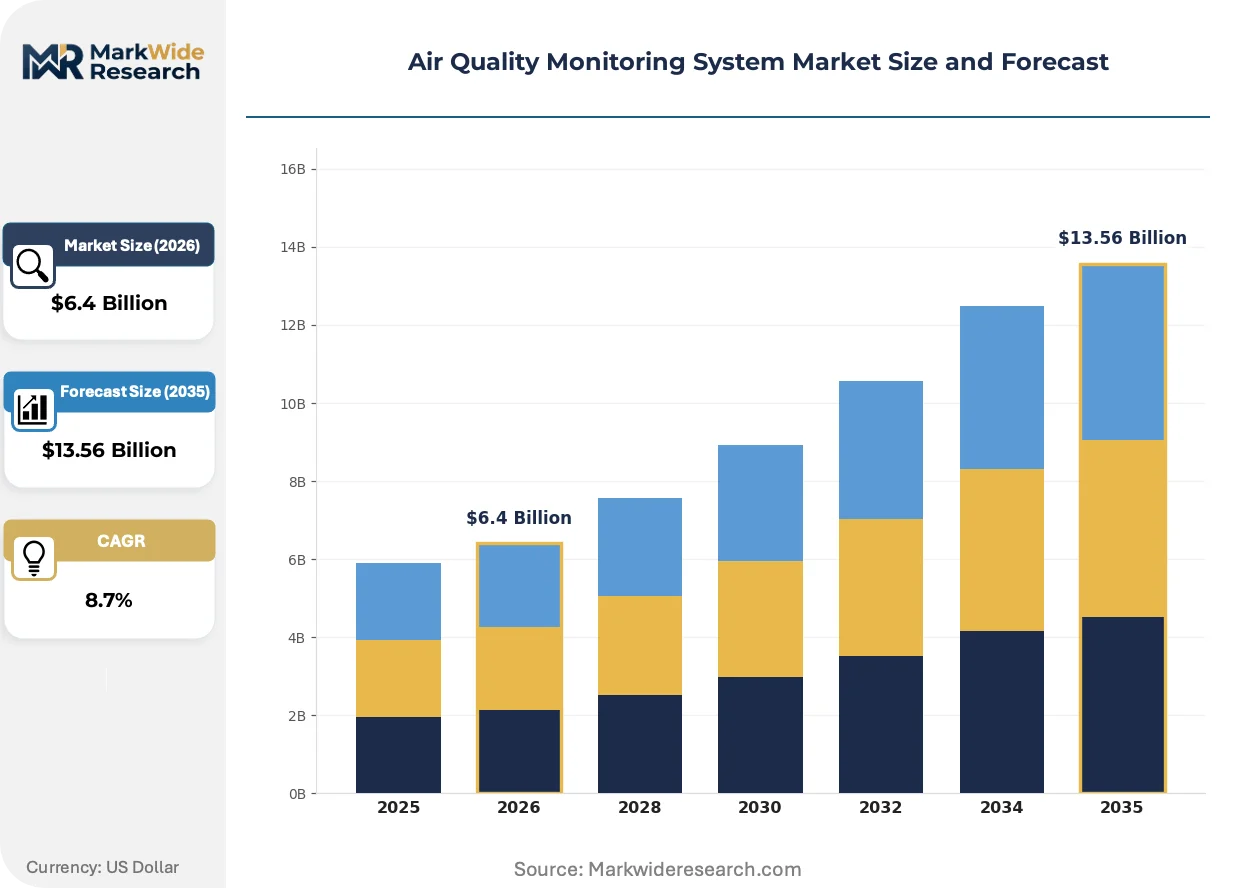
Market Dynamics
The divergence between reference-grade instrumentation and low-cost sensor networks is fragmenting procurement patterns across municipal, industrial, and commercial buyer segments.
Growth Catalysts
- EPA National Ambient Air Quality Standards:Tightened particulate matter thresholds compel continuous emissions monitoring upgrades at power generation and petrochemical facilities across the United States.
- China MEE real-time disclosure mandate:Thousands of urban monitoring stations require tamper-proof data logging and public API connectivity, driving hardware refresh cycles.
- LEED certification protocols:Commercial building developers specify premium indoor monitors to meet wellness building standards and tenant ESG reporting requirements.
Market Restraints
- Reference method sensor cost concentration:Federal equivalent method certification requires traceable optical benches and thermal conditioning modules that concentrate supply among specialized German and Japanese component suppliers.
- Electrochemical cell calibration drift:Six-month recertification cycles for ozone and nitrogen dioxide sensors impose recurring operational expenditure that constrains dense urban deployment economics.
- Satellite validation lag:TROPOMI and GEMS orbital platforms lack ground-truthing density in Sub-Saharan Africa and Central Asia, limiting low-cost sensor network accuracy claims in those markets.
Strategic Opportunities
- India National Clean Air Programme:Non-attainment city mandates create demand for 400+ new continuous ambient monitoring stations with indigenous manufacturing incentives under the PLI scheme.
- Machine learning sensor fusion:Neural network correction algorithms enable electrochemical and optical sensor arrays to achieve reference-grade equivalence at one-tenth hardware cost.
- Workplace safety channel expansion:Industrial hygiene distributors in Brazil and Mexico are adding portable monitor SKUs to capture OSHA-equivalent enforcement expansion in Latin American manufacturing zones.
Industry Challenges
- Embedded firmware cybersecurity certification:IEC 62443 compliance for networked sensor arrays extends product development timelines by eight to fourteen months.
- Field calibration technician scarcity:Zero gas and span gas handling protocols require certified personnel that municipal environmental departments struggle to retain against private sector compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Quality Monitoring System Market |
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $13.56 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Monitors, Portable Monitors, Indoor Monitors, Outdoor Monitors Technology: Electrochemical, Optical, Laser, Infrared End User: Government, Residential, Industrial, Commercial Application: Ambient Air Quality, Indoor Air Quality, Workplace Safety, Environmental Compliance |
| Companies Covered | Thermo Fisher Scientific Inc., Siemens AG, Teledyne Technologies Inc., 3M Company, HORIBA Ltd., Emerson Electric Co., Honeywell International Inc., Aeroqual Ltd., Agilent Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Quality Monitoring System Market Emerging Trajectories
Sensor miniaturization and edge computing architectures are collapsing the cost-performance frontier that historically separated regulatory compliance from operational awareness applications.
Laser-induced breakdown spectroscopy for real-time heavy metal detection is absorbing capital allocation from atomic absorption laboratory systems. Mining operators and waste incineration facilities in Chile and Australia are piloting LIBS units for stack emission screening. The technology is absorbing the mid-market segment between portable XRF and reference method ICP-MS, compressing capital expenditure thresholds for hazardous air pollutant monitoring.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing membrane and filter manufacturers to reformulate hydrophobic gas sampling interfaces. European analyzer OEMs face eighteen-month material qualification cycles to validate polytetrafluoroethylene alternatives. The industrial process monitoring segment is responding by accelerating procurement of legacy PTFE-equipped instruments ahead of sunset dates.
Subscription telemetry models are displacing capital purchase arrangements for urban sensor grid deployments. Singapore and Copenhagen municipalities now contract data-as-a-service providers who retain hardware ownership and calibration liability. Facility management integrators in the Gulf Cooperation Council are adopting identical structures to bundle air quality dashboards with building automation contracts.
Air Quality Monitoring System Market Segmentation
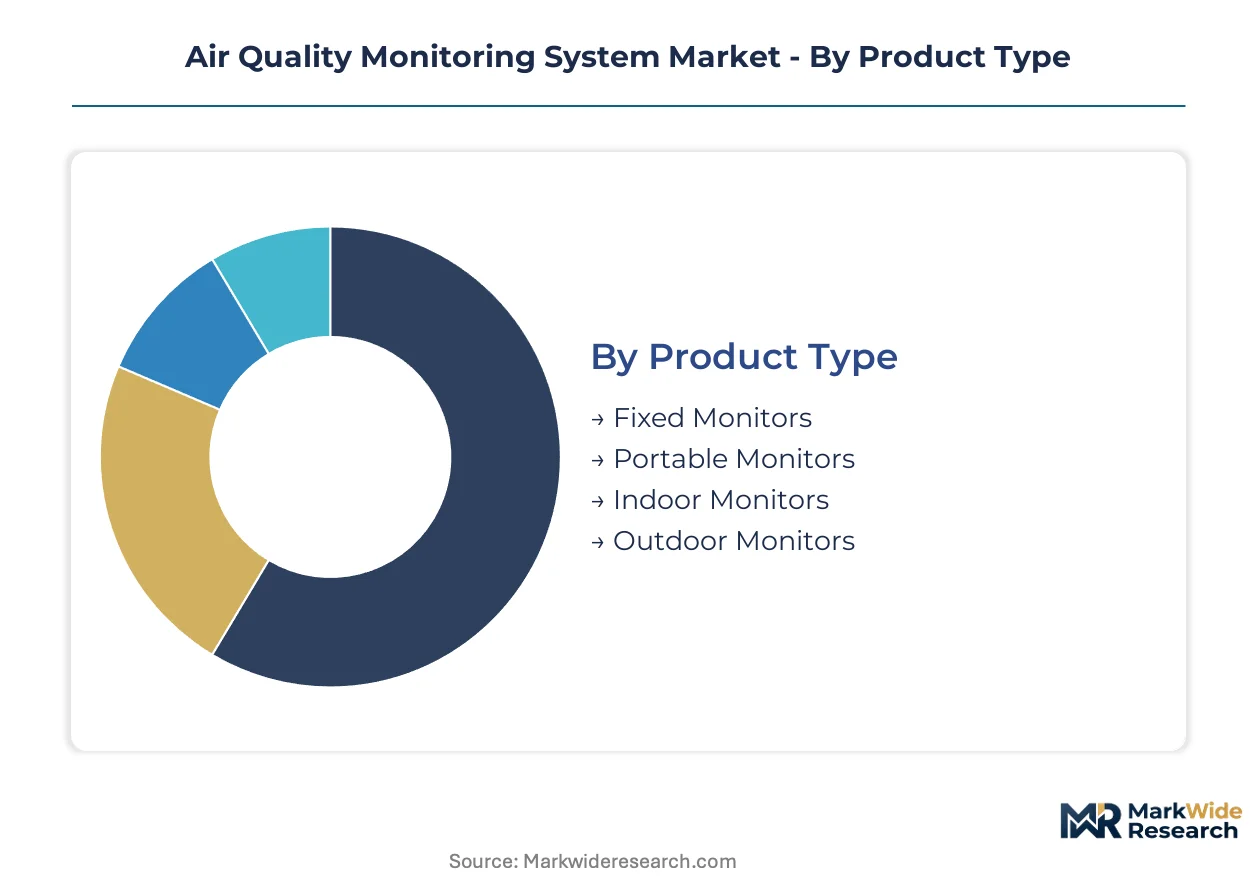
Procurement patterns fragment sharply across hardware tiers and deployment contexts. Capital allocation decisions hinge on whether monitors serve regulatory compliance, operational awareness, or wellness certification purposes.
Product Type:
Fixed monitors demand the highest upfront capital outlay, requiring hardened enclosures, meteorological sensors, and telemetry infrastructure for continuous regulatory-grade operation.
- Fixed Monitors:Permanent installations incorporate federal reference method optical benches and thermal conditioning modules for traceable particulate matter quantification. EPA continuous emissions mandates at US power generation facilities and China MEE real-time disclosure requirements at urban stations drive procurement concentration. Six-month recalibration cycles and zero gas handling protocols impose recurring operational expenditure that municipal environmental departments struggle to fund.
- Portable Monitors:Handheld units with electrochemical and optical sensor arrays enable field audit protocols across industrial and workplace safety applications. OSHA-equivalent enforcement expansion in Latin American manufacturing zones and mining operator stack emission screening in Chile and Australia accelerate demand. Battery-powered designs with Bluetooth data logging reduce per-unit cost to one-tenth of fixed station equivalents.
- Indoor Monitors:Compact sensor nodes target LEED certification and wellness building standards with CO2, VOC, and PM2.5 measurement.
- Outdoor Monitors:Weatherized enclosures for perimeter and fence-line monitoring at petrochemical facilities and construction sites.
Most installed capacity flows through Fixed Monitors. Expansion is steepest in Portable Monitors.
Technology:
Optical methods command premium positioning for regulatory applications, while electrochemical architectures dominate cost-constrained dense urban grids.
- Optical:Beta attenuation and nephelometry techniques deliver traceable measurement uncertainty for federal equivalent method certification. Tightened EPA particulate matter thresholds compel upgrades at petrochemical and power generation facilities. German and Japanese component suppliers concentrate supply of stabilized optical benches and thermal conditioning modules.
- Laser:Laser-induced breakdown spectroscopy enables real-time heavy metal detection for mining and waste incineration stack screening in Chile and Australia. The technology absorbs capital allocation from atomic absorption laboratory systems, compressing hazardous air pollutant monitoring expenditure thresholds.
- Electrochemical:Gas-specific cells for ozone, nitrogen dioxide, and sulfur dioxide measurement in low-cost sensor networks.
- Infrared:Non-dispersive absorption for carbon monoxide and carbon dioxide quantification in indoor and industrial process monitoring.
Optical systems anchor the revenue base. Electrochemical arrays are climbing the fastest on unit volume.
End User:
Government procurement concentrates on reference-grade infrastructure, while commercial buyers prioritize subscription telemetry and integrated building automation.
- Government:National ambient monitoring networks require tamper-proof data logging and public API connectivity under China MEE and EPA mandates. India's National Clean Air Programme drives demand for 400-plus continuous ambient monitoring stations with indigenous manufacturing incentives under the PLI scheme.
- Industrial:Petrochemical, power generation, and mining operators deploy continuous emissions monitoring for environmental compliance and stack emission screening. Field calibration technician scarcity constrains dense deployment economics despite neural network correction algorithm advances.
- Commercial:Facility management integrators in the Gulf Cooperation Council bundle air quality dashboards with building automation contracts under data-as-a-service structures.
- Residential:Consumer-grade sensor nodes for personal exposure awareness and smart home integration.
Industrial buyers deploy the most sensor nodes per contract. Government tenders carry the highest average transaction value.
Application:
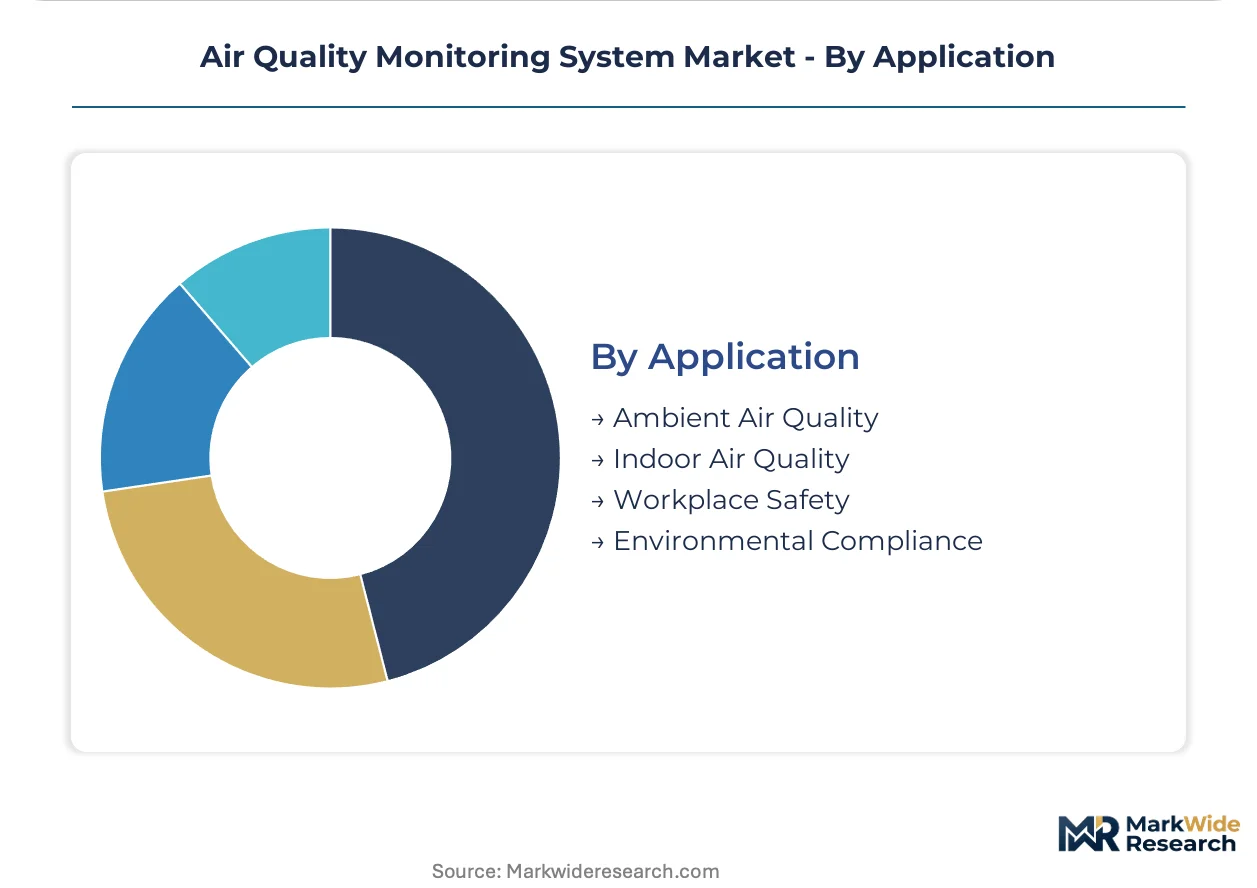
Environmental compliance applications absorb capital expenditure at the highest rates, while workplace safety protocols multiply portable monitor deployment.
- Environmental Compliance:Continuous emissions monitoring and ambient network stations require federal reference or equivalent method certification. EPA tightened standards and China MEE real-time disclosure mandates compel hardware refresh cycles. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances force eighteen-month material qualification cycles for European analyzer OEMs.
- Workplace Safety:Industrial hygiene protocols for manufacturing zones, mining operations, and confined spaces drive portable monitor specification. Brazil and Mexico distributors add SKUs to capture OSHA-equivalent enforcement expansion.
- Ambient Air Quality:Urban sensor grids and national monitoring networks for public health surveillance.
- Indoor Air Quality:Commercial building wellness certification and tenant ESG reporting requirements.
Environmental Compliance commands the largest project scale. Workplace Safety is gaining share fastest on unit shipments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys more networked sensor arrays than any other nation, while the United States concentrates procurement in regulatory-grade continuous emissions infrastructure. Divergent enforcement philosophies shape hardware specification patterns across national markets.
China
The Ministry of Ecology and Environment mandates real-time public disclosure from thousands of urban monitoring stations, compelling hardware refresh cycles with tamper-proof data logging requirements. Municipal governments across the Yangtze River Delta and Pearl River Delta procure dense electrochemical sensor grids. Shanghai and Beijing environmental bureaus specify systems with public API connectivity for citizen-facing air quality dashboards.
United States
The EPA's tightened National Ambient Air Quality Standards drive continuous emissions monitoring upgrades at power generation and petrochemical facilities. Tightened particulate matter thresholds compel traceable optical bench installations. Texas Gulf Coast refineries and Ohio River Valley coal plants anchor the industrial procurement concentration for federal equivalent method certification.
India
The National Clean Air Programme creates demand for over four hundred new continuous ambient monitoring stations in non-attainment cities. Indigenous manufacturing incentives under the PLI scheme reshape supplier selection criteria. Delhi-NCR and Maharashtra state pollution control boards lead deployment with indigenous equipment preferences in the Mumbai-Pune industrial corridor.
Germany
The EU Ambient Air Quality Directive and REACH Annex XVII restrictions shape analyzer certification requirements and material qualification cycles. Eighteen-month validation timelines for PTFE alternatives in gas sampling interfaces delay product launches. The Ruhr industrial region and Bavarian chemical clusters anchor compliance-driven procurement for reference-grade instrumentation.
Brazil
OSHA-equivalent enforcement expansion in manufacturing zones accelerates portable monitor specification through industrial hygiene distributors. Mining operators in Minas Gerais and São Paulo state industrial parks drive field audit protocol adoption. CONAMA resolutions on air quality standards create regulatory pressure for continuous monitoring in petrochemical facilities.
Air Quality Monitoring System Market Vendor Landscape
Top-tier vendors anchor regulatory compliance applications, while mid-tier specialists compete on modular architectures and dense urban deployment economics. The vendor base stratifies across three tiers: analytical instrument heritage players, building automation integrators, and low-cost sensor network specialists. Two dominant competitive moves are reshaping positioning: machine learning-based sensor fusion partnerships that bridge reference-grade and electrochemical performance, and subscription telemetry models that displace capital purchase arrangements.
Within the analytical instrument tier, Thermo Fisher Scientific Inc. and Agilent Technologies Inc. exemplify heritage positioning through traceable measurement uncertainty capabilities. Aeroqual Ltd. occupies a position among modular hardware specialists targeting total cost of ownership reduction. Siemens AG anchors the building automation integration vector with industrial protocol compatibility. These three archetypes represent the competitive structure without exhausting the participant set.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Siemens AG |
| Teledyne Technologies Inc. |
| 3M Company |
| HORIBA Ltd. |
| Emerson Electric Co. |
| Honeywell International Inc. |
| Aeroqual Ltd. |
| Agilent Technologies Inc. |
| Others |
Supply Flow & Price Mechanics
China's MEE real-time disclosure mandate compels municipal governments to procure tamper-proof data logging systems with public API connectivity, forcing component suppliers to certify optical benches and thermal conditioning modules that concentrate among German and Japanese specialists and compress margins for mid-tier assemblers.
Pricing Analysis
Capacity additions in India under the PLI scheme are reshaping price floors for electrochemical sensor arrays. Three-tier pricing structure across reference-grade, federal equivalent method, and low-cost sensor tiers anchors the market, with price differentiation driven by certification level and after-sales calibration bundling. Cost compression in the low-cost tier is intensifying because neural network correction algorithms reduce hardware requirements. Municipal environmental departments exhibit the highest price sensitivity due to recurring zero gas handling expenditure, while petrochemical facilities prioritize traceable measurement uncertainty over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and China anchor hub-and-spoke patterns for optical benches and thermal conditioning modules. Manufacturing concentration in these three countries draws from specialized glass substrates, stabilized laser diodes, and electrochemical cell membranes as critical inputs. Single-source vulnerability around stabilized optical benches from Japanese component suppliers creates procurement risk for EPA-mandated federal equivalent method certification. Distribution runs through industrial automation distributors and environmental instrumentation specialists serving municipal and industrial end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in air quality monitoring systems rests on machine learning-based sensor fusion that collapses cost-performance thresholds between reference-grade and electrochemical tiers, allowing premium-tier vendors to capture mid-market volume without sacrificing certification-grade pricing.
For Market Incumbents: Deploy machine learning sensor fusion partnerships to bridge reference-grade and electrochemical performance gaps before neural network correction algorithms commoditize optical bench differentiation. Deepen backward integration into stabilized laser diode supply to mitigate Japanese component supplier concentration. Capture municipal procurement consolidation by bundling calibration-as-a-service with hardware contracts. For New Entrants and Emerging Players: Portable monitor field audit protocols in Latin American manufacturing zones offer the most penetrable white-space target, with Brazil's CONAMA resolutions and Mexico's OSHA-equivalent enforcement expansion creating regulatory tailwinds. Target industrial hygiene distributors rather than direct municipal sales to bypass incumbent specification lock-in. Lead with battery-powered Bluetooth-enabled designs priced at one-tenth of fixed station equivalents. For Investors and Strategic Acquirers: Asymmetric upside sits with modular hardware specialists possessing machine learning correction algorithm capabilities and established municipal data-as-a-service contracts. Long-term viability across the projection horizon favors vendors that can transition from capital sales to subscription telemetry models retaining hardware ownership and calibration liability. Watch for indigenous manufacturing incentive qualification under India's PLI scheme as an inflection indicator for supplier selection shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Machine Learning Sensor Fusion Development | Neural network correction algorithms enable electrochemical arrays to achieve reference-grade equivalence at reduced hardware cost. |
| Subscription Telemetry Model Transition | Singapore and Copenhagen municipalities now contract data-as-a-service providers who retain calibration liability. |
| Indigenous Manufacturing Capacity Buildout | India's PLI scheme reshapes supplier selection criteria for 400-plus continuous ambient monitoring stations. |
| Portable Monitor Channel Expansion | Brazil and Mexico industrial hygiene distributors add SKUs to capture OSHA-equivalent enforcement expansion. |
| Cybersecurity Certification Investment | IEC 62443 compliance for networked sensor arrays extends product development timelines by eight to fourteen months. |
Methodological Framework
Multiple input streams — regulatory filing analysis, customs and trade data, and equipment procurement records — were reconciled with primary interviews involving environmental instrumentation product managers, municipal environmental department procurement officers, industrial facility compliance directors, and electrochemical sensor component suppliers. Secondary validation drew from EPA continuous emissions monitoring databases, China MEE real-time disclosure platform records, EU EN standard certification registries, and SEC filings of listed analytical instrument manufacturers. Bottom-up unit shipment estimates and top-down market value reconciliation anchored the analytical framework.
Data-stream reconciliation across the projection horizon applied segmentation dimensions spanning product type, technology architecture, end user category, and application context, with additional modeling of certification tier and regional regulatory cluster. CAGRs were derived from trend extrapolation of historical procurement cycles and enforcement mandate implementation timelines. Forecast inputs incorporated satellite validation density for ground-truthing accuracy and field calibration technician availability constraints.
The model holds under steady regulatory enforcement intensity and stable component supply availability; deviation in tariff exposure on German and Japanese optical benches or accelerated REACH Annex XVII sunset dates would shift hardware refresh cycle timing and supplier selection patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Nano Radiation Sensors Market
Sensors and Controls
Electronic Sentry Market
Sensors and Controls
US Smart Air Purifier Market
Sensors and Controls
Italy Digital Thermometer Market
Sensors and Controls
Asia Pacific Lidar Market
Sensors and Controls
Tip Location Devices Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
High-End Accelerometer Market
Sensors and Controls
Global Radar Sensor Market
Sensors and Controls
Smartphone Biometric Sensors Market
Sensors and Controls
North America Wireless Sensors Market
Sensors and Controls
High-Precision Confocal Sensor Market
Sensors and Controls
Non-Glass Capacitive Sensors Market
Sensors and Controls
Global Accelerometers Market
Sensors and Controls
Anemometer Market
Sensors and Controls
Micro-Electro Mechanical Systems Market