
 Fiber Laser Coding System Market | 2026-2036
Fiber Laser Coding System Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Laser Coding System Market Foresight
Modular system bundling is recalibrating how packaging lines procure coding equipment. IPG Photonics Corporation leverages its vertically integrated fiber laser source production to control component costs across system tiers. Videojet Technologies Inc. anchors its competitive position through extensive direct service networks in North America and Europe. Domino Printing Sciences plc differentiates via software-integrated traceability platforms that connect coding hardware to enterprise MES systems.
A fiber laser coding system employs a doped fiber optic gain medium, typically ytterbium-doped at wavelengths near 1064 nm, to generate high-intensity pulsed or continuous-wave laser beams for permanent marking, coding, and engraving on metals, plastics, and coated substrates. The technology serves critical traceability functions across pharmaceutical serialization, food date coding, and electronics component identification. Integrated systems command the largest installed base due to their seamless incorporation into high-speed packaging lines, while modular solutions represent the fastest-expanding category as manufacturers seek field-upgradeable configurations that extend capital equipment life cycles. Ultraviolet laser variants capture premium positioning in cosmetics and medical device applications where heat-sensitive substrates require cold marking processes.
FDA serialization mandates under the Drug Supply Chain Security Act and EU MDR traceability requirements are accelerating pharmaceutical sector investment in permanent coding infrastructure. REACH restrictions on solvent-based inks and EPA volatile organic compound regulations are simultaneously constraining legacy thermal inkjet alternatives in food and beverage packaging. ISO 15415 and GS1 barcode quality standards further dictate minimum contrast and readability thresholds that fiber laser systems routinely exceed. Stakeholders must evaluate wavelength flexibility and beam delivery options against evolving substrate portfolios rather than optimizing solely for current production mixes.
Market Dynamics
Pharmaceutical serialization mandates and REACH chemical restrictions are forcing a wholesale replacement of thermal inkjet systems with permanent fiber laser infrastructure across European and North American packaging lines.
Growth Catalysts
- EU MDR traceability mandates:European medical device manufacturers must implement permanent direct part marking for implantable devices, driving ytterbium-doped fiber laser installations in German and Swiss precision manufacturing clusters.
- Food-grade substrate expansion:Beverage canning facilities in the United States are retrofitting lines with 1064 nm fiber lasers to eliminate solvent-based ink contamination risks under EPA volatile organic compound enforcement.
- Automotive component traceability:Powertrain and electronics suppliers require dot-matrix and Data Matrix codes that survive thermal cycling, accelerating pulsed fiber laser adoption for aluminum engine block marking.
Market Restraints
- Rare-earth fiber cost volatility:Ytterbium-doped gain fiber prices fluctuate with Chinese export quotas on rare-earth oxides, compressing margins for system integrators dependent on IPG Photonics and nLIGHT supply.
- Ultraviolet laser source concentration:Third-harmonic generation modules for 355 nm cold marking remain concentrated among Japanese and German specialty laser houses, creating supply bottlenecks for cosmetics and medical polymer applications.
- Capital intensity threshold:Entry-level fiber laser coders cost three to five times equivalent thermal inkjet systems, excluding small-batch contract packagers from compliance-driven upgrade cycles.
Strategic Opportunities
- Indian pharmaceutical export compliance:CDSCO alignment with FDA Drug Supply Chain Security Act requirements creates demand for serialization-capable fiber laser systems in Ahmedabad and Hyderabad generic drug manufacturing corridors.
- Battery cell traceability:Lithium-ion electrode and pouch cell manufacturers require non-contact marking of conductive substrates, opening greenfield applications for nanosecond-pulsed fiber lasers in South Korean and Chinese gigafactories.
- Software-integrated MES connectivity:OPC-UA and MQTT protocol support enables real-time line integration, allowing coding equipment vendors to capture recurring software license revenue alongside hardware sales.
Industry Challenges
- Laser safety officer certification delays:IEC 60825-1 compliance requires site-specific risk assessments and trained personnel, extending commissioning timelines for multi-line pharmaceutical facilities by four to eight weeks.
- Legacy SCADA integration complexity:Brownfield packaging lines running proprietary Allen-Bradley or Siemens control architectures demand custom gateway development to synchronize fiber laser controllers with existing production databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Laser Coding System Market |
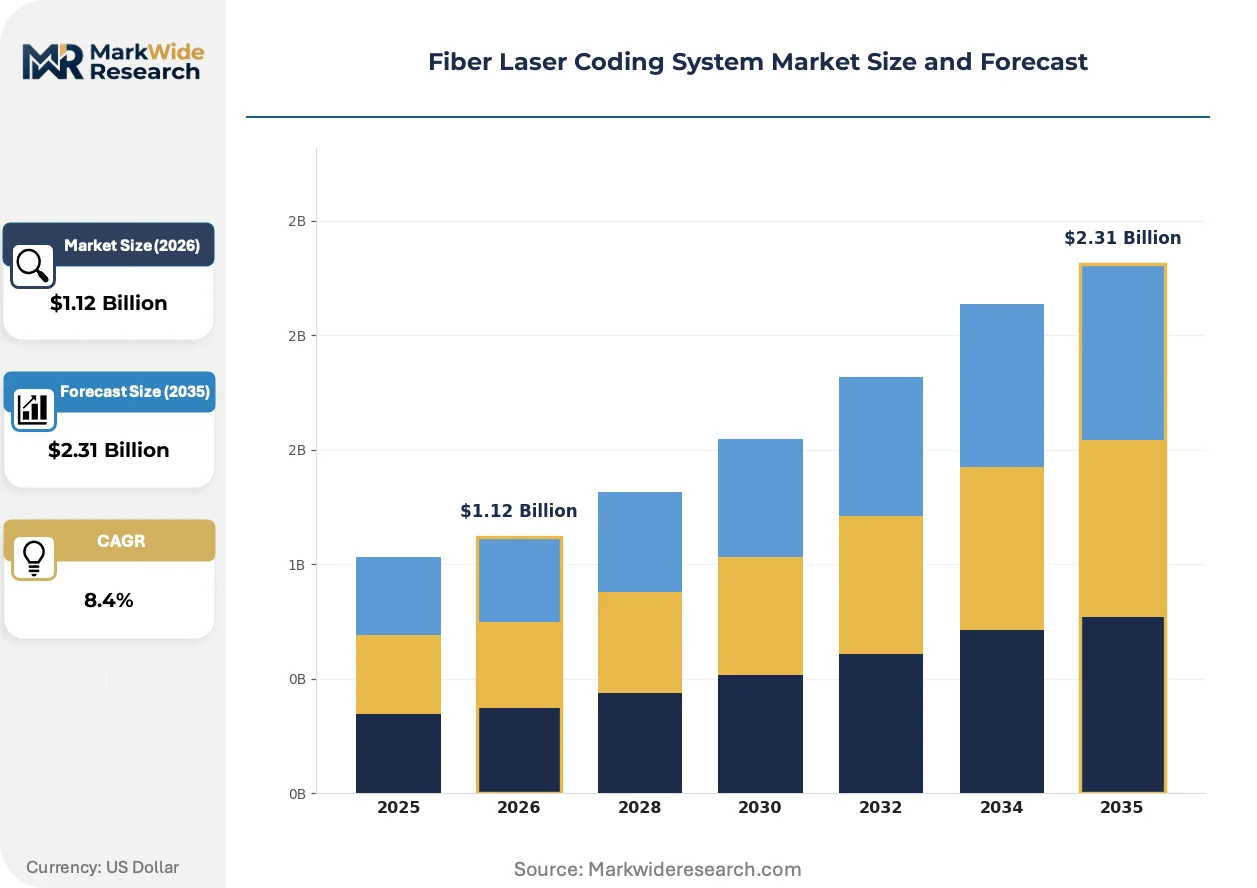
| Market Size in 2026 | $1.12 Billion |
| Market Size in 2035 | $2.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Systems, Integrated Systems, Modular Solutions, Industrial Units Technology: Fiber Laser, CO2 Laser, Ultraviolet Laser, Green Laser End User: Food & Beverage, Pharmaceuticals, Electronics, Cosmetics Application: Packaging, Marking, Engraving, Coding |
| Companies Covered | IPG Photonics Corporation, Videojet Technologies Inc., Domino Printing Sciences plc, Markem-Imaje Corporation, Coherent Inc., Han’s Laser Technology Industry Group Co. Ltd., Trumpf, Keyence Corporation, Macsa ID SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Laser Coding System Market Shifts & Advancements
Packaging line architectures are fragmenting into field-upgradeable subsystems, decoupling laser source investments from beam delivery and control electronics procurement decisions.
Fiber laser engine design is modularizing around standardized 19-inch rack-mountable power and control modules. Pharmaceutical contract manufacturers in Germany and Switzerland are adopting these configurations to swap 20W sources for 50W or 100W variants without replacing galvo scanning heads or f-theta lenses. This architecture compresses capital refresh cycles from seven-year full-system replacement to three-year component-level upgrades.
REACH Annex XVII restrictions on chromium trioxide in electroplating are redirecting automotive marking toward fiber laser surface texturing for friction and wear applications. German KBA type-approval processes now recognize laser-induced periodic surface structures as compliant alternatives to hexavalent chromium coatings. Powertrain suppliers in Stuttgart and Munich are qualifying these processes for transmission gear and bearing race identification.
Service contracting for coding equipment is unbundling from hardware purchase agreements. North American food and beverage packagers are negotiating uptime-guaranteed performance contracts where vendors retain laser source ownership and charge per marked unit. This model concentrates in high-volume carbonated soft drink and ready-to-eat cereal facilities where line utilization exceeds 85 percent and downtime penalties are contractually enforced.
Fiber Laser Coding System Market Segmentation
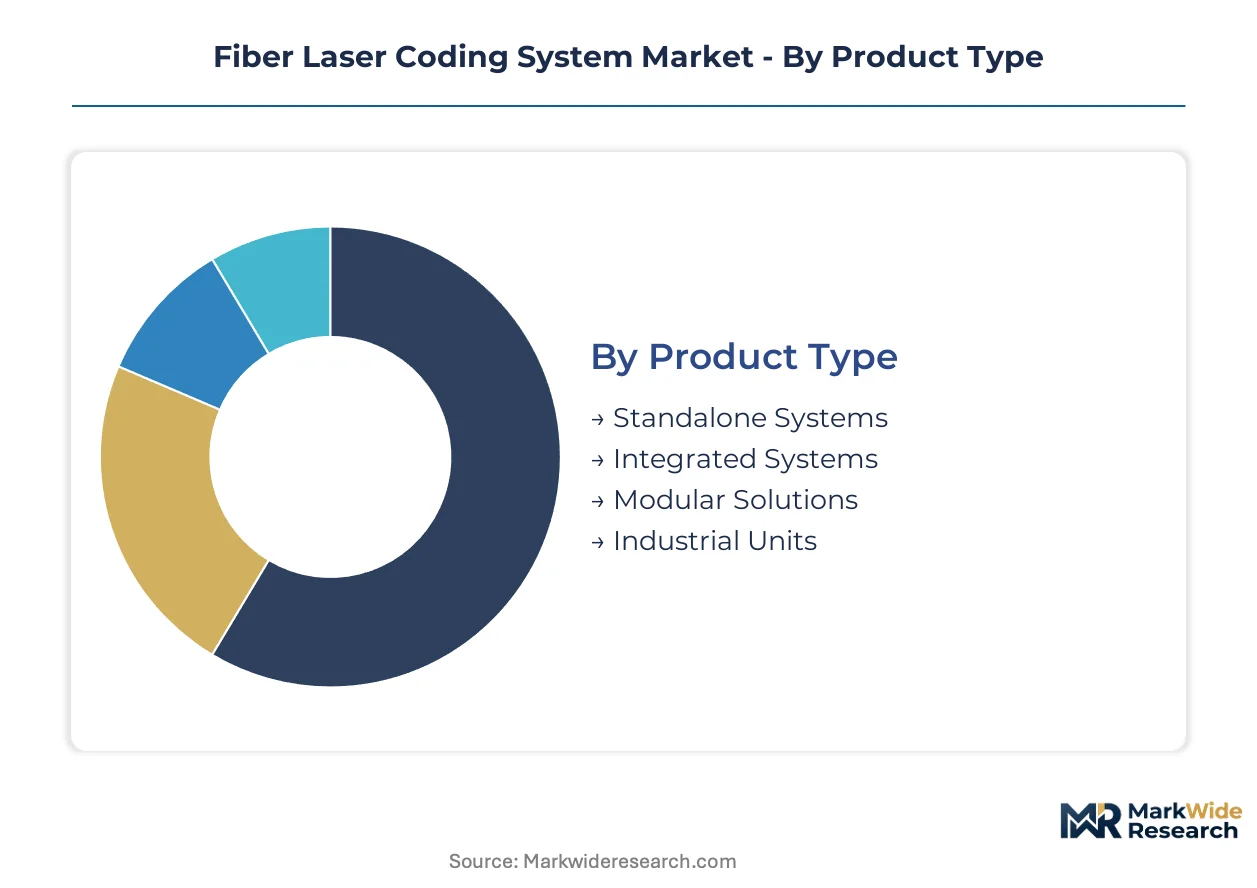
Fiber laser coding systems fragment across hardware architectures, wavelength technologies, and compliance-driven end-use requirements. Procurement decisions hinge on whether installations must satisfy FDA serialization mandates, REACH chemical restrictions, or ISO 15415 barcode quality thresholds.
Product Type:
Certification burdens vary sharply across hardware configurations, with pharmaceutical serialization mandates driving integrated system validation protocols while modular architectures face lighter initial compliance loads.
- Integrated Systems:These units embed directly into high-speed packaging lines with synchronized conveyor controls and vision verification. German pharmaceutical contract manufacturers in Baden-Württemberg specify these configurations for EU MDR-compliant implantable device marking where line integration audits are mandatory.
- Modular Solutions:Field-upgradeable architectures separate laser sources from beam delivery modules and control electronics. Swiss precision manufacturers near Zurich favor these for three-year component refresh cycles that avoid full-system requalification under Swissmedic guidelines.
- Standalone Systems:Benchtop configurations serve low-volume batch operations with minimal line integration requirements.
- Industrial Units:Ruggedized enclosures withstand washdown protocols in food processing environments.
Integrated Systems sits at the top of the volume ranking, with Modular Solutions climbing the fastest.
Technology:
Cost tiers stratify sharply by wavelength engineering complexity, with ytterbium-doped fiber lasers commanding mid-range positioning and ultraviolet sources carrying premium multiples for heat-sensitive substrates.
- Fiber Laser:Ytterbium-doped gain media at 1064 nm deliver nanosecond-pulsed or continuous-wave output for metals and coated plastics. US beverage canning facilities in Wisconsin and Colorado deploy these for EPA-compliant solvent-free date coding on aluminum substrates.
- Ultraviolet Laser:Third-harmonic generation at 355 nm enables cold marking of medical polymers and cosmetic packaging without thermal damage. Japanese and German specialty houses control source supply, creating procurement bottlenecks for cosmetics manufacturers in Osaka and Düsseldorf.
- CO2 Laser:Longer infrared wavelengths suit organic materials and uncoated paperboard.
- Green Laser:Frequency-doubled 532 nm sources address specialized semiconductor marking applications.
Fiber Laser dominates current procurement volumes, though Ultraviolet Laser gains share fastest in medical device and premium cosmetics segments.
End User:
Application maturity diverges across customer types, with pharmaceutical and food sectors representing established compliance-driven demand while electronics and cosmetics present emerging specification territory.
- Pharmaceuticals:Serialization mandates under the US Drug Supply Chain Security Act and EU MDR require permanent tamper-evident marking. Indian generic drug exporters in Ahmedabad and Hyderabad are retrofitting lines for CDSCO-FDA alignment ahead of track-and-trace deadlines.
- Food & Beverage:EPA volatile organic compound enforcement and REACH solvent restrictions are eliminating thermal inkjet alternatives. US cereal and carbonated soft drink packagers negotiate uptime-guaranteed performance contracts where vendors retain source ownership.
- Electronics:Component miniaturization and PCB traceability requirements are opening specifications for Data Matrix marking on conductive substrates.
- Cosmetics:Heat-sensitive packaging materials and premium brand protection needs are driving ultraviolet laser qualification.
Pharmaceuticals anchors current revenue concentration, with Electronics expanding most quickly on battery cell traceability demand.
Application:
Margin structures vary by functional depth, with simple coding commanding commodity pricing while multi-process engraving and marking systems capture value-added positioning.
- Coding:Alphanumeric and barcode marking for serialization and date-lot traceability. German automotive suppliers in Stuttgart apply these for KBA-recognized laser-induced periodic surface structures replacing hexavalent chromium coatings.
- Marking:Permanent identification including Data Matrix and QR codes for component lifecycle tracking. South Korean lithium-ion gigafactories specify non-contact marking for electrode and pouch cell traceability.
- Packaging:Primary and secondary container identification with line-speed synchronization.
- Engraving:Deep material removal for decorative or functional surface texturing applications.
Coding leads in unit shipments, with Marking showing the steepest expansion trajectory on automotive and battery sector adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial fiber laser adoption through Stuttgart and Munich automotive clusters, establishing the technical foundation that spread to Swiss precision manufacturing and US pharmaceutical packaging corridors.
United States
FDA serialization mandates under the Drug Supply Chain Security Act drive pharmaceutical line retrofits. EPA volatile organic compound enforcement eliminates solvent-based ink alternatives in Wisconsin and Colorado beverage canning facilities. Boston-area medical device manufacturers qualify ytterbium-doped systems for implantable device traceability.
Germany
KBA type-approval processes now recognize laser-induced periodic surface structures as compliant alternatives to hexavalent chromium coatings. REACH Annex XVII restrictions redirect automotive marking toward fiber laser surface texturing. Stuttgart powertrain suppliers qualify pulsed fiber lasers for aluminum engine block marking that survives thermal cycling.
Switzerland
Swissmedic guidelines favor modular architectures that avoid full-system requalification during component refresh cycles. Zurich-area precision manufacturers adopt field-upgradeable configurations separating laser sources from beam delivery modules. Medical device clusters near Basel deploy ultraviolet variants for heat-sensitive polymer marking.
India
CDSCO alignment with FDA Drug Supply Chain Security Act requirements creates demand for serialization-capable systems. Ahmedabad and Hyderabad generic drug manufacturing corridors retrofit lines for export compliance ahead of track-and-trace deadlines. Domestic battery cell producers specify non-contact marking for electrode traceability.
South Korea
Lithium-ion electrode and pouch cell manufacturers require non-contact marking of conductive substrates. Seoul and Busan gigafactories open greenfield applications for nanosecond-pulsed fiber lasers in battery traceability. MFDS medical device regulations parallel EU MDR requirements for permanent direct part marking.
Fiber Laser Coding System Market Competitive Landscape
Premium-margin players sit above commodity-margin players across wavelength flexibility and software integration depth. The vendor base stratifies into three tiers: vertically integrated source manufacturers, system integrators with captive service networks, and software-centric traceability platform providers. Consolidation pressure concentrates among mid-scale system houses lacking in-house fiber production or direct service reach. Dominant competitive moves include backward integration into rare-earth fiber supply and geographic expansion through acquisition of regional service distributors.
Within the vertically integrated tier, IPG Photonics Corporation exemplifies upstream control over ytterbium-doped gain media production. Among system integrators with established service infrastructure, Videojet Technologies Inc. and Domino Printing Sciences plc occupy positions anchored by North American and European direct support networks. These three entities represent distinct archetypes: captive source supply, field service density, and software-integrated traceability platforms respectively.
| Leading Market Players |
|---|
| IPG Photonics Corporation |
| Videojet Technologies Inc. |
| Domino Printing Sciences plc |
| Markem-Imaje Corporation |
| Coherent Inc. |
| Han's Laser Technology Industry Group Co. Ltd. |
| Trumpf |
| Keyence Corporation |
| Macsa ID SA |
| Others |
Supply & Pricing Matrix
Pharmaceutical serialization mandates under the FDA Drug Supply Chain Security Act and EU MDR are forcing packaging line operators toward permanent marking infrastructure, compelling suppliers to absorb rare-earth fiber cost volatility while maintaining price accessibility for mid-tier system integrators. This demand-side specification tightening creates asymmetric pricing power for vertically integrated source manufacturers versus assembly-dependent competitors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with ultraviolet laser systems commanding multiples over ytterbium-doped fiber variants due to third-harmonic generation complexity and Japanese-German source concentration. Price differentiation hinges on wavelength flexibility and software-integrated MES connectivity, with FDA-validated pharmaceutical systems least sensitive to cost and small-batch contract packagers most vulnerable to capital intensity thresholds. Cost compression in entry-level configurations is intensifying because Chinese rare-earth export quota fluctuations feed directly into gain fiber pricing.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and China anchor hub-and-spoke fulfillment patterns for laser source modules and galvo scanning heads. Manufacturing concentrates in German precision clusters for automotive qualification, Chinese industrial zones for cost-optimized assembly, and Japanese specialty houses for ultraviolet generation optics. Raw material dependencies draw from Chinese rare-earth oxide deposits for ytterbium-doped fiber, German optical glass for f-theta lenses, and Japanese nonlinear crystals for harmonic generation. Single-source vulnerability in third-harmonic generation modules creates procurement bottlenecks for medical polymer applications. Distribution runs through direct service networks in North America and Europe alongside third-party industrial distributors in Asia-Pacific emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through software-integrated traceability platforms that capture recurring license revenue, offsetting hardware commoditization pressure from Chinese system assemblers.
For Market Incumbents: Cement service network density as the primary defensive moat by extending direct technician coverage into Indian pharmaceutical corridors and South Korean battery gigafactories. Deepen backward integration into rare-earth fiber supply to insulate margins from Chinese export quota volatility. Prioritize OPC-UA and MQTT protocol certification investments to lock in pharmaceutical MES integration contracts before emerging software-centric competitors qualify alternative platforms. For New Entrants and Emerging Players: Begin with modular system architectures targeting Swiss and German precision manufacturers seeking field-upgradeable configurations that avoid full-system requalification under Swissmedic guidelines. White-space opportunity concentrates in Indian generic drug export corridors where CDSCO-FDA alignment deadlines outpace established vendor installation capacity. A software-first go-to-market angle—selling traceability platform subscriptions independent of hardware—bypasses capital intensity barriers blocking thermal inkjet replacement cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale system houses possessing captive ultraviolet laser source relationships or established pharmaceutical validation protocols but lacking geographic scale. Long-term viability favors vendors who can bridge hardware sales into recurring software revenue streams across the 5-10 year compliance-driven replacement cycle. The signal to watch is EPA enforcement intensity against solvent-based inks in food and beverage packaging, which would accelerate thermal inkjet displacement and expand addressable market for permanent marking infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Fiber Supply | Captive ytterbium-doped gain media production insulates margins from Chinese export quota volatility affecting IPG Photonics and nLIGHT supply. |
| Software-Integrated MES Connectivity | OPC-UA and MQTT protocol support enables recurring license revenue from pharmaceutical serialization platforms connecting coding hardware to enterprise systems. |
| Geographic Expansion into Indian Pharmaceutical Corridors | CDSCO alignment with FDA Drug Supply Chain Security Act creates installation demand in Ahmedabad and Hyderabad generic drug manufacturing clusters. |
| Ultraviolet Laser Source Qualification | 355 nm cold marking capability opens premium positioning in cosmetics and medical device applications where heat-sensitive substrates require non-thermal processes. |
| Performance-Based Service Contracting | Uptime-guaranteed per-unit pricing models concentrate in high-volume North American food and beverage facilities where line utilization exceeds 85 percent. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with packaging line engineers, pharmaceutical regulatory affairs leads, laser system procurement managers, and aftermarket service directors alongside secondary validation from FDA 483 inspection observations, EMA medical device guidance documents, EPA enforcement action databases, and SEC filings from listed laser source manufacturers. Bottom-up estimates of installed base and replacement cycles were triangulated against top-down market sizing derived from packaging machinery production statistics and rare-earth fiber import-export data.
Segment-weighting approaches distributed value and volume across hardware architectures, wavelength technologies, and compliance-driven end-use requirements. The analytical framework modeled integrated versus modular system configurations, ytterbium-doped fiber versus ultraviolet versus CO2 laser sources, and pharmaceutical versus food and beverage versus automotive versus electronics end-use segments across the projection horizon. CAGRs were derived from elasticity-adjusted replacement demand curves incorporating regulatory deadline schedules and substrate portfolio evolution in key manufacturing clusters. Forecast inputs included REACH Annex XVII restriction timelines, EU MDR implementation phases, and battery cell traceability specification drafts from South Korean and Chinese gigafactory operators.
Caveats apply where rare-earth export quota volatility, ultraviolet laser source supply disruptions, or delays in FDA and EMA serialization enforcement could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory implementation pace and substrate substitution patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Pin Insertion Machine Market
Industrial Equipment
Cartridge Heaters Market
Industrial Equipment
Digital Tube Roller Market
Industrial Equipment
Thermal Cleaning System Market
Industrial Equipment
Industrial Magnetrons Market
Industrial Equipment
Vacuum Concentrators Market
Industrial Equipment
Industrial Tags Market
Industrial Equipment
Mounted Bearing Market
Industrial Equipment
Industrial Fans Market
Industrial Equipment
Dust Extraction System Market
Industrial Equipment
Global Flat Glass Tempering Machines Market
Industrial Equipment
Middle-East Fans and Blowers Market
Industrial Equipment
Resistance Spot Welding Machines Market
Industrial Equipment
Global Pneumatic Actuators Market
Industrial Equipment
Above 300mm Cooling Fans Market
Industrial Equipment
Industrial Linear Accelerator Market