
 CNC Tool Storage System Market | 2026-2036
CNC Tool Storage System Market Size, Share, and Industry Trends Forecast 2026-2036
CNC Tool Storage System Market Outlook
Subscription-based maintenance and software-defined inventory tracking is broadening what machine-tool vendors monetize beyond hardware. DMG Mori leverages its service network to bundle storage optimization into long-term contracts. Mazak Corporation anchors its North American position through integrated tool-management programs for high-mix production. FANUC Corporation differentiates by embedding storage telemetry within its CNC control ecosystem.
A CNC tool storage system comprises engineered enclosures, retrieval mechanisms, and control interfaces designed to organize cutting tools, holders, and inserts within tolerances that prevent corrosion and dimensional drift, primarily serving automated machining environments where tool-change intervals directly affect equipment utilization rates. Vertical storage towers command the premium segment due to their floor-space efficiency in high-density facilities, while aluminum-constructed systems are gaining share as weight-sensitive aerospace buyers prioritize ergonomics and transportability alongside durability. Steel-framed drawer systems remain the volume workhorse across general manufacturing, though composite-material alternatives are penetrating cleanroom-adjacent healthcare applications where magnetic interference and chemical resistance matter.
OSHA lockout-tagout standards and ISO 9001 quality-management requirements shape how U.S. and international suppliers design access-control and traceability features into storage products. The EU Machinery Directive and CE marking framework mandate interlocking guards and ergonomic load limits that constrain design freedom but create compliance barriers protecting established European vendors. Buyers should scrutinize whether vendor software architectures can integrate with emerging MES platforms without custom middleware, as interoperability becomes the decisive procurement criterion.
Market Dynamics
Spindle utilization targets above 85% are forcing aerospace and automotive producers to treat tool storage as a production asset rather than a facility afterthought. This operational pressure is compressing procurement cycles and elevating telemetry-enabled systems above commodity enclosures.
Growth Catalysts
- OSHA lockout-tagout mandates:U.S. manufacturers must document tool access trails, driving replacement of unmonitored cabinets with interlocked systems that log every retrieval event.
- Aluminum construction adoption:Aerospace assembly floors prioritize lightweight towers that reduce ergonomic injury claims while maintaining corrosion resistance in climate-controlled environments.
- China's eastern manufacturing corridor:Smart factory investments in Jiangsu and Zhejiang provinces outpace domestic supply, creating import demand for CE-certified European storage systems.
Market Restraints
- Steel price volatility:Drawer-system manufacturers face margin compression when alloy costs spike, forcing absorption or pass-through decisions that stall contract negotiations.
- European vendor concentration:CE marking expertise concentrates among established German and Italian producers, creating compliance barriers for Asian entrants seeking EU market access.
- RFID-reader accuracy limitations:Metal-dense environments interfere with wireless inventory tracking, requiring redundant barcode systems that raise total installed cost.
Strategic Opportunities
- India's PLI scheme for precision manufacturing:Domestic machining capacity expansion creates first-mover advantage for vendors offering localized software support and spare-part availability.
- Composite-material cleanroom storage:Medical device manufacturers near Minneapolis and Boston require non-magnetic, chemically inert enclosures for implant machining operations.
- MES platform convergence:Storage systems that embed OPC-UA or MQTT protocols without middleware capture specification authority in brownfield automation projects.
Industry Challenges
- Retrofit integration complexity:Legacy FANUC and Siemens CNC architectures require custom API development to synchronize tool data with new storage telemetry.
- ISO 9001 audit preparation:Documentation of calibration intervals and environmental monitoring for precision holders demands dedicated quality personnel that mid-tier job shops struggle to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CNC Tool Storage System Market |
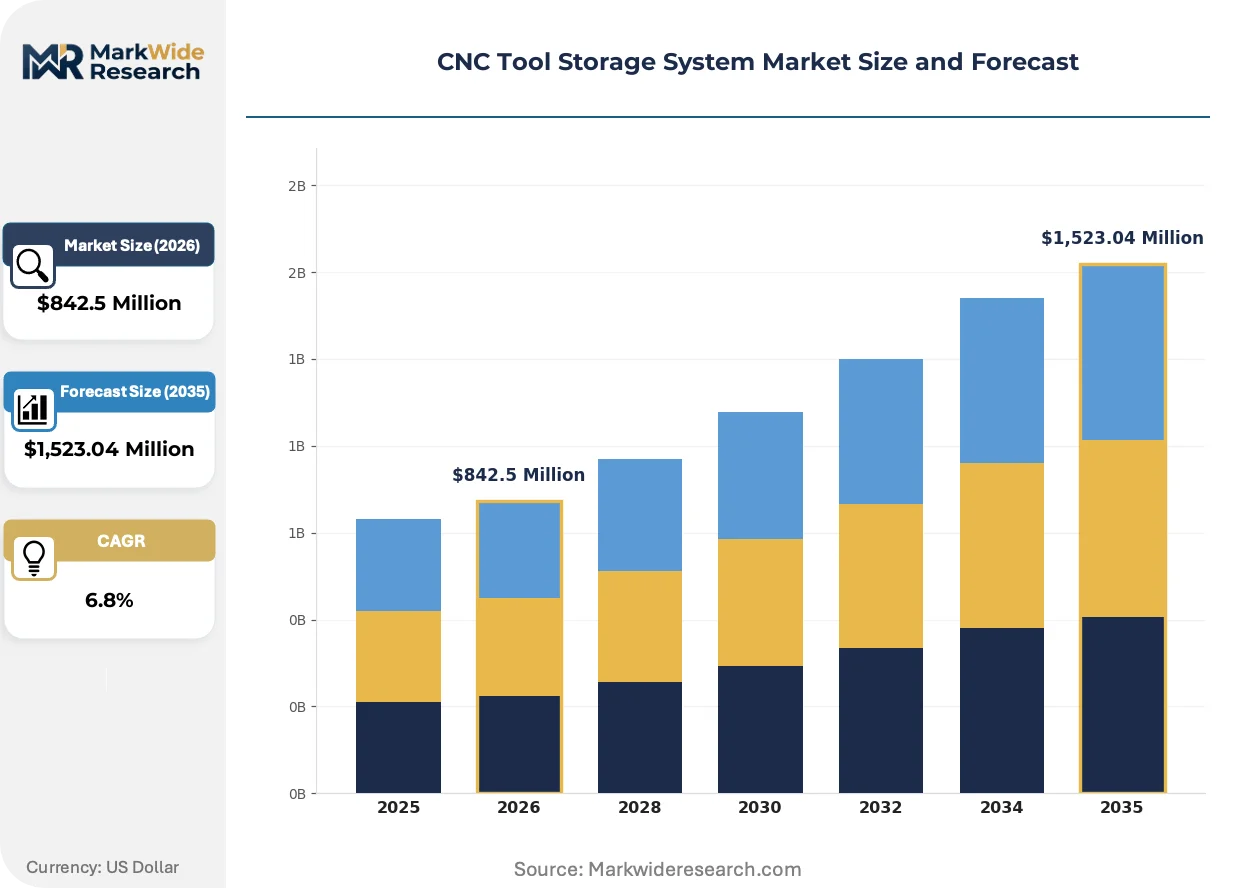
| Market Size in 2026 | $842.5 Million |
| Market Size in 2035 | $1,523.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Storage Towers, Drawer Systems, Racks, Containers Material: Steel, Aluminum, Plastic, Composite End User: Aerospace, Automotive, Manufacturing, Healthcare Installation Type: On-site, Modular, Portable, Custom |
| Companies Covered | DMG Mori, Mazak Corporation, FANUC Corporation, Okuma Corporation, Makino, Haas Automation, JTEKT Corporation, Trumpf, Amada Machine Tools, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CNC Tool Storage System Market Strategic Shifts
Tool storage is transitioning from passive inventory housing to active production nodes that generate operational data. Vendors now compete on software architecture and API breadth rather than enclosure specifications alone.
RFID-integrated drawer systems are integrating real-time location tracking with automated reorder triggers. Tier-one automotive suppliers in Stuttgart and Wolfsburg deploy these configurations to eliminate spindle waits caused by missing inserts. The technology is integrating MES workflows directly into storage hardware, collapsing the boundary between facility logistics and machining operations.
Germany's Machinery Directive interlock requirements are mandating load-sensing guards and ergonomic weight limits that constrain tower design freedom. Domestic producers gain compliance advantage while Asian exporters face extended certification timelines. Medical device manufacturers in Baden-Württemberg respond by specifying only CE-marked systems to preempt audit findings.
Buyers now unbundle hardware procurement from software subscriptions, treating storage optimization as a recurring operational expense. Machine-tool distributors in Chicago and Detroit lose specification authority to direct vendor relationships. This pattern concentrates in high-mix aerospace subcontractors where tool-change frequency justifies ongoing analytics investment.
CNC Tool Storage System Market Segmentation
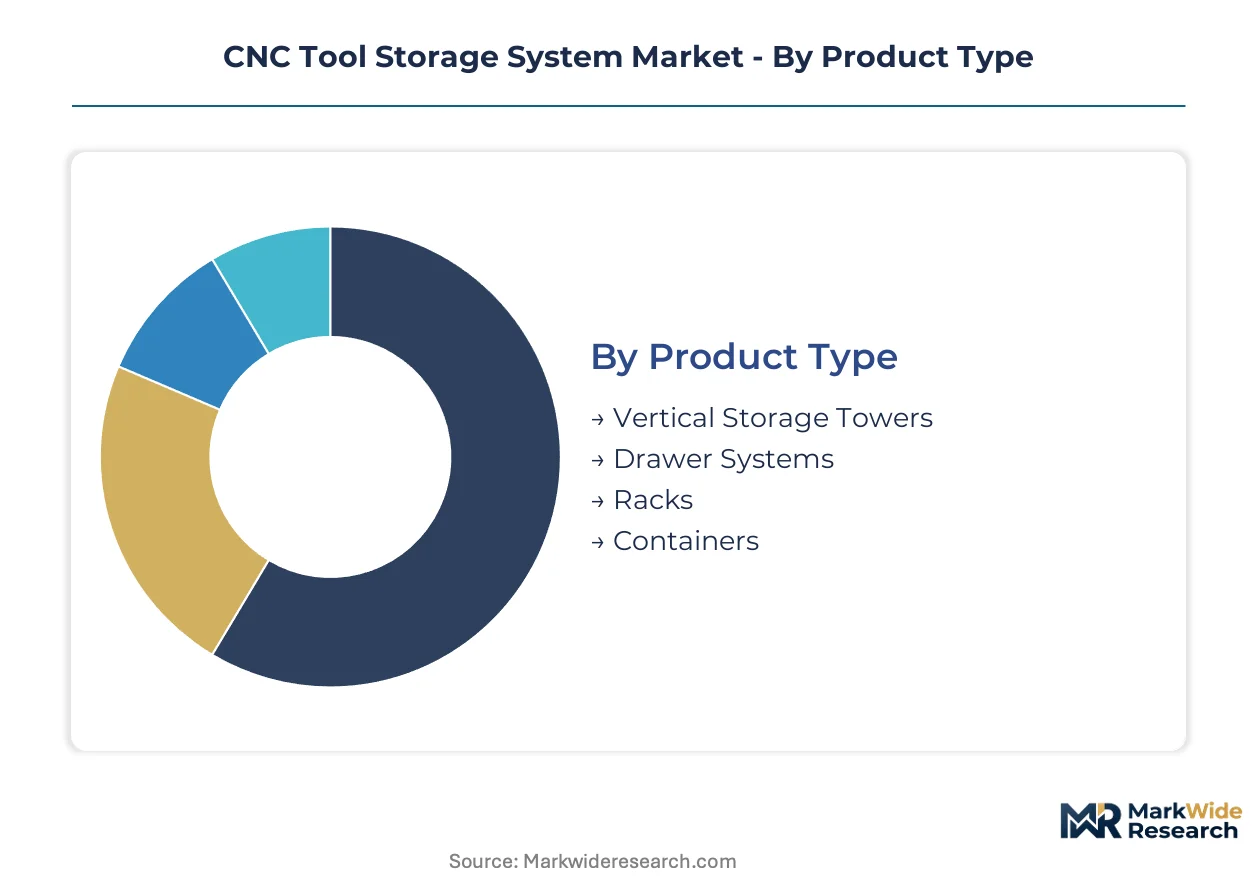
Tool storage purchasing splits sharply between floor-space-constrained aerospace facilities seeking vertical density and general manufacturers prioritizing drawer-system familiarity. Material selection and installation flexibility now determine vendor shortlists as procurement shifts from capital expenditure to operational-technology budgets.
Product Type:
Buyers in this category differentiate primarily by facility footprint constraints and spindle-change frequency requirements.
- Vertical Storage Towers:These engineered enclosures stack tool holders in columnar arrangements with automated retrieval mechanisms. Aerospace manufacturers in Stuttgart and Toulouse specify these for high-mix cells where floor space carries premium lease costs and 85% spindle utilization targets eliminate walking time to distant tool cribs.
- Drawer Systems:Horizontal sliding compartments organize tools by diameter and length in steel-framed cabinets. General manufacturing plants across Ohio and Michigan favor these for their mechanical simplicity and compatibility with existing shop-floor layouts where forklift access is limited.
- Racks:Open-frame shelving accommodates oversized holders and special attachments. Mold-making shops near Boston deploy these for electrode storage where dimensional clearance outweighs security concerns.
- Containers:Portable bins and totes enable point-of-use delivery in cellular layouts. Tier-two automotive suppliers in Alabama use these for sequenced kit delivery to machining centers running scheduled changeovers.
Drawer systems lead volumes today; vertical storage towers are gaining share fastest.
Material:
Cost tier and weight sensitivity separate specification patterns in this category.
- Steel:Cold-rolled and powder-coated alloys form the structural backbone of drawer systems and heavy-duty racks. Volume manufacturers in Indiana and Wisconsin specify these for durability in high-traffic environments where replacement cycles must exceed fifteen years.
- Aluminum:Extruded and anodized profiles reduce enclosure weight by 60% versus steel equivalents. Aerospace final assembly floors at Boeing Charleston and Airbus Mobile prioritize these to meet OSHA ergonomic load limits while maintaining corrosion resistance in climate-controlled hangars.
- Plastic:Injection-molded polymers serve light-duty insert storage and disposable shipping containers. Job shops with limited capital budgets specify these for non-critical tooling where environmental monitoring is unnecessary.
- Composite:Glass-fiber and carbon-fiber reinforced materials eliminate magnetic interference. Medical device manufacturers near Minneapolis specify these for implant machining operations where residual magnetism corrupts titanium surface integrity.
Steel dominates installed base; aluminum is expanding most quickly.
End User:
Application maturity and regulatory exposure drive divergent purchasing sophistication in this category.
- Aerospace:Prime contractors and tier-one subcontractors operate under AS9100 quality mandates requiring full tool traceability. These buyers specify RFID-integrated towers with temperature logging to satisfy FAA audit trails for flight-critical component machining.
- Automotive:High-volume powertrain producers prioritize spindle uptime over enclosure sophistication. OEMs in Detroit and Stuttgart favor drawer systems with simple barcode tracking integrated into existing MES platforms.
- Manufacturing:General industrial machine shops span a wide capability spectrum from prototype to production. These buyers show highest price sensitivity and longest replacement cycles, often deferring storage upgrades until facility renovation triggers.
- Healthcare:Orthopedic and cardiovascular implant manufacturers operate adjacent to cleanroom environments. These facilities specify composite-material storage with chemical resistance to sterilization agents and zero particulate shedding.
Manufacturing represents the largest addressable base; healthcare shows the steepest expansion trajectory.
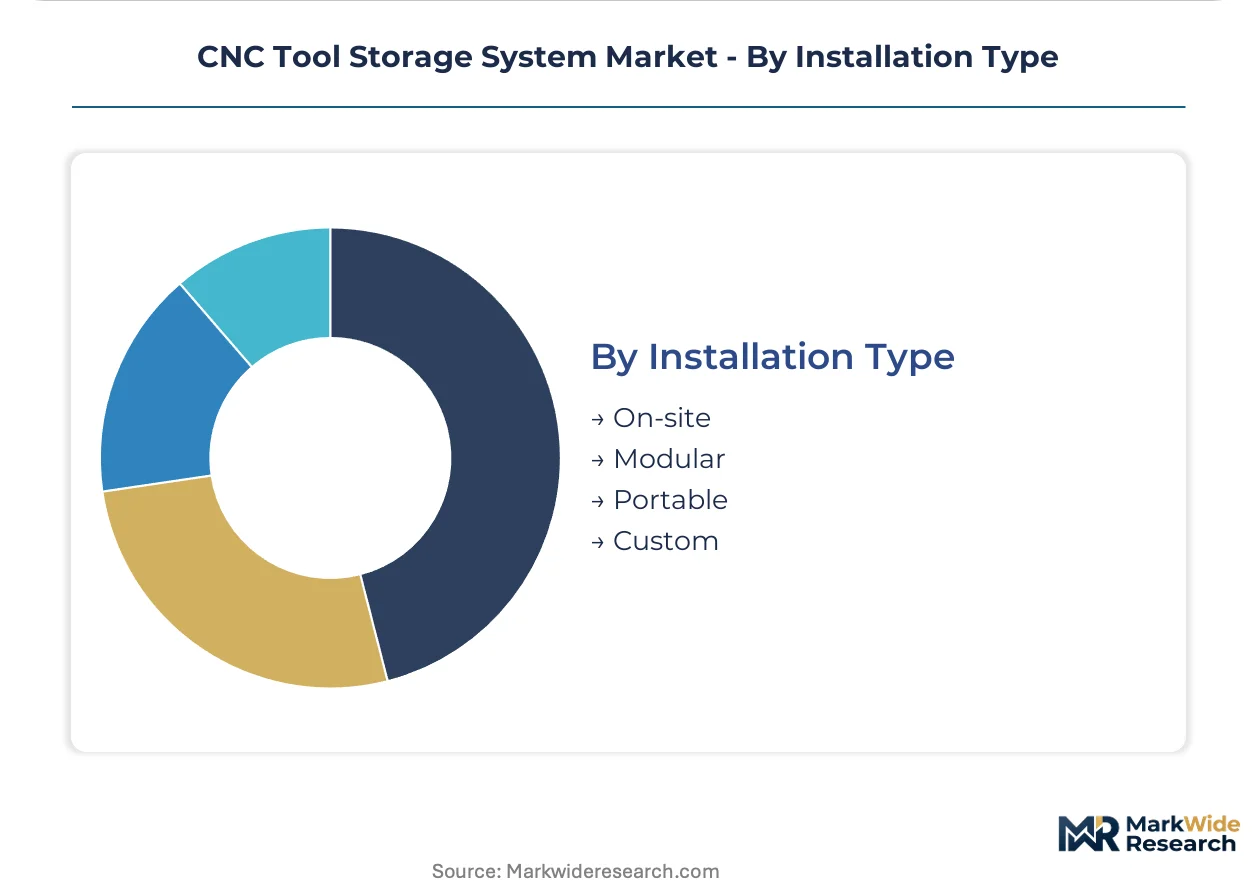
Installation Type:
Capital commitment horizon and facility tenure expectations separate buyers in this category.
- On-site:Permanently anchored systems require concrete footings and electrical rough-in. Major aerospace greenfield projects in South Carolina and Texas specify these for twenty-year operational horizons where relocation probability is negligible.
- Modular:Prefabricated sections bolt together without custom fabrication. Contract manufacturers with three-to-five-year facility leases favor these for depreciation alignment and relocation flexibility.
- Portable:Castor-mounted units relocate via standard pallet jacks. Maintenance departments and tool-room overflow applications specify these for seasonal demand spikes and temporary production lines.
- Custom:Engineered-to-order configurations accommodate non-standard ceiling heights or cleanroom integration. Semiconductor capital equipment suppliers in Oregon and Arizona require these for fab-adjacent machining operations.
On-site installations retain volume leadership; modular configurations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions where CE marking and OSHA compliance costs diverge, with aerospace clusters in Germany and the United States capturing premium specification authority while Chinese manufacturers absorb volume demand through domestic smart factory buildouts.
United States
OSHA lockout-tagout mandates drive replacement cycles for unmonitored tool cribs across Midwest automotive corridors. FAA audit requirements for AS9100-certified subcontractors elevate RFID-integrated towers above commodity alternatives. Boeing's Charleston final assembly floor specifies aluminum-constructed vertical storage to meet ergonomic load limits while maintaining corrosion resistance.
Germany
The Machinery Directive and CE marking framework create compliance barriers protecting domestic producers from Asian import pressure. KBA automotive certification requirements cascade into tool traceability specifications for Stuttgart powertrain suppliers. Baden-Württemberg medical device manufacturers specify composite-material storage systems to preempt audit findings in implant machining operations.
China
Smart factory investments in Jiangsu and Zhejiang provinces outpace domestic supply of certified storage systems, creating import demand for European CE-marked solutions. MIIT industrial internet policies mandate MES integration that favors telemetry-enabled towers over mechanical alternatives. Shanghai aerospace subcontractors deploy vertical storage to achieve 85% spindle utilization targets in high-mix production cells.
Japan
METI productivity mandates accelerate automated tool management adoption among precision component manufacturers. JIS standards for machining center interoperability constrain storage system software architectures. Nagoya automotive suppliers favor drawer systems with simple barcode tracking integrated into existing MES platforms.
India
PLI scheme incentives for precision manufacturing expand domestic machining capacity, creating first-mover advantage for vendors offering localized software support. BIS certification requirements for industrial equipment slow import clearance for non-compliant storage systems. Gujarat and Maharashtra machine tool clusters show highest price sensitivity and longest replacement cycles among major Asian markets.
CNC Tool Storage System Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated machine-tool OEMs capturing specification authority in aerospace while independent fabricators serve price-sensitive general manufacturing. The vendor base concentrates among German and Japanese producers with CE marking expertise, creating tiered access to European regulatory markets. Two strategic archetypes dominate: control-ecosystem integrators embedding storage telemetry within CNC architectures, and modular system builders optimizing for relocation flexibility. Competitive moves center on M&A to acquire software capabilities and strategic partnerships with MES platform vendors.
Among Japanese control-ecosystem specialists, FANUC Corporation and Okuma Corporation exemplify the integration-centric archetype, embedding storage telemetry within proprietary CNC architectures to capture specification authority in brownfield automation projects. DMG Mori represents the German premium-tier model, leveraging established service networks to bundle storage optimization into long-term maintenance contracts. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| DMG Mori |
| Mazak Corporation |
| FANUC Corporation |
| Okuma Corporation |
| Makino |
| Haas Automation |
| JTEKT Corporation |
| Trumpf |
| Amada Machine Tools |
| Others |
Value Chain & Pricing Dynamics
Aerospace spindle utilization mandates above 85% are compressing procurement cycles and forcing supply chains to prioritize telemetry-enabled systems over commodity enclosures, elevating pricing power toward vendors with MES integration capabilities.
Pricing Analysis
Distributor margins compress when machine-tool OEMs bundle storage optimization into long-term maintenance contracts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and software architecture breadth. Pricing pressure stems from steel alloy cost volatility that forces absorption decisions in drawer-system negotiations. General manufacturing job shops in Ohio and Michigan show highest price sensitivity, while AS9100-certified aerospace subcontractors prioritize traceability over unit cost.
Supply Chain Analysis
Refurbishment flows for aluminum tower components concentrate near Stuttgart and Toulouse aerospace clusters, extending asset life cycles. Manufacturing draws from German steel mills, Chinese aluminum extruders, and Japanese precision-machining centers. Single-source vulnerability runs through CE marking expertise concentrated among German and Italian certification bodies. Distribution runs through machine-tool OEM service networks and independent industrial distributors serving regional manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA lockout-tagout mandates and FAA audit requirements are compounding regulatory compliance into a sustained demand driver across North American aerospace and automotive corridors.
For Market Incumbents: Deploy software-defined inventory tracking to capture recurring revenue streams from high-mix aerospace subcontractors. Defensive positioning requires CE marking investment to maintain European market access against Asian import pressure. Backward integration into aluminum extrusion capabilities mitigates raw material cost volatility threatening drawer-system margins. For New Entrants and Emerging Players: Enter via India's PLI scheme for precision manufacturing, where localized software support creates first-mover advantage before domestic supply matures. Composite-material cleanroom storage for Minneapolis and Boston medical device clusters offers penetrable white space with limited incumbent specialization. Go-to-market through direct MES platform partnerships rather than distributor channels. For Investors and Strategic Acquirers: Asymmetric upside sits with modular system builders optimizing for relocation flexibility in contract manufacturing environments. Long-term viability hinges on API breadth and interoperability certification rather than enclosure fabrication scale. Acquisition targets should demonstrate embedded OPC-UA or MQTT protocol capabilities without middleware dependency. Monitor MIIT industrial internet policy enforcement in Jiangsu and Zhejiang as inflection indicator for telemetry-enabled system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Software Architecture Licensing | Enables recurring revenue capture from MES-integrated storage telemetry without hardware shipment. |
| CE Marking Certification Investment | Creates compliance barrier protecting European vendor share against Asian import competition. |
| Composite Material Supply Agreement | Secures non-magnetic, chemically inert inputs for medical device cleanroom storage specifications. |
| Regional Service Network Expansion | Supports localized spare-part availability in India's Gujarat and Maharashtra machine tool clusters. |
| API Development Partnership | Resolves retrofit integration complexity with legacy FANUC and Siemens CNC architectures. |
Study Parameters
Coverage spans Germany, United States, China, and Japan, with primary inputs from each manufacturing corridor. Primary interviews engaged maintenance directors at aerospace tier-one suppliers, plant engineers at automotive powertrain facilities, OEM procurement teams at machine-tool manufacturers, and aftermarket service heads at distributor networks. Secondary validation drew from SEC 10-K filings of listed industrial equipment vendors, customs and trade data for CNC storage system imports, OSHA enforcement databases for lockout-tagout compliance patterns, and MIIT policy bulletins on industrial internet mandates. Bottom-up unit demand estimates triangulated against top-down market sizing from capital expenditure disclosures.
Rate-of-change decomposition separated volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include storage system type, material construction, end-user industry, and installation configuration alongside regional regulatory cluster differentiation. CAGRs derived from regression analysis of historical capital expenditure patterns and forward-looking smart factory investment commitments. Industry-specific inputs incorporated spindle utilization target trajectories and MES platform adoption curves from manufacturing execution system vendors.
The model holds under sustained OSHA and FAA enforcement intensity; deviation in regulatory inspection frequency or CE marking mutual recognition agreements would shift demand timing. Forecasts reflect assumptions regarding aluminum alloy price stability and MES platform consolidation trajectories. Practitioners should monitor MIIT smart factory subsidy disbursement rates and German Machinery Directive amendment timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
COG Bonder Market
Industrial Equipment
Global Twister Winder Market
Industrial Equipment
Soldering Iron Market
Industrial Equipment
Industrial I/O Modules Market
Industrial Equipment
Linear Shaft Motor Market
Industrial Equipment
Plasma Feeder Market
Industrial Equipment
Small Harmonic Reducer Market
Industrial Equipment
Seal Inspection Equipment Market
Industrial Equipment
North America Industrial Embedded Systems Market
Industrial Equipment
Digital Tachometer Market
Industrial Equipment
Global Liquid Handling Systems Market
Industrial Equipment
Magnetizing Equipment Market
Industrial Equipment
Global Flat Glass Tempering Machines Market
Industrial Equipment
Global Abrasive Waterjet Cutting Machine Market
Industrial Equipment
North America Fans and Blowers Market
Industrial Equipment
Grading and Batching Systems Market