
 Rotary Scroll Air Compressor Market | 2026-2036
Rotary Scroll Air Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Rotary Scroll Air Compressor Market Analysis
Market Dynamics
A widening capability gap between capital-heavy integrated manufacturers and asset-light assemblers is bifurcating competitive returns across the rotary scroll air compressor landscape. Atlas Copco leverages captive component foundries and in-house airend production to sustain margin capture across European industrial clusters. Ingersoll Rand anchors its position through dense aftermarket service networks spanning North American manufacturing corridors. Emerson differentiates via electromechanical integration expertise that bridges compressor hardware with building automation systems.
Product Architecture and Segment Structure
A rotary scroll air compressor generates compressed air through orbiting spiral elements that trap and reduce gas volume without piston reciprocation, delivering pulsation-free output typically below 30 horsepower with noise levels under 65 decibels. Oil-free scroll designs achieve ISO 8573-1 Class Zero certification through tip-seal geometries and precision-machined aluminum or cast-iron scroll sets, serving pharmaceutical cleanrooms and semiconductor fabs where lubricant contamination risks batch integrity. Oil-lubricated compressors still dominate installed base value across general manufacturing, though oil-free units command premium positioning in food and beverage processing where FDA and EFSA contact-compliance requirements intensify. Variable speed drive technology captures the fastest expansion trajectory among technology segments, as magnetic bearing controls and permanent magnet motors trim energy consumption during partial-load operation in automotive assembly plants.
Regulatory Environment and Strategic Outlook
EPA emissions guidelines and DOE minimum efficiency standards in the United States, alongside EU Ecodesign regulations and F-Gas phase-down mandates under the European Green Deal, compel compressor OEMs to redesign scroll packages for lower refrigerant leakage and higher specific energy efficiency ratios. China's GB standards on compressor energy labeling and India's BIS certification requirements for pneumatic equipment create layered compliance thresholds that favor manufacturers with multi-jurisdiction testing infrastructure. Stakeholders must monitor how refrigerant transition timelines and carbon border adjustment mechanisms reshape sourcing economics for scroll sets and drive motors.
Market Dynamics
Variable speed drive technology is compressing the installed base of fixed-speed rotary scroll compressors across automotive and electronics manufacturing clusters, forcing incumbent suppliers to recalibrate production footprints and service architectures around electromechanical integration rather than standalone hardware sales.
Growth Catalysts
- ISO 8573-1 Class Zero mandates:Food and beverage packaging lines in Germany and Japan face tightening contamination standards that eliminate oil-lubricated alternatives from cleanroom-adjacent processes.
- Permanent magnet motor advances:Magnetic bearing controls enable partial-load efficiency gains that slash energy consumption during intermittent pneumatic demand cycles.
- Semiconductor fab expansion:Cleanroom-grade oil-free scroll units capture specification wins in wafer fabrication facilities where lubricant vapor risks billion-dollar batch contamination.
Market Restraints
- Aluminum scroll set cost volatility:Precision-machined orbiting elements depend on aerospace-grade aluminum billet supplies subject to tariff-driven price swings.
- Tip-seal material concentration:High-performance polymer seal formulations rely on a narrow supplier base concentrated in German and Japanese specialty chemical producers.
- Power electronics import dependence:Variable frequency drive assemblies for integrated compressor-motor systems face concentrated sourcing from East Asian semiconductor foundries.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO compliance timelines and FDA inspection readiness requirements create specification pull for oil-free Class Zero compressors in active pharmaceutical ingredient production.
- Electromechanical-BAS convergence:Integration of compressor telemetry with building automation systems opens specification channels through MEP contractors rather than traditional industrial distributors.
- Hydrogen electrolyzer auxiliary demand:Oil-free scroll compressors serve electrolyzer balance-of-plant requirements for contaminant-free hydrogen compression in emerging European green hydrogen clusters.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous EPA, DOE, and EU Ecodesign compliance testing stretches engineering bandwidth and delays product launch windows.
- Scroll set machining precision:Sub-micron tolerance requirements for orbiting spiral profiles limit qualified supplier pools and constrain capacity scaling.
- Legacy pneumatic infrastructure integration:Variable speed compressor retrofits face control protocol mismatches with existing fixed-speed header systems in mature manufacturing plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotary Scroll Air Compressor Market |
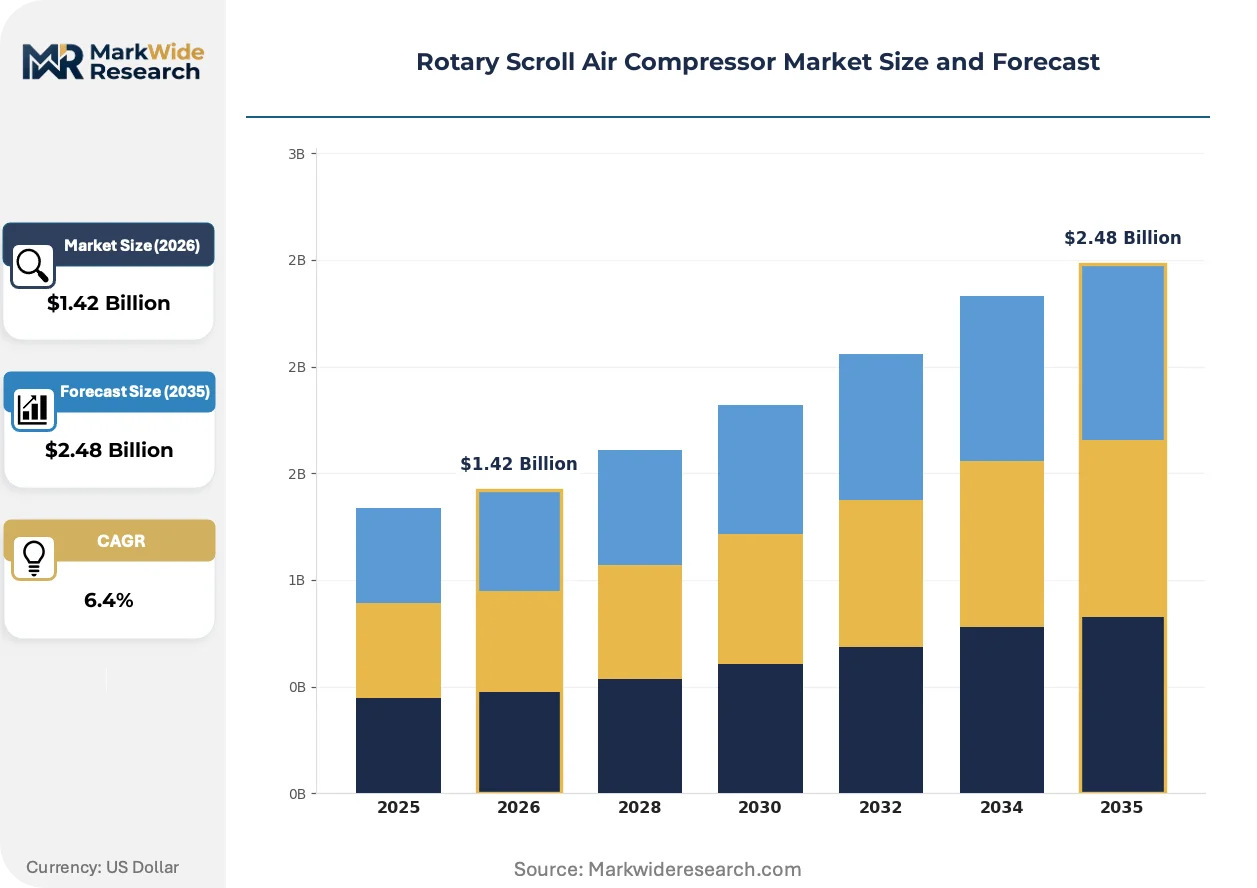
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Oil-Free Compressors, Oil-Lubricated Compressors, Scroll Compressors, Rotary Compressors End User: Manufacturing, Healthcare, Food & Beverage, Textile Application: Pneumatic Tools, Automotive, HVAC Systems, Industrial Cleaning Technology: Variable Speed Drive, Fixed Speed Drive, Direct Drive, Belt Drive |
| Companies Covered | Kaeser Compressors, Danfoss, Atlas Copco, Boge Compressors, Gardner Denver, Ingersoll Rand, Emerson, Hitachi, Sullair, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotary Scroll Air Compressor Market Emerging Trajectories
Permanent magnet motor and magnetic bearing architectures are rewriting competitive differentiation in sub-30 horsepower compressed air, collapsing the historical separation between compressor hardware and power electronics while elevating energy efficiency from specification checkbox to primary procurement criterion.
Integrated variable speed drive packages is displacing conventional fixed-speed scroll compressors across automotive painting operations in China and South Korea. Tier-one suppliers specify permanent magnet motor architectures to trim energy consumption during partial-load conditions. This technology shift is compressing margins for assemblers lacking in-house motor and drive production capabilities.
F-Gas phase-down mandates under the EU Green Deal compel compressor OEMs to redesign scroll packages for lower refrigerant leakage in heat pump and climate control applications. Industrial refrigeration OEMs face reformulation timelines that compress product development cycles. Oil-free scroll designs with hermetic sealing architectures capture specification preference in food retail and cold chain logistics.
Compressed air-as-utility contracting is fragmenting traditional equipment ownership models across German and Japanese manufacturing corridors. Automotive assemblers now procure pneumatic energy by the cubic meter through service agreements that bundle hardware, maintenance, and energy optimization. This unbundling of capital expenditure from operational responsibility favors suppliers with captive service infrastructure and real-time telemetry platforms.
Rotary Scroll Air Compressor Market Segmentation
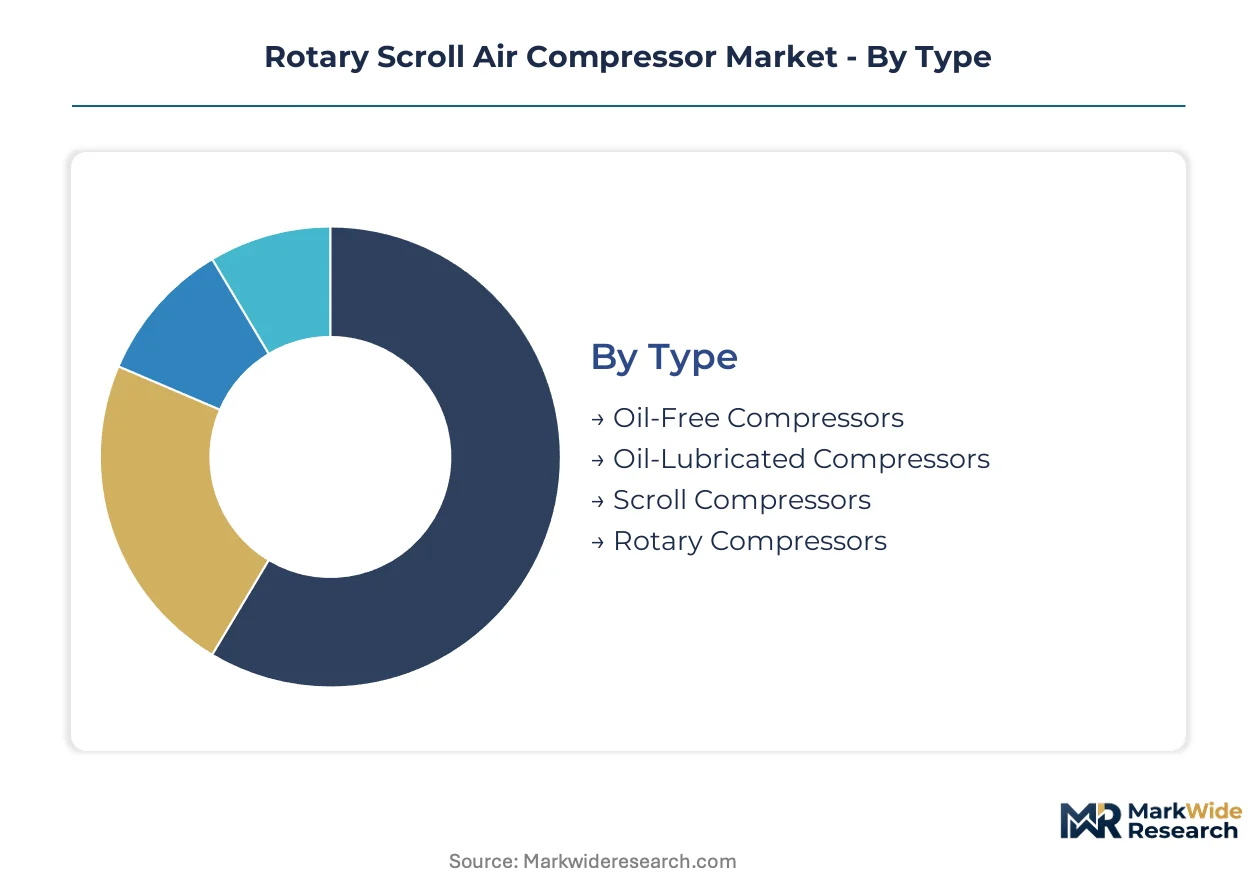
Rotary scroll air compressor procurement patterns diverge sharply across lubrication regimes, end-use contamination tolerances, and drive architectures. Margin capture concentrates where ISO certification requirements intersect with electromechanical integration capabilities.
Type:
Premium positioning clusters around contamination-free designs, while cost-driven replacement cycles sustain volume in conventional lubricated formats.
- Oil-Free Compressors:Tip-seal geometries and precision-machined aluminum scroll sets achieve ISO 8573-1 Class Zero certification. Semiconductor fabs in Germany and Japan specify these units where lubricant vapor risks billion-dollar batch contamination, tightening supplier qualification thresholds.
- Oil-Lubricated Compressors:Cast-iron scroll sets with integrated lubrication circuits dominate general manufacturing installed base value. Automotive component plants in China and South Korea drive replacement demand as legacy units age out of service intervals.
- Scroll Compressors:Orbiting spiral elements deliver pulsation-free output below 30 horsepower with noise levels under 65 decibels.
- Rotary Compressors:Broader category encompassing screw and vane architectures alongside scroll designs in cross-shopping evaluations.
Oil-lubricated compressors hold installed capacity. Oil-free designs are rotating up the share rankings.
End User:
Regulatory compliance intensity and batch integrity exposure determine specification premiums across customer categories.
- Manufacturing:General industrial pneumatic demand spans assembly, material handling, and machine tool actuation. Tier-one automotive suppliers in South Korea specify variable speed packages to trim energy consumption during partial-load painting cycles.
- Healthcare:Hospital surgical suites and laboratory automation require Class Zero oil-free output. FDA inspection readiness protocols at Indian pharmaceutical API producers create specification pull for certified compressor packages.
- Food & Beverage:EFSA contact-compliance requirements intensify in German packaging lines.
- Textile:Air-jet looms and pneumatic material handling drive steady demand in South Asian spinning clusters.
Manufacturing anchors volume procurement. Healthcare is climbing the fastest as certification requirements harden.
Application:
Integration depth with host equipment and duty cycle predictability shape technology selection across use cases.
- Pneumatic Tools:Intermittent demand profiles favor variable speed drive architectures that modulate output to actual consumption rather than venting excess pressure. Construction and maintenance workshops across Japanese industrial corridors specify compact scroll units for portability.
- Automotive:Painting operations in China demand contaminant-free compressed air with precise dew point control. Tier-one suppliers bundle compressor specifications into turnkey finishing line contracts, elevating supplier qualification barriers.
- HVAC Systems:Heat pump and climate control applications face EU F-Gas phase-down mandates.
- Industrial Cleaning:Dry ice blasting and pneumatic surface preparation require sustained pressure delivery.
Pneumatic tools retain broadest deployment. Automotive is gaining share fastest through integrated line specifications.
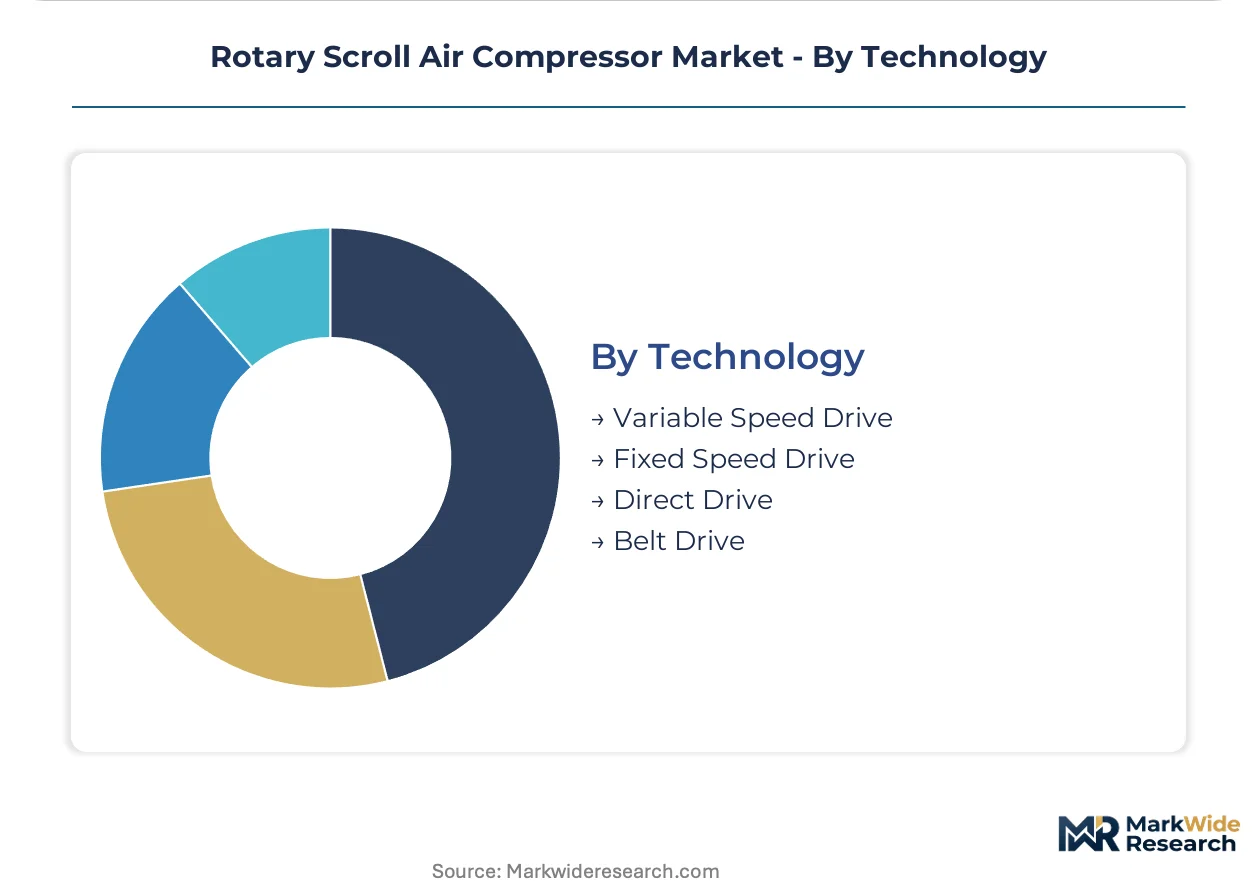
Technology:
Electromechanical convergence is collapsing the historical separation between compressor hardware and power electronics.
- Variable Speed Drive:Permanent magnet motors with magnetic bearing controls enable partial-load efficiency gains that slash energy consumption. Chinese automotive painting operations specify these packages as primary procurement criterion, compressing margins for assemblers lacking in-house motor production.
- Fixed Speed Drive:Conventional induction motor architectures persist in cost-sensitive replacement cycles. Mature manufacturing plants in Germany face control protocol mismatches when retrofitting legacy pneumatic headers.
- Direct Drive:Eliminates belt maintenance and alignment drift in continuous-duty installations.
- Belt Drive:Mechanical speed reduction suits intermittent duty with lower capital outlay.
Fixed speed drive holds legacy installed base. Variable speed drive represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese industrial clusters where ISO 8573-1 Class Zero certification commands substantial premiums, while Chinese manufacturing corridors compete on variable speed drive integration cost. This asymmetry shapes regional specialization patterns across the rotary scroll air compressor landscape.
Germany
Food and beverage packaging lines in Bavaria and Baden-Württemberg drive oil-free compressor specification as EFSA contact-compliance requirements intensify. EU Ecodesign regulations and F-Gas phase-down mandates under the European Green Deal compel OEMs to redesign scroll packages for higher efficiency. Stuttgart's automotive supplier ecosystem specifies integrated variable speed packages for painting operations.
China
Automotive assembly plants in Shanghai and Guangdong province anchor demand for permanent magnet motor architectures that trim energy consumption during partial-load cycles. GB standards on compressor energy labeling create compliance thresholds that favor manufacturers with multi-jurisdiction testing infrastructure. Tier-one suppliers in the Yangtze River Delta bundle compressor specifications into turnkey finishing line contracts.
Japan
Semiconductor fabrication facilities in Kyushu and the Kanto region specify Class Zero oil-free scroll units where lubricant vapor risks billion-dollar batch contamination. METI efficiency guidelines and JIS standards tighten supplier qualification thresholds for cleanroom-grade equipment. Yokohama's precision machinery corridor concentrates tip-seal material suppliers subject to aerospace-grade aluminum billet price volatility.
United States
Pharmaceutical API producers in New Jersey and North Carolina face FDA inspection readiness protocols that create specification pull for certified oil-free compressor packages. EPA emissions guidelines and DOE minimum efficiency standards compel scroll package redesign for lower refrigerant leakage. Houston's petrochemical corridor drives aftermarket service network density for legacy installed base maintenance.
India
Active pharmaceutical ingredient manufacturing in Maharashtra and Gujarat generates CDSCO compliance timelines that accelerate Class Zero compressor adoption. BIS certification requirements for pneumatic equipment create layered compliance thresholds. Pune's automotive component cluster specifies variable speed retrofits that face control protocol mismatches with existing fixed-speed header systems.
Rotary Scroll Air Compressor Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the rotary scroll air compressor market. Integrated manufacturers with captive component foundries capture margin premiums in certification-intensive segments, while asset-light assemblers compete on volume in replacement cycles. Three archetypes dominate: electromechanical integrators bridging compressor hardware with building automation systems; service-intensive operators anchoring position through dense aftermarket networks; and precision machining specialists controlling sub-micron tolerance scroll set production. Competitive moves concentrate on strategic partnerships for electromechanical integration and geographic expansion into pharmaceutical manufacturing corridors.
Among European-based industrial conglomerates, Atlas Copco and Ingersoll Rand occupy positions spanning integrated manufacturing and service infrastructure archetypes. Gardner Denver represents the precision-engineering tier with compressed air system specialization. Japanese industrial groups including Hitachi and Sullair exemplify electromechanical integration capabilities. Emerson anchors the electromechanical-BAS convergence vector through building automation expertise. Kaeser Compressors, Boge Compressors, and Danfoss sit within distinct regional specialization patterns across German engineering corridors and refrigerant system integration.
| Leading Market Players |
|---|
| Kaeser Compressors |
| Danfoss |
| Atlas Copco |
| Boge Compressors |
| Gardner Denver |
| Ingersoll Rand |
| Emerson |
| Hitachi |
| Sullair |
| Others |
Supply Flow & Price Mechanics
Long-term service contracting locks in both supply access and price visibility for rotary scroll air compressor buyers, as German automotive assemblers and Japanese semiconductor fabs shift from capital purchase to cubic-meter-based pneumatic energy procurement. This contract-structure evolution compresses spot-market pricing power while elevating captive service infrastructure as the primary margin capture mechanism.
Pricing Analysis
Configured-to-order pricing spreads 25-40% above standard catalog pricing for ISO 8573-1 Class Zero certified packages. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and electromechanical integration depth. Cost compression in fixed-speed replacement tiers intensifies as Chinese variable speed drive assemblers compete on motor integration cost. General manufacturing procurement teams exhibit highest price sensitivity, while pharmaceutical cleanroom operators accept substantial premiums for batch-integrity assurance.
Supply Chain Analysis
Aerospace-grade aluminum billet supply from German and Japanese specialty metal producers constitutes a critical chokepoint for precision scroll set manufacturing. Tip-seal polymer formulations draw from concentrated German and Japanese chemical suppliers, while power electronics assemblies hinge on East Asian semiconductor foundry output. Single-source vulnerability in magnetic bearing controls exposes integrated compressor-motor systems to geographic concentration risk. Distribution runs through industrial distributor networks in mature markets and direct OEM-to-contractor channels in emerging manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sub-micron machining capability for orbiting scroll profiles represents the binding constraint on capacity scaling, as qualified supplier pools remain narrow across the rotary scroll air compressor landscape. This precision-manufacturing scarcity concentrates margin capture among integrated producers while limiting expansion velocity for asset-light assemblers.
For Market Incumbents: Secure captive supply of aerospace-grade aluminum billet through backward integration or long-term offtake agreements with German and Japanese specialty metal producers. Expand in-house permanent magnet motor production capabilities to defend against margin compression from Chinese electromechanical integrators. Prioritize certification investment in multi-jurisdiction EPA, DOE, and EU Ecodesign compliance to extend qualification lead times against emerging competitors. For New Entrants and Emerging Players: Differentiate on electromechanical-BAS integration capabilities that bypass traditional industrial distributor channels through MEP contractor specifications. Target Indian pharmaceutical manufacturing corridors where CDSCO compliance timelines and FDA inspection readiness create specification pull for Class Zero compressors. Pursue hydrogen electrolyzer auxiliary demand in European green hydrogen clusters as a whitespace application with limited incumbent penetration. For Investors and Strategic Acquirers: Precision machining specialists with sub-micron scroll set production capabilities offer the most defensible acquisition profile within a five-to-ten-year viability window. Monitor F-Gas phase-down mandate implementation velocity as the primary inflection indicator for refrigerant-system integration value creation. Favor targets with established multi-jurisdiction testing infrastructure over pure-play hardware assemblers lacking electromechanical integration depth.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Billet Supply | Secures aerospace-grade material access against tariff-driven price volatility from German and Japanese producers. |
| Permanent Magnet Motor Production Expansion | Captures variable speed drive margins that Chinese automotive painting operations now specify as primary procurement criterion. |
| Multi-Jurisdiction Certification Investment | Compresses product launch windows for EPA, DOE, and EU Ecodesign simultaneous compliance testing. |
| Electromechanical-BAS Integration Development | Opens specification channels through MEP contractors rather than traditional industrial distributors in German manufacturing corridors. |
| Hydrogen Electrolyzer Auxiliary Market Entry | Serves balance-of-plant requirements for contaminant-free hydrogen compression in emerging European green hydrogen clusters. |
Methodological Framework
The analysis maps oil-free and oil-lubricated compressor architectures, variable speed and fixed speed drive technologies, and end-use applications across healthcare, food and beverage, and manufacturing sectors, each validated through primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and MEP contractors. Secondary validation draws from SEC filings, customs and trade data, EPA and DOE regulatory dockets, and EU Ecodesign implementation reports. Bottom-up unit economics triangulate against top-down market sizing across the projection horizon.
Consistency checks against external benchmarks validated volume and value outputs for segment-level CAGRs derived from installed base replacement cycles, technology displacement trajectories, and regulatory compliance timelines. Segmentation dimensions modeled include lubrication regime, drive architecture, end-use contamination tolerance, and regional regulatory cluster. Forecast inputs incorporate semiconductor fab expansion pipelines, automotive painting line retrofit schedules, and pharmaceutical manufacturing capacity buildouts without year-specific references.
Decision-makers should treat outputs as directional under assumptions of steady regulatory enforcement intensity and aluminum billet supply continuity; material deviation in either would warrant model refresh. Revision becomes warranted when F-Gas phase-down implementation velocity or magnetic bearing control sourcing concentration crosses thresholds that alter competitive positioning dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Servo Presses Market
Industrial Equipment
Linear Shaft Motor Market
Industrial Equipment
Battery Spot Welder Market
Industrial Equipment
Pin Marking Machine Market
Industrial Equipment
Industrial Lasers Systems Market
Industrial Equipment
Europe Ceramic Roller Bearings Market
Industrial Equipment
Actuators Market
Industrial Equipment
Industrial Vacuum Evaporation Systems Market
Industrial Equipment
Photography Panoramic Tripod Heads Market
Industrial Equipment
Global Thick Film Heater Market
Industrial Equipment
North America Industrial Embedded Systems Market
Industrial Equipment
Global Strain Wave Gearing Devices Market
Industrial Equipment
Global Special Purpose Machines Market
Industrial Equipment
Press-Insertion Systems Market
Industrial Equipment
Industrial Marking Equipment Market
Industrial Equipment
Contour Measuring Machines Market