
 Global Laboratory Vacuum Pumps Market | 2026-2036
Global Laboratory Vacuum Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Laboratory Vacuum Pumps Market Foresight
German pump manufacturing clusters is rebalancing capacity toward oil-free architectures as semiconductor fabs demand cleaner process environments. Atlas Copco AB leverages its compressor heritage to dominate rotary vane and scroll pump portfolios across European research hubs. Agilent Technologies Inc. anchors its position through deep integration with analytical instrument ecosystems, while Edwards Vacuum competes on magnetically levitated turbo molecular systems for high-vacuum physics applications.
Laboratory vacuum pumps are electromechanical devices that evacuate gases from sealed chambers to achieve pressures ranging from rough vacuum through ultra-high vacuum, serving analytical instrumentation, material synthesis, and contamination-sensitive manufacturing processes. Diaphragm vacuum pumps lead the product type landscape due to their oil-free operation and compatibility with aggressive solvents in pharmaceutical research, whereas scroll vacuum pumps represent the fastest-growing category as semiconductor fabrication demands escalate for particle-free pumping. Dry vacuum technology captures widening margin pools as environmental regulations tighten disposal protocols for oil-sealed systems across biotechnology firms and chemical processing units.
The EPA enforces emissions standards that restrict hydrocarbon discharge from wet vacuum technology systems in U.S. laboratories, while REACH and the EU Green Deal mandate material traceability and energy efficiency disclosures for pumps sold into European academic research institutes. China's SAMR implements GB standards for electromagnetic compatibility and safety certification that govern import access for foreign manufacturers. Stakeholders must monitor how evolving F-Gas Regulation amendments in Europe and state-level efficiency mandates in California reshape product design roadmaps and regional sourcing strategies.
Market Dynamics
Dry vacuum architectures are displacing oil-sealed systems as semiconductor fabs and pharmaceutical cleanrooms impose particle-free process mandates. This technology migration concentrates procurement power among buyers with stringent contamination protocols.
Growth Catalysts
- Semiconductor cleanroom expansion:Domestic chip manufacturers in China are scaling operations around Shanghai and Suzhou, requiring oil-free pumping systems for wafer processing.
- REACH compliance deadlines:ECHA enforcement of material traceability and energy efficiency disclosures accelerates replacement cycles for legacy laboratory equipment across European academic institutes.
- EPA emissions enforcement:Hydrocarbon discharge restrictions from wet vacuum technology systems compel U.S. biotechnology firms to upgrade to dry architectures.
Market Restraints
- Rare earth magnet supply concentration:Magnetically levitated turbo molecular pumps depend on neodymium supply chains concentrated in China, creating input cost volatility and geopolitical exposure.
- Technical limitation in aggressive chemistries:Dry scroll pumps face accelerated wear from hydrogen fluoride and chlorine trifluoride in etching applications, limiting penetration in certain semiconductor process steps.
- F-Gas Regulation friction:Evolving EU amendments to fluorinated gas restrictions complicate product design roadmaps for manufacturers serving European research markets.
Strategic Opportunities
- India biotech corridor emergence:CDSCO regulatory harmonization and PLI scheme incentives for pharmaceutical manufacturing create underpenetrated demand for analytical-grade vacuum systems in Hyderabad and Bengaluru.
- EU AI Act automation mandate:Laboratory equipment intelligence requirements open white space for pump-integrated sensor platforms and predictive maintenance modules.
- Convergence of vacuum and IoT:Remote monitoring capabilities combined with dry pump architectures enable outcome-based service models for distributed research networks.
Industry Challenges
- Turbomolecular bearing specialist scarcity:Magnetically levitated system maintenance requires rare expertise in active magnetic bearing calibration, constraining service network expansion.
- Legacy system integration friction:Retrofitting dry pumps into existing oil-sealed infrastructure demands custom manifold adaptations and control system compatibility workarounds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Laboratory Vacuum Pumps Market |
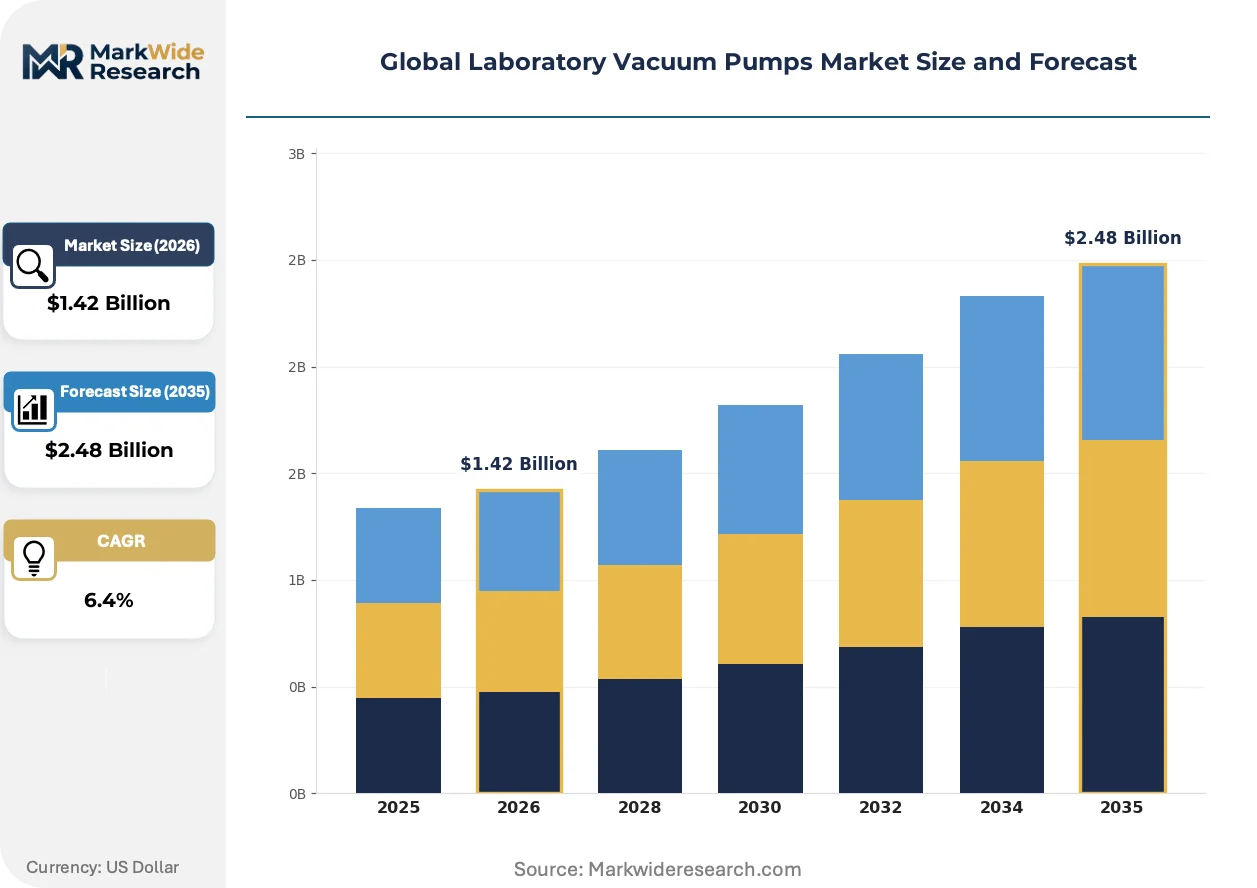
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diaphragm Vacuum Pumps, Rotary Vane Pumps, Piston Vacuum Pumps, Scroll Vacuum Pumps, Turbo Molecular Pumps, Liquid Ring Vacuum Pumps Technology: Dry Vacuum Technology, Wet Vacuum Technology, Oil-Sealed Technology, Magnetically Levitated Technology, Membrane Technology, Ejector Technology Application: Pharmaceutical Research, Chemical Analysis, Material Testing, Environmental Monitoring, Food Processing, Semiconductor Fabrication End User Industry: Academic Research Institutes, Biotechnology Firms, Environmental Labs, Food & Beverage Plants, Semiconductor Manufacturers, Chemical Processing Units |
| Companies Covered | Atlas Copco AB, Agilent Technologies Inc., Edwards Vacuum, Busch Vacuum Solutions, Pfeiffer Vacuum, ULVAC, Inc., VACUUBRAND, KNF Group, Welch Vacuum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Laboratory Vacuum Pumps Market Shifts & Advancements
Technology trajectories in laboratory vacuum systems center on contamination elimination, regulatory automation, and procurement rationalization. These forces compress product lifecycles while elevating service content.
Scroll vacuum technology is consolidating its position in semiconductor fabrication and pharmaceutical synthesis applications. fabs in Germany and the United States are specifying oil-free scroll systems for deposition and etching processes. This adoption pace is compressing rotary vane market share in high-value cleanroom segments.
F-Gas Regulation amendments in Europe are tightening refrigerant and sealing material requirements for laboratory equipment. ECHA enforcement extends to pump energy efficiency disclosures and end-of-life material recovery protocols. Semiconductor research facilities in the Netherlands and France face accelerated compliance timelines for existing installed bases.
Consolidated procurement frameworks are displacing decentralized laboratory purchasing in multinational pharmaceutical organizations. Centralized technical standards and preferred vendor agreements are compressing supplier diversity in analytical instrumentation ecosystems. This concentration is most visible in German and U.S. research hubs where procurement functions have merged under global category management.
Global Laboratory Vacuum Pumps Market Segmentation
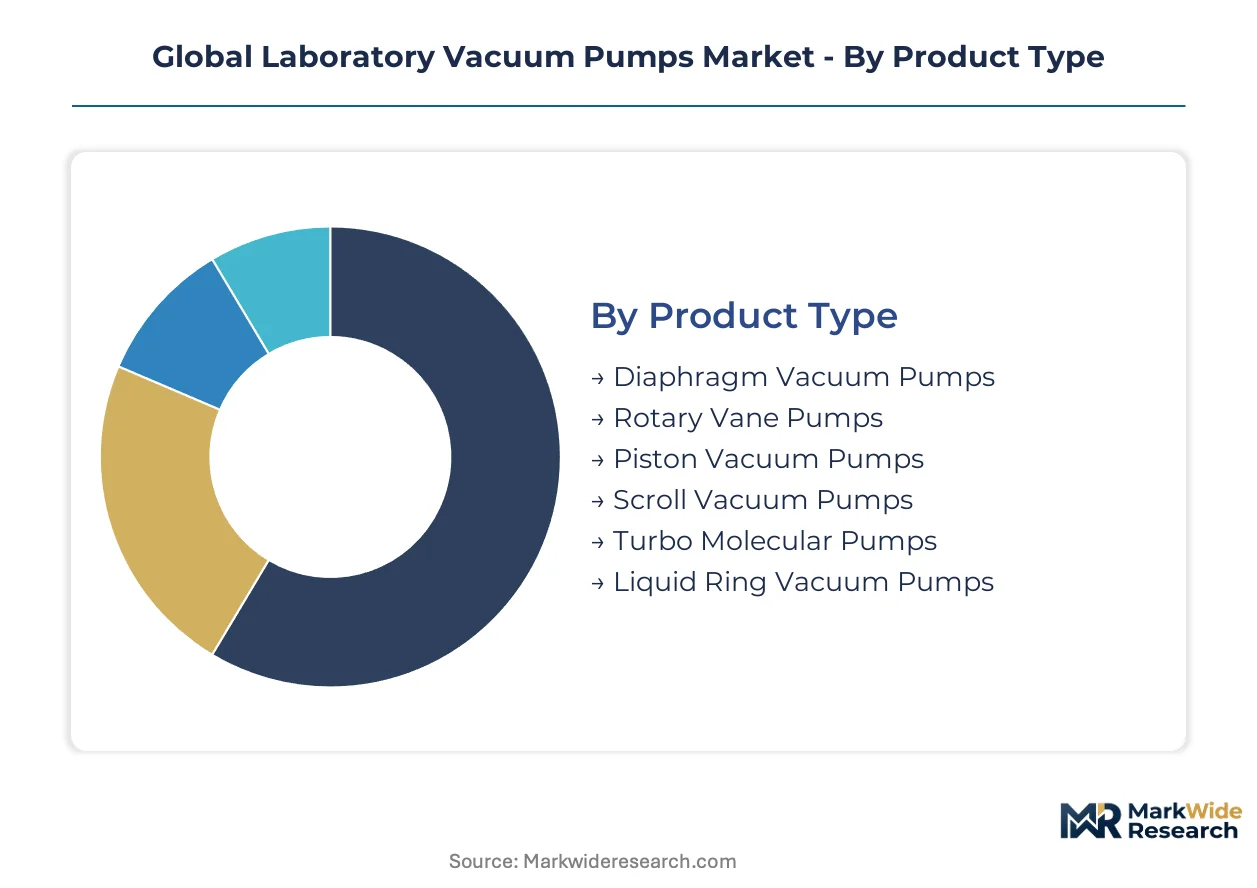
Laboratory vacuum pump procurement hinges on contamination tolerance, pressure regime requirements, and integration complexity with existing analytical infrastructure. Technology selection cascades through application specifications, end-user compliance burdens, and total cost of ownership calculations across multi-year research cycles.
Product Type:
Technical specifications around lubrication architecture and ultimate vacuum capability determine pump selection for aggressive chemistries versus ultra-high vacuum physics.
- Diaphragm Vacuum Pumps:These oil-free systems employ oscillating elastomer membranes to achieve rough vacuum levels without hydrocarbon contamination. Pharmaceutical synthesis operations in Germany and the United States specify diaphragm architectures for solvent recovery applications where product purity is non-negotiable.
- Scroll Vacuum Pumps:Interleaved spiral orbiting mechanisms deliver particle-free pumping without sealing fluids. Semiconductor fabrication facilities in Shanghai and Suzhou are scaling scroll deployments for wafer processing steps where metallic contamination risks disqualify oil-sealed alternatives.
- Rotary Vane Pumps:Eccentrically mounted vanes in oil-sealed chambers remain cost-effective for general laboratory roughing duties.
- Piston Vacuum Pumps:Reciprocating piston mechanisms handle high gas loads in industrial laboratory settings.
- Turbo Molecular Pumps:High-speed rotors on magnetic bearings achieve ultra-high vacuum for surface science and mass spectrometry.
- Liquid Ring Vacuum Pumps:Sealing liquid rings manage condensable vapor loads in chemical processing laboratories.
Diaphragm vacuum pumps lead on scale; scroll vacuum pumps lead on momentum.
Technology:
Cost tier differentiation separates premium dry architectures from maintenance-intensive wet systems in procurement evaluations.
- Dry Vacuum Technology:Oil-free pumping mechanisms eliminate hydrocarbon backstreaming and disposal liabilities. REACH compliance deadlines across European academic institutes are accelerating replacement of legacy wet systems with dry architectures to satisfy material traceability mandates.
- Wet Vacuum Technology:Oil-sealed and liquid-sealed systems retain installed base dominance in budget-constrained settings.
- Oil-Sealed Technology:Rotary vane and piston configurations with mineral or synthetic lubricants dominate legacy infrastructure.
- Magnetically Levitated Technology:Active magnetic bearing suspensions eliminate mechanical contact for extreme high-vuum applications.
- Membrane Technology:Polymer barrier separation enables corrosion-resistant operation in halogenated chemistry environments.
- Ejector Technology:Venturi-based gas compression serves specialized venting and roughing applications without moving parts.
Dry vacuum technology commands premium positioning; magnetically levitated systems claim steepest expansion trajectory.
Application:
Customer type clustering reveals divergent performance requirements between regulated pharmaceutical environments and emerging semiconductor cleanrooms.
- Semiconductor Fabrication:Deposition, etching, and lithography processes demand particle-free pumping at pressures spanning rough to high vacuum. Domestic chip manufacturers in China's Yangtze River Delta are driving specification tightening for oil-free scroll and dry multi-stage systems.
- Pharmaceutical Research:Active pharmaceutical ingredient synthesis and analytical method development require solvent-compatible, contamination-free vacuum. FDA and EMA audit readiness pressures are consolidating procurement around validated dry pump platforms with documented material compliance.
- Chemical Analysis:Mass spectrometry and chromatography systems integrate dedicated roughing and high-vacuum pumps.
- Material Testing:Degassing, impregnation, and thin-film characterization employ varied vacuum regimes.
- Environmental Monitoring:Air sampling and emissions testing applications prioritize portability and chemical resistance.
- Food Processing:Freeze-drying and packaging operations utilize hygienic-design vacuum systems.
Pharmaceutical research anchors current revenue; semiconductor fabrication is gaining share fastest.
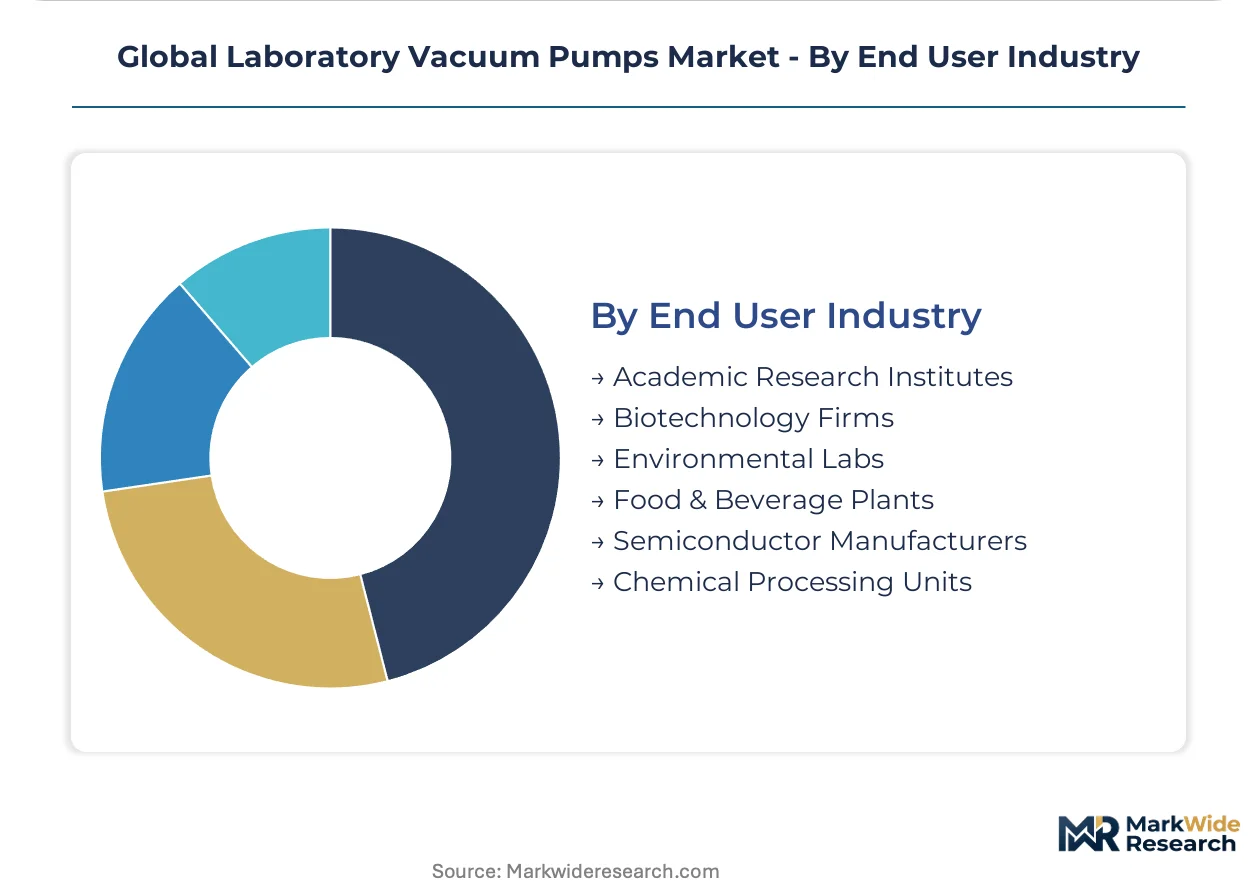
End User Industry:
Supply concentration among multinational equipment vendors shapes procurement access for fragmented versus consolidated buyer segments.
- Semiconductor Manufacturers:Integrated device foundries and memory fabricators operate captive vacuum engineering teams with standardized platform requirements. EPA emissions enforcement and F-Gas Regulation amendments are disqualifying wet pump architectures from new fab specifications in the United States and Europe.
- Biotechnology Firms:Cell culture, fermentation, and downstream processing operations require sterile, oil-free vacuum for product safety. CDSCO regulatory harmonization in India is opening procurement channels for analytical-grade systems in Hyderabad and Bengaluru biotech corridors.
- Academic Research Institutes:University laboratories balance capital constraints against multi-disciplinary application diversity.
- Environmental Labs:Contract testing facilities prioritize reliability and regulatory compliance documentation.
- Food & Beverage Plants:Industrial-scale freeze-drying and modified atmosphere packaging drive robust-duty pump specifications.
- Chemical Processing Units:Petrochemical and specialty chemical R&D facilities manage corrosive vapor loads with material-engineered pump selections.
Semiconductor manufacturers dominate capital deployment; biotechnology firms represent the most dynamic demand frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redistributing laboratory vacuum pump procurement as REACH compliance costs in Europe and EPA enforcement in the United States widen the cost-of-compliance gap against emerging manufacturing zones in Asia. Production migration follows semiconductor fabrication expansion and pharmaceutical research clustering.
United States
Domestic chip manufacturers are scaling cleanroom operations around Phoenix, Austin, and Albany, driving specification tightening for oil-free scroll systems. EPA emissions enforcement restricts hydrocarbon discharge from wet vacuum technology, compelling biotechnology firms in Boston and San Diego to upgrade to dry architectures. Pharmaceutical research laboratories in the Greater Boston corridor are expanding procurement of validated dry pump platforms.
Germany
Pump manufacturing clusters in Baden-Württemberg and Bavaria are rebalancing capacity toward oil-free architectures as semiconductor fabs demand cleaner process environments. ECHA enforcement of REACH material traceability and energy efficiency disclosures accelerates replacement cycles for legacy laboratory equipment across academic institutes in Berlin and Munich. German research hubs are consolidating procurement under global category management frameworks.
China
Domestic semiconductor manufacturers are scaling cleanroom operations in Shanghai and Suzhou, requiring oil-free pumping systems for wafer processing. SAMR implements GB standards for electromagnetic compatibility and safety certification that govern import access for foreign manufacturers. The Yangtze River Delta biotech corridor is concentrating demand for analytical-grade vacuum systems.
India
CDSCO regulatory harmonization and PLI scheme incentives for pharmaceutical manufacturing are opening procurement channels for vacuum systems in Hyderabad and Bengaluru. Biotechnology firms in these corridors require sterile, oil-free vacuum for cell culture and downstream processing operations. Academic research institutes balance capital constraints against multi-disciplinary application diversity.
Japan
Specialty chemical and materials research facilities in Osaka and Nagoya maintain demand for ultra-high vacuum systems in surface science applications. METI industrial standards govern equipment efficiency and safety certification for laboratory infrastructure. Domestic analytical instrumentation ecosystems integrate dedicated roughing and high-vacuum pumps from established supplier relationships.
Global Laboratory Vacuum Pumps Market Competitive Landscape
German and Swedish producers anchor the premium-tier segment through compressor heritage and magnetically levitated system expertise; Japanese and Chinese specialists hold mid-market positions through cost-optimized scroll and diaphragm architectures. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with vacuum divisions, pure-play vacuum technology specialists, and analytical instrumentation integrators with captive pump portfolios. Competitive moves concentrate on geographic expansion into China's biotech corridor and portfolio diversification toward IoT-enabled predictive maintenance modules.
Among diversified industrial conglomerates, Atlas Copco AB exemplifies the compressor-heritage archetype leveraging rotary vane and scroll expertise across European research hubs. Agilent Technologies Inc. occupies a position within analytical instrumentation ecosystems through deep integration with mass spectrometry and chromatography platforms. Edwards Vacuum represents the magnetically levitated specialization tier for high-vacuum physics applications in semiconductor and research environments.
| Leading Market Players |
|---|
| Atlas Copco AB |
| Agilent Technologies Inc. |
| Edwards Vacuum |
| Busch Vacuum Solutions |
| Pfeiffer Vacuum |
| ULVAC, Inc. |
| VACUUBRAND |
| KNF Group |
| Welch Vacuum |
| Others |
Supply & Pricing Matrix
Rare earth magnet price indices cascade through laboratory vacuum pump manufacturing, compressing margins on magnetically levitated turbo molecular systems while widening spreads between oil-free scroll architectures and legacy wet pump alternatives. Neodymium supply volatility from Chinese mining concentrates feeds directly into tiered equipment pricing across semiconductor fabrication and pharmaceutical research procurement channels.
Pricing Analysis
Distributor margins of 15-25 percent separate OEM direct pricing from end-user acquisition costs across European and North American research hubs. Three-tier pricing structure across premium magnetically levitated systems, standard dry scroll architectures, and economy rotary vane configurations reflects certification grade differentiation and after-sales service bundling. Cost compression in mid-tier dry pump segments is intensifying because REACH compliance investments are elevating baseline manufacturing expenses. Academic research institutes exhibit highest price sensitivity, whereas semiconductor manufacturers prioritize contamination specifications over unit economics.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and China anchor hub-and-spoke fulfillment patterns for aftermarket parts and complete pump systems. Manufacturing concentration in Baden-Württemberg, Osaka-Nagoya corridor, and Shanghai-Suzhou delta draws from neodymium magnet feedstocks, precision bearing components, and fluoropolymer sealing materials. Single-source vulnerability around Chinese rare earth processing creates geopolitical exposure for turbo molecular pump producers. Distribution runs through authorized service networks and direct OEM relationships with multinational pharmaceutical and semiconductor capital procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dry vacuum technology migration represents a margin-expansion story as environmental compliance costs eliminate low-cost wet pump competition and premium-tier oil-free architectures capture widening pricing power.
For Market Incumbents: Anticipate scroll pump commoditization pressure from Chinese specialists by deepening captive production of precision spiral wraps and active magnetic bearing assemblies in Germany and Japan. Anchor defensive positioning through exclusive service contracts with semiconductor fabs in the Yangtze River Delta and pharmaceutical research clusters in Boston and Basel. Certification investment in EU AI Act-compliant automation modules creates switching costs against emerging IoT-enabled entrants. For New Entrants and Emerging Players: E-commerce direct channels offer lowest-friction entry path for standardized diaphragm pump configurations serving budget-constrained academic laboratories in India and Southeast Asia. White space concentrates in IoT-integrated predictive maintenance platforms for distributed biotechnology research networks lacking captive vacuum engineering expertise. Partner with analytical instrumentation OEMs in Hyderabad and Bengaluru for validated system integration rather than competing for direct fab procurement. For Investors and Strategic Acquirers: Consolidation pressure builds where rare earth magnet supply volatility and regulatory compliance burdens outpace standalone R&D investment capacity. Long-term viability favors vertically integrated specialists with captive magnetic bearing calibration expertise and established semiconductor fab service relationships. Monitor F-Gas Regulation amendment timelines as inflection indicator for accelerated replacement demand across European installed bases.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Supply | Captive neodymium sourcing from Australian and Vietnamese deposits reduces Chinese supply chain exposure for turbo molecular pump manufacturers. |
| IoT-Enabled Predictive Maintenance Platform Launch | Sensor-integrated dry pump architectures enable subscription revenue models for distributed pharmaceutical research networks. |
| EU AI Act Compliance Certification Investment | Automated vacuum system intelligence meets emerging laboratory equipment mandates across German and French academic institutes. |
| Geographic Expansion into India Biotech Corridor | CDSCO harmonization and PLI incentives create procurement access for analytical-grade systems in Hyderabad and Bengaluru. |
| Green Manufacturing Transition for REACH Alignment | End-of-life material recovery protocols satisfy ECHA enforcement for European pharmaceutical and chemical research markets. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with vacuum pump engineering directors, semiconductor fab procurement managers, pharmaceutical research facility maintenance heads, and analytical instrumentation OEM supply chain executives were combined with secondary validation from SEC filings of listed industrial conglomerates, ECHA regulatory enforcement databases, SAMR GB standard certification records, and semiconductor fab construction permit filings. Triangulation across these sources calibrated installed base estimates and replacement cycle assumptions.
Historical trendline analysis of vacuum technology adoption patterns across pharmaceutical and semiconductor end-use segments informed projection framework construction. Segmentation dimensions modeled include lubrication architecture, ultimate vacuum capability, application protocol, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating REACH compliance deadline acceleration, EPA emissions enforcement intensity, and domestic semiconductor capacity buildout trajectories in China and the United States. Forecast inputs integrated rare earth magnet price volatility indices and fab equipment capital expenditure patterns.
The model assumes a particular technology adoption path; alternative pathways for dry scroll architectures penetrating aggressive etching chemistries would alter the outlook for turbo molecular pump substitution rates. Forecasts reflect documented assumptions regarding regulatory enforcement timelines, rare earth supply concentration, and semiconductor fabrication geographic expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
North America Rental Chillers Market
Industrial Equipment
Global Flat Glass Tempering Machines Market
Industrial Equipment
Industrial Lasers Systems Market
Industrial Equipment
Magnetizing Equipment Market
Industrial Equipment
Dynamic Scales Market
Industrial Equipment
Industrial Polishing Machine Market
Industrial Equipment
Chemical Storage Tank and Bottle for Semiconductor Market
Industrial Equipment
Global Industrial Actuators Market
Industrial Equipment
Electrodynamic Shaker Systems Market
Industrial Equipment
Cleanroom Equipment Market
Industrial Equipment
Magnetic Chip Conveyors Market
Industrial Equipment
Cable Granulator Market
Industrial Equipment
Robotic Ultrasonic NDT Cells for Weld and Pressure Vessel Inspection Market
Industrial Equipment
Cartridge Heaters Market
Industrial Equipment
Global Cold Plate Market
Industrial Equipment
Precision Machine Market