
 Machine Tool Cooling System Market | 2026-2036
Machine Tool Cooling System Market Size, Share, and Industry Trends Forecast 2026-2036
Machine Tool Cooling System Market Insights
High-pressure through-spindle coolant delivery is reshaping thermal management in precision machining, enabling faster cutting speeds and tighter tolerances in hardened materials. SMC Corporation leverages its pneumatic and fluid control portfolio to anchor coolant delivery infrastructure across Asian manufacturing hubs. Daikin Industries sustains technology leadership in refrigerant-based chiller systems for large machine tool installations. Parker Hannifin competes through integrated motion and fluid systems that bundle cooling with lubrication and sealing functions.
A machine tool cooling system regulates cutting zone temperature through controlled delivery of coolant media—water-soluble fluids, oils, compressed air, or cryogenic gases—typically maintaining tool-workpiece interface temperatures below thermal deformation thresholds of 40-60°C to preserve dimensional accuracy and extend cutting edge life. Flood cooling dominates installed base economics due to lower capital burden and compatibility with legacy machining centers, while cryogenic cooling and micro-channel thermoelectric systems capture premium positioning in superalloy and ceramic machining where conventional thermal management fails. Recirculating technology leads volume adoption across OEM and job shop end users, though high-pressure through-spindle configurations generate disproportionate margin pools in aerospace and medical device contract manufacturing.
The EPA regulates coolant fluid disposal and workplace exposure limits under OSHA standards, while the EU F-Gas Regulation and REACH framework constrain refrigerant selection and chemical composition in chiller-based systems sold across Europe. Japan's METI energy efficiency directives shape minimum performance standards for coolant circulation pumps and refrigeration compressors. Stakeholders must monitor refrigerant phase-down schedules and emerging PFAS restrictions in metalworking fluids when specifying next-generation cooling system architectures.
Market Dynamics
High-pressure through-spindle coolant delivery is compressing thermal management cycles in precision machining, forcing incumbent flood-cooling architectures toward obsolescence as aerospace and medical device manufacturers demand sub-40°C tool-workpiece interfaces for hardened material processing.
Growth Catalysts
- Aerospace component manufacturing expansion:Precision machining capacity additions in Germany and Japan are pulling high-pressure coolant infrastructure into new facility builds.
- EU F-Gas Regulation phase-down:The refrigerant transition toward lower-GWP alternatives is accelerating chiller system replacement cycles across European machine tool installations.
- Baden-Württemberg cluster concentration:Germany's machine tool ecosystem generates concentrated demand for integrated cooling-lubrication systems from adjacent automotive and industrial automation sectors.
Market Restraints
- Copper and aluminum input volatility:Heat exchanger and piping raw material costs swing with commodity markets, compressing margins on recirculating system contracts.
- Refrigerant supply concentration:Lower-GWP alternative production centers in China and Japan create geographic chokepoints for EU-compliant chiller manufacturing.
- Legacy flood cooling installed base:Capital depreciation schedules and operator familiarity lock job shops into lower-performance thermal management for 8-12 year replacement cycles.
Strategic Opportunities
- Medical device contract manufacturing:Ceramic and superalloy machining for orthopedic implants creates premium positioning for cryogenic and micro-channel thermoelectric cooling systems.
- Japan METI energy efficiency mandates:Minimum performance standards for coolant circulation pumps and refrigeration compressors create upgrade pull-through for compliant system architectures.
- Digital coolant monitoring convergence:Integration of IoT sensors with predictive maintenance platforms opens recurring revenue streams in system-as-a-service models.
Industry Challenges
- Refrigerant technician certification timelines:EU F-Gas Regulation credential requirements constrain field service expansion velocity for chiller-based system providers.
- Multi-fluid compatibility engineering:Water-soluble, oil, and cryogenic gas handling in unified architectures demands specialized materials science expertise scarce in traditional HVAC talent pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Machine Tool Cooling System Market |
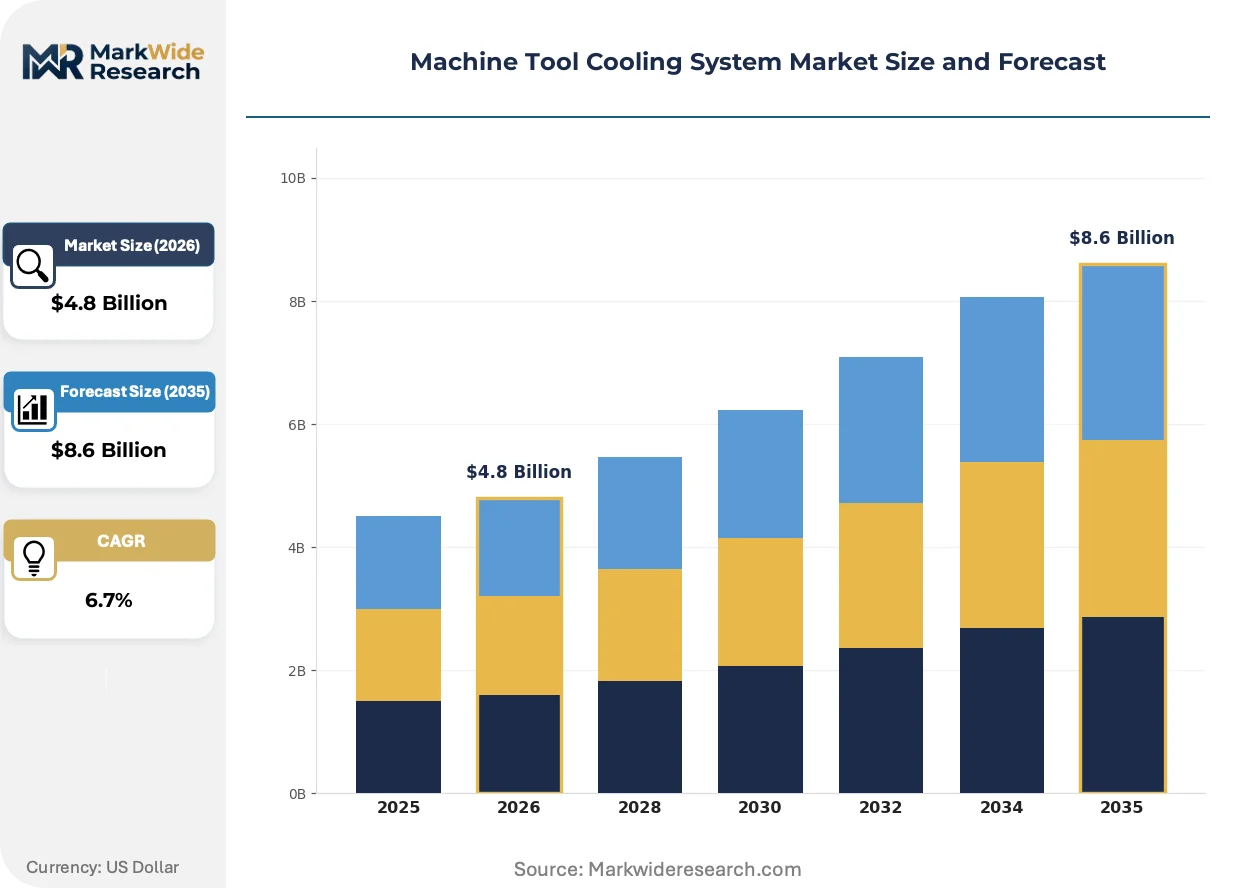
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Flood Cooling, Mist Cooling, Air Cooling, Oil Cooling, Cryogenic Cooling Technology: Recirculating, Single Pass, High Pressure, Micro-Channel, Thermoelectric Application: Metal Cutting, Grinding, Drilling, Milling, Turning End User: OEMs, Job Shops, Contract Manufacturers, Tool & Die Shops |
| Companies Covered | SMC Corporation, Daikin Industries, Glen Dimplex, HYFRA, Habor Precise, LNEYA, Mitsubishi Electric, Parker Hannifin, Pfannenberg, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Machine Tool Cooling System Market Trends and Innovations
Thermal management architectures are bifurcating between commodity flood systems and precision through-spindle configurations, with regulatory refrigerant constraints and aerospace tolerance requirements accelerating this segmentation.
Cryogenic cooling systems using liquid nitrogen or carbon dioxide delivery are rendering obsolete conventional flood cooling in superalloy and ceramic machining applications. Aerospace tier-one suppliers in Germany and Japan are specifying these systems for turbine blade and combustion component production. The technology is compressing capital allocation toward precision thermal management and away from general-purpose coolant infrastructure.
The EU F-Gas Regulation mandates progressive HFC phase-down with complete market prohibition for high-GWP refrigerants in new equipment. Machine tool chiller OEMs are requalifying compressor architectures for R-513A, R-1234ze, and CO2 transcritical loops. German and Italian system integrators face compressed product development timelines to maintain CE marking eligibility across their installed base upgrade pathways.
After-sales service unbundling is fragmenting traditional OEM-captive maintenance relationships. Independent fluid management specialists in the US Midwest and Germany's Ruhr region are capturing coolant monitoring, filtration, and reclamation contracts previously bundled with original equipment sales. Medical device contract manufacturers in Switzerland and Minnesota are driving this disintermediation through ISO 13485 quality system requirements that favor specialized third-party fluid stewardship over generalist OEM service organizations.
Machine Tool Cooling System Market Segmentation
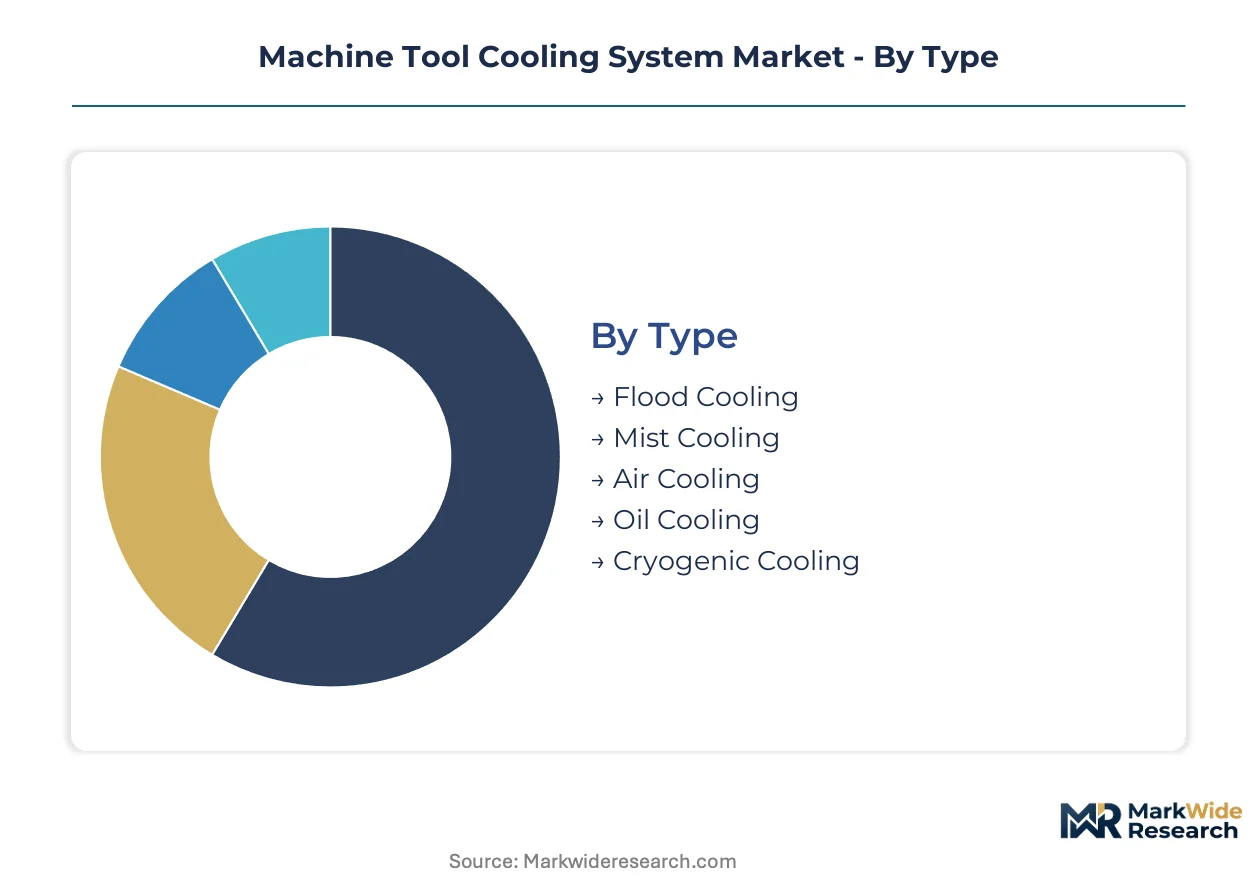
Segmentation in machine tool cooling systems reveals divergent margin structures and service intensity profiles. After-sales attachment rates vary dramatically by technology tier, with precision configurations demanding specialized field engineering while commodity flood systems compete on filter and pump replacement cycles.
Type:
After-sales-service intensity escalates sharply from air-based systems to cryogenic architectures, with fluid reclamation and refrigerant handling creating recurring revenue differentiation.
- Flood Cooling:Water-soluble or oil-based coolant delivered at low pressure in high volumes to the cutting zone. Demand concentrates in German and US Midwest job shops where capital depreciation schedules favor 8-12 year replacement cycles over precision upgrades.
- Cryogenic Cooling:Liquid nitrogen or carbon dioxide delivery systems maintaining sub-zero tool-workpiece interfaces for superalloy and ceramic machining. Japanese aerospace tier-one suppliers in Nagoya and German turbine blade manufacturers in Munich specify these for Inconel and silicon nitride processing where conventional thermal management fails.
- Mist Cooling:Atomized coolant droplets suspended in compressed air for reduced fluid consumption.
- Air Cooling:Compressed air or ambient air circulation for light-duty machining with minimal thermal load.
- Oil Cooling:Neat oil delivery for grinding and honing applications requiring lubrication priority over heat removal.
Flood cooling holds the largest share; momentum sits with cryogenic systems as aerospace tolerance requirements tighten.
Technology:
Cost tier separation between recirculating commodity infrastructure and precision through-spindle configurations determines capital allocation and margin capture.
- Recirculating:Closed-loop coolant recovery with filtration and temperature regulation via chiller or heat exchanger. OEMs in China's Yangtze River Delta and India's Pune manufacturing belt deploy these for volume metal cutting where fluid costs dominate lifecycle economics.
- High Pressure:Through-spindle delivery at pressures exceeding 70 bar for chip evacuation and enhanced heat transfer in deep-hole drilling and titanium milling. Swiss medical device contract manufacturers in Solothurn and Minneapolis orthopedic implant specialists specify these for cobalt-chrome and PEEK machining.
- Single Pass:Disposable coolant flow without recovery infrastructure for contamination-sensitive applications.
- Micro-Channel:Miniaturized fluid passages integrated into cutting tools or fixtures for localized thermal management.
- Thermoelectric:Solid-state Peltier cooling for ultra-precision applications requiring vibration-free temperature control.
Recirculating systems dominate installed volume; high-pressure configurations command the steepest expansion trajectory in aerospace and medical verticals.
Application:
Customer type fragmentation across OEM captive shops and independent job shops shapes specification authority and procurement centralization.
- Metal Cutting:Primary thermal management challenge encompassing turning, milling, and boring operations. German automotive suppliers in Baden-Württemberg and Japanese powertrain manufacturers in Aichi Prefecture drive specification for high-pressure coolant integration with machining center purchases.
- Grinding:Surface and cylindrical grinding generating concentrated heat at the wheel-workpiece interface. Tool and die shops in Detroit and Stuttgart specify oil-based or synthetic coolant delivery with fine filtration for surface finish integrity.
- Drilling:Deep-hole and high-speed drilling requiring chip evacuation and reduced thermal distortion.
- Milling:Multi-axis machining with variable thermal loads across complex geometries.
- Turning:Continuous cutting operations with steady-state thermal conditions.
Metal cutting absorbs the greatest system volume; grinding applications show fastest share gain as precision component tolerances compress.
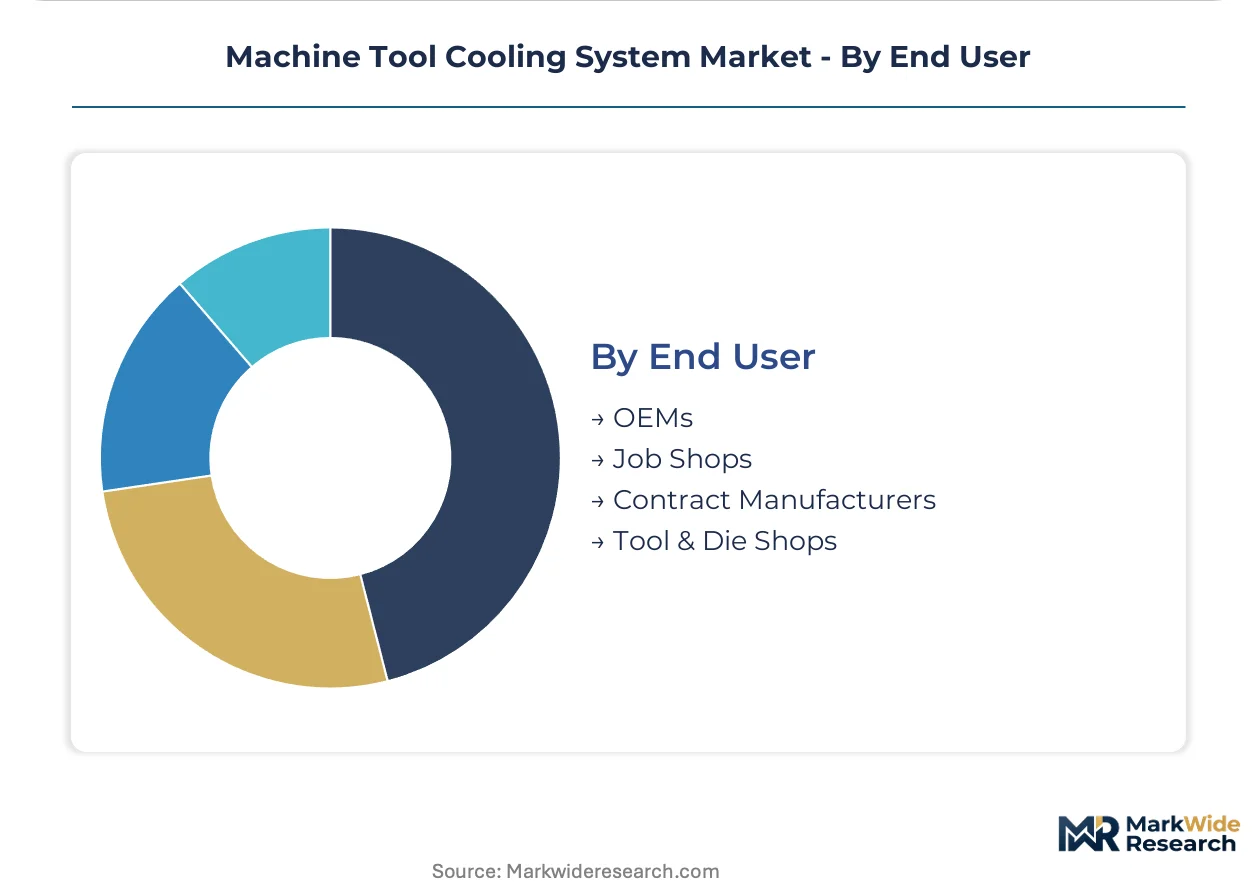
End User:
Geographic concentration in manufacturing clusters determines service network density and spare parts inventory positioning.
- Contract Manufacturers:Third-party precision machining specialists serving aerospace, medical, and industrial OEMs. ISO 13485-certified orthopedic implant manufacturers in Switzerland and Minnesota drive cryogenic and micro-channel cooling specification for ceramic and superalloy processing.
- OEMs:Captive machining operations within automotive, aerospace, and industrial equipment manufacturers. German machine tool builders in Baden-Württemberg integrate cooling-lubrication systems as standard equipment offerings.
- Job Shops:Independent general-purpose machining facilities with legacy flood cooling infrastructure.
- Tool & Die Shops:Mold, die, and fixture manufacturers prioritizing surface finish and dimensional accuracy.
Contract manufacturers represent the fastest-expanding customer segment; OEMs retain the greatest volume concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German machine tool cooling system exports flow primarily to aerospace and automotive manufacturing clusters in Japan, the United States, and China's Yangtze River Delta. This trade corridor shapes specification standards and service network density across destination markets.
Germany
The EU F-Gas Regulation accelerates refrigerant transition timelines for chiller-based systems serving Baden-Württemberg's machine tool cluster. Stuttgart-based manufacturers specify integrated cooling-lubrication architectures for export-bound machining centers. Precision component suppliers in Munich and Aachen drive cryogenic cooling adoption for turbine blade production.
Japan
METI energy efficiency mandates compress upgrade cycles for coolant circulation pumps across Nagoya's aerospace tier-one supplier base. Osaka-based system integrators requalify compressor architectures for lower-GWP refrigerants ahead of 2030 phase-down deadlines. Chubu region manufacturers anchor regional specification authority for through-spindle coolant delivery.
United States
EPA coolant disposal regulations and OSHA workplace exposure limits constrain fluid management practices in Detroit's automotive supplier network. Minnesota medical device contract manufacturers specify cryogenic systems for orthopedic implant machining. Chicago-area job shops retain legacy flood cooling infrastructure despite precision upgrade pressure.
China
MIIT industrial upgrading directives pull high-pressure coolant infrastructure into Yangtze River Delta machining center installations. Suzhou and Shanghai-based OEMs deploy recirculating systems for volume metal cutting where fluid costs dominate lifecycle economics. NMPA medical device regulations shape quality system requirements for precision cooling in implant manufacturing.
Switzerland
Swissmedic medical device quality standards drive specification for cryogenic and micro-channel cooling in Solothurn orthopedic implant manufacturing. Geneva-based contract manufacturers unbundle after-sales service from OEM-captive relationships. Basel-region precision machining clusters demand sub-40°C thermal management for ceramic component processing.
Machine Tool Cooling System Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three identifiable tiers. Integrated motion and fluid systems providers bundle cooling with lubrication and sealing functions to capture specification authority at OEM level. Pneumatic and refrigerant technology specialists anchor coolant delivery infrastructure through component supply relationships. Regional system integrators compete on service proximity and aftermarket attachment rates. Dominant competitive moves include geographic expansion into manufacturing cluster adjacencies and portfolio diversification across cooling technology tiers.
Within the pneumatic-fluid control archetype, SMC Corporation and Parker Hannifin occupy positions spanning component supply through system integration. Daikin Industries exemplifies refrigerant-based chiller specialization for large installation footprints. These three anchors represent divergent strategic postures: component-centric infrastructure control versus refrigerant technology leadership versus integrated motion-fluid bundling.
| Leading Market Players |
|---|
| SMC Corporation |
| Daikin Industries |
| Glen Dimplex |
| HYFRA |
| Habor Precise |
| LNEYA |
| Mitsubishi Electric |
| Parker Hannifin |
| Pfannenberg |
| Others |
Pricing and Supply Chain Analysis
China's dominance in lower-GWP refrigerant production concentrates margin capture upstream, forcing European chiller OEMs to absorb input cost volatility while precision through-spindle system providers in Germany and Japan retain pricing power through aerospace certification barriers. This upstream-downstream tension shapes where value accrues across technology tiers.
Pricing Analysis
The pricing gap between legacy flood cooling, current-generation high-pressure through-spindle systems, and emerging cryogenic architectures spans three performance tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling intensity. Cost compression in commodity recirculating systems intensifies because copper and aluminum heat exchanger input volatility erodes contract margins. Job shops in the US Midwest exhibit highest price sensitivity due to capital depreciation schedules, while ISO 13485-certified medical device contract manufacturers in Switzerland show lowest sensitivity given quality system mandates.
Supply Chain Analysis
Export control regimes on compressor technology and precision machining components constrain cross-border flows from Germany and Japan to emerging manufacturing hubs. Supply concentrates in China for lower-GWP refrigerants, Germany for integrated cooling-lubrication systems, and Japan for energy-efficient circulation pumps. The chain draws from copper and aluminum for heat exchangers, specialized fluoropolymers for multi-fluid compatibility seals, and rare-earth elements for thermoelectric modules. Single-source vulnerability in refrigerant supply creates structural exposure for EU chiller manufacturers. Distribution runs through OEM captive channels for new equipment, with independent fluid management specialists capturing aftermarket service unbundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment. EU F-Gas certification requirements and refrigerant technician credentialing create switching costs that protect incumbent positions against unqualified challengers.
For Market Incumbents: Entrench position through backward integration into refrigerant handling infrastructure and captive certification training programs. Daikin Industries and SMC Corporation should expand field service networks ahead of EU F-Gas phase-down deadlines to lock in upgrade cycle capture. Defend against independent fluid management specialists disintermediating aftermarket relationships by bundling predictive maintenance software with hardware contracts.
For New Entrants and Emerging Players: Pursue white-space opportunities in cryogenic cooling system integration for orthopedic implant contract manufacturers in Minnesota and Solothurn. Target medical device machining verticals where ISO 13485 quality requirements favor specialized thermal management over generalist OEM offerings. Enter through equipment-as-a-service models with IoT-enabled coolant monitoring to bypass capital purchase barriers at mid-sized job shops.
For Investors and Strategic Acquirers: Capital is best deployed toward precision cooling specialists with aerospace tier-one supplier relationships and established refrigerant transition roadmaps. Long-term viability over the coming decade hinges on regulatory compliance architecture and medical device certification density. Watch for inflection signals in Japan METI energy efficiency mandate enforcement timelines, which will accelerate pump and compressor replacement pull-through.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Transition Roadmap | EU F-Gas compliance secures CE marking eligibility for German and Italian system integrators. |
| Backward Integration into Compressor Technology | In-house production of lower-GWP architectures reduces supply chokepoint exposure from China. |
| Medical Device Certification Investment | ISO 13485 alignment opens orthopedic implant machining specifications in Switzerland and Minnesota. |
| Digital Coolant Monitoring Platform | IoT sensor integration enables recurring revenue streams through predictive maintenance subscriptions. |
| Field Service Network Expansion | Geographic proximity to Baden-Württemberg and Nagoya clusters captures upgrade cycle timing. |
Research Methodology
Operator-level perspectives from maintenance directors at aerospace tier-one suppliers, plant engineers at automotive powertrain manufacturers, aftermarket service heads at machine tool OEMs, and procurement leads at medical device contract manufacturers anchored the qualitative base. These primary insights combined with secondary validation from SEC filings of listed cooling system providers, ECHA refrigerant registration databases, EU F-Gas Regulation implementation reports, and METI energy efficiency standard disclosures. Bottom-up sizing of installed base replacement cycles and top-down triangulation against machine tool production statistics ensured methodological robustness.
Scenario-bracketing around refrigerant phase-down timelines and aerospace capital expenditure cycles shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include cooling technology tier, application machining type, end-user customer category, and regional regulatory cluster. CAGRs derived from replacement cycle analysis and technology penetration curves incorporated input cost sensitivity for copper and aluminum commodities alongside energy efficiency mandate compliance rates.
Sensitivities concentrate around EU F-Gas enforcement acceleration, aerospace production schedule volatility, and medical device quality standard revisions. Forecasts reflect documented assumptions on technology substitution elasticities and regulatory implementation pacing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Washdown Scales Market
Industrial Equipment
Small Harmonic Reducer Market
Industrial Equipment
Portable Laser Cleaning Machine Market
Industrial Equipment
Magnetizing Equipment Market
Industrial Equipment
Cartridge Heaters Market
Industrial Equipment
Laser Ablation Systems Market
Industrial Equipment
Glass Washer Market
Industrial Equipment
North America Rental Chillers Market
Industrial Equipment
Industrial Vacuum Evaporation Systems Market
Industrial Equipment
Global Dicing Blades Market
Industrial Equipment
Snowrator Market
Industrial Equipment
Global Liquid Handling Systems Market
Industrial Equipment
Linear Shaft Motor Market
Industrial Equipment
Global DC Drives Market
Industrial Equipment
Dustless Workstations Market
Industrial Equipment
Industrial I/O Modules Market