
 Spherical Roller Bearings Market | 2026-2036
Spherical Roller Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Spherical Roller Bearings Market Analytics
The spherical roller bearings market is pivoting on a widening gap between premium sealed-for-life units and commodity open-design products serving replacement channels. SKF leverages integrated condition-monitoring capabilities to command premium positioning in wind turbine main shaft applications. Timken anchors North American heavy-industry supply chains through backward integration into specialty steel production. NSK Ltd. competes aggressively in Asian automotive transmission segments with compact double-row designs.
Spherical roller bearings incorporate two rows of barrel-shaped rolling elements between an inner ring with two raceways and a common spherical outer ring raceway, accommodating angular misalignment up to several degrees while handling combined radial and axial loads. These components typically operate at bore diameters from 25 mm to over 1,000 mm, with cage designs in machined brass or pressed steel dictating speed and temperature limits. Double-row configurations dominate energy sector installations where shaft deflection from rotor imbalance is routine. Compact variants represent the fastest-expanding material category as electrified drivetrains impose strict envelope constraints. Steel retains margin concentration in large-bore mining and heavy equipment segments where fatigue resistance overrides weight considerations.
FDA oversight of manufacturing equipment in food and pharmaceutical processing indirectly shapes stainless steel bearing specifications for washdown environments. EPA emissions rules and EU Ecodesign requirements pressure OEMs to specify longer service-life bearings that reduce maintenance frequency and material waste. ISO 281 and ISO 15243 standards govern rolling bearing life calculations and mounting practices, creating compliance thresholds for market entry. Stakeholders must monitor how evolving carbon-border mechanisms and remanufacturing incentives reshape total-cost-of-ownership calculations across procurement decisions.
Market Dynamics
The spherical roller bearings market is bifurcating between premium sealed-for-life architectures demanded by wind turbine OEMs and commodity open-design units serving mining fleet replacement cycles. EPA emissions mandates and EU Ecodesign efficiency requirements are compressing acceptable maintenance intervals, forcing specification upgrades across heavy equipment procurement.
Growth Catalysts
- Wind turbine main shaft specifications:Rotor diameters above 150 meters generate substantial shaft deflection. Double-row spherical roller bearings accommodate angular misalignment while handling combined radial and axial loads from rotor imbalance.
- EU Ecodesign Directive:Efficiency mandates for industrial equipment extend minimum service life requirements. OEMs specify higher-grade bearing steels and optimized cage designs to reduce friction losses and maintenance frequency.
- China infrastructure procurement:State-backed steel production capacity expansion and domestic mining fleet modernization sustain large-volume orders for industrial-grade spherical roller bearings in bore diameters exceeding 400 mm.
Market Restraints
- Specialty steel input volatility:Vacuum-degassed bearing steel prices fluctuate with nickel and molybdenum commodity markets. Producers with captive supply chains through backward integration into specialty steel production maintain margin stability.
- Supply concentration in East Asian forging capacity:Large-bore ring rolling and heat treatment infrastructure clusters in specific industrial zones. Geopolitical friction or energy supply disruptions create bottleneck risks for oversized bearing production.
- Ceramic bearing substitution in high-speed spindles:Silicon nitride hybrid bearings penetrate machine tool and precision equipment segments where rotational speed limits constrain spherical roller bearing applicability.
Strategic Opportunities
- India mining equipment localization:The country's national mining regulator and domestic OEMs are expanding local content requirements for heavy machinery components. Joint ventures with forging specialists address import substitution mandates.
- Integrated condition monitoring convergence:Vibration sensors and lubrication analysis systems embed directly into bearing housings. Real-time degradation tracking enables predictive maintenance contracts displacing traditional time-based replacement schedules.
- Remanufacturing incentives under EU circular economy frameworks:Extended producer responsibility schemes and carbon border adjustment mechanisms reward bearing refurbishment over virgin production. Remanufactured large-bore units capture total-cost-of-life advantages in mining applications.
Industry Challenges
- Metallurgical engineering talent scarcity:Heat treatment optimization and failure analysis expertise concentrates among aging specialists. Knowledge transfer gaps threaten quality consistency in fatigue life prediction for custom bearing designs.
- ISO 15243 mounting standard compliance timelines:Certification for high-vibration applications requires extensive test documentation. Smaller manufacturers face protracted approval cycles delaying entry into regulated sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spherical Roller Bearings Market |
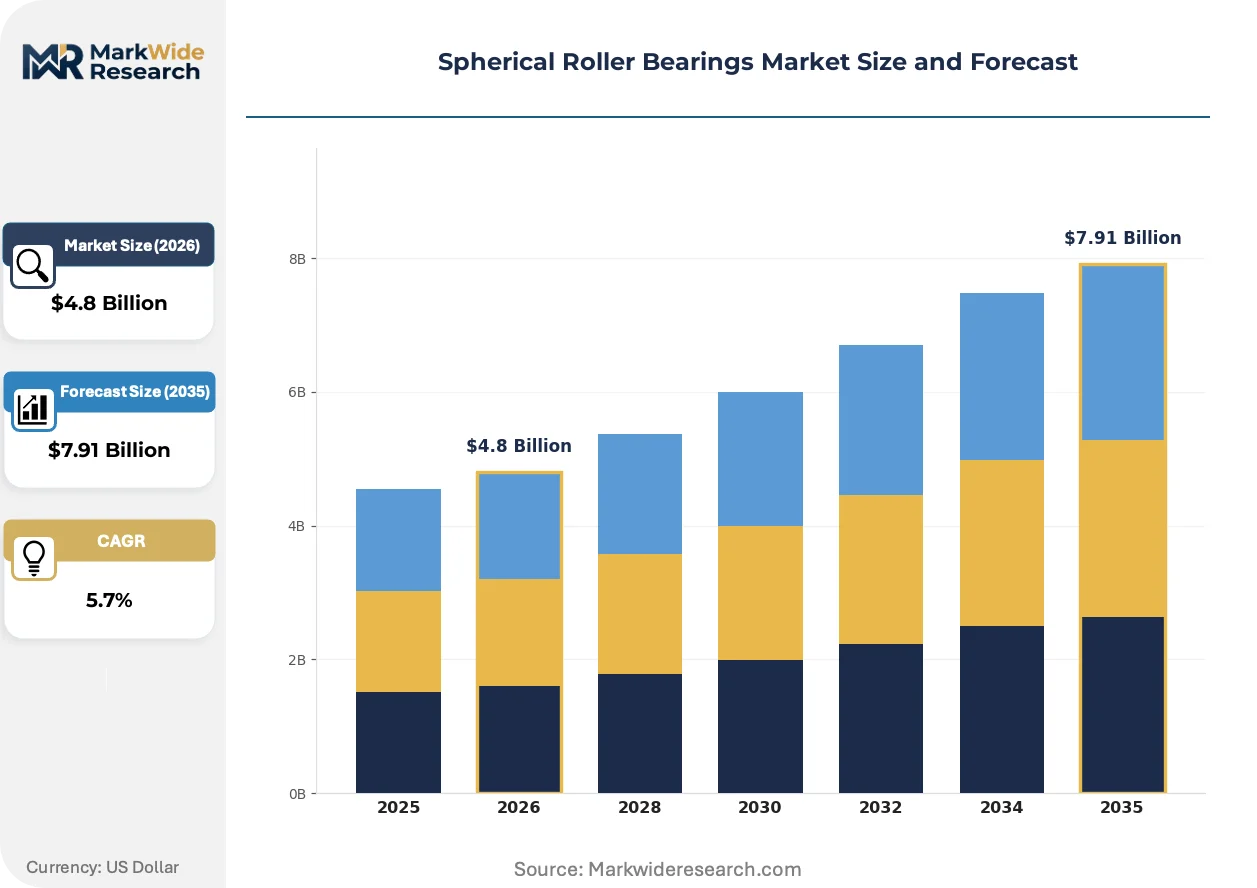
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Row, Double Row, Compact, Custom End User: Aerospace, Automotive, Construction, Industrial Machinery Material: Steel, Stainless Steel, Ceramic, Polymer Application: Heavy Equipment, Mining, Agriculture, Energy |
| Companies Covered | SKF, Timken, NSK Ltd., FAG (Schaeffler Group), NTN Corporation, Schaeffler Group, JTEKT Corporation, Nachi-Fujikoshi Corp., RBC Bearings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spherical Roller Bearings Market Evolving Landscape
Sealed-for-life bearing architectures are displacing traditional regreasable designs as predictive maintenance platforms and extended service intervals reshape equipment specifications across energy and mining verticals.
Polymer cage materials reinforced with glass fiber or PEEK compounds are expanding into wind turbine gearbox and electric vehicle drivetrain applications. OEMs in Germany and Denmark specify these configurations for reduced friction coefficients and elimination of lubricant starvation risks. The technology is expanding into compact envelope designs where metal cage mass limits speed capability.
REACH substance restrictions on hexavalent chromium coatings are forcing conversion to trivalent alternatives or thin-dense chrome plating for corrosion protection. Surface treatment suppliers in Sweden and Japan are scaling deposition capacity for offshore wind and marine applications. European bearing producers face compliance deadlines that compress qualification timelines for alternative coating chemistries.
Consolidated procurement through mining operator fleet management platforms is displacing fragmented distributor channels. Rio Tinto and BHP-style centralized technical specifications reduce supplier count to pre-qualified manufacturers with integrated engineering support. Western Australia and Chilean copper belt operations demonstrate this concentration most visibly, with maintenance contracts bundling bearing supply into power-by-the-hour arrangements.
Spherical Roller Bearings Market Segmentation
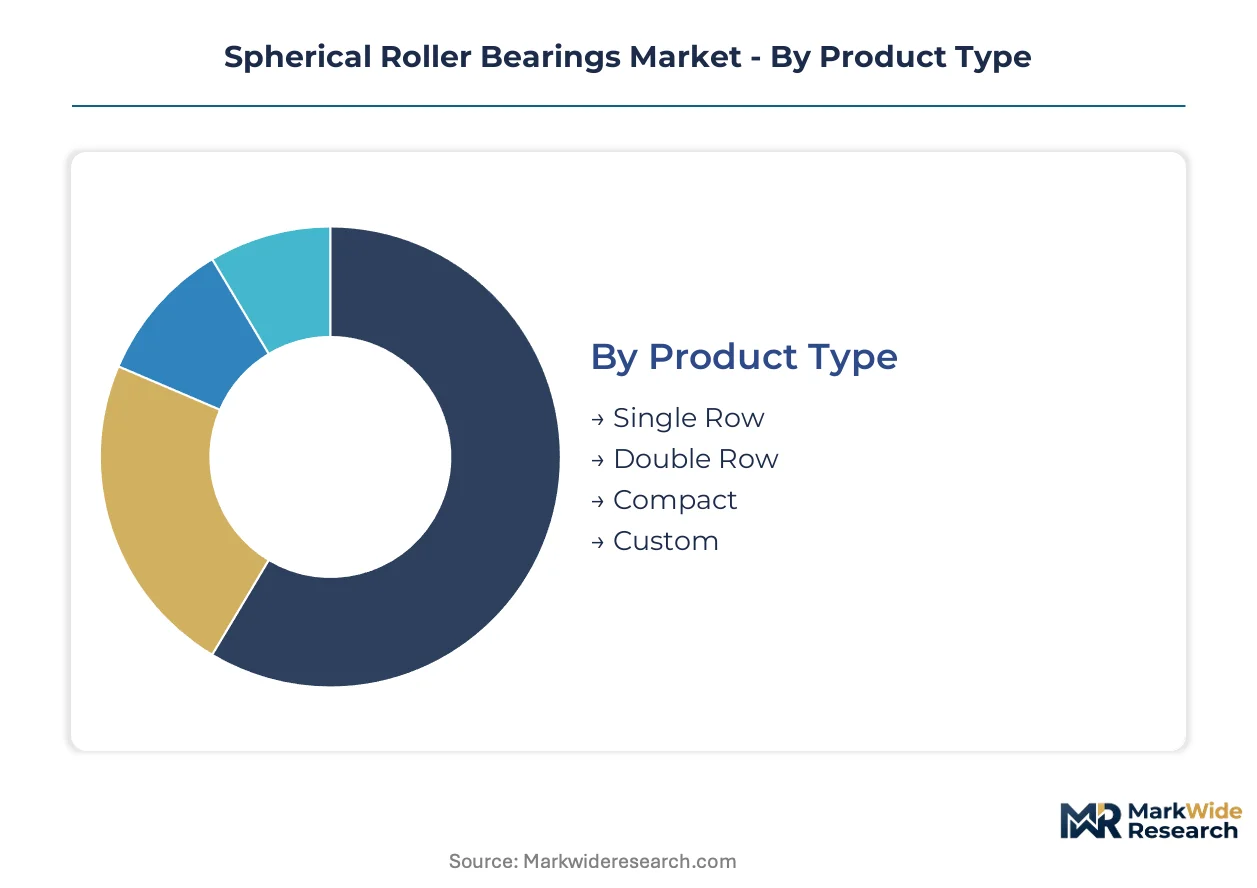
Segmentation in spherical roller bearings reveals how certification requirements, load specifications, and operating environments fragment procurement patterns across industrial verticals. Product architecture, material selection, and end-use application each impose distinct compliance thresholds that reshape supplier qualification and pricing architecture.
Product Type:
ISO 281 life calculation standards and ISO 15243 mounting protocols apply differentially across bearing configurations, with wind turbine OEMs demanding full certification documentation for double-row units while mining replacement channels accept simplified test reports for commodity single-row designs.
- Double Row:Two rows of barrel-shaped rolling elements between inner ring raceways and a common spherical outer ring accommodate angular misalignment up to several degrees. Demand concentrates in wind turbine main shaft installations where rotor diameters above 150 meters generate substantial shaft deflection and combined radial-axial loads.
- Compact:Reduced envelope designs with optimized cage geometries address strict space constraints in electrified drivetrains. Asian automotive transmission producers specify these units for electric vehicle gearbox applications where mass and dimensional limits override fatigue resistance priorities.
- Single Row:Simpler raceway geometry serves cost-sensitive replacement channels in mining fleet maintenance.
- Custom:Application-specific bore diameters and cage materials address non-standard mounting configurations in specialized industrial machinery.
Double Row sits at the top of the volume ranking, with Compact climbing the fastest.
End User:
Cost tier stratification separates aerospace bearing procurement—where FAA airworthiness directives and EASA certification cycles justify 10-15x pricing multiples—from construction equipment channels where OEMs negotiate on raw material indices and forging capacity utilization.
- Industrial Machinery:Broad category spanning pumps, compressors, and process equipment with standardized bore ranges from 25 mm to 400 mm. German and Japanese machine tool builders specify premium sealed-for-life units to minimize maintenance intervals under EU Ecodesign efficiency mandates.
- Automotive:Transmission and driveline applications demand compact double-row designs with polymer cages for reduced friction coefficients. South Korean and Chinese electric vehicle producers are expanding orders for envelope-constrained variants as drivetrain electrification accelerates.
- Aerospace:FAA and EASA certification requirements impose extensive fatigue testing documentation for flight-critical control surface and engine applications.
- Construction:Earthmoving equipment procurement ties bearing specifications to OEM fleet management platforms with centralized technical standards.
Industrial Machinery commands the largest revenue base, with Automotive expanding most quickly.
Material:
Supply concentration in vacuum-degassed bearing steel production creates margin tiering, with integrated producers capturing value through captive specialty steel supply while independent manufacturers absorb nickel and molybdenum commodity volatility.
- Steel:Vacuum-degassed bearing steels with controlled inclusion content dominate large-bore mining and heavy equipment segments where fatigue resistance overrides weight considerations. Chinese state-backed steel production capacity expansion sustains large-volume orders for industrial-grade units in bore diameters exceeding 400 mm.
- Stainless Steel:AISI 440C and precipitation-hardened grades serve FDA-regulated food and pharmaceutical processing equipment requiring washdown corrosion resistance.
- Ceramic:Silicon nitride hybrid bearings penetrate precision equipment segments where rotational speed limits constrain conventional spherical roller applicability.
- Polymer:Glass fiber-reinforced and PEEK compound cages reduce friction in wind turbine gearbox applications.
Steel dominates absolute tonnage, with Polymer gaining share fastest in electrified drivetrain applications.
Application:
Customer type fragmentation separates mining operator fleet management platforms—where consolidated procurement through Rio Tinto and BHP-style centralized specifications reduces supplier count—from agricultural OEM channels with distributed dealer networks and fragmented technical standards.
- Mining:Heavy equipment procurement concentrates in Western Australia and Chilean copper belt operations where maintenance contracts bundle bearing supply into power-by-the-hour arrangements. Remanufactured large-bore units capture total-cost-of-life advantages under EU circular economy frameworks.
- Energy:Wind turbine OEMs in Germany and Denmark specify polymer-cage sealed-for-life architectures for main shaft and gearbox applications. REACH substance restrictions on hexavalent chromium coatings force conversion to trivalent alternatives for offshore installations.
- Heavy Equipment:Construction and earthmoving machinery demands standardized replacement units through OEM dealer networks.
- Agriculture:Seasonal utilization patterns and distributed service infrastructure favor commodity open-design bearings over premium sealed configurations.
Mining leads in large-bore unit volume, with Energy showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's state-backed infrastructure procurement dwarfs Germany's precision manufacturing demand, yet both markets impose divergent technical specifications on spherical roller bearing suppliers.
China
Domestic steel production capacity expansion and mining fleet modernization sustain large-volume orders for industrial-grade units in bore diameters exceeding 400 mm. MIIT industrial equipment efficiency mandates push OEMs toward higher-performance bearing specifications. Manufacturing clusters in Jiangsu and Shandong provinces concentrate forging and heat treatment infrastructure for oversized bearing production.
Germany
Wind turbine OEMs in northern regions specify polymer-cage sealed-for-life architectures for main shaft and gearbox applications. EU Ecodesign Directive efficiency requirements extend minimum service life specifications for industrial equipment. The Ruhr industrial corridor anchors specialty steel production and precision bearing manufacturing for export markets.
United States
EPA emissions mandates compress acceptable maintenance intervals for heavy equipment procurement across mining and construction sectors. The Inflation Reduction Act incentivizes domestic manufacturing reshoring for critical industrial components. Pittsburgh and Cleveland metropolitan areas retain metallurgical engineering expertise and heat treatment infrastructure for large-bore bearing production.
Japan
Automotive transmission producers specify compact double-row designs with optimized cage geometries for electric vehicle drivetrain applications. METI carbon neutrality roadmaps accelerate demand for extended service-life bearings that reduce material waste. The Chubu region around Nagoya concentrates precision forging capacity for compact envelope bearing variants.
India
The national mining regulator and domestic OEMs expand local content requirements for heavy machinery components under import substitution mandates. BIS certification protocols create compliance thresholds for bearing suppliers entering regulated sectors. Gujarat and Maharashtra industrial corridors attract joint ventures with forging specialists to address localization targets.
Spherical Roller Bearings Market Competitive Landscape
Top-tier vendors anchor premium sealed-for-life architectures, while mid-tier specialists compete on forging capacity utilization and commodity replacement channels. The vendor base stratifies across integrated steel producers with captive supply chains, precision manufacturers serving regulated aerospace and wind energy sectors, and regional fabricators focused on mining aftermarket distribution. Two dominant competitive moves define current positioning: backward integration into specialty steel production to stabilize input costs, and embedding integrated condition-monitoring systems into bearing housings to capture predictive maintenance service contracts.
Within the integrated multinational tier, SKF exemplifies premium positioning through condition-monitoring convergence, while Timken anchors North American heavy-industry supply chains through upstream control over specialty steel production. NSK Ltd. occupies a position representing Asian automotive transmission specialization with compact double-row designs.
| Leading Market Players |
|---|
| SKF |
| Timken |
| NSK Ltd. |
| FAG (Schaeffler Group) |
| NTN Corporation |
| Schaeffler Group |
| JTEKT Corporation |
| Nachi-Fujikoshi Corp. |
| RBC Bearings |
| Others |
Value Network & Pricing Analysis
Vacuum-degassed bearing steel price indices cascade through forging and heat treatment stages into three distinct pricing tiers: premium sealed-for-life units for wind energy OEMs, mid-grade industrial bearings for automotive transmission producers, and commodity open-design products serving mining fleet replacement channels. Nickel and molybdenum commodity volatility compresses margins for non-integrated manufacturers while captive steel producers stabilize cost positions.
Pricing Analysis
Capacity additions in China are reshaping price floors for large-bore industrial-grade bearings as state-backed steel production expansion feeds domestic forging clusters. Three-tier pricing structure across premium, standard, and economy levels separates wind turbine OEM specifications with full ISO 281 certification documentation from mining replacement channels accepting simplified test reports. Price differentiation rests on certification grade and volume scale, with ceramic bearing substitution in high-speed spindles intensifying cost compression in precision equipment tiers. Mining fleet operators demonstrate highest price sensitivity through consolidated procurement platforms, while aerospace channels with FAA and EASA requirements show lowest sensitivity.
Supply Chain Analysis
Dual-sourcing requirements from wind turbine OEMs and mining fleet operators mandate multi-supplier qualification across bearing steel producers in China, specialty forging houses in Germany, and precision manufacturers in Japan. Raw material dependencies center on vacuum-degassed bearing steels, nickel-alloy inputs, and polymer cage compounds from PEEK suppliers. Supply chain risk concentrates in East Asian forging capacity clustering, where energy supply disruptions or geopolitical friction create bottleneck exposure for oversized bearing production. Distribution runs through OEM dealer networks for construction equipment, direct technical sales for wind energy, and consolidated fleet management platforms for mining operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spherical roller bearings market functions as a regulatory compounder where EU Ecodesign Directive efficiency mandates and EPA emissions rules continuously upgrade specification thresholds, embedding demand for higher-performance bearing architectures across heavy equipment procurement cycles.
For Market Incumbents: Anticipate ceramic bearing substitution threats in precision equipment segments by deepening captive supply of vacuum-degassed specialty steels and accelerating integrated condition-monitoring system deployment to capture predictive maintenance service contracts. Backward integration into heat treatment infrastructure in Pittsburgh and Cleveland metropolitan areas defends margin stability against nickel and molybdenum commodity volatility. For New Entrants and Emerging Players: Mining equipment distributors in Western Australia and Chilean copper belt operations represent the most penetrable channel for aftermarket bearing supply, as consolidated procurement platforms reduce incumbent supplier counts and create entry points through remanufactured large-bore unit offerings. Joint ventures with forging specialists in Gujarat and Maharashtra industrial corridors address India's import substitution mandates under BIS certification protocols. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier forging specialists possessing heat treatment expertise and aging metallurgical engineering talent bases, as knowledge transfer gaps threaten quality consistency across custom bearing design. The inflection signal to monitor is carbon border adjustment mechanism implementation timelines under EU circular economy frameworks, which would accelerate remanufacturing incentives and total-cost-of-life advantages for refurbished large-bore units.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Steel Production | Captive vacuum-degassed steel supply stabilizes input costs against nickel and molybdenum commodity volatility. |
| Integrated Condition Monitoring Convergence | Vibration sensor embedding enables predictive maintenance contracts displacing time-based replacement schedules. |
| Remanufacturing Capacity Buildout | EU circular economy extended producer responsibility schemes reward bearing refurbishment over virgin production. |
| Polymer Cage Material Transition | Glass fiber-reinforced and PEEK compounds reduce friction coefficients in wind turbine gearbox applications. |
| Regional Forging Joint Ventures | India's national mining regulator localization mandates create partnership opportunities with domestic OEMs. |
Research Methodology
Multiple input streams — primary interviews with maintenance directors, OEM procurement teams, aftermarket service heads, and plant engineers; secondary validation through customs and trade data, SEC 10-K filings, and industry association reports; and technical documentation from ISO standards committees — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Data-stream reconciliation across product type, material grade, end-use application, and regional production cluster dimensions produced volume and value outputs over the projection horizon. CAGRs were derived from segment-level growth trajectory analysis incorporating wind turbine installation pipelines, mining fleet replacement cycles, and automotive electrification content shifts as industry-specific forecast inputs.
Revisions become necessary when REACH substance restriction compliance deadlines accelerate, carbon border adjustment mechanisms reshape total-cost-of-ownership calculations, or specialty steel input volatility exceeds modeled ranges. Deviation in EU Ecodesign Directive enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Screw Air End Market
Industrial Equipment
Electric Actuator Market
Industrial Equipment
Laser Drilling Market
Industrial Equipment
Magnetizing Equipment Market
Industrial Equipment
Global Laser Material Market
Industrial Equipment
Femtosecond Fiber Lasers Market
Industrial Equipment
Battery Spot Welder Market
Industrial Equipment
Floor Scales Market
Industrial Equipment
Thermoelectric Refrigerator Market
Industrial Equipment
Pneumatic Strippers Market
Industrial Equipment
Electric Soldering Iron Gun Market
Industrial Equipment
Laser Plastic Welding Market
Industrial Equipment
Global Flat Glass Tempering Machines Market
Industrial Equipment
Plasma Feeder Market
Industrial Equipment
Global Industrial Centrifuges Market
Industrial Equipment
Microwave Equipment Market