
 Magnetizing Equipment Market | 2026-2036
Magnetizing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetizing Equipment Market Insights
China's expanding rare earth processing corridor is reshaping upstream equipment sourcing patterns. Bunting Magnetics Co. leverages vertically integrated magnet production to anchor North American supply security. Eriez Manufacturing Co. sustains broad application coverage across material handling and testing segments. Sarda Magnets Group specializes in custom coil geometries for defense and aerospace buyers.
Magnetizing equipment comprises systems that apply controlled magnetic fields to align domains within ferromagnetic materials, typically operating at field strengths from several hundred oersteds to over 50 kilo-oersteds depending on alloy composition. Pulse magnetizers dominate high-coercivity applications including sintered neodymium and samarium-cobalt assemblies for traction motors. Direct current technology leads volume shipments for general industrial magnetization, while hybrid systems capture premium positioning in research laboratory settings where field programmability commands price premiums. Electronics manufacturers represent the fastest-growing end user category as data storage and sensor miniaturization intensify.
FDA device regulations and NHTSA motor safety standards in the United States shape medical and automotive magnetizer certification requirements. China's SAMR enforces GB standards on rare earth equipment efficiency, while REACH and RoHS in Europe restrict hazardous substances in magnet coatings and electronic subassemblies. Stakeholders must monitor divergence between regional efficiency mandates and material substance rules when configuring product platforms for cross-border deployment.
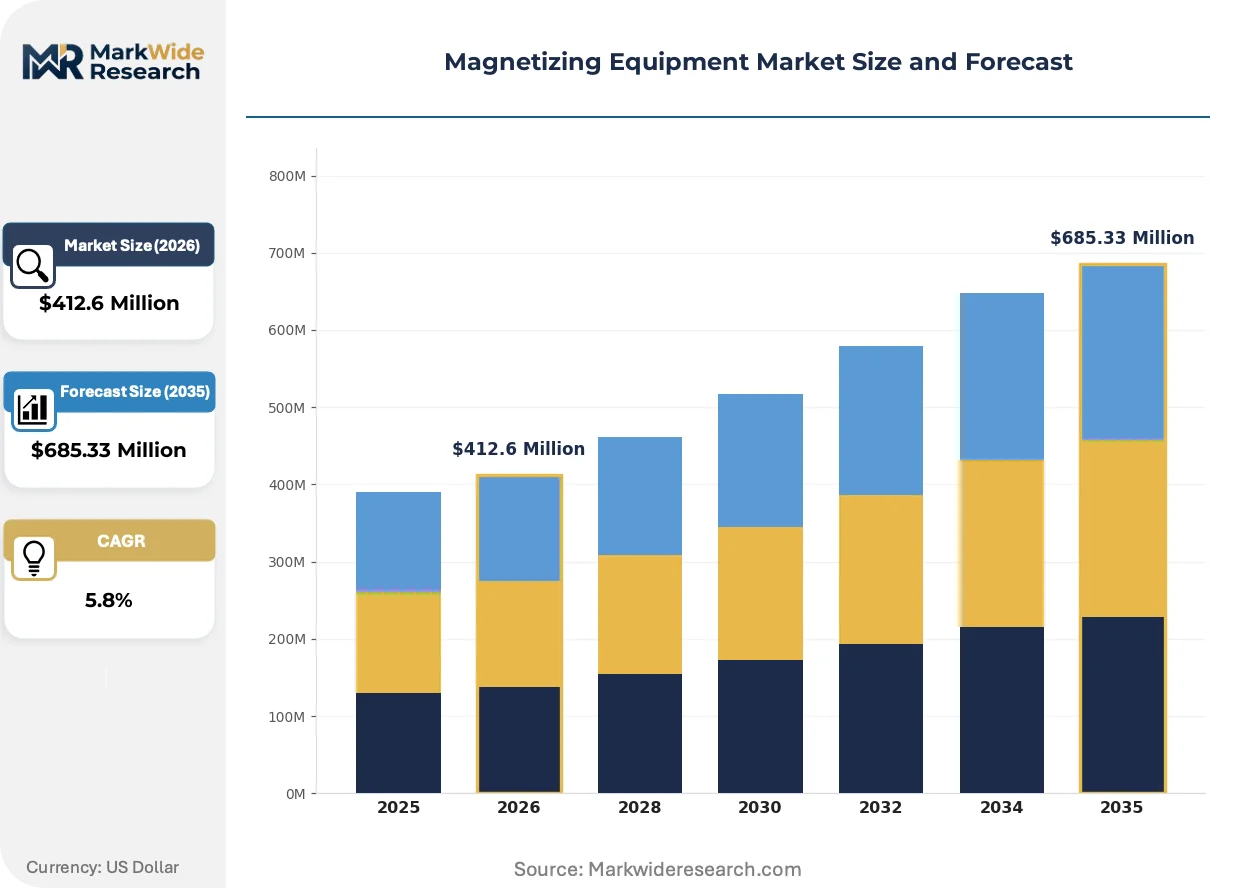
Market Dynamics
Electric vehicle motor manufacturers are consolidating procurement around high-field pulse magnetizing systems capable of saturating sintered neodymium assemblies, compressing vendor qualification timelines and reshaping equipment specification standards across the supply base.
Growth Catalysts
- China's SAMR efficiency mandates:Updated GB standards for rare earth processing equipment are forcing magnetizer upgrades across domestic processing corridors, creating replacement demand for higher-efficiency pulse systems.
- Traction motor assembly lines:Automotive suppliers in Germany's Stuttgart-Munich corridor are retrofitting production lines for neodymium magnet integration, driving capital deployment into automated magnetizing stations.
- Samarium-cobalt traction applications:Elevated temperature performance requirements in aerospace and defense motor programs are accelerating specification of 50+ kilo-oersted pulse systems for high-coercivity alloys.
Market Restraints
- Rare earth concentrate volatility:Neodymium and dysprosium price swings from Chinese processing quotas transmit directly into magnetizer operating cost structures, deterring long-term equipment commitments.
- Specialized coil fabrication concentration:Custom coil geometry production clusters in single-source jurisdictions create supply vulnerability for defense and aerospace program timelines.
- REACH substance restrictions:European coating and electronic subassembly material rules complicate cross-border equipment certification, extending deployment timelines for multi-region vendors.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cell manufacturing:Domestic battery and motor production incentives are creating greenfield demand for industrial-scale magnetizing infrastructure.
- Data storage miniaturization:Electronics manufacturers pursuing sensor and memory component density are opening specification windows for sub-micron precision magnetizing systems.
- Research laboratory hybrid systems:Field programmability requirements in materials science programs are supporting premium positioning for configurable DC-pulse hybrid architectures.
Industry Challenges
- High-voltage pulse engineering talent scarcity:Specialized expertise in capacitor bank design and magnetic field modeling functions constrains equipment manufacturer expansion capacity.
- NHTSA motor safety certification timelines:Extended validation protocols for automotive magnetizer deployments compress available installation windows within model-year production cycles.
- Legacy DC system integration friction:Established industrial magnetizing infrastructure resists pulse system retrofits due to control architecture incompatibilities and retraining requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetizing Equipment Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromagnets, Permanent Magnetizers, Pulse Magnetizers, Coil Magnetizers Technology: Direct Current, Alternating Current, Pulse Technology, Hybrid Systems Application: Data Storage, Magnetic Treatment, Material Testing, Magnetic Assembly End User: Electronics Manufacturers, Metal Fabricators, Research Laboratories, Automotive Suppliers |
| Companies Covered | Sarda Magnets Group, Hishiko Corporation, Bunting Magnetics Co., Magnetic Products, Inc., Kanetec USA Corp., Eriez Manufacturing Co., Magtronics Engineering, Magnetool, Inc., Walker Magnetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetizing Equipment Market Trends and Innovations
Pulse magnetizing architectures are compressing field application timelines while regulatory efficiency mandates and buyer consolidation are rewriting procurement specifications across end-use verticals.
Capacitor-discharge pulse magnetizers are collapsing the distinction between laboratory-grade field control and production-line throughput. Traction motor manufacturers in Germany and China are specifying these systems for 100% saturation verification of sintered neodymium rotors. The technology is collapsing equipment category boundaries as single platforms now span R&D calibration and high-volume assembly applications.
China's GB standards on rare earth equipment efficiency are tightening allowable energy consumption per magnetization cycle. SAMR enforcement is disqualifying legacy DC systems from new processing line approvals. Domestic magnetizer vendors are responding with forced-air cooling retrofits and capacitor regeneration circuits to maintain market access.
Automotive tier-one suppliers are consolidating magnetizer procurement through direct equipment ownership rather than toll-processing arrangements. This behavior shift is displacing regional service bureau networks in Germany and Japan. The restructuring is most visible in Stuttgart, where suppliers now specify in-house pulse systems for just-in-time motor assembly integration.
Magnetizing Equipment Market Segmentation
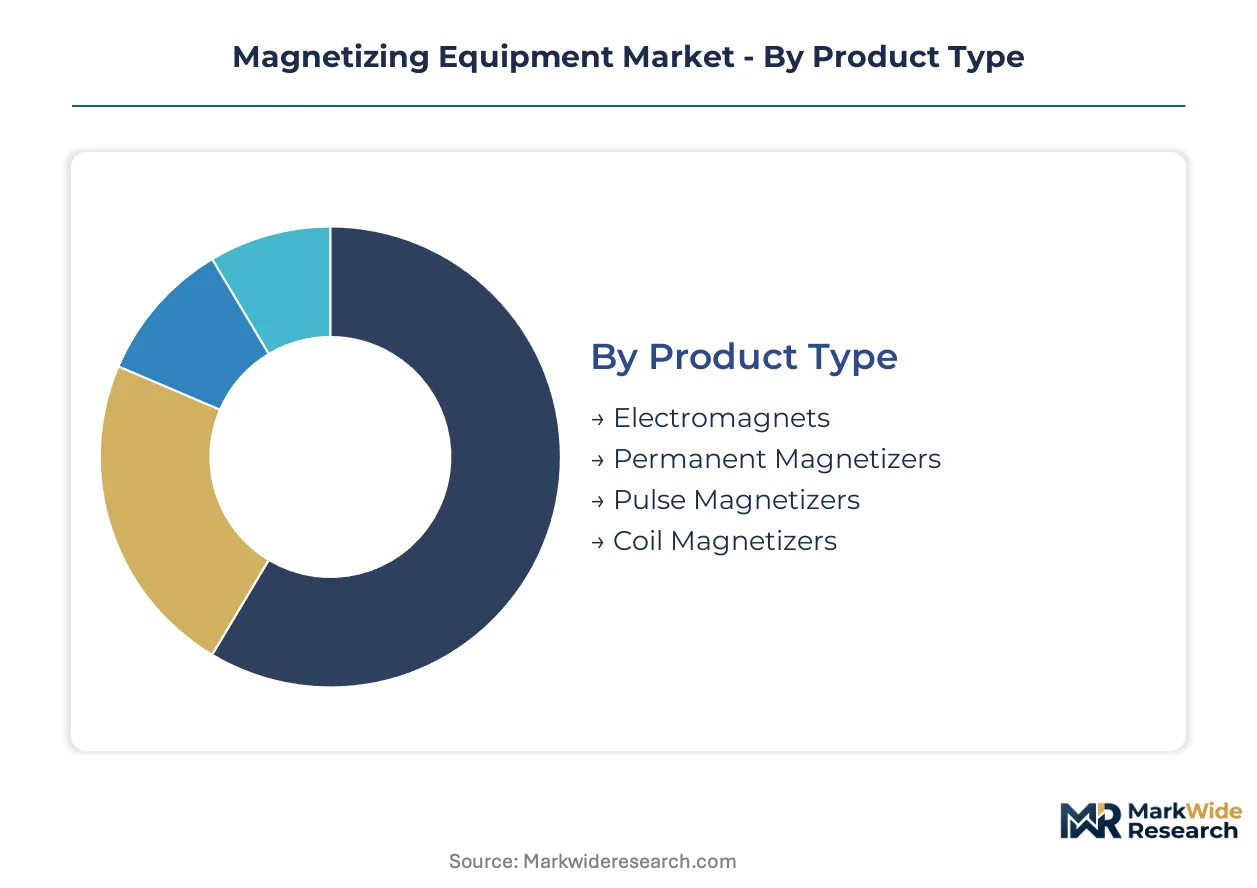
Equipment configuration in the magnetizing equipment market diverges sharply across field strength requirements, throughput demands, and integration complexity. Pulse systems for neodymium saturation command premium positioning against DC workhorses in general industrial settings.
Product Type:
Cost tier stratification separates laboratory-grade precision systems from production-floor workhorses.
- Pulse Magnetizers:Capacitor-discharge architectures generate field strengths exceeding 50 kilo-oersteds for sintered neodymium and samarium-cobalt saturation. EV motor manufacturers in Germany's Stuttgart-Munich corridor specify these for 100% rotor magnetization verification.
- Electromagnets:Variable-field DC systems enable programmable magnetization cycles for research calibration and quality assurance protocols. China's SAMR efficiency mandates are disqualifying legacy units from new rare earth processing line approvals.
- Permanent Magnetizers:Fixed-field fixtures serve high-volume ferrite magnet production with minimal energy overhead per cycle.
- Coil Magnetizers:Custom-wound geometries accommodate irregular component shapes in defense and aerospace motor assemblies.
Pulse Magnetizers command the established base. The steepest expansion runs through Electromagnets as efficiency retrofit demand accelerates.
Technology:
Application intensity determines whether continuous field application or burst-mode saturation delivers optimal economics.
- Pulse Technology:Microsecond-duration field collapse enables complete domain alignment in high-coercivity alloys without thermal damage. Traction motor assembly lines specify these for just-in-time neodymium rotor integration.
- Hybrid Systems:Configurable DC-pulse architectures support research laboratory requirements for field programmability at price premiums exceeding standard production equipment.
- Direct Current:Steady-state field generation dominates general industrial magnetization volumes with lower capital intensity.
- Alternating Current:Demagnetization and conditioning applications in magnetic treatment workflows.
Direct Current retains volume leadership. Hybrid Systems are climbing the fastest as materials science programs expand.
Application:
Customer type concentration varies dramatically between precision electronics and heavy industrial processing.
- Magnetic Assembly:Automated stations integrate magnetizing heads into EV motor production lines for rotor and stator subassembly. Germany's automotive tier-one suppliers are consolidating procurement through direct equipment ownership.
- Data Storage:Sub-micron precision requirements in sensor and memory component manufacturing. Electronics manufacturers pursuing miniaturization are opening specification windows for advanced magnetizing infrastructure.
- Material Testing:Quality assurance protocols for incoming magnet verification and failure analysis.
- Magnetic Treatment:Surface conditioning and stress relief applications in metal fabrication workflows.
Magnetic Assembly anchors current deployment. Data Storage is gaining share fastest as component density intensifies.
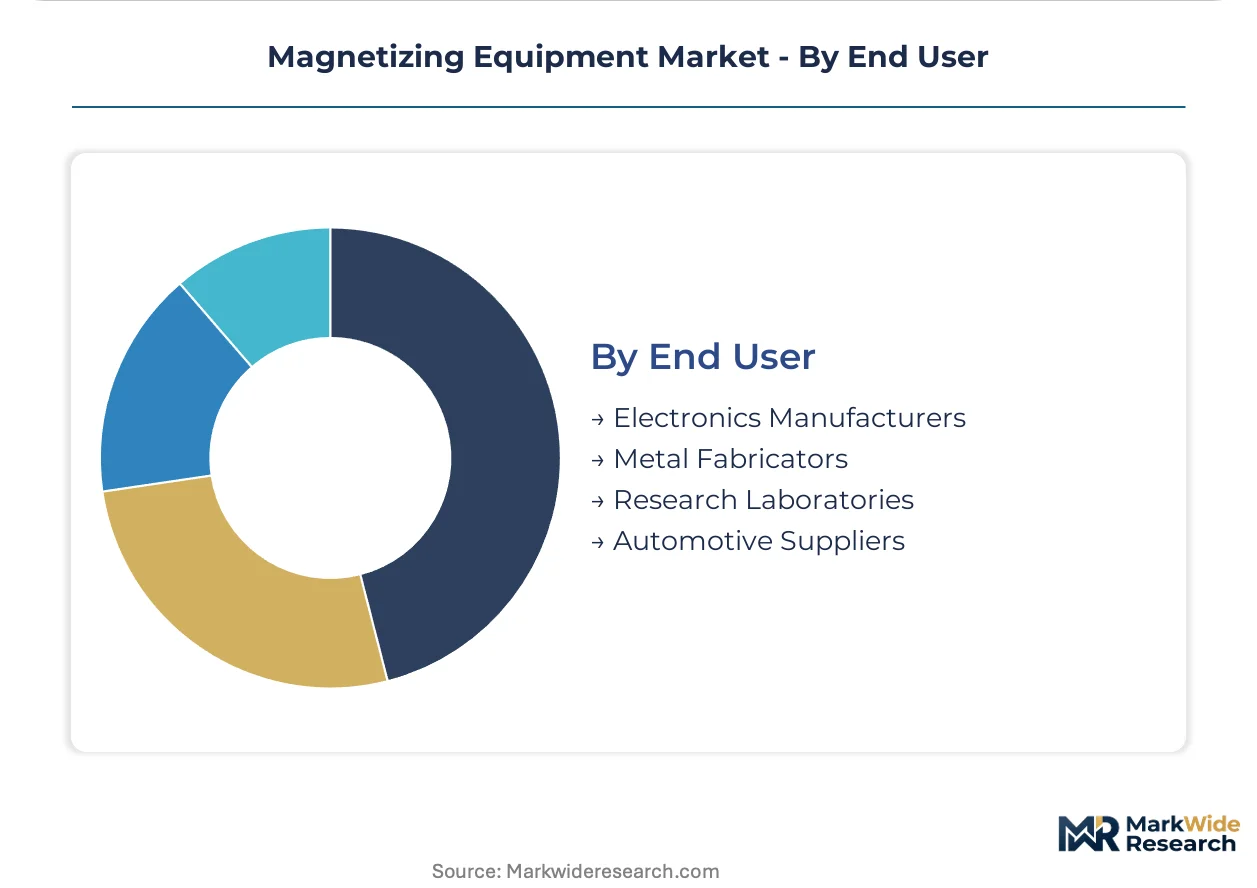
End User:
Procurement scale and technical specification authority separate integrated manufacturers from toll-processing service bureaus.
- Automotive Suppliers:Tier-one motor manufacturers specify high-field pulse systems for in-house neodymium integration, displacing regional service networks. NHTSA safety certification timelines compress available installation windows within model-year cycles.
- Electronics Manufacturers:Sensor and data storage producers drive demand for precision magnetizing at sub-micron scales. India's PLI scheme for advanced chemistry cell manufacturing is creating greenfield infrastructure demand.
- Research Laboratories:Materials science programs require field programmability for alloy characterization studies.
- Metal Fabricators:General industrial magnetization for tooling and component treatment.
Automotive Suppliers dominate capital deployment. Electronics Manufacturers show the steepest trajectory as miniaturization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
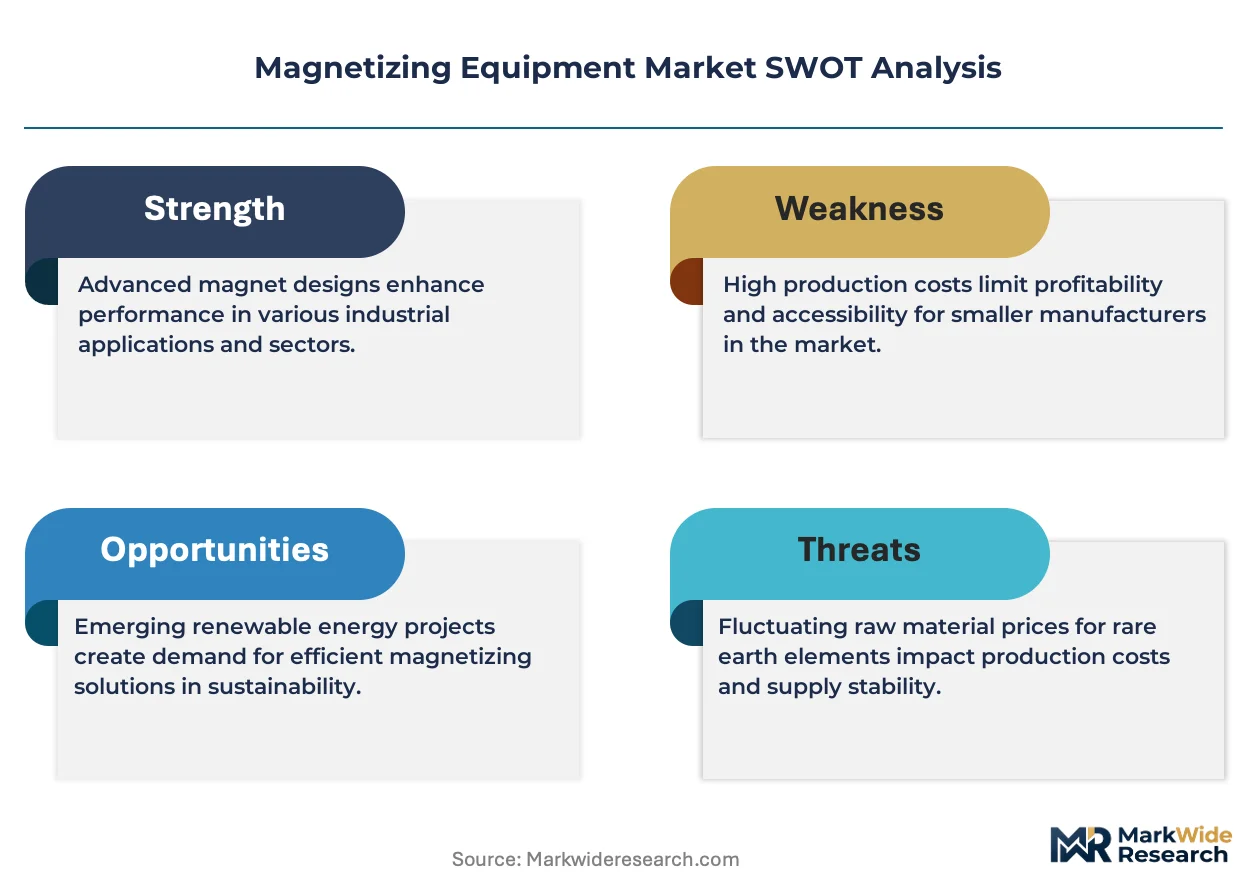
Magnetizing equipment manufacturing clusters tightly around rare earth processing corridors and automotive motor assembly hubs. Equipment procurement patterns diverge sharply between efficiency-driven retrofit markets and greenfield capacity deployment.
China
Rare earth processing corridors in Jiangxi and Inner Mongolia drive pulse magnetizer demand for sintered neodymium saturation. SAMR enforcement of updated GB standards on equipment efficiency is disqualifying legacy DC systems from new line approvals. Domestic vendors in Ningbo and Ganzhou are retrofitting capacitor regeneration circuits to maintain market access.
Germany
Automotive tier-one suppliers in the Stuttgart-Munich corridor are consolidating magnetizer procurement through direct equipment ownership rather than toll-processing. KBA motor safety certification requirements compress installation windows within model-year production cycles. Suppliers in Baden-Württemberg now specify in-house pulse systems for just-in-time neodymium rotor integration.
United States
Defense and aerospace motor programs in the Midwest and Southwest are accelerating specification of 50+ kilo-oersted pulse systems for samarium-cobalt traction applications. NHTSA certification timelines for automotive magnetizer deployments constrain available installation windows. FDA device regulations shape medical magnetizer requirements for imaging equipment manufacturers.
Japan
Electronics manufacturers in the Kanto and Kansai regions are opening specification windows for sub-micron precision magnetizing systems as sensor miniaturization intensifies. METI industrial efficiency guidelines are pressuring legacy equipment replacement. Precision equipment vendors in Nagoya are fielding hybrid DC-pulse architectures for materials science programs.
India
Domestic battery and motor production incentives under the PLI scheme for advanced chemistry cell manufacturing are creating greenfield demand for industrial-scale magnetizing infrastructure. BIS efficiency standards are tightening for imported processing equipment. Tamil Nadu and Gujarat are attracting first-mover magnetizer deployments for EV motor assembly lines.
Magnetizing Equipment Market Competitive Landscape
Vertically integrated magnet producers and specialized coil fabricators split the market between captive supply security and custom geometry expertise. The vendor base organizes around three strategic archetypes: rare earth processors with backward integration into equipment, precision coil specialists serving defense and aerospace, and broad-application industrial equipment houses. Consolidation is accelerating through strategic partnerships between magnet manufacturers and pulse system engineers, while geographic expansion into India's PLI-driven greenfield sites represents the dominant competitive move.
Among North American fabricators, Bunting Magnetics Co. and Eriez Manufacturing Co. occupy positions spanning material handling and industrial magnetization segments. Sarda Magnets Group exemplifies the custom coil geometry specialist archetype serving defense and aerospace program requirements. These three anchors illustrate how competitive positioning diverges between supply-security verticals and precision-engineering boutiques.
| Leading Market Players |
|---|
| Sarda Magnets Group |
| Hishiko Corporation |
| Bunting Magnetics Co. |
| Magnetic Products, Inc. |
| Kanetec USA Corp. |
| Eriez Manufacturing Co. |
| Magtronics Engineering |
| Magnetool, Inc. |
| Walker Magnetics |
| Others |
Pricing and Supply Chain Analysis
Rare earth concentrate processing corridors in Jiangxi and Inner Mongolia anchor upstream magnetizer component supply, concentrating margin capture with coil fabrication specialists serving defense and aerospace programs while compressing equipment OEM profitability.
Pricing Analysis
China's SAMR efficiency mandates dictate the pricing tier structure across pulse magnetizer categories, separating certified high-efficiency systems from legacy DC units facing market access restrictions. Pricing stratifies across premium pulse systems with capacitor regeneration circuits, standard forced-air cooling retrofits, and economy-grade permanent magnet fixtures. Cost compression in standard-tier equipment is intensifying as domestic Chinese vendors absorb efficiency upgrade expenses to maintain GB standard compliance. Automotive tier-one suppliers in Germany exhibit lowest price sensitivity due to NHTSA certification timeline pressures, while Indian PLI-scheme beneficiaries show highest sensitivity as greenfield capital constraints dominate procurement decisions.
Supply Chain Analysis
Neodymium and dysprosium feedstock concentration in China, with secondary processing nodes in Germany and Japan, anchors magnetizer coil and core component sourcing. High-voltage capacitor banks, custom-wound copper coils, and precision magnetic field sensors constitute critical input dependencies. Single-source vulnerability in specialized coil geometry fabrication for 50+ kilo-oersted aerospace systems creates program timeline risk for defense contractors. Distribution runs through direct OEM sales to automotive and electronics manufacturers, with limited aftermarket service bureau presence following procurement consolidation in Stuttgart and Nagoya.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnetizing equipment procurement fragmentation is accelerating as EV motor manufacturers abandon toll-processing networks for in-house pulse system ownership, creating specialist vendor niches across efficiency retrofit and precision miniaturization segments.
For Market Incumbents: Pre-empt coil fabrication capacity constraints by securing captive supply agreements with rare earth processors in Ningbo and Ganzhou before defense program backlogs extend lead times. Reinforce pulse engineering talent pipelines through partnerships with Midwestern US technical universities feeding aerospace motor programs. Prioritize hybrid system R&D investments as materials science laboratory budgets expand faster than production-line equipment cycles. For New Entrants and Emerging Players: Build out sub-micron precision magnetizing capabilities targeting Japanese electronics manufacturers in Kanto and Kansai regions as sensor miniaturization intensifies specification windows. India's Tamil Nadu and Gujarat EV motor assembly greenfields offer the most penetrable geography given PLI scheme infrastructure timelines and limited incumbent service presence. Pursue coil geometry customization expertise as the primary go-to-market angle, leveraging defense and aerospace program requirements for irregular component shapes. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pulse magnetizer manufacturing as capacitor bank engineering and magnetic field modeling functions constrain expansion capacity. Long-term viability favors equipment vendors with backward integration into rare earth processing or forward integration into magnet assembly automation. Acquisition targets should demonstrate established KBA or NHTSA certification relationships compressing automotive installation windows. Monitor China's SAMR enforcement intensity as the signal to watch for replacement demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Processing | Secures neodymium concentrate supply for captive magnetizer coil production amid Chinese quota volatility. |
| Hybrid DC-Pulse System Development | Captures materials science laboratory budgets requiring field programmability at premium price positioning. |
| India PLI-Scheme Geographic Expansion | Establishes first-mover presence in Tamil Nadu and Gujarat EV motor assembly greenfield deployments. |
| Capacitor Regeneration Circuit Retrofit | Maintains China market access under SAMR GB efficiency standards disqualifying legacy DC systems. |
| Defense-Aerospace Coil Geometry Specialization | Locks in long-term program relationships through custom-wound solutions for irregular motor assemblies. |
Research Methodology
A standing panel of pulse magnetizer design engineers, automotive tier-one procurement directors, rare earth processing plant managers, and defense program contracting officers provided ongoing calibration against secondary validation from SEC equipment manufacturer filings, Chinese customs trade data, and NHTSA motor safety certification records. Primary interviews with aftermarket service bureau operators in Germany and Japan supplemented bottom-up demand estimation, while top-down triangulation against GB standard enforcement timelines and PLI scheme disbursement schedules anchored supply-side constraints.
Scenario bracketing around SAMR efficiency mandate enforcement intensity and neodymium price volatility bounds defined the forecast range across the analysis window. Segmentation modeling incorporated product type, technology architecture, application intensity, and end-user procurement scale dimensions. CAGRs derived from equipment shipment trajectories weighted by field strength tier and regional regulatory cluster, with specific inputs including KBA certification timeline compression effects and METI industrial efficiency guideline adoption curves in Japanese electronics manufacturing.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by rare earth processors into equipment manufacturing would shift outcomes through channel foreclosure. Cross-checking against IEA critical minerals supply projections and automotive OEM capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Fiber Laser Coding System Market
Industrial Equipment
Fusion Splicer Market
Industrial Equipment
Global Integrated Drive Systems Market
Industrial Equipment
Medical Laser Marking Machine Market
Industrial Equipment
Sterile Tubing Welder Market
Industrial Equipment
Asia-Pacific Electro Hydraulic Servo Valve Market
Industrial Equipment
COG Bonder Market
Industrial Equipment
Global High Speed Dispenser Market
Industrial Equipment
Diaphragm Coupling Market
Industrial Equipment
Portable Laser Cleaning Machine Market
Industrial Equipment
Fluid Dispensing Equipment Market
Industrial Equipment
Cleanroom Equipment Market
Industrial Equipment
Resistance Spot Welding Machines Market
Industrial Equipment
Industrial Joysticks Market
Industrial Equipment
Global Flat Glass Tempering Machines Market
Industrial Equipment
Sorter Machines Market