
 Leak Testing Machine Market | 2026-2036
Leak Testing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Leak Testing Machine Market Foresight
Automotive electrification is decoupling from conventional combustion-era leak testing protocols as battery cell enclosures and thermal management systems require sub-micron sensitivity thresholds. INFICON leverages its helium leak detection heritage to anchor European EV supply chains where pouch cell sealing validation commands premium equipment specifications. ATEQ Corporation competes through automated pressure decay architectures that sustain high-volume cylindrical battery production lines in Asian manufacturing hubs. Uson L.P. differentiates via specialized medical device applications where FDA-validated test protocols occupy a defensible niche against generalist competitors.
A leak testing machine is a precision instrument engineered to quantify seal integrity by detecting fluid or gas escape from pressurized or evacuated enclosures, typically resolving leak rates down to 10^-9 mbar·l/s in helium-based systems. These machines serve critical quality assurance functions across industries where containment failure risks safety, performance, or environmental compliance. Vacuum-based systems lead in aerospace and semiconductor applications where extreme sensitivity justifies capital intensity, while pressure decay technology captures the fastest growth trajectory in automotive lithium-ion battery manufacturing where cycle speed outweighs ultimate resolution. Helium leak detection retains margin concentration in pharmaceutical and nuclear sectors despite rising helium scarcity, whereas hybrid configurations are gaining traction among quality assurance labs seeking multi-modal flexibility without dedicated single-technology capital deployment.
The EPA enforces Clean Air Act provisions that mandate fugitive emission monitoring in chemical processing, directly stimulating demand for portable leak detection equipment with calibrated certification traceability. EMA and FDA medical device regulations require validated seal integrity for sterile barrier systems, compelling manufacturers to maintain documented test method equivalence across production sites. OSHA process safety management standards further shape industrial procurement by specifying periodic leak inspection intervals for high-hazard chemical systems. Stakeholders must monitor evolving refrigerant regulations and tracer gas availability constraints to determine technology migration timelines before existing equipment amortization cycles conclude.
Market Dynamics
Automotive electrification is compressing test-cycle times while elevating sensitivity requirements, forcing equipment suppliers to reconcile speed with sub-micron resolution thresholds that battery pack validation demands.
Growth Catalysts
- Battery Cell Integrity Mandates:EV manufacturers in Germany enforce pouch cell sealing protocols that require helium-based validation systems. OEM supplier networks propagate these specifications across Tier-1 component producers.
- F-Gas Recovery Directives:The EU F-Gas Regulation mandates helium recovery infrastructure, accelerating capital deployment toward closed-loop tracer gas architectures in precision engineering clusters.
- Semiconductor Node Advancement:Vacuum-based leak detection captures demand from EUV lithography equipment manufacturers where chamber integrity at 10^-9 mbar·l/s sensitivity protects wafer yield.
Market Restraints
- Helium Supply Concentration:US Bureau of Land Management helium auctions dominate global refined gas distribution, exposing European manufacturers to price volatility and allocation rationing.
- Capital Intensity Thresholds:Mass spectrometer-based systems require cleanroom-grade infrastructure that mid-tier automotive suppliers cannot amortize across low-volume EV platform runs.
- Technical Substitution Pressure:Hydrogen tracer methods challenge helium dominance in applications where 10^-6 mbar·l/s resolution satisfies quality gates without rare gas dependency.
Strategic Opportunities
- Medical Device Validation Expansion:FDA 21 CFR Part 820 quality system requirements for sterile barrier systems create defensible demand for validated leak test protocols in US manufacturing.
- Refrigerant Transition Tailwinds:Kigali Amendment phase-down schedules for HFC compounds stimulate retrofit demand for portable leak detection in commercial HVAC service networks.
- Hybrid System Architectures:Quality assurance laboratories converge pressure decay and helium accumulation methods within single-platform configurations, reducing dedicated capital deployment.
Industry Challenges
- Metrology Talent Scarcity:Vacuum physics expertise required for mass spectrometer calibration and maintenance concentrates in aerospace and semiconductor hubs, constraining service network expansion.
- Legacy Protocol Integration:Automotive battery lines retrofit pressure decay stations into existing cylindrical cell production workflows, encountering cycle-time mismatches with robotic handling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leak Testing Machine Market |
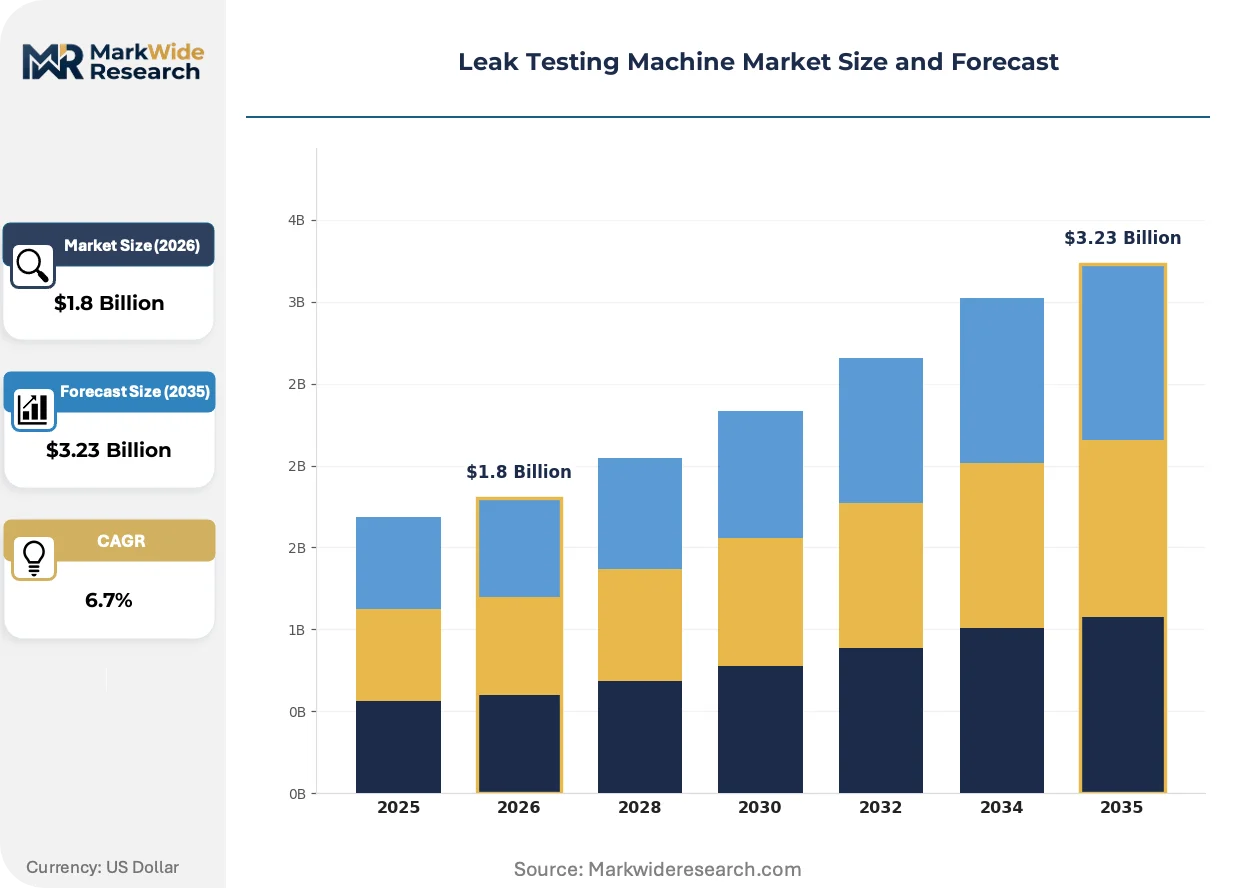
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Automated, Manual, Semi-Automated, Hybrid Application: Aerospace, Automotive, Electronics, Medical Devices Technology: Vacuum, Pressure Decay, Bubble, Helium Leak Detection End User: Manufacturers, Research Institutions, Quality Assurance Labs, Maintenance Providers |
| Companies Covered | INFICON, Drägerwerk AG & Co. KGaA, Honeywell International Inc., Emerson Electric Co., Pfeiffer Vacuum GmbH, ATEQ Corporation, Vacuum Instruments Corporation, CETA TESTSYSTEME GmbH, Uson L.P., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leak Testing Machine Market Shifts & Advancements
Equipment architectures are fragmenting into configurable subsystems that accommodate rapid product changeovers, while regulatory pressure on tracer gas economics accelerates alternative detection chemistry development.
Helium recovery and recycling subsystems are modularizing from standalone auxiliary equipment into integrated machine footprints. Battery pack manufacturers in South Korea adopt these configurations to hedge against helium spot market volatility. The structural compression of operating cost exposure is displacing open-vent gas handling in high-volume production environments.
The EU F-Gas Regulation tightens recovery efficiency mandates for fluorinated greenhouse gases used as tracer alternatives. Industrial gas distributors must certify reclamation rates above 95% to maintain supply authorizations. Pharmaceutical manufacturers in Switzerland and Germany accelerate validation of hydrogen-nitrogen blend methods to preempt compliance-driven supply interruptions.
After-sales service unbundling is fragmenting traditional equipment procurement bundles. Automotive Tier-1 suppliers in Japan now source leak testing stations without embedded maintenance contracts, instead contracting regional metrology service providers for calibration and repair. This channel restructuring compresses OEM service margins while expanding third-party technical labor markets in Nagoya and Osaka industrial corridors.
Leak Testing Machine Market Segmentation
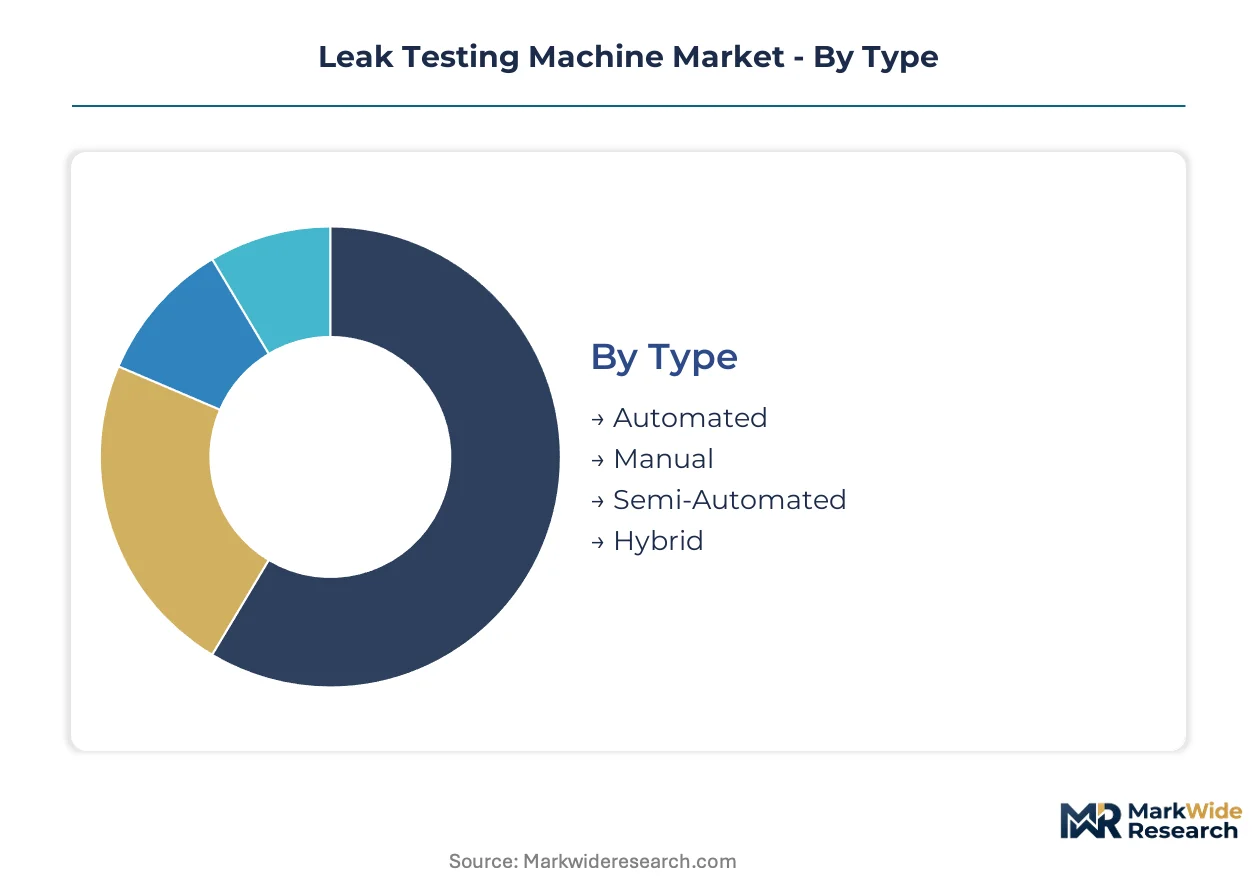
Leak testing equipment procurement varies dramatically by operational scale and sensitivity requirements. Capital deployment decisions hinge on whether facilities need dedicated high-resolution systems or flexible multi-modal configurations.
Type:
Capital intensity stratifies sharply across automation tiers, with fully integrated systems demanding cleanroom infrastructure and specialized metrology labor.
- Automated:Robotic handling and programmable test sequences dominate high-volume battery cell production. South Korean EV manufacturers deploy these systems for sub-60-second cycle times on pouch cell lines.
- Hybrid:Configurable architectures combine pressure decay and helium accumulation methods within single footprints. German precision engineering clusters favor these for multi-product validation without duplicate capital deployment.
- Semi-Automated:Operator-assisted loading with automated test execution suits mid-tier automotive suppliers.
- Manual:Benchtop units serve low-volume prototyping and maintenance applications.
Automated systems absorb the bulk of installed capacity; hybrid configurations are expanding most quickly.
Application:
End-use diversity drives specification divergence, with aerospace and medical device sectors commanding premium pricing for validated protocols.
- Automotive:Battery pack integrity verification requires sub-micron sensitivity thresholds that pressure decay methods struggle to achieve. OEM supplier networks in Germany propagate helium-based validation specifications across Tier-1 producers.
- Medical Devices:FDA-validated sterile barrier testing commands equipment premiums. Swiss and German pharmaceutical manufacturers maintain documented test method equivalence across production sites.
- Aerospace:Vacuum-based systems at 10^-9 mbar·l/s sensitivity protect mission-critical fuel and life support systems.
- Electronics:Semiconductor node advancement drives chamber integrity requirements for EUV lithography equipment.
Automotive applications dominate unit volume; medical device validation delivers the steepest expansion trajectory.
Technology:
Resolution requirements and tracer gas economics determine technology selection, with helium scarcity accelerating alternative method development.
- Helium Leak Detection:Mass spectrometer-based systems achieve 10^-9 mbar·l/s resolution for pharmaceutical and nuclear applications. EU F-Gas Regulation recovery mandates are modularizing recycling subsystems into integrated footprints.
- Pressure Decay:Faster cycle speeds suit high-volume cylindrical battery manufacturing where 10^-6 mbar·l/s resolution satisfies quality gates. Asian production hubs favor these for throughput optimization.
- Vacuum:Extreme sensitivity justifies capital intensity in aerospace and semiconductor chamber validation.
- Bubble:Visual immersion methods persist for coarse leak detection in maintenance and repair contexts.
Pressure decay methods claim the greatest installed base; helium recovery integration is gaining share fastest.
End User:
Procurement authority concentrates among manufacturers with validated production protocols, while service providers fragment demand across portable equipment categories.
- Manufacturers:In-house validation capabilities require capital-intensive fixed installations. Battery cell producers in Germany and South Korea anchor demand for automated production-line integration.
- Quality Assurance Labs:Multi-modal flexibility requirements favor hybrid configurations. Third-party testing facilities in Japan's industrial corridors now source equipment without embedded maintenance contracts.
- Research Institutions:Method development programs drive demand for configurable test parameter ranges.
- Maintenance Providers:Portable equipment requirements concentrate in commercial HVAC service networks facing refrigerant transition timelines.
Manufacturers deploy the majority of fixed assets; quality assurance labs are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in South Korea and precision engineering clusters in southern Germany concentrate high-value leak testing equipment demand. Battery pack validation protocols and EU F-Gas Regulation compliance drive capital deployment toward these locations.
Germany
Bavarian automotive supplier networks enforce helium-based pouch cell sealing standards across Tier-1 producers. The EU F-Gas Regulation mandates tracer gas recovery infrastructure above 95% efficiency. Stuttgart industrial corridors anchor automated production-line integration for EV battery validation.
South Korea
Seoul Capital Area EV manufacturers compress test-cycle times below 60 seconds for high-volume cylindrical cell output. Corporate tax incentives under the K-Semiconductor Belt program subsidize cleanroom-grade metrology infrastructure. Busan-Ulsan industrial zones deploy closed-loop helium recycling to hedge spot market volatility.
United States
EPA Clean Air Act enforcement stimulates portable leak detection procurement for chemical processing fugitive emission monitoring. FDA 21 CFR Part 820 requirements sustain validated sterile barrier testing demand. Greater Boston pharmaceutical clusters maintain documented test method equivalence across multi-site production.
Japan
METI process safety standards specify periodic leak inspection intervals for high-hazard chemical systems. Nagoya and Osaka industrial corridors fragment after-sales service contracts toward third-party metrology providers. Kansai-based Tier-1 suppliers now source equipment without embedded maintenance agreements.
Switzerland
Swissmedic pharmaceutical regulations accelerate hydrogen-nitrogen blend validation to preempt helium supply interruptions. Precision engineering clusters around Basel prioritize hybrid system architectures for multi-modal flexibility. Geneva quality assurance laboratories converge pressure decay and helium accumulation methods within single-platform configurations.
Leak Testing Machine Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated positions in aerospace-grade vacuum systems and fragmented competition in portable HVAC service equipment. The vendor base stratifies into three tiers: mass spectrometer heritage players, pressure decay automation specialists, and regional fabrication houses serving maintenance markets. Dominant competitive moves include M&A to acquire vacuum physics talent and geographic expansion through third-party service network partnerships.
Among European precision instrumentation groups, INFICON and Pfeiffer Vacuum GmbH occupy positions anchored in helium leak detection heritage for semiconductor and pharmaceutical applications. ATEQ Corporation exemplifies the automation-focused archetype competing through high-volume battery production line integration. Uson L.P. represents the validated protocol specialist segment serving FDA-regulated medical device manufacturers.
| Leading Market Players |
|---|
| INFICON |
| Drägerwerk AG & Co. KGaA |
| Honeywell International Inc. |
| Emerson Electric Co. |
| Pfeiffer Vacuum GmbH |
| ATEQ Corporation |
| Vacuum Instruments Corporation |
| CETA TESTSYSTEME GmbH |
| Uson L.P. |
| Others |
Supply & Pricing Matrix
Mass spectrometer calibration expertise concentrated in Bavaria and Stuttgart anchors labor-cost differentials that separate premium helium-based systems from economy-tier pressure decay alternatives. Vacuum physics talent scarcity in these precision engineering clusters widens pricing spreads between validated pharmaceutical-grade equipment and standard automotive configurations.
Pricing Analysis
Short-lead-time premiums of fifteen to twenty percent apply to mass spectrometer-based systems with cleanroom-grade infrastructure, while spot inventory of pressure decay units trades at modest discounts. Three-tier pricing structure across premium, standard, and economy levels reflects certification tier differentiation—FDA-validated sterile barrier protocols command equipment premiums, whereas maintenance-grade bubble testers face price erosion from Asian fabrication houses. Cost compression in the mid-tier automotive segment intensifies because OEM supplier networks propagate standardized specifications across Tier-1 producers. Mid-tier automotive suppliers exhibit highest price sensitivity due to low-volume EV platform amortization constraints; pharmaceutical manufacturers demonstrate lowest sensitivity given regulatory compliance imperatives.
Supply Chain Analysis
Single-source vulnerability sits with US Bureau of Land Management helium auctions that dominate global refined gas distribution. Component manufacturing concentrates in Germany, South Korea, and Japan, drawing from specialized vacuum pump assemblies, mass spectrometer ion sources, and precision pressure transducers. Supply chain risk centers on helium allocation rationing that exposes European manufacturers to spot market volatility. Distribution runs through OEM-integrated production line deployments for automated systems and third-party metrology service providers for aftermarket calibration contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where backward integration into helium recycling subsystems and forward integration into validation protocol software determines margin capture. Players pursuing captive supply of tracer gas recovery infrastructure secure defensible positions against raw material volatility.
For Market Incumbents: Extend service network density in Nagoya and Osaka industrial corridors to preempt third-party metrology provider fragmentation. Consolidate vacuum physics talent through targeted acquisition of specialized calibration houses in Stuttgart and Busan-Ulsan zones. Hydrogen tracer method advancement threatens helium-dominant portfolios; certification investment in FDA-validated sterile barrier protocols defends premium positioning against automation-focused competitors. For New Entrants and Emerging Players: Launch via regional fabrication partnerships serving maintenance providers in commercial HVAC service networks facing Kigali Amendment retrofit timelines. Portable refrigerant detection equipment for HFC phase-down schedules offers the most penetrable white space. Quality assurance laboratories in Switzerland seeking hybrid configurations without embedded maintenance contracts present a second entry vector. Direct equipment sales unbundled from service contracts captures channel restructuring momentum in Japan's industrial corridors. For Investors and Strategic Acquirers: Re-rating potential sits with validated protocol specialists given FDA 21 CFR Part 820 compliance tailwinds in US pharmaceutical manufacturing. Long-term viability over the next decade favors equipment suppliers with software-defined test parameter flexibility rather than fixed-technology hardware platforms. Acquisition targets should display hybrid system architecture capabilities spanning pressure decay and helium accumulation methods. Hydrogen-nitrogen blend validation momentum at Swissmedic-regulated facilities signals technology migration inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Helium Recovery Subsystem Integration | EU F-Gas Regulation mandates above 95% reclamation efficiency for continued supply authorization. |
| Backward Integration into Vacuum Pump Manufacturing | Cleanroom-grade infrastructure requirements concentrate component supply in German and Japanese precision clusters. |
| Software-Defined Test Protocol Development | FDA-validated sterile barrier testing demands documented method equivalence across multi-site production networks. |
| Third-Party Metrology Service Network Partnership | Japanese Tier-1 suppliers now source equipment without embedded maintenance contracts, fragmenting traditional bundles. |
| Hydrogen Tracer Method Validation Investment | Swissmedic pharmaceutical regulations accelerate hydrogen-nitrogen blend adoption to preempt helium supply interruptions. |
Research Methodology
Multi-period observation of battery pack validation protocol adoption and tracer gas recovery infrastructure deployment anchored the trend analysis, supplemented by interviews with vacuum physics specialists, OEM procurement teams at Tier-1 automotive suppliers, pharmaceutical quality assurance directors, and third-party metrology service providers. Secondary validation drew from EU F-Gas Regulation implementation filings, FDA 21 CFR Part 820 quality system documentation, EPA Clean Air Act enforcement records, semiconductor equipment capex disclosures, and customs trade data for vacuum pump assemblies. Bottom-up equipment shipment tracking and top-down end-use demand estimation provided triangulation across independent analytical paths.
Segment-weighting across technology type, automation tier, application vertical, and end-user category structured the analytical framework across the projection horizon. Modeled dimensions included helium leak detection versus pressure decay versus vacuum versus bubble methods; automated, hybrid, semi-automated, and manual configurations; automotive, medical device, aerospace, and electronics applications; and manufacturers, quality assurance labs, research institutions, and maintenance providers. CAGRs were derived from equipment replacement cycles, regulatory compliance deadlines, and EV production ramp assumptions. Forecast inputs incorporated EU lithography equipment chamber integrity requirements and South Korean cylindrical cell output expansion trajectories.
The model assumes a particular technology adoption path; alternative pathways for hydrogen tracer methods displacing helium dominance would alter the outlook. Forecasts reflect assumptions regarding F-Gas Regulation enforcement stringency, helium auction allocation continuity, and semiconductor node advancement schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
VXI Test Equipment Market
Test and Measurement
Handheld Digital Multimeter Market
Test and Measurement
Over-The-Air (OTA) Testing Market
Test and Measurement
Indoor Air Quality Multi-Pollutant Sensor Calibration Test Equipment Market
Test and Measurement
Continuous Level Measurement Market
Test and Measurement
Test and Measurement Equipment Market
Test and Measurement
Battery Testing Equipment Market
Test and Measurement
Digital Weighing Terminal Market
Test and Measurement
Metal Testing Equipment Market
Test and Measurement
Test Rig Market
Test and Measurement
AI-Enabled Semiconductor Defect Classification and Review Systems Market
Test and Measurement
Global Inspection Machines Market
Test and Measurement
Digital Thickness Gauge Market
Test and Measurement
Ground Grid Tester Market
Test and Measurement
Electric Vehicle Edrive Test System Market
Test and Measurement
Asia-Pacific Laser Interferometer Market