
 Global Flat Glass Tempering Machines Market | 2026-2036
Global Flat Glass Tempering Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flat Glass Tempering Machines Market Foresight
Aftermarket service revenue is tilting toward predictive maintenance contracts as tempering furnace operators seek uptime guarantees rather than episodic repairs. NorthGlass Group Co., Ltd. leverages its domestic installed base in China to sustain recurring parts revenue. Grenzebach Maschinenbau GmbH anchors European demand through specialized convection system retrofits. Glaston Corporation competes on remote diagnostics capability across multiple continents.
Flat glass tempering machines heat annealed glass above its transformation temperature, then rapidly quench it with forced air to induce compressive surface stress typically between 69 and 165 megapascals, producing safety glass that fractures into granular rather than shard patterns. Continuous tempering lines dominate volume throughput in automotive component plants where uninterrupted sheet flow reduces unit energy cost. Infrared heating technology leads R&D investment due to faster thermal response and reduced nitrogen oxide emissions compared to gas-fired systems. Fully automatic inline tempering captures premium pricing from solar panel producers requiring zero-contact handling to preserve anti-reflective coatings.
China's MEE enforces dual carbon goals that compel furnace upgrades with waste heat recovery, while the EU F-Gas Regulation restricts blowing agent chemistry in quench nozzles and REACH governs refractory material composition. The United States EPA and OSHA jointly influence thermal processing equipment emissions and worker exposure limits at fabrication sites. Stakeholders must monitor how fragmented national efficiency standards reshape equipment export compliance costs and localize supply chain sourcing decisions.
Market Dynamics
Automotive OEMs are consolidating tempered glass procurement under single-source furnace operators, compressing equipment vendor margins while forcing continuous throughput guarantees and energy efficiency upgrades.
Growth Catalysts
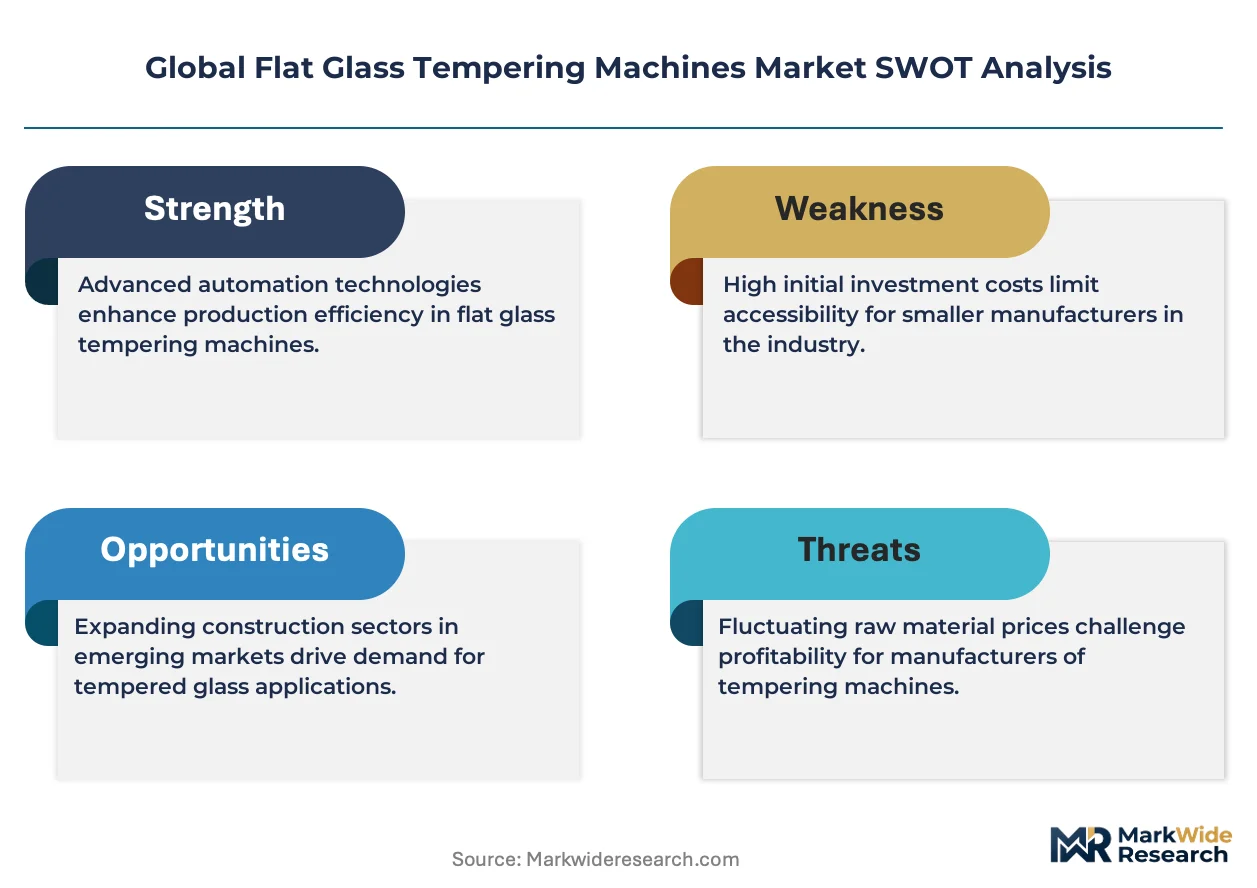
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon blowing agents in quench nozzle chemistry forces furnace retrofits across German and Italian fabrication clusters, generating replacement demand for compliant convection systems.
- Photovoltaic deployment:Solar panel manufacturers in China and the United States are specifying zero-contact inline tempering lines to preserve anti-reflective coating integrity on high-transmission glass substrates.
- China's dual carbon goals:MEE mandates for waste heat recovery in heavy industry are accelerating furnace upgrades at domestic architectural glass producers seeking compliance with 2030 efficiency benchmarks.
Market Restraints
- Refractory material supply concentration:High-purity alumina-zirconia-silica crucible sourcing depends on limited Chinese and Ukrainian producers, exposing furnace operators to input cost volatility and geopolitical disruption.
- Natural gas price sensitivity:Conventional tempering lines retain substantial exposure to regional gas pricing, compressing operating margins when energy markets tighten and limiting payback periods for efficiency investments.
- REACH compliance friction:ECHA substance restrictions on nickel and chromium compounds in heating element alloys extend European equipment certification timelines and raise retrofit material costs.
Strategic Opportunities
- India's PLI scheme for solar manufacturing:Domestic content requirements for photovoltaic module assembly are attracting tempered glass investments to Gujarat and Tamil Nadu, creating greenfield furnace demand.
- Infrared-electric hybrid heating:Convergence of ceramic infrared emitters with precision SCR power controls enables sub-90-second thermal response cycles, opening premium positioning against conventional gas-fired systems.
- Predictive maintenance channel expansion:Aftermarket service unbundling allows furnace vendors to capture recurring revenue through vibration-sensor and thermal-imaging subscription contracts rather than transactional spare parts sales.
Industry Challenges
- Control systems integration complexity:Legacy tempering lines with proprietary PLC architectures resist seamless retrofit with modern IoT diagnostics, forcing costly parallel control layer installations.
- Thermal process engineer scarcity:Specialized expertise in glass transformation temperature profiling and quench pressure optimization is concentrating at incumbent OEMs, constraining independent service provider expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flat Glass Tempering Machines Market |
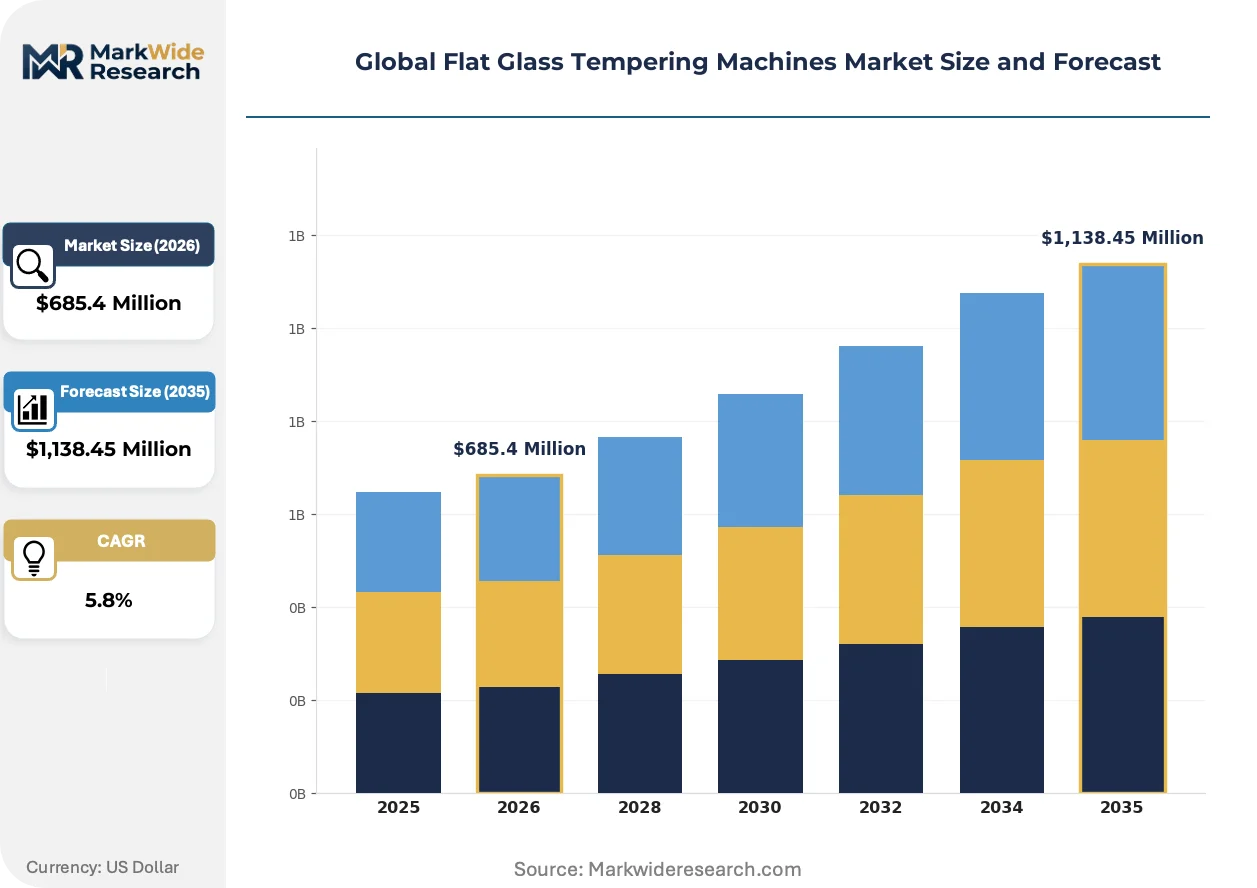
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Tempering, Continuous Tempering, Semi-Automatic, Fully Automatic, Inline Tempering Technology: Electric Heating, Gas Heating, Infrared Heating, Induction Heating, Hybrid Heating Application: Architectural Glass, Automotive Components, Solar Panels, Consumer Electronics, Furniture Glass End User: Construction Contractors, Vehicle Manufacturers, Solar Energy Firms, Appliance Makers, Interior Designers |
| Companies Covered | NorthGlass Group Co., Ltd., Bystronic Glass AG, LandGlass Technology Co., Ltd., Grenzebach Maschinenbau GmbH, Lisec Austria GmbH, Glaston Corporation, Bottero S.p.A., Beijing Hanjiang Automatic Glass Machinery Equipment Co., Ltd., Luoyang North Glass Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flat Glass Tempering Machines Market Shifts & Advancements
Infrared heating architectures are displacing conventional gas-fired convection across premium tempering installations, while regulatory chemistry restrictions and buyer procurement consolidation reshape competitive positioning.
Forced-air quench technology is migrating from high-pressure blower arrays to variable-frequency-driven centrifugal fan systems with laminar flow nozzles. Automotive component plants in Germany and the United States are specifying these configurations for continuous lines processing windscreen blanks. The technology is migrating from premium solar and automotive segments toward mid-volume architectural producers seeking nitrogen oxide emission reductions without throughput sacrifice.
China's MEE enforcement of dual carbon goals is compelling furnace operators to install waste heat recovery exchangers and regenerative burner systems. The industrial consequence is extended capital planning cycles as fabricators weigh compliance-driven upgrades against greenfield electric furnace investments. Architectural glass producers in Hebei and Guangdong provinces are responding by consolidating production at fewer, larger facilities with integrated heat recovery.
Aftermarket service contracting is displacing episodic repair procurement among tempering furnace operators. Solar panel manufacturers in China and the United States are demanding uptime guarantees with penalty clauses, forcing equipment vendors to embed predictive diagnostics and remote monitoring. This pattern is most visible in photovoltaic glass fabrication clusters where coating damage from unplanned downtime carries material scrap costs exceeding service contract premiums.
Global Flat Glass Tempering Machines Market Segmentation
Segmentation in flat glass tempering machines determines after-sales service intensity, spare parts predictability, and upgrade pathway design. Equipment vendors structure maintenance contracts and remote diagnostics capabilities around the operational tempo and thermal stress profiles inherent to each segment configuration.
Product Type:
After-sales service intensity varies sharply across tempering line configurations, with continuous and inline systems demanding predictive maintenance subscriptions while batch units rely on episodic repair cycles.
- Batch Tempering:Intermittent furnace operation processes discrete glass loads through heating and quench cycles, suiting low-volume architectural fabricators and custom furniture producers. Demand concentrates at small and mid-sized European glass shops where flexibility outweighs throughput metrics, though these operators resist premium service contracts due to irregular utilization patterns.
- Continuous Tempering:Uninterrupted sheet flow through integrated heating and cooling zones serves high-volume automotive component plants in Germany and the United States. MEE waste heat recovery mandates in China and EPA emissions guidelines in the United States are forcing upgrades to regenerative burner configurations at these installations.
- Semi-Automatic:Operator-assisted loading with automated thermal profiling reduces labor requirements at mid-scale architectural producers.
- Fully Automatic:Complete material handling automation eliminates human contact with glass surfaces, critical for solar panel manufacturers preserving anti-reflective coatings.
- Inline Tempering:Direct integration with coating and cutting lines enables zero-buffer production flows at photovoltaic glass facilities in China and India.
Continuous tempering holds the largest share; momentum sits with inline tempering as solar manufacturing scales.
Technology:
Heating technology selection governs capital expenditure tiers, operating cost structures, and compliance trajectories across regulatory jurisdictions.
- Electric Heating:Resistance-element furnaces deliver precise temperature control with minimal nitrogen oxide emissions, aligning with EU F-Gas Regulation constraints on blowing agent chemistry. Demand clusters at German automotive suppliers seeking REACH-compliant refractory configurations and stable energy pricing environments.
- Infrared Heating:Ceramic emitter arrays achieve sub-90-second thermal response cycles with reduced thermal mass, opening premium positioning against gas-fired alternatives. Solar panel producers in China and the United States are specifying these systems for coating preservation and energy efficiency benchmarking.
- Gas Heating:Conventional convection retains installed base dominance but faces margin compression from regional natural gas price volatility.
- Induction Heating:Electromagnetic coupling enables rapid selective heating for specialized automotive component geometries.
- Hybrid Heating:Combined infrared-electric architectures optimize thermal response and emissions profiles at high-throughput architectural facilities.
Gas heating retains dominant installed capacity; infrared configurations are climbing the fastest as efficiency mandates tighten.
Application:
Application-driven segmentation aligns equipment specifications with fracture pattern requirements, optical clarity thresholds, and coating compatibility constraints.
- Architectural Glass:Tempered safety glass for facades and curtain walls requires compressive surface stress between 69 and 165 megapascals per building codes. China's MEE dual carbon enforcement is consolidating production at fewer Hebei and Guangdong facilities with integrated waste heat recovery.
- Solar Panels:High-transmission tempered glass with anti-reflective coatings demands zero-contact handling to preserve surface treatments. Photovoltaic deployment in China and the United States is specifying fully automatic inline tempering lines with remote diagnostics integration.
- Automotive Components:Windscreen and side-lite blanks require precise fragmentation patterns for occupant safety certification.
- Consumer Electronics:Thin-glass tempering for display covers necessitates tight thickness tolerance control.
- Furniture Glass:Decorative and structural tempered glass for interior applications prioritizes aesthetic edge quality.
Architectural glass commands the greatest installed machine base; solar panel applications are gaining share fastest on photovoltaic manufacturing expansion.
End User:
End user category determines procurement centralization, technical specification authority, and service contract negotiation leverage.
- Construction Contractors:Project-based glass procurement with variable volume forecasting challenges furnace utilization planning at supplier facilities.
- Vehicle Manufacturers:Automotive OEMs are consolidating tempered glass procurement under single-source furnace operators, compressing equipment vendor margins while mandating continuous throughput guarantees.
- Solar Energy Firms:Vertically integrated photovoltaic manufacturers specify uptime guarantee contracts with penalty clauses, forcing predictive maintenance embedding.
- Appliance Makers:Refrigerator and oven door glass requirements prioritize thermal shock resistance over optical properties.
- Interior Designers:Custom furniture and decorative glass demand drives batch tempering utilization at specialized fabricators.
Vehicle manufacturers represent the most concentrated procurement authority; solar energy firms are expanding their tempering equipment footprint most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States absorb premium pricing for efficiency-compliant systems with minimal elasticity, while Chinese fabricators prioritize capital cost minimization even when operating margins compress under MEE enforcement.
China
Photovoltaic glass manufacturers in Jiangsu and Anhui provinces are expanding tempered glass procurement as solar deployment accelerates. MEE dual carbon mandates compel furnace operators to install waste heat recovery exchangers and regenerative burner systems. Production consolidates at fewer, larger facilities in Hebei and Guangdong provinces with integrated heat recovery infrastructure.
Germany
Automotive component plants in Bavaria and Baden-Württemberg specify continuous tempering lines with laminar flow quench configurations for windscreen blank processing. EU F-Gas Regulation phasedown of hydrofluorocarbon blowing agents forces convection system retrofits across German fabrication clusters. Stuttgart and Munich anchor specialized furnace engineering expertise concentrated at incumbent OEMs.
United States
Solar panel producers in Arizona and Texas demand zero-contact inline tempering lines to preserve anti-reflective coating integrity on high-transmission substrates. EPA and OSHA jointly influence thermal processing equipment emissions and worker exposure limits at fabrication sites. Michigan and Ohio automotive glass clusters operate continuous lines with uninterrupted sheet flow reducing unit energy cost.
India
Domestic content requirements under the PLI scheme for solar manufacturing are attracting tempered glass investments to Gujarat and Tamil Nadu. Bureau of Indian Standards certification timelines extend equipment import clearance for European and Chinese furnace vendors. Greenfield furnace demand concentrates at photovoltaic module assembly facilities in the Mundra and Sri City industrial corridors.
Japan
Display cover glass producers in the Kanto region require thin-glass tempering systems with tight thickness tolerance control for consumer electronics applications. METI efficiency benchmarks accelerate infrared-electric hybrid heating adoption against conventional gas-fired alternatives. Nagoya automotive suppliers specify precise fragmentation pattern certification for occupant safety compliance.
Global Flat Glass Tempering Machines Market Competitive Landscape
Capability concentration sits with specialized convection system engineers; scale advantage sits with diversified machinery conglomerates serving adjacent glass processing segments. The vendor base organizes around three strategic archetypes: integrated furnace OEMs with captive control system development, regional fabricators with cost-optimized batch line configurations, and precision heating technology specialists. Competitive moves center on predictive maintenance service unbundling and geographic expansion through localized assembly partnerships rather than direct export.
Among Chinese furnace specialists, NorthGlass Group Co., Ltd. and LandGlass Technology Co., Ltd. exemplify the integrated OEM archetype with domestic installed base leverage for recurring parts revenue. German engineering houses including Grenzebach Maschinenbau GmbH anchor European demand through specialized convection expertise. Glaston Corporation occupies a position spanning multiple continents with remote diagnostics capability as a service differentiation vector.
| Leading Market Players |
|---|
| NorthGlass Group Co., Ltd. |
| Bystronic Glass AG |
| LandGlass Technology Co., Ltd. |
| Grenzebach Maschinenbau GmbH |
| Lisec Austria GmbH |
| Glaston Corporation |
| Bottero S.p.A. |
| Beijing Hanjiang Automatic Glass Machinery Equipment Co., Ltd. |
| Luoyang North Glass Technology Co., Ltd. |
| Others |
Supply & Pricing Matrix
Hebei province's architectural glass consolidation into fewer, larger facilities with integrated waste heat recovery has compressed supplier margins while elevating pricing power for furnace operators with captive service capabilities. Chinese fabricators prioritize capital cost minimization even as MEE enforcement tightens operating margins, creating bifurcated pricing dynamics between efficiency-compliant and legacy equipment tiers.
Pricing Analysis
Predictive maintenance subscriptions now drive lifetime value capture, with vendors embedding vibration-sensor and thermal-imaging contracts to offset compressed upfront equipment margins. Three-tier pricing structure across premium, standard, and economy levels segments by after-sales bundling intensity and remote diagnostics capability. Cost compression in standard-tier batch systems is intensifying because automotive OEM procurement consolidation forces throughput guarantees at fixed contract rates. Solar energy firms exhibit lowest price sensitivity, accepting premium positioning for zero-contact inline configurations with uptime penalty clauses.
Supply Chain Analysis
Extended payment terms from 90 to 120 days now characterize procurement relationships between European automotive clusters and furnace vendors, straining working capital for mid-tier equipment manufacturers. High-purity alumina-zirconia-silica crucible sourcing draws from concentrated Chinese and Ukrainian producers, exposing operators to input cost volatility. Single-source vulnerability in refractory material supply represents the dominant structural risk. Distribution runs through direct OEM-fabricator relationships for continuous lines, with regional service partners handling batch system aftermarket in fragmented European architectural markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flat glass tempering equipment demand tracks photovoltaic manufacturing cycles, with current solar deployment acceleration indicating an upswing phase through the mid-term projection window.
For Market Incumbents: Harden predictive maintenance service architectures against emerging IoT-native competitors by embedding thermal-imaging diagnostics into standard warranty terms. Deepen backward integration into control system firmware development to reduce retrofit friction at legacy installations. Consolidate regional service partnerships in Gujarat and Tamil Nadu ahead of PLI-scheme capacity buildout. For New Entrants and Emerging Players: Mid-volume architectural producers in Southeast Asia represent the most penetrable entry point, as these operators seek nitrogen oxide emission reductions without premium-tier capital expenditure. Infrared-electric hybrid heating retrofits for existing gas-fired lines offer a service-led entry angle with lower upfront customer commitment. Target BIS certification support as a differentiated value proposition to accelerate Indian market access. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specialized convection engineering expertise concentrates at incumbent OEMs while customer procurement rationalization favors scaled service networks. Acquisition targets should exhibit captive control system development and installed base density in photovoltaic or automotive clusters. Watch MEE enforcement intensity in Hebei and Guangdong as the signal for compliance-driven replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Service Unbundling | Recurring revenue contracts with solar panel manufacturers offset compressed equipment margins. |
| Infrared-Electric Hybrid Heating Retrofit | Sub-90-second thermal response cycles open premium positioning against gas-fired alternatives. |
| Waste Heat Recovery Integration | MEE dual carbon compliance mandates drive architectural glass producer consolidation. |
| Regional Assembly Partnership | Localized production in Gujarat and Tamil Nadu navigates BIS certification timelines. |
| Control System Firmware Captivity | Proprietary PLC architectures reduce competitive threat from IoT-native retrofit specialists. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across furnace OEMs, automotive glass procurement teams, solar panel manufacturing engineers, and aftermarket service directors. Secondary validation drew from MEE enforcement bulletins, EU F-Gas Regulation implementation reports, SEC filings of listed machinery conglomerates, and photovoltaic deployment databases. Bottom-up equipment shipment tallies and top-down glass fabrication capacity estimates were triangulated to anchor market sizing.
Calibration against historical MEE upgrade cycles and EU regulatory phase-in patterns informed trajectory assumptions across the projection horizon. Segmentation modeling spanned product configuration, heating technology, application end-use, and regional regulatory cluster dimensions. CAGRs were derived from installed base turnover rates and greenfield capacity announcements rather than extrapolated trend lines. Natural gas price volatility scenarios and refractory material supply disruption events were incorporated as sensitivity inputs.
Macroeconomic conditions sit as an overlay; deviation in photovoltaic subsidy regimes, automotive production schedules, or natural gas pricing would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement timelines and technology substitution elasticities. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Femtosecond Fiber Lasers Market
Industrial Equipment
Floor Scales Market
Industrial Equipment
Laser Ablation Systems Market
Industrial Equipment
Precision Dispensing Accessories Market
Industrial Equipment
Industrial Vacuum Evaporation Systems Market
Industrial Equipment
Photography Panoramic Tripod Heads Market
Industrial Equipment
Europe Fans and Blowers Market
Industrial Equipment
Asia-Pacific Fans and Blowers Market
Industrial Equipment
Microwave Equipment Market
Industrial Equipment
Europe Fusion Splicer Market
Industrial Equipment
Global DC Drives Market
Industrial Equipment
Laser Drilling Market
Industrial Equipment
Global Thick Film Heater Market
Industrial Equipment
Pin Marking Machine Market
Industrial Equipment
Linear Shaft Motor Market
Industrial Equipment
UV Conveyor Systems Market