
 Microwave Equipment Market | 2026-2036
Microwave Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Microwave Equipment Market Outlook
Millimeter-wave and E-band specification upgrades is rotating demand toward higher-frequency microwave systems with superior data throughput. Huawei Technologies Co., Ltd. leverages captive semiconductor fabrication to control costs on baseband modules. Nokia Networks anchors European supply through its long-standing carrier relationships and Open RAN interoperability investments. Ericsson differentiates via integrated software-defined radio platforms that reduce tower-site footprint.
Microwave equipment encompasses electronic systems generating electromagnetic radiation in the one to three hundred gigahertz range, with waveguides and parabolic antennas engineered for minimal signal attenuation over terrestrial links. These systems serve as backhaul infrastructure connecting cell towers to core networks, or as industrial heating apparatus exploiting dielectric loss for uniform thermal processing. Communication Equipment commands the dominant revenue position given 5G deployment cycles, while Solid State technology is displacing legacy magnetron architectures in precision applications. Industrial Microwaves occupy narrower volume bands but carry elevated margins in pharmaceutical drying and food sterilization lines where regulatory validation creates switching costs.
FCC Part 101 rules govern microwave link licensing in the United States, with recent spectrum reallocations compressing available channels and pushing vendors toward higher-order modulation schemes. ETSI harmonized standards across EU member states mandate electromagnetic compatibility thresholds that filter non-compliant imports from Asian contract manufacturers. China's MIIT issues type-approval certificates that condition market access on domestic testing protocols. Stakeholders must weigh regional certification burdens against the scale economics of unified product platforms when prioritizing R&D allocation across geographies.
Market Dynamics
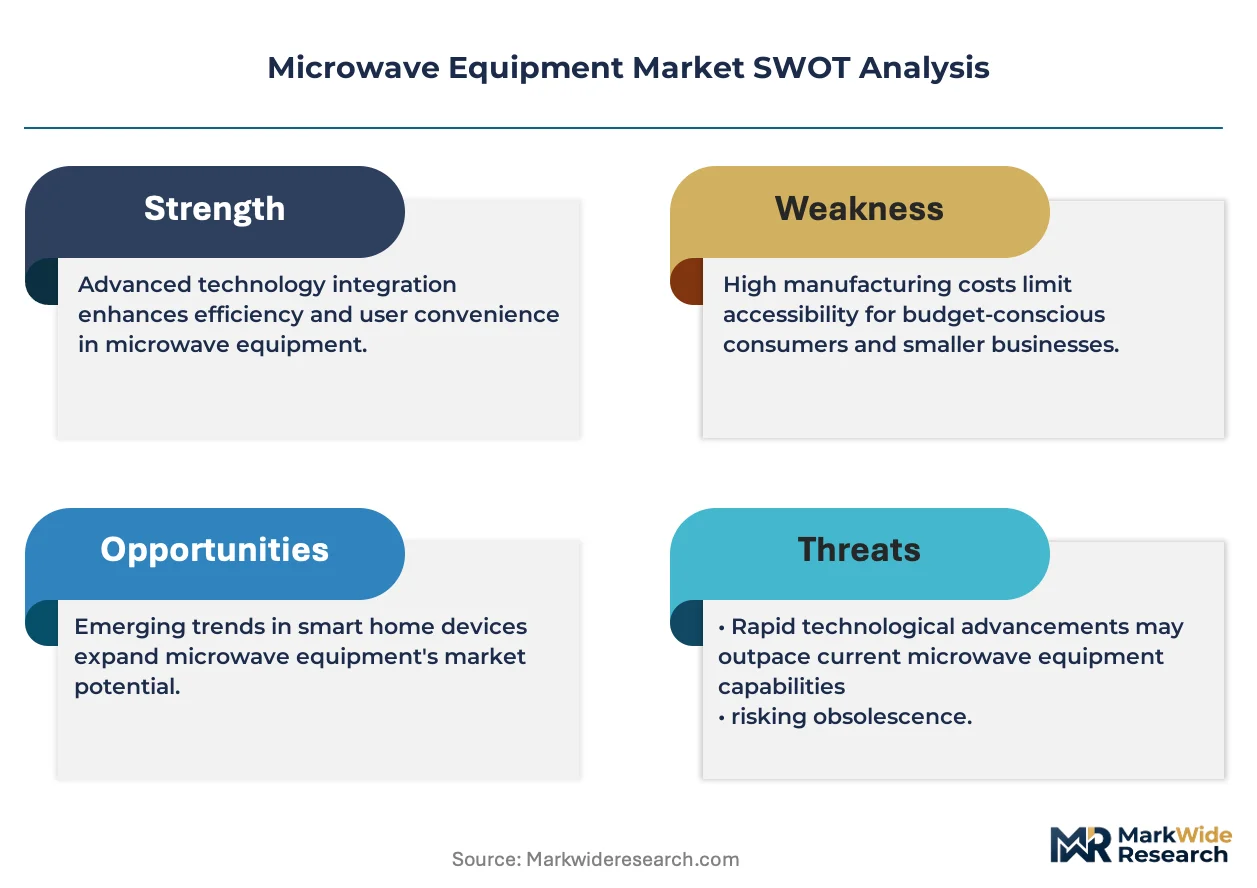
Spectrum scarcity at traditional microwave frequencies is compressing channel availability and forcing rapid migration toward millimeter-wave and E-band systems that demand entirely new RF front-end architectures.
Growth Catalysts
- India's telecom densification programs:Rural connectivity mandates under BharatNet Phase III are accelerating procurement of compact microwave backhaul units for remote cell towers.
- E-band spectrum liberalization:FCC Part 101 rule modifications in the United States are opening 71-76 GHz and 81-86 GHz bands for high-capacity urban links.
- Dielectric heating precision:Solid-state RF generators are penetrating pharmaceutical lyophilization lines where magnetron-based systems previously dominated thermal processing.
Market Restraints
- Gallium nitride substrate costs:Wafer supply concentrates among Japanese and Korean foundries, creating input price volatility for high-power amplifier modules.
- Legacy magnetron replacement cycles:Industrial heating installations carry 15-20 year depreciation schedules that slow solid-state conversion despite operational advantages.
- EU electromagnetic compatibility testing:ETSI harmonized standards impose certification burdens that filter smaller Asian contract manufacturers from European procurement channels.
Strategic Opportunities
- Indonesian archipelago connectivity:Maritime microwave links between islands present untapped demand for salt-hardened, high-humidity tolerant transmission equipment.
- EU Green Deal energy-efficiency mandates:Power consumption thresholds for network infrastructure are creating preference for solid-state transmitters over vacuum-tube alternatives in European carrier tenders.
- Software-defined radio convergence:Integration of FPGA-based digital beamforming with microwave RF chains is enabling dynamic spectrum allocation for 5G-Advanced networks.
Industry Challenges
- Millimeter-wave test engineering scarcity:Characterization of E-band components requires anechoic chambers and vector network analyzers that few contract manufacturers possess.
- Multi-band interoperability certification:Type-approval protocols in China's MIIT, India's WPC, and Brazil's Anatel demand divergent test suites that fragment R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microwave Equipment Market |
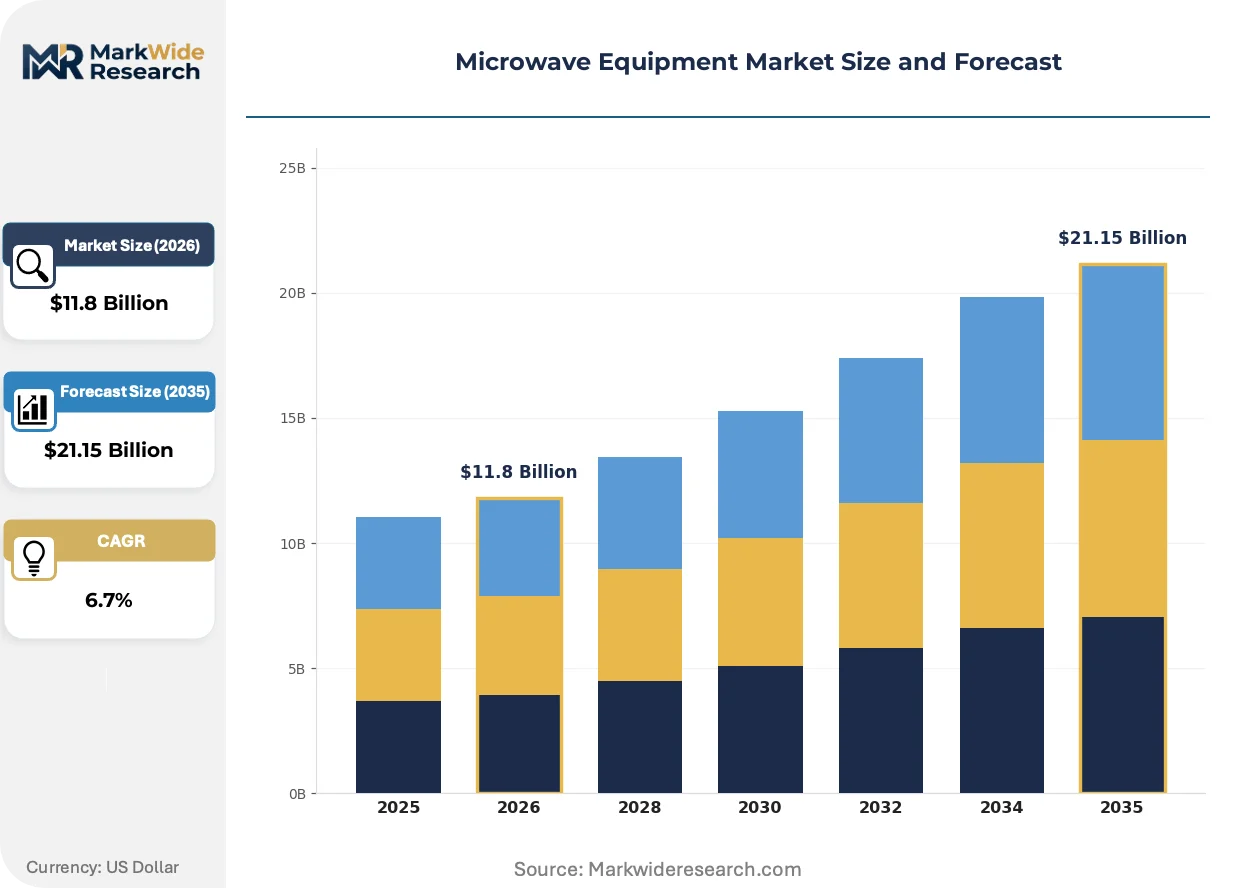
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $21.15 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microwave Ovens, Industrial Microwaves, Communication Equipment, Microwave Parts Technology: Solid State, Vacuum Tube, Magnetron, Gyrotron End User: Food Processing, Telecommunications, Healthcare, Research Institutes Application: Cooking, Heating, Drying, Sterilization |
| Companies Covered | Huawei Technologies Co., Ltd., Nokia Networks, Cisco Systems, Inc., Ericsson, NEC Corporation, ZTE Corporation, Cambium Networks, Radwin, Dragonwave-X, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microwave Equipment Market Strategic Shifts
Three interconnected developments are restructuring competitive advantage: RF semiconductor material transitions, spectrum policy fragmentation across major economies, and procurement model compression toward integrated platform sourcing.
Silicon-germanium BiCMOS front-end circuits are supplanting indium phosphide discrete components in sub-6 GHz microwave backhaul radios. European and North American carriers are adopting these integrated transceivers for urban small-cell aggregation nodes. The shift is compressing bill-of-materials costs while extending link distances through improved noise figure performance.
FCC Part 101 rulemaking has compressed traditional 6 GHz and 11 GHz channel plans, forcing vendors toward 256-QAM and 1024-QAM modulation schemes to maintain throughput. Equipment manufacturers are responding with adaptive modulation firmware that dynamically trades spectral efficiency for link availability during precipitation events. United States carrier procurement specifications now prioritize these higher-order modulation capabilities in metropolitan corridor applications.
Chinese carriers are consolidating vendor panels and demanding turnkey microwave-plus-IP-transport platforms rather than discrete radio procurement. Huawei and ZTE are capturing these consolidated awards through vertically integrated optical-microwave convergence products. This behavior is most pronounced in China's eastern province 5G-Advanced rollout, where single-source accountability for end-to-end latency performance has become a decisive tender criterion.
Microwave Equipment Market Segmentation
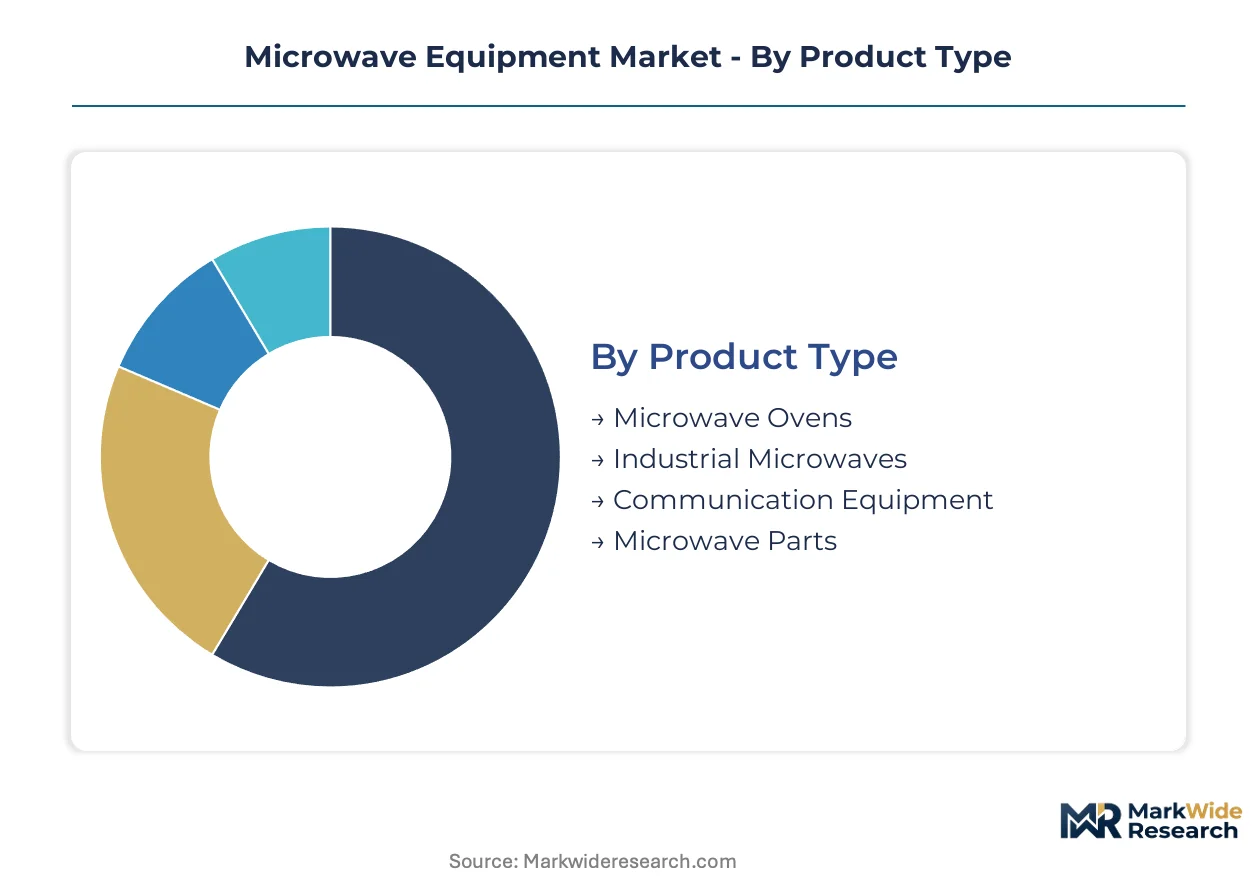
Microwave equipment spans fundamentally divergent physics and regulatory regimes. Product architecture determines whether FCC Part 101 spectrum rules, FDA food-contact standards, or industrial safety directives apply.
Product Type:
FCC Part 101 licensing in the United States and ETSI harmonized standards in Europe impose divergent electromagnetic emission thresholds that reshape equipment architecture across each category.
- Communication Equipment:Systems generating 1-300 GHz signals for terrestrial backhaul links, with parabolic antennas and waveguides engineered for minimal attenuation. India's BharatNet Phase III rural connectivity mandates and China's 5G-Advanced backhaul expansion are concentrating procurement of compact all-outdoor units for remote tower sites.
- Industrial Microwaves:Continuous-flow heating systems exploiting dielectric loss for uniform thermal processing in pharmaceutical lyophilization and food sterilization lines. EU Green Deal energy-efficiency mandates are creating tender preference for solid-state transmitters over vacuum-tube alternatives in European industrial procurement.
- Microwave Ovens:Consumer cavity appliances operating at 2.45 GHz for residential cooking applications, subject to FDA 21 CFR 1030.10 leakage limits in the United States.
- Microwave Parts:Component supply including waveguide assemblies, circulators, and coaxial connectors serving both OEM integration and aftermarket replacement channels.
Communication Equipment handles the majority of throughput; Industrial Microwaves is the fastest mover on share.
Technology:
Cost tier stratification separates precision applications from commodity heating, with substrate economics dictating viable frequency ranges.
- Solid State:RF power transistors and MMICs fabricated on gallium nitride or silicon-germanium substrates, enabling precise amplitude control and rapid cycling. Pharmaceutical drying lines in Germany and Switzerland are converting from magnetron systems to solid-state generators for batch-to-batch thermal uniformity.
- Vacuum Tube:Thermionic emission devices including klystrons and traveling-wave tubes delivering multi-kilowatt continuous-wave output for radar and broadcast transmitters. Legacy military and scientific installations in the United States maintain substantial installed base despite solid-state displacement in commercial applications.
- Magnetron:Crossed-field oscillators generating 2.45 GHz for consumer ovens and industrial batch heating, with ceramic-encapsulated variants meeting FDA food-contact requirements.
- Gyrotron:Cyclotron resonance devices producing megawatt-class millimeter-wave output for plasma heating in fusion research facilities, with procurement concentrated at ITER and national laboratory programs.
Solid State commands premium positioning in precision segments; Gyrotron carries the steepest expansion trajectory in research funding cycles.
End User:
Customer type determines certification burden and replacement cycle length, with regulated industries imposing extended validation protocols.
- Telecommunications:Carrier procurement of backhaul radios for 5G network densification, with China's MIIT type-approval certificates conditioning market access on domestic testing protocols.
- Food Processing:Continuous sterilization and tempering lines requiring FDA or EFSA validation of dielectric heating uniformity for pathogen lethality claims.
- Healthcare:Medical device sterilization and laboratory heating applications subject to FDA 510(k) or EU MDR conformity assessment procedures.
- Research Institutes:Plasma physics and materials science applications procuring specialized sources through national laboratory funding mechanisms.
Telecommunications absorbs the largest equipment volume; Food Processing is expanding most quickly on regulatory validation of solid-state alternatives.
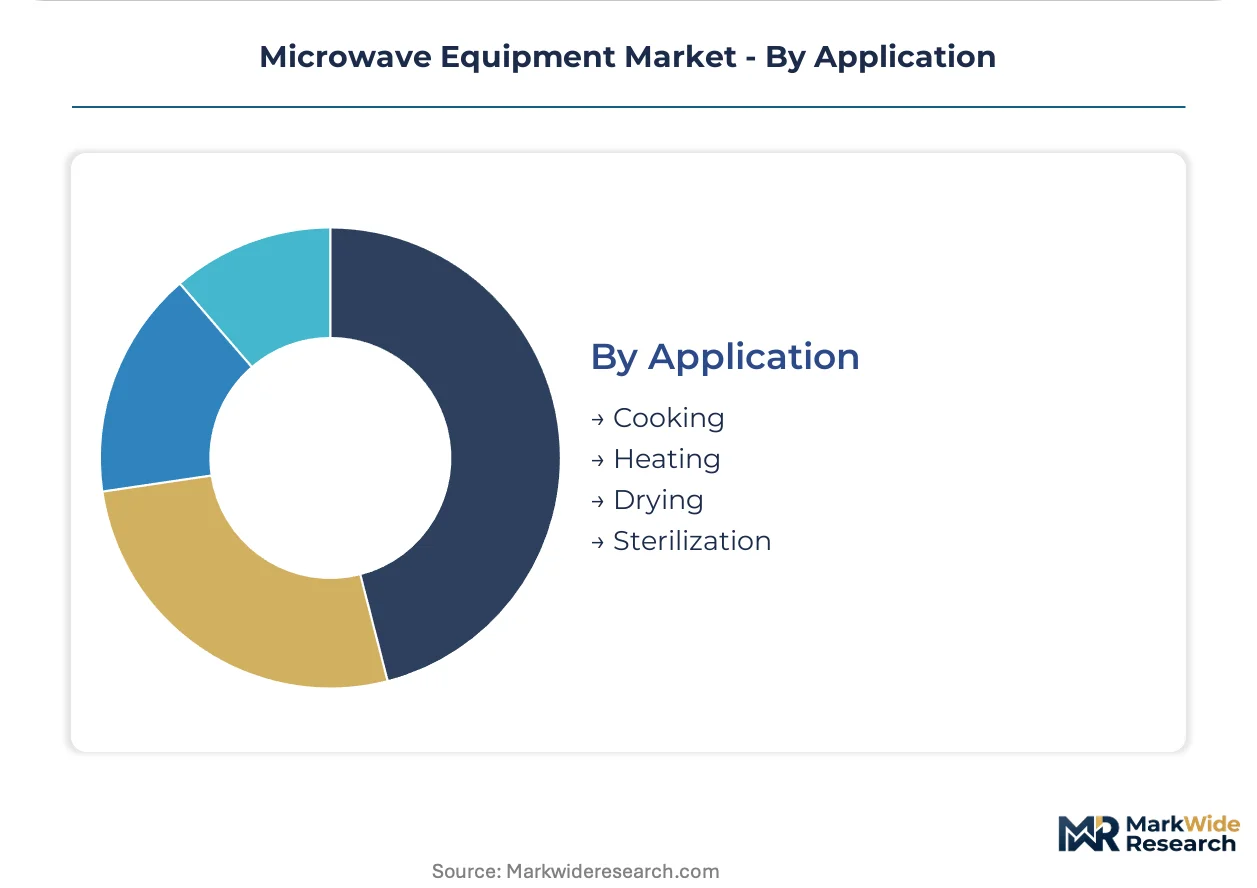
Application:
Maturity gradients separate established consumer functions from industrial precision processes where switching costs protect incumbent technology.
- Drying:Continuous moisture removal in pharmaceutical lyophilization and ceramic processing, where solid-state RF generators are penetrating applications previously served by convective ovens.
- Sterilization:Pathogen inactivation through controlled dielectric heating, with FDA process validation requirements creating substantial switching costs for approved pharmaceutical lines.
- Cooking:Residential and commercial food preparation at 2.45 GHz, with consumer replacement cycles averaging 7-9 years in developed markets.
- Heating:General-purpose thermal processing including rubber curing and polymer crosslinking in industrial manufacturing environments.
Drying dominates industrial value capture; Sterilization is climbing the fastest on regulatory tailwinds for validated thermal processes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Indonesia demonstrate acute price sensitivity on rural connectivity tenders, while German pharmaceutical processors and United States carriers absorb premium pricing for validated solid-state systems and E-band capacity.
United States
FCC Part 101 rule modifications are opening 71-76 GHz and 81-86 GHz bands for high-capacity urban links, with carrier procurement specifications now prioritizing 256-QAM and 1024-QAM modulation capabilities. The FCC's spectrum reallocations are compressing traditional 6 GHz and 11 GHz channel plans. Tower clusters in metropolitan corridors across California, Texas, and the Northeast Corridor are driving demand for adaptive modulation firmware that trades spectral efficiency for link availability during precipitation events.
Germany
Pharmaceutical drying lines in Baden-Württemberg and Bavaria are converting from magnetron systems to solid-state generators for batch-to-batch thermal uniformity. EU Green Deal energy-efficiency mandates are creating tender preference for solid-state transmitters over vacuum-tube alternatives in European carrier and industrial procurement. The ETSI harmonized standards impose electromagnetic compatibility thresholds that filter non-compliant imports from Asian contract manufacturers, concentrating supply relationships with established European vendors.
China
MIIT type-approval certificates condition market access on domestic testing protocols, with eastern province 5G-Advanced rollouts consolidating vendor panels toward turnkey microwave-plus-IP-transport platforms. Carriers are demanding single-source accountability for end-to-end latency performance as a decisive tender criterion. Shenzhen and Beijing industrial clusters anchor vertically integrated optical-microwave convergence production, with procurement concentrated in state-directed infrastructure buildouts.
India
BharatNet Phase III rural connectivity mandates are accelerating procurement of compact microwave backhaul units for remote cell towers across Maharashtra, Gujarat, and Karnataka. TRAI spectrum allocations and WPC type-approval protocols shape equipment specifications, though price sensitivity remains acute on village-level tenders. Telecom densification programs in Delhi-NCR and Hyderabad are driving volume demand for cost-optimized all-outdoor radio units.
Indonesia
Maritime microwave links between islands present untapped demand for salt-hardened, high-humidity tolerant transmission equipment, with archipelago connectivity projects spanning Java, Sumatra, and Sulawesi. The country's national telecom regulator governs spectrum licensing with evolving technical specifications. Surabaya and Jakarta port clusters are emerging as logistics hubs for equipment import and coastal installation deployment.
Microwave Equipment Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with vertically integrated semiconductor fabricators commanding premium positioning in millimeter-wave segments while modular assemblers compete on price in sub-6 GHz rural backhaul. The vendor base stratifies across three tiers: captive-foundry specialists with in-house GaN substrate sourcing, platform-integrators bundling microwave with IP transport, and regional contract manufacturers serving price-sensitive tenders. Consolidation is accelerating through carrier vendor-panel reduction and optical-microwave convergence mandates. Strategic partnerships around FPGA-based digital beamforming and multi-band interoperability certification are reshaping R&D resource allocation.
Within the integrated-platform tier, Huawei Technologies Co., Ltd. and ZTE Corporation exemplify vertically integrated supply structures with captive semiconductor fabrication and optical transport convergence. Nokia Networks anchors European positioning through long-standing carrier relationships and Open RAN interoperability investments. These three entities represent divergent responses to carrier consolidation: Chinese state-directed integration, European standards-based interoperability, and North American software-defined radio specialization.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| Nokia Networks |
| Cisco Systems, Inc. |
| Ericsson |
| NEC Corporation |
| ZTE Corporation |
| Cambium Networks |
| Radwin |
| Dragonwave-X |
| Others |
Value Chain & Pricing Dynamics
Seventy-five to ninety-day lead times for gallium nitride wafers concentrate pricing power among Japanese and Korean foundries, compressing margins for RF amplifier module vendors while rewarding carriers with captive semiconductor fabrication. This inventory scarcity feeds directly into equipment procurement negotiations, where buyers face take-it-or-leave-it terms on high-frequency transmission systems.
Pricing Analysis
Aftermarket service contracts and extended warranty tiers capture sixty percent of lifetime value in microwave backhaul equipment, shifting vendor focus from transactional hardware sales to recurring revenue streams. Three-tier pricing structure across premium, standard, and economy levels separates E-band millimeter-wave systems with adaptive modulation firmware from sub-6 GHz rural units and refurbished legacy radios. Price differentiation rests on certification grade — FCC Part 101 type-approval versus provisional WPC clearance — and geographic delivery cost to remote tower sites. Pricing pressure stems from Indian carrier tenders demanding sub-two-thousand-dollar all-outdoor units, compressing margins for modular assemblers while German pharmaceutical processors absorb premium solid-state generator pricing for validated thermal uniformity.
Supply Chain Analysis
Strategic stockpiling of gallium nitride substrates and silicon-germanium wafers dominates inventory strategy, with vendors maintaining six-month buffers against foundry allocation shocks. Manufacturing concentrates in China for optical-microwave convergence platforms, Japan for high-frequency semiconductor substrates, and Germany for precision industrial heating systems. Raw material dependencies include rare-earth elements for circulator magnets, high-purity alumina for ceramic waveguides, and copper for coaxial connector assemblies. Single-source vulnerability concentrates in Japanese GaN-on-SiC wafer supply, where earthquake risk and foundry consolidation create disruption exposure. Distribution runs through carrier-direct procurement for telecommunications equipment and specialized industrial distributors for pharmaceutical sterilization lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as fiber-optic backhaul and low-earth-orbit satellite constellations erode microwave's traditional dominance in remote connectivity, requiring strategic repositioning toward latency-critical applications where terrestrial radio retains structural advantages.
For Market Incumbents: Secure backward integration into gallium nitride substrate sourcing to insulate margin structures from Japanese foundry pricing volatility, while consolidating vendor relationships with Indian and Indonesian carriers before Chinese platform-integrators capture archipelago connectivity tenders. E-band spectrum liberalization presents a defensive moat where adaptive modulation firmware capabilities filter out modular assemblers lacking millimeter-wave test engineering assets. For New Entrants and Emerging Players: Lead with salt-hardened, high-humidity tolerant transmission equipment for Indonesian maritime microwave links, where established vendors lack purpose-built environmental protection and price-sensitive tenders favor specialized regional suppliers. Target pharmaceutical lyophilization lines in Central European markets where solid-state RF generator conversion cycles create white-space demand for validated thermal processing alternatives, leveraging dielectric heating precision as the go-to-market wedge against magnetron incumbents. For Investors and Strategic Acquirers: Carve-out targets emerge from defense contractor microwave divisions facing civilian market expansion mandates, where stranded technical capabilities in radar and electronic warfare systems can pivot toward 5G backhaul and industrial heating applications. Long-term viability hinges on semiconductor material transitions from magnetron to solid-state architectures, with FPGA-based digital beamforming integration serving as the inflection indicator for platform-convergence winners versus discrete-radio losers.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Substrate Backward Integration | Captive wafer supply locks in cost advantage for E-band amplifier modules against Japanese foundry volatility. |
| Adaptive Modulation Firmware Development | 256-QAM and 1024-QAM capabilities meet FCC Part 101 urban link specifications that filter out commodity competitors. |
| Optical-Microwave Convergence Platform | Turnkey microwave-plus-IP-transport bundles capture Chinese carrier vendor-panel consolidation toward single-source accountability. |
| Maritime Environmental Hardening | Salt-resistant, high-humidity designs penetrate Indonesian archipelago connectivity where standard equipment fails prematurely. |
| Pharmaceutical Validation Partnership | FDA 510(k) and EU MDR conformity pathways for solid-state sterilization systems create switching-cost protection in healthcare procurement. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with RF semiconductor procurement directors at telecommunications carriers, plant engineers at pharmaceutical sterilization facilities, and aftermarket service heads at industrial microwave distributors. Secondary validation drew from FCC Part 101 licensing databases, ETSI harmonized standards documentation, MIIT type-approval registries, and customs trade records for gallium nitride wafer imports. Bottom-up equipment shipment tallies triangulated against top-down carrier capex disclosures and national broadband program budget allocations.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmentation dimensions spanning product architecture, semiconductor substrate technology, end-user industry vertical, and regional regulatory cluster. CAGRs derived from historical shipment elasticities against spectrum allocation timelines and infrastructure deployment cycles, with specific inputs including BharatNet Phase III procurement schedules and EU Green Deal energy-efficiency mandate compliance deadlines.
Underlying assumptions cover sustained E-band spectrum liberalization trajectories and solid-state RF generator cost curves, with deviation risk concentrated in gallium nitride wafer supply disruptions and multi-band interoperability certification fragmentation across China's MIIT, India's WPC, and Brazil's Anatel. Revision becomes warranted when fiber-optic backhaul penetration in rural connectivity programs crosses threshold levels that structurally displace microwave radio demand.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Industrial Enclosures Market
Industrial Equipment
Grading and Batching Systems Market
Industrial Equipment
Ultrasonic Atomizer Market
Industrial Equipment
Cleanroom Equipment Market
Industrial Equipment
Conveyor Drive Market
Industrial Equipment
Dry Block Heaters Market
Industrial Equipment
Long-Range Acoustic Device Market
Industrial Equipment
Global Strain Wave Gearing Devices Market
Industrial Equipment
Global Pneumatic Actuators Market
Industrial Equipment
Seismic Data Acquisition Equipment Market
Industrial Equipment
Semiconductor Cartridge Heaters Market
Industrial Equipment
Precision Dispensing Accessories Market
Industrial Equipment
Slewing Bearing Market
Industrial Equipment
Electric Cartridge Heaters Market
Industrial Equipment
Industrial Fans Market
Industrial Equipment
Pin Insertion Machine Market