
 Refrigeration Coolers Market | 2026-2036
Refrigeration Coolers Market Size, Share, and Industry Trends Forecast 2026-2036
Refrigeration Coolers Market Analytics
The EU F-Gas Regulation is pivoting European food retail toward lower-GWP refrigerant architectures. Carrier Global Corporation leverages its compressor manufacturing scale to anchor retrofit programs across EU supermarket chains. Daikin Industries, Ltd. competes through specialized CO2 transcritical systems for northern European climates. Johnson Controls International plc extends its building automation integration to capture full-facility energy contracts.
Refrigeration coolers are thermally insulated enclosures engineered to maintain temperatures between 0°C and 4°C for perishable goods preservation, utilizing polyurethane foam insulation and hermetic compressor circuits to achieve coefficient of performance ratings above 2.5. Walk-in coolers dominate commercial infrastructure deployments due to their modular panel construction and scalable cubic-meter configurations. Vapor compression technology sustains overwhelming market presence despite thermoelectric advances gaining traction in compact display cases for convenience stores. Magnetic refrigeration occupies emerging R&D pipelines with prototype systems achieving temperature spans relevant to medical cold chains.
The US EPA SNAP program and Japan's METI refrigerant roadmap collectively constrain hydrofluorocarbon availability while certifying alternative chemistries for commercial deployment. China's MEE enforces GB standards that phase down high-GWP substances in domestic manufacturing, reshaping export compliance requirements for multinational suppliers. Stakeholders must monitor refrigerant quota allocation mechanisms and compressor efficiency benchmarks as these frameworks tighten product eligibility criteria across major economies.
Market Dynamics
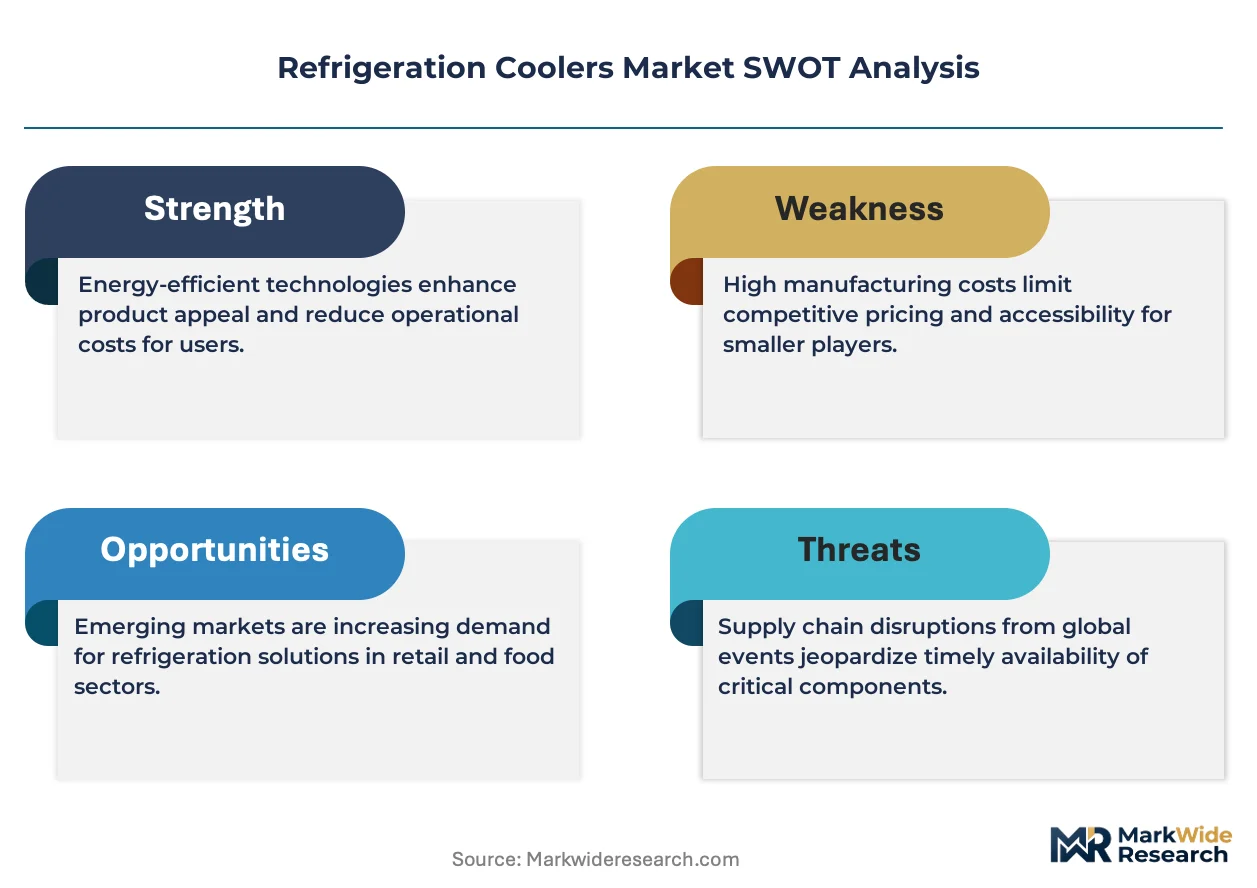
The EU F-Gas Regulation is compressing hydrofluorocarbon supply chains while mandating natural refrigerant transitions across commercial cold storage, fundamentally restructuring equipment procurement criteria and retrofit timelines for European food retail operators.
Growth Catalysts
- Natural refrigerant mandates:The EU F-Gas Regulation phases down high-GWP substances, compelling supermarket chains to accelerate CO2 and ammonia system deployments.
- Quick-service restaurant expansion:India's QSR sector drives walk-in cooler demand for centralized kitchen infrastructure and frozen inventory management.
- Cold-chain fleet retrofits:Southeast Asian logistics operators upgrade refrigerated transport containers to meet pharmaceutical and fresh produce distribution standards.
Market Restraints
- Copper and aluminum price volatility:Raw material cost swings for heat exchanger components compress manufacturer margins and destabilize equipment pricing.
- Compressor supply concentration:European and Japanese hermetic compressor specialists control critical component availability, creating bottleneck risks for system integrators.
- CO2 transcritical climate limitations:Ambient temperature thresholds constrain natural refrigerant system efficiency in subtropical and tropical operating environments.
Strategic Opportunities
- Medical cold chain expansion:Vaccine distribution networks in Indonesia and Vietnam require ultra-low temperature storage infrastructure with redundant backup systems.
- Building automation convergence:Integration of refrigeration controls with HVAC and lighting management platforms enables full-facility energy performance contracting.
- US EPA SNAP incentives:Alternative refrigerant certification pathways accelerate hydrocarbon and HFO adoption in commercial display case retrofits.
Industry Challenges
- Natural refrigerant technician scarcity:CO2 and ammonia system installation and maintenance requires specialized certification programs that training institutions have not scaled to match equipment deployment rates.
- Legacy control system integration:Retrofitting smart monitoring and predictive maintenance capabilities into existing hermetic compressor circuits demands custom engineering and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refrigeration Coolers Market |
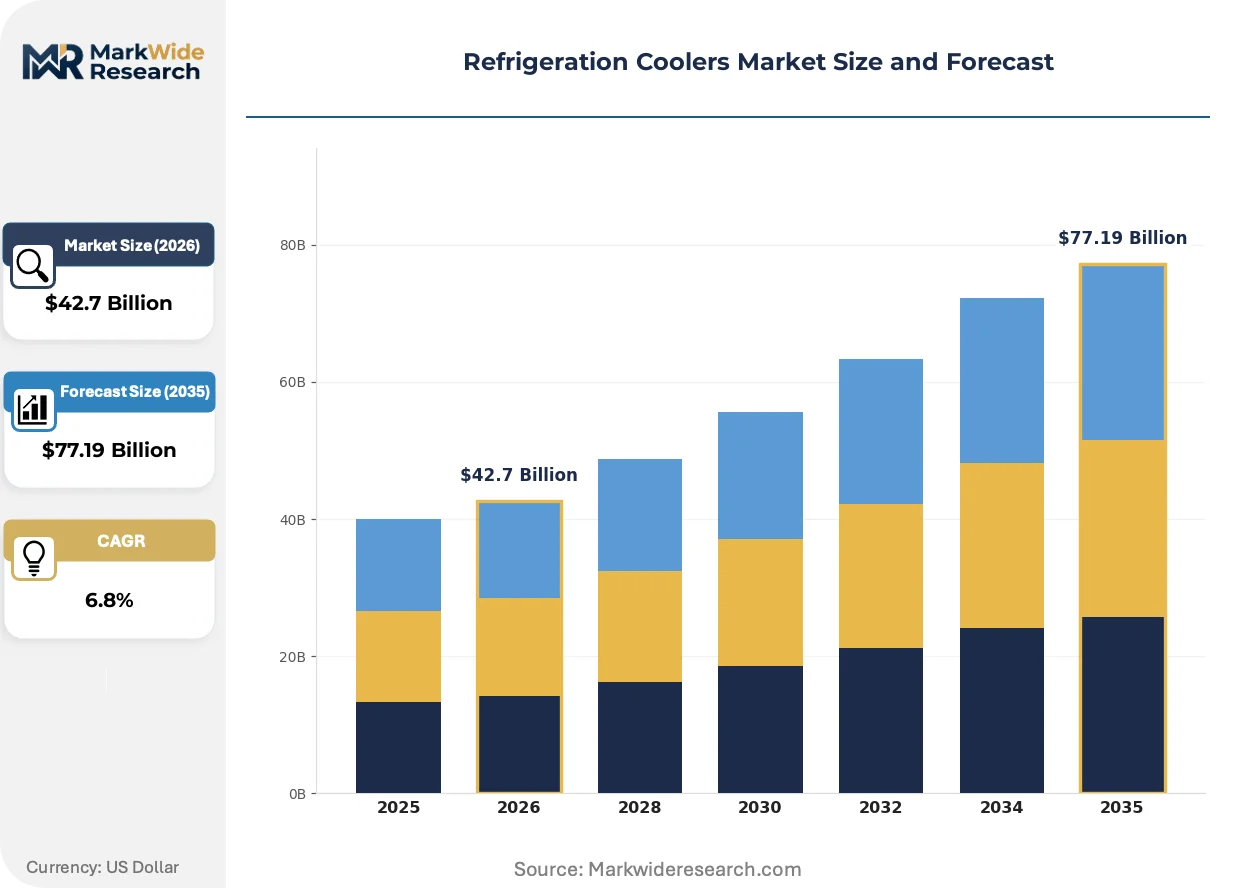
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $77.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Coolers, Display Cases, Ice Cream Freezers, Walk-in Coolers End User: Convenience Stores, Restaurants, Supermarkets, Hotels Technology: Vapor Compression, Absorption, Thermoelectric, Magnetic Refrigeration Capacity: Small, Medium, Large, Extra-Large |
| Companies Covered | Daikin Industries, Ltd., Carrier Global Corporation, Emerson Electric Co., Danfoss A/S, Johnson Controls International plc, Trane Technologies plc, Electrolux, Haier Inc., AHT Cooling Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refrigeration Coolers Market Evolving Landscape
Refrigeration equipment is pivoting from standalone thermal hardware to connected energy assets, with compressor intelligence, refrigerant chemistry, and procurement models all undergoing simultaneous transformation.
CO2 transcritical booster systems are expanding into southern European supermarket applications previously dominated by hydrofluorocarbon architectures. Spanish and Italian food retailers now specify these units for stores in Madrid, Rome, and Barcelona where ambient conditions previously disqualified natural refrigerant performance. The technology is expanding into climate zones once considered inaccessible, compressing the addressable market for conventional synthetic refrigerant equipment.
The EU F-Gas Regulation tightens refrigerant quota allocations annually through 2030, forcing importers and equipment manufacturers to document lifecycle GWP calculations. Commercial refrigeration OEMs now embed refrigerant charge minimization into compressor circuit design, while service providers track leak rates for regulatory compliance reporting. Northern European supermarket chains respond fastest, with Denmark and Sweden already achieving majority natural refrigerant penetration in new build specifications.
Third-party cold storage operators now bundle refrigeration equipment with temperature monitoring and energy management under performance-based contracts. Food manufacturers and pharmaceutical distributors in Germany and the Netherlands prefer vendors who guarantee uptime and thermal compliance rather than owning capital equipment directly. This procurement restructuring shifts risk to equipment suppliers while compressing traditional hardware-only sales cycles.
Refrigeration Coolers Market Segmentation
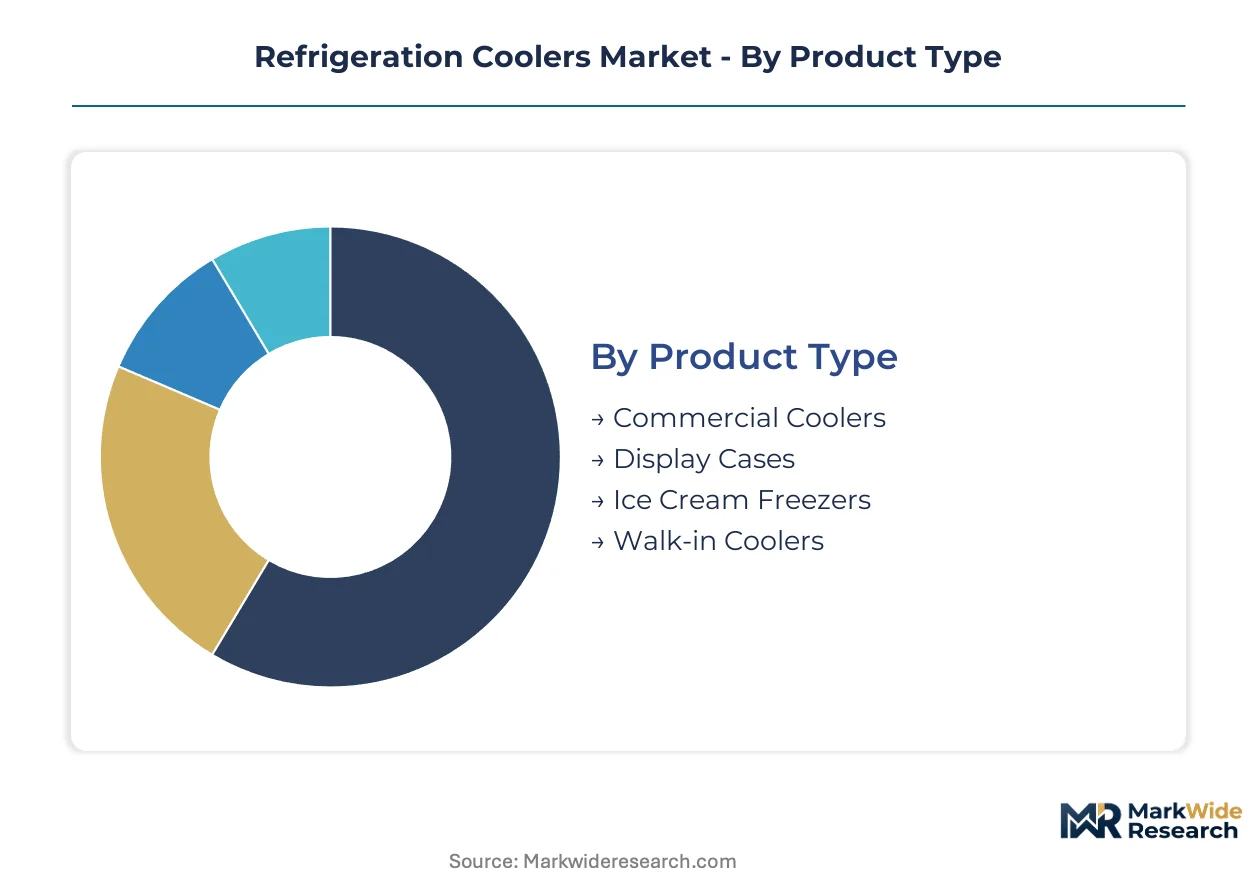
Equipment specification, end-use thermal requirements, and refrigerant chemistry together determine procurement patterns across the refrigeration coolers market. Segmentation reveals how technology maturity, capacity scale, and buyer operational models create distinct competitive arenas for suppliers.
Product Type:
Buyers differentiate primarily by installation footprint and whether equipment serves customer-facing display or back-of-house storage functions.
- Walk-in Coolers:Modular polyurethane panel systems with hermetic compressor circuits enable scalable cubic-meter configurations for centralized cold storage. India's quick-service restaurant chains deploy these for frozen inventory hubs in Bangalore and Mumbai, driven by centralized kitchen infrastructure buildouts.
- Display Cases:Glass-fronted units with LED illumination and gravity coil evaporators maintain 0°C to 4°C for customer-facing merchandise presentation. European supermarket retrofit programs under the EU F-Gas Regulation accelerate CO2-compatible display case procurement across Denmark and Sweden.
- Commercial Coolers:Reach-in and under-counter configurations serve foodservice prep areas with compact footprints and rapid door-recovery performance.
- Ice Cream Freezers:Hard-top and glass-lid units maintain -18°C to -24°C with forced-air or static cooling for frozen dessert retail.
Walk-in coolers lead volumes today; display cases are gaining share fastest.
End User:
Operational intensity and regulatory exposure shape equipment selection across buyer categories.
- Supermarkets:Full-facility cold chains integrate multiple temperature zones from -25°C frozen storage through 15°C produce displays. German and Dutch food retailers now prefer performance-based equipment contracts bundling refrigeration with energy management and uptime guarantees.
- Restaurants:Quick-service and full-service operators prioritize rapid recovery times and compact footprints for high-turnover kitchen environments. India's QSR sector drives walk-in cooler demand for frozen protein and dairy inventory management.
- Convenience Stores:Limited floor space demands vertical display cases and slim-line beverage coolers with 24/7 reliability.
- Hotels:Banquet and room-service operations require discrete under-counter units with low acoustic signatures for guest area proximity.
Supermarkets anchor current procurement volumes; restaurants show the steepest expansion trajectory.
Technology:
Energy efficiency benchmarks and refrigerant chemistry availability determine technology adoption timelines.
- Vapor Compression:Hermetic and semi-hermetic compressor circuits dominate with coefficient of performance ratings above 2.5, though hydrofluorocarbon phase-downs under the EU F-Gas Regulation and US EPA SNAP program constrain refrigerant selection.
- Thermoelectric:Solid-state Peltier modules eliminate moving parts for compact display cases in convenience stores where maintenance access is limited and noise restrictions apply.
- Absorption:Heat-activated systems using ammonia-water or lithium bromide pairs suit facilities with waste heat recovery or off-grid thermal energy sources.
- Magnetic Refrigeration:Magnetocaloric effect prototypes achieve temperature spans relevant to medical cold chains, occupying emerging R&D pipelines without commercial scale.
Vapor compression holds dominant share; thermoelectric systems are climbing the fastest in compact applications.
Capacity:
Volume throughput and inventory turnover velocity dictate cubic-meter requirements.
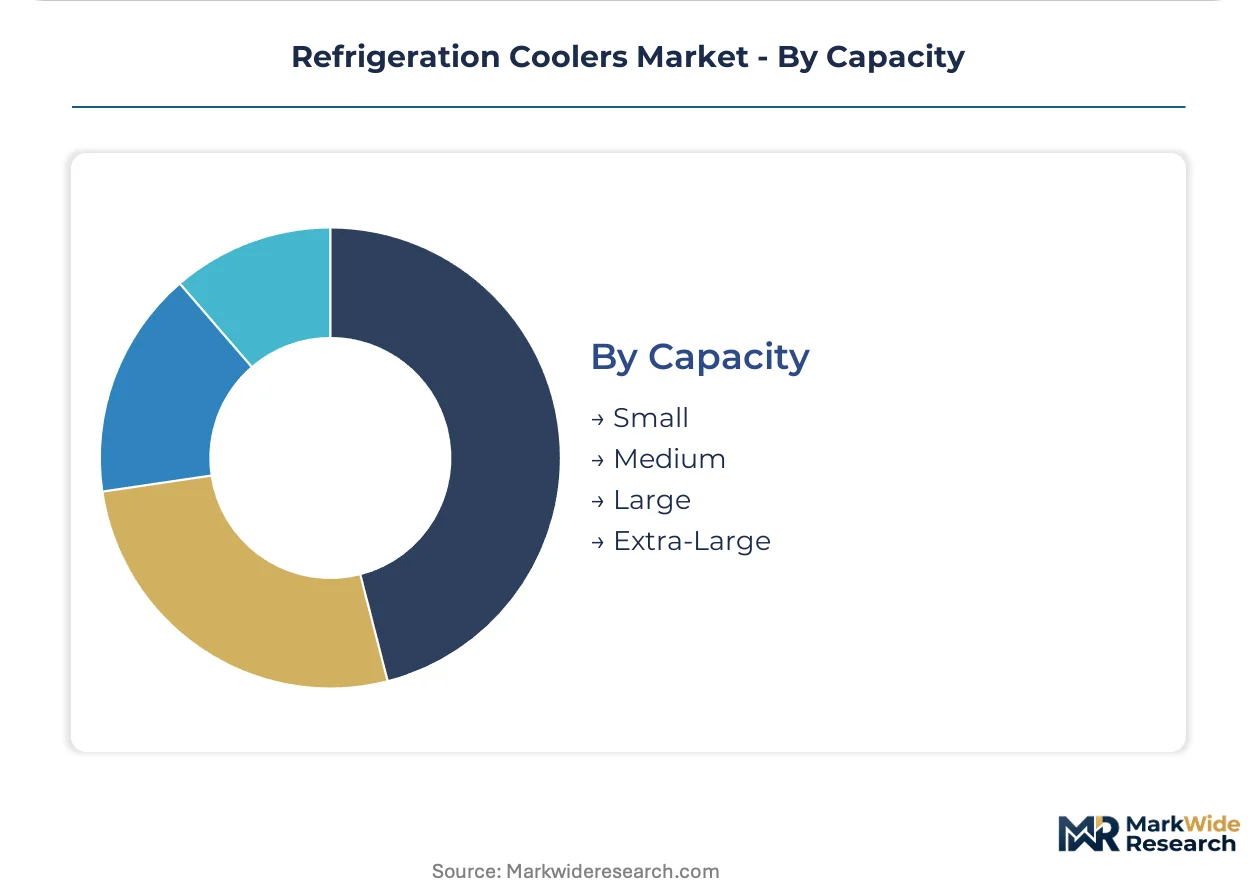
- Large:Exceeding 50 cubic meters, these systems serve distribution centers and central kitchens with multiple compressor racks and redundant temperature zones. Southeast Asian cold-chain logistics operators specify large-capacity units for pharmaceutical and fresh produce fleet retrofits.
- Extra-Large:Above 100 cubic meters, custom-engineered systems integrate with building automation for full-facility energy performance contracting in German industrial food processing.
- Medium:20-50 cubic meter configurations balance footprint and storage volume for independent restaurants and regional supermarkets.
- Small:Under 20 cubic meter units serve convenience stores, hotel pantries, and specialty retail with plug-and-play installation.
Large capacity systems lead installed base; extra-large configurations are expanding most quickly in automated distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The refrigeration coolers industry traces its commercial origins to early twentieth-century industrial cold storage facilities in the United States, where mechanical compression systems first achieved scale in meatpacking and dairy distribution networks before spreading to European and Asian manufacturing centers.
United States
Quick-service restaurant chains and pharmaceutical cold-chain operators drive equipment procurement across Texas, California, and the Midwest. The US EPA SNAP program certifies alternative refrigerant chemistries while constraining hydrofluorocarbon availability for commercial retrofits. Chicago and Dallas-Fort Worth anchor centralized kitchen infrastructure buildouts for frozen inventory management.
Germany
Supermarket chains and third-party cold storage operators prioritize performance-based equipment contracts bundling refrigeration with energy management. The EU F-Gas Regulation mandates annual quota reductions through 2030, forcing natural refrigerant transitions. The Rhine-Ruhr industrial corridor hosts dense clusters of system integrators serving Dutch and Belgian cross-border distribution.
India
Quick-service restaurant expansion in Bangalore, Mumbai, and Delhi-NCR generates walk-in cooler demand for centralized kitchen infrastructure. The Bureau of Indian Standards enforces energy efficiency labeling for commercial refrigeration equipment under its mandatory certification scheme. Gujarat and Maharashtra host manufacturing facilities supplying domestic QSR chains and Southeast Asian export markets.
Japan
Convenience store operators and precision medical cold-chain networks specify compact display cases with ultra-low temperature reliability. METI's refrigerant roadmap phases down high-GWP substances while promoting CO2 and hydrocarbon alternatives. The Kanto region around Tokyo concentrates compressor technology R&D and advanced manufacturing for regional export.
Vietnam
Pharmaceutical distributors and fresh produce exporters upgrade refrigerated transport and storage infrastructure to meet international compliance standards. The country's national environmental regulator implements refrigerant import controls aligned with Montreal Protocol phase-down schedules. Ho Chi Minh City and Hanoi anchor cold-chain logistics hub development for ASEAN market access.
Refrigeration Coolers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across refrigerant technology sophistication and building automation integration depth. The vendor base spans multinational industrial conglomerates with compressor manufacturing scale, specialized natural refrigerant system integrators, and regional fabricators serving price-sensitive retrofit markets. Three archetypes dominate: full-facility energy contractors, component-scale compressor specialists, and climate-specific technology licensors. Consolidation pressures favor M&A activity among European system integrators, while capacity expansion concentrates in Asian manufacturing for QSR export demand.
Within the full-facility energy contracting tier, Carrier Global Corporation and Johnson Controls International plc exemplify archetypes combining refrigeration hardware with building automation platforms. Daikin Industries, Ltd. occupies a position representing specialized CO2 transcritical system development for northern European climates. These three anchors illustrate how competitive positioning diverges between scale-driven component supply and integrated performance contracting models.
| Leading Market Players |
|---|
| Daikin Industries, Ltd. |
| Carrier Global Corporation |
| Emerson Electric Co. |
| Danfoss A/S |
| Johnson Controls International plc |
| Trane Technologies plc |
| Electrolux |
| Haier Inc. |
| AHT Cooling Systems |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between natural refrigerant-compliant systems and legacy hydrofluorocarbon equipment manifests in both procurement premiums and supply chain bifurcation. Buyers in Germany and Sweden absorb higher upfront costs for CO2 transcritical architectures while Southeast Asian QSR operators prioritize standard vapor-compression units with shorter lead times from regional fabricators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs equipment procurement, with EU F-Gas Regulation compliance tiers and compressor efficiency ratings as primary differentiation drivers. Pricing pressure stems from copper and aluminum volatility in heat exchanger manufacturing, compressing margins for mid-tier system integrators. Quick-service restaurant chains in India exhibit highest price sensitivity, while German supermarket operators prioritize performance guarantees over capital expenditure minimization.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from European supermarket chains, while distributor networks serve fragmented retrofit markets across Southeast Asia. Manufacturing concentrates in China, Japan, and Germany, with hermetic compressor production anchored in Japanese and European facilities. Supply chains draw from specialized polyurethane foam insulation suppliers and precision aluminum tubing producers. Single-source vulnerability in semi-hermetic compressor components creates bottleneck exposure for system integrators lacking backward integration into compressor manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The refrigeration coolers market functions as a stable compounder, with regulatory-mandated equipment replacement cycles providing predictable demand visibility across decades-long asset lifecycles.
For Market Incumbents: Anchor market position through captive control over compressor manufacturing capacity and accelerated certification investment for CO2 transcritical system deployment. Defend against specialized natural refrigerant integrators by bundling full-facility energy performance contracts that shift buyer procurement from capital expenditure to operational expenditure models. Prioritize R&D allocation toward magnetic refrigeration prototypes for medical cold chain applications.
For New Entrants and Emerging Players: The EU F-Gas Regulation in Europe opens a window for specialized CO2 system integration services targeting mid-sized supermarket chains lacking in-house engineering capabilities. White-space opportunities concentrate in Vietnamese pharmaceutical cold storage and Indonesian vaccine distribution infrastructure. Penetrate through performance-based contracting models that assume thermal compliance risk and bundle remote monitoring subscriptions.
For Investors and Strategic Acquirers: Consolidation pressure builds where regional fabricators lack scale to absorb refrigerant transition engineering costs and compliance documentation burdens. Long-term viability favors platforms with backward integration into compressor technology and building automation software stacks. Acquisition targets include European system integrators with established natural refrigerant installation networks. Monitor refrigerant quota auction prices as inflection indicator for equipment replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Captive supply of hermetic components insulates margin pressure from Japanese and European specialist bottlenecks. |
| Natural Refrigerant Certification Program | EU F-Gas Regulation compliance credentials unlock premium procurement from Danish and Swedish supermarket chains. |
| Performance-Based Equipment Contracting | Shift from hardware sales to uptime guarantees aligns revenue streams with German energy management outsourcing trends. |
| Medical Cold Chain Partnership | Vietnamese pharmaceutical distributor alliances address ultra-low temperature storage gaps in ASEAN vaccine networks. |
| Building Automation Platform Integration | Johnson Controls and Carrier architectures demonstrate full-facility energy contracting captures multi-year service revenue. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cold chain logistics operators, supermarket procurement directors, compressor manufacturing engineers, and refrigeration system integrators with secondary validation against customs trade data, SEC equipment manufacturer filings, EU refrigerant quota registries, and BIS energy efficiency certification records. Bottom-up equipment shipment analysis and top-down end-use demand estimation provided cross-verification.
Comparable-period anchoring linked projection models to historical replacement cycle patterns and regulatory phase-down schedules across the analysis window. Segmentation dimensions modeled include product type, end-user vertical, refrigerant technology, and capacity tier alongside climate-zone operating conditions as industry-specific variable. CAGRs derived from equipment deployment trajectories under alternative refrigerant adoption scenarios, with compressor efficiency benchmarks and raw material cost indices as forecast sensitivity inputs.
Revisions become necessary when refrigerant quota allocation mechanisms tighten beyond modeled trajectories or copper-aluminum price volatility exceeds historical bands. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technician certification program scaling. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Servo Motor Market
Industrial Equipment
Global Temperature Control Units (TCU) Market
Industrial Equipment
Industrial Tags Market
Industrial Equipment
Plasma Feeder Market
Industrial Equipment
Industrial Monitor Market
Industrial Equipment
Ultrasonic Cleaning Equipment Market
Industrial Equipment
Demagnetizer Market
Industrial Equipment
Fluid Dispensing Equipment Market
Industrial Equipment
CO2 Laser Market
Industrial Equipment
Commercial Refrigeration System Market
Industrial Equipment
Europe Vacuum Pump Market
Industrial Equipment
Fiber Laser Coding System Market
Industrial Equipment
Dust Extraction System Market
Industrial Equipment
Glass Engraving Machines Market
Industrial Equipment
Cash Sorting Machines Market
Industrial Equipment
Global Industrial Enclosures Market