
 Global Dicing Blades Market | 2026-2036
Global Dicing Blades Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dicing Blades Market Analysis
The price-performance gap between premium and commodity dicing blades is hardening as foundries demand sub-20-micron kerf widths for silicon carbide wafers while legacy silicon operations prioritize cost per cut. DISCO Corporation dominates ultra-precision blade systems for compound semiconductors. ASAHI Diamond Industrial Co., Ltd. leverages synthetic diamond supply chain control across Asia-Pacific manufacturing hubs. 3M Company competes through proprietary resin matrix formulations that extend blade life in high-volume LED dicing lanes.
Dicing blades are precision abrasive tools, typically 30–80 mm in diameter with diamond or cubic boron nitride grains bonded in metal, resin, or ceramic matrices, manufactured through hot pressing or electroplating to achieve kerf widths below 30 microns for singulating semiconductor wafers. Metal bonded blades lead in silicon carbide applications where extreme hardness outweighs chipping concerns, while resin bonded configurations capture fastest growth in gallium nitride RF devices where edge quality determines yield. Custom size blades concentrate margin pools as IDMs and OSATs specify proprietary hub geometries and bond thicknesses for dedicated dicing platforms.
Japan's METI enforces JIS standards on abrasive tool dimensional tolerances that directly shape export qualification requirements for blade suppliers. The US EPA regulates synthetic diamond manufacturing waste streams under hazardous substance protocols, elevating compliance costs for electroplated blade producers. China's NMPA and GB standards govern imported superhard materials used in domestic semiconductor packaging facilities. Stakeholders must monitor how REACH substance restrictions and evolving dual carbon goals in Beijing reshape raw material sourcing and bond chemistry roadmaps.
Market Dynamics
The EU F-Gas Regulation and REACH substance restrictions are compressing formulation options for blade manufacturers while Taiwan's concentrated backend ecosystem concentrates procurement power among a handful of OSATs and foundries.
Growth Catalysts
- Advanced packaging node expansion:Semiconductor foundries are scaling blade procurement for sub-5nm logic dies and 3D-IC architectures. Backend service ecosystems in Taiwan and South Korea drive specification tightening.
- REACH compliance innovation:European chemical restrictions are accelerating resin-bonded blade development with lower environmental footprints. Manufacturers reformulate bond matrices to maintain EU market access.
- Silicon carbide wafer singulation:Electric vehicle power module fabrication demands metal-bonded blades capable of sub-20-micron kerf widths on ultra-hard substrates. Compound semiconductor foundries specify custom hub geometries.
Market Restraints
- Synthetic diamond supply concentration:Electroplated blade production depends on controlled synthetic diamond supply chains concentrated in select Asia-Pacific manufacturing hubs. Price volatility in superhard materials elevates input cost uncertainty.
- JIS dimensional tolerance enforcement:Japan's METI standards create export qualification friction for non-compliant blade suppliers. Certification timelines extend market entry barriers.
- Resin matrix substitution limits:Metal-bonded configurations retain performance advantages in silicon carbide applications where resin alternatives face chipping yield losses. Bond chemistry roadmaps face technical ceiling constraints.
Strategic Opportunities
- Gallium nitride RF device dicing:5G base station and radar module fabrication creates demand for resin-bonded configurations prioritizing edge quality over hardness. Blade life extension in high-volume LED lanes captures margin pools.
- China dual carbon alignment:Beijing's emissions reduction mandates create procurement preference for low-carbon-footprint blade formulations. Domestic packaging facilities source compliant superhard materials under NMPA and GB standards.
- Custom specification services:IDMs and OSATs specify proprietary hub geometries and bond thicknesses for dedicated dicing platforms. Technical collaboration models replace transactional blade supply.
Industry Challenges
- Bond chemistry R&D talent scarcity:Formulation expertise spanning resin, metal, and ceramic matrices concentrates among veteran engineers in Japan and Germany. Knowledge transfer gaps threaten pipeline depth.
- Multi-regulatory compliance synchronization:Simultaneous EPA hazardous substance protocols, REACH restrictions, and METI tolerance standards create documentation burden. Certification cycle compression demands dedicated regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dicing Blades Market |
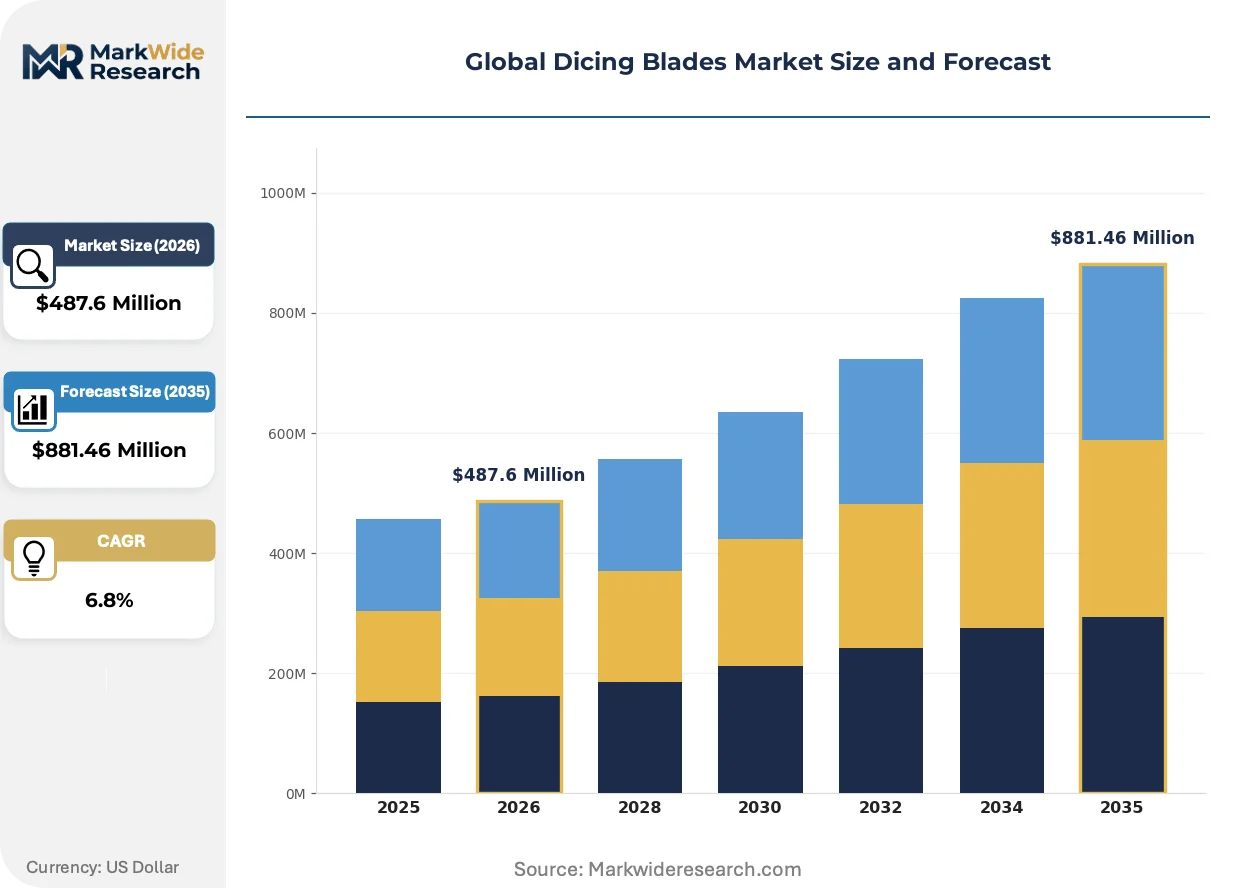
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resin Bonded, Metal Bonded, Electroplated, Ceramic End User: Semiconductors, Electronics, Solar Cells, Automotive Size: Small Diameter, Medium Diameter, Large Diameter, Custom Size Application: Wafer Dicing, PCB Dicing, Diamond Dicing, Material Processing |
| Companies Covered | ASAHI Diamond Industrial Co., Ltd., Accretech, DISCO Corporation, UKAM Industrial Superhard Tools, Kinik Company, Advanced Dicing Technologies Ltd., 3M Company, Shanghai Sinyang Semiconductor Materials Co., Ltd., Kulicke & Soffa Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dicing Blades Market Emerging Trajectories
Blade architecture is fragmenting into application-specific configurations as material science advances enable bond matrix customization for discrete substrate types.
Laser-assisted dicing systems are modularizing traditional mechanical blade workflows by integrating thermal ablation pre-processing with precision abrasive finishing. Memory and logic foundries in Taiwan and South Korea pilot hybrid configurations for brittle compound semiconductor substrates. Equipment OEMs are compressing standalone blade system deployment through platform interoperability.
REACH substance restrictions and the EU F-Gas Regulation are eliminating perfluorinated compounds from resin matrix formulations. Blade manufacturers in Germany and Japan reformulate bond chemistry to maintain CE marking eligibility. Resin-bonded product lines face accelerated R&D cycles to preserve European market access.
Consolidated procurement by Taiwan-based OSATs is compressing supplier negotiation cycles and unbundling after-sales service from blade supply contracts. Volume commitments now dictate pricing tiers and technical support allocation. Foundry-direct relationships are displacing traditional distribution channels for high-specification custom blades.
Global Dicing Blades Market Segmentation
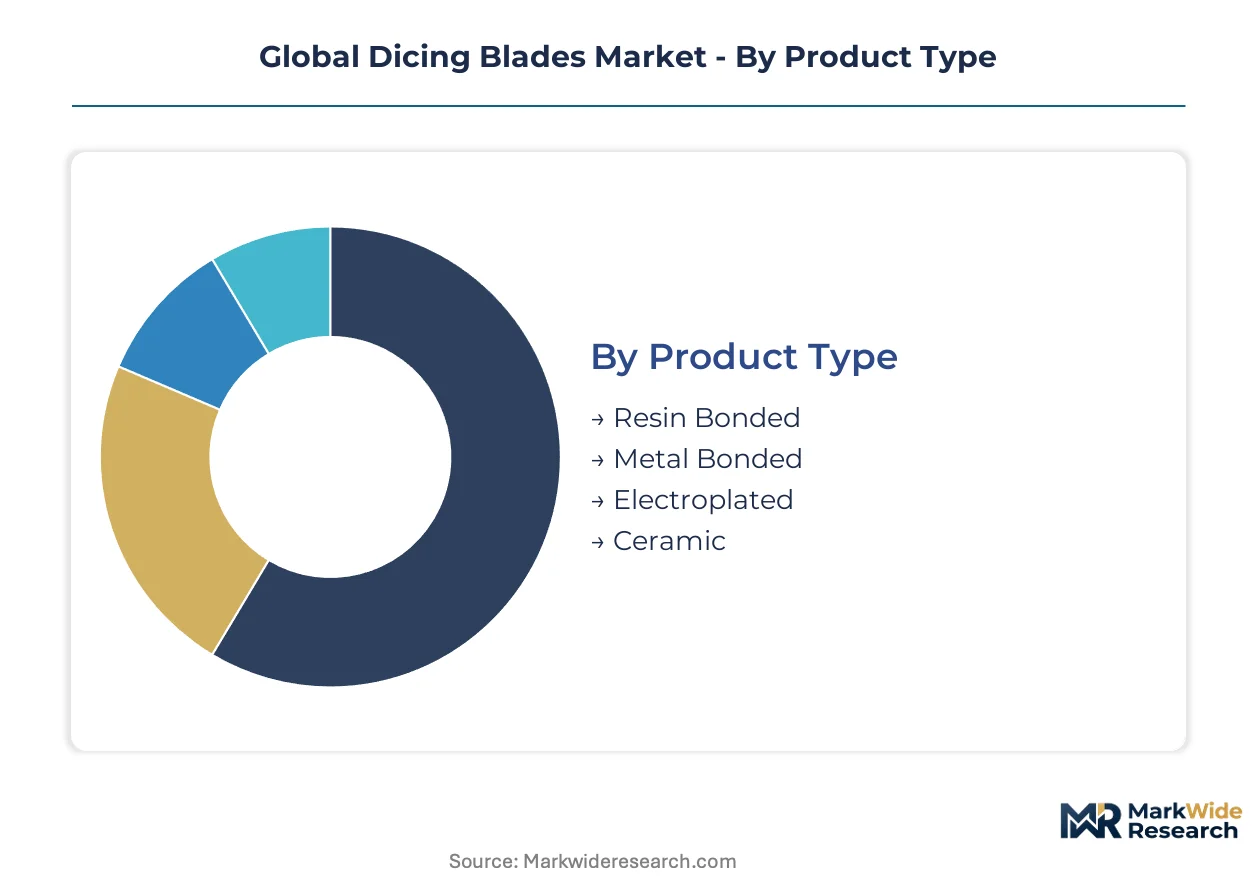
Dicing blade procurement splits across substrate hardness requirements and foundry process nodes. Specification divergence between silicon carbide power modules and gallium nitride RF devices fragments supplier portfolios into application-dedicated configurations.
Product Type:
Buyers select bond matrices based on substrate hardness and edge quality trade-offs for their specific singulation workflows.
- Metal Bonded:Diamond grains sintered within nickel or bronze matrices deliver extreme hardness for silicon carbide wafer dicing. TSMC's backend subcontractors in Taiwan specify metal-bonded configurations for electric vehicle power module fabrication where chipping tolerance exceeds edge finish priority.
- Resin Bonded:Polymer matrices with dispersed abrasive grains prioritize cut quality over durability for brittle compound semiconductors. Gallium nitride RF device foundries in South Korea drive specification tightening here as 5G base station module yields depend on micro-crack elimination.
- Electroplated:Single-layer diamond deposition on steel cores offers cost-efficient solutions for legacy silicon dicing lanes.
- Ceramic:Glass or vitrified bond systems serve specialized optical material processing with thermal stability requirements.
Volume sits with Metal Bonded; growth tilts toward Resin Bonded.
End User:
Customer concentration follows semiconductor capital expenditure cycles and packaging technology roadmaps.
- Semiconductors:Logic and memory foundries consume precision blades for sub-5nm die singulation and 3D-IC architectures. Taiwan's concentrated OSAT ecosystem concentrates procurement power among a handful of buyers specifying proprietary hub geometries.
- Electronics:LED packaging houses and discrete component manufacturers prioritize blade life extension in high-volume lanes. Cost per cut metrics dominate sourcing decisions here against premium precision specifications.
- Solar Cells:Crystalline silicon wafer dicing employs commodity-grade blades with lower kerf width tolerances.
- Automotive:Power module fabrication for electric traction inverters creates demand for silicon carbide-compatible configurations.
Procurement scale clusters with Semiconductors; margin expansion favors Automotive.
Size:
Equipment platform compatibility and substrate diameter dictate blade dimension selection.
- Custom Size:Proprietary hub geometries and bond thicknesses engineered for dedicated dicing platforms capture premium pricing tiers. IDMs and OSATs collaborate directly with blade manufacturers on application-specific designs, displacing transactional supply relationships.
- Small Diameter:30–50 mm blades serve compact dicing systems for LED and small-die logic applications.
- Medium Diameter:50–65 mm configurations balance throughput and precision for standard semiconductor wafer formats.
- Large Diameter:65–80 mm blades address large-area substrate singulation in power module and display panel manufacturing.
Standard diameters dominate unit shipments; Custom Size commands pricing power.
Application:
Process integration requirements fragment blade architecture between standalone mechanical systems and hybrid laser-ablation workflows.
- Wafer Dicing:Silicon, silicon carbide, and gallium nitride substrate singulation demands sub-20-micron kerf widths with minimal subsurface damage. Metal-bonded and resin-bonded configurations split this segment by substrate hardness.
- PCB Dicing:Printed circuit board depanelization employs thicker kerf blades with reduced precision requirements compared to semiconductor applications.
- Diamond Dicing:Superhard material processing for gemstone and industrial diamond fabrication utilizes specialized bond formulations.
- Material Processing:General abrasive cutting applications in ceramics and composites represent non-semiconductor demand.
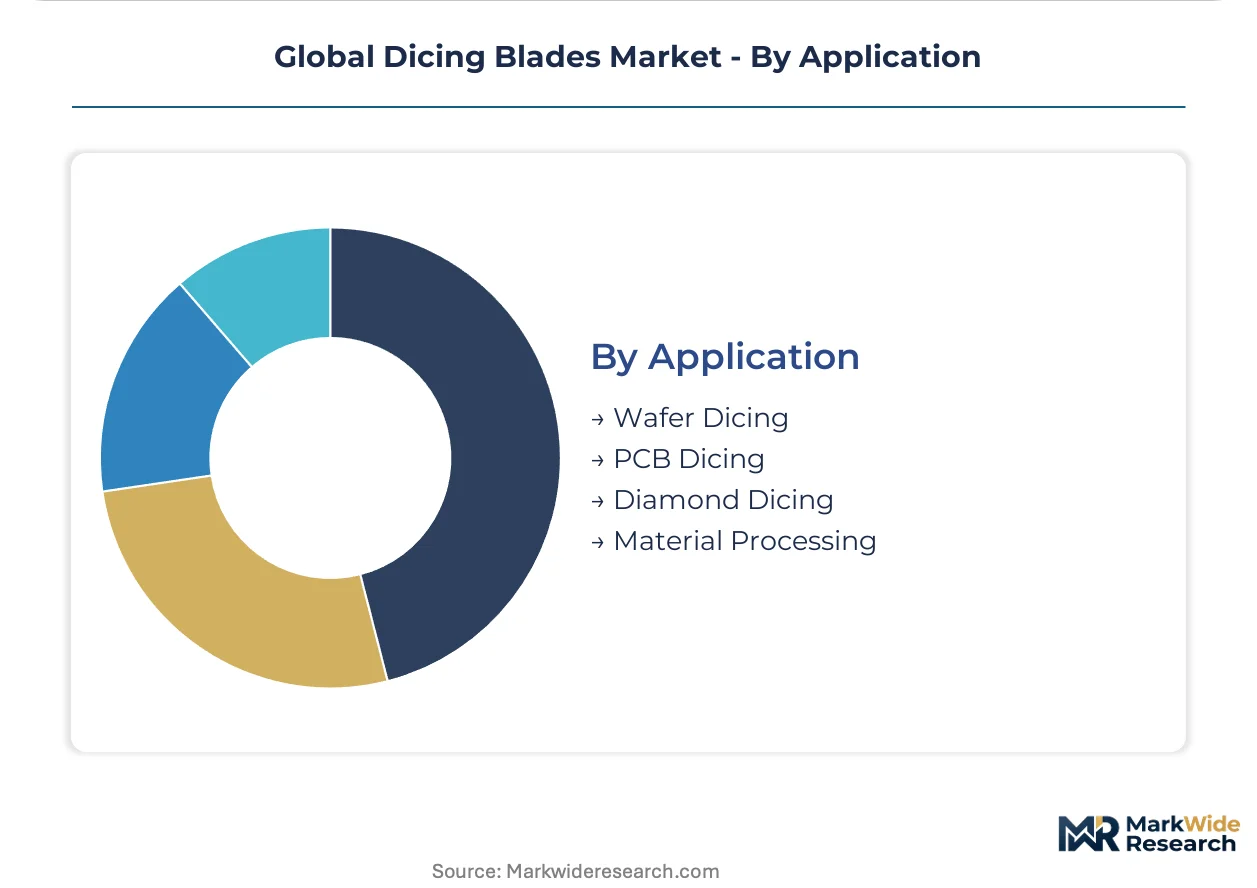
Revenue concentrates in Wafer Dicing; diversification opportunities emerge in Material Processing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu City anchors blade procurement concentration as TSMC's foundry complex drives specification tightening for sub-5nm singulation workflows. Backend service ecosystems in Taiwan's northwest corridor concentrate procurement power among a handful of OSATs.
United States
Silicon carbide power module fabrication for electric vehicle traction inverters drives blade demand in Michigan and Ohio manufacturing corridors. The EPA regulates synthetic diamond manufacturing waste streams under hazardous substance protocols, elevating compliance costs for electroplated blade producers. Austin's semiconductor cluster attracts backend service investments from Taiwanese OSATs seeking proximity to Tesla and Rivian supply chains.
Japan
Compound semiconductor foundries in Kyushu and Nagoya specify metal-bonded configurations for silicon carbide wafer singulation. METI enforces JIS standards on abrasive tool dimensional tolerances that directly shape export qualification requirements for blade suppliers. Tokyo-based blade manufacturers leverage synthetic diamond supply chain control across domestic manufacturing hubs.
Germany
Automotive power electronics fabrication for EV traction systems creates demand for sub-20-micron kerf width capabilities in Bavaria and Baden-Württemberg. REACH substance restrictions and the EU F-Gas Regulation eliminate perfluorinated compounds from resin matrix formulations, forcing bond chemistry reformulation. Dresden's semiconductor cluster pilots laser-assisted dicing systems for brittle compound semiconductor substrates.
South Korea
Gallium nitride RF device foundries in Gyeonggi Province drive specification tightening for resin-bonded configurations prioritizing edge quality. The national semiconductor regulator aligns with international standards for superhard material import certification. Seoul's concentrated backend ecosystem compresses supplier negotiation cycles for high-volume LED dicing lanes.
China
Domestic packaging facilities in Jiangsu and Guangdong provinces source compliant superhard materials under NMPA and GB standards for compound semiconductor singulation. Beijing's dual carbon goals create procurement preference for low-carbon-footprint blade formulations. Shanghai's semiconductor materials corridor attracts resin-bonded blade manufacturing investments serving local LED packaging houses.
Global Dicing Blades Market Vendor Landscape
Capital-heavy producers compete with asset-light designers as blade architecture fragments into application-specific configurations. The market structures around three tiers: integrated superhard material suppliers controlling synthetic diamond feedstock, precision tool specialists engineering proprietary bond matrices, and equipment-integrated blade providers bundling consumables with dicing platforms. Consolidation concentrates among Japanese and German manufacturers with decades of formulation expertise, while Chinese and Taiwanese challengers expand through cost-optimized electroplated offerings. Dominant competitive moves include backward integration into synthetic diamond production and technical collaboration models replacing transactional supply relationships with IDMs and OSATs.
Within the integrated materials tier, ASAHI Diamond Industrial Co., Ltd. exemplifies supply chain control spanning synthetic diamond production through precision tool fabrication. DISCO Corporation occupies a position representing ultra-precision blade systems for compound semiconductor applications. 3M Company anchors the resin matrix innovation vector through proprietary formulations that extend blade life in high-volume processing environments. These three entities collectively illustrate the competitive spectrum from feedstock dominance to application-specific chemistry engineering.
| Leading Market Players |
|---|
| ASAHI Diamond Industrial Co., Ltd. |
| Accretech |
| DISCO Corporation |
| UKAM Industrial Superhard Tools |
| Kinik Company |
| Advanced Dicing Technologies Ltd. |
| 3M Company |
| Shanghai Sinyang Semiconductor Materials Co., Ltd. |
| Kulicke & Soffa Industries |
| Others |
Supply Flow & Price Mechanics
Formulation chemists with resin-matrix expertise cluster in Osaka and Aachen, where labor-cost differentials between Japanese and German technical centers widen pricing-tier spreads for custom-bonded blades against mass-market electroplated alternatives from lower-cost manufacturing hubs.
Pricing Analysis
Yield-per-cut guarantees anchor value-based pricing for resin-bonded configurations in gallium nitride RF dicing lanes. Three-tier pricing structure across premium, standard, and economy levels segments by kerf-width tolerance and hub-geometry customization. Cost compression in commodity electroplated blades intensifies because Chinese producers expand capacity for legacy silicon applications. LED packaging houses exhibit highest price sensitivity, while automotive power-module foundries absorb premiums for sub-20-micron kerf-width certification.
Supply Chain Analysis
Freight costs for synthetic diamond feedstock from Zhongshan to electroplating facilities in Taichung add 8-12% to landed input costs for Taiwan-based blade manufacturers. Supply concentrates in Japan for metal-bonded sintering equipment, China for synthetic diamond production, and Germany for resin-matrix polymer feedstocks. Electroplated blade production draws from nickel sulfate, synthetic diamond grit, and precision-ground steel cores. Single-source vulnerability concentrates in synthetic diamond supply from select Asia-Pacific manufacturing hubs. Distribution runs through foundry-direct contracts with TSMC backend subcontractors and consolidated OSAT procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around formulation expertise as REACH compliance costs and JIS certification timelines force sub-scale resin-bonded producers toward exit or acquisition.
For Market Incumbents: Deepen backward integration into synthetic diamond production to secure feedstock cost advantages against Chinese electroplated blade challengers. Expand resin-matrix R&D capacity in Germany to capture REACH-compliant formulation leadership before EU F-Gas restrictions tighten. Bond chemistry talent scarcity in Japan threatens pipeline depth; acquire specialist formulation teams in Aachen or Osaka to defend technical moats. For New Entrants and Emerging Players: Enter via laser-assisted dicing system partnerships with equipment OEMs in Dresden and Hsinchu, where hybrid mechanical-thermal workflows displace standalone blade procurement. White-space concentrates in ceramic-bonded configurations for optical material processing and custom hub geometries for IDM-specific dicing platforms. Target automotive power-module foundries in Bavaria with silicon carbide-compatible metal-bonded specifications. For Investors and Strategic Acquirers: The window for entry favors mid-cap resin-bonded specialists with captive synthetic diamond supply and existing CE marking pathways. Long-term viability hinges on formulation IP depth and regulatory compliance infrastructure rather than scale economies alone. Watch for TSMC backend subcontractor consolidation announcements as inflection indicators for blade procurement centralization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Diamond Production | Captive supply of superhard materials insulates margin structures from Asia-Pacific feedstock volatility. |
| REACH-Compliant Resin Matrix Reformulation | CE marking eligibility under EU F-Gas Regulation preserves access to German automotive power-module foundries. |
| Custom Hub Geometry Collaboration Models | Technical partnerships with TSMC subcontractors displace transactional supply and capture premium pricing tiers. |
| Laser-Assisted Dicing Platform Integration | Hybrid system partnerships with Dresden equipment OEMs open compound semiconductor substrate opportunities. |
| JIS Certification Investment for Export Qualification | METI dimensional tolerance compliance unlocks Kyushu and Nagoya compound semiconductor foundry procurement. |
Methodological Framework
Independent corroboration across blade procurement managers at Taiwan OSATs, formulation chemists at German resin-matrix suppliers, and METI certification officials underwrites the qualitative findings. Primary interviews with dicing equipment OEMs, synthetic diamond producers in Zhongshan, and automotive power-module foundry engineers in Bavaria combined with secondary validation from SEC filings, Japanese customs trade data, and ECHA REACH substance restriction updates. Bottom-up blade shipment estimates triangulate against top-down semiconductor capital expenditure forecasts.
Comparable-period anchoring to historical wafer dicing volumes and foundry capacity expansion timelines structured the projection horizon across bond matrix types, substrate hardness requirements, and regional regulatory clusters. Segmentation dimensions modeled include metal-resin-electroplated-ceramic bond configurations, silicon carbide-gallium nitride-silicon substrate types, and custom-standard diameter tiers. CAGRs derive from equipment installation forecasts and blade replacement cycle assumptions. Industry-specific inputs incorporate TSMC backend subcontractor procurement patterns and EU F-Gas Regulation phase-out schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under synthetic diamond supply disruption or accelerated laser-assisted dicing adoption. Forecasts reflect assumptions about REACH substance restriction enforcement timelines and JIS certification backlog durations. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
North America Rental Chillers Market
Industrial Equipment
Actuators Market
Industrial Equipment
Cable Granulator Market
Industrial Equipment
Global Twister Winder Market
Industrial Equipment
Diaphragm Coupling Market
Industrial Equipment
Europe Fans and Blowers Market
Industrial Equipment
Global Abrasive Waterjet Cutting Machine Market
Industrial Equipment
Long-Range Acoustic Device Market
Industrial Equipment
Sorter Machines Market
Industrial Equipment
China Ceramic Roller Bearings Market
Industrial Equipment
Pin Marking Machine Market
Industrial Equipment
Industrial I/O Modules Market
Industrial Equipment
Air Filters Market
Industrial Equipment
Servo Drive Market
Industrial Equipment
Microbubble Cleaning Device Market
Industrial Equipment
Vibration Isolation Tables Market