
 Next Generation Memory Market | 2026-2036
Next Generation Memory Market Size, Share, and Industry Trends Forecast 2026-2036
Next Generation Memory Market Intelligence
Software-defined memory management, enabling dynamic resource allocation, is realigning the value proposition beyond raw hardware capacity. Samsung Electronics Co., Ltd. leverages its vast manufacturing scale to drive down costs for emerging memory types. Intel Corporation differentiates through its development of proprietary technologies like 3D XPoint. SK Hynix Inc. competes by focusing on high-bandwidth memory solutions for AI accelerators.
Next generation memory encompasses a class of non-volatile storage technologies designed to bridge the performance gap between DRAM and NAND flash. These technologies, such as Phase Change Memory (PCM), utilize changes in material properties rather than trapping electrical charge to store data. Within applications, data centers and artificial intelligence systems are the primary consumers, demanding low latency and high endurance. Magnetoresistive RAM (MRAM) is gaining traction for embedded systems due to its persistence and speed, while other memory types target different performance tiers.
Compliance with the EU's RoHS directive on hazardous substances and China's GB standards for electronic components sets a baseline for material composition. Concurrently, ISO 9001 certification remains a critical quality assurance standard for semiconductor manufacturers supplying the automotive and industrial sectors. Stakeholders must now decide whether to invest in scaling up production of a single promising technology or maintain a diversified R&D portfolio across multiple memory types.
Market Dynamics
The intense concentration of advanced semiconductor fabrication and R&D investment within South Korea establishes the central dynamic for the next generation memory market. This geographic focus creates economies of scale but also introduces significant supply chain vulnerabilities for global consumers.
Growth Catalysts
- Artificial Intelligence Workloads:The proliferation of AI and machine learning applications in data centers demands memory solutions with lower latency and higher bandwidth than conventional NAND, directly spurring adoption of technologies like MRAM and PCM.
- Automotive System Requirements:Advanced driver-assistance systems and in-vehicle infotainment in the automotive sector require non-volatile memory with high endurance and fast boot times, creating a dedicated and high-value demand stream.
- EU Environmental Directives:The EU's RoHS directive restricts hazardous materials, pushing manufacturers to innovate with new, compliant materials for memory components and promoting more sustainable designs that can be marketed globally.
Market Restraints
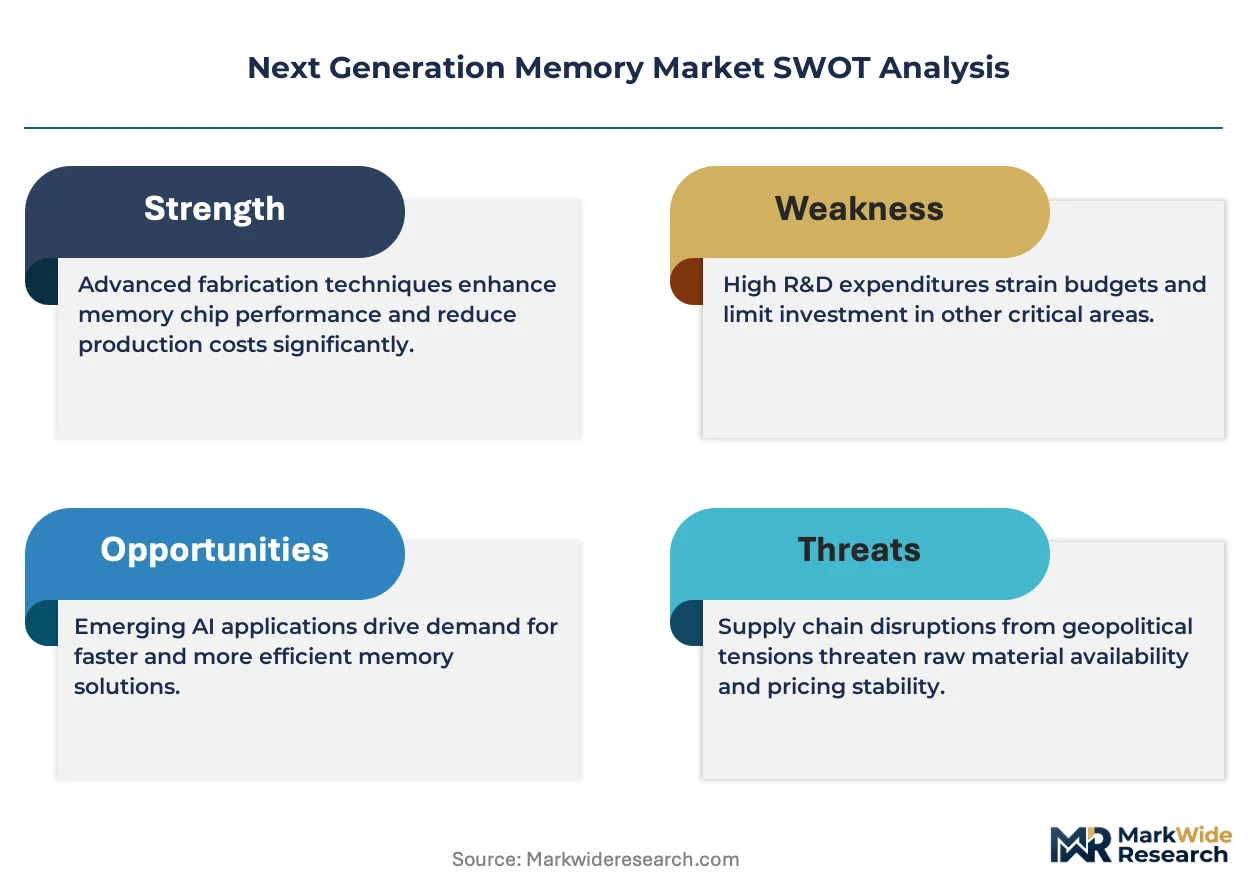
- High Fabrication Costs:Manufacturing emerging memory types like PCM requires novel materials and complex deposition processes, leading to significantly higher initial capital expenditure and per-unit costs compared to mature DRAM and NAND technologies.
- Material Scalability Limits:Certain next generation memory technologies face fundamental physical challenges in scaling to smaller process nodes, limiting their density and cost-competitiveness against established memory solutions for mass-market applications.
- Supply Chain Concentration:The reliance on a small number of foundries, primarily located in South Korea and Taiwan, for the production of advanced memory creates a bottleneck and exposes the market to geopolitical and logistical risks.
Strategic Opportunities
- Edge Computing Integration:The expansion of IoT and edge computing devices provides a significant opportunity for low-power, persistent memory like MRAM to be embedded directly into sensors and local processing units in industrial and consumer electronics.
- Hybrid Memory Architectures:Developing and promoting hybrid memory modules that combine next generation memory with DRAM and NAND flash allows for the creation of tiered storage systems, optimizing performance and cost for specific enterprise workloads.
- Data Center Expansion in India:The rapid build-out of data center infrastructure in India presents a large, underpenetrated market for high-performance, low-latency memory solutions to support its growing digital economy and cloud services sector.
Industry Challenges
- System Integration Complexity:Integrating novel memory technologies into existing computing architectures presents a substantial challenge, requiring new controllers, firmware, and software ecosystem support to achieve full performance potential without compatibility issues.
- Standardization Delays:The absence of universally accepted JEDEC standards for interfaces, form factors, and command protocols for technologies like MRAM and ReRAM slows down broad adoption by system designers and creates market fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Generation Memory Market |
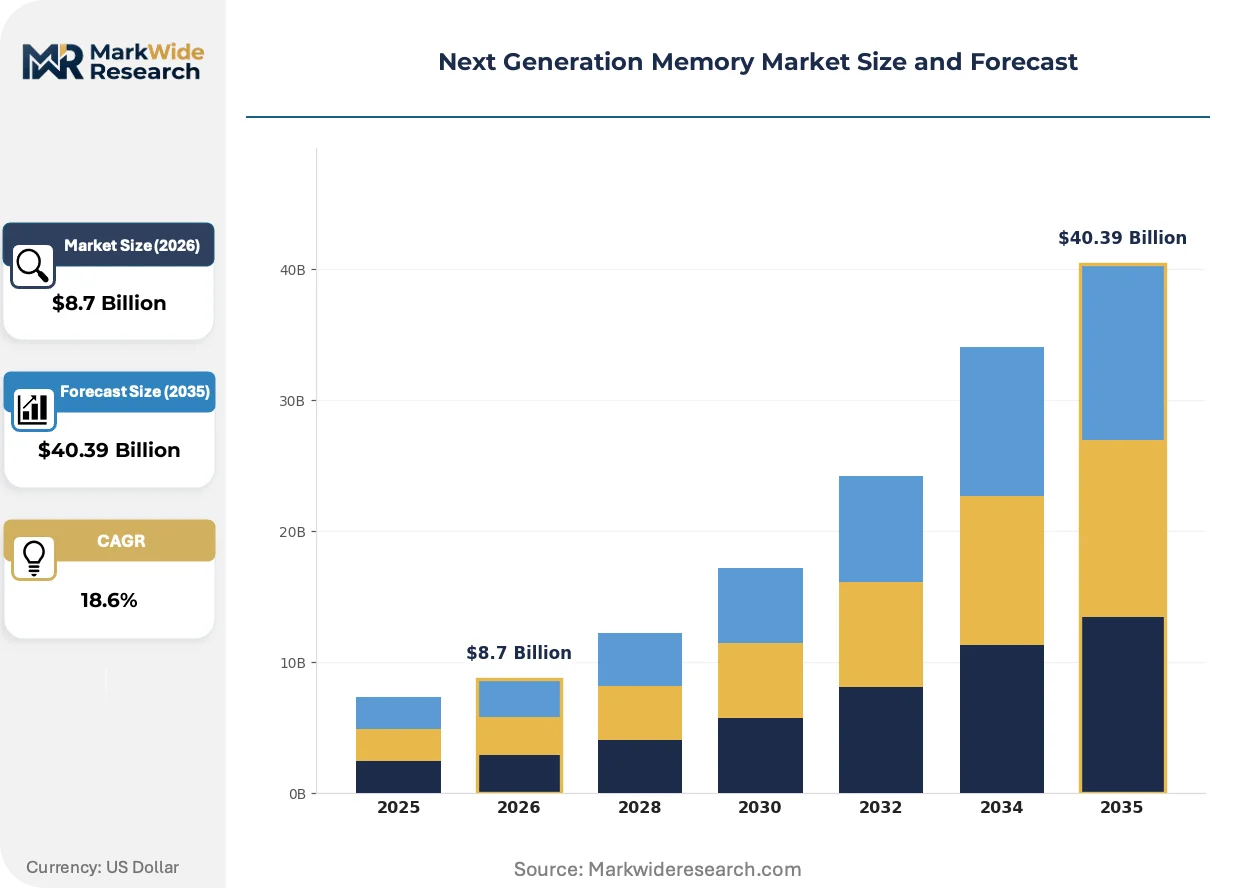
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $40.39 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Memory Type: Resistive RAM, Phase Change Memory, Magnetoresistive RAM, Ferroelectric RAM, 3D XPoint Technology: Spintronics, Nanotube, Molecular Memory, Photonic, Quantum Dot Application: Consumer Electronics, Data Centers, Cloud Computing, Artificial Intelligence Systems, Robotics End User: Semiconductor Manufacturers, OEMs, Data Storage Providers, Research Institutions, Embedded Systems |
| Companies Covered | Samsung Electronics Co., Ltd., Micron Technology, Inc., SK Hynix Inc., Intel Corporation, Kioxia Holdings Corporation, Western Digital Corporation, Infineon Technologies AG, Everspin Technologies, Inc., Crossbar, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Generation Memory Market Strategic Shifts & Innovations
The market is defined by a strategic shift away from a one-size-fits-all memory hierarchy. Instead, a more heterogeneous and application-specific approach is emerging, where different memory technologies are deployed based on their unique performance, endurance, and cost characteristics.
Software-defined memory management pools diverse physical memory resources into a single, unified virtual space. Hyperscale data centers and cloud service providers are the primary adopters, seeking to maximize resource utilization and flexibility. This technology is decentralizing memory management, abstracting it from the underlying hardware and enabling dynamic allocation based on real-time application demands.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is compelling greater transparency in the electronics supply chain. This regulation mandates detailed disclosure on environmental impacts, including energy consumption and material sourcing for components. Semiconductor firms are most affected, now facing pressure to document and improve the lifecycle footprint of memory products, influencing material selection for fabrication.
A notable behavioral change involves enterprise customers moving from raw component purchasing to acquiring pre-validated memory subsystems. This disrupts the traditional distributor-led channel for individual memory chips, favoring system integrators who offer workload-optimized solutions. This pattern is most prominent in the high-performance computing sectors of the United States and Germany, particularly for AI training clusters.
Next Generation Memory Market Segmentation
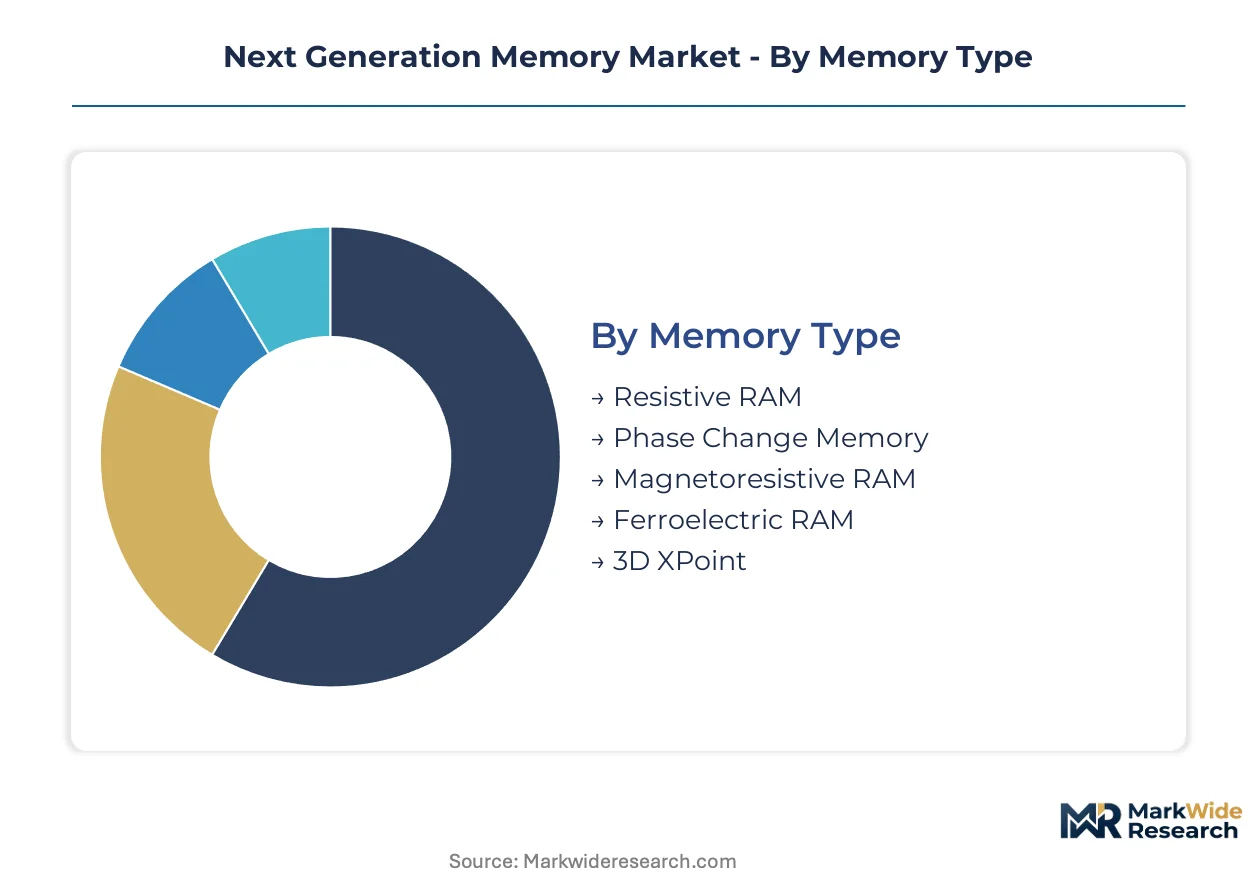
The next generation memory market is highly segmented, reflecting the diverse technical requirements and performance objectives across various computing environments. Understanding these distinct segments is crucial for stakeholders to identify specific growth vectors and tailor product development strategies.
Memory Type:
The next generation memory market bifurcates across a spectrum from highly standardized, mass-produced memory types to specialized, application-specific solutions.
- Magnetoresistive RAM (MRAM):This non-volatile memory technology stores data using magnetic tunnel junctions, offering persistence and high endurance. Demand is concentrating in embedded systems and industrial IoT devices in Germany, driven by stringent reliability and speed requirements.
- Phase Change Memory (PCM):Utilizes changes in the amorphous and crystalline states of chalcogenide alloys to store data, providing high performance and non-volatility. Data centers in the United States are a primary consumer, requiring low latency and high endurance for artificial intelligence workloads.
- Resistive RAM (ReRAM):This memory type employs resistance switching effects in dielectric materials for data storage, promising high density and low power consumption.
- Ferroelectric RAM (FeRAM):A non-volatile memory that uses a ferroelectric capacitor for data storage, known for its fast write speeds and low power usage.
- 3D XPoint:A proprietary non-volatile memory technology developed by Intel, offering a unique blend of high performance, density, and endurance for enterprise applications.
Most installed capacity flows through Magnetoresistive RAM. Expansion is steepest in Phase Change Memory.
Technology:
Technology development in next generation memory spans from approaches targeting cost-effective scaling to those pursuing ultra-high performance at a premium.
- Spintronics:Leverages the intrinsic spin of electrons in addition to their charge for data storage and processing, enabling novel memory and logic devices. Research institutions in Japan are actively exploring spintronics for advanced memory and logic devices.
- Nanotube:Employs carbon nanotubes as active elements in memory devices, promising high density, energy efficiency, and mechanical flexibility. Data storage providers in South Korea are investigating nanotube memory for future high-capacity solutions.
- Molecular Memory:Utilizes individual molecules or molecular assemblies for information storage, offering potential for ultra-high density at the nanoscale.
- Photonic:Stores and processes data using photons instead of electrons, offering high speed, low power consumption, and immunity to electromagnetic interference.
- Quantum Dot:Incorporates semiconductor nanocrystals for memory applications, enabling novel storage mechanisms with potential for high density and multi-level cell capabilities.
Innovation efforts concentrate in Spintronics, with Nanotube showing promising long-term potential.
Application:
Application demands for next generation memory range from ubiquitous consumer devices to specialized, high-performance computing environments.
- Data Centers:Requires memory solutions with low latency and high endurance to manage massive data volumes and diverse workloads, including virtualization and database operations. Hyperscale operators in the United States are driving significant adoption for server and storage acceleration.
- Artificial Intelligence Systems:Demands high-bandwidth memory and fast data processing for training and inference, directly spurring new memory deployments in specialized accelerators. AI accelerators in China are increasingly integrating these advanced memory types for performance gains.
- Consumer Electronics:Integrates non-volatile memory for fast boot times, persistent storage, and energy efficiency in devices like smartphones, wearables, and smart home appliances.
- Cloud Computing:Leverages next generation memory for enhanced virtualization performance, improved data access speeds, and reduced total cost of ownership across distributed infrastructures.
- Robotics:Utilizes persistent and low-latency memory for real-time decision-making, sensor data processing, and autonomous operation in industrial and service robots.
The largest volume consumption originates from Data Centers, while Artificial Intelligence Systems exhibits the fastest expansion.
End User:
End users of next generation memory span the entire value chain, from foundational material producers to final product integrators.
- Semiconductor Manufacturers:Develop and fabricate the core memory chips, investing heavily in R&D and production capabilities for novel memory types. South Korean firms like Samsung and SK Hynix are central to this segment's advancements.
- OEMs (Original Equipment Manufacturers):Integrate memory components into their final products, including servers, automotive systems, and consumer devices, requiring specific form factors and performance profiles. Automotive OEMs in Germany are increasingly specifying next-gen memory for ADAS applications.
- Data Storage Providers:Utilize advanced memory to enhance the performance and reliability of their storage arrays, solid-state drives, and cloud services, seeking improved IOPS and reduced latency.
- Research Institutions:Conduct fundamental and applied research into novel memory materials and architectures, pushing technological boundaries and exploring future applications.
- Embedded Systems:Incorporate compact, persistent, and low-power memory directly into specialized devices for industrial control, medical equipment, and IoT applications.
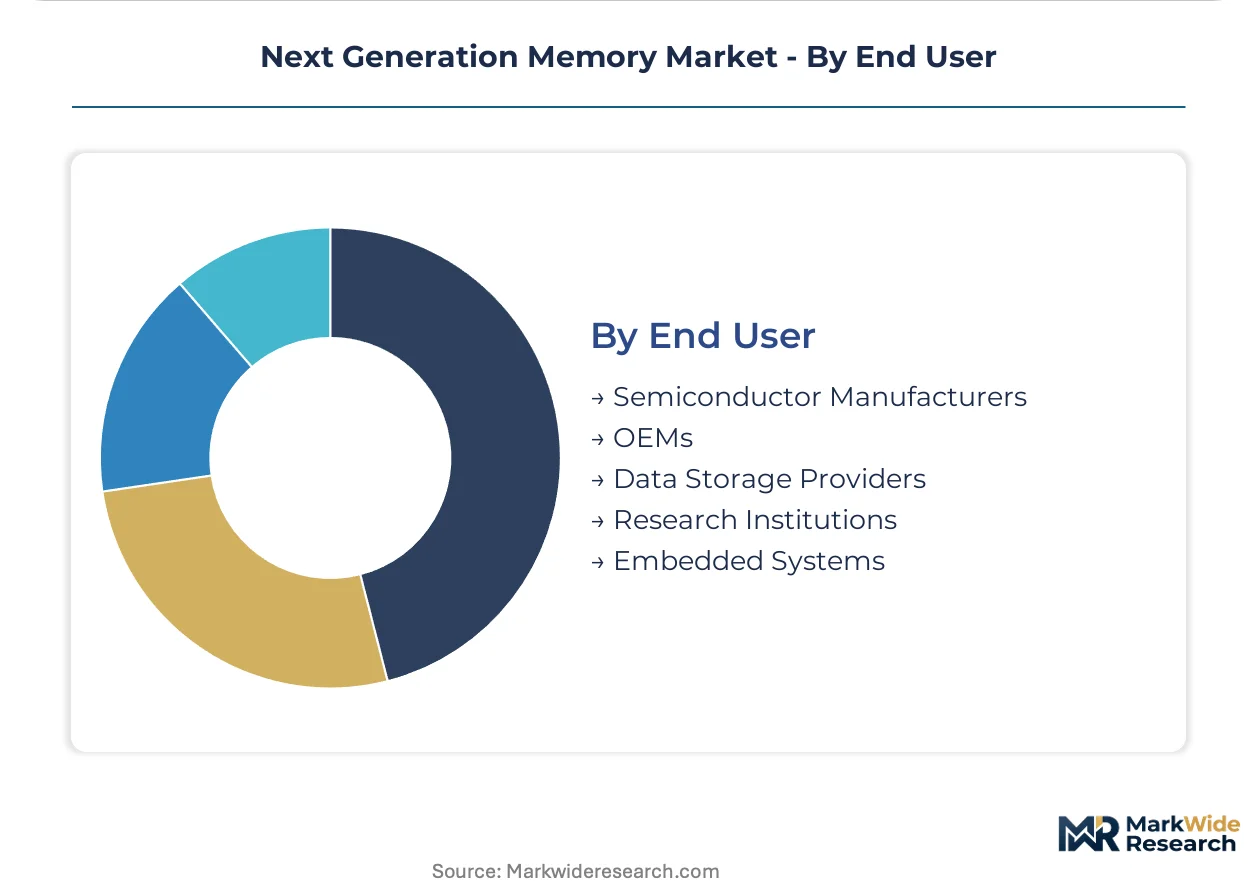
Market influence is strongest among Semiconductor Manufacturers, with OEMs driving significant adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea dominates manufacturing, while the United States drives significant demand for next generation memory solutions. This geographic split reflects distinct roles in the global supply chain, with Asian nations focusing on production and Western markets on high-performance application integration. The market's regional dynamics are shaped by localized technological advancements and regulatory landscapes.
South Korea
Semiconductor manufacturing and advanced R&D initiatives drive demand for next generation memory in South Korea. The government actively supports the semiconductor industry through various industrial policies and investment incentives. Major fabrication hubs in Suwon and Hwaseong anchor significant production capacities for memory components.
United States
Data centers and artificial intelligence systems are primary consumers of low-latency, high-endurance memory in the United States. Federal initiatives, such as those promoting AI research and development, indirectly boost demand for advanced memory. Silicon Valley and Northern Virginia's data center alley represent key clusters for memory integration in hyperscale operations.
Germany
Embedded systems, industrial IoT, and the automotive sector create specific demand for persistent memory like MRAM in Germany. Compliance with the EU's RoHS directive influences material selection for memory components across European markets. The Dresden region, known as Silicon Saxony, maintains a strong focus on semiconductor research and manufacturing.
China
Artificial intelligence accelerators and expanding data center infrastructure are spurring demand for high-bandwidth memory solutions in China. The country's GB standards for electronic components set material and quality baselines for memory products. Technology hubs in Shenzhen and Beijing are actively integrating advanced memory into domestic AI and computing platforms.
Japan
Research into spintronics and advanced material science underpins Japan's contribution to next generation memory development. The Ministry of Economy, Trade and Industry (METI) supports strategic investments in semiconductor and materials innovation. Tokyo and Osaka remain centers for high-tech manufacturing and memory-related research institutions.
Next Generation Memory Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting varied strategies for market penetration. The next generation memory market features a concentrated core of large integrated device manufacturers, alongside a more fragmented ecosystem of specialized technology developers. Strategic partnerships and extensive R&D investment are dominant competitive moves for market participants.
At the scale-driven end, Samsung Electronics Co., Ltd. and SK Hynix Inc. exemplify integrated device manufacturers leveraging vast production capabilities to drive cost efficiencies. Intel Corporation occupies a distinct position, differentiating through proprietary technologies like 3D XPoint for enterprise applications. Everspin Technologies, Inc. represents a specialized archetype, focusing on Magnetoresistive RAM solutions for specific embedded and industrial markets.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| Micron Technology, Inc. |
| SK Hynix Inc. |
| Intel Corporation |
| Kioxia Holdings Corporation |
| Western Digital Corporation |
| Infineon Technologies AG |
| Everspin Technologies, Inc. |
| Crossbar, Inc. |
| Others |
Cost & Logistics Intelligence
Enterprise customers moving to pre-validated memory subsystems are reshaping procurement, shifting demand from raw chips to integrated solutions. This transformation impacts component-level pricing and how value is captured across the supply chain.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for commodity-grade next generation memory components. Pricing largely follows contract-based long-term offtake agreements, with differentiation driven by performance tier and customization level for enterprise solutions. Pressure stems from fierce competition among integrated device manufacturers. Data centers are least price-sensitive for high-performance tiers, while consumer electronics OEMs remain most sensitive to per-unit costs.
Supply Chain Analysis
Specialized material supply rests on a concentrated base of chemical producers in Japan and Germany for novel memory types. Geographic concentration of advanced fabrication centers in South Korea and Taiwan creates a critical dependency. Key inputs include chalcogenide alloys for PCM and magnetic tunnel junctions for MRAM. Single-source vulnerability for advanced deposition equipment creates bottlenecks, while distribution runs through direct sales to hyperscale operators and system integrators, alongside traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The next generation memory market presents a geographic-arbitrage play, leveraging lower manufacturing costs in Asian fabrication hubs against high-value application demand in Western markets.
For Market Incumbents: Hedge against the threat of material scalability limits by investing in diversified R&D portfolios across multiple memory technologies. Consolidate smaller specialized memory IP firms to secure critical intellectual property. Expand capacity in South Korea for established memory types to maintain cost leadership. Focus R&D on heterogeneous integration and advanced packaging to deliver workload-optimized solutions, mitigating the threat from emerging specialized startups.
For New Entrants and Emerging Players: A price-point gap between premium high-performance memory and cost-sensitive embedded solutions presents an entry opportunity. Target niche embedded systems in industrial IoT and specialized AI accelerators for edge computing. The most penetrable segment lies within embedded systems in Germany, driven by stringent reliability needs. Offer pre-validated, application-specific memory modules with integrated controllers to simplify system integration for OEMs.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized IP developers focusing on novel materials and architectures for future memory generations. Technologies bridging the memory-storage gap will be critical for future computing paradigms across the analysis window. Target mid-cap firms with proprietary material science or advanced packaging IP. A clear signal to watch is the establishment of JEDEC standardization for new memory interfaces, indicating broader market readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in South Korea | This move addresses the growing global demand for next generation memory components. |
| Strategic Partnerships with AI Accelerator Firms | These collaborations co-develop memory solutions optimized for high-performance AI workloads in China. |
| R&D Diversification into Spintronics and Quantum Dot | This explores long-term potential for ultra-high density and energy-efficient memory devices in Japan. |
| Enhanced ISO 9001 and RoHS Compliance | This ensures market access and meets stringent quality and environmental standards for automotive OEMs in Germany. |
| IP Acquisition of Specialized Memory Firms | This strengthens the technology portfolio and secures proprietary material science for future product lines. |
Research Approach
Bottom-up data center and AI systems modeling reconciled against top-down semiconductor manufacturing tracking forms the analytical core of this study. This approach integrates primary interviews with CTOs at hyperscale operators, R&D directors at memory foundries, and procurement leads at automotive OEMs. Secondary validation draws from semiconductor industry association reports, academic research papers on novel memory, and corporate financial filings. A robust triangulation process ensures data integrity.
An input-output matrix underpins the quantitative forecast for the next generation memory market. The framework models segmentation dimensions including memory type, technology, application, end-user, and geographic region across the analysis window. Compound annual growth rates are extrapolated from historical trends and projected technological adoption rates. Key forecast inputs include AI processing unit shipments and global data center build-out rates.
Caveats apply where rapid technological advancements or unforeseen geopolitical shifts could materially shift the outlook for next generation memory. Forecasts reflect assumptions regarding JEDEC standardization and stable global supply chains; delays in technology adoption or new trade restrictions represent specific risk factors. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Smartphone RAM Market
Memory Chips
Memristor Market
Memory Chips
Hybrid Memory Cube Market
Memory Chips
Memory IC Market
Memory Chips
Mobile DRAM Market
Memory Chips
Automotive Memory Market
Memory Chips
Memory Chip Market
Memory Chips
Static RAM Market
Memory Chips
eMMC Master Control Chip Market
Memory Chips
Asia Pacific Semiconductor Memory Market
Memory Chips
Ferroelectric RAM Market
Memory Chips
Automotive DRAM Market
Memory Chips
In-Memory Computing Market
Memory Chips
MRAM Market
Memory Chips
Global Emerging Non-Volatile Memory Market
Memory Chips
Next Generation Non Volatile Memory Market