
 Laser Marking Equipment Market | 2026-2036
Laser Marking Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Marking Equipment Market Outlook
Modular system architecture is recalibrating buyer choice across the laser marking equipment landscape. TRUMPF SE Co. KG leverages its integrated galvo-system portfolio to anchor premium positioning in automotive traceability lines. Han's Laser Technology Industry Group Co., Ltd. dominates cost-optimized fiber laser configurations for electronics serialization in Asia. Keyence Corporation differentiates through compact, software-embedded units that reduce floor-space requirements for packaging contractors.
Laser marking equipment employs focused electromagnetic radiation—typically fiber lasers at 1064 nm, CO2 lasers at 10600 nm, or UV lasers at 355 nm—to induce permanent surface alterations on metals, polymers, ceramics, and composites without material removal. The process achieves mark resolutions down to 0.001 inch with speeds exceeding 2000 mm per second, serving primary purposes in product identification, anti-counterfeiting, and supply-chain traceability. Fiber laser systems command the largest installed base due to their efficiency with metals and minimal maintenance requirements, while UV laser configurations represent the fastest-expanding segment as medical device and electronics manufacturers demand cold-marking capability for heat-sensitive substrates. CO2 laser equipment retains structural importance in packaging and organic material applications where wavelength-material coupling optimizes mark contrast.
The FDA's UDI rule and the EU MDR framework mandate permanent, machine-readable marks on medical devices, directly expanding equipment procurement across North American and European manufacturing facilities. China's SAMR enforces GB standards for product traceability that accelerate domestic laser marking deployment in consumer goods. Stakeholders must monitor evolving harmonization between ISO 15415 barcode quality standards and emerging blockchain-anchored serialization protocols that could redefine equipment software requirements.
Market Dynamics
Medical device traceability mandates are compressing procurement cycles and forcing manufacturers to integrate laser marking directly into production lines rather than treating it as a secondary operation.
Growth Catalysts
- FDA UDI Rule:The mandate for permanent, machine-readable device identification creates immediate equipment replacement demand across North American medical manufacturing facilities.
- Fiber laser efficiency:Minimal maintenance requirements and superior metal coupling efficiency position this technology as the default choice for automotive component serialization.
- Stuttgart precision cluster:Germany's concentrated automotive and medical device engineering ecosystem generates sustained demand for high-resolution marking systems.
Market Restraints
- UV laser source concentration:Dependence on limited suppliers for 355 nm diode-pumped solid-state sources creates input cost volatility and lead-time risk.
- CO2 wavelength limitation:Poor metal marking performance confines this technology to organic substrates, restricting addressable market expansion.
- EU MDR compliance timeline:Staggered implementation deadlines create demand lumpiness that complicates equipment manufacturer capacity planning.
Strategic Opportunities
- Blockchain-anchored serialization:Emerging ISO 15415 harmonization with distributed ledger protocols opens software-integrated equipment sales to pharmaceutical packaging.
- India medical device manufacturing:CDSCO traceability enforcement under the Medical Device Rules creates first-mover advantage for localized service support networks.
- UV-cold marking convergence:Heat-sensitive electronics substrates and biodegradable polymers drive adoption of 355 nm systems in consumer goods packaging.
Industry Challenges
- Galvo-optics calibration expertise:Shortage of technicians capable of maintaining sub-micron beam positioning accuracy extends equipment downtime and strains OEM service organizations.
- Legacy ERP integration:Connecting laser marking controllers to existing manufacturing execution systems requires custom middleware development that delays deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Marking Equipment Market |
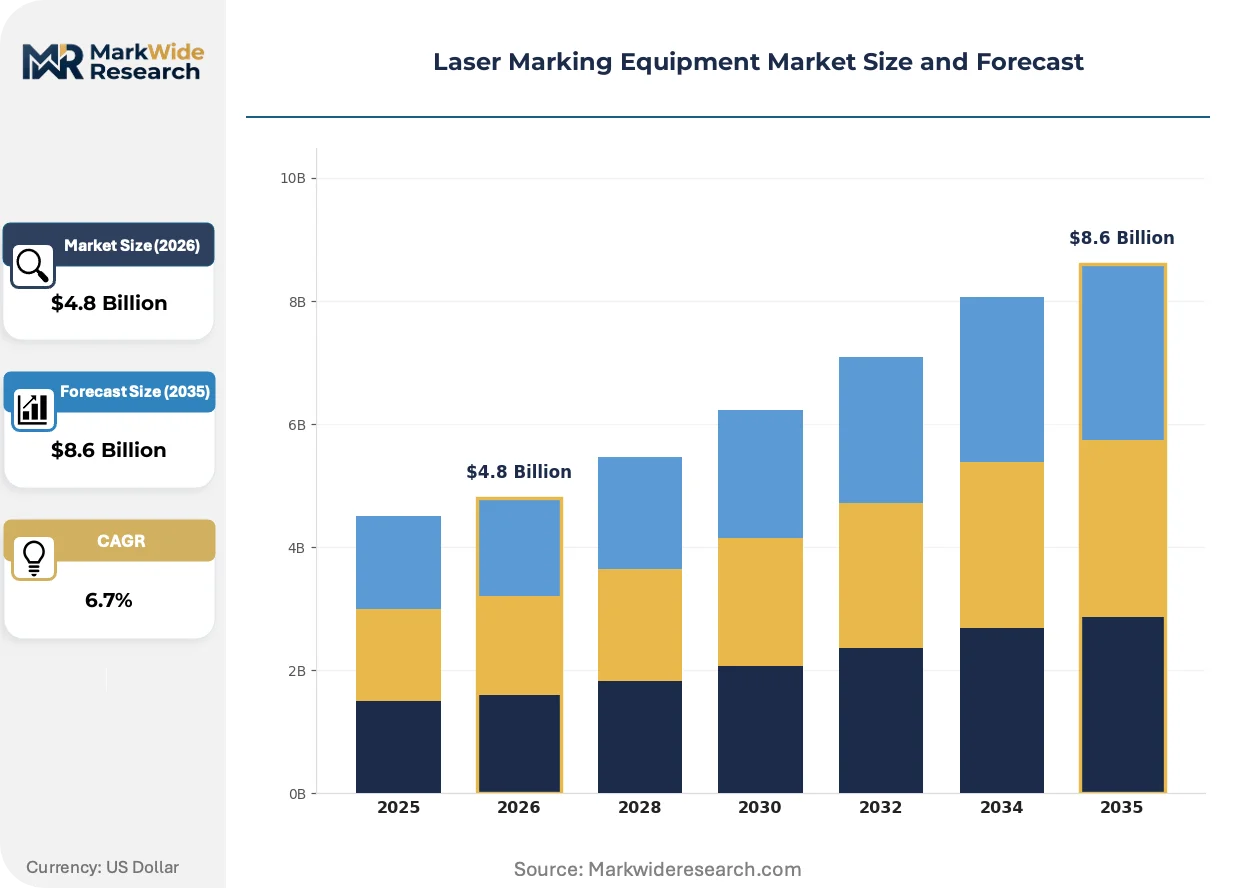
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Laser, CO2 Laser, UV Laser, Green Laser End User: Electronics, Automotive, Packaging, Medical Devices Technology: Dot Peen, Laser Jet, Galvo System, Integrated Systems Application: Identification, Branding, Serialization, Traceability |
| Companies Covered | TRUMPF SE Co. KG, IPG Photonics Corp., Han's Laser Technology Industry Group Co., Ltd., Coherent Inc., Keyence Corporation, Videojet Technologies Inc., Trotec Laser GmbH, Epilog Laser Inc., Jenoptik AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Marking Equipment Market Strategic Shifts
Equipment architecture is pivoting toward software-defined marking parameters that reduce mechanical adjustment dependencies and enable remote diagnostic capabilities.
Ultrafast picosecond laser technology is consolidating market positioning in electronics and medical device manufacturing. These systems deliver cold ablation with minimal heat-affected zones. Semiconductor packaging facilities in South Korea and Taiwan are adopting picosecond configurations for wafer-level marking. The technology is consolidating premium pricing power away from conventional nanosecond fiber systems by enabling processing of previously unmarkable thin-film substrates.
EU MDR Article 27 traceability requirements are mandating direct part marking for implantable devices across all risk classes. Manufacturers must maintain readable marks through sterilization cycles and device lifetime. German and Irish medical device facilities are prioritizing UV laser investments to satisfy these durability specifications. The regulation is compressing equipment procurement timelines as legacy ink-based marking methods lose compliance eligibility.
Contract packaging organizations are unbundling after-sales service agreements from initial equipment purchases. Large pharmaceutical packagers in the United States now negotiate separate multi-year maintenance contracts with performance-based uptime guarantees. This procurement evolution shifts revenue recognition patterns for equipment vendors and concentrates service capabilities among providers with regional spare parts inventories. The model is most advanced in North American and Western European markets where buyer consolidation has strengthened negotiating leverage.
Laser Marking Equipment Market Segmentation
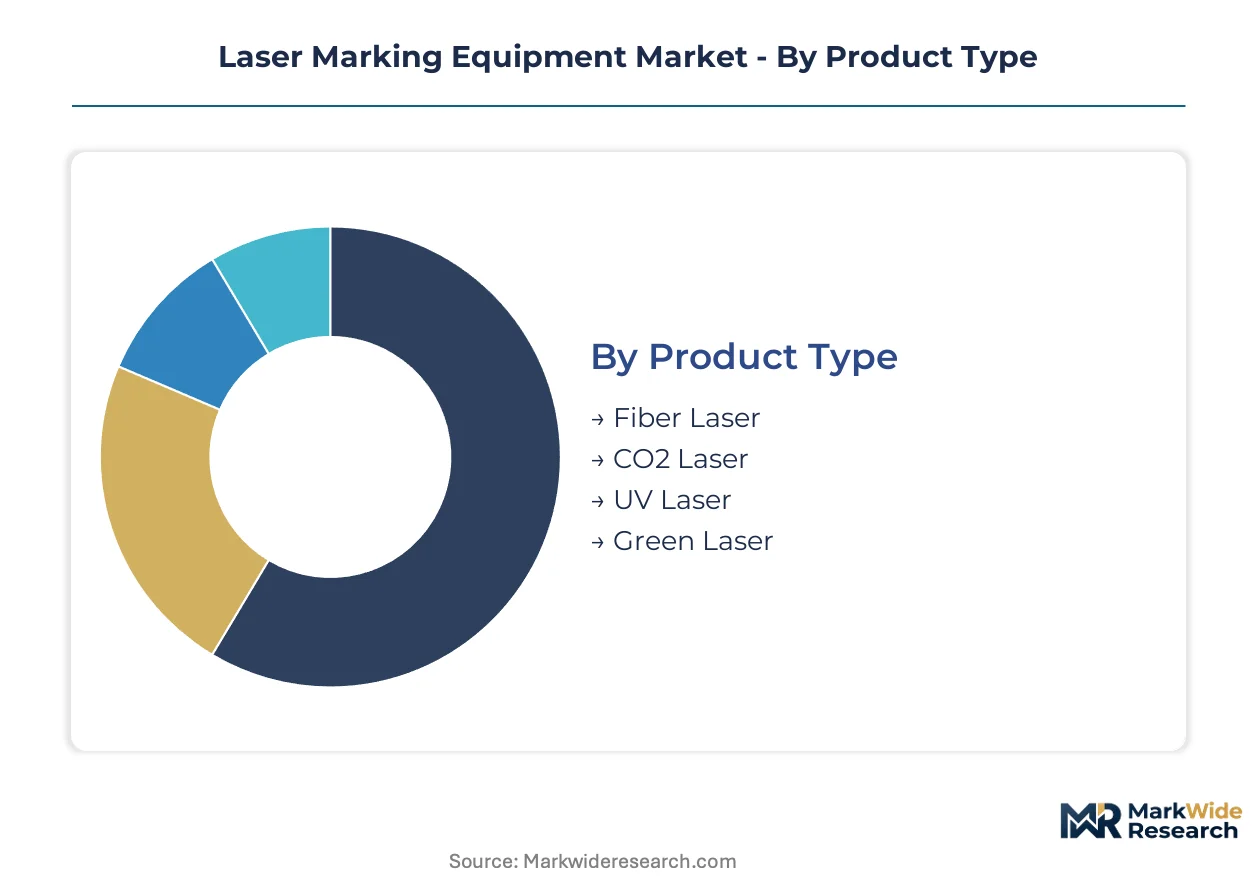
Laser marking equipment segmentation reveals how technology choices align with integration depth across production environments. Equipment buyers select configurations based on substrate compatibility, line speed requirements, and regulatory compliance mandates.
Product Type:
Standalone marking stations serve job shops and low-volume manufacturers, while embedded fiber and UV systems dominate high-throughput automotive and electronics lines.
- Fiber Laser:These 1064 nm solid-state systems deliver 20,000+ hour diode lifetimes with minimal thermal drift. Demand concentrates in German automotive stamping plants and Chinese battery manufacturing facilities where metal coupling efficiency determines throughput economics. The technology anchors the largest installed base due to maintenance simplicity and broad metal compatibility.
- UV Laser:Cold-marking 355 nm configurations induce photochemical rather than thermal substrate alteration. Medical device manufacturers in Ireland and Switzerland prioritize these systems for heat-sensitive polymers and implantable device substrates facing EU MDR durability requirements.
- CO2 Laser:10600 nm gas laser systems excel at organic material marking for packaging applications in US food processing facilities.
- Green Laser:532 nm frequency-doubled Nd:YAG sources serve specialized semiconductor and photovoltaic marking where visible wavelength absorption optimizes precision.
Volume placements concentrate in Fiber Laser; the faster expansion belongs to UV Laser.
End User:
Customer segments diverge sharply on mark durability specifications and integration complexity, with regulated industries commanding premium system configurations.
- Electronics:Semiconductor packaging facilities in Taiwan and South Korea drive demand for picosecond-class systems enabling wafer-level marking without die damage. Miniaturization trends force sub-50 micron feature resolution that conventional nanosecond systems cannot achieve.
- Medical Devices:FDA UDI and EU MDR mandates require permanent, sterilization-resistant marks on implantable devices. German and Massachusetts manufacturers are replacing inkjet systems with UV laser configurations to satisfy readability-through-lifetime requirements.
- Automotive:Component traceability for powertrain and chassis parts relies heavily on fiber laser integration at Germany's Stuttgart precision engineering cluster.
- Packaging:Pharmaceutical contract packagers in New Jersey and Illinois prioritize compact, software-embedded units for serialization compliance with DSCSA track-and-trace requirements.
Electronics captures the highest unit volumes; Medical Devices posts the steepest expansion trajectory as regulatory deadlines compress procurement timelines.
Technology:
Mechanism selection determines mark permanence, speed, and software integration depth across manufacturing execution systems.
- Galvo System:High-speed mirror positioning enables 2000+ mm per second marking with sub-micron beam placement accuracy. Automotive tier-one suppliers in Bavaria and Michigan embed these configurations directly into transfer press lines for real-time component serialization.
- Integrated Systems:Pre-engineered marking modules with embedded controllers reduce deployment timelines for packaging lines requiring rapid serialization compliance. Large pharmaceutical packagers now specify these configurations with separate multi-year uptime-guaranteed service contracts.
- Dot Peen:Mechanical indentation technology retains cost advantage for deep-marking steel components in heavy equipment manufacturing.
- Laser Jet:Continuous inkjet alternatives serve temporary marking applications where permanence is not required.
Galvo System dominates current revenue; Integrated Systems are climbing fastest as procurement shifts toward software-defined, service-unbundled contracts.
Application:
Functional purpose dictates laser wavelength selection and controller software complexity, with traceability applications commanding the most sophisticated integration.
- Traceability:Machine-readable 2D codes and human-readable alphanumeric strings enable supply chain tracking and regulatory compliance. Medical device manufacturers in Minnesota and Baden-Württemberg invest heavily in UV systems to ensure mark survival through multiple sterilization cycles.
- Serialization:Unique identifier assignment at unit level drives pharmaceutical and electronics packaging demand. India's CDSCO enforcement under Medical Device Rules is accelerating localized deployment for export-oriented manufacturers.
- Identification:Basic part numbering and logo marking serves general industrial manufacturing with lower software integration requirements.
- Branding:Aesthetic surface marking for consumer goods prioritizes visual quality over machine readability.
Traceability commands the highest average system values; Serialization gains share fastest as blockchain-anchored protocols emerge in pharmaceutical packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones and precision manufacturing clusters concentrate laser marking equipment procurement across four dominant national markets. Tax-advantaged industrial parks in Germany, China, the United States, and Japan anchor regional demand through automotive, electronics, and medical device manufacturing density.
Germany
Stuttgart's automotive engineering corridor and Munich's medical technology cluster generate sustained demand for high-resolution galvo systems. The EU MDR framework mandates permanent device identification, compressing procurement timelines for implantable manufacturers in Baden-Württemberg and Bavaria. TRUMPF SE Co. KG anchors premium positioning through integrated galvo-portfolio dominance in these precision engineering zones.
China
Shenzhen's electronics manufacturing ecosystem and Suzhou's semiconductor packaging facilities drive fiber laser volume placements. SAMR enforces GB standards for consumer goods traceability that accelerate domestic deployment. Han's Laser Technology Industry Group Co., Ltd. exemplifies cost-optimized configuration dominance across these coastal manufacturing belts.
United States
Minnesota's medical device corridor and Michigan's automotive stamping plants prioritize UV laser investments for UDI compliance. The FDA's unique device identification rule creates immediate equipment replacement demand across North American manufacturing facilities. Pharmaceutical packagers in New Jersey and Illinois negotiate separate multi-year maintenance contracts with performance-based uptime guarantees.
Japan
Tokyo-Osaka electronics manufacturing belt and Nagoya's automotive component suppliers demand picosecond-class systems for wafer-level marking. METI industrial standards emphasize traceability integration that shapes procurement specifications. Semiconductor packaging facilities in Kyushu and Chubu regions adopt ultrafast configurations for thin-film substrate processing without thermal damage.
Switzerland
Geneva and Basel pharmaceutical manufacturing clusters prioritize cold-marking UV systems for heat-sensitive packaging substrates. Swissmedic traceability requirements align with EU MDR durability specifications for implantable devices. Precision watchmaking manufacturers in Jura Arc deploy compact software-embedded units for anti-counterfeiting serialization at component level.
Laser Marking Equipment Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across technology tiers, creating a bifurcated vendor structure. The market consolidates around three strategic archetypes: integrated galvo-system providers commanding premium automotive traceability lines, cost-optimized fiber laser fabricators serving electronics serialization, and compact software-embedded unit specialists reducing floor-space requirements for packaging contractors. Competitive dynamics center on strategic partnerships for regional service networks and technology licensing for wavelength-specific source integration.
Within the integrated-system tier, TRUMPF SE Co. KG and Jenoptik AG represent German-engineered precision positioning, while Keyence Corporation exemplifies Japanese compact-embedded controller specialization. IPG Photonics Corp. occupies a position among fiber laser source providers that supply downstream equipment fabricators. These named entities anchor archetype differentiation rather than exhaustive market coverage, with regional pure-plays and sector specialists filling gaps between these positioning poles.
| Leading Market Players |
|---|
| TRUMPF SE Co. KG |
| IPG Photonics Corp. |
| Han's Laser Technology Industry Group Co., Ltd. |
| Coherent Inc. |
| Keyence Corporation |
| Videojet Technologies Inc. |
| Trotec Laser GmbH |
| Epilog Laser Inc. |
| Jenoptik AG |
| Others |
Value Chain & Pricing Dynamics
EU MDR sterilization durability mandates gate qualified UV laser supply and premium-tier pricing access for medical device manufacturers. German and Irish implantable device producers must source 355 nm systems capable of surviving autoclave cycles, compressing vendor qualification pools and anchoring price premiums.
Pricing Analysis
Margin tightening in mid-tier fiber laser configurations reflects Han's Laser cost-optimized pressure from Chinese battery manufacturing demand. Three-tier pricing structure across premium galvo-integrated, standard embedded, and economy standalone levels separates automotive traceability from packaging serialization buyers. Certification grade—specifically FDA UDI compliance tier and ISO 15415 barcode quality grade—drives price differentiation between medical device and general industrial procurement. Pharmaceutical contract packagers in New Jersey exhibit highest price sensitivity due to unbundled service contract negotiations, while German automotive tier-one suppliers show lowest sensitivity given integration complexity premiums.
Supply Chain Analysis
ISO 13485 medical device quality system certification gates supplier access for UV laser source procurement. 355 nm diode-pumped solid-state sources concentrate in Japan and Germany, with fiber laser pump diodes drawing from Chinese and American semiconductor foundries. Galvo-optics assemblies hinge on Swiss and German precision machining capabilities. Single-source vulnerability for picosecond laser crystals creates lead-time risk for semiconductor packaging facilities. Distribution runs through OEM-direct sales for automotive integration projects and specialized industrial distributors for job-shop standalone units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Limited 355 nm source fabrication capacity props pricing premiums as medical device procurement deadlines compress. UV laser diode foundry expansion lags EU MDR compliance timelines by several years.
For Market Incumbents: Acquire regional service depot networks to defend against emerging Asian entrants offering remote-only support. TRUMPF and Keyence should backward integrate into galvo-optics calibration training programs to offset technician scarcity. Certification investment in India's CDSCO traceability compliance creates channel control leverage as manufacturing migrates. For New Entrants and Emerging Players: The mid-tier price-point gap between Keyence compact units and Trotec job-shop configurations offers white-space entry for software-embedded fiber laser specialists. India's medical device export corridor represents the most penetrable geography given localized service gaps. A rental-leasing go-to-market angle targets pharmaceutical packagers seeking to unbundle capital expenditure from compliance timelines. For Investors and Strategic Acquirers: CDSCO enforcement acceleration is the leading indicator that Indian medical device manufacturing capacity will require laser marking retrofit investment. Five-to-ten year viability favors picosecond laser technology specialists with semiconductor packaging relationships over legacy nanosecond fiber fabricators. Watch for blockchain-anchored serialization protocol adoption in pharmaceutical packaging as the inflection signal for software-integrated equipment demand.| Strategic Initiative | Industry Significance |
|---|---|
| UV Laser Source Backward Integration | Captive 355 nm diode supply secures margin for EU MDR-compliant medical device systems. |
| Regional Service Depot Expansion | India CDSCO compliance deadlines demand localized spare parts inventory for uptime guarantees. |
| Software-Defined Controller Development | Remote diagnostic capability reduces galvo-optics calibration downtime for automotive lines. |
| Picosecond Laser Platform Launch | Wafer-level marking precision captures semiconductor packaging demand from Taiwan facilities. |
| Blockchain Serialization Partnership | ISO 15415 harmonization with distributed ledger protocols opens pharmaceutical packaging sales. |
Study Parameters
Trade association filings, customs shipment records, and regulatory enforcement databases formed the secondary backbone for laser marking equipment demand modeling. Primary interviews with biomedical engineers at German implantable device manufacturers, GPO contracts managers at US hospital systems, and aftermarket service heads at automotive tier-one suppliers validated secondary estimates. Bottom-up and top-down triangulation cross-checked equipment unit placements against end-user capital expenditure disclosures.
Bottom-up modeling aggregated segment-level demand across fiber, UV, CO2, and green laser technologies. Segmentation dimensions included product type, end-user industry, galvo versus integrated system architecture, and traceability versus branding application purpose. CAGRs were derived from regression analysis of historical procurement patterns against regulatory deadline schedules. Forecast inputs incorporated FDA UDI phase-in timelines and EU MDR Article 27 implementation stages across the analysis window.
Inputs from SAMR GB standard enforcement notices and CDSCO Medical Device Rules amendments were available through the study window; gaps in real-time OEM order backlog disclosure introduce uncertainty bands around near-term volume estimates. Forecasts reflect assumptions regarding technician training pipeline expansion and galvo-optics calibration automation development. A model refresh is warranted upon material change in blockchain-anchored serialization protocol adoption rates or picosecond laser cost-down trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Abrasive Waterjet Cutting Machine Market
Industrial Equipment
Cable Granulator Market
Industrial Equipment
Cash Sorting Machines Market
Industrial Equipment
Battery Spot Welder Market
Industrial Equipment
Industrial Polishing Machine Market
Industrial Equipment
Soldering Iron Market
Industrial Equipment
Snowrator Market
Industrial Equipment
Pin Marking Machine Market
Industrial Equipment
Global Refrigeration Compressor Market
Industrial Equipment
Japan Ceramic Roller Bearings Market
Industrial Equipment
Europe Ceramic Roller Bearings Market
Industrial Equipment
Global Strain Wave Gearing Devices Market
Industrial Equipment
Grading and Batching Systems Market
Industrial Equipment
Linear Motion (LM) Shaft Market
Industrial Equipment
Middle East and Africa Industrial Centrifuge Market
Industrial Equipment
Industrial Lasers Systems Market