
 Dry Block Heaters Market | 2026-2036
Dry Block Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Block Heaters Market Analysis
Chinese precision instrument manufacturers is broadening export capacity for temperature-controlled laboratory equipment. Grant Instruments leverages its Cambridge engineering heritage to sustain premium positioning in European research markets. Thermo Fisher Scientific anchors North American supply through its extensive distribution and service infrastructure. Eppendorf differentiates with digital control integration and programmable protocol libraries for automated workflows.
Dry block heaters are electrically heated aluminum or metal alloy blocks with precision-machined wells that accommodate tubes, vials, or microplates for controlled sample incubation, typically operating from ambient to 150°C with uniformity within ±0.1°C to ±0.5°C depending on model grade. Laboratory-grade units dominate installed base volume, while programmable microprocessor-controlled systems capture expanding margin pools as pharmaceutical quality control labs upgrade from analog instruments. Bench-top configurations lead research institution procurement, though portable formats are gaining traction in field-based environmental monitoring and point-of-care diagnostic development.
FDA Good Laboratory Practice standards and ISO 17025 accreditation requirements shape equipment validation documentation and calibration traceability obligations for suppliers serving regulated industries. The EPA and OSHA frameworks influence material safety and electrical compliance specifications for instruments deployed in environmental testing and industrial hygiene laboratories. Stakeholders must monitor evolving EMA guidance on analytical method validation as European pharmaceutical outsourcing continues to expand.
Market Dynamics
ISO 17025 accreditation mandates and FDA Good Laboratory Practice standards are compressing validation timelines, forcing pharmaceutical quality control labs to retire analog thermal instruments in favor of digitally traceable systems with automated documentation capabilities.
Growth Catalysts
- EMA analytical method validation guidance:European contract research organizations in Germany and Switzerland are upgrading thermal equipment to meet tightening documentation requirements for drug stability protocols.
- Aluminum alloy precision machining:Advances in CNC well-bore tolerances are enabling ±0.1°C uniformity standards that support PCR and nucleic acid amplification workflows.
- Point-of-care diagnostic expansion:Field-based environmental monitoring teams in Australia and Canada are procuring portable dry block formats for remote sample processing.
Market Restraints
- Heating element supply concentration:Ceramic cartridge and resistance wire sourcing clusters in China's Jiangsu province create single-geography vulnerability for mid-tier manufacturers.
- Platinum RTD sensor cost volatility:Precious metal price swings directly impact bill-of-materials for high-precision temperature control modules.
- Water bath substitution in low-spec applications:Academic teaching laboratories continue specifying circulating water baths where ±1.0°C tolerance suffices, capping dry block penetration in budget-constrained segments.
Strategic Opportunities
- India's PLI scheme for analytical instruments:Domestic manufacturing incentives are opening local assembly partnerships for temperature-controlled laboratory equipment serving CDMO expansion.
- Cloud-connected protocol libraries:Integration of Wi-Fi-enabled dry blocks with LIMS systems is unifying thermal cycling data with electronic batch records in FDA-regulated facilities.
- Saudi Arabia's biotechnology cluster development:King Abdullah Financial District life science initiatives are generating demand for GMP-compliant thermal equipment in emerging Middle East pharmaceutical hubs.
Industry Challenges
- Metrology technician scarcity:Calibration and validation specialists with ISO 17025 audit experience command premium compensation, extending service lead times for equipment qualification.
- Legacy analog fleet retrofit complexity:Pharmaceutical quality control departments face integration friction when connecting 1990s-era dry blocks to modern data integrity frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Block Heaters Market |
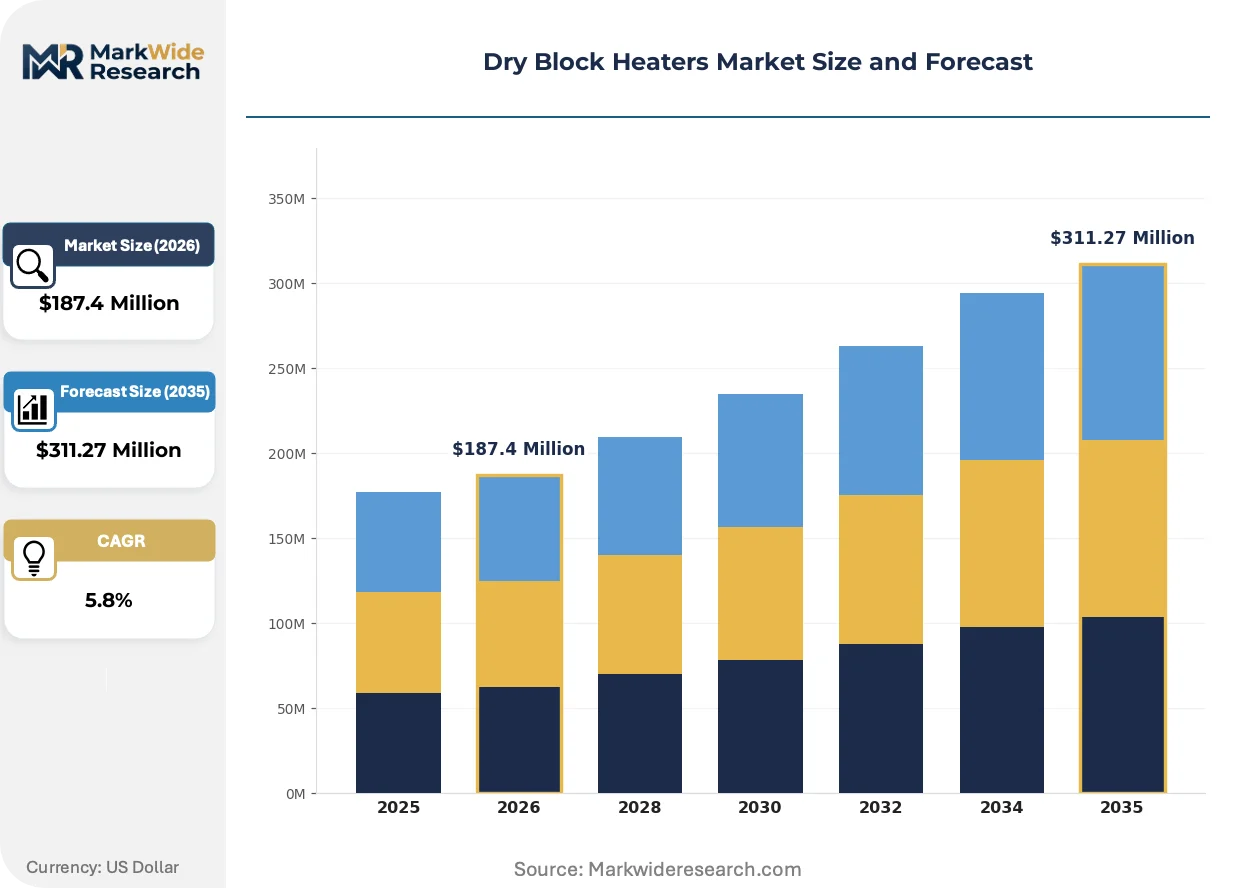
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Laboratory, Industrial, Bench-top End User: Research Institutions, Pharmaceutical Companies, Universities, Quality Control Labs Temperature Range: Low-Temperature, Medium-Temperature, High-Temperature, Ultra-High-Temperature Control Mechanism: Analog, Digital, Programmable, Microprocessor-Controlled |
| Companies Covered | Grant Instruments, IKA, VLM GmbH, Stuart Equipment, Corning Life Sciences, Ratek, Thermo Fisher Scientific, Eppendorf, Labnet International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Block Heaters Market Emerging Trajectories
Digital control architectures are displacing analog thermostat systems across pharmaceutical and environmental testing laboratories, compressing the replacement cycle for installed base equipment while enabling remote monitoring and audit-ready documentation workflows.
Microprocessor-based PID controllers with touchscreen interfaces are unifying temperature programming, data logging, and alarm management into single-instrument platforms. Biopharmaceutical quality control departments in Switzerland and Massachusetts are specifying these systems for stability chamber backup and forced degradation studies. This convergence is compressing demand for standalone data loggers and manual temperature recorders in regulated facilities.
EPA Good Laboratory Practice amendments for environmental toxicity testing are mandating enhanced temperature traceability for aquatic life cycle studies. Contract laboratories serving agrochemical registration submissions in the US and Brazil are retrofitting dry block inventories with calibrated data output modules. The environmental testing segment is absorbing compliance costs through extended service contracts with original equipment manufacturers.
Consolidated procurement through group purchasing organizations is compressing vendor margins while elevating service and calibration bundling requirements. Academic medical centers in Germany and the Netherlands are migrating from transactional equipment purchases to multi-year thermal equipment service agreements. This behavioral shift is most pronounced in university hospital systems where shared research infrastructure budgets centralize laboratory equipment decisions.
Dry Block Heaters Market Segmentation
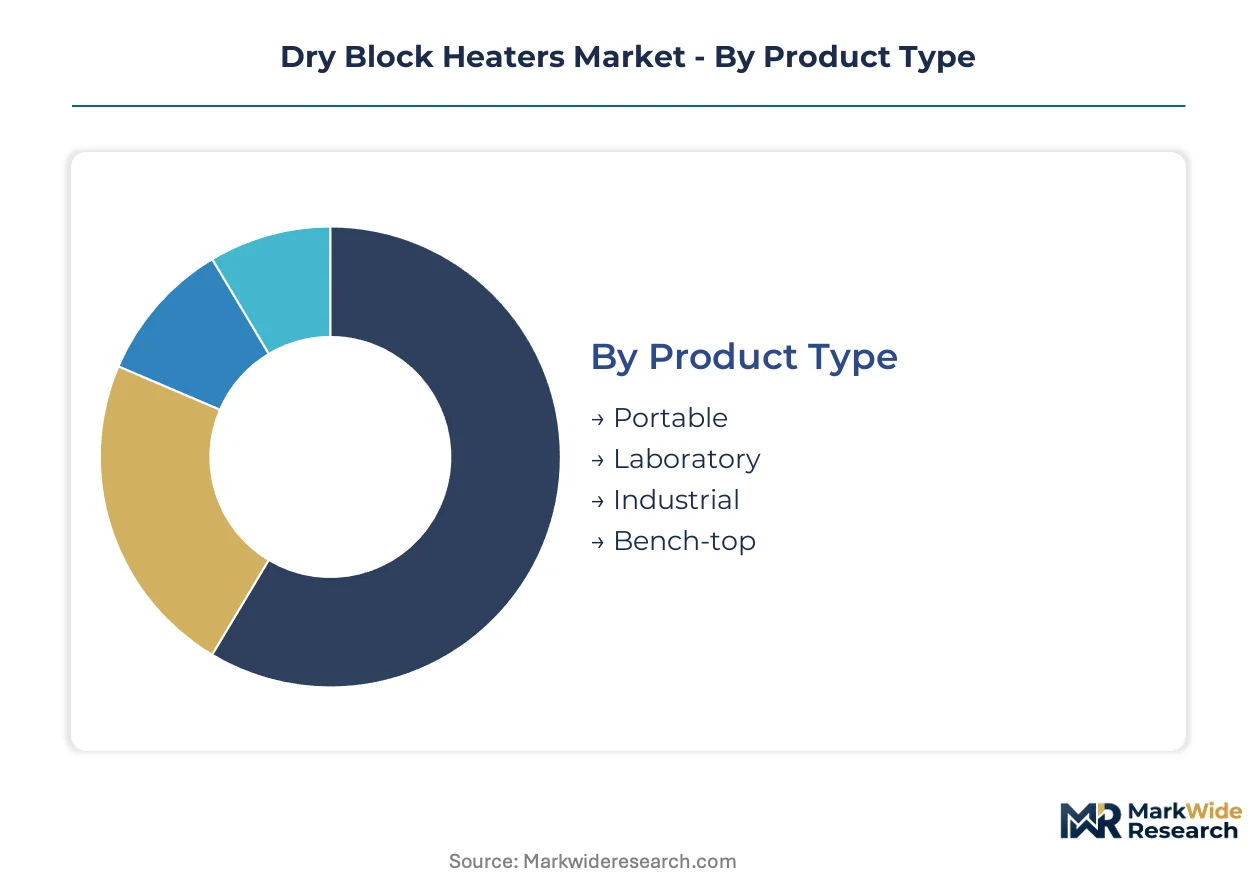
Dry block heater procurement splits across four structural dimensions that determine validation requirements, price positioning, and replacement cycles. Product format and control sophistication drive capital allocation, while end-user category shapes service bundling and calibration frequency.
Product Type:
Laboratory and industrial formats demand substantially higher upfront investment due to precision machining requirements and multi-well configurations.
- Laboratory:These units feature precision-machined aluminum alloy blocks with 24-96 well configurations, achieving ±0.1°C uniformity for PCR and nucleic acid workflows. Pharmaceutical quality control labs in Germany and Switzerland specify these for forced degradation studies under EMA analytical method validation guidance.
- Bench-top:Compact footprint designs with 12-24 well capacity serve shared research infrastructure in university hospital systems. Academic medical centers in the Netherlands are migrating from transactional purchases to multi-year thermal equipment service agreements for these units.
- Portable:Battery-compatible formats with insulated well jackets enable field-based environmental monitoring in remote locations. Environmental testing teams in Australia and Canada procure these for point-of-care diagnostic development workflows.
- Industrial:Heavy-duty steel-block constructions with 150-200 well arrays support high-throughput quality control in contract manufacturing settings. CDMO expansion in India under the PLI scheme for analytical instruments is stimulating demand for these robust configurations.
Laboratory-grade systems absorb the bulk of installed capacity; portable formats are expanding most quickly.
End User:
Regulatory exposure varies sharply across user categories, with pharmaceutical and quality control labs facing the strictest documentation obligations.
- Pharmaceutical Companies:GMP-compliant facilities require ISO 17025-traceable calibration certificates and automated data logging for FDA Good Laboratory Practice submissions. These users command premium pricing for programmable systems with electronic batch record integration.
- Quality Control Labs:Contract research organizations in Germany's dense CRO cluster prioritize ±0.1°C uniformity and rapid thermal ramp rates for drug stability protocol validation. EPA amendments for environmental toxicity testing are mandating enhanced temperature traceability for aquatic life cycle studies at these facilities.
- Research Institutions:Shared core facilities balance precision requirements against budget constraints, often specifying mid-tier digital control systems for general incubation workflows.
- Universities:Teaching laboratories frequently specify analog or basic digital units where ±1.0°C tolerance suffices, with circulating water baths competing for budget-constrained segments.
Pharmaceutical companies anchor revenue concentration; quality control labs are climbing the fastest as European outsourcing expands.
Temperature Range:
Sensor and heating element costs escalate non-linearly above 150°C, fragmenting supplier capabilities across thermal bands.
- Medium-Temperature:Ambient-to-150°C ranges with platinum RTD sensors dominate biopharmaceutical applications. Precious metal price volatility directly impacts bill-of-materials for these precision control modules.
- High-Temperature:150-300°C blocks with ceramic-insulated elements serve materials science and polymer testing. These configurations require specialized alloy machining that concentrates among European and North American suppliers.
- Low-Temperature:Sub-ambient to 50°C systems with Peltier cooling extensions support enzyme preservation workflows. Demand concentrates in academic research settings with limited capital budgets.
- Ultra-High-Temperature:300-450°C ranges with silicon carbide heating elements address specialized catalysis and petrochemical applications. Limited installed base reflects narrow application scope and extreme material costs.
Medium-temperature systems command the largest revenue share; high-temperature units show steepest expansion trajectory in materials testing.
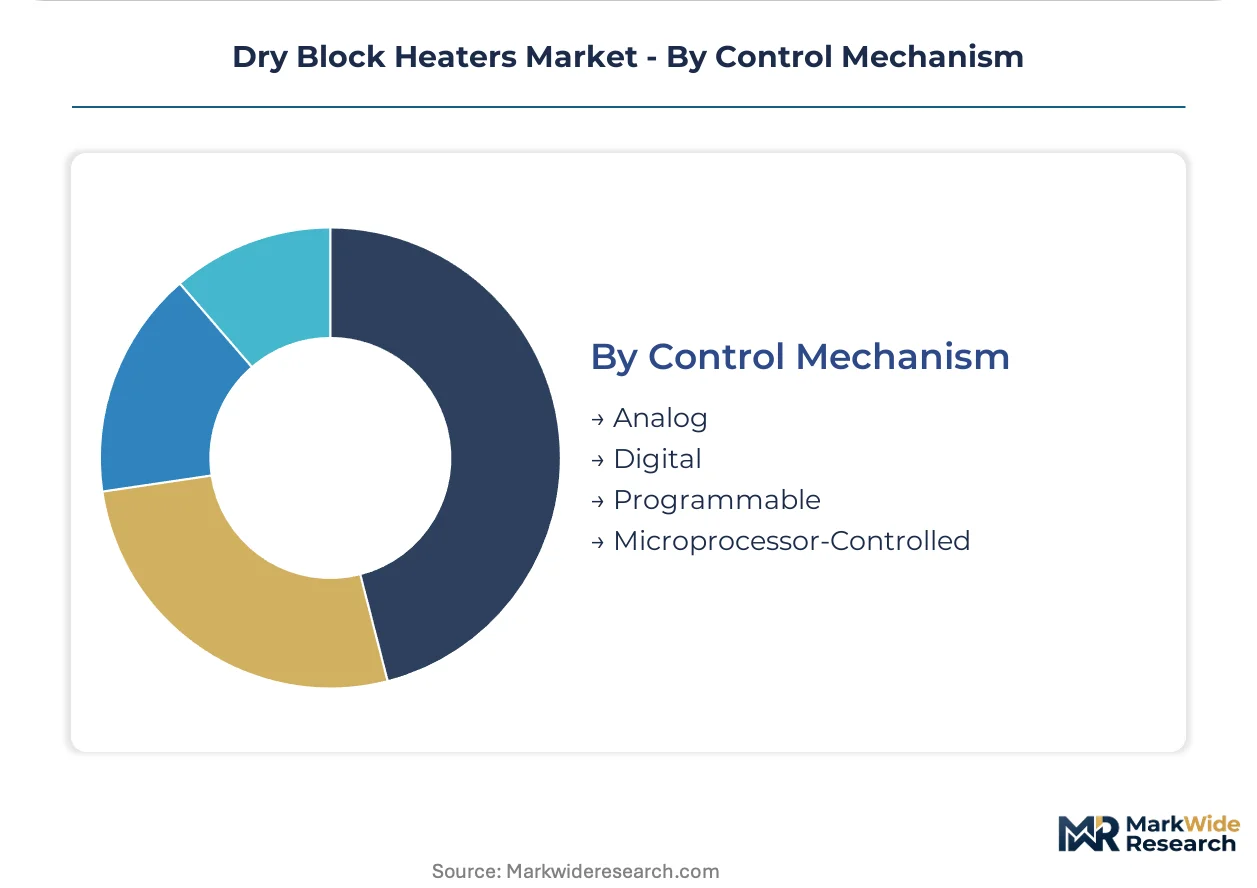
Control Mechanism:
Digital architecture migration is compressing replacement cycles as analog fleets face data integrity framework integration friction.
- Microprocessor-Controlled:Touchscreen PID controllers with programmable protocol libraries unify temperature cycling, data logging, and alarm management. Biopharmaceutical quality control departments in Massachusetts and Switzerland specify these for stability chamber backup systems.
- Programmable:Wi-Fi-enabled units with cloud-connected protocol libraries integrate directly with LIMS systems. FDA-regulated facilities are adopting these for unified thermal cycling data and electronic batch records.
- Digital:Basic microprocessor units with fixed ramp rates and digital displays serve mid-tier quality control labs upgrading from analog instruments. ISO 17025 accreditation mandates are accelerating retirement of older thermostat systems in favor of these traceable alternatives.
- Analog:Dial-based thermostat controls with bimetallic sensors persist in budget-constrained academic settings. Legacy fleet retrofit complexity creates integration friction when connecting 1990s-era equipment to modern data integrity frameworks.
Microprocessor-controlled systems capture expanding margin pools; programmable configurations are gaining share fastest in regulated pharmaceutical facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Jiangsu province anchors heating element supply for temperature-controlled laboratory equipment, with ceramic cartridge and resistance wire manufacturing clusters feeding assembly operations across Asia-Pacific and European markets.
Germany
Contract research organizations in Munich and Heidelberg are upgrading thermal equipment for EMA analytical method validation compliance. The country's national pharmaceutical regulator enforces strict documentation requirements for drug stability protocols. Bavaria's dense CRO cluster absorbs premium-priced programmable dry block systems with automated data logging capabilities.
United States
FDA-regulated biopharmaceutical facilities in Massachusetts and North Carolina specify microprocessor-controlled systems for electronic batch record integration. EPA Good Laboratory Practice amendments mandate enhanced temperature traceability for environmental toxicity testing. Boston-area quality control labs are retiring analog fleets in favor of digitally traceable alternatives.
China
Precision instrument manufacturers in Shanghai and Suzhou are expanding export capacity for temperature-controlled laboratory equipment. The country's national medical products administration aligns with international standards for analytical instrument validation. Yangtze River Delta production clusters serve domestic CDMO expansion while penetrating Southeast Asian research markets.
India
Domestic manufacturing incentives under the PLI scheme for analytical instruments are attracting assembly partnerships for temperature-controlled equipment. The Central Drugs Standard Control Organization tightens validation protocols for pharmaceutical quality control labs. Maharashtra's CDMO corridor generates demand for industrial-format dry block systems with high-throughput well configurations.
Switzerland
Biopharmaceutical quality control departments in Basel specify programmable systems for stability chamber backup and forced degradation studies. Swissmedic guidance on analytical method validation shapes equipment procurement specifications. The country's pharmaceutical manufacturing cluster sustains premium positioning for precision thermal instruments with ±0.1°C uniformity standards.
Dry Block Heaters Market Vendor Landscape
Global majors compete with regional champions across distribution infrastructure and service bundling capabilities. The vendor base stratifies between integrated life science conglomerates with extensive calibration networks and specialized temperature-control fabricators with engineering heritage positioning. Three archetypes dominate: precision engineering specialists leveraging geographic origin reputation, diversified laboratory equipment platforms with consolidated procurement relationships, and emerging Asia-Pacific manufacturers competing on cost-adjusted specifications. Capacity expansion and cloud-connected protocol library development represent the dominant competitive vectors as pharmaceutical facilities upgrade validation capabilities.
Among European precision engineering specialists, Grant Instruments and IKA exemplify heritage-based positioning in research markets. Thermo Fisher Scientific anchors the integrated platform tier with North American distribution density. Eppendorf occupies a position within the programmable control segment, representing digital architecture migration trends in regulated facilities. These three company profiles illustrate the competitive tension between engineering tradition and integrated service scale.
| Leading Market Players |
|---|
| Grant Instruments |
| IKA |
| VLM GmbH |
| Stuart Equipment |
| Corning Life Sciences |
| Ratek |
| Thermo Fisher Scientific |
| Eppendorf |
| Labnet International |
| Others |
Supply Flow & Price Mechanics
Microprocessor-based PID controller migration is compressing replacement cycles while simultaneously concentrating manufacturing capability among suppliers with precision machining and firmware development competencies. This technological shift elevates bill-of-materials for platinum RTD sensors and ceramic-insulated heating elements, creating cost asymmetries between legacy analog fabricators and digitally integrated platforms.
Pricing Analysis
Extended warranty and calibration service bundling separates premium-tier programmable systems from unbundled bench-top configurations in academic procurement. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 17025 certification grade and electronic batch record integration depth. Pricing pressure stems from consolidated procurement through group purchasing organizations compressing vendor margins. Universities exhibit highest price sensitivity, while GMP-compliant pharmaceutical facilities absorb premium positioning for automated documentation capabilities.
Supply Chain Analysis
Direct-to-laboratory channels serve pharmaceutical quality control labs requiring qualification documentation, while distributor networks handle academic and research institution volume. Ceramic cartridge and resistance wire manufacturing clusters in China's Jiangsu province feed assembly operations across Asia-Pacific and European markets. Raw material dependencies center on aluminum alloy precision stock, platinum RTD sensors, and silicon carbide heating elements. Single-geography concentration in Jiangsu province creates vulnerability to regional disruption. Distribution runs through OEM service contracts for regulated facilities and independent laboratory distributors for budget-constrained segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around digitally traceable systems as ISO 17025 accreditation mandates force analog-dependent suppliers toward obsolescence. Weaker players lacking firmware development capabilities or calibration service infrastructure face exclusion from pharmaceutical procurement.
For Market Incumbents: Anticipate margin compression from Chinese precision instrument manufacturers expanding export capacity. Defensive moves require deepening cloud-connected protocol library development and securing multi-year thermal equipment service agreements with university hospital systems. Threat substitution from water baths in budget-constrained academic segments demands tiered product architecture protecting premium positioning. For New Entrants and Emerging Players: Contract research organization procurement channels in Germany's Bavaria cluster offer lowest barrier-to-entry for programmable system penetration. White-space targets include portable format supply for Australian and Canadian environmental monitoring teams and local assembly partnerships under India's PLI scheme for analytical instruments. Go-to-market positioning should emphasize Wi-Fi-enabled LIMS integration for mid-tier quality control labs upgrading from analog fleets. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated life science conglomerates seeking calibration network density. Long-term viability favors precision engineering specialists with Cambridge or German heritage positioning and established pharmaceutical validation documentation. Acquisition target archetype: mid-tier digital control fabricators with ISO 17025-traceable certificate capabilities and regional service infrastructure. Signal to watch: EMA analytical method validation guidance amendments tightening documentation requirements for drug stability protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Protocol Library Development | Wi-Fi-enabled dry blocks unify thermal cycling data with FDA-regulated electronic batch records. |
| Multi-Year Service Agreement Migration | Academic medical centers in Germany and Netherlands shift from transactional purchases to bundled thermal equipment contracts. |
| Local Assembly Partnership Formation | India's PLI scheme for analytical instruments attracts CDMO-serving manufacturing joint ventures. |
| Precision Machining Capability Investment | CNC well-bore tolerance advances enable ±0.1°C uniformity standards for PCR workflows. |
| Calibration Network Geographic Expansion | Metrology technician scarcity in ISO 17025 audit experience extends service lead times, rewarding dense coverage. |
Methodological Framework
Document review covered FDA 483 inspection observations, EMA guidance documents on analytical method validation, and ISO 17025 accreditation body reports, complemented by interviews with laboratory equipment procurement managers at German contract research organizations, quality control directors at Swiss biopharmaceutical facilities, and aftermarket service heads at temperature-control OEMs. Secondary validation drew from SEC filings of listed life science conglomerates, customs data on precision instrument trade flows, and pharmaceutical manufacturing capacity expansion announcements. Bottom-up demand modeling from installed base replacement cycles and top-down market sizing from supplier revenue disclosures were triangulated for convergence.
Historical analog-to-digital replacement velocity was cross-referenced against panel input from procurement committees at academic medical centers and GMP facility qualification specialists. The analytical framework spans product format, control mechanism sophistication, end-user regulatory exposure, and temperature range band across the projection horizon. CAGRs were derived from segment-level growth rate differentials weighted by revenue concentration. Industry-specific forecast inputs include EMA guidance amendment timing and CDMO expansion rates under India's PLI scheme for analytical instruments.
Several conditions sit outside the modeled scope, including platinum spot price volatility impacts on high-precision temperature module costs and unannounced regulatory guidance shifts from FDA or EMA. Forecasts reflect base-case assumptions on accreditation mandate enforcement intensity and pharmaceutical outsourcing trajectory. Periodic stress-testing of base assumptions is recommended against metrology technician labor market tightness and heating element supply concentration developments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Industrial Refrigeration Systems Market
Industrial Equipment
Global Dosing Systems Market
Industrial Equipment
Air Preparation Equipment (FRL) Market
Industrial Equipment
Digital Tube Roller Market
Industrial Equipment
Electronic Beam Machining Market
Industrial Equipment
North America Rental Chillers Market
Industrial Equipment
Global DC Drives Market
Industrial Equipment
Europe Vacuum Pump Market
Industrial Equipment
Commercial Refrigeration System Market
Industrial Equipment
United States Fusion Splicer Market
Industrial Equipment
Femtosecond Fiber Lasers Market
Industrial Equipment
Rotary Scroll Air Compressor Market
Industrial Equipment
Semiconductor Cartridge Heaters Market
Industrial Equipment
Global Laser Material Market
Industrial Equipment
Global Temperature Control Units (TCU) Market
Industrial Equipment
Europe Ceramic Roller Bearings Market