
 Ceramic Roller Bearings Market | 2026-2036
Ceramic Roller Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Roller Bearings Market Intelligence
Aftermarket service revenue is rewriting margin capture across the ceramic roller bearings value chain. CeramTec GmbH leverages captive silicon nitride powder production to sustain cost discipline across precision bearing lines. NSK Ltd. anchors its position through R&D intensity in hybrid bearing architectures for electric vehicle powertrains. Schaeffler Technologies AG & Co. KG competes via manufacturing scale at its German and Chinese plants, extending geographic coverage for industrial OEM accounts.
Ceramic roller bearings are antifriction rolling-element bearings fabricated from silicon nitride, alumina, zirconia, or ceramic matrix composites, typically achieving operating temperatures above 500°C with density roughly 40% below steel equivalents; they serve critical functions in spindles, turbines, and precision motion systems where corrosion resistance, electrical insulation, or extreme thermal stability is mandatory. Silicon nitride bearings dominate aerospace and medical equipment applications where fatigue life and thermal shock resistance command premium positioning, while hybrid bearings—combining ceramic rolling elements with steel races—represent the fastest-growing material configuration as automotive and industrial machinery customers balance performance gains against retrofit compatibility. Precision bearings capture the deepest margin pools, though custom bearings for semiconductor fabrication equipment and specialized medical imaging systems are expanding fastest among end-user segments.
EPA emissions standards for industrial machinery and automotive powertrains are tightening tolerance requirements for bearing systems, directly elevating ceramic specifications in US-manufactured equipment. ECHA REACH compliance and the EU F-Gas Regulation are reshaping material qualification pathways for European suppliers, while China's GB standards and MIIT industrial upgrading directives are accelerating domestic substitution in high-precision bearing categories. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's embodied carbon tracking converge on ceramic bearing supply chains, as lifecycle emissions accounting becomes a procurement gate for multinational OEMs.
Market Dynamics
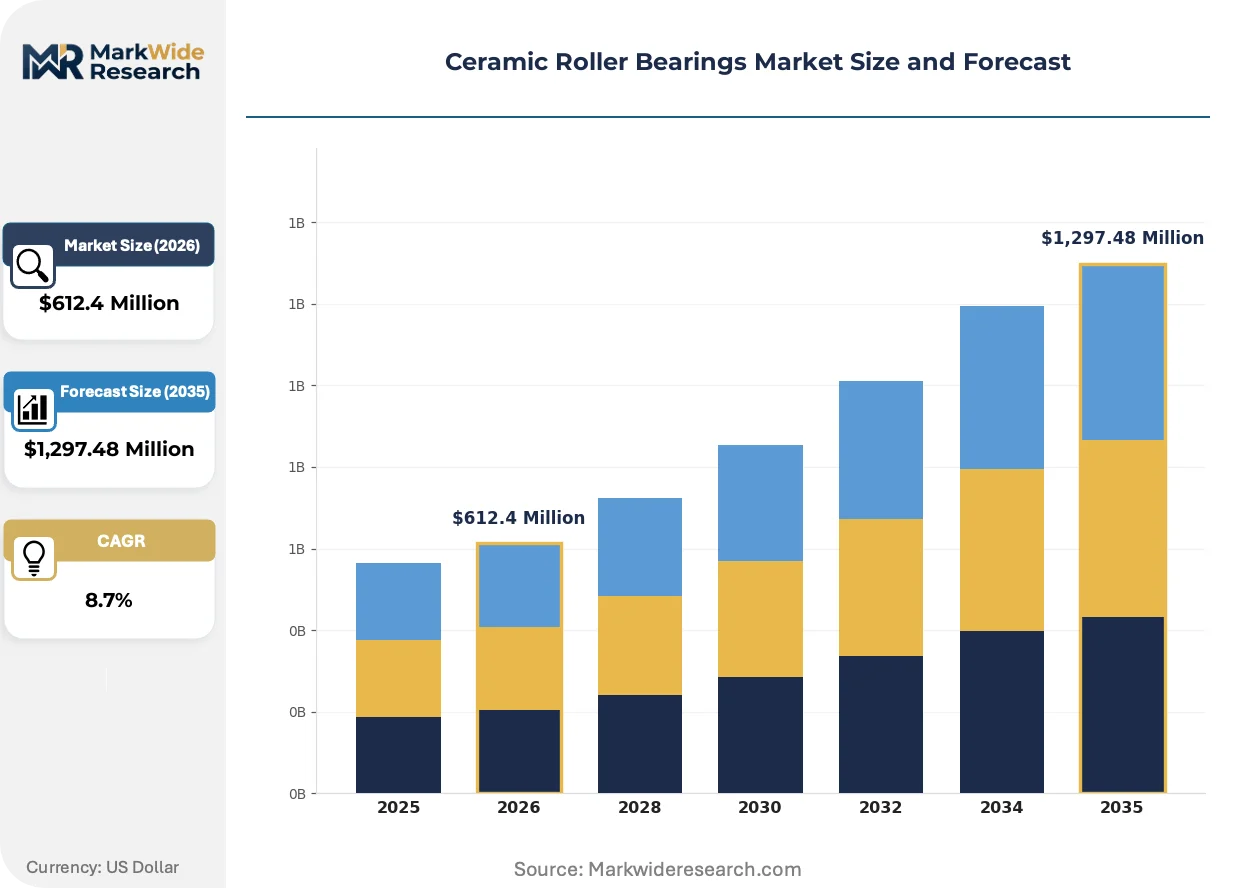
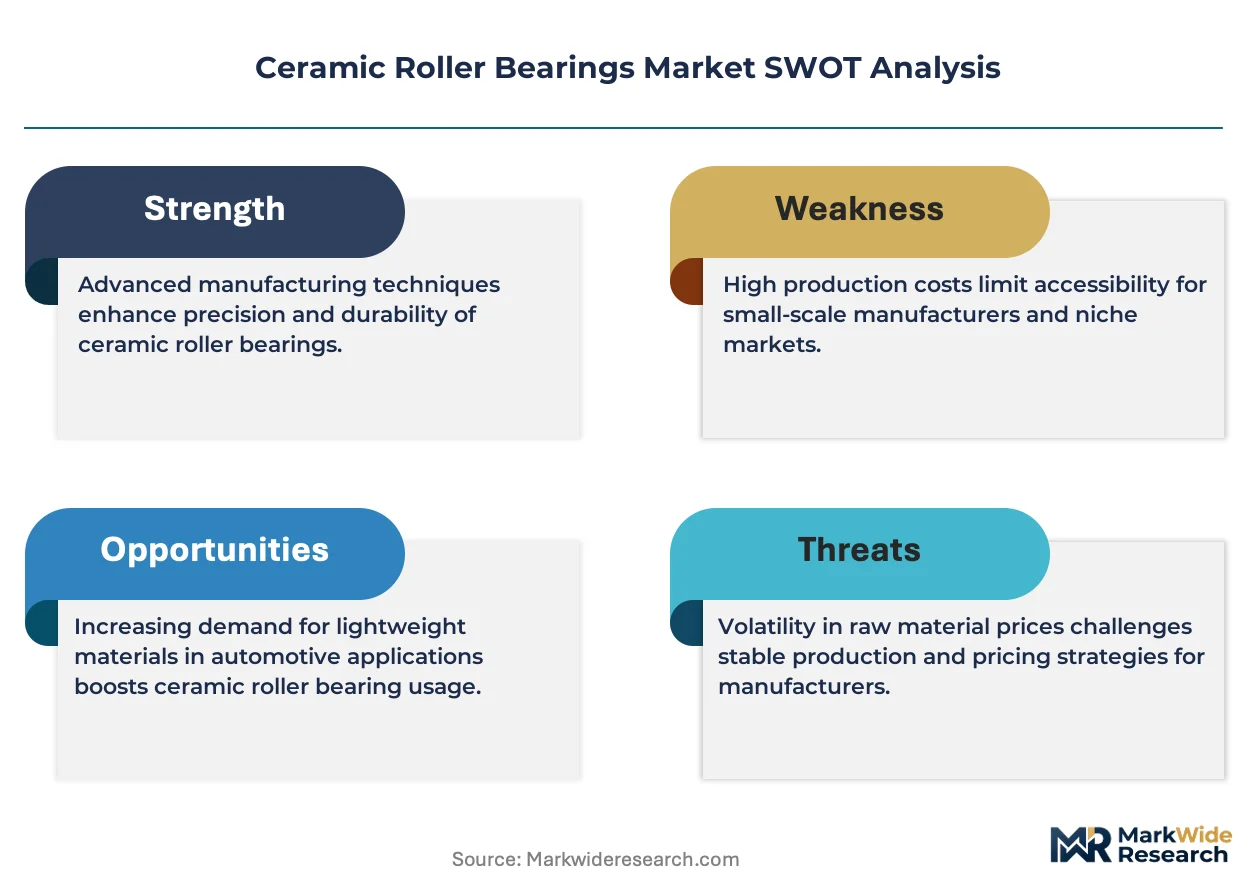
Silicon nitride powder supply concentration and EPA emissions mandates for industrial equipment are compressing procurement timelines while elevating technical qualification barriers for bearing suppliers across aerospace and automotive tiers.
Growth Catalysts
- EPA Industrial Emissions Standards:Tightening tolerance requirements for US-manufactured machinery are forcing specification upgrades toward ceramic bearing systems that maintain dimensional stability under thermal cycling.
- Electric Vehicle Powertrain Architectures:Automotive OEM technical centers in Germany are accelerating hybrid ceramic bearing adoption for motor spindle applications requiring electrical insulation and reduced rotational mass.
- Silicon Nitride Fatigue Performance:Material innovations extending rolling-contact fatigue life beyond steel equivalents are displacing conventional bearings in high-speed turbine applications.
Market Restraints
- Raw Material Concentration:High-purity silicon nitride powder production concentrates among Japanese and German specialty chemical suppliers, creating input cost volatility and qualification bottlenecks.
- ECHA REACH Compliance Burden:European material qualification pathways impose 18-24 month registration timelines for new ceramic formulations, delaying product launches.
- Hybrid Bearing Substitution Pressure:Steel-ceramic hybrid configurations are capturing mid-performance applications where full ceramic specifications previously dominated, compressing addressable volume for monolithic designs.
Strategic Opportunities
- China Domestic Substitution Mandates:MIIT industrial upgrading directives and GB standards alignment are opening procurement channels for local ceramic bearing producers in semiconductor fabrication equipment.
- Medical Imaging System Integration:MRI and CT scanner manufacturers are specifying ceramic bearings for non-magnetic precision motion systems, creating application white space outside traditional industrial and aerospace segments.
- EU Green Deal Embodied Carbon Tracking:Lifecycle emissions accounting requirements are favoring ceramic bearings in multinational OEM procurement gates due to extended service intervals and reduced lubricant consumption.
Industry Challenges
- Ceramic Grinding Specialist Scarcity:Precision finishing operations require technicians trained in diamond wheel conditioning and subsurface damage control, with workforce gaps concentrated in Midwest US and Eastern European manufacturing regions.
- AS9100D Certification Timelines:Aerospace bearing suppliers face 14-18 month qualification cycles for production facility approvals, constraining capacity expansion responsiveness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Roller Bearings Market |
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,297.48 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Bearings, Precision Bearings, Custom Bearings, Hybrid Bearings Application: Aerospace, Automotive, Industrial Machinery, Medical Equipment Material: Ceramic Matrix Composites, Silicon Nitride, Alumina, Zirconia End User: Manufacturers, OEMs, Aftermarket Providers, Service Centers |
| Companies Covered | AB SKF, Cerabea Co. Ltd., CeramicSpeed, CeramTec GmbH, Emerson Bearing Company, Hentec Oy Ab, JTEKT Corporation, NSK Ltd., Schaeffler Technologies AG & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Roller Bearings Market Strategic Shifts & Innovations
Material science advances and regulatory emissions frameworks are converging to redefine bearing specification criteria across precision engineering clusters, with hybrid architectures and lifecycle accountability emerging as dominant design principles.
Silicon nitride rolling elements are hybridizing with steel races to create bearing configurations that balance thermal performance against retrofit compatibility. Automotive powertrain engineers in Stuttgart and Detroit are specifying these hybrids for electric motor applications at accelerating rates. This architecture is hybridizing the competitive landscape by enabling incumbent steel bearing manufacturers to defend position without full ceramic conversion capex.
EPA emissions standards for industrial machinery are tightening tolerance bands on rotating equipment, directly elevating ceramic bearing specifications in US-manufactured compressors and pumps. Equipment OEMs are responding by pre-qualifying ceramic options in new platform designs rather than retrofitting legacy steel configurations. The industrial machinery segment is most affected, with specification intensity concentrating in Texas and Ohio manufacturing corridors.
Aftermarket service unbundling is separating bearing replacement from original equipment vendor maintenance contracts. Industrial machinery operators in Germany's precision engineering clusters are procuring ceramic bearings directly from specialty distributors, bypassing OEM service networks. This pattern is most visible in automotive supplier parks around Munich and Wolfsburg, where technical buyers maintain in-house tribology expertise.
Ceramic Roller Bearings Market Segmentation
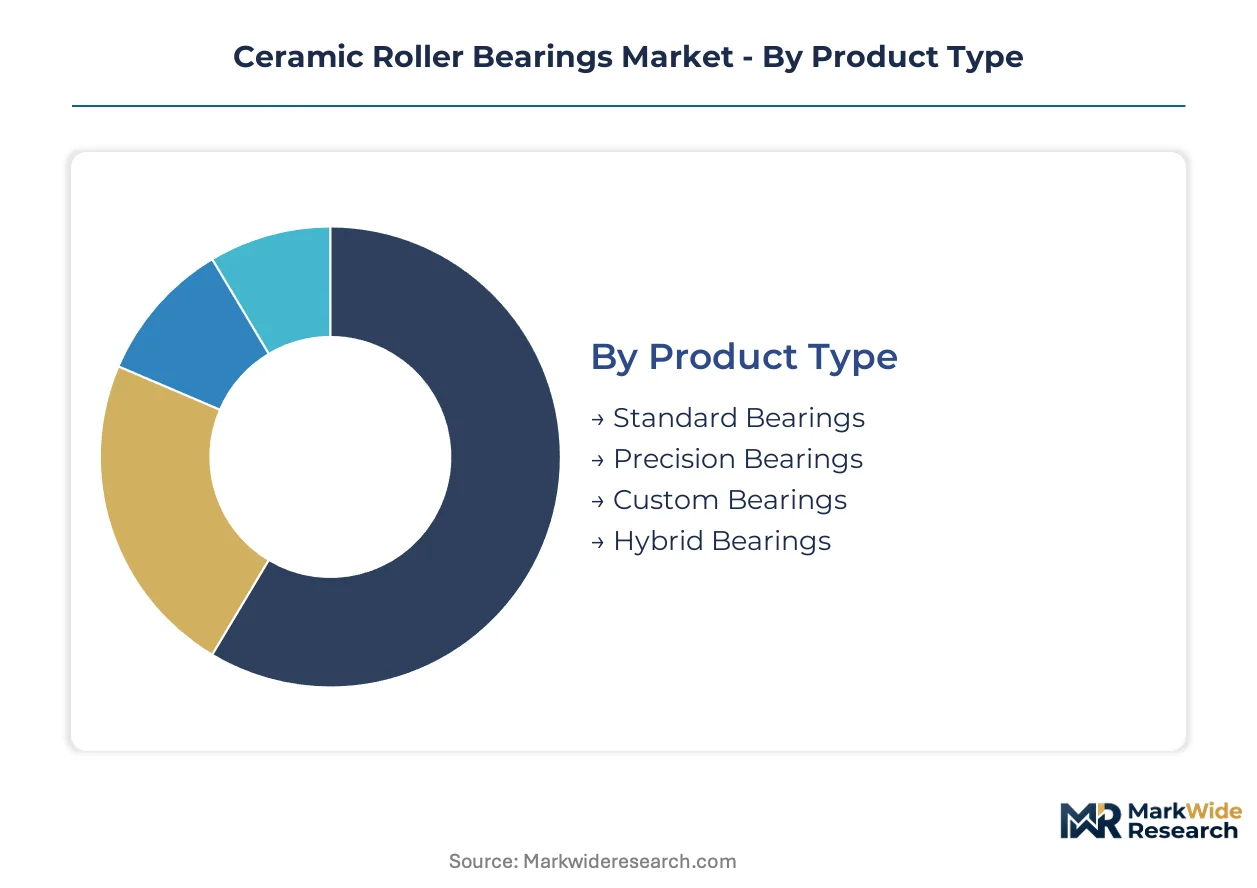
Ceramic roller bearing procurement cycles vary dramatically across product tiers, with standard inventory turning in weeks while custom semiconductor-grade bearings stretch to quarters. Aerospace qualification timelines further stratify replacement demand, creating predictable revenue concentration patterns that suppliers must map against capacity planning.
Product Type:
Replacement velocity separates commodity bearings from engineered solutions, with standard catalogs cycling fastest and custom fabrication locking working capital longest.
- Standard Bearings:Off-the-shelf dimensions with ISO tolerances serve maintenance departments across industrial machinery parks. German automotive supplier clusters around Wolfsburg and Munich drive volume through consolidated distributor procurement.
- Hybrid Bearings:Silicon nitride rolling elements paired with steel races balance thermal performance against retrofit economics. Stuttgart powertrain engineering centers specify these for electric motor spindles requiring electrical insulation and reduced rotational mass.
- Precision Bearings:Sub-micron tolerances for semiconductor fabrication equipment and medical imaging systems.
- Custom Bearings:Application-specific geometries for specialized turbine and scanner integrations.
Standard bearings dominate installed base. Hybrid bearings are where expansion concentrates.
Application:
Margin capture potential inverts against volume scale, with aerospace and medical commanding premium positioning while industrial machinery supplies foundational revenue.
- Aerospace:Turbine engine bearings must survive thermal cycling above 500°C while maintaining fatigue resistance under centrifugal loading. AS9100D certification requirements in US and German manufacturing corridors constrain supplier eligibility.
- Medical Equipment:MRI and CT scanner manufacturers specify non-magnetic ceramic bearings for precision motion systems where electromagnetic interference corrupts imaging quality. FDA device center regulations and EU MDR compliance shape qualification pathways.
- Automotive:Electric powertrain architectures in Detroit and Stuttgart technical centers.
- Industrial Machinery:Compressors and pumps under tightening EPA emissions standards.
Industrial machinery anchors volume throughput. Medical equipment is climbing the fastest.
Material:
Performance tiering follows fracture toughness and thermal shock resistance hierarchies, with silicon nitride commanding aerospace specification while alumina serves cost-sensitive industrial applications.
- Silicon Nitride:Highest rolling-contact fatigue life and thermal shock resistance among monolithic ceramics. Japanese and German powder suppliers concentrate high-purity feedstock production, creating input bottlenecks for tier-two bearing manufacturers.
- Ceramic Matrix Composites:Fiber-reinforced architectures for extreme thermal gradient applications in next-generation turbine designs. US DOE advanced manufacturing programs and EU Horizon funding accelerate development timelines.
- Alumina:Cost-effective electrical insulation for standard industrial duty cycles.
- Zirconia:Transformation-toughened grades for moderate load-bearing with improved fracture resistance.
Silicon nitride dominates premium specification. Ceramic matrix composites show steepest expansion trajectory.
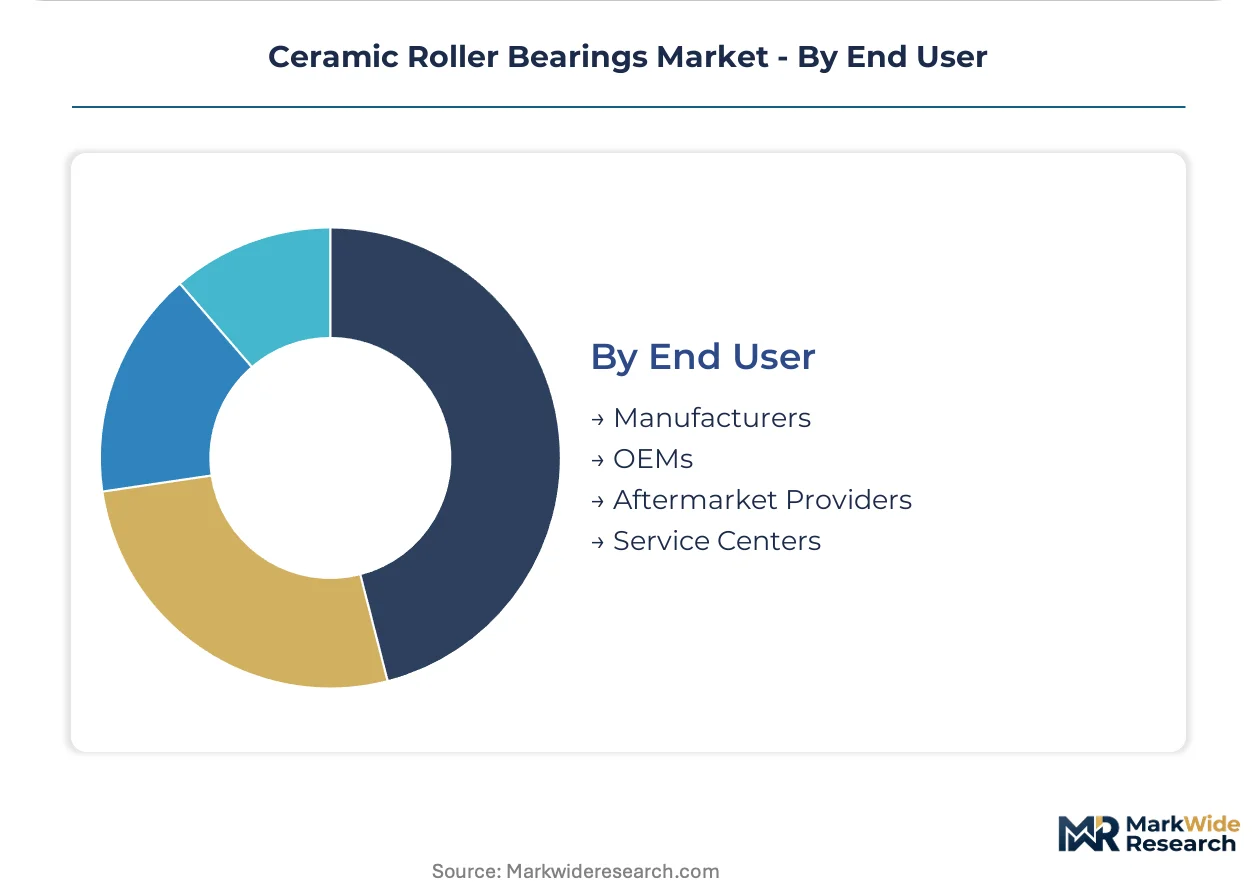
End User:
Channel control and technical buying power determine pricing realization, with OEM captive procurement commanding deepest discounts and aftermarket direct sales capturing fullest margin.
- OEMs:Original equipment manufacturers in aerospace and automotive sectors leverage platform-level procurement authority to negotiate multi-year supply agreements. German automotive OEM technical centers specify hybrid architectures at volume scale.
- Aftermarket Providers:Independent distributors and service networks are unbundling bearing replacement from OEM maintenance contracts. Precision engineering clusters in Bavaria and Baden-Württemberg host technical buyers with in-house tribology expertise.
- Manufacturers:Captive bearing production for integrated equipment builders.
- Service Centers:Maintenance contractors with regional equipment coverage.
OEMs dominate contract value. Aftermarket providers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity silicon nitride powder production clusters in Japan and Germany feed precision bearing fabrication across three continents. Aerospace turbine manufacturers in the United States and Germany drive specification intensity for thermal-resistant bearing systems. Automotive OEM technical centers in Stuttgart and Detroit accelerate hybrid ceramic bearing procurement for electric powertrain architectures.
United States
EPA emissions standards for industrial machinery tighten tolerance requirements on rotating equipment in Texas and Ohio manufacturing corridors. Equipment OEMs pre-qualify ceramic bearing options in new compressor and pump platform designs. Aerospace bearing suppliers face 14-18 month AS9100D certification cycles for production facility approvals, constraining capacity expansion in Midwest precision manufacturing regions.
Germany
Precision engineering clusters in Bavaria and Baden-Württemberg host automotive supplier technical centers specifying hybrid ceramic bearings for electric motor spindles. ECHA REACH compliance imposes 18-24 month registration timelines for new ceramic formulations, delaying product launches. Aftermarket service unbundling separates bearing replacement from OEM maintenance contracts in automotive supplier parks around Munich and Wolfsburg.
China
MIIT industrial upgrading directives and GB standards alignment accelerate domestic substitution in high-precision bearing categories for semiconductor fabrication equipment. Dual carbon goals converge on ceramic bearing supply chains as lifecycle emissions accounting becomes a procurement gate for multinational OEMs. Yangtze River Delta manufacturing bases expand captive silicon nitride powder production to reduce import dependency.
Japan
Japanese specialty chemical suppliers concentrate high-purity silicon nitride powder production, creating input cost volatility for tier-two bearing manufacturers. METI industrial policy supports advanced ceramic matrix composite development for next-generation turbine applications. JIS standards alignment shapes qualification pathways for domestic bearing producers serving automotive and industrial machinery segments.
Ceramic Roller Bearings Market Key Industry Players
Material-integrated specialists and scale-driven diversified manufacturers split the market along vertical integration and geographic coverage vectors. Japanese and European suppliers anchor premium specification tiers through captive powder production and precision finishing capabilities. Competitive moves concentrate on backward integration into silicon nitride feedstock and strategic partnerships with aerospace OEMs for long-term supply agreements.
Among Germany-based fabricators, CeramTec GmbH and Schaeffler Technologies AG & Co. KG exemplify the material-integrated archetype through upstream control over ceramic powder production. NSK Ltd. represents the diversified multinational tier with R&D intensity in hybrid bearing architectures. These three anchors demonstrate how competitive positioning stratifies between feedstock security and application engineering depth.
| Leading Market Players |
|---|
| AB SKF |
| Cerabea Co. Ltd. |
| CeramicSpeed |
| CeramTec GmbH |
| Emerson Bearing Company |
| Hentec Oy Ab |
| JTEKT Corporation |
| NSK Ltd. |
| Schaeffler Technologies AG & Co. KG |
| Others |
Cost & Logistics Intelligence
Yokohama-to-Rotterdam container freight corridors transmit silicon nitride powder cost volatility directly into European bearing fabrication economics, amplifying price spreads between Japanese feedstock-anchored suppliers and tier-two converters dependent on spot procurement.
Pricing Analysis
EPA emissions standards dictate the pricing tier structure across US-manufactured industrial equipment, with AS9100D-certified aerospace bearings commanding premium positioning over standard ISO-grade industrial variants. Price differentiation rests on certification grade and volume scale, with automotive OEM multi-year contracts securing deepest discounts against aftermarket direct procurement. Cost compression in hybrid bearing tiers is intensifying because steel-ceramic configurations enable incumbent manufacturers to compete without full ceramic conversion investment. Aftermarket providers serving Bavarian precision engineering clusters exhibit lowest price sensitivity due to captive tribology expertise.
Supply Chain Analysis
High-purity silicon nitride powder production concentrates in Japan and Germany, with tier-two bearing manufacturers drawing from concentrated Japanese specialty chemical suppliers for feedstock qualification. Raw material dependencies center on silicon nitride powder, diamond grinding wheels, and precision steel races for hybrid architectures. Single-source vulnerability in Japanese powder supply creates qualification bottlenecks during demand surges. Distribution runs through OEM captive procurement networks for aerospace and automotive volumes, with independent distributors gaining share in German aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ceramic roller bearings market is exiting a procurement downturn as aerospace turbine production rates recover and automotive electrification capex cycles inflect, creating cyclical tailwinds for specification-intensive suppliers.
For Market Incumbents: Harden feedstock security through backward integration into silicon nitride powder production or long-term offtake agreements with Japanese suppliers, insulating margin structures from input volatility. Deepen AS9100D certification coverage across Midwest US and Eastern European manufacturing corridors to defend aerospace tier positioning against emerging Asian competitors.
For New Entrants and Emerging Players: Build out medical imaging system integration capabilities, targeting MRI and CT scanner manufacturers in North American and European healthcare equipment clusters where non-magnetic bearing specifications create application white space. Pursue direct distributor relationships with German automotive supplier parks around Munich and Wolfsburg, bypassing OEM service networks to capture aftermarket margin pools.
For Investors and Strategic Acquirers: Precision finishing specialists with captive diamond wheel conditioning capabilities and subsurface damage control expertise represent the most defensible acquisition archetype in a market where workforce scarcity constrains capacity expansion. Monitor MIIT industrial upgrading directive implementation velocity as the inflection signal for Chinese domestic substitution momentum in semiconductor fabrication equipment bearings.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Nitride Feedstock | CeramTec GmbH's captive powder production sustains cost discipline against Japanese supply volatility. |
| AS9100D Certification Expansion | Midwest US facilities face 14-18 month qualification cycles that constrain competitor capacity responsiveness. |
| Hybrid Bearing Architecture R&D | Stuttgart and Detroit technical centers specify silicon nitride-steel configurations for electric motor spindles. |
| Medical Imaging System Partnerships | MRI manufacturers in North America specify non-magnetic ceramic bearings for precision motion systems. |
| Aftermarket Channel Direct Access | Bavarian precision engineering clusters bypass OEM service networks through independent distributor procurement. |
Research Approach
A standing panel of aerospace procurement directors, automotive Tier 1 supplier engineers, industrial maintenance managers, and ceramic powder production specialists provided ongoing calibration across primary interview cycles, validated against customs trade data, SEC filings from listed bearing manufacturers, EPA emissions compliance databases, and MIIT industrial policy directives. Bottom-up demand modeling triangulated against top-down market sizing across product type, application, material grade, and end-user channel dimensions.
Scenario-bracketing around EPA implementation timelines, aerospace production rate trajectories, and Chinese domestic substitution velocity framed the analytical envelope across the projection horizon. Segmentation modeling incorporated product tier, end-use industry, material specification, and geographic production cluster dimensions. CAGRs derived from rolling-contact fatigue life extension curves, electric vehicle powertrain penetration assumptions, and industrial machinery replacement cycle analysis.
Stress conditions across silicon nitride powder supply disruption, AS9100D certification timeline extension, and hybrid bearing substitution acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against aerospace OEM long-term supply agreement disclosure patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Linear Bearings Market
Industrial Equipment
Diaphragm Coupling Market
Industrial Equipment
Global High Speed Dispenser Market
Industrial Equipment
Global High Power Laser Systems Market
Industrial Equipment
Snowrator Market
Industrial Equipment
Above 300mm Cooling Fans Market
Industrial Equipment
Vibration Isolation Tables Market
Industrial Equipment
Air Preparation Equipment (FRL) Market
Industrial Equipment
Cartridge Heaters Market
Industrial Equipment
Industrial Monitor Market
Industrial Equipment
Laser Plastic Welding Market
Industrial Equipment
Parts and Equipment Market
Industrial Equipment
Fume Extractor Market
Industrial Equipment
Global Refrigeration Compressor Market
Industrial Equipment
Fiber Laser Coding System Market
Industrial Equipment
Global Industrial Dispensing System and Equipment Market