
 Above 300mm Cooling Fans Market | 2026-2036
Above 300mm Cooling Fans Market Size, Share, and Industry Trends Forecast 2026-2036
Above 300mm Cooling Fans Market Insights
Skilled motor-winding technicians is rotating from consumer electronics toward industrial and HVAC applications, tightening labor availability for high-diameter fan production. ebm-papst leverages its German engineering base to dominate premium centrifugal designs for cleanroom environments. Delta Electronics anchors Asia-Pacific supply through backward integration into driver IC and magnet manufacturing. Nidec Corporation competes on scale in axial platforms serving hyperscale data centers.
Above 300mm cooling fans are electromechanical air movers with impeller diameters exceeding 300 millimeters, typically constructed from glass-filled nylon or aluminum alloys and driven by brushless DC or AC induction motors to deliver airflow volumes above 2,500 cubic feet per minute for industrial thermal management. Axial configurations retain the largest installed base due to straightforward ducting compatibility and lower first cost in HVAC and electronics cooling, though centrifugal types command superior margins in aerospace and cleanroom applications where static pressure performance determines specification. Aluminum material grades are gaining specification share in high-power segments as thermal expansion coefficients and structural rigidity requirements intensify.
The EPA's fan efficiency rating standards and China's GB motor efficiency tiers are reshaping product roadmaps by disqualifying single-phase induction drives in favor of electronically commutated platforms. REACH substance restrictions and RoHS compliance obligations in Europe filter material choices for blade coatings and winding insulation, favoring suppliers with in-house regulatory certification capabilities. Stakeholders must monitor how evolving IEC 60034 efficiency classes and emerging carbon border adjustment mechanisms will reconfigure sourcing geography and technology investment priorities.
Market Dynamics
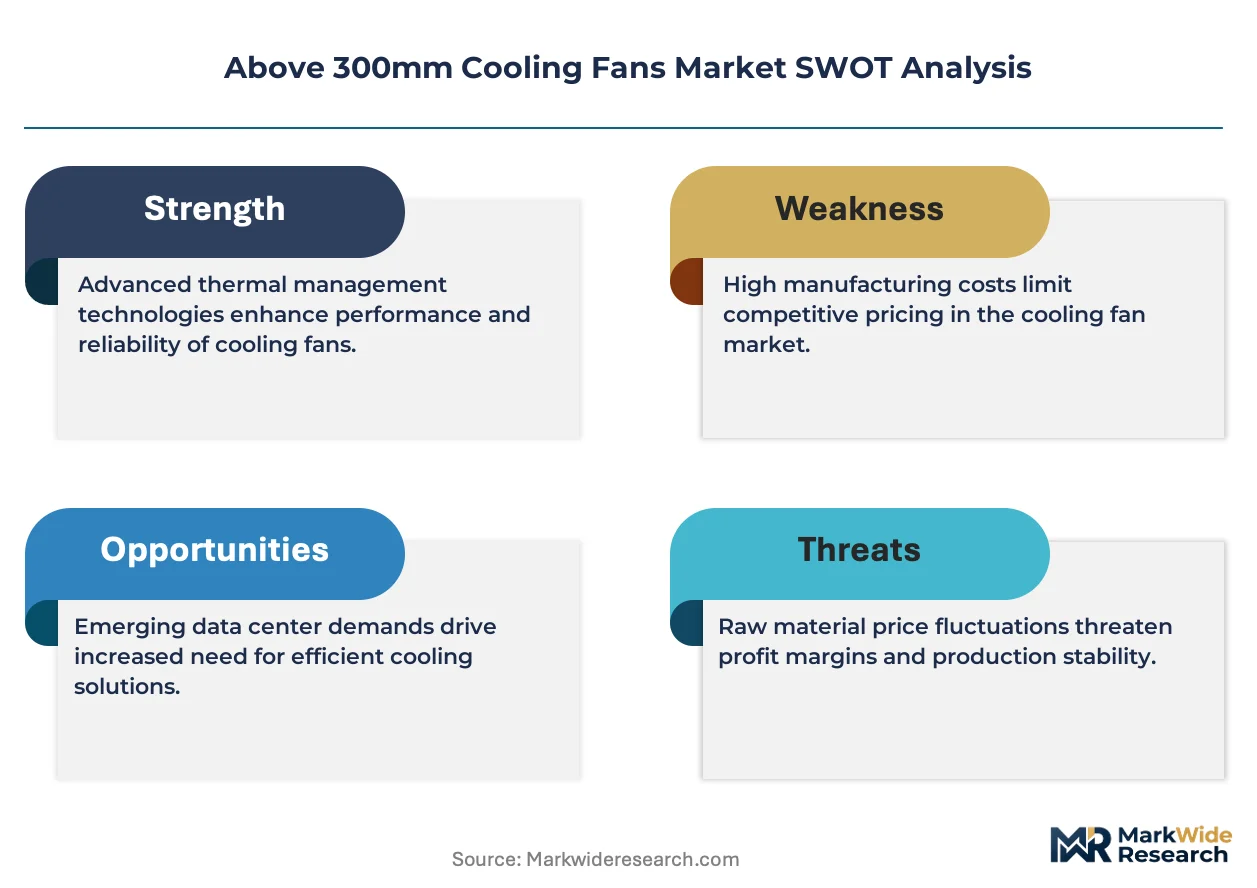
AI server rack densities above 50 kilowatts per cabinet are forcing hyperscale operators to abandon traditional air-cooled architectures, redirecting specification authority from HVAC contractors toward semiconductor thermal engineers who prioritize static pressure curves over first-cost metrics.
Growth Catalysts
- EPA Fan Efficiency Rating Standards:The US EPA's FER mandates are phasing out single-phase induction motors in commercial buildings, creating specification pull for electronically commutated platforms that deliver variable airflow with reduced wattage draw.
- Automotive Battery Testing Facilities:Germany's industrial automation corridor is expanding precision thermal chambers for lithium-ion validation, requiring centrifugal configurations that maintain ±0.5°C uniformity across 300mm+ impeller spans.
- Glass-Filled Nylon Compounds:Advanced polymer formulations with 35% fiber loading are reducing blade mass by 40% versus aluminum while meeting UL 94 V-0 flame ratings, enabling quieter operation in data center white spaces.
Market Restraints
- Neodymium Price Volatility:Rare earth magnet costs for brushless DC motors fluctuate with Chinese export quota policies, compressing margins on premium centrifugal platforms where magnet mass exceeds 200 grams per unit.
- Cleanroom Certification Bottlenecks:ISO 14644-1 Class 5 validation timelines extend 14-18 months for aluminum impeller assemblies, delaying revenue recognition on aerospace and pharmaceutical contracts.
- Heat Pump Substitution:Liquid cooling loops with cold plates are capturing specification share in AI training clusters above 100 kilowatts per rack, threatening axial fan volumes in the highest-density server segments.
Strategic Opportunities
- India's PLI Scheme for Electronics:Production-linked incentives for semiconductor packaging facilities are attracting greenfield data center investments in Telangana and Gujarat, creating first-mover advantage for localized cooling component suppliers.
- EU F-Gas Regulation Phase-Down:The progressive HFC refrigerant quota reductions are accelerating indirect evaporative cooling architectures that depend on high-diameter axial banks for adiabatic heat rejection.
- Digital Twin Integration:Convergence of CFD simulation tools with IoT vibration sensors enables predictive blade fatigue modeling, opening recurring software revenue streams alongside hardware sales.
Industry Challenges
- Motor Winding Technician Scarcity:Skilled labor capable of precision coil insertion in 300mm+ stator frames is migrating toward electric vehicle powertrain manufacturing, lengthening production lead times for custom winding configurations.
- IEC 60034-30-1 Compliance Complexity:Multi-tier efficiency class certifications require redundant testing protocols across 50Hz and 60Hz electrical domains, inflating R&D overhead for suppliers serving both European and North American utilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Above 300mm Cooling Fans Market |
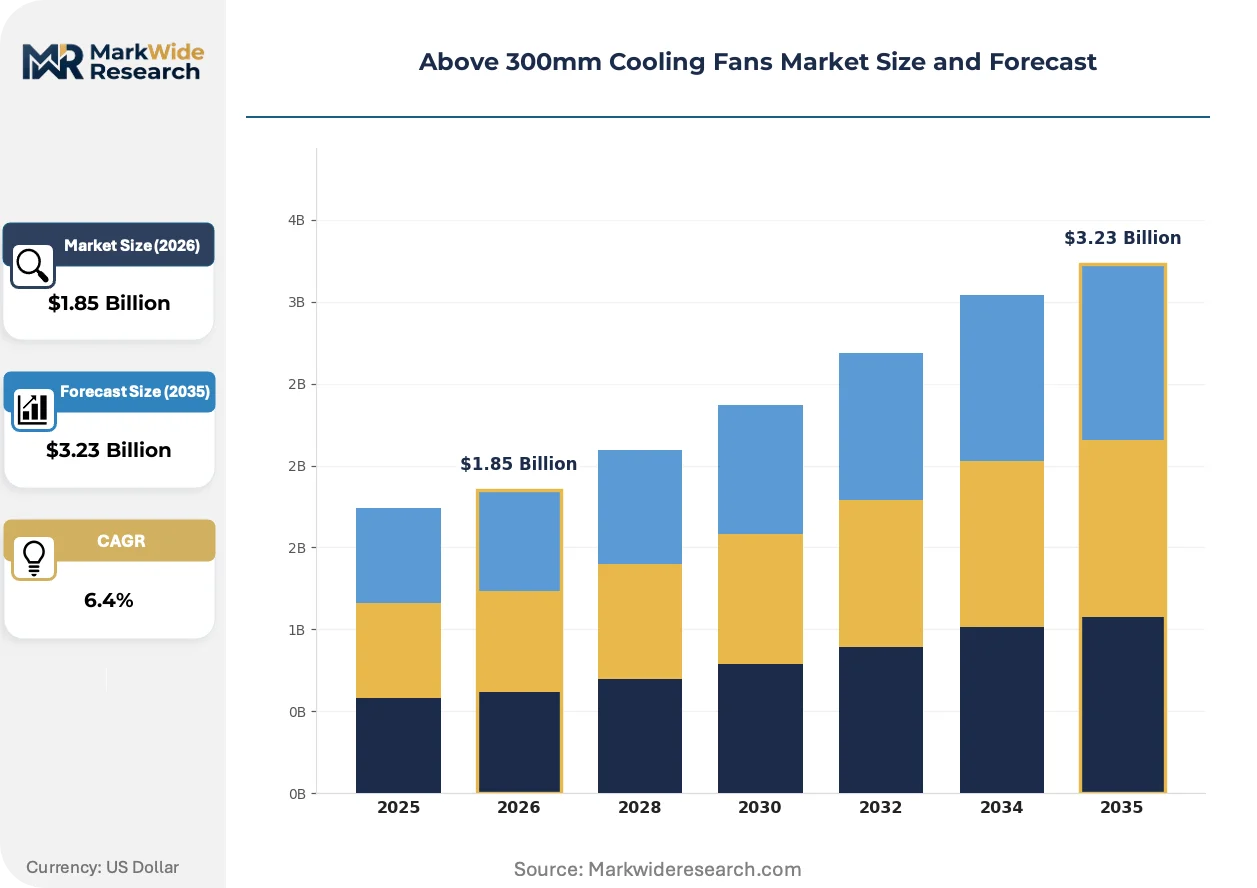
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Axial, Centrifugal, Mixed Flow, Bladeless Application: HVAC, Industrial Equipment, Electronics Cooling, Aerospace Material: Plastic, Metal, Composite, Aluminum Power Rating: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | Delta Electronics, ebm-papst, Nidec Corporation, Sunonwealth Electric Machine Industry, Sanyo Denki, Asia Vital Components, NMB Technologies Corporation, MinebeaMitsumi, Ziehl-Abegg, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Above 300mm Cooling Fans Market Trends and Innovations
Active magnetic bearing systems and advanced blade aerodynamics are converging to redefine performance benchmarks for rotating thermal management equipment, compressing maintenance intervals while extending operational lifespans in continuous-duty industrial environments.
Permanent magnet synchronous motors with integrated variable frequency drives are displacing traditional AC induction platforms in HVAC specifications above 5 horsepower. Data center operators in Virginia and Texas are specifying these configurations for chiller plant upgrades to meet utility demand-response incentives. The technology is displacing legacy wound-rotor designs by eliminating slip losses and enabling precise airflow modulation without external VFD cabinets.
China's GB 18613-2020 motor efficiency tiers are disqualifying IE2 induction platforms from government procurement catalogs, redirecting state-backed infrastructure tenders toward IE4 and IE5 premium efficiency categories. Domestic manufacturers in Jiangsu and Zhejiang provinces are retooling stator winding lines to capture this mandated upgrade cycle. The regulation most severely impacts centrifugal fan suppliers serving municipal wastewater treatment plants where continuous duty cycles amplify energy cost exposure.
Specification authority is migrating from mechanical contractors toward facility energy managers who prioritize total cost of ownership models over first-cost procurement. Industrial buyers in Germany's automotive battery testing corridor now require 10-year operational cost projections including predicted maintenance and energy consumption. This behavioral shift is most pronounced in cleanroom applications where unplanned downtime carries six-figure hourly penalties.
Above 300mm Cooling Fans Market Segmentation
Segmentation in the above 300mm cooling fans market reveals how substitution pressures and efficiency mandates reshape procurement priorities across impeller geometries, end-use applications, material platforms, and power classifications. Buyers increasingly segment by total cost of ownership rather than first-cost metrics, particularly in continuous-duty industrial environments.
Type:
Liquid cooling architectures and thermoelectric alternatives exert uneven substitution pressure across impeller configurations, with some geometries more defensible than others against emerging thermal management technologies.
- Axial:Straight-through airflow designs with propeller-style blades mounted parallel to the motor shaft deliver high volume at low static pressure. Data center operators in Virginia and Texas specify these for chiller plant upgrades and adiabatic heat rejection banks, though liquid cooling loops threaten volumes in AI training clusters above 100 kilowatts per rack.
- Centrifugal:Radial discharge configurations with forward- or backward-curved blades generate pressure rises exceeding 2,000 Pascals. Germany's automotive battery testing corridor demands these for precision thermal chambers requiring ±0.5°C uniformity, where static performance trumps first-cost metrics and substitution risk remains minimal.
- Mixed Flow:Hybrid geometries combining axial and radial flow characteristics serve ducted HVAC applications with moderate pressure requirements.
- Bladeless:Air-multiplier designs using induction and entrainment principles address noise-sensitive environments in commercial buildings.
Axial configurations anchor the volume base while centrifugal designs gain share at the steepest rate as specification authority migrates toward semiconductor thermal engineers prioritizing pressure curves.
Application:
End-use segmentation reflects diverging customer maturity levels, with some applications demanding decade-long operational cost projections while others remain fixated on procurement price.
- HVAC:Building climate control systems including chillers, air handling units, and cooling towers constitute the largest installed base. EPA Fan Efficiency Rating mandates are phasing out single-phase induction motors, redirecting commercial building specifications toward electronically commutated platforms with variable airflow capability.
- Electronics Cooling:Server racks, power supplies, and telecommunications equipment drive demand for compact high-flow solutions. AI server densities above 50 kilowatts per cabinet are forcing hyperscale operators to abandon traditional air-cooled architectures, compressing volumes in the highest-density segments.
- Industrial Equipment:Continuous-duty manufacturing processes including metal forming, welding, and material handling require robust thermal management.
- Aerospace:Aircraft environmental control systems and ground support equipment demand certified configurations with extended validation timelines.
HVAC absorbs the dominant share of unit shipments while electronics cooling contracts fastest where liquid alternatives capture specification authority.
Material:
Material selection increasingly hinges on regulatory compliance burdens and thermal expansion requirements rather than purely mechanical properties.
- Aluminum:Cast and extruded grades offer thermal conductivity exceeding 200 W/m·K and structural rigidity for high-speed rotation. High-power segments specify these as thermal expansion coefficients and centrifugal loading requirements intensify, particularly in aerospace and cleanroom applications where ISO 14644-1 certification demands dimensional stability.
- Plastic:Glass-filled nylon compounds with 35% fiber loading reduce blade mass by 40% versus metal alternatives while meeting UL 94 V-0 flame ratings. Data center white space deployments favor these for acoustic performance, though REACH substance restrictions filter coating and insulation choices.
- Metal:Steel and magnesium alloys serve cost-sensitive industrial applications with moderate performance requirements.
- Composite:Carbon fiber and hybrid laminates address weight-critical aerospace specifications with premium pricing.
Plastic dominates unit economics for volume production while aluminum captures expanding specification share in performance-intensive segments.
Power Rating:
Power segmentation tracks the efficiency tier migration reshaping motor technology roadmaps across regulatory jurisdictions.
- Medium Power:Configurations between 1 and 5 horsepower serve the broadest cross-section of industrial and commercial applications. China's GB 18613-2020 motor efficiency tiers are disqualifying IE2 induction platforms from government procurement, redirecting tenders toward IE4 and IE5 premium efficiency categories in this bracket.
- High Power:Systems exceeding 5 horsepower integrate permanent magnet synchronous motors with variable frequency drives. These displace legacy wound-rotor designs by eliminating slip losses and enabling precise airflow modulation without external VFD cabinets in chiller plant upgrades.
- Low Power:Sub-1 horsepower units address residential and light commercial ventilation with cost-constrained specifications.
- Ultra High Power:Configurations above 15 horsepower serve heavy industrial processes and large-scale HVAC infrastructure.
Medium power ratings constitute the revenue core while high power segments expand most quickly as facility energy managers prioritize total cost of ownership models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium centrifugal configurations command 40% price premiums in Germany versus comparable axial units in China, reflecting divergent specification authority between precision industrial corridors and volume-driven manufacturing zones.
United States
Hyperscale data center construction in Virginia and Texas drives specification pull for electronically commutated platforms with variable airflow capability. EPA Fan Efficiency Rating mandates are phasing out single-phase induction motors in commercial buildings. Northern Virginia's Data Center Alley anchors North American demand as operators abandon traditional air-cooled architectures above 50 kilowatts per cabinet.
Germany
Automotive battery testing facilities in the industrial automation corridor demand centrifugal configurations maintaining ±0.5°C uniformity across 300mm+ impeller spans. REACH substance restrictions and RoHS compliance obligations filter material choices for blade coatings and winding insulation. Stuttgart and Munich precision engineering clusters concentrate specification authority for cleanroom-certified aluminum impeller assemblies.
China
GB 18613-2020 motor efficiency tiers are disqualifying IE2 induction platforms from government procurement catalogs, redirecting state-backed infrastructure tenders toward IE4 and IE5 premium efficiency categories. Dual carbon goals accelerate demand for high-efficiency axial and centrifugal platforms. Jiangsu and Zhejiang province manufacturers are retooling stator winding lines to capture mandated upgrade cycles in municipal wastewater treatment applications.
India
Production-linked incentives for semiconductor packaging facilities in Telangana and Gujarat are attracting greenfield data center investments, creating first-mover advantage for localized cooling component suppliers. BIS efficiency standards are tightening compliance requirements for imported motor platforms. Bengaluru and Hyderabad technology corridors concentrate demand for medium-power configurations serving continuous-duty industrial environments.
Japan
METI efficiency guidelines and JIS standards are reshaping product roadmaps for brushless DC motor platforms in industrial automation applications. Permanent magnet synchronous motors with integrated variable frequency drives are displacing traditional AC induction platforms in precision manufacturing. Nagoya and Osaka industrial clusters anchor demand for high-reliability configurations in continuous-duty metal forming and material handling processes.
Above 300mm Cooling Fans Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with German engineering houses dominating premium centrifugal designs while Asian electronics conglomerates anchor volume production through backward integration into driver IC and magnet manufacturing. The vendor base organizes around three strategic archetypes: precision engineering specialists with cleanroom certification capabilities, scale-driven axial platform manufacturers serving hyperscale data centers, and vertically integrated motor houses controlling upstream magnet and winding supply. Consolidation pressure is intensifying through capacity expansion in India's PLI corridors and strategic partnerships targeting EU F-Gas regulation compliance.
Among the precision engineering tier, ebm-papst and Ziehl-Abegg occupy positions anchored by German manufacturing heritage and regulatory certification depth. Delta Electronics and Nidec Corporation exemplify the scale-driven archetype, with the former representing Asia-Pacific supply chain integration and the latter anchoring axial platform volumes for hyperscale operators. Sunonwealth Electric Machine Industry sits within the mid-tier specialist category, reflecting Taiwanese electronics manufacturing ecosystem positioning.
| Leading Market Players |
|---|
| Delta Electronics |
| ebm-papst |
| Nidec Corporation |
| Sunonwealth Electric Machine Industry |
| Sanyo Denki |
| Asia Vital Components |
| NMB Technologies Corporation |
| MinebeaMitsumi |
| Ziehl-Abegg |
| Others |
Pricing and Supply Chain Analysis
ISO 14644-1 Class 5 cleanroom certification gates both supplier qualification and centrifugal fan price premiums simultaneously, compressing margins for uncertified aluminum impeller assemblies while rewarding German engineering houses with 40% pricing power over Chinese axial volume producers.
Pricing Analysis
Configured-to-order centrifugal platforms for automotive battery testing facilities command substantial premiums over standard axial units for data center HVAC. Three-tier pricing structure across premium certified, standard industrial, and economy HVAC levels reflects certification depth and magnet mass. Cost compression in economy axial tiers is intensifying because neodymium price volatility feeds through brushless DC motor bills of materials. Data center operators exhibit lowest price sensitivity, prioritizing static pressure curves and 10-year total cost of ownership over first-cost procurement.
Supply Chain Analysis
China and Taiwan anchor stator winding and driver IC fabrication for brushless DC motor platforms serving volume electronics cooling applications. Jiangsu province manufacturers draw from captive magnet supply chains while Taiwan-based producers rest on backward integration into semiconductor components. Single-source vulnerability concentrates in rare earth magnet processing, where Chinese export quota policies create input cost volatility. Distribution runs through direct OEM supply agreements for hyperscale data center operators and industrial distributor networks for HVAC retrofit contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The above 300mm cooling fans market sits in early-cycle recovery as AI server density investments reactivate capital expenditure programs deferred during efficiency mandate compliance periods.
For Market Incumbents: Consolidate certification capabilities and magnet supply security against liquid cooling substitution threats in AI training clusters above 100 kilowatts per rack. Deepen backward integration into driver IC manufacturing to defend margin position against Taiwanese electronics conglomerates. Prioritize ISO 14644-1 Class 5 validation capacity expansion in Germany's automotive battery testing corridor where specification authority concentrates. For New Entrants and Emerging Players: India's PLI scheme for semiconductor packaging facilities offers certification fast-track pathways for localized cooling component suppliers targeting Telangana and Gujarat greenfield data centers. Penetrate the medium-power IE4 motor efficiency tier where China's GB 18613-2020 disqualification of IE2 platforms creates specification whitespace. Pursue joint venture structures with established winding houses to bypass technician scarcity bottlenecks. For Investors and Strategic Acquirers: EPA Fan Efficiency Rating mandates reshape the acquisition landscape toward electronically commutated platform specialists with variable airflow IP. Five-to-ten year viability favors precision engineering houses with cleanroom certification depth over commodity axial assemblers. Monitor hyperscale data center construction permits in Virginia and Texas as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Certification Expansion | ISO 14644-1 Class 5 validation unlocks aerospace and pharmaceutical contracts with 14-18 month revenue recognition timelines. |
| Magnet Supply Security Programs | Neodymium procurement hedging insulates margins against Chinese export quota volatility in premium centrifugal platforms. |
| Digital Twin Integration | CFD-IoT convergence enables predictive blade fatigue modeling and recurring software revenue alongside hardware sales. |
| India PLI Localization | Telangana and Gujarat manufacturing footprint captures semiconductor packaging facility cooling demand with import substitution advantages. |
| IE4/IE5 Motor Platform Retooling | GB 18613-2020 compliance positions suppliers for Chinese state-backed infrastructure tenders in municipal wastewater treatment. |
Research Methodology
A standing panel of thermal management engineers, data center facility managers, HVAC procurement directors, and motor winding technicians provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation against EPA FER compliance databases, GB 18613-2020 procurement catalogs, and hyperscaler capital expenditure disclosures. Bottom-up unit shipment estimates triangulated against top-down energy efficiency mandate penetration models.
Consistency checks validated volume and value outputs against chiller plant upgrade cycles, AI server rack density trajectories, and automotive battery testing facility construction permits. Segmentation dimensions modeled include impeller geometry, end-use application, material platform, power rating, and regional regulatory cluster. CAGRs derived from installed base replacement cycles and efficiency tier upgrade elasticity. Forecast inputs incorporated neodymium price volatility scenarios and cleanroom certification queue lengths.
Decision-makers should treat outputs as directional under assumptions of continued AI infrastructure investment and stable rare earth export policy; material deviation in either driver would warrant model refresh. Recalibration cycles align with material shifts in EPA enforcement patterns, GB standard revisions, and hyperscale data center construction permitting velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Soldering Iron Market
Industrial Equipment
Air Bearing Spindle Market
Industrial Equipment
Industrial Lasers Systems Market
Industrial Equipment
Global Dicing Blades Market
Industrial Equipment
Electronic Beam Machining Market
Industrial Equipment
Global DC Drives Market
Industrial Equipment
Industrial Vacuum Evaporation Systems Market
Industrial Equipment
South America Fans and Blowers Market
Industrial Equipment
Linear Transfer System Market
Industrial Equipment
Global Laboratory Vacuum Pumps Market
Industrial Equipment
TIG Torch Market
Industrial Equipment
Global Electro Hydraulic Servo Valve Market
Industrial Equipment
Global Special Purpose Machines Market
Industrial Equipment
Fume Extractor Market
Industrial Equipment
Servo Drive Market
Industrial Equipment
Equipment Cases Market