
 Roll Slitting Machines Market | 2026-2036
Roll Slitting Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Roll Slitting Machines Market Intelligence
CE marking under the EU Machinery Directive is reorganizing competitive access for European-bound equipment. Windmöller & Hölscher leverages its German engineering heritage to dominate high-speed film slitting lines. Atlas Converting Equipment anchors the UK market with specialized duplex slitter-rewinder configurations. CMC Converting Machinery Cevenini Srl competes through narrow-web precision systems for label stock applications.
Roll slitting machines cut master rolls of flexible materials into narrower strips using rotary knives or shear blades, with web tensions typically controlled between 50 and 500 N/m depending on substrate gauge. These systems serve primary converting operations across packaging, electronics, and automotive supply chains where precise width tolerance prevents downstream lamination defects. Mechanical slitters still occupy the largest installed base due to lower capital requirements and simpler maintenance protocols, though automatic operation modes are capturing replacement cycles as labor costs rise and throughput targets tighten. Film and plastic substrates represent the fastest-growing material category, driven by flexible packaging substitution for rigid containers in food and pharmaceutical distribution.
FDA regulations on food-contact substrate purity directly influence slitter design for US packaging converters, requiring smooth blade surfaces that eliminate contamination risk from metallic debris. OSHA machine guarding standards mandate two-hand actuation and light-curtain enclosures on manual and semi-automatic units sold into American manufacturing facilities. ISO 9001 quality management certification has become a baseline qualifier for OEM procurement teams evaluating European and Asian equipment suppliers. Stakeholders must weigh total cost of ownership against automation depth as substrate portfolios diversify and batch sizes shrink.
Market Dynamics
CE marking mandates under the EU Machinery Directive are compressing equipment replacement cycles as converters accelerate upgrades to avoid compliance gaps in cross-border sales.
Growth Catalysts
- Food-grade film specifications:Asia-Pacific flexible packaging converters are expanding slitting capacity to meet pharmaceutical and food-contact purity standards. FDA regulations on substrate contamination risk drive blade surface engineering investments.
- OSHA machine guarding standards:US manufacturing facilities now require two-hand actuation and light-curtain enclosures on manual units. This regulatory pull is accelerating replacement of unguarded legacy installations.
- Shear blade automation:Rotary knife systems with automatic knife positioning are capturing share from mechanical slitters as labor costs rise and width tolerance requirements tighten below 0.1 millimeter.
Market Restraints
- Alloy steel price volatility:Tungsten carbide blade material costs fluctuate with mining supply from China and Russia. Converters face margin compression when raw material spikes coincide with fixed equipment contracts.
- Technical service scarcity:Skilled technicians for tension control calibration and vibration analysis are concentrated in Germany, Italy, and Japan. Remote facilities face extended downtime during blade alignment failures.
- Electronics substrate substitution:Direct-to-substrate digital printing is reducing master roll consumption for label stock in North American and European commercial print segments.
Strategic Opportunities
- Battery separator film slitting:Lithium-ion cell manufacturers in South Korea and China require ultra-clean slitting environments for ceramic-coated polyolefin separators. This application commands premium pricing against packaging norms.
- India PLI scheme for packaging machinery:Domestic production incentives are creating localized assembly opportunities for mid-speed duplex slitter-rewinders serving South Asian flexible packaging growth.
- Remote diagnostics convergence:Integration of IoT vibration sensors with predictive maintenance software enables aftermarket service contracts that extend OEM revenue beyond initial equipment sales.
Industry Challenges
- ISO 9001 certification timelines:European OEM procurement teams require documented quality management systems. Asian suppliers face 12-18 month accreditation delays that exclude them from tier-one converter vendor lists.
- Legacy tension control integration:Automated slitter-rewinders must interface with existing unwind stands and downstream laminators. Proprietary fieldbus protocols from 1990s-era equipment create commissioning friction and cost overruns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roll Slitting Machines Market |
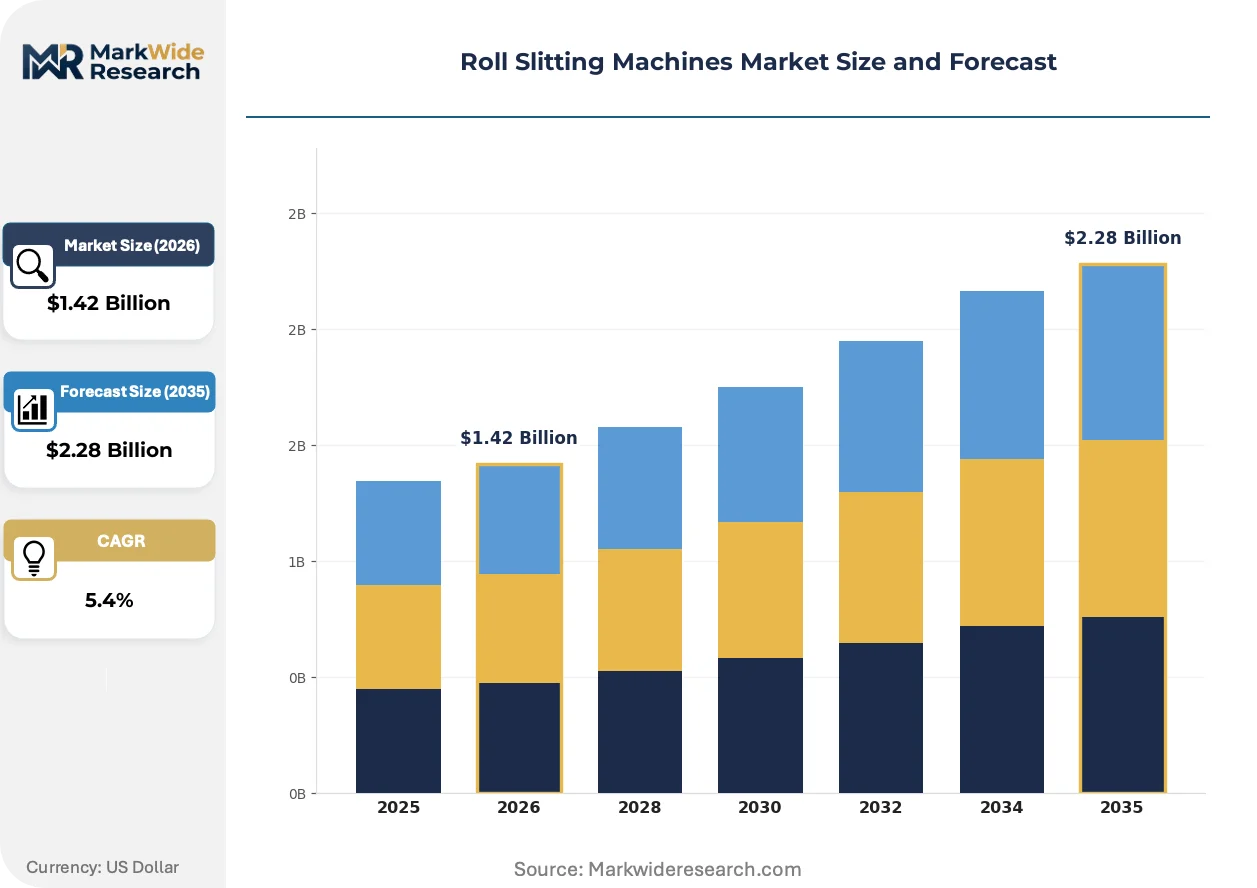
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Slitters, Electrical Slitters, Hydraulic Slitters, Pneumatic Slitters Material: Metal, Plastic, Paper, Film End User: Packaging, Textile, Automotive, Electronics Operation Mode: Automatic, Semi-Automatic, Manual, Custom |
| Companies Covered | ALS, CMC Converting Machinery Cevenini Srl, Ghezzi & Annoni, Windmöller & Hölscher, Rosenthal Manufacturing, Oteman, ASHE Converting Equipment, Atlas Converting Equipment, Comexi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roll Slitting Machines Market Strategic Shifts & Innovations
Digital blade positioning systems and contamination-control architectures are redefining equipment specifications across pharmaceutical and battery material applications.
Electromechanical knife positioning is fragmenting the traditional pneumatic actuator installed base. High-precision servo motors now enable real-time blade gap adjustment during production runs. Pharmaceutical converters in Switzerland and Germany are adopting these systems to eliminate manual setup downtime between narrow-batch jobs.
EU machinery safety directives now mandate interlocked guarding systems with category 3 safety PLCs for all new slitting equipment sold into member states. This regulatory compression is forcing redesign of legacy manual feed stations. UK and Italian OEMs are integrating laser scanner enclosures to preempt enforcement variance across national market surveillance authorities.
Converter procurement teams are unbundling after-sales service from initial equipment purchases. Third-party blade regrinding specialists and independent vibration analysts are capturing maintenance contracts that OEMs previously held captive. This disintermediation is most advanced in China's coastal manufacturing provinces where vertical film producers operate dense clusters of identical slitting lines.
Roll Slitting Machines Market Segmentation
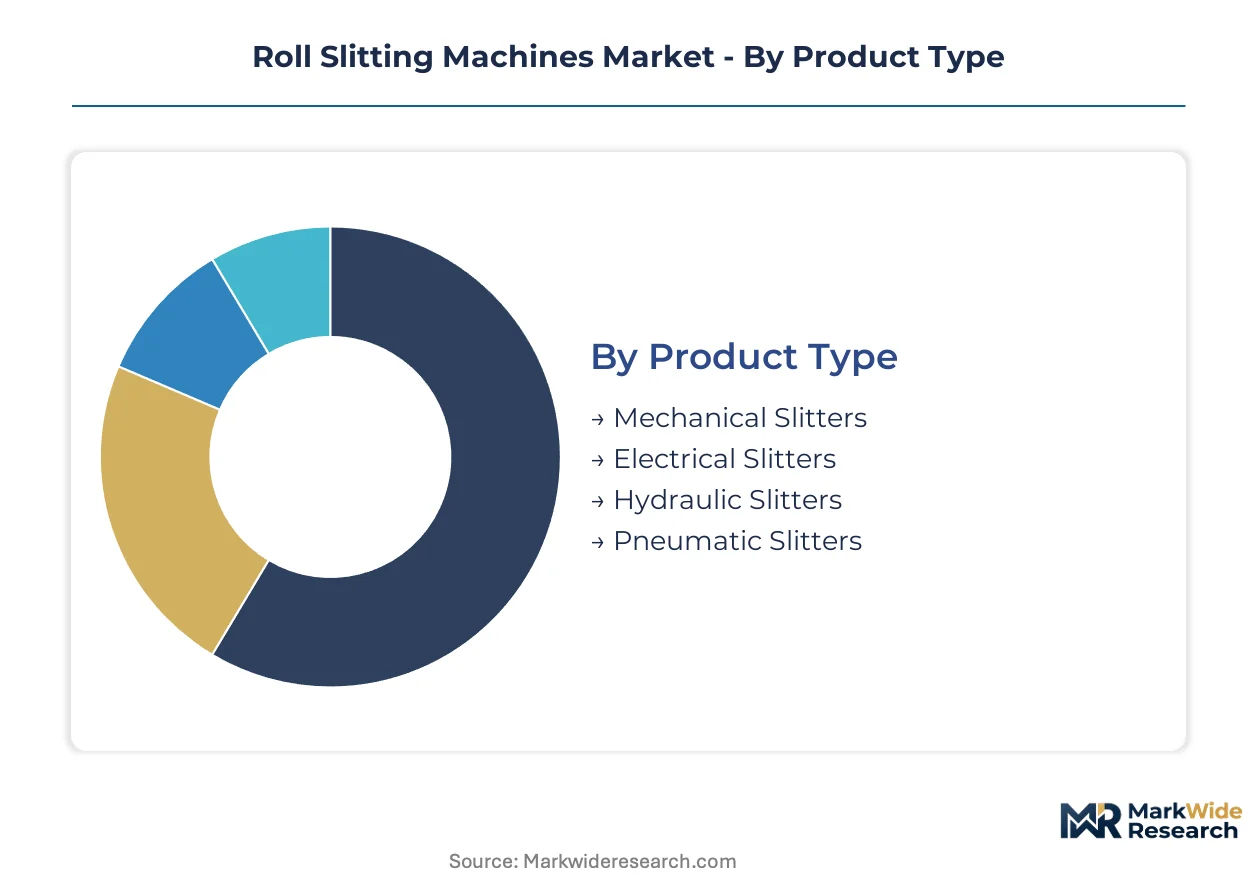
Roll slitting machine procurement channels diverge sharply by automation depth and material handling requirements. OEMs configure distribution strategies around converter capital cycles, with high-speed film lines flowing through direct technical sales while standard mechanical units move through regional equipment dealers.
Product Type:
Mechanical and electrical systems dominate channel volume through diverging sales architectures—mechanical units flow through distributor networks serving price-sensitive converters, while electrical platforms require factory-direct commissioning support.
- Mechanical Slitters:Rotary knife assemblies with manual blade positioning serve installed base replacement cycles in emerging manufacturing clusters. Demand concentrates in India's Gujarat and Maharashtra states where packaging SMEs prioritize capital efficiency over automation depth. Labor availability and lower throughput requirements sustain this segment's channel presence.
- Electrical Slitters:Servo-driven knife positioning systems enable real-time gap adjustment during production runs. Pharmaceutical converters in Switzerland and Germany specify these platforms to eliminate batch-to-batch setup downtime. FDA contamination-risk protocols drive blade surface engineering investments in US-bound configurations.
- Hydraulic Slitters:High-torque cutting heads process thick-gauge metal substrates for automotive gasket production.
- Pneumatic Slitters:Compressed-air actuation remains prevalent in legacy textile converting facilities across Turkey and Vietnam.
By volume, mechanical slitters lead. By expansion trajectory, electrical platforms are climbing the fastest.
Material:
Cost tier stratification separates commodity substrate handling from precision film applications requiring contamination control architectures.
- Film:Ceramic-coated polyolefin separators for lithium-ion batteries demand ultra-clean slitting environments with HEPA filtration and electrostatic dissipation. South Korean and Chinese cell manufacturers command premium pricing against packaging norms. METI cleanroom standards in Japan constrain supplier qualification to a narrow OEM tier.
- Plastic:Flexible food-grade specifications drive blade surface engineering investments across Asia-Pacific coastal provinces. FDA substrate purity regulations directly influence slitter design for US converters, requiring smooth blade finishes that eliminate metallic debris risk.
- Paper:Label stock applications face demand pressure from direct-to-substrate digital printing in North American commercial print.
- Metal:Alloy steel price volatility from Chinese and Russian mining supply creates margin compression for gasket and shielding tape producers.
Film commands the steepest value per installed meter. Plastic handles the widest volume base across converting operations.
End User:
Application maturity determines automation penetration, with packaging leading installed base and electronics driving specification intensity.
- Packaging:Flexible film converters in China's Shandong and Zhejiang provinces operate dense clusters of identical slitting lines. CE marking mandates under EU Machinery Directive compress replacement cycles as exporters accelerate upgrades to avoid compliance gaps in cross-border sales.
- Electronics:Battery separator film slitting requires vibration analysis capabilities and tension control calibration expertise concentrated in Germany, Italy, and Japan. Remote facilities face extended downtime during blade alignment failures.
- Automotive:Gasket and acoustic damping material producers specify hydraulic platforms for thick-gauge processing.
- Textile:Narrow-web precision systems serve label and ribbon applications with lower automation requirements.
Packaging holds the broadest installed footprint. Electronics exhibits the most rapid specification escalation.
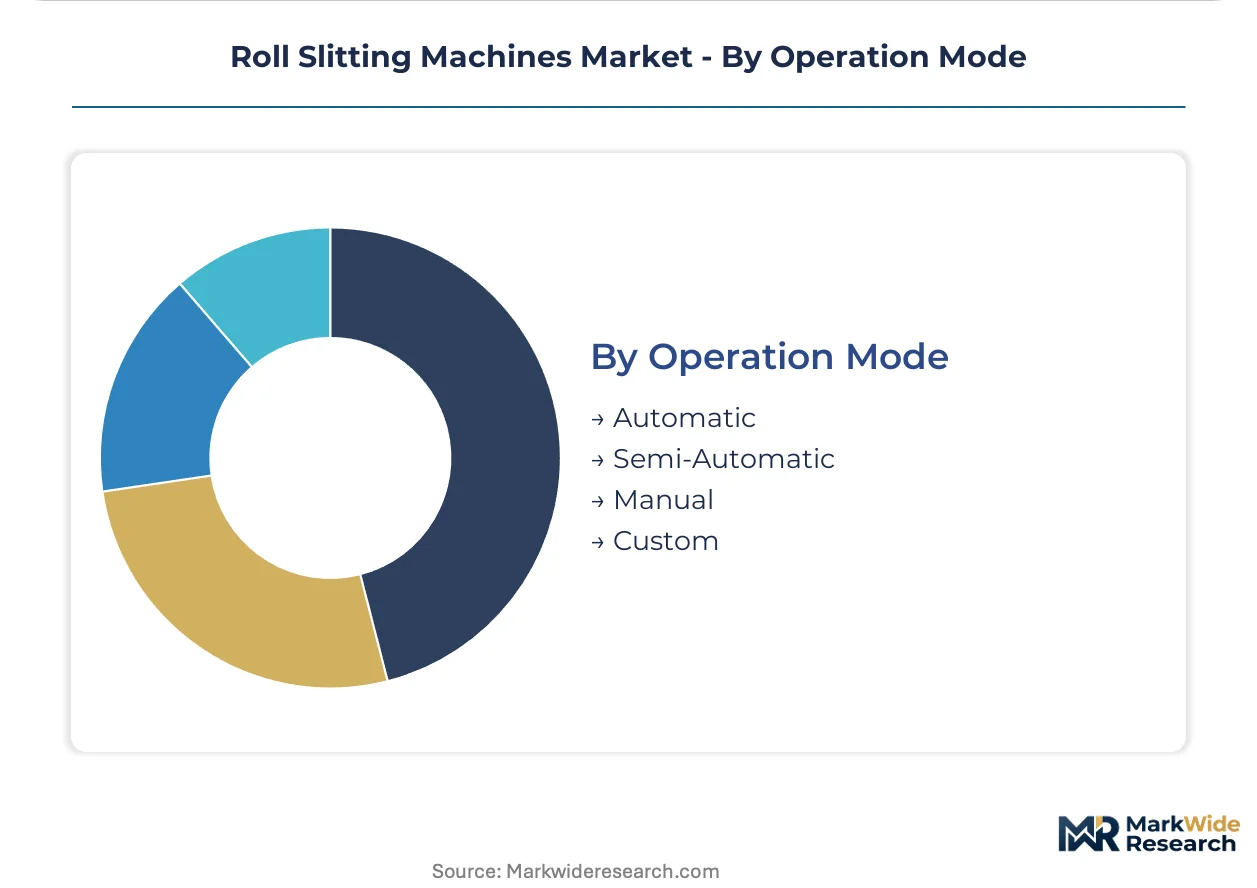
Operation Mode:
Customer type and batch size distribution determine automation tier selection across converter capital planning cycles.
- Automatic:Continuous production environments with fixed width portfolios justify servo-driven knife positioning and integrated tension control. OSHA machine guarding standards mandate two-hand actuation and light-curtain enclosures on US-bound units, accelerating replacement of unguarded legacy installations.
- Semi-Automatic:Mid-volume converters balance labor cost escalation against batch flexibility requirements. India's PLI scheme for packaging machinery creates localized assembly opportunities for this tier serving South Asian growth.
- Manual:Job shops and prototype converters maintain mechanical platforms for narrow-batch flexibility.
- Custom:Specialty substrate producers require modified unwind stands and proprietary fieldbus protocol integration.
Automatic systems capture the majority of new capital expenditure. Semi-automatic configurations retain share in cost-sensitive emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for packaging machinery is accelerating localized assembly investments across South Asian flexible packaging corridors. Germany's CE marking mandates under the EU Machinery Directive compress equipment replacement cycles as exporters upgrade to maintain cross-border sales access.
China
Coastal manufacturing provinces in Shandong and Zhejiang host dense clusters of vertical film producers expanding slitting capacity for food-grade specifications. MIIT cleanroom standards constrain supplier qualification for battery separator applications. Ningbo and Qingdao anchor the dominant equipment procurement zones for lithium-ion cell manufacturers.
Germany
Precision engineering heritage sustains demand for high-speed film slitting lines serving pharmaceutical converters. CE marking mandates under the EU Machinery Directive force redesign of legacy manual feed stations. Bavaria and Baden-Württemberg concentrate the technical service expertise for tension control calibration.
United States
OSHA machine guarding standards mandate two-hand actuation and light-curtain enclosures on manual and semi-automatic units. FDA regulations on food-contact substrate purity drive blade surface engineering investments. Midwest packaging converters in Illinois and Ohio accelerate replacement of unguarded legacy installations.
India
The PLI scheme for packaging machinery creates localized assembly opportunities for mid-speed duplex slitter-rewinders. FSSAI food-grade specifications push blade surface investments across Gujarat and Maharashtra packaging SMEs. Ahmedabad and Mumbai anchor the capital expenditure flows for emerging flexible film converters.
South Korea
Lithium-ion cell manufacturers require ultra-clean slitting environments for ceramic-coated polyolefin separators. MFDS pharmaceutical regulations extend contamination-control architectures to medical film applications. Gyeonggi-do and Busan-Ulsan regions command premium pricing against packaging equipment norms.
Roll Slitting Machines Market Key Industry Players
Listed leaders compete with private specialists across automation depth and geographic reach. The vendor base organizes into three functional tiers: German engineering houses dominating high-precision pharmaceutical lines, Italian narrow-web specialists serving label stock applications, and Asian fabricators capturing cost-sensitive mechanical slitter replacement cycles. Consolidation pressure intensifies as CE marking compliance costs favor scaled R&D investment. Strategic moves concentrate on M&A for tension control IP and capacity expansion in India's PLI-subsidized zones.
Within the premium-tier vector, Windmöller & Hölscher GmbH exemplifies German engineering heritage positioning for high-speed pharmaceutical and battery film applications. Atlas Converting Equipment anchors UK-based specialization in duplex slitter-rewinder configurations. CMC Converting Machinery Cevenini Srl occupies the narrow-web precision tier for label stock and specialty converting segments.
| Leading Market Players |
|---|
| ALS |
| CMC Converting Machinery Cevenini Srl |
| Ghezzi & Annoni |
| Windmöller & Hölscher |
| Rosenthal Manufacturing |
| Oteman |
| ASHE Converting Equipment |
| Atlas Converting Equipment |
| Comexi |
| Others |
Cost & Logistics Intelligence
Fourteen-to-eighteen-week lead times for tungsten carbide blade assemblies from German and Japanese suppliers concentrate pricing power with OEMs holding captive forging relationships, while inventory carrying costs for alloy steel stock force mid-tier fabricators toward spot-market exposure.
Pricing Analysis
Certification level creates the primary spread between equipment tiers, with CE-marked and FDA-compliant configurations commanding substantial premia over uncertified mechanical units. Three-tier pricing structure across premium servo-driven systems, standard semi-automatic platforms, and economy mechanical slitters reflects automation depth and compliance investment. Pricing pressure stems from alloy steel cost volatility originating in Chinese and Russian mining supply, compressing margins for fixed-contract equipment vendors. Small and mid-size packaging converters in India's Gujarat and Maharashtra states exhibit the highest price sensitivity, while pharmaceutical and battery film producers prioritize contamination-control specifications over unit cost.
Supply Chain Analysis
Inventory concentration for precision tension control components and servo motor assemblies rests on suppliers in Germany, Japan, and Italy, creating extended lead time exposure for remote facilities. Tungsten carbide blade material, HEPA filtration systems, and category 3 safety PLC modules constitute critical input dependencies. Single-source vulnerability in ceramic-coated polyolefin separator film supply for battery applications generates qualification bottlenecks for South Korean and Chinese cell manufacturers. Distribution runs through factory-direct technical sales for high-speed pharmaceutical lines and regional equipment dealer networks for standard mechanical units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized calibration expertise for tension control systems and vibration analysis remains concentrated in Bavaria, Baden-Württemberg, and select Japanese industrial zones, constraining expansion velocity for converters lacking proximity to technical service hubs.
For Market Incumbents: Secure captive blade regrinding capabilities and predictive maintenance software IP to offset third-party service disintermediation threatening aftermarket revenue streams. Backward integration into tungsten carbide supply relationships mitigates raw material volatility exposure from Chinese and Russian mining sources. Capacity expansion in India's PLI-subsidized zones captures emerging flexible packaging demand while CE marking compliance investments defend European market access. For New Entrants and Emerging Players: ISO 9001 fast-track accreditation programs unlock tier-one OEM procurement lists currently closed to Asian suppliers facing 12-18 month certification delays. India's packaging machinery PLI scheme offers the most penetrable entry point for mid-speed duplex slitter-rewinder assembly. Target battery separator film applications in South Korea and China where ultra-clean specifications command premium pricing against packaging norms and technical service scarcity limits incumbent coverage. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized converting equipment divisions lacking dedicated pharmaceutical or battery film focus. Long-term viability hinges on automation IP depth and installed base density enabling aftermarket service contract conversion. Watch for inflection when remote diagnostics penetration crosses threshold sufficient to support predictive maintenance subscription models at scale.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Compliance Investment | EU Machinery Directive mandates force redesign of legacy manual feed stations to maintain cross-border sales access. |
| Battery Separator Film Capability Buildout | Lithium-ion cell manufacturers in South Korea and China require ultra-clean slitting environments with HEPA filtration. |
| Remote Diagnostics Platform Integration | IoT vibration sensors with predictive maintenance software extend OEM revenue beyond initial equipment sales. |
| India PLI Zone Capacity Expansion | Domestic production incentives create localized assembly opportunities for mid-speed duplex slitter-rewinders. |
| Backward Integration into Blade Material Supply | Tungsten carbide sourcing relationships mitigate margin compression from Chinese and Russian mining volatility. |
Research Approach
A spread of perspectives from plant engineers at flexible packaging converters, OEM procurement teams, aftermarket service technicians, and regulatory compliance officers converged on the working assumptions underlying equipment demand forecasts. Primary fieldwork combined structured interviews with maintenance directors and tension control specialists across Germany, Italy, China, and India with secondary validation from EU Machinery Directive implementation records, FDA food-contact substrate guidance documents, and MIIT cleanroom standard filings. Bottom-up triangulation of installed base replacement cycles and top-down cross-check against capital expenditure flows in coastal Chinese manufacturing provinces anchored volume estimates.
Segmentation dimensions modeled span automation mode, substrate material category, end-use application, and regional regulatory cluster across the projection horizon. CAGRs derive from equipment shipment trajectories weighted by average selling price evolution and aftermarket service contract attach rates. Forecast inputs incorporate battery separator film capacity buildout schedules in South Korea and China, PLI scheme disbursement timelines in India, and CE marking enforcement variance across EU national market surveillance authorities.
Decision-makers should treat outputs as directional under assumptions of sustained alloy steel supply continuity and stable regulatory enforcement intensity; material deviation in tungsten carbide sourcing or Machinery Directive interpretation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Industrial Static Equipment Market
Material Handling Equipment
Heavy Loader Market
Material Handling Equipment
Die Casting Market
Material Handling Equipment
Pharmaceutical Material Handling Equipment Market
Material Handling Equipment
Loading Platform Canopies Market
Material Handling Equipment
Rubber Tired Gantry (RTG) Crane Market
Material Handling Equipment
Portable Forklift Ramps Market
Material Handling Equipment
Slag Handling Machine Market
Material Handling Equipment
Crate Handling Systems Market
Material Handling Equipment
Mobile Conveyor Market
Material Handling Equipment
Light Duty Telehandler Market
Material Handling Equipment
Industrial Bag Dust Filter Market
Material Handling Equipment
Global Bucket Loader Market
Material Handling Equipment
Middle East and Africa Conveyors Market
Material Handling Equipment
US and Mexico Metal Stamping Market
Material Handling Equipment
Industrial Mezzanines Market