
 Multi Wire Cutting Machine Market | 2026-2036
Multi Wire Cutting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Multi Wire Cutting Machine Market Insights
Skilled wire saw technicians is rotating from stone processing into electronics substrate cutting, creating labor scarcity in traditional quarrying hubs while unlocking precision manufacturing capacity. Fujian Province Hualong Machinery leverages its granite-cutting heritage to compete in emerging silicon wafer applications. Breton S.p.A anchors European demand through its CNC-controlled architectural stone systems. Simec Macchine Industriali dominates Italian quarry equipment exports with specialized multi-wire configurations.
Multi wire cutting machines deploy multiple parallel abrasive or diamond-impregnated wires to slice hard materials simultaneously, achieving kerf widths below 0.35 millimeters at feed rates governed by workpiece hardness and wire tension. The equipment serves primary industrial purposes in dimensional stone block squaring, semiconductor ingot wafering, and precision ceramic sectioning. CNC Controlled machine types capture the dominant margin pool as electronics OEMs demand programmable tension and speed parameters for brittle material processing. Laser Assisted technology leads growth trajectories where thermal-softening reduces wire wear on superhard ceramics. Metal Fabrication applications sustain mature replacement cycles while Aerospace Component Cutting generates premium pricing through AS9100-certified precision requirements.
China's MIIT enforces GB standards for machine tool safety and electromagnetic compatibility, conditioning market access for imported and domestic equipment alike. The EU Machinery Directive and CE marking mandate emergency stop integration and noise emission controls that shape European product development priorities. ISO 230 standards for machine tool accuracy testing create baseline certification thresholds for international competitive bidding. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's embodied carbon tracking reshape wire consumption metrics and equipment lifecycle accounting.
Market Dynamics
Precision electronics manufacturing is compressing wire saw tolerances below 0.25 millimeters, forcing equipment suppliers to reengineer tension control systems and abandon legacy granite-cutting architectures. This technical escalation is redistributing competitive advantage toward firms with integrated CNC and materials science capabilities.
Growth Catalysts
- Semiconductor substrate expansion:Silicon carbide wafering for electric vehicle power electronics requires multi-wire systems capable of slicing ultra-hard ceramics without thermal damage. Electronics OEMs in East Asia are qualifying domestic equipment for 200mm wafer production.
- MIIT equipment localization mandates:China's GB standards for machine tool safety and electromagnetic compatibility are conditioning procurement toward certified domestic suppliers. Fujian Province machinery clusters are capturing redirected public and private capital.
- Laser-assisted wire technology:Thermal softening of superhard ceramics reduces diamond wire consumption and extends cutting cycles. Japanese and Korean ceramics processors are piloting hybrid thermal-mechanical systems for aerospace component sectioning.
Market Restraints
- Diamond wire cost volatility:Synthetic diamond supply concentrates in Henan Province and limited Ukrainian deposits. Price swings in abrasive materials compress margins for stone processing operators running high-wire-count configurations.
- Technical limitation in thin-wafer handling:Kerf widths below 0.20 millimeters induce crack propagation in brittle III-V semiconductors. Equipment makers lack validated process windows for gallium nitride ingots exceeding 150mm diameter.
- EU Machinery Directive compliance friction:CE marking mandates for emergency stop integration and noise emission controls extend product development timelines. European architectural stone equipment faces certification bottlenecks when adapting designs for electronics applications.
Strategic Opportunities
- Underpenetrated aerospace component cutting:AS9100-certified precision requirements generate premium pricing for wire saw systems capable of titanium aluminide sectioning. US and French aerospace subcontractors are consolidating supplier qualification lists.
- Technology convergence of AI-driven predictive maintenance:Machine learning models trained on wire tension and vibration data enable preemptive replacement scheduling. German and Japanese equipment makers are bundling sensor packages with service contracts.
- India's PLI scheme for advanced manufacturing:Production-linked incentives for semiconductor and solar equipment are attracting wire saw technology transfers. Gujarat and Tamil Nadu industrial corridors are emerging as qualification sites for imported and licensed domestic systems.
Industry Challenges
- Wire saw technician scarcity:Skilled operators are rotating from stone quarries into electronics substrate facilities. Traditional granite-cutting hubs in Fujian and Carrara face labor attrition while semiconductor fabs compete for the same talent pool.
- ISO 230 accuracy certification timelines:Machine tool testing protocols require extended validation cycles for CNC-controlled tension and speed parameters. Equipment suppliers face order-to-delivery stretches that strain customer project schedules.
- Integration complexity with legacy fab automation:Multi-wire systems must interface with existing MES and SCADA architectures. Semiconductor OEMs demand custom protocol bridges that extend commissioning periods and inflate engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi Wire Cutting Machine Market |
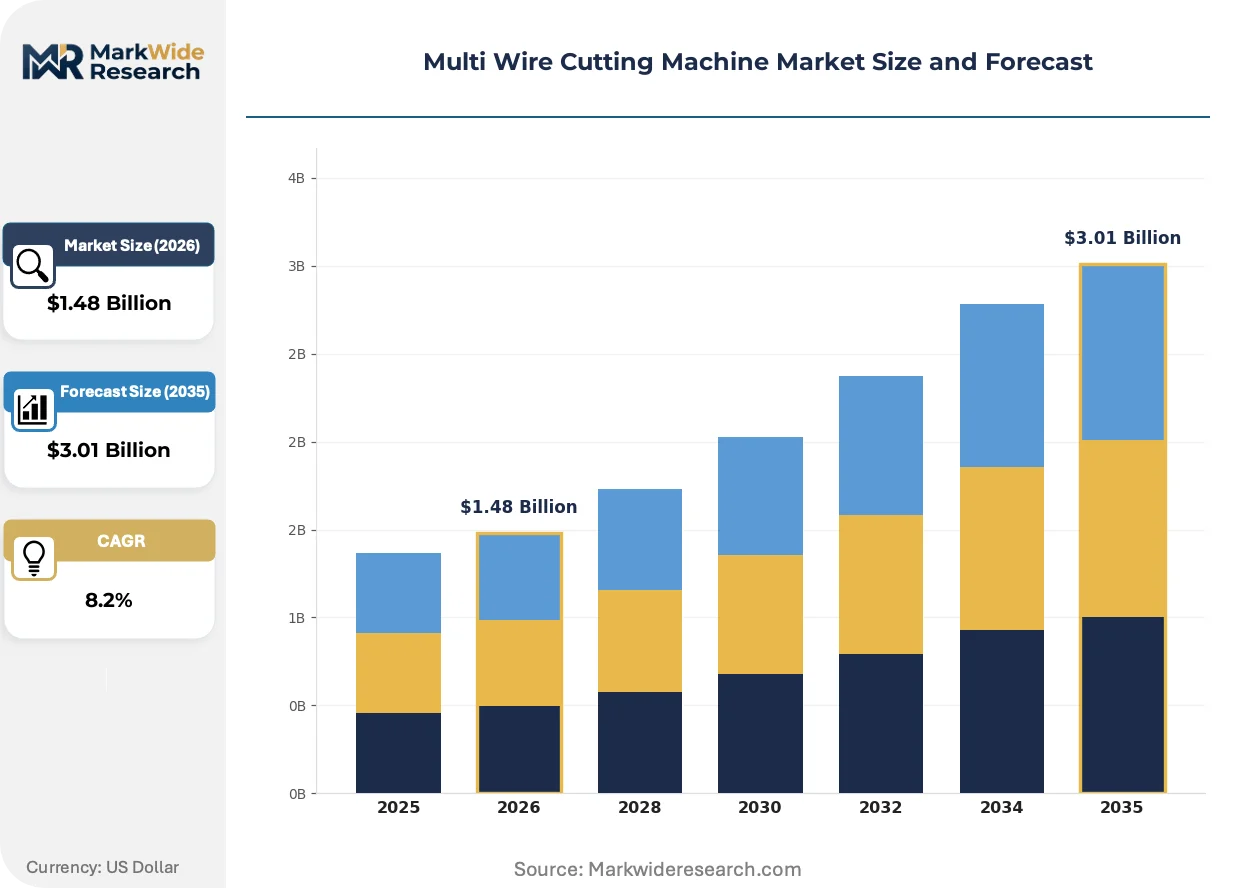
| Market Size in 2026 | $1.48 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Machine Type: High-Speed, Precision, CNC Controlled, Semi-Automatic, Fully Automatic Technology: Laser Assisted, Water Jet, Electrical Discharge, Plasma, Ultrasonic Application: Metal Fabrication, Electronics Manufacturing, Aerospace Component Cutting, Jewelry Production, Tool Manufacturing End User Industry: Metalworking Workshops, Electronics OEMs, Aerospace Engineering Firms, Jewelry Artisans, Precision Toolmakers |
| Companies Covered | Simec Macchine Industriali, Park Industries, Fujian Province Hualong Machinery, Fujian Xiapu Zhongyuan Machinery, Xiamen Qicheng Superhard Material, Breton S.p.A, Fujian Skystone Technology, Dinosaw Machine, Dalian Heida Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi Wire Cutting Machine Market Trends and Innovations
Active materials research and regulatory pressure on embodied carbon are reshaping how wire saw equipment is specified, operated, and retired. Suppliers are repositioning around energy efficiency metrics and circular material flows.
Diamond-impregnated wire with engineered grain distribution is supplanting traditional slurry-based cutting in silicon wafer production. Solar ingot processors in Southeast Asia are adopting fixed-abrasive technology to reduce kerf loss and improve yield rates. This transition is compressing demand for loose abrasive consumables while elevating capital intensity for wire inventory management.
China's dual carbon goals and the EU Green Deal's embodied carbon tracking are forcing lifecycle accounting into equipment procurement criteria. Wire consumption metrics per square meter of processed material now factor into total cost of ownership calculations. Stone processing operators in Italy and Spain are piloting carbon-footprint labeling for dimensional block exports.
Electronics OEMs are consolidating vendor relationships around integrated solution providers capable of process development support. Single-source contracting for wire, equipment, and technical service is displacing fragmented procurement across separate consumable and capital equipment channels. This concentration is most visible in Taiwan and South Korea, where semiconductor foundries are reducing qualified supplier lists to three or fewer per technology node.
Multi Wire Cutting Machine Market Segmentation
Multi wire cutting machine procurement patterns diverge sharply across automation levels and precision tiers. Electronics OEMs prioritize programmable CNC architectures while stone processors favor semi-automatic configurations for cost control. Technology selection tracks material hardness requirements, with thermal and mechanical methods competing for superhard ceramic applications.
Machine Type:
Domestic Chinese demand concentrates in semi-automatic and fully automatic systems serving Fujian Province stone clusters. Export markets in Germany and Japan absorb precision and CNC-controlled equipment for electronics and aerospace specifications.
- CNC Controlled:Programmable tension and speed parameters enable kerf widths below 0.35 millimeters for brittle semiconductor substrates. Electronics OEMs in Taiwan and South Korea specify these systems for 200mm silicon carbide wafer production. MIIT GB standards for electromagnetic compatibility condition procurement toward certified domestic suppliers.
- Fully Automatic:Integrated material handling and wire replacement systems minimize operator intervention for high-volume solar ingot processing. Southeast Asian photovoltaic manufacturers deploy these configurations to reduce labor dependence amid technician scarcity.
- High-Speed:Optimized feed rates for soft stone and architectural block squaring.
- Precision:Tolerance-critical systems for aerospace component sectioning with AS9100 traceability.
- Semi-Automatic:Cost-efficient configurations dominating Carrara and Fujian quarry operations.
CNC Controlled commands the established base. The steepest expansion runs through Fully Automatic.
Technology:
Cost stratification separates capital-intensive thermal methods from mechanical abrasion systems. Japanese ceramics processors pay premium pricing for laser-assisted hybrid configurations.
- Laser Assisted:Thermal softening of superhard ceramics reduces diamond wire consumption by modifying material brittleness ahead of mechanical cutting. Korean aerospace subcontractors pilot these systems for titanium aluminide sectioning where conventional abrasion generates excessive tool wear.
- Water Jet:Cold cutting without heat-affected zones suits heat-sensitive semiconductor materials and precision jewelry alloys. Italian stone finishers combine water jet with multi-wire systems for complex architectural profiles.
- Electrical Discharge:Conductive material specialization for tool steel and hardened alloy processing.
- Plasma:High-throughput ferrous metal cutting in heavy fabrication workshops.
- Ultrasonic:Vibration-assisted sectioning for brittle advanced ceramics and glass substrates.
Water Jet retains the largest installed base. Laser Assisted gains share fastest in premium electronics applications.
Application:
Volume concentration tracks regional industrial specialization. Metal fabrication sustains replacement cycles while aerospace generates premium pricing through certification requirements.
- Electronics Manufacturing:Silicon wafering and ceramic substrate processing demand kerf widths below 0.25 millimeters with crack-free output. East Asian foundries qualify domestic equipment for gallium nitride ingots, though process windows for diameters exceeding 150mm remain unvalidated.
- Aerospace Component Cutting:AS9100-certified precision requirements and full material traceability generate pricing premiums three to four times above stone processing equivalents. French and US aerospace subcontractors consolidate supplier qualification lists around integrated solution providers.
- Metal Fabrication:Mature demand for structural steel and alloy sectioning in general manufacturing.
- Jewelry Production:Precision cutting of precious metals and gemstone rough in artisan workshops.
- Tool Manufacturing:Hard alloy blank preparation for cutting tool and die production.
Metal Fabrication holds the broadest installed base. Electronics Manufacturing shows the steepest climb.
End User Industry:
Customer type determines service bundling and procurement channel structure. Integrated solution contracts displace fragmented purchasing across equipment and consumable categories.
- Electronics OEMs:Single-source contracting for wire, equipment, and process development support reduces qualified supplier lists to three or fewer per technology node. Taiwan and South Korea foundries demand custom protocol bridges for MES and SCADA integration.
- Aerospace Engineering Firms:Extended validation cycles for ISO 230 accuracy certification and material traceability documentation strain project schedules. German equipment makers bundle sensor packages with predictive maintenance service contracts.
- Metalworking Workshops:Price-sensitive procurement with emphasis on consumable cost per meter cut.
- Jewelry Artisans:Small-batch precision requirements with manual override preferences.
- Precision Toolmakers:Tolerance-critical applications for cutting tool blank preparation.
Metalworking Workshops represent the deepest installed base. Electronics OEMs drive the fastest capacity expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys multi-wire cutting machines primarily for semiconductor substrate processing, while Italy and the United States concentrate these systems in dimensional stone and aerospace component cutting respectively. This consumption-mix differential reflects divergent industrial bases rather than technology preference.
China
Electronics OEMs in East Asia are qualifying domestic equipment for silicon carbide wafer production. MIIT enforces GB standards for machine tool safety and electromagnetic compatibility, redirecting procurement toward certified local suppliers. Fujian Province machinery clusters capture redirected public and private capital, with wire saw specialization creating dense supplier ecosystems serving both stone and electronics industries.
Italy
Architectural stone processors in Carrara sustain mature replacement cycles for granite-cutting systems. The EU Machinery Directive mandates CE marking with emergency stop integration and noise emission controls. Breton S.p.A anchors European demand through CNC-controlled architectural stone systems, while Simec Macchine Industriali dominates quarry equipment exports with specialized multi-wire configurations.
United States
Aerospace subcontractors consolidate supplier qualification lists around AS9100-certified precision requirements. FAA regulations and ITAR controls shape equipment specification for defense-adjacent applications. French and US aerospace engineering firms generate premium pricing for wire saw systems capable of titanium aluminide sectioning with full material traceability.
Japan
Ceramics processors pilot hybrid thermal-mechanical systems for superhard ceramic sectioning. METI industrial policy supports advanced manufacturing equipment development through targeted R&D subsidies. Nagoya-area industrial corridors host precision machinery clusters where Japanese equipment makers bundle sensor packages with predictive maintenance service contracts.
Germany
Machine tool accuracy testing under ISO 230 standards creates baseline certification thresholds for international competitive bidding. The EU Green Deal's embodied carbon tracking forces lifecycle accounting into equipment procurement criteria. Bavarian and Baden-Württemberg industrial regions concentrate German equipment manufacturing, with sensor-integrated systems serving electronics and aerospace precision requirements.
Multi Wire Cutting Machine Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with competitive advantage redistributing toward firms possessing integrated CNC and materials science capabilities. The market structure separates precision electronics suppliers from stone-processing heritage firms adapting to semiconductor applications. Two strategic archetypes dominate: integrated solution providers bundling equipment, wire, and technical service; and heritage machinery firms leveraging granite-cutting expertise for silicon wafer applications. M&A activity concentrates on sensor technology acquisitions, while capacity expansion targets Southeast Asian photovoltaic manufacturing corridors.
Within the heritage-adaptation tier, Fujian Province Hualong Machinery exemplifies Chinese stone-processing firms rotating skilled technicians into electronics substrate cutting. Breton S.p.A occupies a position among European architectural stone system specialists seeking electronics application certification. Simec Macchine Industriali represents Italian quarry equipment exporters with specialized multi-wire configurations serving global stone markets.
| Leading Market Players |
|---|
| Simec Macchine Industriali |
| Park Industries |
| Fujian Province Hualong Machinery |
| Fujian Xiapu Zhongyuan Machinery |
| Xiamen Qicheng Superhard Material |
| Breton S.p.A |
| Fujian Skystone Technology |
| Dinosaw Machine |
| Dalian Heida Machinery |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts for diamond-impregnated wire lock in supply access for Fujian Province electronics OEMs while compressing price visibility for stone processors exposed to Henan Province synthetic diamond spot markets. This contract-structure bifurcation concentrates procurement power with semiconductor foundries and fragments negotiating leverage across Carrara quarry operators.
Pricing Analysis
Project-based pricing dominates aerospace component cutting where AS9100 certification tiers separate premium quotations from standard equipment rates. Price differentiation hinges on electromagnetic compatibility certification under MIIT GB standards and bundled predictive maintenance service contracts. Cost compression in semi-automatic stone processing configurations intensifies as Ukrainian diamond feedstock volatility transmits through wire consumable costs. Metalworking workshops exhibit highest price sensitivity while electronics OEMs absorb premium positioning for CNC-controlled tension systems.
Supply Chain Analysis
China and Japan anchor synthetic diamond wire production with Fujian Province machinery clusters feeding downstream electronics substrate facilities. Raw material flows draw from Henan Province synthetic diamond synthesis, Ukrainian natural diamond deposits, and Nagoya-area precision wire drawing operations. Single-source vulnerability concentrates in abrasive grain supply where geopolitical disruption to Ukrainian deposits would cascade through wire pricing. Distribution runs through integrated solution providers in Taiwan and South Korea that bundle equipment, consumables, and technical service under consolidated procurement contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates acquisition opportunities as precision electronics specifications splinter vendor qualification lists across technology nodes. Semiconductor foundry consolidation around three-supplier limits per node generates tiered niche positions for specialized entrants.
For Market Incumbents: Consolidate sensor technology capabilities through targeted acquisitions to defend against AI-driven predictive maintenance entrants. Deepen backward integration into diamond wire production to capture margin pools currently leaking to Henan Province suppliers. Lock in Fujian Province technician training pipelines to preempt labor attrition toward semiconductor fabs.
For New Entrants and Emerging Players: Lead with laser-assisted thermal-mechanical hybrid systems targeting Korean aerospace titanium aluminide sectioning where incumbent tooling wear rates remain elevated. Gujarat and Tamil Nadu industrial corridors under India's PLI scheme offer the most penetrable qualification environment for imported technology transfers. Position around AS9100 certification support as a bundled service differentiator.
For Investors and Strategic Acquirers: Heritage stone-processing machinery firms with granite-cutting expertise and existing CNC adaptation programs represent the most defensible acquisition profile for silicon wafer application pivots. Monitor MIIT equipment localization mandate enforcement intensity as the inflection signal for domestic supplier valuation premiums versus import-dependent competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Technology Acquisition | Captures predictive maintenance revenue pools from German and Japanese equipment makers bundling vibration analysis packages. |
| Backward Integration into Diamond Wire | Reduces exposure to Henan Province synthetic diamond price volatility for high-wire-count configurations. |
| AS9100 Certification Investment | Unlocks premium pricing tiers from French and US aerospace subcontractors consolidating supplier qualification lists. |
| PLI Scheme Qualification in India | Positions for technology transfer partnerships in Gujarat and Tamil Nadu semiconductor manufacturing corridors. |
| Laser-Assisted R&D Partnership | Accelerates hybrid thermal-mechanical system development for Korean ceramics processors piloting superhard ceramic sectioning. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with semiconductor fab equipment procurement managers, wire saw maintenance technicians, aerospace subcontractor quality directors, and stone quarry operations supervisors. Secondary validation drew from MIIT GB standard filings, EU Machinery Directive CE marking databases, ISO 230 machine tool accuracy certification records, and customs trade data tracking diamond wire import flows. Bottom-up equipment shipment tallies triangulated against top-down electronics OEM capital expenditure disclosures.
Across the analysis window, the forecasting framework modeled volume and value outputs through machine type automation tiers, technology thermal-mechanical segmentation, application precision requirements, and end-user industry procurement channel structures. CAGRs were derived from regression analysis against semiconductor wafer diameter expansion trajectories and photovoltaic ingot processing capacity buildouts. Industry-specific inputs included wire tension parameter evolution rates and diamond grain distribution engineering cycles.
The analysis sits within stated boundaries; outcomes outside sustained MIIT localization enforcement, continued silicon carbide substrate adoption curves, or stable synthetic diamond supply from Henan Province would require recalibration. Forecasts reflect documented assumptions regarding technician labor pool rotation rates and EU Green Deal embodied carbon accounting implementation timing. Recalibration cycles align with material shifts in GB standard revision schedules and aerospace certification backlog clearance rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Tooling Market
Tools
Striking Tools Market
Tools
Self-Clinching Fasteners Market
Tools
Portable Pressure Washer Market
Tools
Rotary Hammer Drill Market
Tools
L Allen Wrench Market
Tools
Telescopic Tool Boxes Market
Tools
Boring Tools Market
Tools
Hand Tools and Woodworking Tools Market
Tools
Turning Tools Market
Tools
Fine Blanking Tools Market
Tools
Woodworking CNC Tools Market
Tools
Welding Products Market
Tools
Foam Cutting Machine Market
Tools
Structural Wood Screws Market
Tools
Steel Measuring Tape Market