
 Loading Platform Canopies Market | 2026-2036
Loading Platform Canopies Market Size, Share, and Industry Trends Forecast 2026-2036
Loading Platform Canopies Market Analytics
Certified welder and structural steel fabricator availability is redrawing competitive boundaries across the Loading Platform Canopies market. ThyssenKrupp AG leverages its captive steel supply and in-house engineering to dominate large-scale industrial installations. Rite-Hite Holding Corporation sustains North American channel control through direct specification relationships with warehousing operators. Promstahl GmbH anchors European demand with fabrication facilities located near German logistics corridors.
Loading platform canopies are engineered overhead structures, typically fabricated from galvanized steel or aluminum framing with PVC, fabric, or composite membrane roofing, designed to shield personnel, equipment, and goods from precipitation, wind, and thermal exposure during truck-to-facility transfer operations. Fixed canopies occupy the mature volume base in heavy manufacturing and bulk distribution, while retractable and custom canopy configurations capture expanding margin pools as just-in-time logistics operators seek flexible weather protection. Aluminum and steel materials lead structural specifications, though fabric membranes are gaining specification share in commercial retail applications where rapid deployment and lower foundation loads matter.
OSHA fall-protection and loading dock safety standards in the United States, CE marking requirements under EU machinery directives, and ISO 9001 quality management frameworks collectively shape product certification pathways and installation compliance costs. The EU Green Deal and evolving national building codes are embedding energy-efficiency and recyclability criteria into canopy material selection and lifecycle assessments. Stakeholders must monitor how regulatory convergence between occupational safety and environmental performance standards reshapes supplier qualification criteria and project bidding requirements.
Market Dynamics
Certified welder scarcity and captive steel supply control are compressing margins for fabricators without backward integration into raw material sourcing and in-house structural engineering capabilities.
Growth Catalysts
- EU machinery directives:CE marking mandates for loading equipment safety systems are compelling warehouse operators across Germany, France, and Poland to upgrade uncovered dock infrastructure.
- Temperature-sensitive freight expansion:Pharmaceutical and fresh-food distribution networks are specifying insulated canopy systems with integrated HVAC tie-ins to protect cold-chain integrity during transfer operations.
- Aluminum framing adoption:Corrosion-resistant alloy specifications are displacing galvanized steel in coastal logistics hubs where salt exposure accelerates structural degradation.
Market Restraints
- Structural steel price volatility:Hot-rolled coil fluctuations tied to energy input costs are destabilizing project bidding accuracy for fixed-price canopy contracts.
- German fabricator concentration:Three specialized steelwork clusters near the Rhine-Ruhr corridor control premium industrial-grade canopy production capacity.
- Foundation load limitations:Existing warehouse slabs lacking engineered reinforcement restrict specification of heavy steel canopy systems without costly substructure remediation.
Strategic Opportunities
- Indian logistics corridor buildout:Dedicated freight corridors connecting Delhi-Mumbai and Chennai-Bengaluru are generating greenfield demand for all-weather loading infrastructure at new multimodal terminals.
- EU Green Deal material incentives:Recyclability scoring in public procurement frameworks favors aluminum and fabric membrane specifications over conventional steel.
- Modular quick-assembly systems:Bolt-together framing with pre-tensioned membrane roofing is opening specification access to mid-scale retail distribution operators previously served only by permanent construction.
Industry Challenges
- Certified welder pipeline gaps:European vocational training programs are producing insufficient coded welders to match installation demand from automotive and chemical distribution hub expansions.
- Multi-standard compliance sequencing:Simultaneous OSHA fall-protection, ISO 9001 quality, and EU machinery directive audits are extending project approval timelines for cross-border operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Loading Platform Canopies Market |
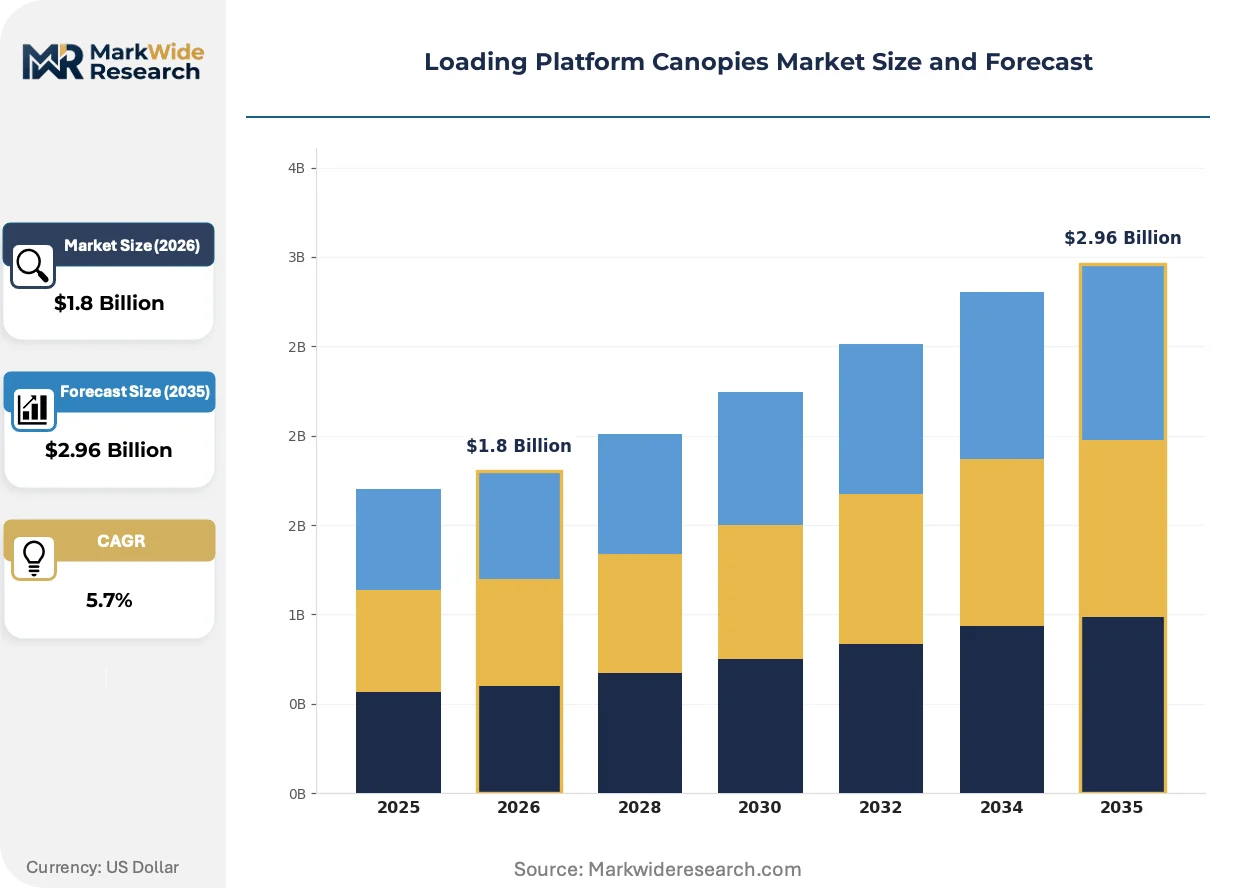
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Canopies, Retractable Canopies, Portable Canopies, Custom Canopies Material: Aluminum, Steel, PVC, Fabric Application: Industrial Use, Commercial Use, Retail, Agricultural Use End User: Logistics Companies, Warehousing, Manufacturing Units, Distributors |
| Companies Covered | ThyssenKrupp AG, Alapont Global, Promstahl GmbH, Rite-Hite Holding Corporation, Hormann Group, Assa Abloy Group, Nordock Inc., Blue Giant Equipment Corporation, SafeRack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Loading Platform Canopies Market Evolving Landscape
Material science advances and regulatory tightening around embodied carbon are compressing traditional specification hierarchies, forcing fabricators to demonstrate lifecycle performance rather than upfront durability alone.
Photovoltaic-integrated membrane roofing is miniaturizing. Thin-film solar laminates embedded in tensioned fabric canopies now generate on-site power for dock lighting and HVAC systems. Third-party logistics operators in the Netherlands and California are specifying these hybrid systems for net-zero warehouse certifications. The technology is miniaturizing balance-of-system components, reducing structural load penalties and installation complexity compared to conventional panel arrays.
REACH chemical restrictions on hexavalent chromium surface treatments are accelerating specification shifts toward powder-coated aluminum and stainless steel hardware. German automotive distribution hubs are now rejecting galvanized components that cannot demonstrate Cr(VI)-free passivation. Fabricators with in-house coating capabilities are capturing specification share from commodity suppliers dependent on outsourced finishing.
Buyer consolidation among pan-European logistics real estate investment trusts is compressing vendor qualification lists. Blackstone and Prologis portfolio managers are mandating single-source canopy contracts across multi-site rollouts, displacing regional fabricators who lack cross-border installation networks. This concentration is most visible in the Benelux corridor, where three investment vehicles control over sixty percent of new speculative warehouse development.
Loading Platform Canopies Market Segmentation
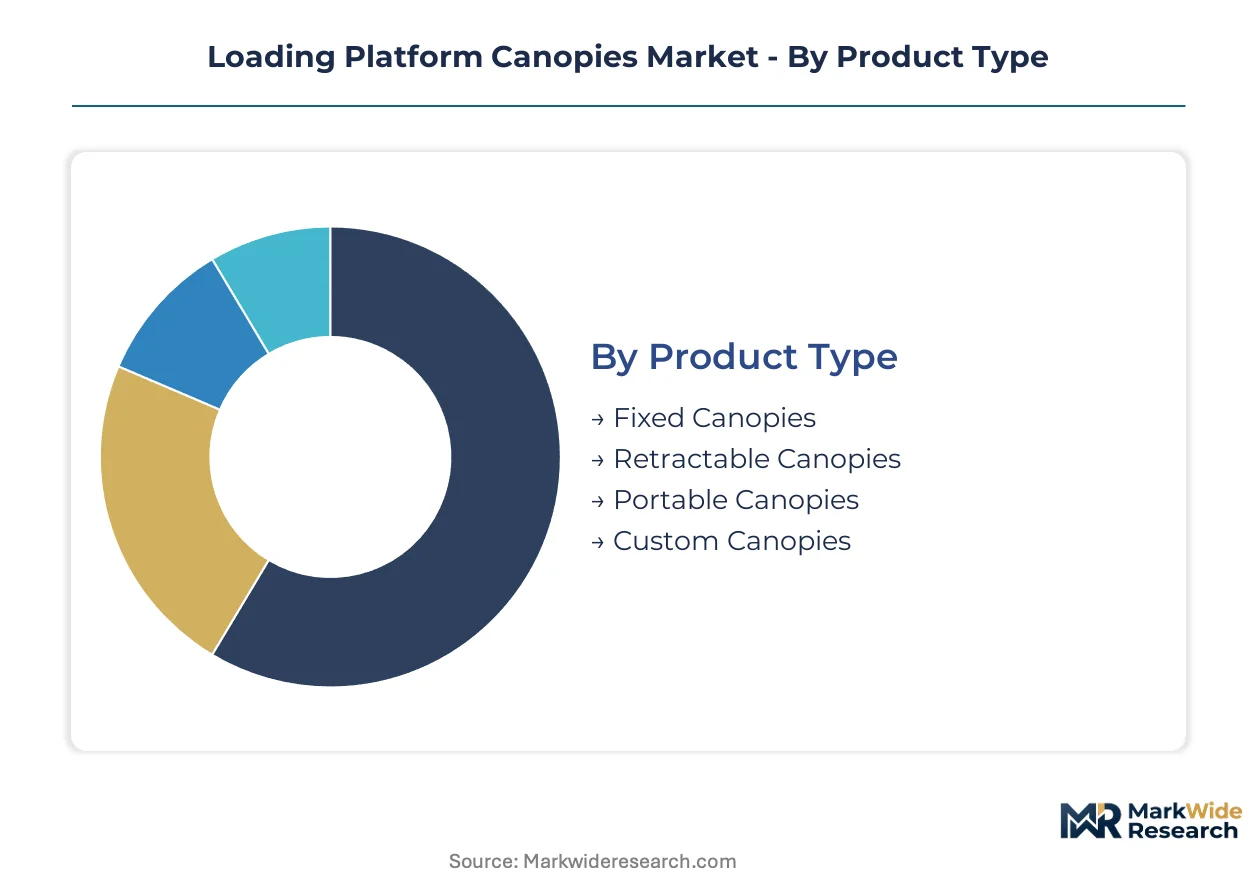
Loading platform canopy specifications diverge sharply across installation permanence, structural material, and operational intensity. Procurement decisions hinge on OSHA fall-protection compliance for fixed industrial installations versus CE marking flexibility for modular retail deployments.
Product Type:
Regulatory differentiation separates permanent installations requiring structural engineering certification from temporary systems governed by lighter machinery directives.
- Fixed Canopies:Permanent galvanized steel or aluminum framing with composite membrane roofing anchored to engineered foundations. Heavy manufacturing facilities in Germany's Rhine-Ruhr corridor specify these for automotive and chemical distribution hubs where OSHA-equivalent EU machinery directives mandate documented load-bearing capacity.
- Retractable Canopies:Motorized tensioned fabric systems mounted on rolling track assemblies allowing weather-responsive deployment. Third-party logistics operators in the Netherlands specify these for net-zero warehouse certifications where photovoltaic-integrated membrane roofing generates on-site dock power.
- Portable Canopies:Bolt-together aluminum framing with pre-tensioned membrane roofing designed for rapid relocation without foundation work.
- Custom Canopies:Engineered-to-order structures accommodating irregular dock configurations or integrated HVAC tie-ins for cold-chain protection.
Established volume favors Fixed Canopies; emerging adoption favors Retractable Canopies.
Material:
Cost tier differentiation separates premium corrosion-resistant alloys from commodity galvanized specifications, with recyclability scoring increasingly influencing public procurement.
- Steel:Hot-rolled and cold-formed galvanized structural sections delivering maximum load capacity for heavy manufacturing applications. German automotive distribution hubs are rejecting galvanized components lacking Cr(VI)-free passivation under REACH chemical restrictions.
- Aluminum:Corrosion-resistant alloy extrusions displacing steel in coastal logistics hubs where salt exposure accelerates structural degradation. EU Green Deal material incentives favor aluminum's recyclability scoring in public procurement frameworks.
- PVC:Rigid polyvinyl chloride cladding and roofing membranes specified for chemical resistance in industrial washdown environments.
- Fabric:High-tenacity polyester or fiberglass base fabrics with PVC or PTFE coatings enabling rapid deployment and lower foundation loads.
Steel dominates legacy industrial specifications; aluminum gains share fastest in coastal and sustainability-weighted procurement.
Application:
Application segmentation tracks operational intensity from 24/7 freight transfer to seasonal agricultural protection, with compliance burdens scaling accordingly.
- Industrial Use:Heavy-duty installations serving continuous manufacturing and bulk distribution operations. Blackstone and Prologis portfolio managers mandate single-source canopy contracts across multi-site industrial rollouts, compressing vendor qualification lists.
- Commercial Use:Mid-scale warehousing and mixed-use logistics facilities balancing durability with cost efficiency.
- Retail:Rapid-deployment membrane systems for last-mile distribution centers where lower foundation loads and quick assembly matter.
- Agricultural Use:Seasonal protection for grain handling and produce packing operations with intermittent usage patterns.
Industrial Use commands premium pricing; Retail represents the steepest expansion trajectory as e-commerce fulfillment networks proliferate.
End User:
Customer type segmentation reveals divergent procurement sophistication, from integrated logistics real estate investment trusts to fragmented agricultural operators.
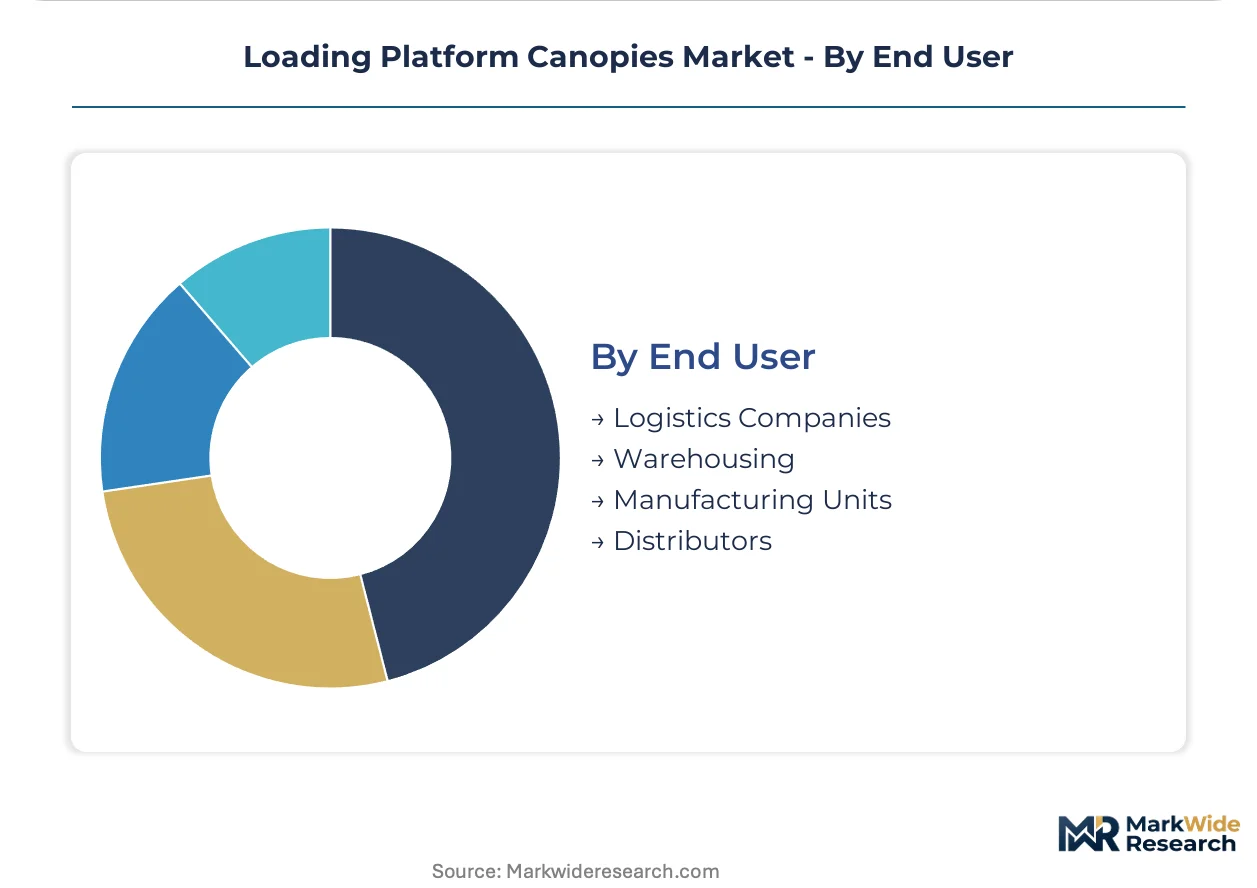
- Logistics Companies:Pan-European and North American third-party operators specifying standardized canopy systems across distributed networks. These buyers leverage direct specification relationships with fabricators to control multi-site rollout consistency.
- Warehousing:Dedicated storage facility operators focused on dock safety compliance and temperature-sensitive freight protection. Pharmaceutical and fresh-food distribution networks here specify insulated canopy systems with integrated HVAC tie-ins.
- Manufacturing Units:Captive industrial facilities with in-house engineering teams capable of structural specification.
- Distributors:Intermediate goods handlers with variable throughput requiring flexible weather protection configurations.
Logistics Companies consolidate procurement power; Warehousing drives specification innovation for cold-chain integrity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA workplace safety mandates in the United States and equivalent EU machinery directives are accelerating structural upgrade requirements across the dominant geographies for loading platform canopy installations.
United States
Third-party logistics operators are expanding covered loading infrastructure to protect temperature-sensitive freight across the Southeast and Midwest distribution corridors. OSHA fall-protection and loading dock safety standards compel warehouse operators to upgrade uncovered dock infrastructure with certified structural systems. The Chicago-Memphis-Atlanta logistics triangle drives concentrated demand from e-commerce fulfillment networks.
Germany
Automotive and chemical distribution hubs in the Rhine-Ruhr corridor require all-weather loading protection with documented load-bearing capacity under EU machinery directives. REACH chemical restrictions on hexavalent chromium surface treatments are accelerating specification shifts toward powder-coated aluminum and stainless steel hardware. Stuttgart and Wolfsburg automotive clusters now reject galvanized components lacking Cr(VI)-free passivation.
Netherlands
Third-party logistics operators are specifying photovoltaic-integrated membrane roofing for net-zero warehouse certifications in the Rotterdam-Antwerp port corridor. EU Green Deal material incentives favor aluminum and fabric membrane specifications over conventional steel in public procurement frameworks. Eindhoven-based distribution centers are deploying motorized tensioned fabric systems with thin-film solar laminates.
India
Dedicated freight corridors connecting Delhi-Mumbai and Chennai-Bengaluru are generating greenfield demand for all-weather loading infrastructure at new multimodal terminals. BIS standards and state-level industrial safety codes are mandating weather protection systems at major logistics parks. The Maharashtra and Gujarat logistics hubs are prioritizing rapid-deployment canopy systems for pharmaceutical export facilities.
China
Coastal logistics hubs in the Yangtze River Delta and Pearl River Delta are displacing galvanized steel with corrosion-resistant aluminum framing where salt exposure accelerates structural degradation. GB standards for loading equipment safety and dual carbon goals are embedding recyclability criteria into material selection. Shanghai and Shenzhen cold-chain operators are specifying insulated canopy systems with integrated HVAC tie-ins.
Loading Platform Canopies Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Loading Platform Canopies market, with captive steel supply and in-house engineering capabilities compressing margins for fabricators lacking backward integration. The upper tier controls large-scale industrial installations through direct specification relationships with warehousing operators and pan-European logistics real estate investment trusts. Three strategic archetypes dominate: integrated steel-to-fabrication conglomerates, specialized dock equipment manufacturers, and regional metalwork fabricators with coating capabilities. Competitive moves concentrate on single-source contract consolidation across multi-site rollouts and modular quick-assembly system development.
Among Germany-based fabricators, ThyssenKrupp AG exemplifies the integrated conglomerate archetype through captive steel supply and structural engineering dominance. Promstahl GmbH anchors the specialized regional tier with fabrication facilities positioned near German logistics corridors. Rite-Hite Holding Corporation represents the North American dock equipment specialist model, sustaining channel control through direct specification relationships with warehousing operators. These three occupy positions that illustrate how geographic proximity to demand clusters and control over critical fabrication inputs determine competitive viability.
| Leading Market Players |
|---|
| ThyssenKrupp AG |
| Alapont Global |
| Promstahl GmbH |
| Rite-Hite Holding Corporation |
| Hormann Group |
| Assa Abloy Group |
| Nordock Inc. |
| Blue Giant Equipment Corporation |
| SafeRack |
| Others |
Value Network & Pricing Analysis
Aluminum alloy displacement of galvanized steel specifications is simultaneously shifting procurement geography toward coastal logistics hubs and compressing margin structures for fabricators locked into legacy steel supply chains. This material substitution dynamic rewards suppliers with captive smelter relationships while penalizing commodity distributors dependent on spot-market coil purchases.
Pricing Analysis
Geographic price spreads between German automotive cluster specifications and Indian greenfield logistics corridor deployments now exceed the cost of intercontinental freight for containerized aluminum extrusions. Three-tier pricing structure across premium certified, standard industrial, and economy modular levels dominates procurement frameworks, with CE marking and OSHA fall-protection certification tiers commanding substantial premiums. Pricing pressure stems from certified welder scarcity extending installation timelines and inflating labor cost pass-throughs. Logistics real estate investment trusts demonstrate lowest price sensitivity due to single-source contract consolidation, while fragmented agricultural operators drive aggressive commodity negotiation.
Supply Chain Analysis
Inbound logistics costs from Rotterdam port congestion and container availability constraints on Asia-Europe trade lanes are destabilizing just-in-time material flows for fabricators without regional steel stocking. Supply concentrates in Germany, China, and India, with German Rhine-Ruhr fabricators controlling premium industrial-grade capacity and Chinese Yangtze Delta producers dominating aluminum extrusion feedstock. Raw material dependencies center on hot-rolled steel coil, primary aluminum ingot, and high-tenacity polyester membrane substrates. Single-source vulnerability pervades the certified welder labor pool, particularly across European vocational training pipelines. Distribution runs through direct specification relationships with pan-European logistics operators and warehousing procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among pan-European logistics real estate investment trusts, with Blackstone and Prologis portfolio consolidation compressing vendor qualification lists and mandating multi-site single-source contracts that displace regional fabricators.
For Market Incumbents: Secure captive steel supply through backward integration or long-term offtake agreements with Rhine-Ruhr mills to defend margin position against aluminum substitution momentum. Invest in in-house powder-coating capabilities to meet REACH chemical restrictions on hexavalent chromium passivation, as German automotive distribution hubs now reject non-compliant galvanized components. Channel control through direct specification relationships with warehousing operators remains the critical defensive lever against emerging modular quick-assembly competitors. For New Entrants and Emerging Players: Differentiate on rapid-deployment modular systems targeting Indian pharmaceutical export facilities along Delhi-Mumbai and Chennai-Bengaluru freight corridors, where BIS standards mandate weather protection but foundation load limitations favor bolt-together aluminum framing. The most penetrable white space sits in mid-scale retail distribution previously served only by permanent construction, accessible through pre-tensioned membrane roofing with lower engineering certification barriers. Pursue specification partnerships with third-party logistics operators seeking net-zero warehouse certifications through photovoltaic-integrated canopy systems. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated steel-to-fabrication conglomerates with captive raw material supply and cross-border installation networks. Long-term viability over the next decade hinges on demonstrated lifecycle performance under tightening EU Green Deal recyclability criteria and OSHA-equivalent machinery directive convergence. Acquisition targets should display in-house coating capabilities and proximity to German logistics corridors. The signal to watch is buyer consolidation velocity among logistics real estate investment trusts, as single-source contract mandates will accelerate vendor list compression beyond organic growth capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Supply | Captive hot-rolled coil access insulates ThyssenKrupp from energy-input cost volatility destabilizing fixed-price contracts. |
| Modular Quick-Assembly System Development | Bolt-together aluminum framing opens specification access to mid-scale retail distribution operators previously excluded from permanent construction. |
| Photovoltaic-Integrated Membrane Roofing | Thin-film solar laminates embedded in tensioned fabric enable Netherlands third-party logistics operators to achieve net-zero warehouse certifications. |
| In-House Powder-Coating Capability Investment | REACH-compliant finishing captures specification share from commodity suppliers dependent on outsourced hexavalent chromium passivation. |
| Cross-Border Installation Network Expansion | Pan-European coverage satisfies Prologis and Blackstone single-source mandates across Benelux corridor speculative warehouse development. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary validation across regulatory and trade databases. Primary interviews encompassed plant engineers at automotive distribution hubs, procurement leads at third-party logistics operators, structural steel fabricator operations managers, and aftermarket service heads at dock equipment specialists. Secondary sources included OSHA enforcement databases, EU machinery directive CE marking registries, customs and trade flow data for steel and aluminum inputs, and SEC filings from integrated logistics real estate investment trusts. Bottom-up canopy installation counts triangulated against top-down construction spending allocations across logistics infrastructure.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmented demand drivers including product type permanence, structural material substitution patterns, application intensity tiers, and end-user procurement sophistication. Segmentation dimensions encompassed fixed versus retractable versus portable canopy configurations, steel versus aluminum versus fabric membrane material specifications, and industrial versus commercial versus retail application contexts. CAGRs derived from regression analysis against logistics construction indices and regulatory compliance mandate timelines, with specific inputs from certified welder pipeline gap projections and EU Green Deal material incentive adoption curves.
Material uncertainties — structural steel price volatility tied to energy input costs, REACH chemical restriction enforcement variance, and vocational training program output fluctuations — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory convergence between occupational safety and environmental performance standards. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Port Material Handling Equipment Vehicle Market
Material Handling Equipment
Middle East and Africa Conveyors Market
Material Handling Equipment
Resistance Welding Products Market
Material Handling Equipment
Industrial Girth Gear Market
Material Handling Equipment
Global Lifting Columns Market
Material Handling Equipment
Hose Pump Market
Material Handling Equipment
Spiral Fitting Machines Market
Material Handling Equipment
Global Air Cannon System Market
Material Handling Equipment
Industrial Elevator Market
Material Handling Equipment
Dewatering Screen Market
Material Handling Equipment
Wire Pulling and Tensioning Market
Material Handling Equipment
Pipe Wipers Market
Material Handling Equipment
Hoist Controller Market
Material Handling Equipment
Hydraulic Cylinder Rod Market
Material Handling Equipment
Pipe Jacking Machines Market
Material Handling Equipment
Overhead Conveyor Systems Market