
 Hydraulic Cab Tilt System Market | 2026-2036
Hydraulic Cab Tilt System Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Cab Tilt System Market Outlook
Aftermarket service revenue is tilting toward integrated electronic-hydraulic platforms as fleets extend vehicle lifecycles. Parker Hannifin Corporation leverages its fluid power portfolio to dominate replacement channels for commercial vehicle hydraulics. Haldex anchors European aftermarket distribution through its dense service network. JOST Werke specializes in cab suspension and tilt systems for heavy-duty trucks across German and Scandinavian OEM supply chains.
A hydraulic cab tilt system employs pressurized fluid actuation—typically mineral oil-based hydraulic fluid at operating pressures between 150 and 250 bar—to raise and lower truck cabs for engine access and maintenance. Double cylinder configurations lead product type demand due to their stability in heavy machinery and construction equipment applications where cab weights exceed 800 kilograms. OEM installation channels capture the dominant margin pool as truck and construction equipment manufacturers integrate tilt systems at the assembly stage rather than deferring to aftermarket retrofit. Electronic control technology within the technology segment is gaining share as integrated sensors enable position feedback and automated safety interlocks.
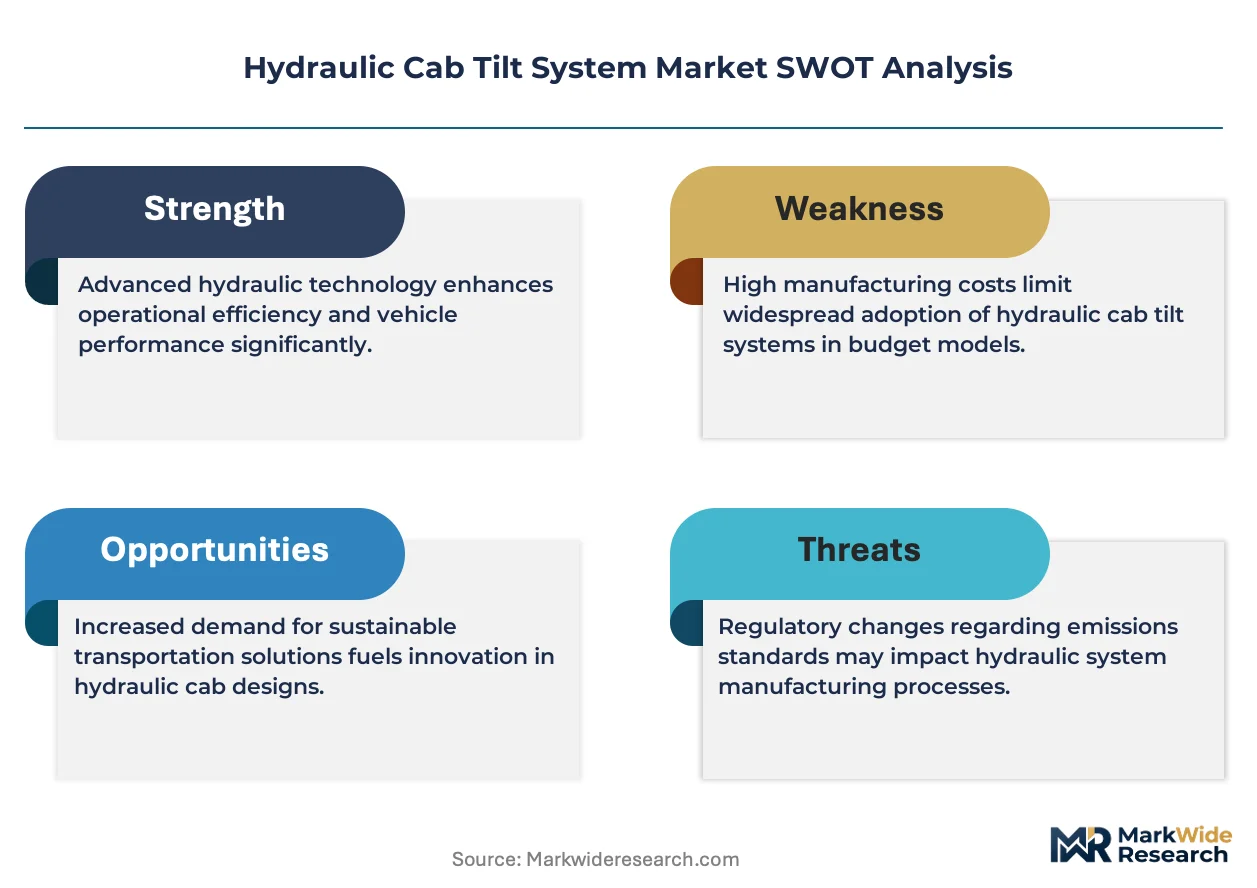
NHTSA cab crashworthiness standards and EPA emissions regulations jointly shape hydraulic system specifications by mandating lighter cab structures that remain serviceable. ISO 26262 functional safety requirements increasingly influence electronic control module designs for cab tilt actuation. Stakeholders must monitor the migration from standalone hydraulic units to electromechanical hybrid systems as OEMs pursue weight reduction targets without sacrificing service accessibility.
Market Dynamics
The hydraulic cab tilt system market is undergoing structural compression as electromechanical hybrid architectures displace pure hydraulic actuation in next-generation commercial vehicle platforms. This technology migration is forcing incumbent suppliers to reconfigure fluid power portfolios while defending installed-base aftermarket revenue streams.
Growth Catalysts
- NHTSA crashworthiness mandates:Lighter cab structures must maintain service accessibility, compelling OEMs to specify integrated tilt mechanisms at the factory assembly stage rather than deferring to field retrofit.
- Fleet lifecycle extension programs:Commercial trucking operators in Germany and Scandinavia are retaining vehicles beyond traditional replacement cycles, expanding demand for replacement hydraulic cylinders and electronic control modules.
- Construction equipment electrification:Battery-electric excavators and wheel loaders require redesigned cab mounting systems that accommodate high-voltage architectures while preserving hydraulic tilt functionality for maintenance access.
Market Restraints
- Steel and aluminum price volatility:Cylinder barrel and piston rod materials account for substantial bill-of-materials exposure, compressing margins when commodity markets spike.
- German supply concentration:Critical casting and machining capacity clusters around Stuttgart and Munich industrial corridors, creating geographic vulnerability to localized energy cost shocks or labor disruptions.
- Electromechanical substitution:Screw jack and linear motor alternatives are capturing specification share in sub-500 kilogram cab applications where hydraulic power density offers diminishing returns.
Strategic Opportunities
- Brazilian commercial vehicle production:ANVISA safety regulations and expanding domestic truck assembly create whitespace for hydraulic tilt system localization beyond established European supply chains.
- ISO 26262 functional safety certification:Electronic control modules meeting automotive safety integrity levels command pricing premiums and create switching costs against uncertified competitors.
- Sensor-integrated smart cylinders:Convergence of position feedback transducers with hydraulic actuators enables predictive maintenance offerings that capture recurring service revenue.
Industry Challenges
- Embedded software validation:Functional safety certification for electronic-hydraulic control units requires specialized automotive software engineering talent scarce in traditional fluid power organizations.
- Legacy fleet retrofit complexity:Pre-2015 commercial vehicles lack CAN bus architecture compatibility, fragmenting aftermarket product development and inventory requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Cab Tilt System Market |
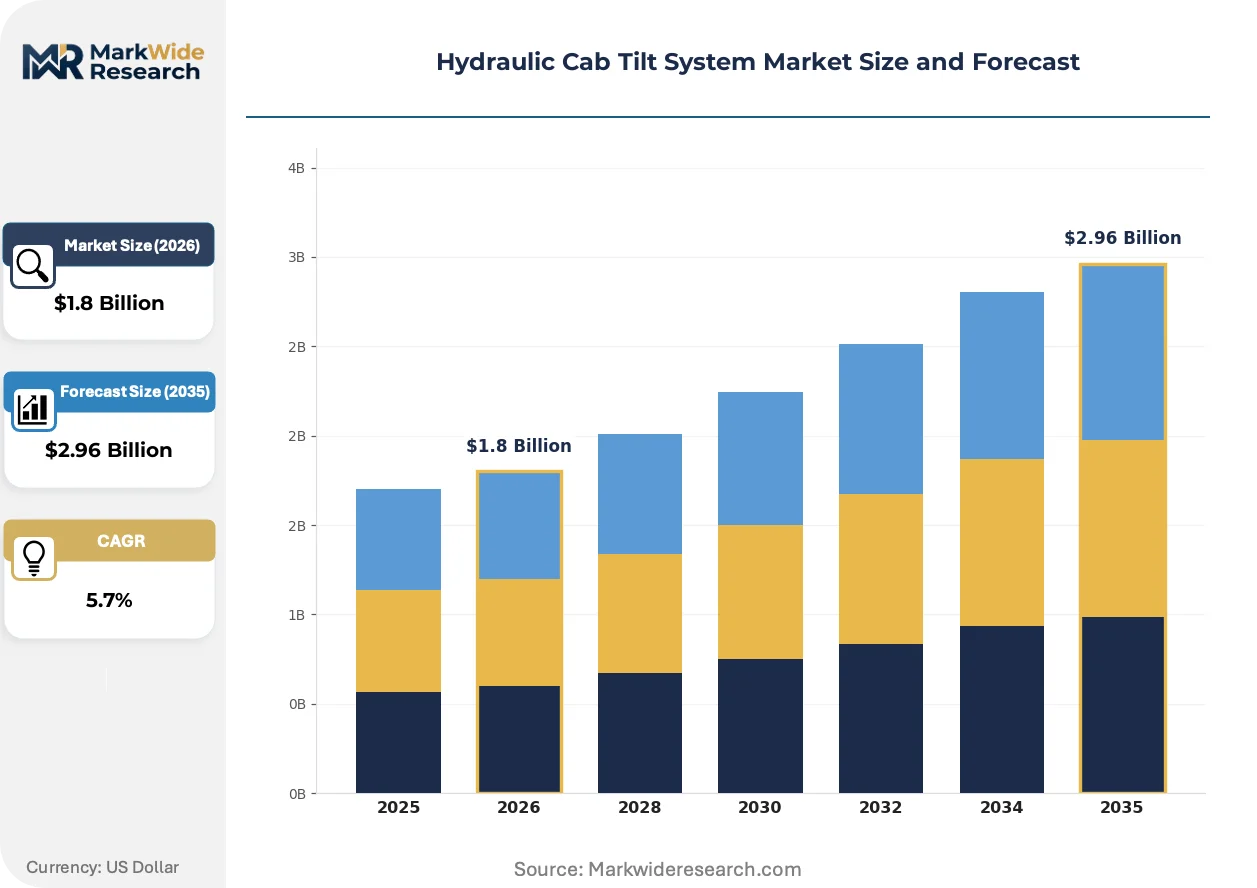
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Cylinder, Double Cylinder, Pneumatic, Electric End User: Heavy Machinery, Commercial Vehicles, Construction Equipment, Emergency Services Technology: Hydraulic, Mechanical, Electronic, Integrated Control Installation Type: OEM, Aftermarket, Retrofit, Custom |
| Companies Covered | Parker Hannifin Corporation, Caterpillar Inc., Wipro Infrastructure Engineering, Haldex, Power-Packer, Bendix Commercial Vehicle Systems, WABCO, JOST Werke, Volvo Trucks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Cab Tilt System Market Strategic Shifts
Electrification imperatives are forcing simultaneous redesign of cab structures and their actuation systems, compressing development timelines and collapsing traditional supplier-OEM boundaries. Three distinct vectors are reshaping competitive positioning in hydraulic cab tilt technology.
Electro-hydraulic actuator architectures are collapsing the distinction between standalone hydraulic power units and integrated mechatronic subsystems. These compact units combine variable displacement pumps with brushless DC motors and onboard controllers, enabling OEMs to eliminate separate hydraulic reservoirs and routing. European heavy truck manufacturers are specifying these integrated modules for electric vehicle platforms where packaging space and weight carry premium valuations. The structural consequence is collapsing tier-2 supplier margins as mechatronics competence becomes mandatory for hydraulic component vendors.
EPA Phase 3 greenhouse gas standards and corresponding EU CO2 regulations for heavy-duty vehicles are mandating aerodynamic cab designs with tighter engine bay packaging. These regulatory frameworks reduce physical clearance for maintenance access, intensifying reliance on tilt mechanisms that maximize angular displacement within constrained hinge geometries. North American long-haul tractor segments are responding with specification requirements for 70-degree tilt angles, driving cylinder stroke and linkage design innovation.
Service contract unbundling is fragmenting traditional aftermarket relationships as fleet maintenance providers separate parts procurement from labor scheduling. Independent service networks in the United States are establishing direct sourcing relationships with hydraulic component manufacturers, bypassing traditional OEM captive distribution. This channel disintermediation is most pronounced in for-hire trucking segments where third-party maintenance providers manage multi-brand fleets and prioritize parts commonality over brand loyalty.
Hydraulic Cab Tilt System Market Segmentation
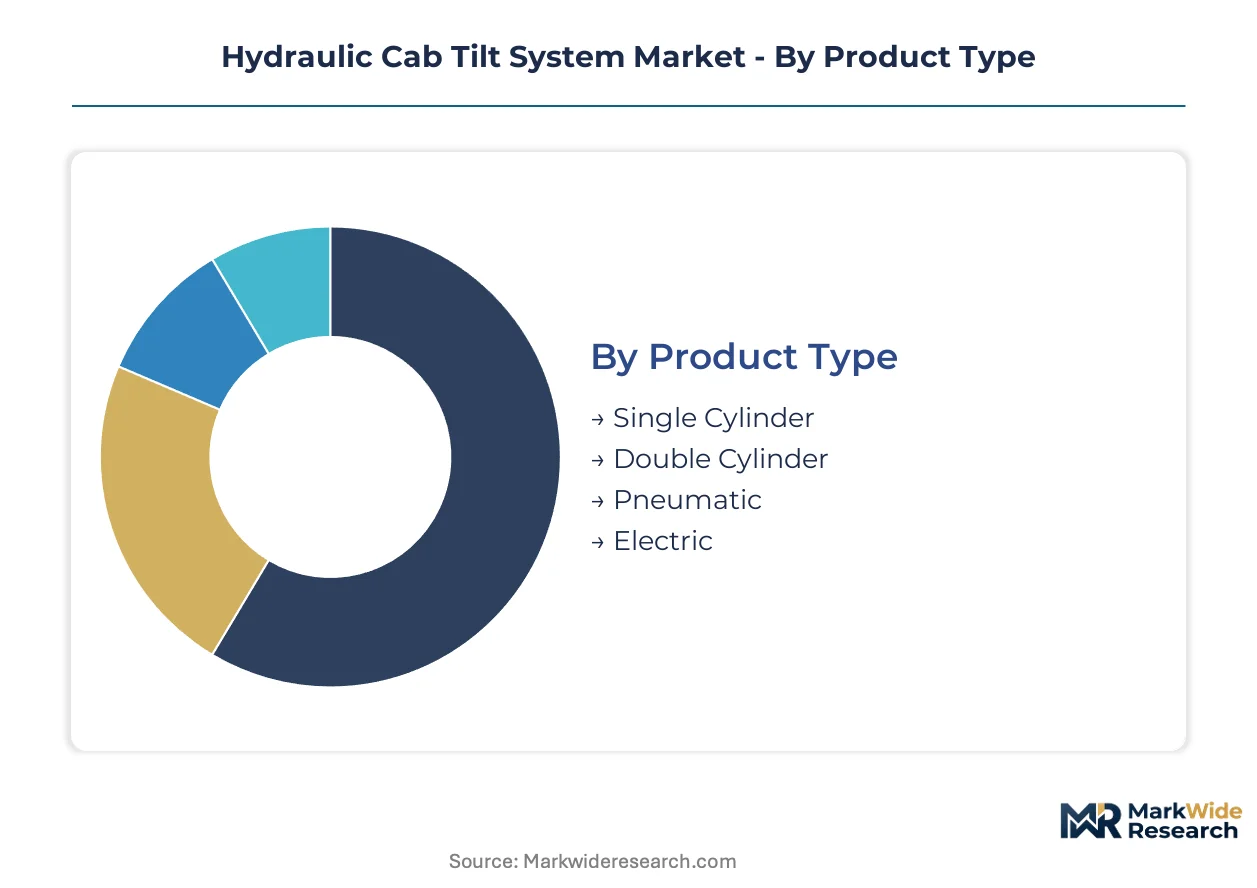
Segmentation in hydraulic cab tilt systems reveals divergent margin structures and service intensity profiles across product architectures. Aftermarket revenue concentration varies sharply by cylinder configuration and control technology, shaping supplier portfolio priorities.
Product Type:
After-sales service intensity diverges dramatically across actuation architectures, with multi-cylinder systems generating recurring seal replacement and synchronization calibration revenue streams that single-cylinder alternatives cannot match.
- Double Cylinder:Twin-actuator configurations employ synchronized hydraulic circuits with cross-flow balancing valves to maintain cab stability during tilt operations. Demand clusters in German and Scandinavian heavy-duty tractor programs where cab weights routinely exceed 800 kilograms and angular displacement requirements reach 70 degrees. Fleet operators in these markets prioritize the configuration's redundancy characteristics for uptime-critical long-haul applications.
- Single Cylinder:Centralized actuation through one high-bore cylinder reduces system complexity and initial acquisition cost for sub-500 kilogram cab applications. Brazilian and Indian commercial vehicle assemblers specify this architecture for mid-range trucks where maintenance access frequency remains lower than premium European segments.
- Pneumatic:Compressed air actuation serves niche applications in mining and explosive atmosphere environments where hydraulic fluid leakage poses ignition risks.
- Electric:Ball screw and linear motor alternatives are displacing hydraulic solutions in battery-electric urban delivery vehicles where auxiliary power unit elimination is mandatory.
By volume, Single Cylinder leads. By growth pace, Electric is ahead.
End User:
Cost tier stratification separates specification requirements, with premium segments demanding integrated electronic controls while value-oriented categories accept basic hydraulic functionality.
- Commercial Vehicles:Heavy-duty trucking fleets in Germany and North America specify factory-integrated tilt systems with CAN bus position feedback to minimize warranty exposure and maximize residual values. NHTSA crashworthiness mandates compel OEMs to engineer lighter cab structures that retain service accessibility through optimized hinge geometry.
- Construction Equipment:Excavator and wheel loader manufacturers face simultaneous pressure from electrification imperatives and maintenance access requirements. Battery-electric machine architectures demand redesigned cab mounting systems that accommodate high-voltage isolation while preserving hydraulic tilt functionality.
- Heavy Machinery:Mining trucks and material handlers require extreme-duty cylinder specifications with hardened rod coatings and redundant sealing systems.
- Emergency Services:Fire apparatus and rescue vehicle builders prioritize rapid tilt deployment for engine bay access during incident response.
Commercial Vehicles capture the dominant revenue share. Construction Equipment shows the steepest expansion trajectory as electrification drives platform redesign.
Technology:
Volume concentration favors mature hydraulic architectures, though margin migration toward electronic modules is accelerating supplier R&D allocation.
- Hydraulic:Mineral oil-based systems operating at 150-250 bar dominate installed base and replacement part revenue. Parker Hannifin and Haldex anchor aftermarket distribution through dense service networks in Europe and North America.
- Electronic:Control modules with ISO 26262 functional safety certification command pricing premiums and create switching costs against uncertified competitors. Integrated sensors enable position feedback and automated safety interlocks that reduce operator injury liability.
- Mechanical:Manual pump and release valve configurations persist in emerging market price-sensitive segments.
- Integrated Control:Combined electro-hydraulic units with onboard brushless DC motors and variable displacement pumps eliminate separate reservoirs.
Hydraulic technology maintains volume leadership. Electronic modules are climbing the fastest as safety certification becomes mandatory.
Installation Type:
Customer type segmentation separates captive OEM supply relationships from fragmented aftermarket procurement patterns.
- OEM:Factory installation at vehicle assembly captures the dominant margin pool as truck and construction equipment manufacturers integrate tilt systems rather than deferring to field retrofit. German manufacturers JOST Werke specialize in direct supply to Stuttgart and Munich production corridors.
- Aftermarket:Service contract unbundling is fragmenting traditional relationships as fleet maintenance providers separate parts procurement from labor scheduling. Independent networks in the United States establish direct sourcing relationships with component manufacturers.
- Retrofit:Pre-2015 commercial vehicles lack CAN bus architecture compatibility, fragmenting product development and inventory requirements.
- Custom:Specialty vehicle builders and modification shops specify non-standard stroke lengths and mounting geometries.
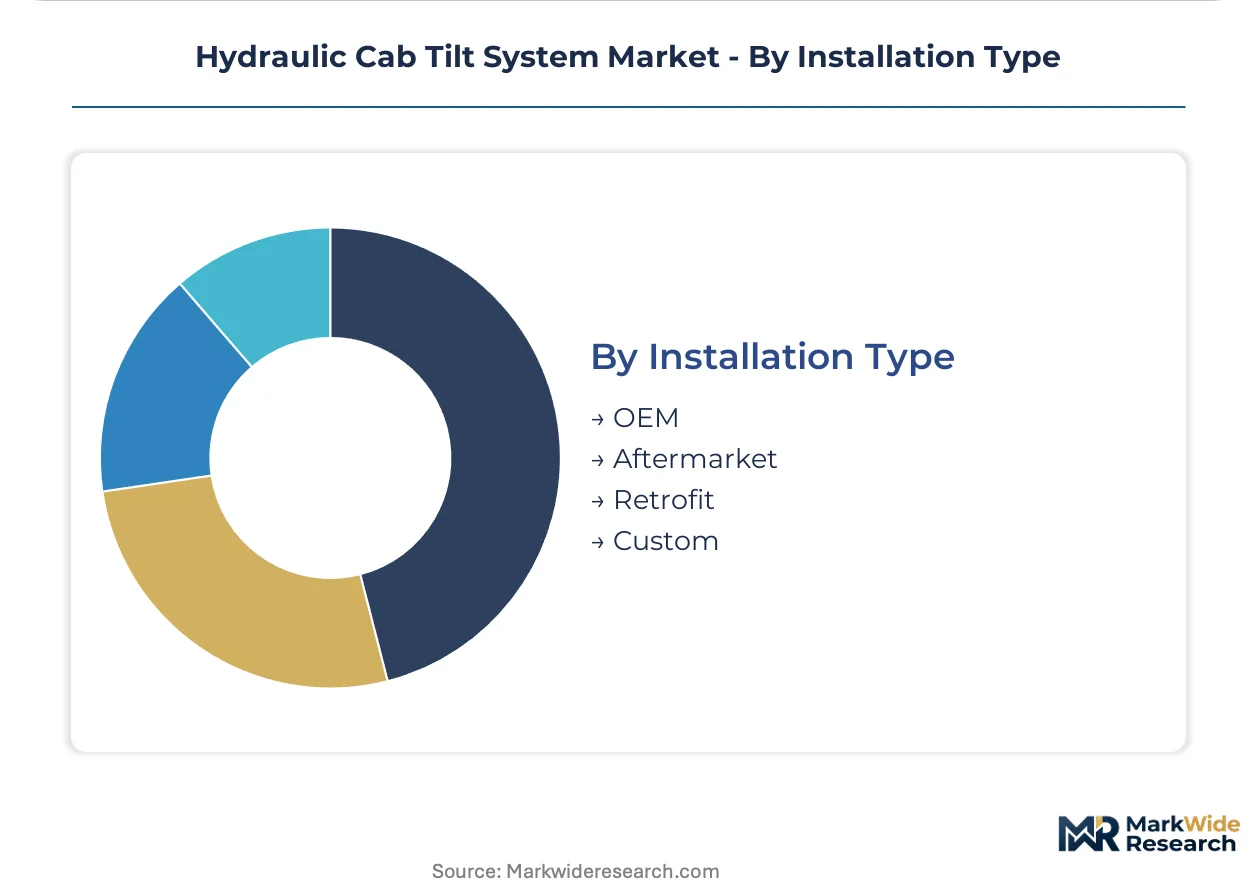
OEM installation leads by unit volume. Aftermarket channels are expanding most quickly as fleet lifecycle extension programs proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fleet operators tilt cabs three times more frequently than North American counterparts due to denser service networks and stricter inspection intervals, while Brazilian buyers prioritize single-cylinder simplicity over electronic feedback systems.
United States
Long-haul trucking fleets operating 70-degree tilt specifications drive specification intensity. NHTSA crashworthiness mandates compel Detroit-based OEMs to engineer lighter cab structures with factory-integrated mechanisms. Independent service networks in Ohio and Texas establish direct sourcing relationships with hydraulic component manufacturers.
Germany
Heavy-duty tractor programs exceeding 800-kilogram cab weights demand twin-actuator redundancy. KBA vehicle safety protocols mandate position feedback integration for new type approvals. Stuttgart and Munich industrial corridors concentrate critical casting and machining capacity for European supply chains.
Brazil
Mid-range truck assemblers specify centralized single-cylinder architectures to contain acquisition costs. ANVISA safety regulations create compliance whitespace beyond established European supply chains. São Paulo state production clusters expand domestic assembly capacity for South American distribution.
China
Battery-electric commercial vehicle platforms require redesigned cab mounting systems accommodating high-voltage isolation. MIIT new energy vehicle mandates accelerate electrification timelines for heavy-duty segments. Yangtze River Delta manufacturing bases prototype electro-hydraulic integrated modules.
Sweden
Scandinavian heavy-duty OEMs prioritize uptime-critical redundancy characteristics for Arctic operating conditions. EU CO2 regulations for heavy-duty vehicles mandate aerodynamic cab designs with constrained hinge geometries. Gothenburg production corridors anchor Nordic supply chain integration for tilt system specification.
Hydraulic Cab Tilt System Market Competitive Environment
Capability concentration sits with fluid power specialists commanding aftermarket distribution density; scale advantage sits with diversified industrial conglomerates supplying captive OEM channels. The vendor base separates into three strategic archetypes: integrated mechatronics developers, pure-play hydraulic component fabricators, and construction equipment OEMs with captive tilt system production. Dominant competitive moves include geographic localization beyond German supply corridors and functional safety certification investments creating switching costs.
Within the fluid power specialist tier, Parker Hannifin Corporation and Haldex exemplify aftermarket channel dominance through dense service network coverage. Parker Hannifin Corporation represents the diversified industrial conglomerate archetype with cross-sector fluid power portfolio leverage. Haldex occupies a position anchoring European aftermarket distribution. JOST Werke sits within the German supply chain specialist category, reflecting Stuttgart-Munich production corridor concentration.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Caterpillar Inc. |
| Wipro Infrastructure Engineering |
| Haldex |
| Power-Packer |
| Bendix Commercial Vehicle Systems |
| WABCO |
| JOST Werke |
| Volvo Trucks |
| Others |
Value Chain & Pricing Dynamics
German casting and machining capacity clustering around Stuttgart and Munich industrial corridors concentrates upstream supply leverage, directing margin capture toward OEM factory installation channels rather than fragmented aftermarket retrofit tiers. This geographic concentration enables tier-1 suppliers to command pricing premiums for synchronized twin-actuator configurations while squeezing single-cylinder fabricators competing on acquisition cost.
Pricing Analysis
Long-term offtake agreements dominate procurement between heavy-duty truck OEMs and hydraulic system integrators, with spot purchasing confined to aftermarket seal kits and emergency cylinder replacements. Price differentiation separates ISO 26262-certified electronic control modules from basic hydraulic architectures lacking position feedback integration. Pricing pressure stems from electromechanical substitution in sub-500 kilogram cab applications where screw jack alternatives undercut hydraulic power density economics. Fleet operators in Brazil and India exhibit highest price sensitivity, specifying centralized single-cylinder architectures, while German and Scandinavian premium tractor programs absorb twin-actuator premiums for redundancy assurance.
Supply Chain Analysis
Tariff exposure between China and North America disrupts electro-hydraulic integrated module sourcing as Yangtze River Delta manufacturing bases prototype next-generation architectures. Critical supply draws from Germany, China, and Brazil, with cylinder barrel steel, piston rod alloys, and high-pressure sealing compounds anchoring bill-of-materials volatility. Single-source vulnerability concentrates in German precision casting capacity serving Stuttgart-Munich production corridors. Distribution runs through captive OEM supply chains for factory installation, while independent service networks in the United States establish direct component sourcing relationships bypassing traditional distribution tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial vehicle production cycles are recovering from cyclical troughs as fleet replacement deferrals exhaust and NHTSA crashworthiness mandates accelerate cab redesign programs across North American and European OEM platforms.
For Market Incumbents: Build certification moats around ISO 26262 functional safety compliance for electronic-hydraulic control modules, creating switching costs against uncertified competitors. Deepen backward integration into precision casting capacity within German industrial corridors to defend against energy cost shocks and labor disruptions. Secure long-term offtake agreements with Brazilian and Chinese commercial vehicle assemblers to anchor volume visibility amid electromechanical substitution threats in lightweight cab segments. For New Entrants and Emerging Players: Pursue whitespace in Brazilian mid-range truck assembly where ANVISA safety regulations create compliance entry points beyond established European supply chain incumbents. Target sensor-integrated smart cylinder architectures for predictive maintenance service contracts, capturing recurring revenue streams that pure hardware vendors cannot match. Establish direct sourcing relationships with independent fleet maintenance networks in the United States where channel disintermediation fragments traditional OEM captive distribution. For Investors and Strategic Acquirers: Capital is best deployed toward electro-hydraulic integrated module developers possessing mechatronics competence mandatory for next-generation electric vehicle platform specifications. Long-term viability hinges on supplier positioning within battery-electric commercial vehicle redesign cycles rather than legacy internal combustion aftermarket exposure. Monitor specification share capture in Chinese MIIT new energy vehicle mandate programs as the critical inflection signal for technology migration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 26262 Functional Safety Certification | Electronic control modules meeting automotive safety integrity levels command pricing premiums against uncertified competitors. |
| Electro-Hydraulic Integrated Module Development | Combined pump-motor-controller units eliminate separate reservoirs for electric vehicle packaging constraints. |
| Brazilian Supply Chain Localization | ANVISA safety regulations and expanding domestic truck assembly create whitespace beyond European incumbents. |
| Sensor-Integrated Smart Cylinder Launch | Position feedback transducers enable predictive maintenance offerings capturing recurring service revenue streams. |
| Backward Integration into Precision Casting | In-house cylinder barrel production defends margin compression from steel and aluminum commodity volatility. |
Study Parameters
The analysis maps hydraulic cab tilt system architectures across double-cylinder, single-cylinder, pneumatic, and electric configurations, each validated through interviews with OEM platform engineers, aftermarket service directors, fleet maintenance managers, and hydraulic component procurement leads. Primary fieldwork combined with secondary validation from SEC 10-K filings, commercial vehicle production databases, EPA and NHTSA regulatory dockets, and customs trade data established demand quantification. Bottom-up unit shipment modeling triangulated against top-down market value reconstruction to ensure segmentation consistency.
Assumptions held fixed include NHTSA crashworthiness mandate enforcement timelines, EPA Phase 3 greenhouse gas standard compliance trajectories, and MIIT new energy vehicle penetration rates for heavy-duty segments, while commodity price volatility and electromechanical substitution velocity were treated as scenario variables across the projection horizon. Segmentation dimensions modeled encompass product type, end-user industry, technology tier, and installation channel, with CAGRs derived from regression analysis of historical production volumes and OEM platform lifecycle timing. Industry-specific forecast inputs incorporated fleet lifecycle extension program prevalence and construction equipment electrification capital expenditure patterns.
Macroeconomic conditions sit as an overlay; deviation in commercial vehicle production cycles, steel and aluminum commodity pricing, or German industrial energy costs would shift the trajectory materially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electro-Mech Systems
Rigid Metal Electrical Conduit Market
Electro-Mech Systems
Movable Scaffolding System Market
Electro-Mech Systems
Electric Overhead Travelling (EOT) Cranes Market
Electro-Mech Systems
Light Gauge Framing System Market
Electro-Mech Systems
HVAC Relay Market
Electro-Mech Systems
Wiring Duct Market
Electro-Mech Systems
Agitator Drive Units Market
Electro-Mech Systems
Mechanical Auger Boring Machine Market
Electro-Mech Systems
Tubular Motors Market
Electro-Mech Systems
Escalators and Moving Walkways Market
Electro-Mech Systems
Electric Winch Market
Electro-Mech Systems
Elevator Door-Motor Market
Electro-Mech Systems
Rodless Cylinders Market
Electro-Mech Systems
Automatic Slack Adjusters Market