
 Mobile Conveyor Market | 2026-2036
Mobile Conveyor Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Conveyor Market Analytics
Germany's industrial belt is tilting toward automated material-handling infrastructure, with Siemens Logistics leveraging its control-system expertise to anchor high-throughput port installations. Terex Corporation competes through rugged chassis designs purpose-built for quarry terrain, while Daifuku Co., Ltd. specializes in modular sortation architecture that extends across Asian distribution centers.
A mobile conveyor is a self-propelled or towable belt-transport system engineered to move bulk or unitized loads across variable distances, typically rated for throughputs exceeding 500 tonnes per hour with incline capabilities up to 20 degrees. Its primary industrial purpose is to eliminate fixed infrastructure costs while enabling rapid redeployment between extraction faces, stockpiles, or loading vessels. Telescopic product types dominate margin pools in mining export terminals where vessel-loading precision commands premium pricing, while electric technology leads growth trajectories as port operators phase out diesel hydraulics under carbon-reduction mandates. Foldable designs occupy the fastest-expanding niche in construction waste recycling where site access constraints demand compact transport footprints.
MSHA governs dust-exposure limits and emergency-stop spacing for US mining deployments, while the EU Green Deal's F-Gas Regulation restricts hydraulic refrigerants in European-built mobile equipment, redirecting procurement toward all-electric drivetrains. China's GB standards mandate brake-system redundancy and operator visibility zones for domestic port machinery, creating certification barriers for non-compliant imports. Stakeholders must weigh regional certification divergence against platform standardization economics when configuring global product portfolios.
Market Dynamics
Carbon-reduction mandates across port authorities are compressing equipment replacement cycles, forcing operators to retire diesel-hydraulic units ahead of schedule and absorb premature depreciation costs.
Growth Catalysts
- EU F-Gas Regulation:The phase-down of hydrofluorocarbon refrigerants in European mobile equipment is redirecting procurement toward all-electric drivetrains, expanding addressable market for zero-emission conveyor manufacturers.
- Telescopic vessel-loading systems:Mining export terminals in Australia and Chile are specifying precision-loading units to minimize demurrage penalties and maximize bulk carrier utilization rates.
- E-commerce logistics clusters:China's inland port hubs require rapid container-loading mobility to synchronize with automated sortation infrastructure, pulling demand for foldable electric conveyors.
Market Restraints
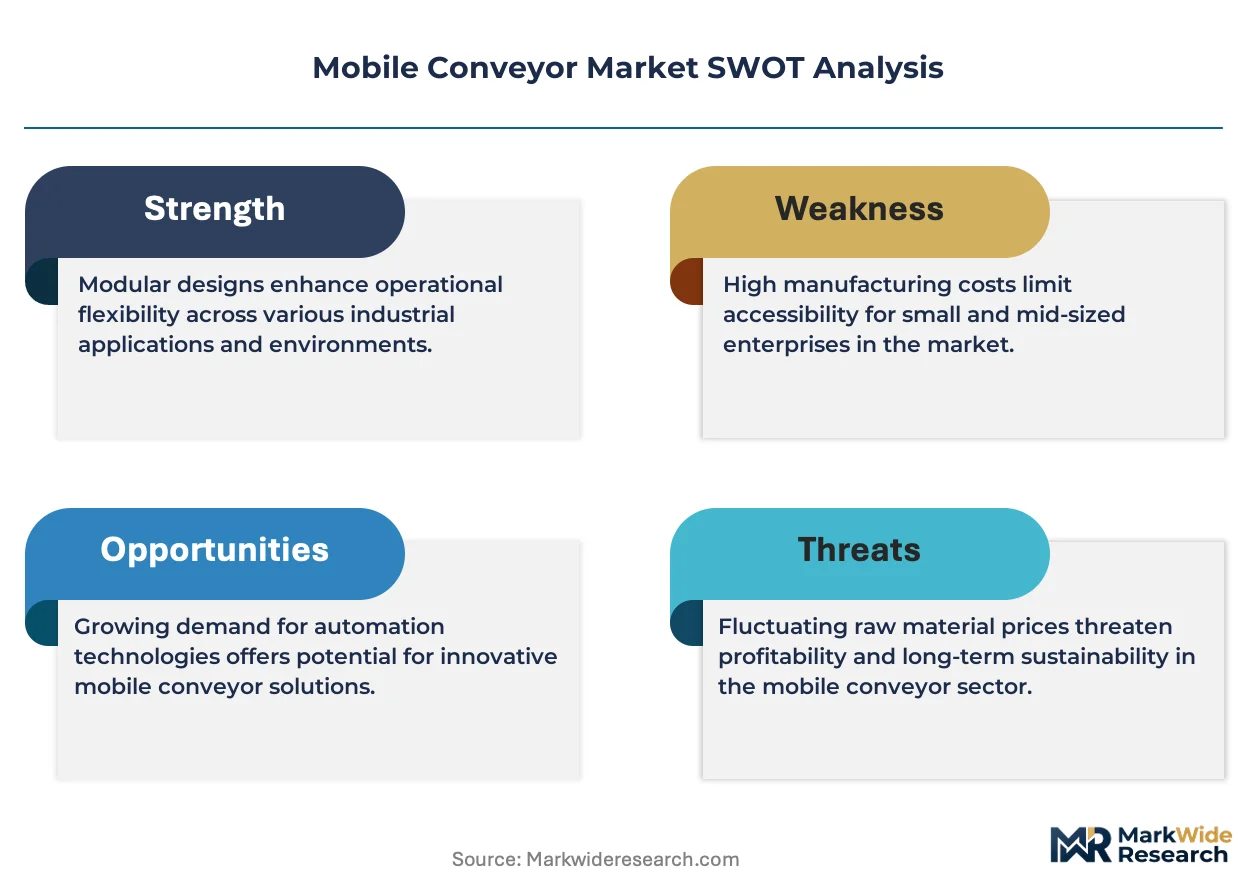
- High-grade steel input volatility:Chassis fabrication depends on specialized abrasion-resistant plate grades subject to mining-sector demand spikes and energy-intensive production constraints.
- Certification divergence:China's GB brake-redundancy standards create non-tariff barriers for non-compliant imports, fragmenting global platform economics.
- Fixed infrastructure substitution:Permanent overland conveyors and rail spurs retain total-cost advantages on long-haul routes exceeding five kilometers, capping mobile system addressable share.
Strategic Opportunities
- Construction waste recycling:Site access constraints in urban demolition projects favor compact foldable designs with sub-three-meter transport widths, an underpenetrated application vertical.
- US MSHA dust-emission rules:Stricter exposure limits for respirable silica are mandating enclosed electric-drive architectures, creating specification pull for sealed-belt manufacturers.
- Remanufacturing services:Equipment-as-a-service models combining telemetry-based predictive maintenance with component remanufacturing are penetrating European quarry operations seeking capital preservation.
Industry Challenges
- Electromechanical integration complexity:Retrofitting legacy diesel chassis with battery-electric powertrains requires recalibration of weight distribution and brake-system redundancy, extending engineering timelines.
- Multi-jurisdiction certification timelines:Simultaneous compliance with US MSHA emergency-stop spacing, EU machinery directives, and Chinese GB visibility zones stretches type-approval cycles by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Conveyor Market |
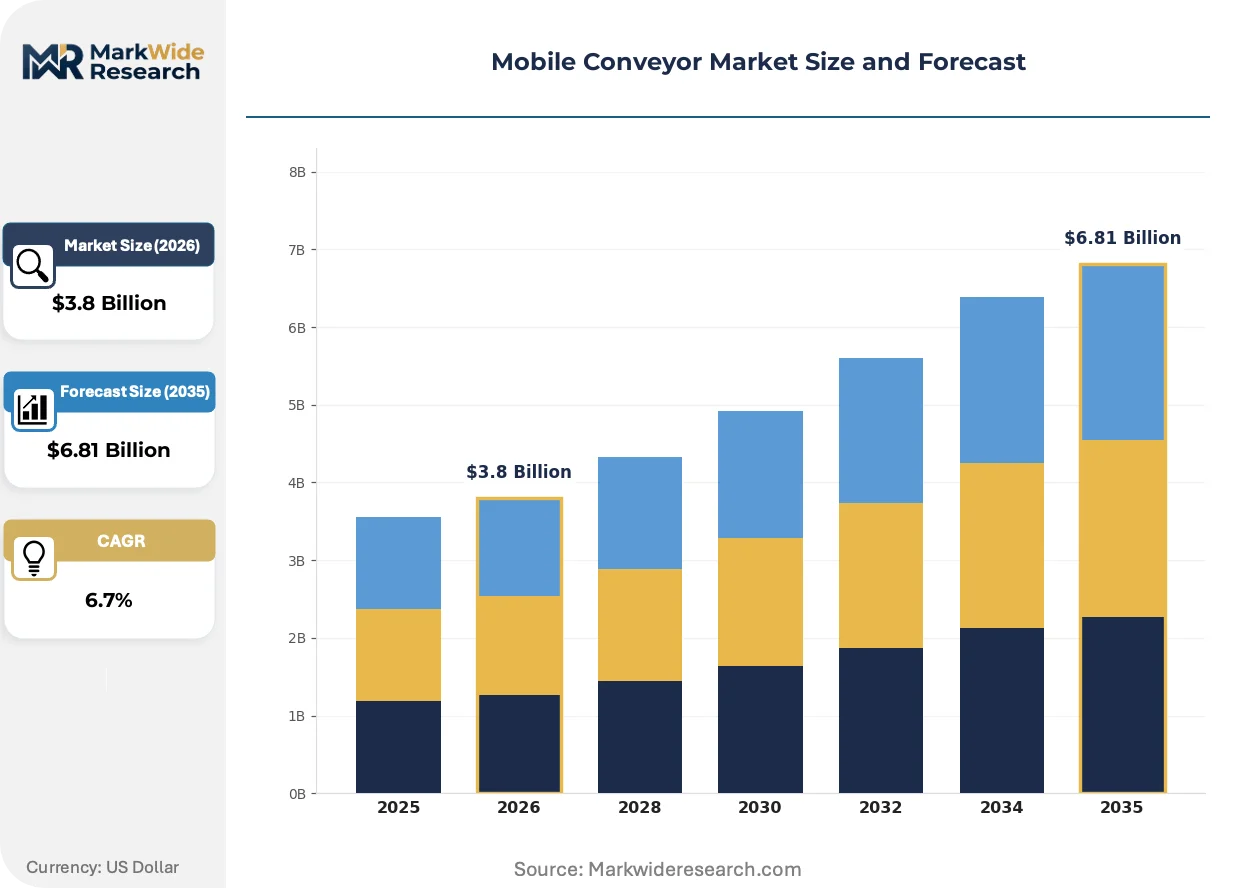
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telescopic, Foldable, Standard, Modular End User: Mining, Construction, Agriculture, Logistics Technology: Electric, Hydraulic, Pneumatic, Gravity Installation: Fixed, Portable, Semi-Fixed, Mobile |
| Companies Covered | Siemens Logistics, Terex Corporation, Daifuku Co., Ltd., Telestack, Metso Outotec, Continental AG, KION Group, SANDVIK AB, Honeywell Intelligrated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Conveyor Market Evolving Landscape
Electrification architectures and predictive maintenance platforms are redefining equipment lifecycle economics, while regulatory pressure on emissions intensifies specification divergence across geographies.
Battery-electric drivetrain technology is migrating from auxiliary power units to full traction and conveyor-belt propulsion in port applications. European terminal operators in Rotterdam and Hamburg are specifying lithium-ion packs with opportunity-charging infrastructure to eliminate diesel particulate exposure in enclosed vessel holds. This shift is compressing the residual value of second-hand hydraulic units and fragmenting secondary market liquidity.
The EU Green Deal's F-Gas Regulation is prohibiting hydrofluorocarbon refrigerants in mobile equipment hydraulic systems starting with the next equipment generation. German and Dutch manufacturers are accelerating sealed electromechanical actuator development to replace refrigerant-dependent cooling circuits. Port machinery in Northern Europe is experiencing the most acute specification pressure, with procurement committees now weighting carbon intensity scores above upfront capital cost.
Telemetry-enabled condition monitoring is replacing scheduled maintenance intervals with predictive component replacement. Mining operators in Western Australia are unbundling after-sales service contracts and procuring uptime guarantees directly from conveyor OEMs, transferring operational risk to equipment suppliers. This behavioral shift is most visible in high-throughput bulk export terminals where unplanned downtime costs exceed five figures hourly.
Mobile Conveyor Market Segmentation
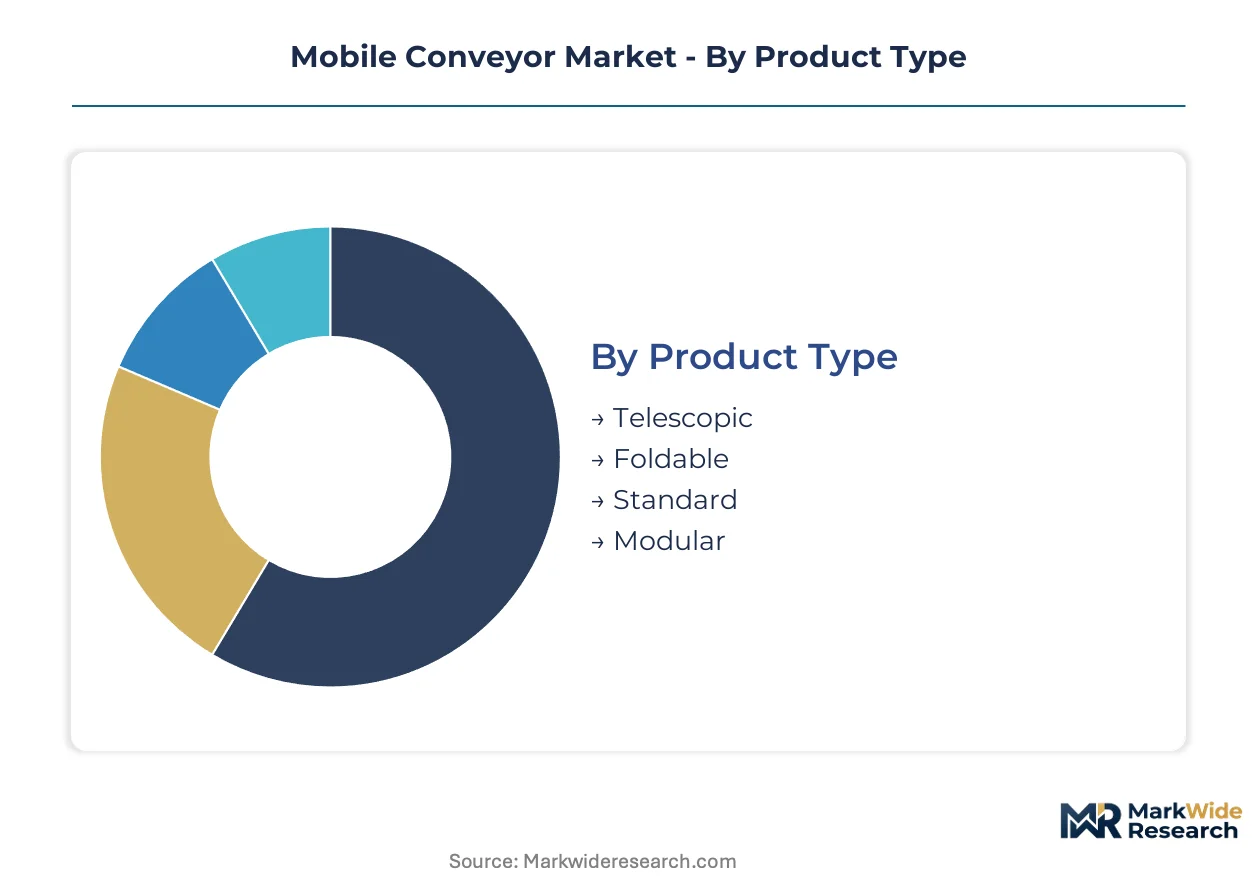
Mobile conveyor segmentation reveals divergent service intensity patterns across product architectures. Telescopic systems demand intensive predictive maintenance contracts, while foldable units concentrate replacement-part revenue in aftermarket channels.
Product Type:
After-sales-service intensity varies sharply across product architectures, with precision-loading systems requiring continuous calibration support and compact designs relying on modular component swaps.
- Telescopic:Extendable boom configurations achieve vessel-loading precision through multi-stage hydraulic or electromechanical extension. Mining export terminals in Australia specify these units to minimize demurrage penalties during bulk carrier loading. Service contracts bundle laser-alignment calibration with wear-component replacement.
- Foldable:Articulated frame designs collapse to sub-three-meter transport widths for urban demolition site access. Construction waste recycling operators in China's Yangtze River Delta favor these for rapid deployment between confined job sites. Component modularity enables field repairs without crane support.
- Standard:Fixed-length belt systems serve baseline quarry and aggregate applications with minimal customization requirements.
- Modular:Sectional belt-truss assemblies permit length reconfiguration between extraction faces and stockpiles.
By volume, Standard systems lead. By growth pace, Foldable designs are climbing the fastest.
End User:
Customer procurement sophistication separates mining's uptime-guarantee contracting from construction's spot-rental economics.
- Mining:Bulk ore transport demands throughputs exceeding 500 tonnes per hour with abrasion-resistant belting. Western Australian iron ore operators unbundle maintenance contracts and procure availability guarantees directly from OEMs. Predictive telemetry transfers operational risk to equipment suppliers.
- Logistics:E-commerce hub synchronization requires rapid container-loading mobility matched to automated sortation infrastructure. China's inland port clusters specify electric foldable units for cross-dock flexibility. Procurement committees weight carbon intensity scores above upfront capital cost.
- Construction:Quarry and demolition applications favor rental fleets with rapid redeployment between project phases.
- Agriculture:Grain handling and fertilizer distribution utilize lower-duty cycle equipment with seasonal utilization patterns.
By installed base, Mining dominates. By specification change velocity, Logistics is gaining share fastest.
Technology:
Powertrain selection determines residual value trajectory and secondary market liquidity across port and mining deployments.
- Electric:Battery-electric and grid-tethered drivetrains eliminate diesel particulate exposure in enclosed vessel holds. Rotterdam and Hamburg terminal operators specify lithium-ion packs with opportunity-charging infrastructure. The EU F-Gas Regulation accelerates sealed electromechanical actuator development to replace refrigerant-dependent cooling circuits.
- Hydraulic:Diesel-hydraulic systems retain installed base dominance in remote mining sites lacking charging infrastructure. Residual values are compressing as carbon-reduction mandates force premature retirement.
- Pneumatic:Compressed-air propulsion serves specialized explosive-environment applications with spark-free operation requirements.
- Gravity:Decline-angle bulk transport eliminates power consumption for downhill material flow.
By current fleet share, Hydraulic leads. By procurement momentum, Electric shows the steepest expansion trajectory.
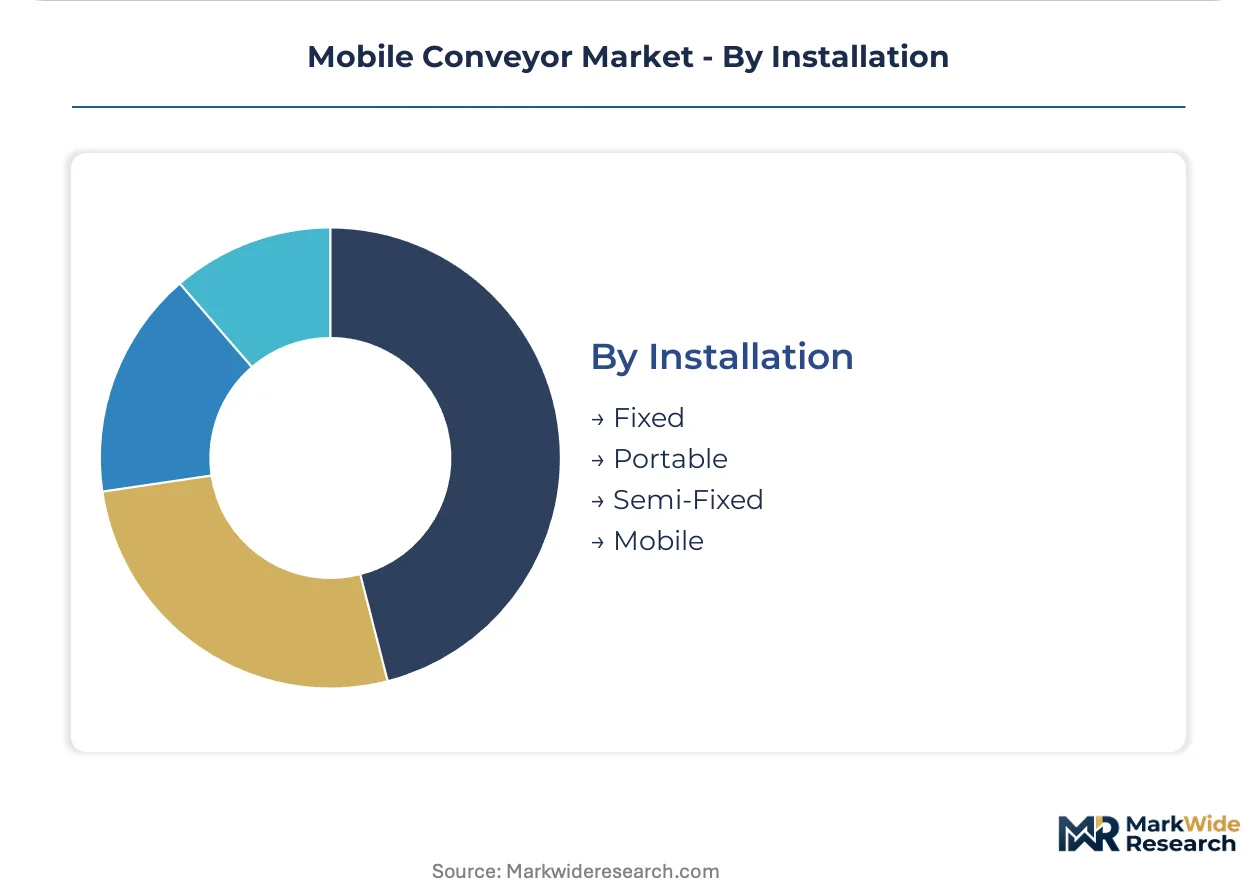
Installation:
Mobility classification determines transport logistics cost structure and site-permitting complexity.
- Mobile:Self-propelled crawler or wheeled chassis enable autonomous relocation between extraction faces without external haulage. High capital cost is offset by elimination of fixed infrastructure and rapid redeployment flexibility.
- Portable:Towable or skid-mounted configurations require external transport but permit lighter chassis construction. Construction waste recycling favors these for truck-mounted deployment to urban demolition sites.
- Semi-Fixed:Modular foundations permit seasonal repositioning with limited crane support.
- Fixed:Permanent installations compete with overland conveyors on routes exceeding five kilometers.
By unit shipments, Portable systems lead. By margin expansion, Mobile configurations are advancing most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering houses and Australian mining contractors dominate high-specification manufacturing, while Chinese fabricators capture volume production for inland port logistics. Component supply chains radiate from specialized steel mills in the Ruhr Valley and conveyor-belt specialists in Osaka.
United States
Surface mining operators in the Powder River Basin are replacing legacy diesel-hydraulic fleets ahead of MSHA enforcement deadlines. The EPA's Tier 4 Final emission standards for non-road equipment are accelerating electric-drivetrain procurement timelines. Pittsburgh-based engineering consultants are specifying enclosed-belt architectures for Appalachian coal loadout terminals.
Australia
Iron ore exporters in the Pilbara region are unbundling maintenance contracts and procuring uptime guarantees directly from OEMs. The country's national mining regulator mandates emergency-stop spacing and brake-system redundancy for autonomous haulage integration. Port Hedland's bulk export terminals specify telescopic vessel-loading systems to minimize demurrage penalties.
China
E-commerce logistics hubs in the Yangtze River Delta require rapid container-loading mobility synchronized with automated sortation infrastructure. GB standards mandate brake-system redundancy and operator visibility zones for domestic port machinery, creating certification barriers for non-compliant imports. Ningbo-Zhoushan port cluster operators are specifying foldable electric conveyors for cross-dock flexibility.
Germany
Port terminal operators in Hamburg and Rotterdam are specifying lithium-ion battery packs with opportunity-charging infrastructure to eliminate diesel particulate exposure. The EU F-Gas Regulation prohibits hydrofluorocarbon refrigerants in mobile equipment hydraulic systems, redirecting procurement toward sealed electromechanical actuators. Ruhr Valley steel fabricators supply abrasion-resistant chassis plate to mining OEMs worldwide.
Chile
Copper mining consortiums in the Atacama Desert are expanding fleet orders for telescopic units to handle bulk ore transport from remote extraction faces. The country's national mining regulator enforces dust-exposure limits comparable to MSHA standards, favoring enclosed conveyor designs. Antofagasta's export terminals specify precision-loading equipment to maximize bulk carrier utilization rates.
Mobile Conveyor Market Competitive Landscape
Systems integrators and component specialists split the market along the engineering-versus-fabrication divide. Siemens Logistics anchors the control-system tier through port automation integration, while Terex Corporation occupies the rugged-chassis segment purpose-built for quarry terrain. Consolidation pressure is intensifying as carbon-reduction mandates force equipment replacement cycles and compress residual values of legacy hydraulic fleets.
Within the premium-tier vector, Siemens Logistics and Daifuku Co., Ltd. exemplify divergent specialization paths. Siemens leverages German engineering heritage to anchor high-throughput port installations with integrated control architectures. Daifuku occupies a position within Asian distribution center automation, representing the modular sortation archetype that extends across logistics hubs. Terex Corporation sits within the North American rugged-equipment tradition, its corporate structure reflecting decades of quarry-focused product development. These three anchors illustrate how geographic origin and corporate history shape competitive positioning without requiring identical capability portfolios.
| Leading Market Players |
|---|
| Siemens Logistics |
| Terex Corporation |
| Daifuku Co., Ltd. |
| Telestack |
| Metso Outotec |
| Continental AG |
| KION Group |
| SANDVIK AB |
| Honeywell Intelligrated |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese steel fabrication is compressing chassis margins while concentrating procurement leverage among Australian and Chilean mining operators who bundle fleet orders. This utilization asymmetry forces European and North American manufacturers to absorb premium-grade steel input volatility or cede volume to lower-cost fabricators.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across European port machinery procurement. Three-tier pricing structure across premium, standard, and economy levels separates sealed electromelectric actuator systems from refrigerant-dependent hydraulic units from basic diesel configurations. Cost compression in mid-tier electric conversions is intensifying because battery-pack integration requires recalibration engineering. Logistics operators in China's inland port clusters demonstrate highest price sensitivity, while Australian iron ore exporters prioritize uptime guarantees over capital cost.
Supply Chain Analysis
Ruhr Valley steel fabricators and Osaka conveyor-belt specialists hold concentrated capacity for abrasion-resistant chassis plate and specialized belting. Component sourcing draws from Germany, Japan, and China for precision actuators, high-tensile belting, and lithium-ion powertrains. Single-source vulnerability runs through Japanese specialty steel mills serving mining-grade applications. Distribution runs through OEM-direct contracting for large mining fleets and rental-fleet intermediaries for construction applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile conveyor procurement is shifting toward equipment-as-a-service platforms where telemetry interoperability determines supplier lock-in. This ecosystem inflection rewards control-system integrators who can embed predictive maintenance APIs across heterogeneous fleet architectures.
For Market Incumbents: Pre-empt margin erosion in hydraulic legacy fleets by accelerating sealed electromechanical actuator development before EU F-Gas prohibitions take full effect. Consolidate aftermarket service contracts into bundled uptime guarantees to capture recurring revenue streams and raise switching costs for Australian mining operators.
For New Entrants and Emerging Players: Establish a beachhead in construction waste recycling by offering foldable electric units with sub-three-meter transport widths and field-repairable component modularity. Target China's Yangtze River Delta demolition contractors through rental-fleet partnerships rather than direct OEM sales.
For Investors and Strategic Acquirers: Long-term, this sits as a carbon-transition infrastructure play because port authority decarbonization mandates are compressing replacement cycles and fragmenting secondary market liquidity for diesel-hydraulic assets. Monitor MSHA enforcement timelines and EU carbon-border adjustment mechanisms as inflection signals for electric-drivetrain adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Sealed Electromechanical Actuator Development | Eliminates F-Gas refrigerant dependency for EU Green Deal compliance in Hamburg and Rotterdam terminals. |
| Predictive Maintenance Platform Integration | Enables uptime-guarantee contracting with Western Australian iron ore operators transferring operational risk. |
| Foldable Chassis Miniaturization | Captures urban demolition site access constraints in China's Yangtze River Delta recycling clusters. |
| Battery-Electric Powertrain Retrofit | Addresses MSHA dust-emission rules for Appalachian coal loadout terminals seeking enclosed architectures. |
| Remanufacturing Service Capability | Preserves capital for European quarry operators facing compressed residual values on hydraulic legacy fleets. |
Research Methodology
The analysis maps telescopic vessel-loading systems, foldable urban demolition units, and modular quarry configurations, each validated through maintenance directors at mining export terminals, port authority procurement committees, construction fleet rental managers, and aftermarket service heads. Primary interview insights were cross-referenced against customs trade data, EU machinery directive filings, MSHA enforcement calendars, and OEM SEC disclosures. Bottom-up unit economics were triangulated with top-down port infrastructure investment flows.
Assumptions held fixed include EU F-Gas phase-down timelines, MSHA silica exposure limits, and Chinese GB brake-redundancy certification requirements; variables tested included lithium-ion cell cost curves, high-grade steel input volatility, and autonomous haulage integration adoption rates. Segmentation modeling spanned product architecture, end-use industry, powertrain technology, and mobility classification. CAGRs were derived from installed base turnover analysis and replacement-cycle compression factors across the projection horizon. Industry-specific inputs incorporated demurrage penalty structures at Australian bulk terminals and e-commerce logistics hub synchronization requirements in China.
Stress conditions across steel price spikes, battery supply constraints, and multi-jurisdiction certification delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of port authority carbon-reduction mandate announcements, MSHA enforcement action calendars, and Chinese inland port automation investment flows is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Electric Tugger Market
Material Handling Equipment
East Africa Elevator and Escalator Market
Material Handling Equipment
Wear Plates Market
Material Handling Equipment
Cable Conduit Market
Material Handling Equipment
Conveyor Belt Market
Material Handling Equipment
Global Precision Gearboxes Market
Material Handling Equipment
Pneumatic Caster Market
Material Handling Equipment
Asia-Pacific Conveyors Market
Material Handling Equipment
Hoist Chains Market
Material Handling Equipment
Steel Coil Handling Equipment Market
Material Handling Equipment
Manual Lifting Light Tower Market
Material Handling Equipment
Industrial Elevator Market
Material Handling Equipment
Vibrating Screen Market
Material Handling Equipment
Dust Extractors Market
Material Handling Equipment
Material Handling Automation Market
Material Handling Equipment
Australia Forklift Rental Market