
 Light Duty Telehandler Market | 2026-2036
Light Duty Telehandler Market Size, Share, and Industry Trends Forecast 2026-2036
Light Duty Telehandler Market Outlook
The split between premium and commodity tiers is hardening in concrete terms around boom metallurgy, telematics integration, and after-sales service density. JCB leverages its vertical integration into engine and axle production to command pricing power in the premium rough-terrain segment. Manitou competes through specialized compact architectures purpose-built for European rental fleets with tight yard constraints.
A light duty telehandler is a wheeled material-handling machine with a telescopic boom typically rated below 4,000 kg lift capacity and under 17 meters maximum reach, designed for maneuvering pallets, bulk loads, and personnel platforms across uneven ground. Its primary industrial purpose centers on replacing forklift-truck and crane combinations in confined jobsites where vertical lift and forward reach must operate simultaneously. Rough terrain units anchor the largest revenue pool given their indispensability on construction sites with graded or loose substrates, while electric technology represents the fastest-growing segment as lithium-ion pack costs compress and indoor emission rules tighten. Compact configurations sustain above-average margins by addressing landscaping and urban renovation niches where machine footprint governs equipment selection.
EPA Tier 4 Final and EU Stage V emissions frameworks compel diesel engine redesigns or electrification pivots, directly shaping R&D allocation and factory retooling timelines for manufacturers selling into North America and Europe. OSHA and ISO 16368 standards governing load-chart accuracy and operator protection structures dictate baseline safety architecture and create compliance barriers for new entrants lacking certified testing facilities. Stakeholders must monitor battery supply chain localization progress and regional incentive structures for zero-emission construction equipment to time capital deployment and product portfolio shifts effectively.
Market Dynamics
Electrification mandates and lithium-ion cost compression are forcing simultaneous redesigns of powertrain architecture and fleet financing models across the light duty telehandler sector.
Growth Catalysts
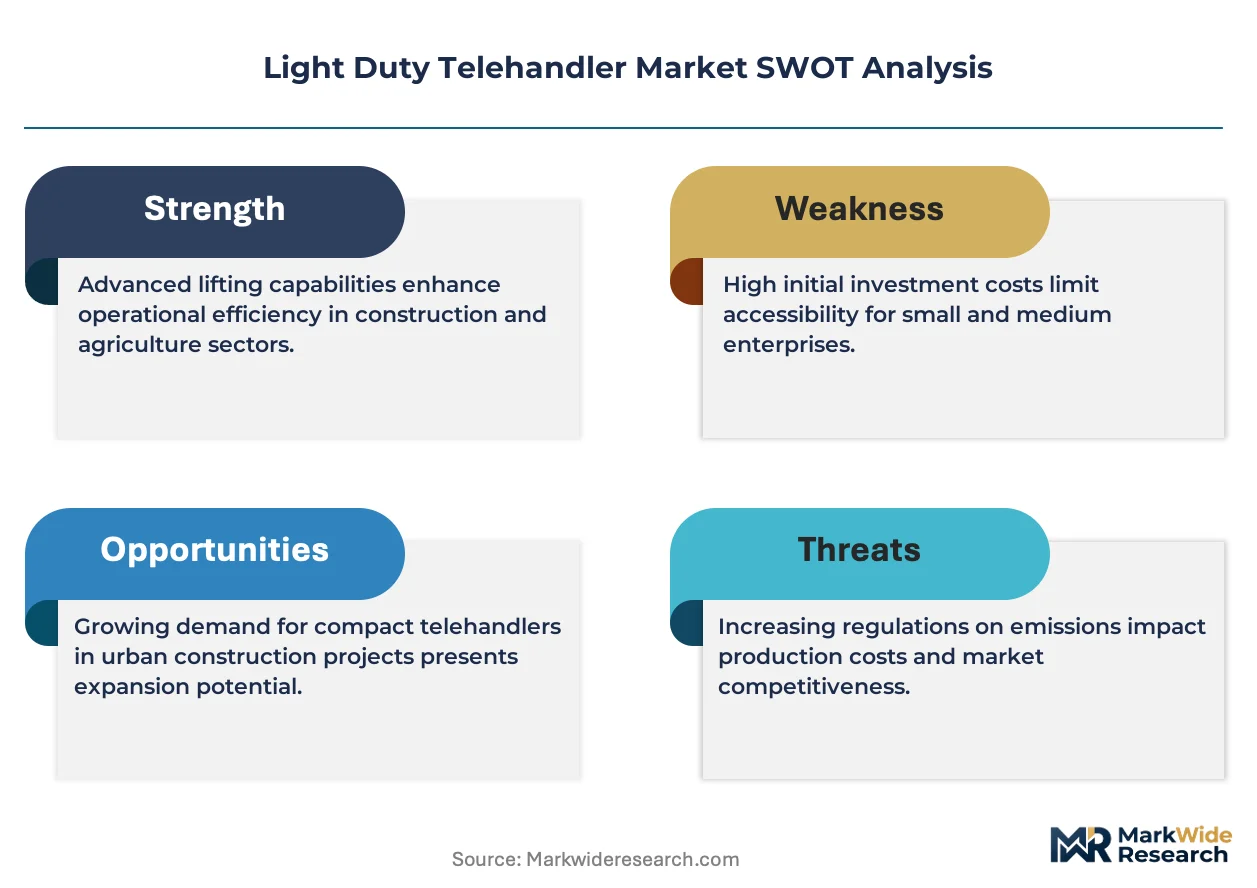
- EPA Tier 4 Final and EU Stage V:Diesel engine redesign requirements accelerate manufacturer investment in electric drivetrains, expanding addressable market into indoor construction and warehousing.
- Rental fleet replacement cycles:Aging equipment in United States and German rental pools drives above-average order volumes for compact configurations with telematics integration.
- Agricultural mechanization:China's subsidy programs for farm equipment upgrade smallholder operations from manual handling to telescopic boom systems.
Market Restraints
- Battery pack cost volatility:Lithium carbonate price swings compress margin visibility for electric variant producers dependent on Asian cell suppliers.
- Certified testing facility scarcity:ISO 16368 load-chart verification capacity concentrates in Germany and the United States, creating queue delays for new entrants.
- Compact loader substitution:Skid-steer loaders with telescopic attachments capture landscaping tenders on upfront price sensitivity.
Strategic Opportunities
- India infrastructure build-out:National highway and rural road programs create first-time demand for rough-terrain units in Tier-2 and Tier-3 construction markets.
- Telematics-as-a-service:Usage-based insurance and predictive maintenance bundles unlock recurring revenue streams from rental fleet operators.
- CE marking fast-track:Modular platform architectures reduce EU conformity assessment timelines for manufacturers with in-house testing capabilities.
Industry Challenges
- Electrification skill gaps:Field technician shortages for high-voltage system diagnostics extend service response times and elevate warranty costs.
- Legacy diesel inventory absorption:Pre-Stage V stock liquidation in European dealer networks depresses residual values and trade-in allowances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light Duty Telehandler Market |
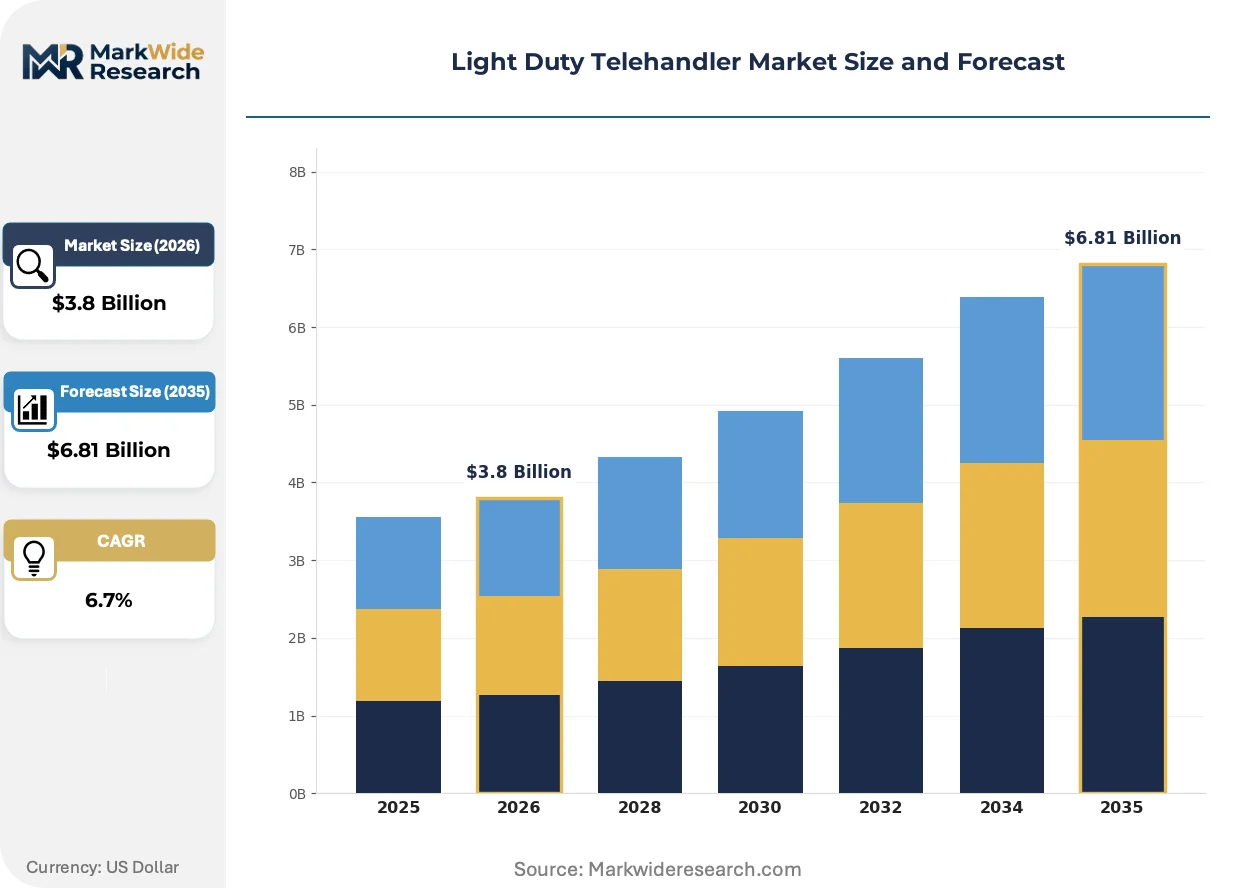
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rough Terrain, High Reach, Compact, Multi-Purpose End User: Construction, Agriculture, Landscaping, Rental Services Application: Material Handling, Lifting Operations, Construction Sites, Agricultural Tasks Technology: Hydraulic, Electric, Diesel, Pneumatic |
| Companies Covered | JCB, Manitou, Merlo, Caterpillar, Bobcat, Liebherr, Wacker Neuson, CNH Industrial, Terex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light Duty Telehandler Market Strategic Shifts
Powertrain electrification, emissions compliance automation, and rental fleet digitization are converging to redefine equipment specifications and ownership economics.
Lithium-ion battery packs with integrated thermal management are consolidating position as the dominant electric architecture for sub-4,000 kg telehandlers. Rental operators in Germany and the Netherlands specify these systems for urban renovation contracts with indoor emission restrictions. Battery swapping protocols and standardized connector geometries are consolidating aftermarket service networks around fewer specialist providers.
EU Stage V real-driving emissions monitoring and EPA onboard diagnostics requirements are mandating telematics integration as factory-standard equipment. Manufacturers must embed cellular connectivity and cloud-based fault logging to satisfy type-approval conditions in North America and Europe. Rough-terrain units destined for cross-border rental deployment now ship with dual-certification firmware to avoid customs delays.
Equipment-as-a-service contracting is displacing traditional term financing for mid-size rental fleets. Operators in the United States negotiate fixed monthly rates inclusive of maintenance and uptime guarantees, transferring residual risk to manufacturers or their captive finance arms. This model concentrates most rapidly in metropolitan construction corridors where utilization transparency justifies the premium pricing structure.
Light Duty Telehandler Market Segmentation
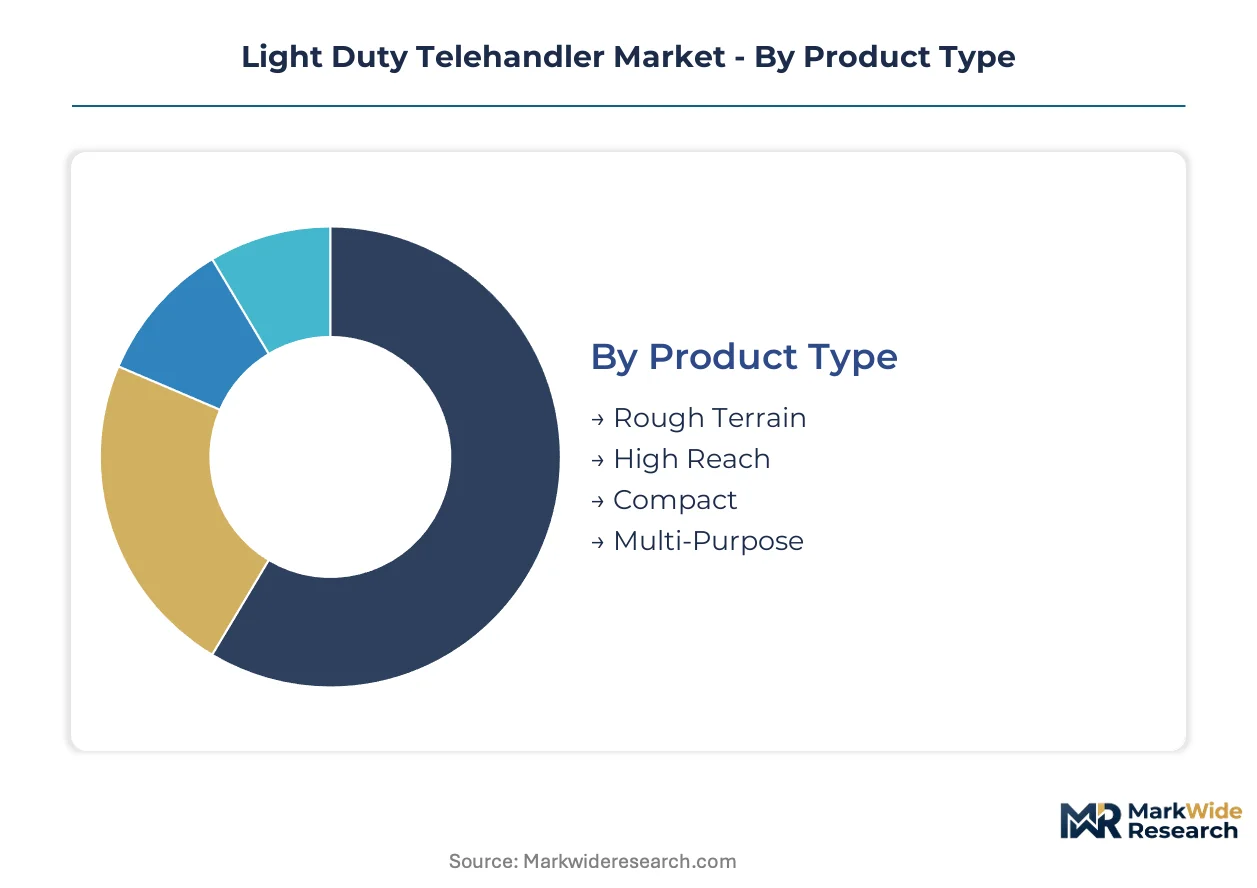
Telehandler procurement patterns diverge sharply across job site constraints, ownership models, and powertrain requirements. Fleet managers select configurations based on substrate conditions, lift envelope needs, and regulatory exposure rather than generic payload ratings.
Product Type:
The customization-vs-standardization spectrum stretches from purpose-built rough-terrain architectures to modular multi-purpose platforms adaptable across attachments.
- Rough Terrain:These units feature oscillating axles, four-wheel-drive differentials, and reinforced booms rated for loose or graded substrates. Construction sites in the United States and Germany absorb the majority of production volume as infrastructure renewal programs accelerate fleet turnover.
- Compact:Machines with sub-2.5 meter width and sub-3,500 kg operating weight dominate European rental yards facing urban yard constraints. Landscaping contractors in the Netherlands specify these for canal-side renovation work where machine footprint governs access.
- High Reach:Extended boom sections exceeding 14 meters maximum lift height serve specialized industrial maintenance and warehouse racking installation.
- Multi-Purpose:Quick-attach carriage systems accommodate forks, buckets, and personnel platforms on a single chassis base.
Most installed capacity flows through Rough Terrain units. Expansion is steepest in Compact configurations.
End User:
Volume concentration tracks capital intensity and equipment utilization economics across ownership models.
- Rental Services:Fleet operators in Germany and the United States negotiate multi-year procurement contracts with telematics integration and uptime guarantee clauses. Telematics-as-a-service bundles unlock recurring revenue streams from usage-based insurance and predictive maintenance contracts.
- Construction:General contractors on metropolitan corridor projects specify electric variants for indoor emission compliance, particularly in Dutch and German urban cores with Stage V restrictions.
- Agriculture:China's subsidy programs for farm mechanization upgrade smallholder operations from manual handling to telescopic boom systems for bulk feed and fertilizer movement.
- Landscaping:Municipal parks departments and private grounds maintenance contractors prioritize compact footprints over lift capacity.
Rental Services channel the highest unit volumes. Agriculture is expanding most quickly.
Application:
Functional requirements determine boom geometry, stability management systems, and attachment compatibility.
- Material Handling:Pallet fork operations with repetitive lift-and-carry cycles dominate warehouse-adjacent construction logistics. Battery-electric systems with regenerative hydraulics reduce energy consumption in high-cycle indoor environments.
- Lifting Operations:Personnel platform work demands load-moment indicators and secondary guarding systems certified to ISO 16368. German rental fleets specify these for wind turbine maintenance and industrial facade access.
- Construction Sites:Rough-terrain mobility with simultaneous vertical lift and forward reach replaces forklift-crane combinations on uneven substrates.
- Agricultural Tasks:Bulk loading of grain, silage, and fertilizer requires high-torque hydraulics and corrosion-resistant finishes.
Material Handling absorbs the majority of machine hours. Lifting Operations is climbing the fastest.
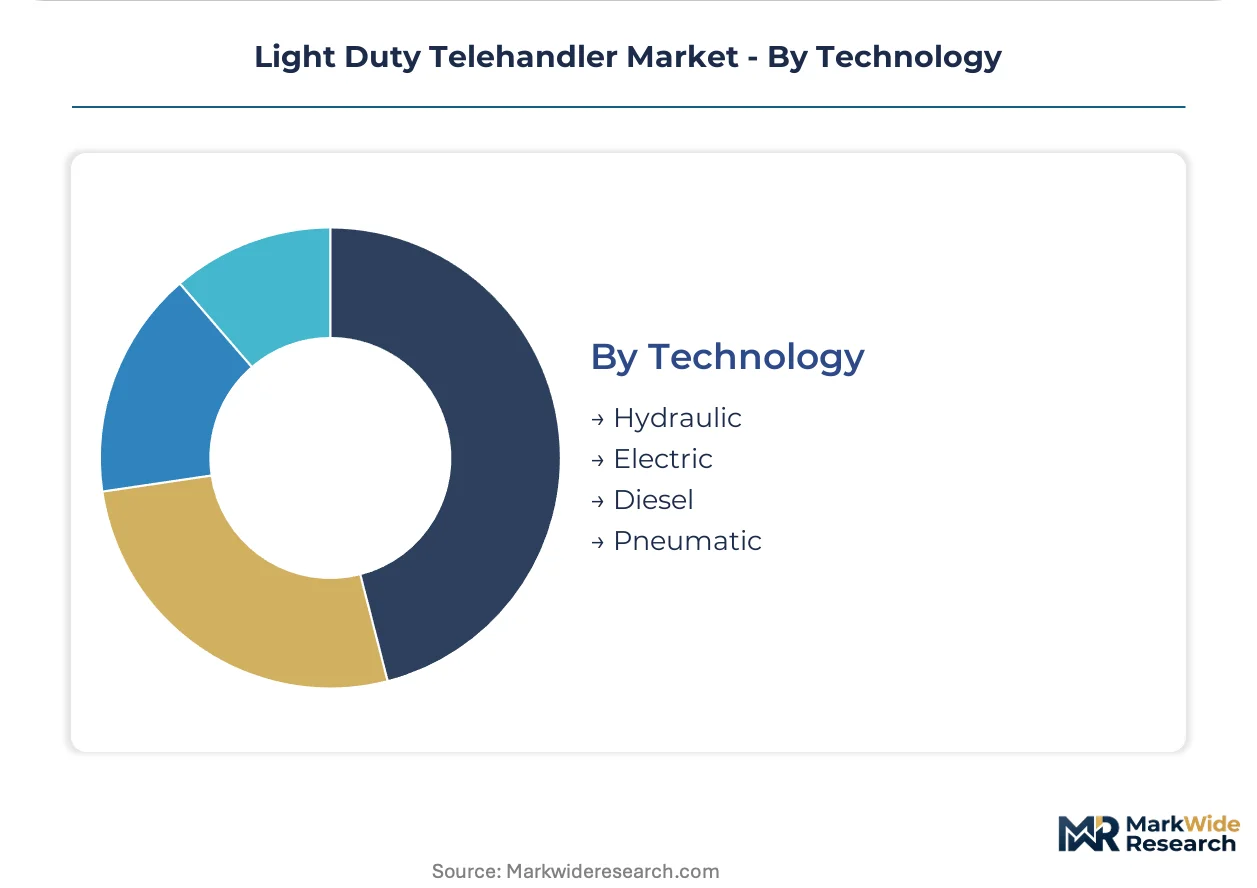
Technology:
Powertrain selection hinges on duty cycle intensity, indoor emission exposure, and total cost of ownership horizons.
- Electric:Lithium-ion packs with integrated thermal management consolidate position for sub-4,000 kg machines. German and Dutch rental operators specify these for urban renovation contracts with indoor emission restrictions.
- Diesel:EPA Tier 4 Final and EU Stage V compliance mandates selective catalytic reduction and diesel particulate filter integration, adding cost and maintenance complexity.
- Hydraulic:Load-sensing circuits with variable displacement pumps remain standard for boom articulation and stabilizer deployment across all powertrain types.
- Pneumatic:Compressed-air actuation serves niche explosive atmosphere applications in chemical processing and mining support roles.
Diesel retains the largest installed base. Electric is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled technicians and certified testing engineers cluster around Stuttgart, Munich, and Chicago, anchoring the industry's technical workforce density in markets where precision manufacturing and regulatory compliance intersect.
United States
Rental fleet operators in Texas and Florida accelerate replacement cycles for aging rough-terrain units as infrastructure renewal contracts multiply. EPA Tier 4 Final compliance mandates drive diesel engine redesigns or electrification pivots among manufacturers supplying the domestic market. Chicago-area construction corridors concentrate demand for compact electric variants with telematics integration.
Germany
Metropolitan renovation projects in Berlin and Hamburg tighten indoor emission restrictions, expanding addressable market for lithium-ion powered machines. EU Stage V real-driving emissions monitoring requires factory-standard telematics and cloud-based fault logging for type approval. Stuttgart's industrial belt hosts ISO 16368 certified testing facilities that create queue delays for new market entrants.
China
Agricultural mechanization subsidies upgrade smallholder operations in Shandong and Henan provinces from manual handling to telescopic boom systems. The country's national farm equipment regulator channels subsidy eligibility toward domestic manufacturers meeting updated safety benchmarks. Yangtze River Delta construction clusters absorb initial volumes of imported rough-terrain architectures for port and logistics infrastructure.
India
National highway and rural road programs generate first-time demand for rough-terrain units in Tier-2 and Tier-3 construction markets across Maharashtra and Karnataka. The Bureau of Indian Standards imposes structural safety certifications that foreign manufacturers must navigate for import clearance. Mumbai-Pune industrial corridor rental yards experiment with compact configurations for urban infrastructure maintenance.
Netherlands
Canal-side renovation contractors in Amsterdam and Rotterdam specify compact telehandlers where machine footprint governs site access. EU Stage V restrictions eliminate pre-certified diesel inventory from cross-border rental deployment. Eindhoven-region equipment distributors consolidate battery swapping service networks around standardized lithium-ion connector geometries.
Light Duty Telehandler Market Competitive Environment
Top-tier vendors anchor premium pricing through captive engine and axle production, while mid-tier specialists compete on modular platform architectures and regional certification speed. The vendor base organizes around three strategic archetypes: vertically integrated rough-terrain specialists, compact-configuration rental fleet suppliers, and electrification-focused urban equipment providers. Consolidation pressure intensifies as M&A activity targets telematics capabilities and battery supply chain integration.
Within the integrated manufacturing tier, JCB and Manitou exemplify divergent competitive positioning. JCB anchors premium rough-terrain positioning through in-house production of powertrain components. Manitou occupies a specialist role purpose-building compact architectures for European rental constraints. Merlo represents the mid-tier archetype competing on multi-purpose platform flexibility.
| Leading Market Players |
|---|
| JCB |
| Manitou |
| Merlo |
| Caterpillar |
| Bobcat |
| Liebherr |
| Wacker Neuson |
| CNH Industrial |
| Terex |
| Others |
Value Chain & Pricing Dynamics
Certified telematics engineers and ISO 16368 testing specialists cluster around Stuttgart and Chicago, anchoring labor-cost premiums that widen spreads between premium rental-grade configurations and bare-unit commodity sales.
Pricing Analysis
Bundled equipment-as-a-service contracts now compete with unbundled machine-only transactions across German and United States rental markets. Three-tier pricing structure across premium, standard, and economy levels separates telematics-integrated uptime guarantees from basic rough-terrain units with limited after-sales coverage. Cost compression in electric drivetrain tiers is intensifying because lithium carbonate volatility squeezes margin visibility for manufacturers dependent on Asian cell suppliers. Municipal landscaping departments exhibit highest price sensitivity, while metropolitan rental fleet operators absorb premium pricing for predictive maintenance bundles.
Supply Chain Analysis
Dual-sourcing requirements from United States and German fleet operators mandate multi-supplier qualification for lithium-ion battery packs and selective catalytic reduction components. Manufacturing concentrates in Germany, China, and the United States, with axle and boom steel drawing from specialized forging operations in these markets. Supply chain risk hinges on single-source vulnerability for high-voltage motor controllers sourced from limited Asian semiconductor foundries. Distribution runs through manufacturer-owned dealer networks and independent rental fleet procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The light duty telehandler market functions as a stable compounder, with infrastructure renewal programs and agricultural mechanization subsidies delivering predictable replacement-cycle demand across multiple geographies.
For Market Incumbents: Deepen backward integration into battery pack assembly and telematics firmware development to defend margin position against emerging electric-specialist entrants. Prioritize captive service network density in United States metropolitan corridors where uptime guarantees command pricing premiums. Invest in ISO 16368 certified testing capacity to accelerate EU conformity assessment timelines.
For New Entrants and Emerging Players: Rental fleet operators in India's Tier-2 and Tier-3 construction markets represent the most penetrable channel partner type for first-time rough-terrain deployment. Target compact electric configurations for Dutch canal-side renovation contractors facing strict Stage V indoor emission restrictions. Pursue joint certification pathways with established component suppliers to bypass testing facility queue delays.
For Investors and Strategic Acquirers: Construction equipment OEMs with captive finance arms are the most active acquirer in this space, seeking telematics capabilities and battery supply chain integration. Long-term viability centers on manufacturers with modular platform architectures adaptable across diesel, hybrid, and electric powertrains. Monitor lithium-ion cell localization progress in Europe and North America as the critical inflection signal for capital deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Chain Localization | European cell manufacturing investments reduce tariff exposure and Stage V compliance lead times. |
| Telematics Platform Integration | Cloud-based fault logging satisfies EPA onboard diagnostics and EU real-driving emissions mandates. |
| Modular Platform Architecture | Multi-purpose chassis designs accelerate CE marking timelines for rental fleet specifications. |
| Certified Testing Capacity Expansion | In-house ISO 16368 facilities eliminate queue delays for new market entrants. |
| Equipment-as-a-Service Contracting | Fixed monthly rates with uptime guarantees transfer residual risk from rental operators to manufacturers. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with rental fleet procurement directors, construction equipment maintenance heads, agricultural cooperative managers, and OEM aftermarket service leads. Secondary validation draws from EPA certification databases, EU type-approval records, customs trade flows, and SEC equipment manufacturer filings. Bottom-up unit demand modeling triangulates against top-down infrastructure spending projections.
Granularity-level framing applies country-specific replacement cycle assumptions and regulatory phase-in schedules across product type, end user, application, and technology segmentation dimensions. CAGRs derive from regression-based equipment stock turnover modeling and fleet age distribution analysis. Forecast inputs incorporate lithium-ion cost curves, Stage V enforcement timelines, and agricultural subsidy program allocations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery chemistry transitions and trade policy shifts affecting semiconductor controller availability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Port Material Handling Equipment Vehicle Market
Material Handling Equipment
United States Automated Material Handling Market
Material Handling Equipment
High-Performance Seals Market
Material Handling Equipment
Hoist Market
Material Handling Equipment
Pick and Carry (PNC) Crane Market
Material Handling Equipment
Conveyor Sprocket Market
Material Handling Equipment
Reinforced Ultrafine Mill Market
Material Handling Equipment
Global Screw Conveyors Market
Material Handling Equipment
Drag Chain for Machine Market
Material Handling Equipment
Selective Pallet Racking System Market
Material Handling Equipment
Loading Platform Canopies Market
Material Handling Equipment
Global Linear Guide Market
Material Handling Equipment
Pipe Wrapping Machines Market
Material Handling Equipment
Industrial Lift Ladder Market
Material Handling Equipment
Global Automatic Palletizer and Depalletizer Market
Material Handling Equipment
Global Industrial Lifting Equipment Market