
 Industrial Static Equipment Market | 2026-2036
Industrial Static Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Static Equipment Market Foresight
Capital-intensity divergence between integrated fabricators and assembly-only suppliers is redrawing competitive boundaries in industrial static equipment. Emerson Electric Co. leverages its automation-to-hardware integration to command premium positioning in pressure vessel systems. Alfa Laval AB specializes in heat exchanger technologies for energy-intensive process industries. Pentair plc anchors its portfolio around filtration and separation static equipment for water and industrial applications.
Industrial static equipment encompasses non-rotating process apparatus including pressure vessels, heat exchangers, storage tanks, and columns, typically fabricated from carbon steel, stainless steel, or exotic alloys through welding, forging, and rolling processes designed to contain, transfer, or transform process fluids under controlled pressure and temperature conditions. Switchgear and transformers within the product type segmentation dominate current revenue as grid modernization and industrial electrification accelerate replacement cycles. Oil-insulated technology retains installed-base dominance while SF6 faces regulatory pressure, creating a structural shift toward air-insulated and vacuum alternatives in new installations.
EPA emissions rules and ASME Boiler and Pressure Vessel Code standards in the United States, combined with EU Pressure Equipment Directive and REACH compliance requirements in Europe, elevate material certification and traceability costs while restricting market access for uncertified suppliers. China's MEE environmental enforcement and GB standards for pressure vessels impose additional conformity burdens on domestic and imported equipment alike. Stakeholders must monitor regulatory divergence between jurisdictions to optimize manufacturing location and certification strategies without duplicating compliance expenditure.
Market Dynamics
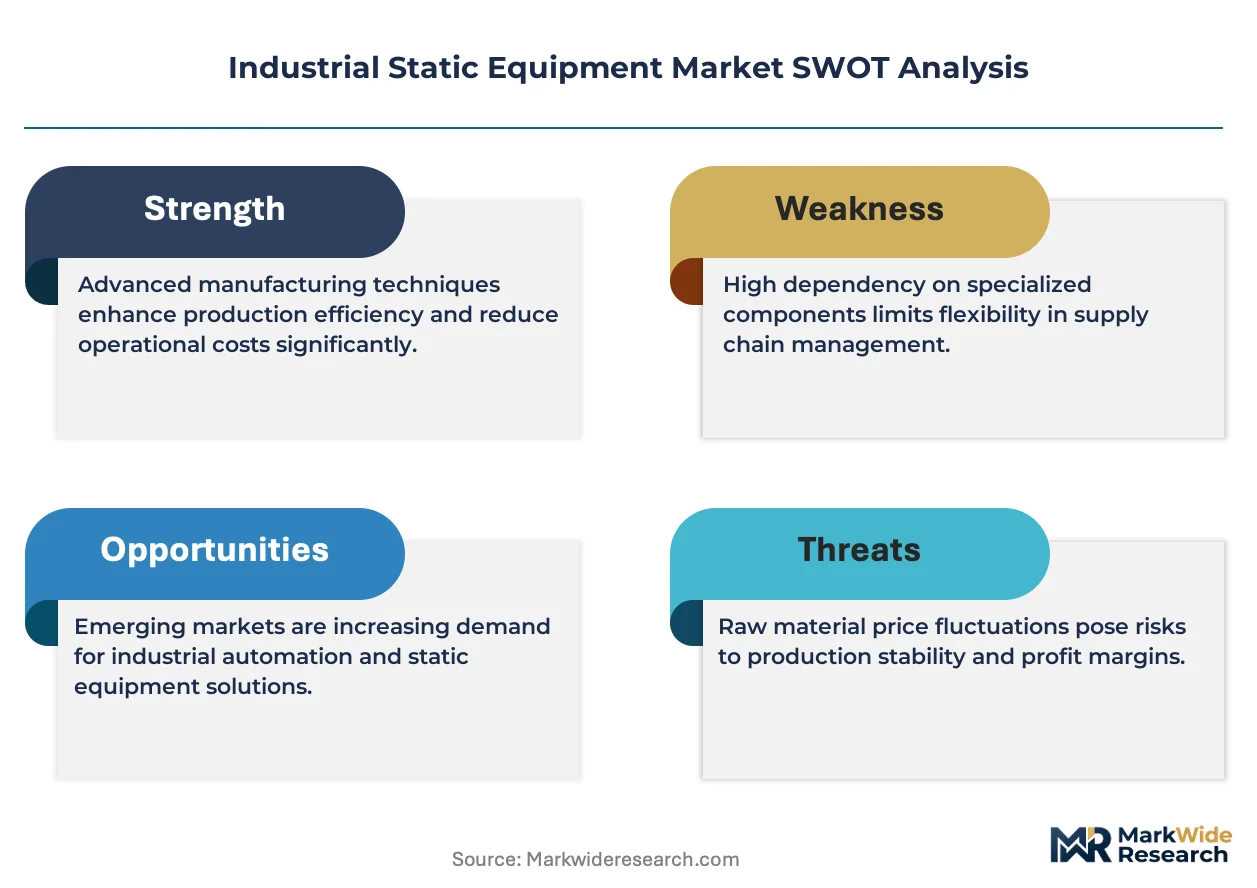
Refinery operators in the US Gulf Coast and Middle East are replacing aging infrastructure with corrosion-resistant vessel designs as EPA and MEE emissions frameworks tighten. This regulatory compression is redrawing procurement priorities toward certified fabricators with integrated automation capabilities.
Growth Catalysts
- EPA Emissions Mandates:US refineries must upgrade to low-leakage vessel designs, creating replacement demand for pressure-rated static equipment with advanced sealing technologies.
- India's Petrochemical Buildout:Indian Oil Corporation and Reliance Industries are expanding cracker complexes, concentrating procurement for heat exchangers and separation columns in Gujarat and Maharashtra clusters.
- Dual Carbon Goals in China:Beijing's carbon neutrality targets are accelerating coal-to-chemical conversions, requiring new hydrogen-ready pressure vessels and cryogenic storage systems.
Market Restraints
- Alloy Supply Concentration:Nickel and molybdenum sourcing concentrates in Indonesian and Russian mining jurisdictions, exposing fabricators to price volatility and export restriction risks.
- ASME Certification Backlogs:US-based inspection capacity constraints are extending pressure vessel certification timelines from 12 to 18 months, freezing project commissioning schedules.
- Modular Fabrication Substitution:Pre-assembled skid-mounted process units are displacing field-erected static equipment in mid-scale installations, compressing addressable market scope.
Strategic Opportunities
- Saudi Arabia's Giga-Project Wave:NEOM and Red Sea tourism developments are creating demand for desalination and industrial water treatment static equipment at unprecedented scale.
- Hydrogen Infrastructure Buildout:Convergence of high-pressure composite vessel technology with cryogenic storage systems is opening new product categories for 700-bar hydrogen distribution.
- EU Green Deal Funding:The European Commission's Innovation Fund is subsidizing carbon capture vessel retrofits, creating preferential procurement channels for REACH-compliant fabricators.
Industry Challenges
- Welding Inspector Scarcity:ASME Section IX-certified welders and NDT technicians are in acute shortage across US fabrication yards, constraining throughput expansion.
- Legacy System Integration:Digital twin implementations for aging refinery vessel fleets require reconciling 1980s construction records with modern IoT sensor architectures.
- REACH Compliance Documentation:European fabricators face escalating traceability burdens for exotic alloy chemistries, with material certification chains extending to fourth-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Static Equipment Market |
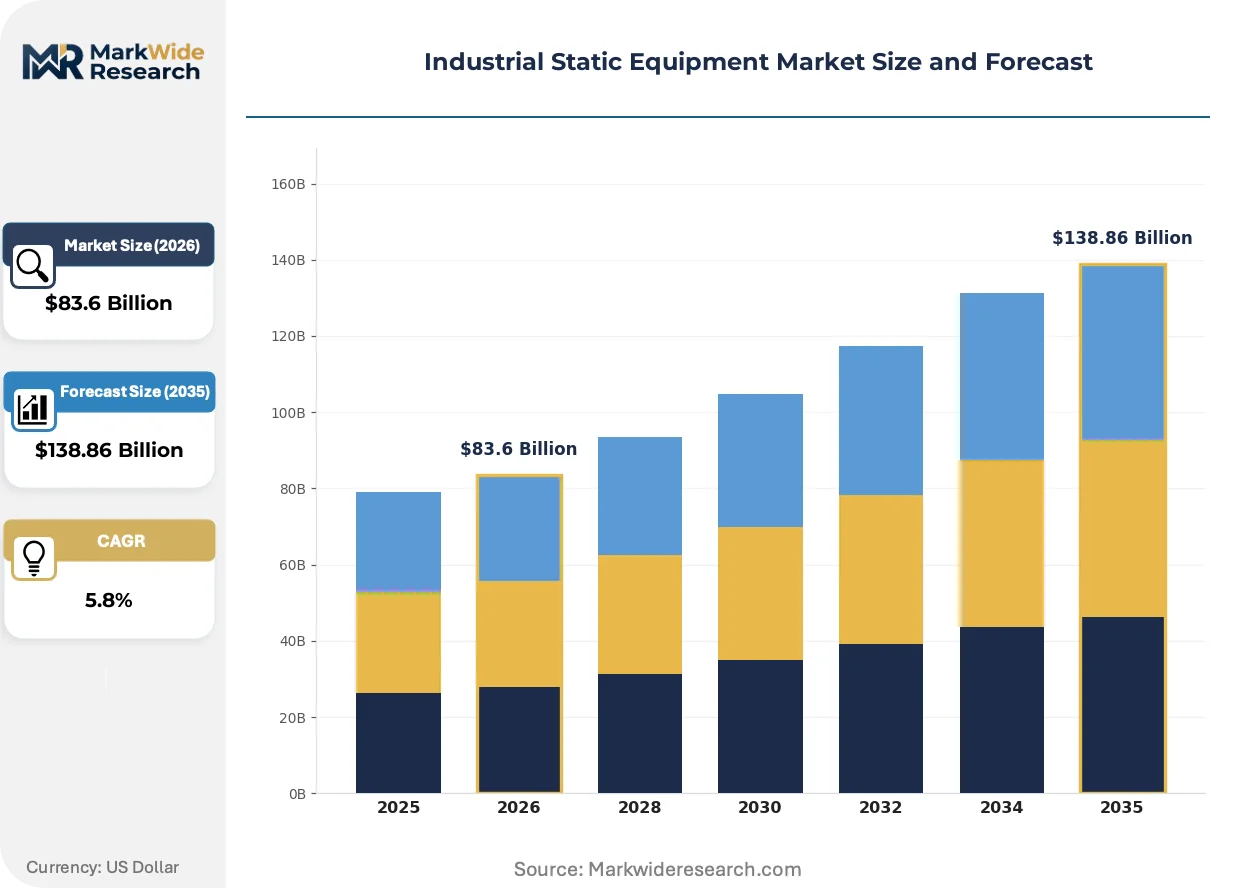
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $138.86 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
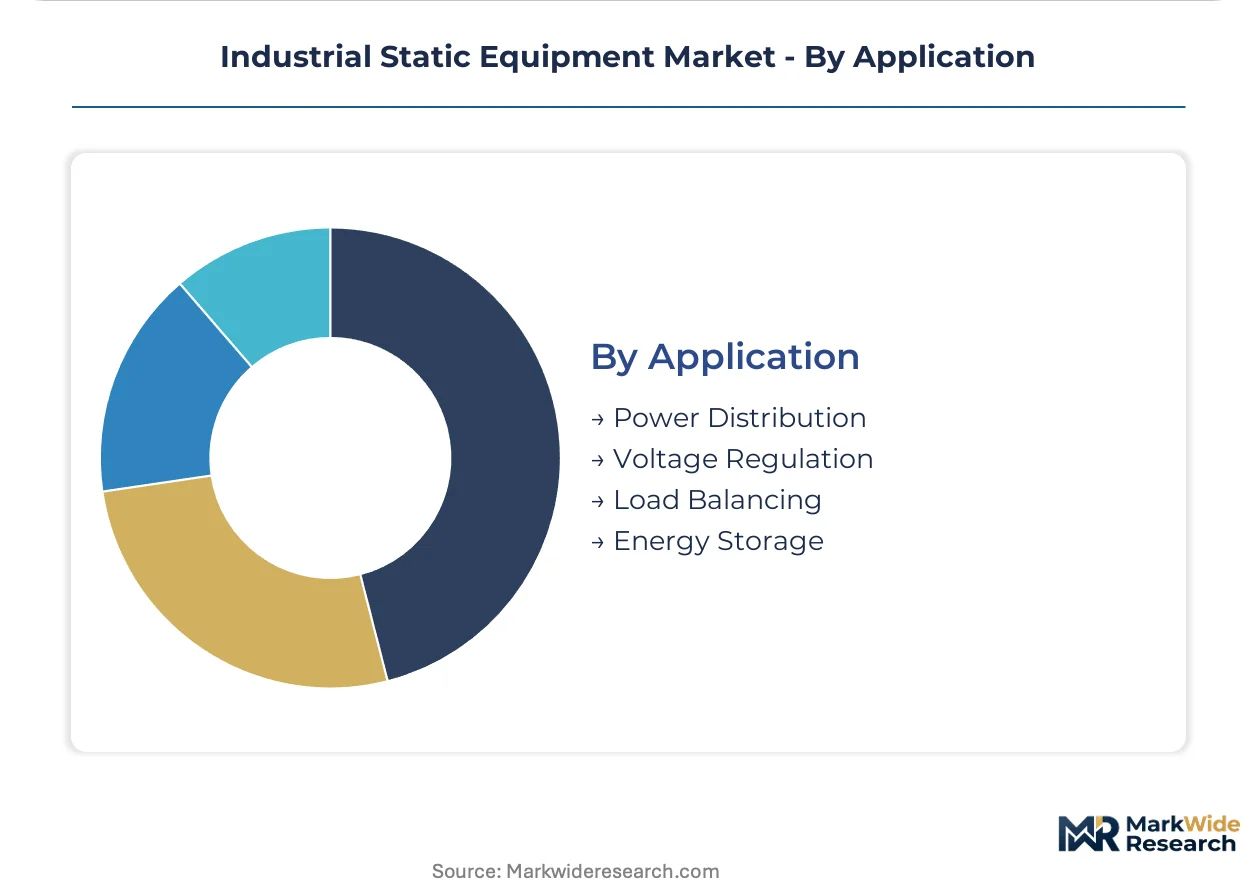
| Segmentation | Product Type: Transformers, Capacitors, Switchgear, Inductors Technology: Vacuum, Oil-Insulated, Air-Insulated, SF6 End User: Manufacturing, Utilities, Construction, Mining Application: Power Distribution, Voltage Regulation, Load Balancing, Energy Storage |
| Companies Covered | Flowserve Corporation, Emerson Electric Co., Alfa Laval AB, Danfoss A/S, Mitsubishi Heavy Industries, Ltd., Pentair plc, Metso Oyj, Atlas Copco AB, TechnipFMC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Static Equipment Market Shifts & Advancements
Material science advances and regulatory enforcement patterns are fragmenting competitive advantage across the static equipment value chain. Fabricators must now synchronize alloy innovation with jurisdictional compliance architectures to maintain specification access.
Additive manufacturing of reactor internals is bifurcating the supply base between integrated metallurgical innovators and conventional machining houses. BASF and Dow Chemical are piloting 3D-printed heat exchanger tube inserts for fouling-resistant operation. This capability compression is enabling rapid prototyping cycles that collapse traditional 18-month development timelines.
China's MEE environmental enforcement and GB 150 pressure vessel standards are tightening material traceability requirements for both domestic and imported equipment. Fabricators must now maintain parallel documentation systems for Chinese and ASME jurisdictions. The heat exchanger segment bears the heaviest burden, with dual-certification costs adding 8-12% to project engineering budgets.
Refinery operators are unbundling maintenance contracts from original equipment supply, creating standalone service markets for vessel inspection and remaining-life assessment. Suncor and Valero have separated procurement functions for new builds versus turnaround services. This channel fragmentation is most visible in the US Gulf Coast, where specialized NDT contractors now capture 30-40% of lifetime equipment value through inspection subscriptions.
Industrial Static Equipment Market Segmentation
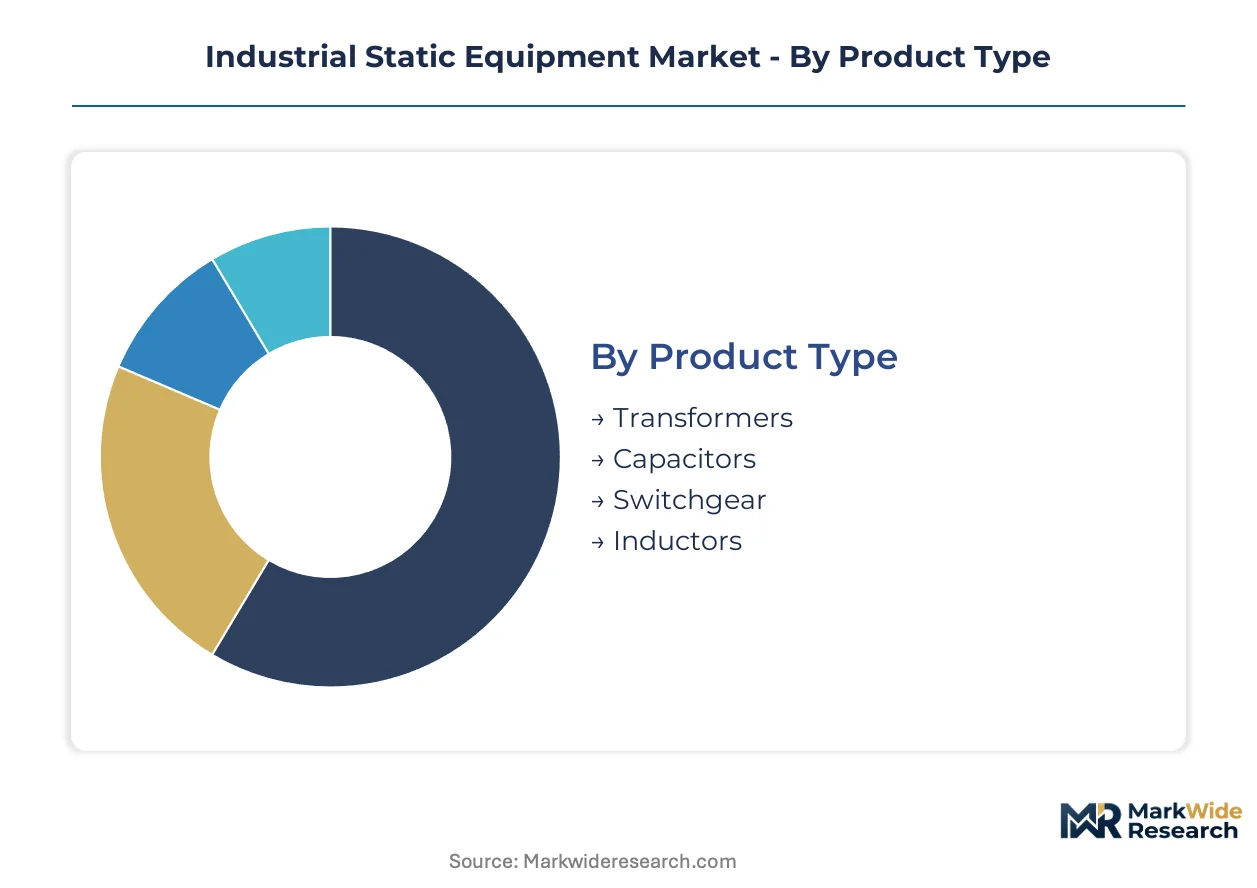
Static equipment procurement patterns fragment sharply across voltage classes, insulation media, and end-use intensity. Fabricators must align certification portfolios with the specific compliance architectures governing each segment's dominant applications.
Product Type:
Margin pools concentrate in high-voltage transformer systems where core steel and winding copper account for 60% of bill-of-materials costs, creating differentiation through metallurgical sourcing relationships.
- Transformers:Core-and-coil assemblies rated from distribution-class 10kVA to grid-intertie 1000MVA units, with amorphous metal cores penetrating utility replacement cycles. Demand concentrates in US Gulf Coast refinery electrification and India's transmission utility tenders as Power Grid Corporation expands inter-regional capacity.
- Switchgear:Metal-enclosed assemblies housing circuit breakers, disconnectors, and protective relays for fault isolation and operational control. Procurement is rotating toward air-insulated alternatives in European utilities under F-Gas Regulation pressure, while SF6-retrofit demand persists in Middle East infrastructure.
- Capacitors:Power factor correction and harmonic filtering banks for industrial voltage stability. Aluminum electrolytic and film dielectric technologies dominate heavy manufacturing loads in China's eastern provinces.
- Inductors:Choke coils and reactors for current limiting and filtering in variable-frequency drives. Mining sector procurement in Western Australia and Chile's Atacama copper belt drives specification for tropicalized enclosures.
Transformers hold installed capacity. Switchgear is rotating up the share rankings.
Technology:
Insulation medium selection now determines market access more than performance metrics, with regulatory jurisdictions enforcing phased transitions that strand legacy manufacturing lines.
- Oil-Insulated:Mineral or ester-based dielectric fluids in conservator-type or hermetically sealed transformer tanks, delivering proven thermal management for bulk power applications. US utilities under FERC grid reliability mandates maintain replacement demand despite fire-risk liabilities in urban substations.
- SF6:Sulfur hexafluoride gas insulation for compact high-voltage switchgear, facing EU F-Gas Regulation phase-down quotas and California Air Resources Board restrictions. Remaining demand concentrates in space-constrained offshore platforms and urban underground substations where footprint constraints override environmental compliance costs.
- Vacuum:Arc extinction in sealed interrupter bottles for medium-voltage circuit breakers, eliminating gas handling entirely. Indian and Chinese switchgear OEMs are scaling vacuum interrupter production for 12-36kV distribution networks.
- Air-Insulated:Open-phase construction with atmospheric dielectric, requiring larger footprints but zero gas containment. European TSOs under EU Green Deal procurement guidelines specify air-insulated switchgear for new 145kV substations.
Oil-insulated systems hold installed capacity. Vacuum technology is rotating up the share rankings.
End User:
Customer-type profitability diverges between price-tendered utility procurement and specification-driven industrial projects where engineering approval cycles extend timelines but preserve margins.
- Utilities:Transmission and distribution operators procuring standardized equipment through multi-year framework agreements. State Grid Corporation and Southern California Edison drive volume for 110kV-500kV transformer classes with 30-year service life requirements.
- Manufacturing:Automotive, chemical, and metals processors specifying custom unit substations for plant-wide power quality. German automotive OEMs in Bavaria and Baden-Württemberg demand harmonic-compensated transformer designs for robotic welding loads.
- Mining:Open-pit and underground operations requiring mobile substations and flameproof switchgear for dragline and conveyor electrification. Pilbara iron ore operators in Western Australia specify IP66-rated enclosures for cyclic loading profiles.
- Construction:Temporary power infrastructure for major infrastructure projects, favoring skid-mounted transformer packages with rapid deployment capability. Saudi giga-project sites around NEOM and the Red Sea coast are absorbing prefabricated substation capacity.
Utilities hold installed capacity. Manufacturing is rotating up the share rankings.
Application:
Functional segmentation tracks grid modernization investment waves, with voltage regulation and energy storage applications capturing capital flows from renewable integration mandates.
- Power Distribution:Step-down transformation and feeder protection for last-mile electricity delivery. Rural electrification programs in Indonesia and Nigeria are expanding 33/11kV distribution transformer procurement.
- Voltage Regulation:On-load tap changers and static VAR compensators for grid stability under fluctuating renewable generation. ERCOT and CAISO interconnection queues are forcing Texas and California utilities to upgrade regulation bandwidth.
- Energy Storage:Power conversion interfaces for battery and pumped-hydro systems, requiring bidirectional transformer capability. Grid-scale battery projects in South Korea's Jeolla and Gyeongsang provinces specify inverter-duty transformer designs.
- Load Balancing:Phase balancing and peak-shaving equipment for industrial demand-side management. Cement and steel plants in India's Chhattisgarh and Odisha states deploy capacitor banks to avoid utility penalty tariffs.
Power distribution holds installed capacity. Energy storage is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between geographies. US Gulf Coast refiners prioritize corrosion-resistant vessel replacements under EPA mandates, while Chinese operators focus on hydrogen-ready pressure systems for coal-to-chemical conversions. Indian procurement concentrates on heat exchangers for petrochemical buildouts in western industrial corridors.
United States
US refineries along the Texas and Louisiana coastlines are replacing aging pressure vessels with low-leakage designs. EPA emissions rules under the Clean Air Act are forcing upgrades to advanced sealing technologies. The Houston Ship Channel cluster hosts concentrated procurement for ASME-certified fabricators serving ExxonMobil and Valero turnaround schedules.
China
Beijing's dual carbon goals are accelerating demand for hydrogen-ready pressure vessels and cryogenic storage systems. MEE environmental enforcement and GB 150 pressure vessel standards impose strict material traceability requirements. The Ningbo-Zhoushan petrochemical base in Zhejiang province is absorbing the largest share of new heat exchanger capacity.
India
Indian Oil Corporation and Reliance Industries are expanding cracker complexes across Gujarat and Maharashtra. Central Electricity Authority grid codes and Petroleum and Natural Gas Regulatory Board standards govern equipment specifications. The Jamnagar refining complex anchors procurement concentration for separation columns and reactor vessels.
Germany
German chemical producers are retrofitting carbon capture vessels under EU Green Deal Innovation Fund subsidies. REACH compliance and Pressure Equipment Directive standards elevate certification costs for exotic alloy documentation. The BASF Ludwigshafen complex drives specification demand for corrosion-resistant reactor internals.
Saudi Arabia
NEOM and Red Sea tourism giga-projects are creating unprecedented demand for desalination and industrial water treatment static equipment. SFDA industrial safety frameworks and SASO technical regulations govern pressure system approvals. The Jubail industrial city cluster concentrates procurement for high-capacity storage tanks and process vessels.
Industrial Static Equipment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in industrial static equipment supply. The upper tier commands premium positioning through automation-to-hardware integration and captive metallurgical capabilities. Mid-scale fabricators compete on ASME and GB dual-certification agility. Dominant competitive moves include backward integration into alloy sourcing and geographic expansion through local certification partnerships.
Among diversified industrial conglomerates, Emerson Electric Co. and Mitsubishi Heavy Industries, Ltd. exemplify integrated leaders with spanning capabilities across pressure systems and process automation. Alfa Laval AB occupies a specialist position exemplifying heat exchanger-focused engineering. Pentair plc anchors the filtration and separation equipment tier. Flowserve Corporation and Danfoss A/S represent mid-scale fabricators with regional certification depth.
| Leading Market Players |
|---|
| Flowserve Corporation |
| Emerson Electric Co. |
| Alfa Laval AB |
| Danfoss A/S |
| Mitsubishi Heavy Industries, Ltd. |
| Pentair plc |
| Metso Oyj |
| Atlas Copco AB |
| TechnipFMC |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts with take-or-pay clauses dominate procurement between Gulf Coast refiners and ASME-certified fabricators, locking in nickel-alloy supply access while capping price volatility across multi-year vessel replacement cycles. This contract architecture shields buyers from spot-market swings in molybdenum and chromium but commits capital early in project development timelines.
Pricing Analysis
Aftermarket service contracts for pressure vessel inspection and remaining-life assessment now drive lifetime value capture, with NDT subscription models generating recurring revenue streams that offset compressed margins on initial equipment sales. Three-tier pricing structure across premium, standard, and economy levels separates integrated automation-hardware bundles from bare-vessel procurement, with ASME-GB dual-certified fabricators commanding 15-20% premiums over single-jurisdiction suppliers. Pricing pressure stems from modular skid-mounted unit substitution in mid-scale installations, eroding field-erected vessel margins. Price-sensitive independent EPCs in India's western corridors favor economy-tier Chinese imports, while Gulf Coast majors prioritize premium-tier domestic fabricators despite higher upfront costs.
Supply Chain Analysis
Strategic stockpiling of nickel and molybdenum feedstock dominates inventory strategy among integrated fabricators, insulating production schedules from Indonesian mining export restrictions and Russian supply disruptions. Raw material sourcing concentrates in Indonesia, Russia, and Australia for nickel; South Africa and China for chromium; Peru and Chile for molybdenum. Supply chain risk centers on single-source vulnerability for super-duplex stainless grades used in sour-gas service. Distribution runs through direct mill relationships for Tier 1 fabricators, while mid-scale suppliers rely on Rotterdam and Singapore metal traders for alloy procurement flexibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as hydrogen infrastructure buildouts and carbon capture retrofits create specification demand for cryogenic and high-pressure vessel categories that barely existed five years ago.
For Market Incumbents: Secure captive supply relationships for nickel and molybdenum feedstock before Indonesian export license restrictions tighten further, while accelerating ASME Section IX welder apprenticeship pipelines to relieve throughput constraints at US Gulf Coast fabrication yards. Threat substitution from composite pressure vessels in hydrogen distribution applications demands preemptive R&D investment in 700-bar metallic liner technology to defend specification access in emerging energy vectors. For New Entrants and Emerging Players: Anchor in Saudi desalination and water treatment static equipment procurement for NEOM and Red Sea giga-projects, where local content requirements and SFDA certification pathways create protected demand pools absent entrenched incumbent relationships. White-space opportunity concentrates in modular hydrogen storage skids for European port infrastructure, with REACH-compliant fabrication capabilities as the critical go-to-market credential. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale fabricators with demonstrated dual-certification agility across ASME and GB jurisdictions, positioned to capture India and China petrochemical buildout demand without legacy cost structures. Long-term viability hinges on hydrogen-ready pressure vessel capabilities and integrated automation offerings. Watch for inflection when European Innovation Fund carbon capture vessel subsidies accelerate procurement timelines beyond current 18-month ASME certification backlogs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Sourcing | Captive nickel and molybdenum supply shields margins from Indonesian export volatility. |
| Dual-Certification Investment | ASME-GB parallel documentation opens specification access in India and China petrochemical clusters. |
| Hydrogen-Ready Vessel Development | 700-bar composite-metal hybrid designs capture emerging hydrogen distribution infrastructure demand. |
| Modular Skid Partnership | Pre-assembled unit alliances with EPCs defend market scope against field-erected displacement. |
| NDT Service Capability Buildout | Inspection subscription models capture 30-40% lifetime equipment value from unbundled maintenance contracts. |
Research Methodology
Desk research of ASME certification databases, EPA enforcement records, and customs trade flows preceded structured interviews with refinery maintenance directors, pressure vessel procurement leads at Indian Oil Corporation, fabrication yard operations managers, and aftermarket NDT service contractors. Secondary validation drew from SEC 10-K filings of listed fabricators, MEE environmental enforcement bulletins, and EU Pressure Equipment Directive guidance documents. Bottom-up project pipeline enumeration triangulated against top-down petrochemical capacity expansion forecasts.
Variance decomposition across product type, insulation technology, end-user intensity, and regional regulatory framework shaped the analytical framework over the projection horizon. Modeled segmentation dimensions included pressure rating class, material grade tier, and hydrogen-service certification status. CAGRs were derived from installed-base replacement cycles and greenfield capacity absorption rates, with alloy price elasticity and certification timeline delays as industry-specific forecast sensitivity inputs.
Decision-makers should treat outputs as directional under base assumptions of sustained EPA and MEE enforcement intensity and stable nickel-molybdenum supply flows; material deviation would warrant model refresh. Specific risk factors include ASME inspector capacity constraints extending certification timelines and REACH documentation burdens escalating exotic alloy traceability costs. Revision becomes warranted when modular fabrication substitution rates exceed threshold penetration in mid-scale refinery and chemical plant installations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Industrial Racking Systems Market
Material Handling Equipment
Hook Lifts and Skip Loaders Market
Material Handling Equipment
Electric Single Beam Crane Market
Material Handling Equipment
Spiral Fitting Machines Market
Material Handling Equipment
Freight Elevators Market
Material Handling Equipment
Light Duty Telehandler Market
Material Handling Equipment
Container Handling Equipment Market
Material Handling Equipment
Lump Breaker Machines Market
Material Handling Equipment
Bulk Material Handling System Market
Material Handling Equipment
Cable Duct Market
Material Handling Equipment
Global Linear Guide Market
Material Handling Equipment
Scraper Conveyor Market
Material Handling Equipment
Vertical Platform Lift Market
Material Handling Equipment
Linear Slide Units Market
Material Handling Equipment
Global Lifting Columns Market
Material Handling Equipment
Hoist Sling Chains Assemblies Market