
 Slitting Machines Market | 2026-2036
Slitting Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Slitting Machines Market Outlook
Software-defined tension control is repositioning slitting machine value propositions from hardware sales to performance-guaranteed service contracts. Kampf Schneid- und Wickeltechnik GmbH & Co. KG leverages its German engineering base to dominate high-precision shear slitting for battery electrode foils. Atlas Converting Equipment Ltd anchors European flexible packaging demand through extensive retrofit service networks. Maxcess International differentiates via integrated web guiding and slitting automation platforms that reduce material waste.
Slitting machines cut continuous webs of paper, film, foil, and metal into narrower rolls using rotary knives, razor blades, or shear cutters with tolerances often below 0.1 millimeters. Rotary slitters lead installed capacity across packaging converters due to proven throughput on polymer films, though shear slitters capture margin pools in electronics-grade copper and aluminum foils where burr-free edges prevent short circuits. Fully automatic CNC slitting lines are displacing manual and semi-automatic units in automotive and electronics end-use segments as lot sizes shrink and changeover frequency rises.
Germany's KBA enforces machinery safety standards under the EU Machinery Directive that constrain slitting equipment design for European exports. China's SAMR mandates GB standard compliance for domestic and imported industrial equipment, creating certification barriers for non-Chinese suppliers. The US FDA regulates direct-contact food packaging substrates, indirectly shaping slitter cleanliness and material segregation requirements. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's embodied carbon tracking reshape equipment energy efficiency specifications and retrofit investment cycles.
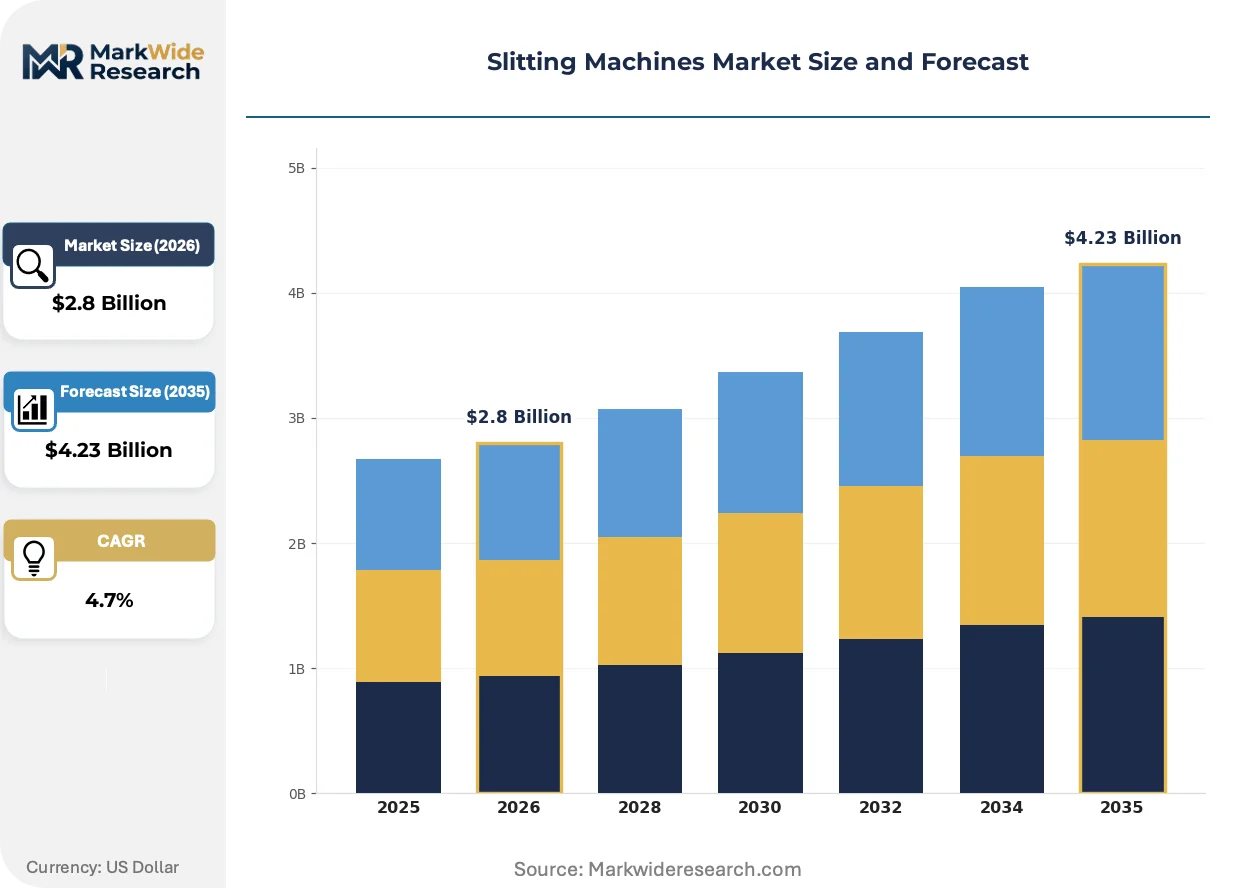
Market Dynamics
Software-defined tension control is collapsing the traditional hardware-sales model into performance-guaranteed service contracts, forcing OEMs to restructure revenue recognition and field-service organizations around uptime metrics rather than equipment delivery.
Growth Catalysts
- EU Green Deal embodied carbon tracking:Battery foil producers in Germany and Poland are retrofitting legacy lines with precision shear slitters to document carbon footprints per roll batch for automotive OEM supply agreements.
- Thinner-gauge metal strips:China's dual carbon goals are accelerating demand for sub-6-micron aluminum foils in EV batteries, requiring slitters with verified edge-burr control below 0.05 millimeters.
- FDA food-contact material requirements:North American flexible packaging converters are automating slitting lines to eliminate cross-contamination risks between adhesive-laminated and direct-contact substrates.
Market Restraints
- High-precision bearing and servo motor costs:Shear slitting heads require Japanese or German-sourced motion-control components that carry 40-60 week lead times and currency-hedged pricing volatility.
- REACH-aligned chemical safety standards:Germany's ECHA enforcement on adhesive film formulations is forcing slitter OEMs to redesign web-path geometries to prevent solvent residue accumulation in machine frames.
- Laser slitting for ceramics and composites:Non-contact thermal cutting is capturing pilot-line trials in solid-state battery separator films, threatening mechanical slitter incumbents in next-generation cell manufacturing.
Strategic Opportunities
- India's PLI scheme for battery manufacturing:Domestic cell producers in Gujarat and Tamil Nadu lack precision slitting capacity for electrode foils, creating first-mover openings for equipment vendors with local service infrastructure.
- Remote diagnostic and predictive maintenance platforms:Cloud-connected tension sensors and knife-wear algorithms are enabling OEMs to unbundle hardware from subscription-based performance contracts.
- Solid-state battery commercialization:Ceramic-coated separator films demand slitters with contamination-free environments and electrostatic discharge control, a specification gap unaddressed by incumbent packaging-focused suppliers.
Industry Challenges
- Mechatronics technician scarcity:Converters in China's coastal provinces struggle to hire engineers capable of calibrating closed-loop dancer tension systems across multi-axis servo networks.
- Legacy DCS integration:Retrofit slitting lines must communicate with 1990s-era plant historians via proprietary fieldbus protocols, extending commissioning timelines and requiring custom gateway development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slitting Machines Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Slitters, Razor Slitters, Shear Slitters, Combined Slitters End User: Packaging, Textile, Automotive, Electronics Technology: Manual, Semi-Automatic, Fully Automatic, CNC Application: Metal Strips, Film Production, Paper Rolls, Foil Sheets |
| Companies Covered | Universal Converting Equipment, Atlas Converting Equipment Ltd, Kampf Schneid- und Wickeltechnik GmbH & Co. KG, HCI Converting Equipment Co. Ltd, Rosenthal MFG, ASHE Converting Equipment, Parkinson Technologies, Inc., Maxcess International, PATECH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slitting Machines Market Strategic Shifts
Active material traceability requirements and sub-micron tolerance demands are compressing development cycles for next-generation slitting architectures across battery, electronics, and pharmaceutical packaging end uses.
Shear slitting with ceramic-coated circular knives is overtaking conventional razor-slitting in lithium-ion electrode foil processing. Korean and Chinese battery producers are specifying these systems for all new gigafactory lines. The technology is overtaking legacy razor configurations by eliminating edge-burr defects that cause internal short circuits in stacked cell geometries.
China's SAMR enforcement of updated GB standards for industrial equipment safety is mandating redundant emergency-stop circuits and documented risk assessments for all imported slitting machinery. Domestic OEMs are accelerating certification timelines to capture replacement demand from European suppliers facing compliance delays. Electronics-grade foil producers in Jiangsu and Guangdong provinces are absorbing the compliance costs to maintain supply relationships with state-backed cell manufacturers.
Converters are unbundling slitter procurement from long-term service agreements and evaluating vendors on per-meter cutting cost rather than capital expenditure. This behavior is compressing OEM margins and favoring suppliers with captive blade resharpening and rapid spare-part logistics. The shift is most visible in North American flexible packaging, where private-equity-backed roll-stock distributors are consolidating supplier panels and demanding guaranteed throughput clauses.
Slitting Machines Market Segmentation
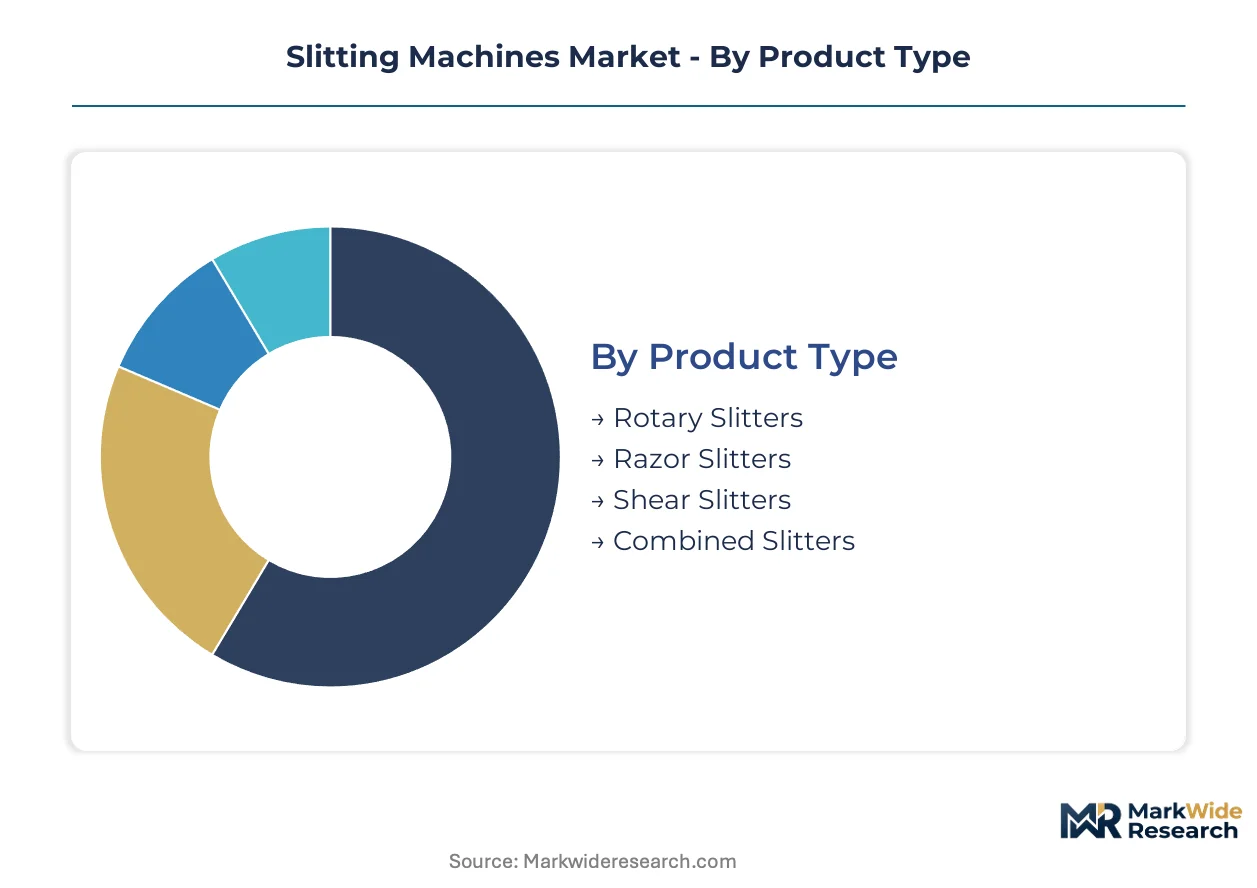
Segmentation in slitting machines reveals how upgrade cycles diverge across precision requirements and automation maturity. Converter investment patterns now separate commodity packaging retrofits from battery-grade foil line builds.
Product Type:
Replacement cycles accelerate where edge-quality specifications tighten and legacy mechanical systems face obsolescence.
- Rotary Slitters:These systems employ circular knives mounted on arbors to score and separate polymer webs at speeds exceeding 600 meters per minute. Demand clusters in North American flexible packaging converters modernizing lines for FDA food-contact compliance, where throughput volume outweighs absolute edge precision. Volume placements concentrate in Rotary Slitters; the faster expansion belongs to Shear Slitters.
- Shear Slitters:Overlapping circular blades apply scissor-like cutting action to achieve burr-free edges below 0.05 millimeters on copper and aluminum electrode foils. Korean and Chinese battery producers specify these systems exclusively for new gigafactory lines, displacing legacy razor configurations that risk internal short circuits in stacked cell geometries.
- Razor Slitters:Single-edge blades drawn across supported webs suit low-tension paper and non-critical film applications.
- Combined Slitters:Modular platforms allow rapid reconfiguration between rotary and shear modes for contract converters serving mixed end-use portfolios.
Margin pools shift toward shear architectures as battery foil tolerances compress.
End User:
Customer-type segmentation exposes how capital deployment rhythms vary between cyclical packaging and secular battery expansion.
- Packaging:Flexible film and label converters operate the largest installed base, though automation upgrades concentrate in North American operations facing FDA segregation mandates for food-contact substrates. Electronics represents the fastest-climbing end-use trajectory as solid-state battery commercialization demands contamination-controlled slitting environments.
- Electronics:Electrode foil producers in China's Jiangsu and Guangdong provinces drive specification-setting for sub-6-micron aluminum processing with verified material traceability per roll batch.
- Automotive:EV battery supply agreements require documented carbon footprints that retrofit legacy slitting lines cannot deliver.
- Textile:Nonwoven and technical fabric processors favor lower-speed razor configurations with minimal capital outlay.
Electronics procurement now outpaces packaging in average system value per line.
Technology:
Automation tier selection tracks workforce availability and changeover frequency pressures across converter operations.
- Fully Automatic:Closed-loop tension control and automatic knife positioning enable sub-0.1-millimeter tolerance maintenance without operator intervention. China's coastal provinces absorb these systems fastest where mechatronics technician scarcity makes manual calibration unsustainable.
- CNC:Computer numerical control architectures store hundreds of product recipes for electronics-grade foil producers managing shrinking lot sizes and rising changeover frequency.
- Semi-Automatic:Intermediate platforms retain manual loading while automating tension zones, suiting mid-volume converters in India's emerging battery supply chain.
- Manual:Hand-cranked systems persist only in developing-market textile operations with minimal precision requirements.
Fully Automatic systems dominate new line procurement; CNC retrofits capture existing asset upgrades.
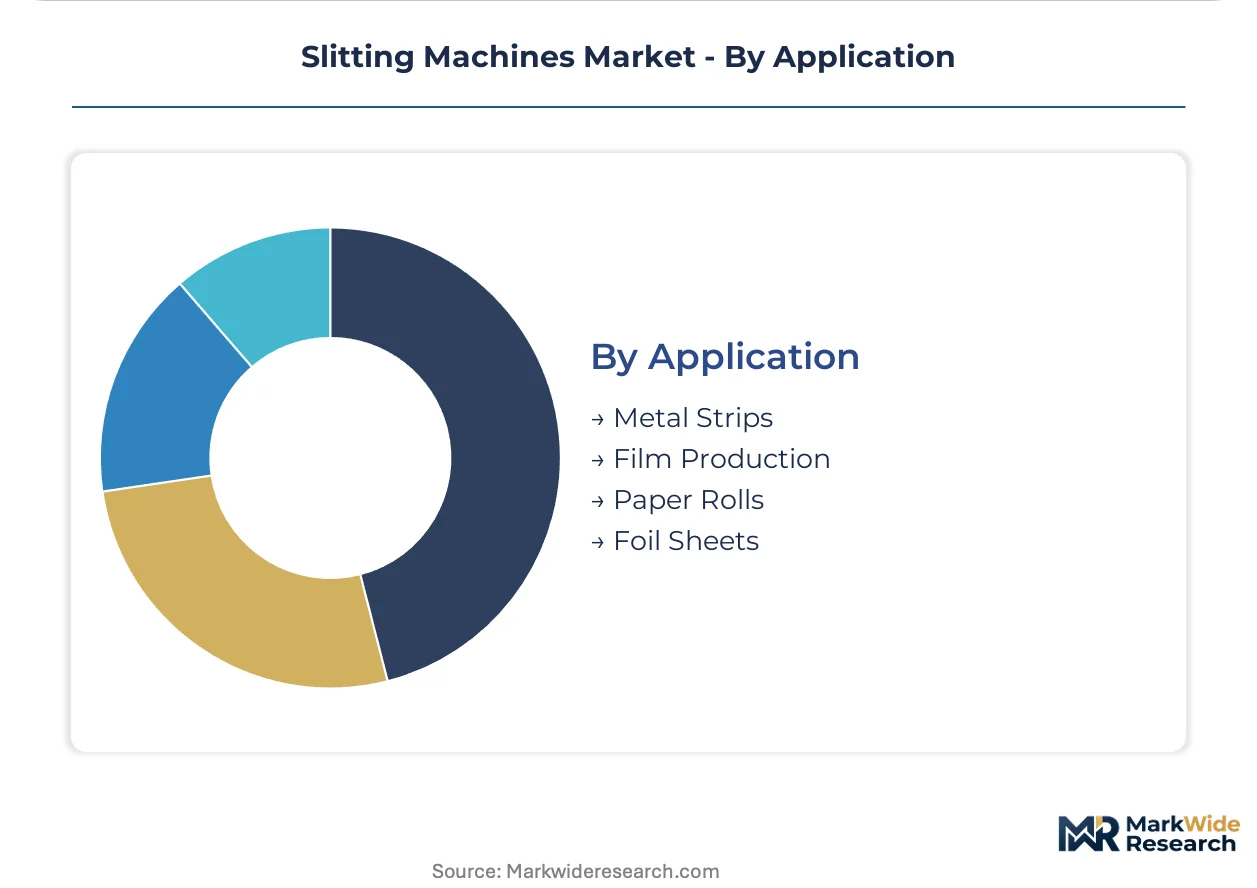
Application:
Material-specific segmentation aligns cutting mechanism selection with substrate mechanical properties and downstream quality thresholds.
- Foil Sheets:Battery electrode foils demand shear slitting with ceramic-coated circular knives to eliminate edge-burr defects. Germany's KBA machinery safety standards and China's SAMR GB compliance requirements constrain equipment design for cross-border supply relationships.
- Metal Strips:Sub-6-micron aluminum foils for EV batteries require verified edge-burr control below 0.05 millimeters, specifications unreachable by conventional rotary configurations.
- Film Production:Biaxially oriented polyester and polypropylene webs tolerate rotary scoring at high speeds across packaging converters.
- Paper Rolls:Newsprint and label stock processing favors cost-minimized razor slitting with lower capital recovery thresholds.
Foil sheet applications command premium pricing; film production maintains volume leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China produces the majority of battery electrode foils consumed worldwide, yet Germany and the United States deploy the most advanced precision slitting systems for automotive-grade specifications. This production-technology divide shapes regional investment patterns and equipment sourcing decisions across the value chain.
China
Jiangsu and Guangdong provinces host the densest concentration of electronics-grade foil producers retrofitting lines for sub-6-micron aluminum processing. SAMR enforcement of updated GB standards for industrial equipment safety is mandating redundant emergency-stop circuits on all imported machinery. Domestic OEMs in Shanghai and Shenzhen are accelerating certification timelines to displace European suppliers facing compliance delays.
Germany
Battery foil producers in Saxony and Bavaria are retrofitting legacy slitting lines to document carbon footprints per roll batch under EU Green Deal embodied carbon tracking requirements. KBA machinery safety standards under the EU Machinery Directive constrain equipment design for cross-border supply relationships. Industrial clusters around Stuttgart and Munich are absorbing precision shear slitters with verified material traceability systems.
United States
Flexible packaging converters in Wisconsin and Ohio are automating slitting capacity to meet FDA food-contact material segregation mandates. The FDA regulates direct-contact packaging substrates, indirectly shaping slitter cleanliness requirements and web-path geometries. Private-equity-backed roll-stock distributors in the Midwest are consolidating supplier panels and demanding guaranteed throughput clauses.
South Korea
Cell manufacturers in Gyeonggi Province and Chungcheongnam-do are specifying shear slitting systems exclusively for new gigafactory lines, displacing legacy razor configurations. MFDS pharmaceutical packaging regulations are creating secondary demand for contamination-controlled slitting environments in Seoul satellite facilities. Equipment vendors with local service infrastructure are capturing retrofit cycles from Chinese and Japanese competitors.
India
Domestic cell producers in Gujarat and Tamil Nadu lack precision slitting capacity for electrode foils despite PLI scheme incentives for battery manufacturing. BIS industrial equipment standards are creating certification barriers for non-Indian suppliers entering the market. First-mover equipment vendors establishing local service infrastructure in Ahmedabad and Chennai are securing early procurement commitments from state-backed manufacturers.
Slitting Machines Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the slitting machine value chain, creating a tiered structure where full-system integrators face pressure from specialized component suppliers. The vendor base separates into three strategic archetypes: German engineering houses dominating high-precision shear applications, Asian fabricators capturing volume placements in packaging converters, and integrated automation platforms bundling web guiding with slitting control. Dominant competitive moves include geographic expansion into India's emerging battery supply chain and technology licensing agreements for software-defined tension control systems.
Within the German engineering tier, Kampf Schneid- und Wickeltechnik GmbH & Co. KG and Atlas Converting Equipment Ltd exemplify precision-focused market positioning. Kampf Schneid- und Wickeltechnik GmbH & Co. KG occupies a position anchored in German machinery safety standards, while Atlas Converting Equipment Ltd represents the European retrofit service network model. Maxcess International sits within the integrated automation archetype, bundling web guiding and slitting control platforms that reduce material waste across converter operations.
| Leading Market Players |
|---|
| Universal Converting Equipment |
| Atlas Converting Equipment Ltd |
| Kampf Schneid- und Wickeltechnik GmbH & Co. KG |
| HCI Converting Equipment Co. Ltd |
| Rosenthal MFG |
| ASHE Converting Equipment |
| Parkinson Technologies, Inc. |
| Maxcess International |
| PATECH |
| Others |
Value Chain & Pricing Dynamics
Procurement consolidation among North American flexible packaging converters is compressing OEM margins and forcing suppliers to unbundle hardware from long-term service agreements. This buyer-side restructuring compels slitting machine vendors to absorb blade resharpening and spare-part logistics costs into per-meter cutting contracts, reshaping how pricing power distributes across the value chain.
Pricing Analysis
Cost compression in standard rotary slitting configurations traces to private-equity-backed roll-stock distributors consolidating supplier panels and demanding guaranteed throughput clauses. Pricing stratifies across premium shear systems for battery-grade foils, mid-tier CNC retrofits for packaging converters, and economy manual units for textile operations. Price differentiation hinges on FDA food-contact certification tier and captive after-sales service bundling. Battery electrode foil producers show lowest price sensitivity due to sub-6-micron tolerance requirements, while Asian packaging converters drive hardest bargain on capital expenditure.
Supply Chain Analysis
High-precision bearing and servo motor supply rests on Japanese and German motion-control component producers. Shear slitting heads draw from German engineering houses for ceramic-coated circular knives, while aluminum foil substrates feed from Chinese smelters in Jiangsu and Guangdong provinces. Single-source vulnerability concentrates in Japanese-sourced servo drives carrying extended lead times. Distribution runs through OEM direct sales for large battery producers and specialized distributor networks for mid-volume packaging converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over blade resharpening networks and predictive maintenance software determines who captures recurring revenue streams.
For Market Incumbents: Hedge against laser slitting substitution in solid-state battery separator films by acquiring ceramic-coating technology for circular knives. Deepen backward integration into tension sensor manufacturing to reduce exposure to Japanese motion-control component lead times. Lock in exclusive service contracts with Korean and Chinese gigafactory operators before domestic OEMs complete SAMR GB standard certification.
For New Entrants and Emerging Players: India's domestic cell producers in Gujarat and Tamil Nadu lack precision slitting capacity despite PLI scheme incentives. Establish local service infrastructure in Ahmedabad and Chennai to capture first-mover procurement commitments from state-backed manufacturers. Lead with contamination-controlled slitting environments as a specification gap unaddressed by incumbent packaging-focused suppliers.
For Investors and Strategic Acquirers: The window for entry favors equipment vendors with software-defined tension control platforms capable of unbundling hardware from subscription-based performance contracts. Target mid-cap specialists with proven battery foil installations and existing SAMR compliance documentation. Watch for EU Green Deal embodied carbon tracking mandates to accelerate retrofit investment cycles as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Tension Control Licensing | Enables OEMs to convert hardware sales into subscription-based performance contracts with uptime guarantees. |
| Ceramic-Coated Knife Manufacturing Integration | Captures margin pools in battery electrode foil processing where edge-burr control prevents cell short circuits. |
| SAMR GB Standard Certification Acceleration | Domestic Chinese OEMs exploit compliance delays facing European suppliers to displace imports in Jiangsu and Guangdong. |
| India Local Service Infrastructure Buildout | First-mover vendors in Ahmedabad and Chennai secure procurement commitments from PLI-backed cell producers. |
| Predictive Maintenance Platform Development | Cloud-connected knife-wear algorithms allow remote diagnostics that reduce converter downtime and bind customer relationships. |
Study Parameters
Document review covered OEM technical specifications, SAMR GB standard filings, and EU Machinery Directive compliance records, complemented by interviews with plant engineers at flexible packaging converters, procurement leads at battery electrode foil producers, aftermarket service heads at slitting machine distributors, and technical R&D directors at motion-control component suppliers. Secondary validation drew from customs trade data, SEC equipment manufacturer filings, and industrial machinery production databases. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Historical shipment data cross-referenced against panel input from converter operations informed the analytical framework. Segmentation dimensions modeled include cutting mechanism type, automation tier, end-use industry, material application, and regional regulatory cluster. CAGRs derived from slope analysis of equipment replacement cycles and greenfield capacity announcements. Industry-specific forecast inputs incorporated battery gigafactory construction timelines and FDA food-contact compliance retrofit schedules.
Revisions become necessary when solid-state battery commercialization accelerates beyond pilot-line trials, when Japanese servo motor lead times extend further, or when India's PLI scheme disbursement triggers sudden capacity buildouts. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Heavy Duty Ramp Market
Material Handling Equipment
Hydraulic Hoist Market
Material Handling Equipment
Tipper Pads Market
Material Handling Equipment
Hydraulic Fittings Market
Material Handling Equipment
Slag Handling Equipment Market
Material Handling Equipment
Global Hydraulic Equipment Market
Material Handling Equipment
Retractable Lift Market
Material Handling Equipment
Reach Trucks Market
Material Handling Equipment
Hoist Market
Material Handling Equipment
Global Mechanical Seals Market
Material Handling Equipment
Australia and New Zealand Industrial Fasteners Market
Material Handling Equipment
Loader Crane Market
Material Handling Equipment
Cherry Picker Crane Market
Material Handling Equipment
US Forklift Market
Material Handling Equipment
Material Handling Monorails Market
Material Handling Equipment
Europe Automated Material Handling (AMH) Market