
 Automotive Torque Tools Market | 2026-2036
Automotive Torque Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Torque Tools Market Analysis
Electric vehicle powertrain assembly is rebalancing demand away from traditional internal combustion service bays toward high-precision battery and motor fastening operations. Stanley Black & Decker leverages its cordless platform breadth to capture share in EV greenfield plants. Snap-on Incorporated anchors its position through mobile tool distribution networks serving fleet maintenance depots. Atlas Copco AB dominates industrial-grade electric nutrunner installations at European vehicle assembly lines.
Automotive torque tools are instruments designed to apply a specific rotational force to threaded fasteners, typically calibrated in Newton-meters or foot-pounds, with electronic variants incorporating strain-gauge sensors and angle encoders to achieve clamp-load accuracy within plus or minus two percent. Their primary purpose is preventing under-tightening that causes joint failure or over-tightening that damages components in safety-critical assemblies. Electric torque wrenches command premium positioning as OEMs phase out pneumatic lines to reduce energy intensity and noise exposure on factory floors. Smart torque tools with cloud-connected audit trails are capturing fastest-growing share among quality-conscious vehicle assemblers tracking fastening data for warranty defense. Manual torque wrenches retain volume dominance in aftermarket service channels where capital constraints limit digital tool adoption.
The US Occupational Safety and Health Administration enforces workplace exposure limits that accelerate pneumatic-to-electric tool transitions, while ISO 6789 calibration standards mandate periodic recertification that sustains recurring revenue streams for tool service providers. The EU Machinery Directive and CE marking requirements shape product design specifications for torque tools sold into European vehicle assembly operations. Stakeholders must monitor evolving battery electric vehicle platform architectures to anticipate which fastening applications will require new torque ranges and tool form factors.
Market Dynamics
ISO 6789 calibration mandates are compressing tool replacement cycles while EV battery pack assembly lines demand precision fastening systems that exceed pneumatic tool accuracy thresholds. This dual pressure is restructuring procurement patterns across vehicle manufacturing corridors.
Growth Catalysts
- EU Machinery Directive compliance:CE marking requirements for torque tools sold into European vehicle assembly operations are accelerating certified digital tool adoption over uncalibrated manual alternatives.
- EV powertrain fastening:Battery module and electric motor assembly lines require torque accuracy within plus or minus two percent, driving demand for strain-gauge sensor equipped nutrunners.
- Stuttgart manufacturing cluster:Germany's automotive corridor around Stuttgart and Wolfsburg concentrates procurement of industrial-grade electric fastening systems for premium vehicle platforms.
Market Restraints
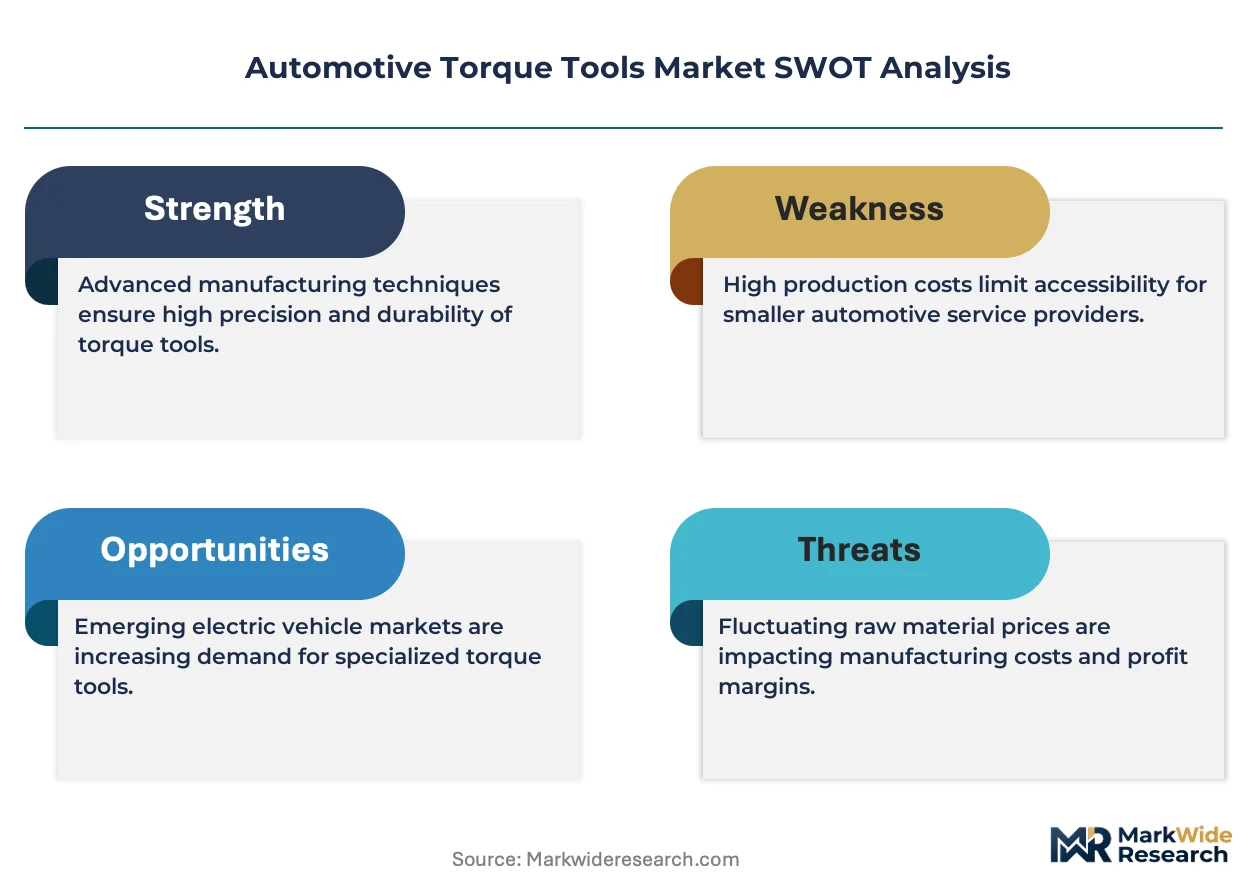
- Strain-gauge sensor cost volatility:Precision sensor components face input price instability that compresses margins on mid-tier digital torque wrench offerings.
- Pneumatic infrastructure lock-in:Legacy compressed air systems at established assembly plants create switching friction against electric tool migration despite energy efficiency gains.
- Calibration service concentration:ISO 6789 recertification capacity clusters with specialized metrology providers, creating geographic access barriers for distributed maintenance operations.
Strategic Opportunities
- Cloud-connected audit trails:Smart torque tools with wireless data logging are capturing share among quality-conscious assemblers tracking fastening records for warranty defense.
- Mobile tool distribution networks:Fleet maintenance depots present underpenetrated channels for calibrated digital tool penetration beyond factory floor installations.
- OSHA exposure limit enforcement:US workplace noise regulations are accelerating pneumatic-to-electric transitions in domestic vehicle assembly and aftermarket service bays.
Industry Challenges
- Metrology technician scarcity:ISO 6789 calibration expertise remains concentrated among aging specialist workforces, constraining service network expansion.
- Legacy system integration:Digital torque tool data streams require MES/ERP connectivity that many brownfield plants lack, complicating smart tool deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Torque Tools Market |
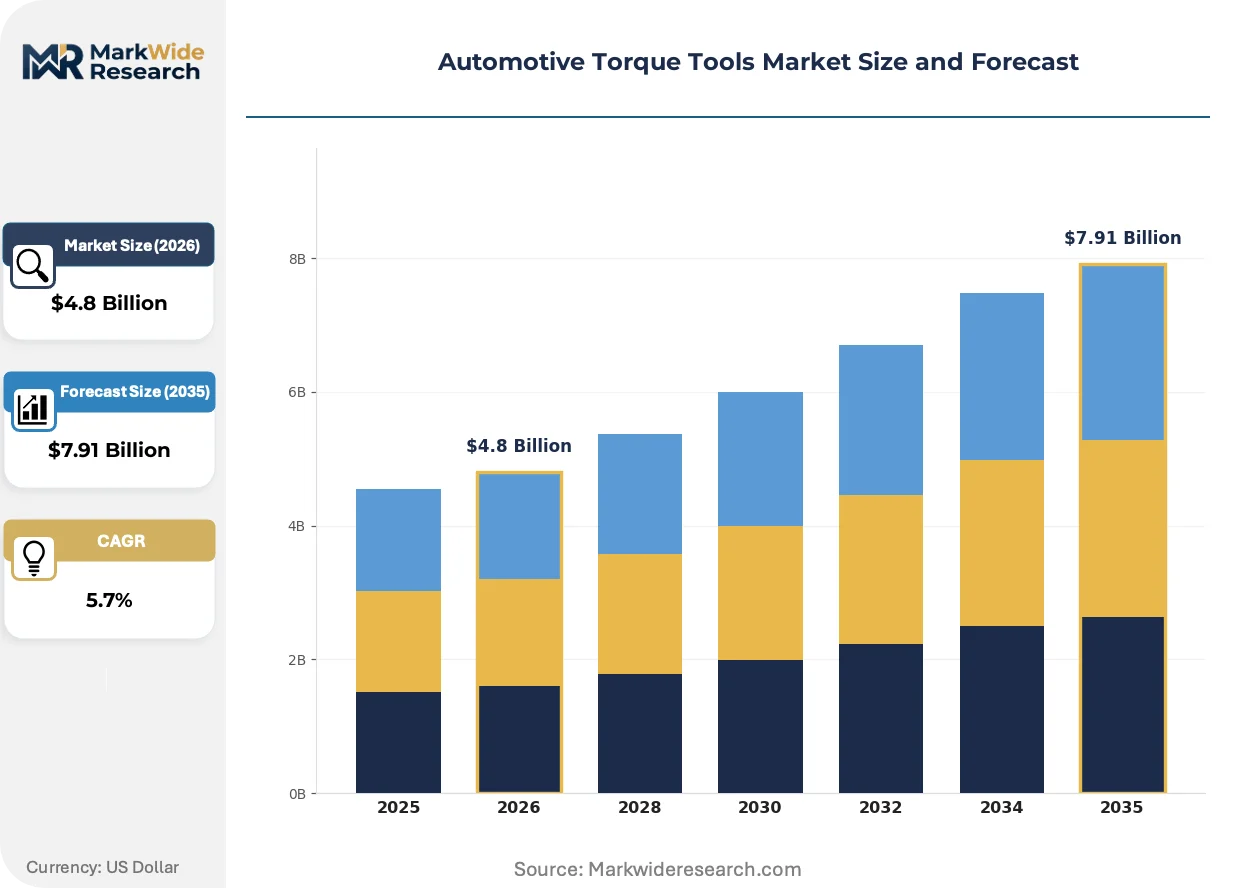
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Torque Wrenches, Electric Torque Wrenches, Pneumatic Torque Wrenches, Hydraulic Torque Wrenches End User: OEMs, Aftermarket Service Providers, Vehicle Assemblers, Maintenance Shops Technology: Digital Torque Tools, Mechanical Torque Tools, Electronic Torque Tools, Smart Torque Tools Application: Automotive Assembly, Repair Work, Inspection Services, Maintenance Tasks |
| Companies Covered | Stanley Black & Decker, Snap-on Incorporated, Apex Tool Group, Atlas Copco AB, Ingersoll Rand, Bosch, Makita Corporation, Norbar Torque Tools, DeWalt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Torque Tools Market Emerging Trajectories
Automotive torque tooling is absorbing sensor fusion and connectivity architectures that transform fastening from isolated mechanical acts into traceable quality events. This shift redefines value capture around data rather than hardware alone.
Brushless DC motor technology is absorbing the core actuation role in precision fastening equipment, replacing pneumatic vane motors with electronically controlled torque delivery. Tier-one battery pack assemblers in Germany and South Korea are specifying cordless electric nutrunners for greenfield EV plants. The technology is absorbing maintenance cost structures by eliminating compressed air infrastructure and reducing energy intensity per fastening cycle.
REACH substance restrictions and RoHS compliance requirements are reshaping material specifications for torque tool housings and electronic components sold into European markets. Manufacturers must reformulate coatings and solder compositions to maintain CE marking eligibility. Battery electric vehicle platforms face the strictest scrutiny, as their production lines fall under combined machinery and battery supply chain regulations.
Service contract unbundling is fragmenting traditional tool-plus-maintenance bundles into separate hardware and calibration subscriptions. Fleet operators and independent repair chains now procure calibrated tool access without capital ownership, pressuring distributor margins. This pattern concentrates in North American aftermarket channels where capital constraints limit upfront digital tool purchases.
Automotive Torque Tools Market Segmentation
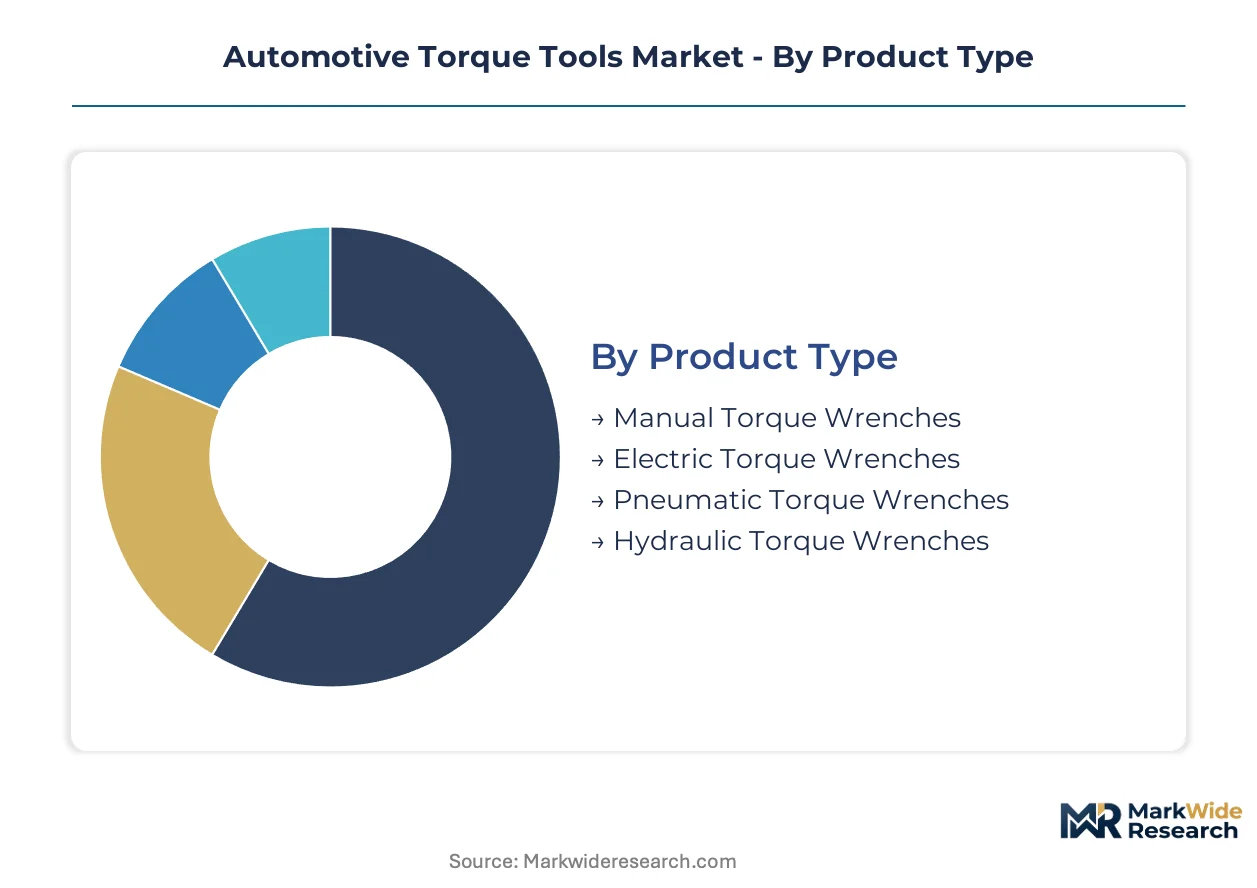
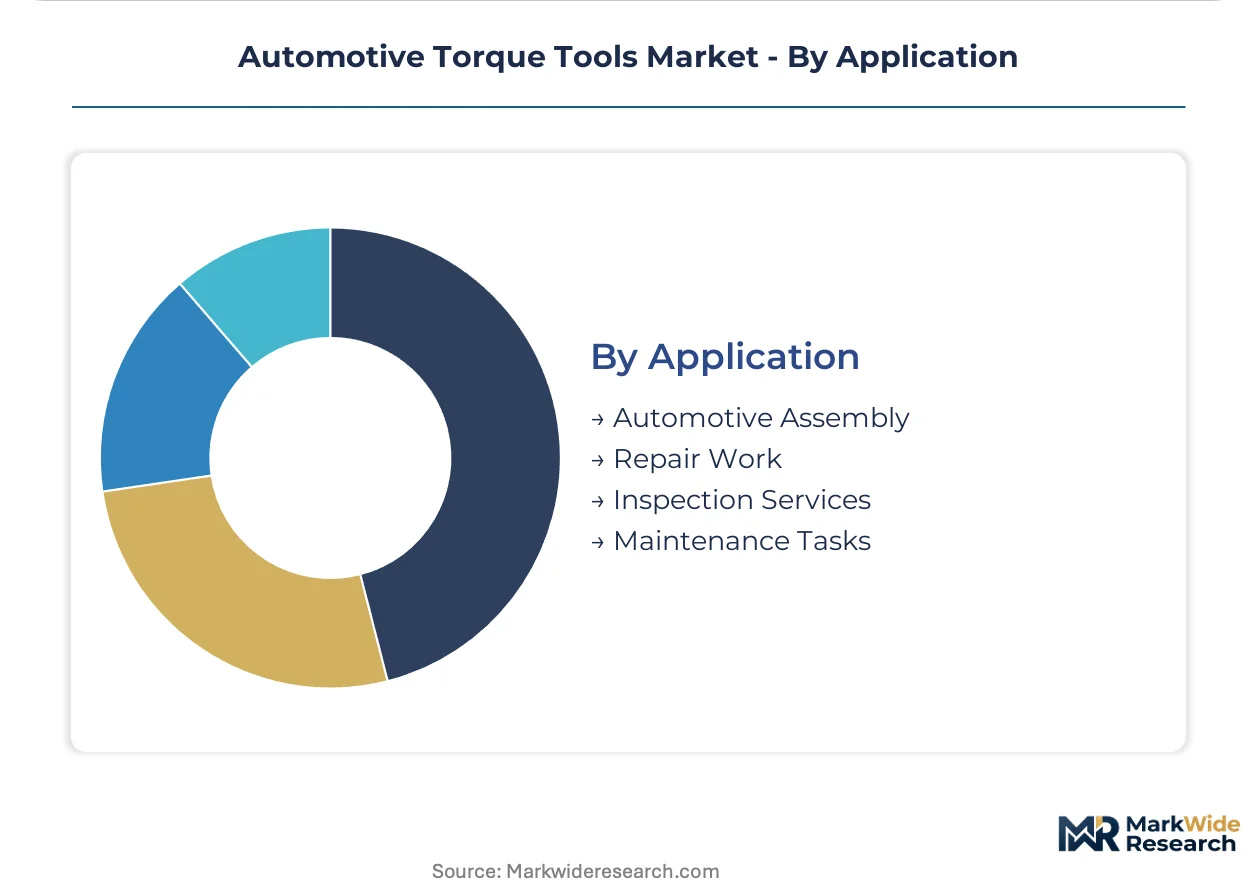
Segmentation in automotive torque tooling reveals how procurement priorities diverge between precision-driven EV battery assembly and cost-sensitive aftermarket service. Each dimension exposes distinct buyer logic: capital-intensive manufacturers prioritize calibration and connectivity, while independent shops favor durability and price accessibility.
Product Type:
Buyers in this category separate by capital intensity and accuracy requirements, with EV manufacturers tolerating premium pricing for precision while legacy service channels resist infrastructure overhaul costs.
- Electric Torque Wrenches:Brushless DC motor systems deliver electronically controlled torque delivery within plus or minus two percent accuracy. Demand concentrates at greenfield EV battery plants in Germany and South Korea where cordless nutrunners eliminate compressed air infrastructure. OSHA workplace noise enforcement accelerates displacement of pneumatic alternatives in US assembly operations.
- Manual Torque Wrenches:Beam and click-type mechanisms provide calibrated mechanical torque without power dependency. Volume concentrates in aftermarket service channels across India and Brazil where capital constraints limit digital tool adoption and ISO 6789 recertification cycles sustain replacement demand.
- Pneumatic Torque Wrenches:Vane motor actuation remains entrenched at brownfield internal combustion engine plants with existing compressed air infrastructure.
- Hydraulic Torque Wrenches:High-force applications in heavy-duty commercial vehicle assembly require multi-thousand Newton-meter capacity beyond electric motor limits.
Manual torque wrenches lead volumes today; electric torque wrenches are gaining share fastest.
End User:
Procurement scale and technical specification authority distinguish buyers, with vehicle assemblers dictating precision standards that cascade through supplier tiers.
- Vehicle Assemblers:Tier-one manufacturers specify strain-gauge equipped fastening systems for warranty-defensible clamp-load documentation. Battery pack assembly lines at Hyundai and SK Innovation facilities in South Korea mandate cloud-connected audit trails for every critical joint.
- OEMs:Original equipment manufacturers procure calibrated tool fleets for powertrain component supplier qualification and inbound quality verification. Stuttgart-based premium vehicle platforms require CE-marked digital tools compliant with EU Machinery Directive specifications.
- Aftermarket Service Providers:Fleet maintenance depots prioritize mobile tool distribution and subscription-based calibration access over capital ownership.
- Maintenance Shops:Independent repair operations favor manual and entry-level electronic tools with extended service intervals and minimal metrology dependency.
Vehicle assemblers command the steepest expansion trajectory; maintenance shops anchor volume concentration.
Technology:
Maturity gradients separate segments, with established mechanical platforms defending installed base against data-centric smart tool architectures.
- Smart Torque Tools:Wireless connectivity and MES/ERP integration transform fastening into traceable quality events with cloud-stored torque-angle curves. Premium assemblers in Germany and Japan deploy these systems for battery electric vehicle warranty defense against thermal runaway liability claims.
- Digital Torque Tools:LCD displays and programmable target settings bridge mechanical reliability with electronic feedback. Mid-tier vehicle assemblers in Mexico and Eastern Europe adopt these for ISO 6789 compliance without full smart tool infrastructure investment.
- Electronic Torque Tools:Basic strain-gauge measurement without connectivity serves cost-conscious precision requirements.
- Mechanical Torque Tools:Calibrated spring and beam mechanisms persist where electromagnetic interference or explosive atmospheres prohibit electronics.
Mechanical torque tools retain volume dominance; smart torque tools are expanding most quickly.
Application:
Process criticality determines specification stringency, with safety-critical assembly operations demanding calibration traceability absent in routine maintenance.
- Automotive Assembly:High-volume production lines require synchronized tool fleets with centralized calibration management and real-time defect alerting. EV powertrain fastening at Tesla's Berlin-Brandenburg facility exemplifies this specification tier.
- Repair Work:Variable job-shop environments favor adaptable tool platforms with quick-change drive configurations. US dealership service departments balance OEM warranty requirements against flat-rate labor economics.
- Inspection Services:Third-party quality auditors require ISO 17025-traceable calibration certificates for regulatory submission.
- Maintenance Tasks:Scheduled preventive maintenance operates on extended tool life cycles with minimal accuracy verification between annual service intervals.
Automotive assembly leads value concentration; inspection services are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration patterns reveal a widening cost-of-compliance arbitrage between jurisdictions with stringent calibration mandates and emerging manufacturing zones where enforcement remains uneven. Tool suppliers face divergent certification burdens across major automotive corridors.
United States
OSHA workplace noise exposure limits accelerate pneumatic-to-electric tool transitions at vehicle assembly plants in Michigan and Tennessee. The Department of Labor enforces permissible exposure limits that render compressed air systems economically unviable for new capital investments. Detroit's automotive corridor concentrates procurement of cordless nutrunners for EV retooling programs.
Germany
CE marking requirements under the EU Machinery Directive shape procurement specifications for Stuttgart and Wolfsburg manufacturing clusters. REACH substance restrictions and RoHS compliance reshape material specifications for torque tool housings sold into European markets. The Baden-Württemberg automotive corridor anchors industrial-grade electric fastening system demand for premium vehicle platforms.
China
GB standards and MIIT industrial policy directives accelerate domestic precision tool manufacturing capacity expansion. Dual carbon goals pressure factory floors to eliminate energy-intensive pneumatic infrastructure in favor of electric alternatives. The Yangtze River Delta battery pack assembly corridor drives specification of strain-gauge equipped fastening systems for export-bound EV production.
Japan
METI industrial standards and JIS calibration specifications maintain rigorous quality verification protocols for automotive assembly equipment. PMDA-adjacent quality management practices influence supplier qualification requirements for precision fastening systems. The Nagoya-Toyota manufacturing belt concentrates demand for cloud-connected audit trail systems among tier-one assemblers.
South Korea
MFDS-aligned quality frameworks and KSA industrial standards govern tool calibration protocols for battery electric vehicle production. Government-backed EV transition subsidies accelerate greenfield plant construction with electric-first tooling specifications. The Gyeonggi-do battery manufacturing cluster around SK Innovation and LG Energy Solution facilities mandates precision fastening systems with wireless data logging capabilities.
Automotive Torque Tools Market Vendor Landscape
Portfolio diversification dominates the current landscape as established tool manufacturers reposition around EV powertrain assembly requirements. The vendor base separates into three distinct tiers: diversified industrial conglomerates with cordless platform breadth, specialized precision fastening equipment manufacturers with metrology expertise, and mobile distribution networks serving aftermarket channels. Strategic archetypes include platform-integrated hardware suppliers, calibration-service bundlers, and fleet-focused tool-as-a-service operators. M&A activity and technology licensing agreements represent the primary competitive vectors reshaping market structure.
Among diversified industrial tool manufacturers, Stanley Black & Decker and Snap-on Incorporated exemplify contrasting distribution archetypes. Atlas Copco AB occupies a position within the industrial-grade precision equipment tier, representing European engineering specialization in assembly line nutrunner systems. These three anchors illustrate how competitive positioning fragments across factory floor installations versus mobile service depot penetration versus metrology-integrated precision systems.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Snap-on Incorporated |
| Apex Tool Group |
| Atlas Copco AB |
| Ingersoll Rand |
| Bosch |
| Makita Corporation |
| Norbar Torque Tools |
| DeWalt |
| Others |
Supply Flow & Price Mechanics
ISO 6789 calibration mandates from European vehicle assemblers are forcing suppliers to absorb recurring metrology service costs into hardware pricing, compressing margins on mid-tier digital torque wrench offerings while premium smart tool vendors capture value through subscription unbundling. This specification-driven procurement shift rewards certified tool providers with service network density and penalizes distributors lacking geographic calibration coverage.
Pricing Analysis
Distributor markups of 25-35% on industrial-grade electric nutrunners separate factory-direct OEM pricing from aftermarket channel economics. Three-tier pricing structure across premium smart tools, standard digital wrenches, and economy manual alternatives reflects calibration certification grade and connectivity features. Cost compression in mid-tier electronic segments is intensifying because strain-gauge sensor input volatility erodes manufacturing margins. Fleet maintenance depots exhibit highest price sensitivity due to capital constraints, while German premium vehicle assemblers demonstrate lowest sensitivity given warranty defense requirements.
Supply Chain Analysis
Freight cost differentials between Asian component sources and European assembly markets favor regional manufacturing footprints for finished torque tools. Brushless DC motors and strain-gauge sensors draw from China, Japan, and Germany; precision gearboxes and battery cells rest on South Korean and Chinese supply bases. Single-source vulnerability concentrates in high-precision sensor components where qualified suppliers number fewer than ten globally. Distribution runs through authorized industrial distributors for factory floor sales and mobile tool trucks serving aftermarket service depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Automotive Torque Tools Market functions as a stable compounder anchored by mandatory ISO 6789 recertification cycles that sustain replacement demand regardless of vehicle production cyclicality.
For Market Incumbents: Hedge against cordless platform commoditization by deepening metrology service network density in Stuttgart and Wolfsburg manufacturing corridors. Acquire specialized calibration providers to defend margin position against unbundled subscription competitors. Prioritize MES/ERP integration capabilities that brownfield plants require for smart tool deployment. For New Entrants and Emerging Players: Independent repair chains in India and Brazil represent the most penetrable buyer archetype for affordable digital torque tools with extended calibration intervals. Target fleet maintenance depots with tool-as-a-service offerings that eliminate upfront capital barriers. Pursue mobile distribution partnerships rather than direct sales force buildout. For Investors and Strategic Acquirers: Asymmetric upside sits with precision fastening equipment manufacturers possessing captive metrology expertise and CE marking regulatory capabilities. The 5-10 year viability window favors targets with established service contract revenue streams over pure hardware vendors. Monitor EV battery plant construction announcements as inflection indicators for industrial-grade electric nutrunner demand.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Network Expansion | CE marking compliance and ISO 6789 mandates from German OEMs require geographic proximity to manufacturing clusters. |
| Smart Tool Platform Integration | Cloud-connected audit trails satisfy Hyundai and SK Innovation battery plant specifications for warranty documentation. |
| Mobile Distribution Channel Development | Fleet maintenance depots in North America favor subscription-based calibrated tool access over capital ownership. |
| Brushless DC Motor Manufacturing Scale-Up | Cordless electric nutrunners specified at Tesla Berlin-Brandenburg displace pneumatic infrastructure investments. |
| Metrology Technician Training Programs | Aging specialist workforces constrain ISO 6789 service network expansion across distributed maintenance operations. |
Methodological Framework
Direct dialogue with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributor principals, and calibration service technicians grounded qualitative findings in operational reality. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings of listed tool manufacturers, and EU Machinery Directive implementation guidance. Bottom-up segment sizing triangulated against top-down industry value estimates across product type, end user, technology, and application dimensions.
Forecasts produced annual growth trajectories across the projection horizon by modeling penetration rates of electric versus pneumatic tools, EV powertrain content per vehicle, and aftermarket replacement cycles. Segmentation dimensions included tool actuation technology, buyer capital intensity, calibration connectivity tier, and regional regulatory enforcement stringency. CAGRs derived from weighted average of historical replacement patterns and announced greenfield plant tooling specifications.
Inputs from OEM procurement teams and calibration service providers were available through the study window; gaps in brownfield plant MES integration timelines introduce uncertainty bands around smart tool adoption velocity. Forecasts reflect assumptions regarding EV platform standardization and ISO 6789 enforcement consistency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Parting-Off Blades Market
Tools
Woodworking Router Bits Market
Tools
Global Tools Storage Products Market
Tools
CNC Metal Cutting Machine Tools Market
Tools
Global Swaging Machine Market
Tools
Ripper Market
Tools
Wood-Sanding Machine Market
Tools
Cordless Trim Routers Market
Tools
Metal Forming Tools Market
Tools
Clamps Market
Tools
Tile Cutter Market
Tools
Stationary Wood Planer Market
Tools
Drywall Tool Market
Tools
Concrete Saw Market
Tools
Manual Cutting Equipment Market
Tools
Assembly Fastening Tool Market