
 Rubber Tired Gantry (RTG) Crane Market | 2026-2036
Rubber Tired Gantry (RTG) Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber Tired Gantry (RTG) Crane Market Analytics
Buyer concentration among top-ten global container terminal operators is rebalancing as second-tier ports in Vietnam, Indonesia, and India fragment procurement across regional vendors. Konecranes leverages its automation software stack to anchor premium contracts at transshipment hubs. Shanghai Zhenhua Heavy Industries Co., Ltd. dominates manufacturing scale, sustaining cost advantages on large electric orders. Kalmar differentiates through hybrid powertrain integration, positioning its offering for ports with strict emissions rules.
A rubber tired gantry crane is a mobile container handling crane mounted on rubber tires, typically spanning six to eight container rows with lifting capacities of 40 to 50 metric tons, designed for stacking and transferring intermodal containers within terminal yards. Its primary purpose is to optimize yard density and vessel turnaround times at ports and inland freight facilities. Electric and hybrid product types are capturing margin pools as diesel faces regulatory compression across European and East Asian ports. Automated and remote-controlled technology segments are expanding fastest, though conventional systems still occupy the majority of installed base in emerging markets.
EU port authorities enforce the F-Gas Regulation and local emissions standards that restrict diesel RTG operations, while China's MEE mandates dual carbon compliance timelines for domestic terminal equipment. The International Organization for Standardization and IEC frameworks govern crane safety and electromagnetic compatibility, shaping product certification requirements for cross-border sales. Stakeholders must monitor how automation retrofits interact with evolving cybersecurity standards and port labor agreements.
Market Dynamics
Electrification mandates from port authorities are compressing diesel RTG lifecycles and forcing capital redeployment toward hybrid and fully electric stackers before residual value collapse.
Growth Catalysts
- EU F-Gas Regulation:Terminal operators in Rotterdam and Hamburg face operational restrictions on diesel equipment, accelerating fleet renewal timelines for compliant alternatives.
- Transshipment volume surge:Southeast Asian manufacturing relocation is expanding container throughput at Cai Mep and Tanjung Priok, requiring additional yard crane capacity.
- Automation software integration:Terminal operating systems from vendors like Navis are embedding crane control modules, reducing human-operator dependencies in high-lane-density yards.
Market Restraints
- Steel and copper input volatility:Crane superstructure fabrication depends on commodity-priced materials, exposing manufacturers to margin compression during supply shocks.
- Chinese manufacturing concentration:Heavy fabrication capacity clusters in Shanghai and Nantong, creating single-source vulnerability for European and Latin American buyers.
- Battery energy density limitations:Current lithium-ion configurations restrict continuous duty cycles for high-throughput terminals, forcing hybrid compromises.
Strategic Opportunities
- Vietnam port expansion:Lach Huyen and Cai Lan terminals are greenfield developments without legacy diesel infrastructure, enabling pure-electric deployments from commissioning.
- EU Green Deal funding windows:Sustainable transport infrastructure grants cover 30-50% of electrification capex for qualifying port authorities.
- Predictive maintenance convergence:IoT sensor networks and digital twin modeling are merging to offer uptime-guarantee service contracts.
Industry Challenges
- Automation technician scarcity:Ports in India and Indonesia lack sufficient PLC programmers and crane control specialists to support retrofitted remote-operation systems.
- Legacy yard infrastructure incompatibility:Older terminals with narrow lane spacing and uneven surfaces require civil works before automated crane installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber Tired Gantry (RTG) Crane Market |
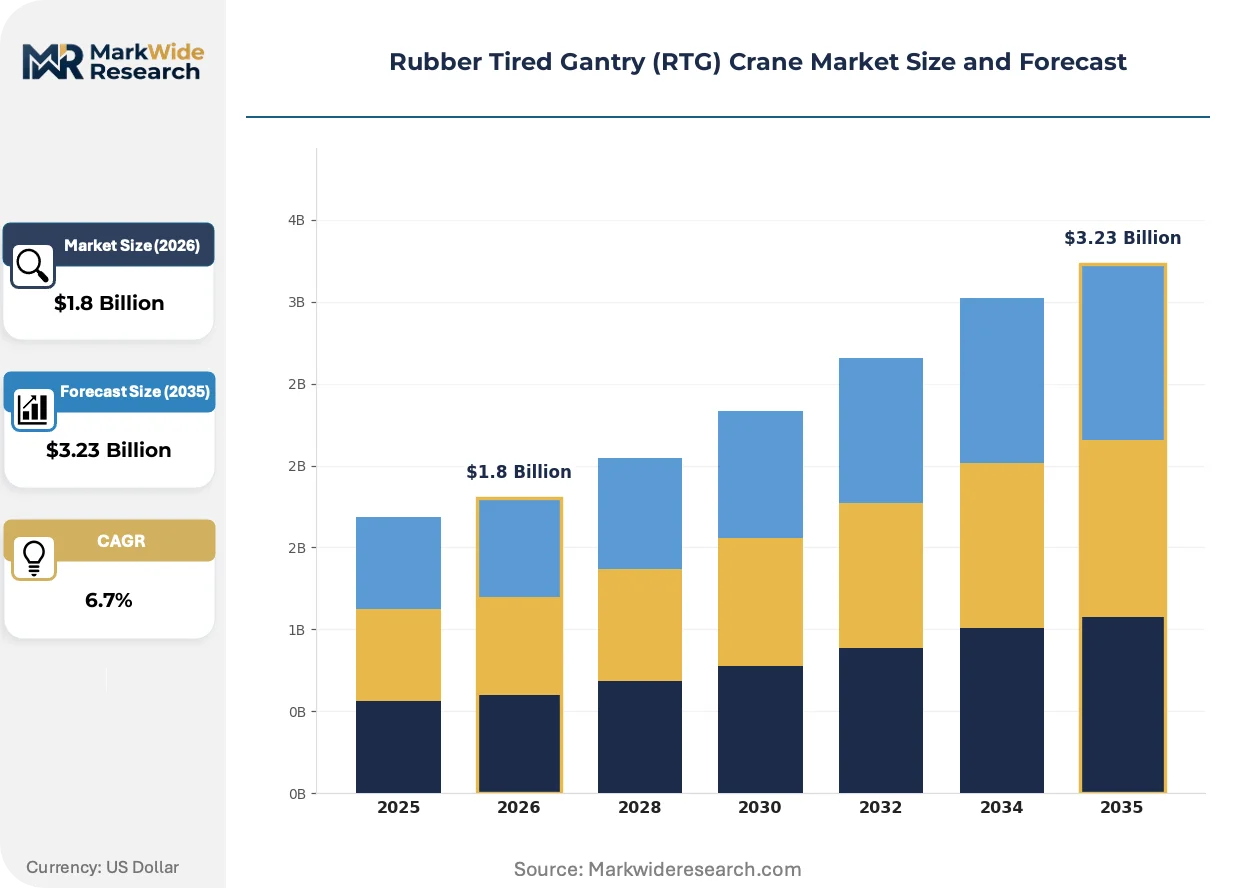
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Diesel, Hybrid, Manual Application: Container Handling, Maintenance, Heavy Lifting, Warehouse Operations End User: Ports, Freight Terminals, Shipping Companies, Logistic Providers Technology: Automated, Remote-Controlled, Teleoperated, Conventional |
| Companies Covered | Shanghai Zhenhua Heavy Industries Co., Ltd., Mi-Jack Products, Konecranes, Anupam Industries Limited, Cargotec, Kalmar, SANY Group, ELECTROMECH MATERIAL HANDLING SYSTEMS (INDIA) PVT. LTD., Liebherr, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber Tired Gantry (RTG) Crane Market Evolving Landscape
Remote operation and autonomous stacking are converging to redefine labor models and safety protocols in container yards. Equipment vendors are racing to integrate these capabilities into standard product lines.
Lithium-iron-phosphate battery systems are consolidating as the dominant energy storage architecture for electric RTGs. Major transshipment hubs in Singapore and Barcelona are specifying this chemistry for its thermal stability and cycle life. The technology is consolidating procurement specifications and marginalizing nickel-cobalt alternatives in port electrification tenders.
The EU F-Gas Regulation and national emissions standards are phasing out diesel RTG operations in North Sea and Mediterranean ports. Terminal operators must demonstrate compliance through equipment replacement or exhaust after-treatment retrofits. Electric and hybrid product categories are capturing preference share in procurement evaluations as a direct response.
Terminal operators are unbundling crane purchases from long-term maintenance contracts. Large container lines like MSC and CMA CGM are negotiating direct equipment procurement while sourcing aftermarket services from third-party specialists. This pattern is most visible in emerging markets where OEM service networks remain underdeveloped.
Rubber Tired Gantry (RTG) Crane Market Segmentation
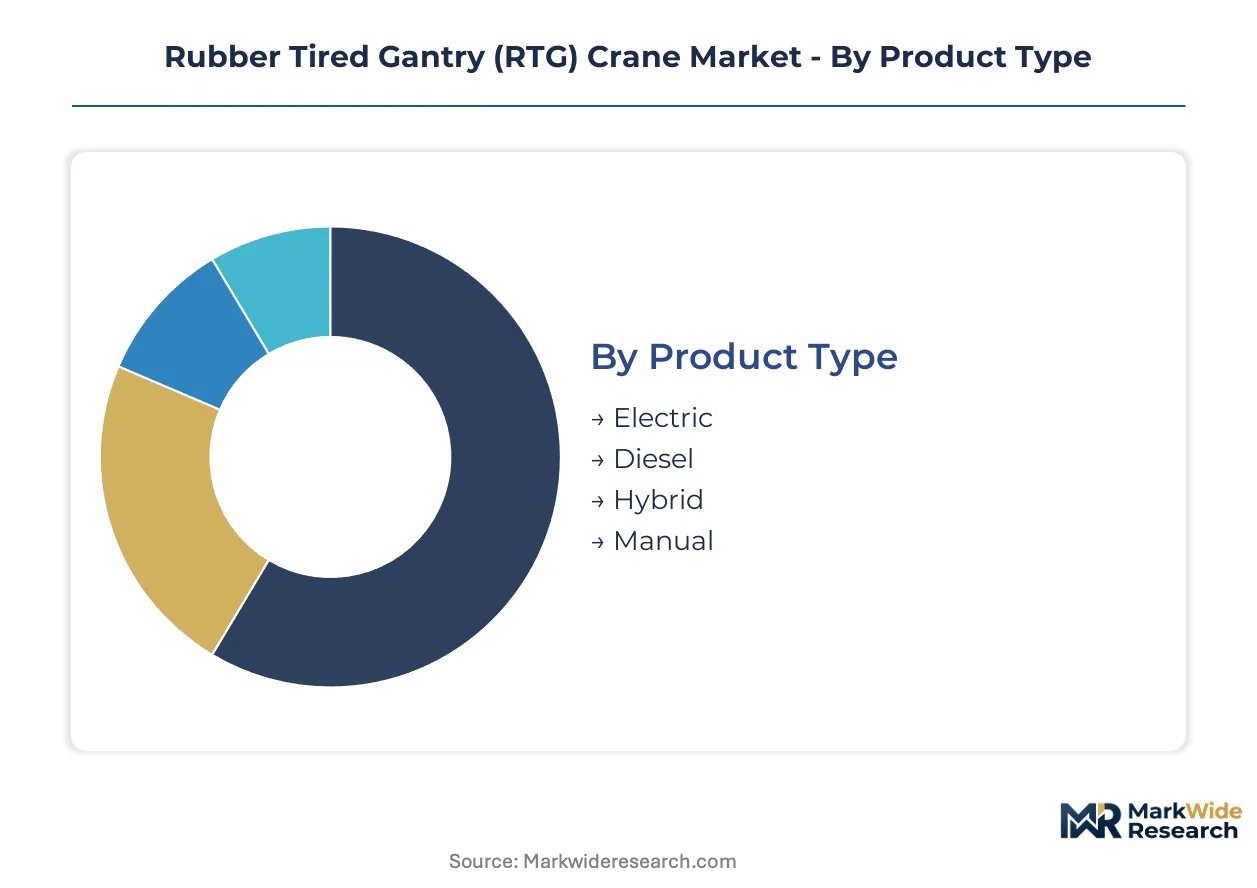
RTG crane procurement decisions hinge on powertrain compatibility with port infrastructure, yard automation readiness, and throughput requirements. Terminal operators evaluate segments against regulatory deadlines, labor availability, and retrofit feasibility before committing capital.
Product Type:
Upgrade cycles vary sharply by powertrain, with electrification mandates compressing diesel replacement timelines while hybrid options bridge infrastructure gaps.
- Electric:Lithium-iron-phosphate battery systems deliver thermal stability for continuous stacking operations. Singapore's PSA terminals and Barcelona's port cluster specify this chemistry exclusively, driven by EU F-Gas Regulation compliance deadlines and zero-emission berth requirements.
- Diesel:Legacy fleets dominate installed bases in India and Indonesia where grid infrastructure remains insufficient for pure-electric conversion. Residual values are collapsing in European ports as operational restrictions take effect.
- Hybrid:Combines diesel generators with battery buffers to maintain duty cycles during peak container movements. Vietnam's Cai Mep terminal operators favor this architecture for transshipment volume surges without full grid dependency.
- Manual:Human-powered systems persist in small-scale inland freight facilities with low container volumes and minimal automation budgets.
Electric sits at the top of the volume ranking, with Hybrid climbing the fastest as ports balance emissions compliance against infrastructure constraints.
Application:
Cost tier differentiation separates high-throughput transshipment hubs from maintenance-heavy secondary terminals with intermittent crane utilization.
- Container Handling:Primary stacking and vessel-to-yard transfers at density-optimized terminals. Vietnam's Lach Huyen and Indonesia's Tanjung Priok are expanding fleets to capture manufacturing relocation from China.
- Heavy Lifting:Out-of-gauge cargo and breakbulk operations requiring reinforced superstructures. Limited deployment at specialized multipurpose terminals with non-container revenue streams.
- Maintenance:Periodic yard equipment repositioning and infrastructure repair support. Lower utilization rates characterize this segment across secondary ports in India.
- Warehouse Operations:Indoor container storage and cross-dock facilities with height-restricted environments and controlled atmosphere requirements.
Container Handling commands the largest procurement budgets, with Heavy Lifting gaining share fastest in multipurpose terminal expansions.
End User:
Customer type determines contract structure complexity, with global container lines demanding automation integration while regional logistics providers prioritize acquisition cost.
- Ports:Public and private terminal authorities managing multi-operator facilities. Rotterdam and Hamburg port authorities enforce electrification mandates through concession agreements.
- Shipping Companies:MSC and CMA CGM are unbundling equipment purchases from maintenance contracts, sourcing RTGs directly while negotiating aftermarket services separately.
- Freight Terminals:Inland intermodal facilities with lower throughput and narrower lane spacing that constrains automated crane deployment.
- Logistic Providers:Third-party operators with variable demand profiles and shorter equipment replacement cycles.
Ports absorb the majority of capital expenditure, with Shipping Companies expanding fleet ownership fastest as vertical integration deepens.
Technology:
Maturity gradients separate established conventional systems from emerging autonomous stacks requiring cybersecurity protocols and labor retraining.
- Automated:Fully autonomous stacking with terminal operating system integration and collision avoidance sensors. Singapore's next-generation yards specify this capability for 24-hour operations with minimal staffing.
- Remote-Controlled:Operator stations relocated from cabin to control room via camera networks and latency-optimized connectivity. Barcelona and Rotterdam terminals deploy this intermediate step toward full automation.
- Teleoperated:Human operators retain direct control through networked interfaces, bridging gaps where AI stacking algorithms remain unproven.
- Conventional:Cabin-based manual operation dominating installed bases in India and Indonesia where technician scarcity limits retrofit feasibility.
Conventional retains the largest installed base, with Automated expanding most quickly in greenfield transshipment hubs lacking legacy infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's port electrification momentum contrasts with India's diesel-dependent legacy fleets, revealing divergent infrastructure readiness across emerging manufacturing hubs. Terminal operators in Southeast Asia are capturing supply chain relocation flows while European ports enforce accelerated equipment replacement cycles.
Germany
Transshipment hubs at Hamburg and Bremerhaven are converting diesel RTG fleets under EU F-Gas Regulation deadlines. The federal government channels EU Green Deal infrastructure grants toward terminal electrification projects. North Sea port clusters are specifying lithium-iron-phosphate battery systems for new crane procurements.
Vietnam
Lach Huyen and Cai Mep terminals are expanding yard capacity to handle manufacturing relocation from China. The Ministry of Transport prioritizes greenfield port developments with pure-electric infrastructure from commissioning. Northern port provinces are attracting fleet orders without legacy diesel equipment constraints.
Indonesia
Tanjung Priok and Surabaya terminals are scaling RTG deployments for transshipment volume growth. The national port authority issues concession agreements favoring hybrid powertrain specifications. Java-based manufacturing corridors are driving container throughput expansion requiring additional yard crane density.
Singapore
PSA terminals are specifying fully automated RTG systems for 24-hour operations with minimal staffing. The Maritime and Port Authority mandates zero-emission berth requirements at major terminals. Tuas Port development is embedding autonomous stacking capabilities into greenfield crane specifications.
Netherlands
Rotterdam port authority enforces electrification mandates through terminal concession renegotiations. The national government covers 30-50% of electrification capital expenditure through sustainable transport infrastructure programs. Maasvlakte terminal operators are retrofitting remote-control capabilities onto existing crane fleets.
Rubber Tired Gantry (RTG) Crane Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure that concentrates fabrication capacity in East Asian manufacturing clusters. Tiered procurement patterns separate premium automation-integrated contracts from cost-driven bulk orders. Strategic archetypes include scale-driven heavy fabricators, hybrid powertrain integrators, and automation software providers. Competitive moves center on backward integration into battery supply chains and geographic expansion through regional service partnerships.
Among Chinese fabricators, Shanghai Zhenhua Heavy Industries Co., Ltd. and SANY Group exemplify scale-driven manufacturing archetypes serving high-volume electric orders. Konecranes anchors the automation-integrated premium tier, while Kalmar occupies a position within hybrid powertrain specialization for emissions-regulated ports.
| Leading Market Players |
|---|
| Shanghai Zhenhua Heavy Industries Co., Ltd. |
| Mi-Jack Products |
| Konecranes |
| Anupam Industries Limited |
| Cargotec |
| Kalmar |
| SANY Group |
| ELECTROMECH MATERIAL HANDLING SYSTEMS (INDIA) PVT. LTD. |
| Liebherr |
| Others |
Value Network & Pricing Analysis
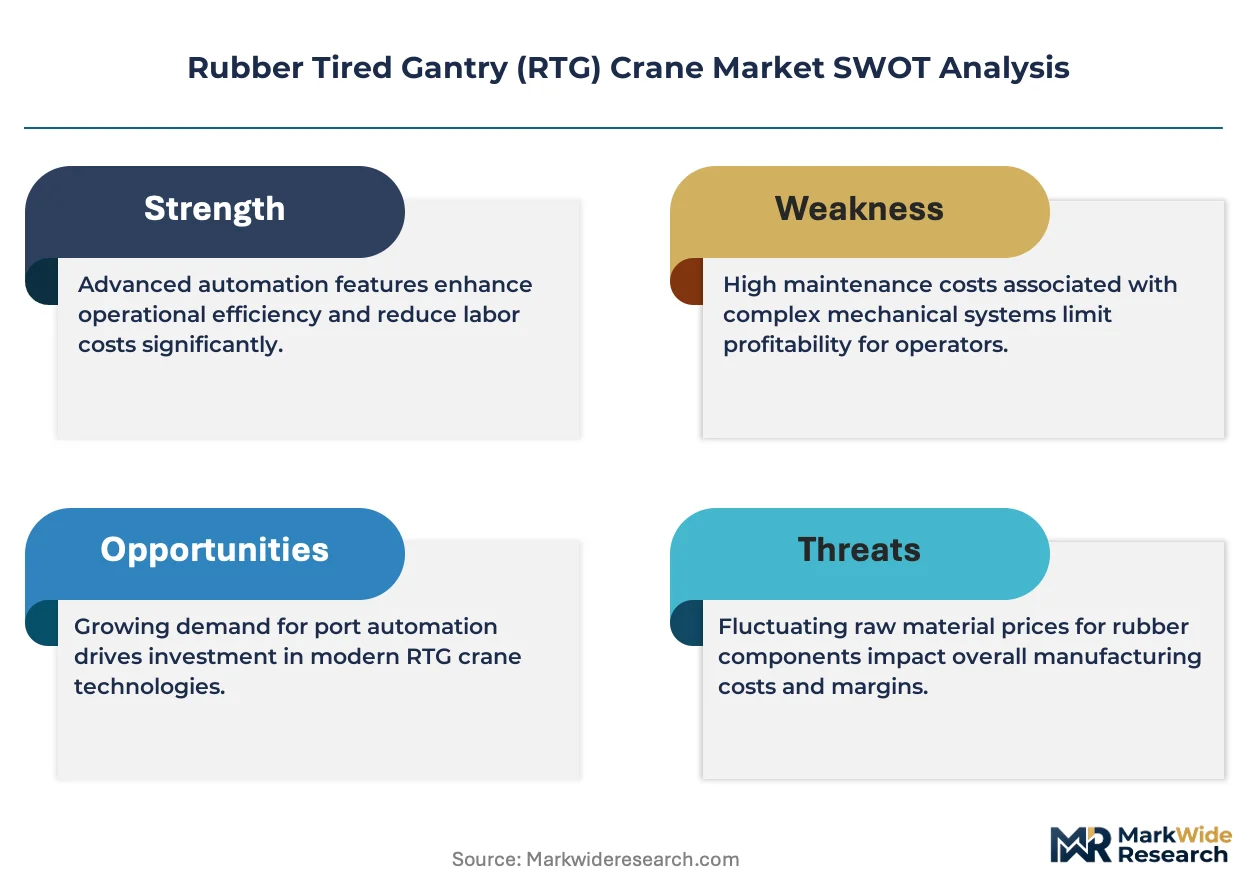
Certification-grade divergence between automation-integrated premium RTGs and conventional manual systems manifests in pricing spreads exceeding three-to-one, while supply chain configurations cluster fabrication capacity in Shanghai and Nantong for cost-tier units versus Finland and Sweden for software-anchored premium tiers. This bifurcation concentrates margin capture among hybrid powertrain specialists serving EU F-Gas compliance deadlines.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for electric RTG superstructures, compressing margins for regional fabricators serving Southeast Asian bulk orders. Three-tier pricing structure across premium automation-integrated, standard hybrid, and economy manual levels differentiates by software stack depth and battery chemistry specification. Cost compression in economy tiers intensifies because Vietnamese and Indonesian terminal operators prioritize acquisition cost over lifecycle service bundling. Shipping companies like MSC and CMA CGM demonstrate lowest price sensitivity, absorbing automation premiums for unbundled procurement structures.
Supply Chain Analysis
Welder and crane control specialist scarcity in Shanghai and Nantong is constraining output elasticity for high-volume electric orders. Heavy fabrication draws from Chinese steel mills, South Korean battery cell suppliers, and German sensor component manufacturers. Single-source vulnerability concentrates in Shanghai Zhenhua Heavy Industries' dominance of superstructure welding capacity. Distribution runs through direct OEM-terminal operator contracts for premium tiers, while regional distributors handle aftermarket parts for legacy diesel fleets in India and Indonesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The RTG crane market compounds steadily as container throughput at Southeast Asian transshipment hubs expands manufacturing relocation flows from China, embedding recurring fleet renewal demand into terminal operator capital planning.
For Market Incumbents: Acquire battery system integration capabilities to anchor hybrid powertrain margins as EU F-Gas Regulation deadlines accelerate diesel replacement cycles. Secure exclusive service partnerships with Vietnam's Lach Huyen and Cai Mep terminals before greenfield commissioning locks in supplier relationships. Automation software differentiation from Navis-embedded control modules defends against Chinese fabricators' cost advantages on pure-electric orders. For New Entrants and Emerging Players: Regional aftermarket service providers in India and Indonesia represent the most penetrable channel partner type for automation retrofit contracts, given PLC programmer scarcity limits incumbent OEM service coverage. Target secondary ports in India's Jawaharlal Nehru Port Trust hinterland with teleoperated upgrade kits that bridge technician gaps without full autonomous stacking. Position through port authority electrification grant advisory services to access procurement decision-makers before tender issuance. For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid powertrain specialists possessing validated lithium-iron-phosphate integration for EU port compliance deadlines. Five-to-ten year viability hinges on automation software stack depth rather than fabrication scale alone. Monitor Vietnam Ministry of Transport greenfield port development announcements as inflection indicators for pure-electric deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Supply | Kalmar's hybrid powertrain margins expand through captive lithium-iron-phosphate cell sourcing. |
| Automation Software Licensing | Konecranes anchors premium contracts via Navis terminal operating system integration modules. |
| Regional Service Partnership Expansion | Third-party maintenance networks in Indonesia capture unbundled aftermarket contracts from MSC. |
| Greenfield Terminal Early Engagement | Pre-commissioning specification at Vietnam's Lach Huyen locks out retrofit competitors. |
| Predictive Maintenance Platform Launch | IoT sensor networks enable uptime-guarantee contracts at Singapore PSA terminals. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with terminal operations directors, port authority procurement leads, OEM sales engineers, and aftermarket service managers with secondary validation against customs trade data, port throughput statistics, and EU Green Deal funding disclosure records. Bottom-up equipment shipment tallies and top-down terminal capital expenditure forecasts were triangulated to anchor volume estimates.
Comparable historical fleet replacement cycles across Rotterdam, Hamburg, and Singapore provided reference anchors for projecting hybrid and electric adoption slopes over the projection horizon. Segmentation modeling incorporated powertrain type, automation technology tier, end-user category, and regional regulatory cluster dimensions. CAGRs were derived from fitted adoption curves weighted by announced port expansion timelines and electrification mandate enforcement schedules.
Revisions become necessary when EU F-Gas Regulation enforcement intensity shifts, battery energy density breakthroughs alter hybrid-electric economics, or Vietnam-Indonesia manufacturing relocation flows stall. Material deviation in transshipment volume growth or port authority grant funding availability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Conveyor Scales Market
Material Handling Equipment
Circular Stacker and Reclaimer Market
Material Handling Equipment
Forklift Work Platforms Market
Material Handling Equipment
Cable Conduit Systems Market
Material Handling Equipment
Torque Limiting Couplings Market
Material Handling Equipment
Vertical Lift Module (VLM) Market
Material Handling Equipment
Sifter Fitment Market
Material Handling Equipment
Modular Self-Contained Aisle and Racking Systems Market
Material Handling Equipment
Automated Material Handling (AMH) Market
Material Handling Equipment
East Africa Elevator and Escalator Market
Material Handling Equipment
Electric Stacker Market
Material Handling Equipment
High Pressure Grease Hose Market
Material Handling Equipment
Global Linear Guide Market
Material Handling Equipment
Mobile Crane Market
Material Handling Equipment
Overhead Hoist Transport (OHT) Market
Material Handling Equipment
Global Hydraulic Equipment Market