
 Industrial Bag Dust Filter Market | 2026-2036
Industrial Bag Dust Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Bag Dust Filter Market Analysis
ISO 16890 certification for filter testing and classification is redrawing competitive boundaries in the industrial bag dust filter sector. Donaldson Company Inc. leverages its vertical integration in filter media manufacturing to control quality from fiber to finished bag. Thermax Global anchors its position through captive engineering services bundled with baghouse installations across South Asian cement corridors. Parker Hannifin Corporation competes on hydraulic and pneumatic integration, offering filter systems that interface directly with plant automation architectures.
An industrial bag dust filter is a fabric-based separation device constructed from woven or non-woven media—typically polyester, aramid, or PTFE felts rated for 0.3 to 100 micron particle retention—installed in baghouse housings to capture particulate matter from industrial gas streams. Pulse jet filters dominate installed capacity due to their continuous-cleaning capability and compatibility with high dust-loading environments found in cement manufacturing and metal production. Baghouse systems retain the largest technology share while eco-friendly filter formulations using bio-based or recyclable media represent the fastest-expanding margin pool as end users face Scope 3 emissions accounting requirements.
The US EPA enforces Maximum Achievable Control Technology standards under the Clean Air Act that mandate particulate capture efficiency above 99 percent for major source categories, directly specifying baghouse or equivalent control for Portland cement kilns and secondary metal smelters. China's MEE implements GB 4915 emission limits for cement plants that compel filter media upgrades to PTFE membranes or hybrid composites capable of sustained sub-10 mg per cubic meter outlet concentrations. Stakeholders must weigh capital replacement cycles against emerging filter monitoring technologies that predict media failure before breach, shifting maintenance from scheduled to condition-based regimes.
Market Dynamics
Retrofit mandates for aging baghouse infrastructure are compressing replacement cycles across heavy industry, forcing capital allocation toward continuous-cleaning pulse jet systems over legacy mechanical shaker designs.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for fluorinated gases are accelerating membrane media upgrades to PTFE and hybrid composites in cement and steel installations across Germany, Poland, and Italy.
- China steel output:Blast furnace expansion along the Yangtze River corridor is absorbing high-temperature aramid filter capacity at rates outpacing regional supply.
- Predictive maintenance platforms:IoT-enabled differential pressure monitoring is converting scheduled bag replacement to condition-based regimes, extending effective filter life by 15-30 percent in pilot deployments.
Market Restraints
- PTFE resin supply concentration:Virgin polytetrafluoroethylene feedstock depends on Chinese and Japanese chemical producers, exposing filter manufacturers to input cost volatility and quota restrictions.
- Technical limitation at high moisture:Standard polyester felts suffer hydrolysis degradation above 130°C in wet gas streams, forcing expensive aramid or PPS substitutions in pulp and paper applications.
- Regulatory friction from REACH:Registration requirements for imported filter media containing nano-scale surface treatments are delaying European market entry for Asian suppliers by 12-18 months.
Strategic Opportunities
- India cement corridor expansion:Rajasthan and Madhya Pradesh greenfield plants are specifying integrated baghouse contracts with 10-year media supply agreements, locking in aftermarket revenue.
- Biodegradable filter media:PLA and PHA-based felts for non-critical dust loads are capturing Scope 3 accounting premiums from food processing and pharmaceutical packagers.
- Carbon capture integration:Baghouse upstream of amine scrubbers requires sub-5 mg outlet loading, creating specification tiers for membrane-laminated media in pilot CCS projects.
Industry Challenges
- Specialized welding certification:PTFE membrane bonding requires thermal seaming technicians scarce outside Germany and Japan, constraining local production scale-up.
- Legacy DCS integration:Pulse jet controllers from 1990s-vintage baghouses lack digital outputs for modern plant automation, forcing expensive control system retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Bag Dust Filter Market |
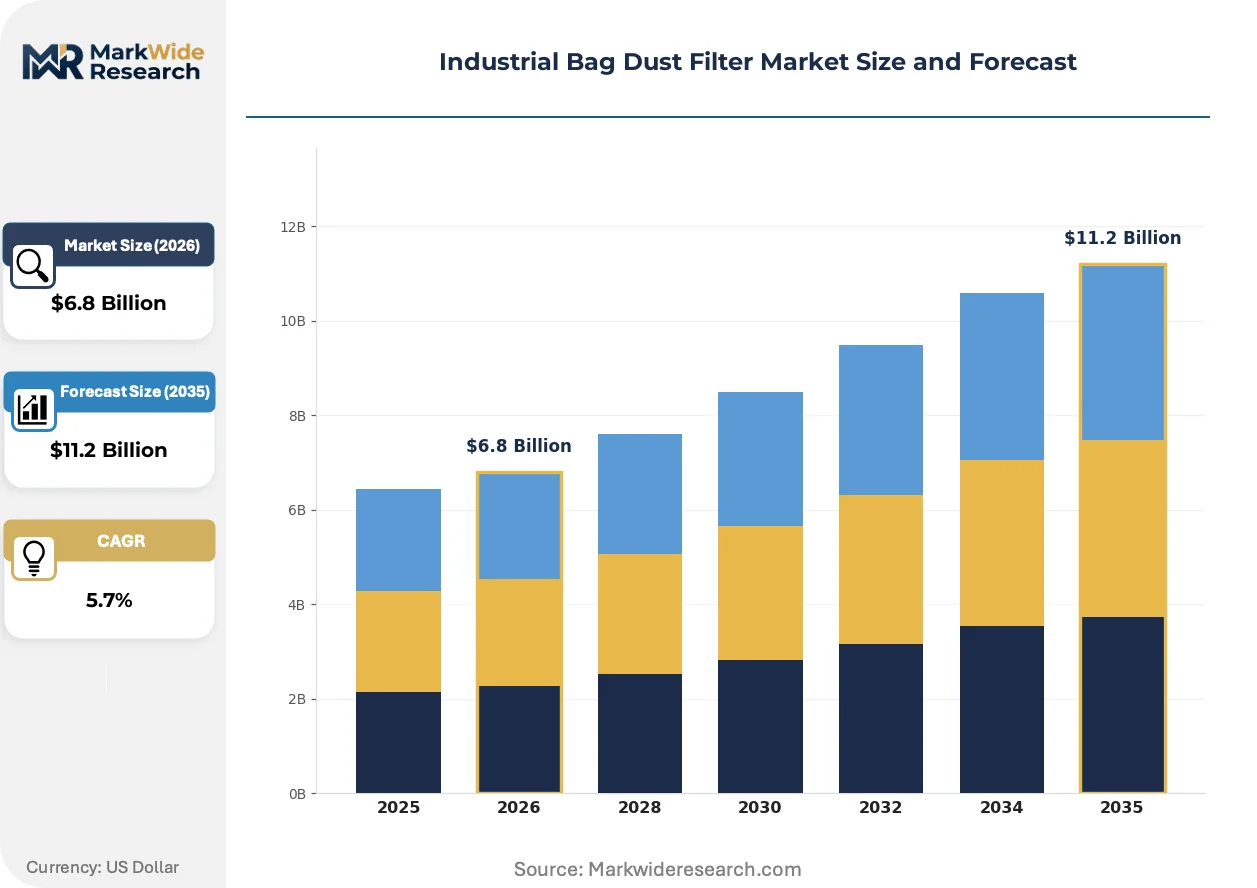
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pulse Jet Filters, Reverse Air Filters, Shaker Filters, Cartridge Filters Application: Cement Manufacturing, Chemical Processing, Metal Production, Food Processing Technology: Baghouse Systems, Eco-Friendly Filters, HEPA Filters, V-Bank Filters End User: Manufacturing Plants, Power Generation Facilities, Mining Operations, Pharmaceuticals |
| Companies Covered | Donaldson Company Inc., Thermax Global, Babcock & Wilcox Co., Parker Hannifin Corporation, Camfil Farr Inc., Eaton Corporation, Pall Corporation, Lenntech B.V., Filter Concept Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Bag Dust Filter Market Emerging Trajectories
Filter media engineering is converging with digital monitoring and circular material science, compressing the gap between commodity bag replacement and engineered air quality systems.
Membrane-laminated needle felts are miniaturizing effective pore structures to sub-micron scales without sacrificing permeability. Cement producers in Vietnam and Indonesia are specifying these composites for kiln bypass gas streams previously requiring electrostatic precipitators. The technology is miniaturizing the physical footprint of high-efficiency filtration, enabling baghouse retrofits where space constraints previously blocked upgrades.
EPA Maximum Achievable Control Technology reviews are tightening particulate limits for Portland cement and secondary aluminum smelters. The 2024 proposal lowers allowable outlet loading from 0.04 to 0.02 grains per dry standard cubic foot. Plants in Texas and California are pre-emptively installing PTFE membrane bags and upgrading pulse jet cleaning energy to meet anticipated enforcement.
Maintenance contracting is fragmenting from bundled OEM service to third-party specialty providers. Independent filter management firms in the US Midwest are offering guaranteed outlet concentration contracts, assuming operational risk for baghouse performance. This model is displacing capital purchase decisions with operating expenditure frameworks most visible in chemical processing and power generation facilities.
Industrial Bag Dust Filter Market Segmentation
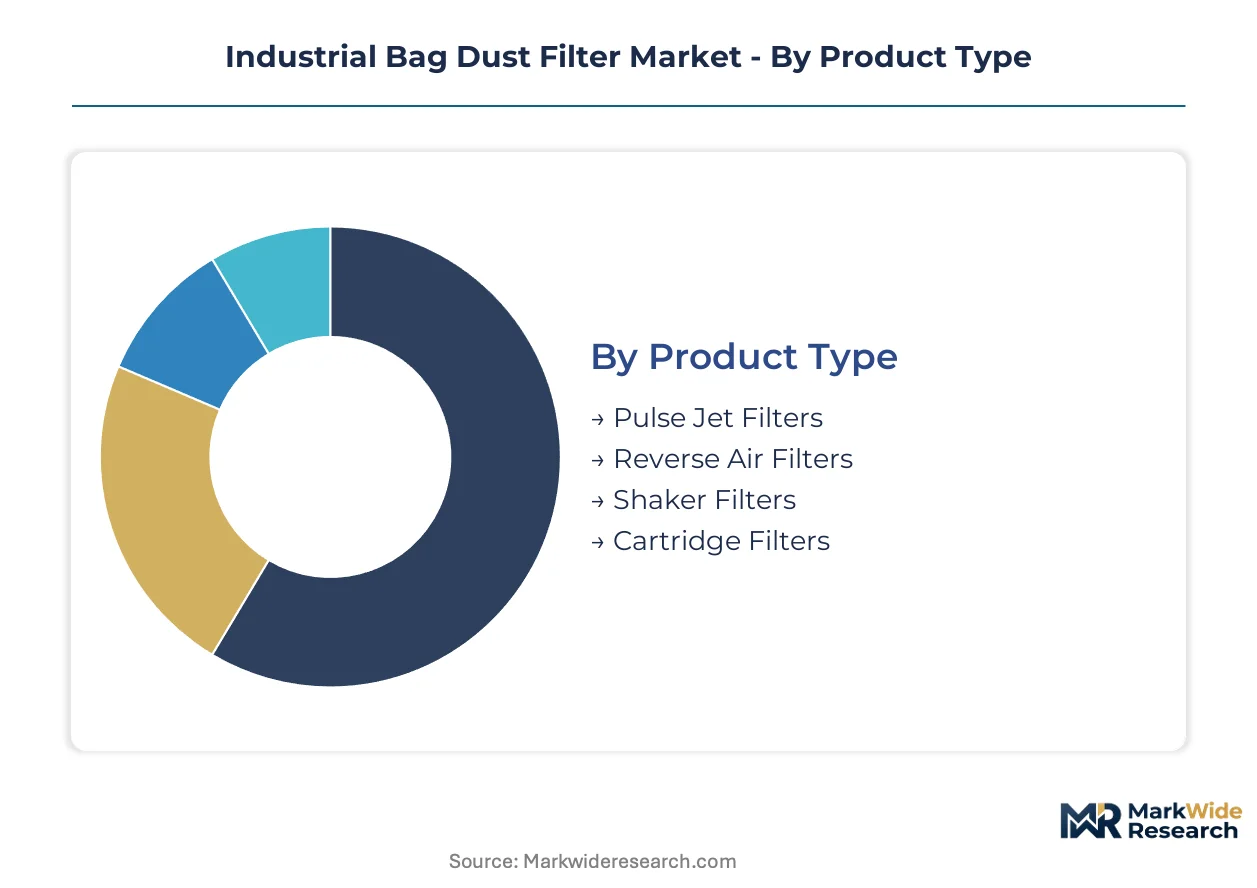
Industrial bag dust filter procurement decisions split across technical performance requirements, regulatory compliance tiers, and operational scale. Segmentation reveals where capital concentrates versus where specification margins expand.
Product Type:
EPA MACT standards and China's GB 4915 limits create divergent specification pathways across cleaning mechanisms.
- Pulse Jet Filters:Compressed-air pulse cleaning enables continuous operation without process shutdown. Cement plants in Vietnam and Indonesia specify these for kiln bypass retrofits where space constraints eliminated electrostatic precipitator options.
- Reverse Air Filters:Gentle cleaning action preserves delicate glass fiber or PTFE membranes in high-temperature steel foundry applications. Blast furnace expansion along China's Yangtze River corridor absorbs this capacity faster than regional supply can match.
- Shaker Filters:Mechanical shaking suits intermittent-duty operations in small-scale mining and quarrying where capital budgets exclude compressed-air infrastructure.
- Cartridge Filters:Pleated media geometry delivers higher surface area per footprint in pharmaceutical cleanrooms and food packaging lines requiring ISO 16890-compliant fine particulate capture.
Pulse jet configurations handle the majority of throughput; cartridge filters are gaining share fastest in retrofit-constrained urban manufacturing zones.
Application:
Emission limit stringency and dust loading severity separate applications by media specification and replacement frequency.
- Cement Manufacturing:Kiln systems, clinker coolers, and finish mills generate abrasive alkaline dust at 120-180°C. Plants in Rajasthan and Madhya Pradesh specify integrated baghouse contracts with decade-long media supply agreements.
- Chemical Processing:Aggressive acid or solvent vapors demand PTFE, PPS, or fiberglass media with corrosion-resistant finishes. REACH registration delays for nano-treated imports favor established European suppliers.
- Metal Production:Electric arc furnaces and secondary aluminum smelters push 200°C+ gas temperatures requiring aramid or hybrid ceramic felts.
- Food Processing:Bio-based PLA and PHA filter media capture Scope 3 accounting premiums from packagers facing supply chain carbon disclosure mandates.
Cement manufacturing anchors installed base volume; food processing shows the steepest specification upgrade trajectory as sustainability accounting tightens.
Technology:
Integration depth with plant automation and carbon capture architectures differentiates technology tiers.
- Baghouse Systems:Modular housing designs with configurable compartmentalization dominate heavy industry. Legacy 1990s-vintage pulse jet controllers lack digital outputs for modern DCS integration, forcing expensive control retrofits.
- Eco-Friendly Filters:Recyclable or biodegradable media formulations address Scope 3 emissions accounting in consumer-facing supply chains. Pilot deployments in European pharmaceutical packaging show 15-30 percent filter life extension through IoT-enabled differential pressure monitoring.
- HEPA Filters:Sub-micron efficiency ratings serve cleanroom and containment applications in active pharmaceutical ingredient manufacturing.
- V-Bank Filters:Compact geometry maximizes media area in space-constrained HVAC retrofits for commercial and institutional buildings.
Baghouse systems retain the dominant installed footprint; eco-friendly formulations are expanding most quickly on sustainability-linked procurement criteria.
End User:
Operational scale and maintenance capability determine whether users self-manage or outsource filter lifecycle management.
- Manufacturing Plants:Integrated production facilities with captive maintenance teams favor condition-based replacement regimes using predictive analytics platforms.
- Power Generation Facilities:Coal and biomass plants upstream of carbon capture systems require sub-5 mg outlet loading, creating specification tiers for membrane-laminated media in pilot CCS projects.
- Mining Operations:Remote site logistics favor extended-life media and bulk procurement contracts with regional distributors.
- Pharmaceuticals:cGMP compliance and batch record requirements drive validated filter change protocols with full traceability documentation.
Manufacturing plants represent the largest addressable base; pharmaceuticals command the highest specification premiums per unit volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers of industrial bag dust filters concentrate in heavy industry clusters where emission enforcement is tightening and aging infrastructure requires retrofit. Cement plants, steel mills, and chemical processors dominate procurement volumes across manufacturing belts in Asia, Europe, and North America.
China
Blast furnace expansion along the Yangtze River corridor and cement kiln upgrades in Shandong Province absorb high-temperature aramid filter capacity faster than regional supply can match. The Ministry of Ecology and Environment enforces GB 4915 emission limits that compel filter media upgrades to PTFE membranes or hybrid composites capable of sustained sub-10 mg per cubic meter outlet concentrations. Zhejiang and Jiangsu provinces host the densest concentration of baghouse retrofit activity as steel output scales.
United States
Portland cement kilns in Texas and secondary aluminum smelters in the Midwest face pre-emptive upgrades ahead of anticipated EPA Maximum Achievable Control Technology enforcement. The 2024 proposal lowers allowable outlet loading from 0.04 to 0.02 grains per dry standard cubic foot. California and Texas plants are installing PTFE membrane bags and upgrading pulse jet cleaning energy to meet stricter standards.
Germany
Cement manufacturers in the North Rhine-Westphalia industrial belt retrofit aging baghouse systems to meet tightening particulate emission rules under the EU F-Gas Regulation and Industrial Emissions Directive. Phase-down schedules for fluorinated gases accelerate membrane media upgrades to PTFE and hybrid composites. The Ruhr region and Bavarian cement corridors drive specification demand for ISO 16890-certified filter testing and classification.
India
Greenfield cement plants in Rajasthan and Madhya Pradesh specify integrated baghouse contracts with decade-long media supply agreements, locking in aftermarket revenue. The Central Electricity Authority and state pollution control boards enforce stricter stack emission norms for thermal power and cement. The Delhi-Mumbai Industrial Corridor and western cement belt anchor filter procurement volumes.
Japan
Specialized thermal seaming technicians for PTFE membrane bonding remain concentrated in Osaka and Nagoya industrial zones, constraining local production scale-up for export markets. METI standards and JIS certification requirements shape filter media specifications for domestic steel and chemical processors. The Chubu and Kansai regions maintain technical leadership in high-performance membrane fabrication.
Industrial Bag Dust Filter Market Vendor Landscape
Player mix skews toward diversified filtration conglomerates with captive media manufacturing and regional engineering specialists bundling installation with aftermarket service. Market structure shows moderate consolidation at the top tier with long-tail fragmentation among local fabricators and maintenance contractors. Two strategic archetypes dominate: vertically integrated multinationals controlling fiber-to-finished-bag quality chains, and project-centric regional players anchoring relationships through captive service networks. Competitive moves concentrate on backward integration into membrane lamination capacity and condition-based maintenance platform deployment.
Within the integrated multinational tier, Donaldson Company Inc. and Parker Hannifin Corporation exemplify archetypes of quality-controlled manufacturing and automation-ready system design respectively. Thermax Global occupies a position representing the project-centric regional model, anchoring market presence through bundled engineering services. These three entities illustrate how competitive positioning diverges between technology-led specification setting and relationship-driven aftermarket capture.
| Leading Market Players |
|---|
| Donaldson Company Inc. |
| Thermax Global |
| Babcock & Wilcox Co. |
| Parker Hannifin Corporation |
| Camfil Farr Inc. |
| Eaton Corporation |
| Pall Corporation |
| Lenntech B.V. |
| Filter Concept Pvt. Ltd. |
| Others |
Supply Flow & Price Mechanics
Blast furnace capacity utilization above 85 percent in China's Yangtze River corridor concentrates PTFE membrane demand among a handful of aramid fiber producers, compressing supplier margins while cement plants in Rajasthan negotiate decade-long media supply agreements that lock in price floors. This scale asymmetry between concentrated raw material supply and fragmented end-user procurement creates divergent pricing power across the value chain.
Pricing Analysis
Cost-plus contracts with virgin PTFE resin indexation dominate long-term agreements between filter manufacturers and cement producers in India and China. Price differentiation rests on ISO 16890 certification tier and pulse jet controller integration depth, with premium membrane-laminated bags commanding substantial spreads over standard polyester felts. Cost compression in the standard felt tier is intensifying because Chinese resin suppliers face export quota restrictions. Small-scale mining operations in Southeast Asia show the highest price sensitivity, while pharmaceutical cleanroom operators demonstrate minimal elasticity due to cGMP compliance requirements.
Supply Chain Analysis
Shanghai port congestion and Red Sea transit disruptions expose just-in-time filter media deliveries to 15-20 day delays, forcing cement plants to hold larger safety stocks. Geographic supply concentration centers on China, Japan, and Germany for virgin PTFE resin, high-temperature aramid fibers, and specialized thermal seaming equipment respectively. Raw material dependencies draw from fluoropolymer feedstocks, needle-punch nonwoven machinery, and nano-scale surface treatment chemistries. Single-source vulnerability persists for membrane lamination capacity outside Osaka and Nagoya industrial zones. Distribution runs through regional engineering specialists bundling installation with aftermarket service rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrostatic precipitator retrofits in Vietnamese and Indonesian cement plants threaten baghouse incumbent positions as space-constrained kiln bypass applications reconsider legacy technology. Incumbents must demonstrate continuous-cleaning pulse jet superiority against this substitute threat.
For Market Incumbents: Fortify backward integration into membrane lamination capacity to control quality from fiber to finished bag and neutralize Chinese resin cost volatility. Deploy IoT-enabled differential pressure monitoring platforms to convert scheduled replacement revenue into condition-based service contracts, defending against independent filter management firms offering guaranteed outlet concentration performance. Prioritize captive engineering service networks in South Asian cement corridors where Thermax Global has established bundled installation relationships. For New Entrants and Emerging Players: Lead with biodegradable PLA and PHA filter media for food processing and pharmaceutical packaging applications where Scope 3 emissions accounting creates specification premiums absent in commodity cement procurement. Target the European Union's F-Gas Regulation compliance window, where REACH registration delays for nano-treated imports from Asia create 12-18 month entry barriers for established suppliers. Position as sustainability-certified alternatives to incumbent PTFE-heavy portfolios, leveraging circular material science credentials in procurement tenders from consumer-facing supply chains. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors membrane-laminated media specialists with demonstrated sub-5 mg outlet loading performance for carbon capture integration pilots. Long-term viability rests on baghouse upstream of amine scrubber architectures becoming standard in power generation and cement decarbonization pathways. Acquisition target archetype: regional engineering specialists with decade-long media supply agreements locking in aftermarket revenue streams. Monitor EPA Maximum Achievable Control Technology enforcement timing as the critical inflection signal for North American retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Lamination | Captive PTFE membrane production insulates margin from Chinese resin quota volatility. |
| Condition-Based Maintenance Platform Deployment | IoT differential pressure monitoring converts capital sales to recurring service revenue. |
| Biodegradable Media Formulation Development | PLA and PHA felts capture Scope 3 accounting premiums from food packagers. |
| Long-Term Media Supply Agreements | Decade-long contracts in Rajasthan and Madhya Pradesh cement corridors lock aftermarket revenue. |
| Carbon Capture Integration Certification | Sub-5 mg outlet loading qualification positions baghouse upstream of amine scrubber pilots. |
Methodological Framework
Cross-validation between plant engineer interviews and customs trade data anchors the qualitative findings on regional procurement patterns. Primary fieldwork engaged maintenance directors at cement and steel facilities, OEM procurement teams specifying integrated baghouse contracts, aftermarket service heads managing filter lifecycle programs, and technical R&D directors developing membrane-laminated composites. Secondary validation drew from EPA MACT regulatory filings, China's MEE emission standard disclosures, EU Industrial Emissions Directive implementation reports, and SEC 10-K disclosures from diversified filtration conglomerates. Bottom-up segment sizing triangulated against top-down industry association capacity estimates.
Sensitivity analysis around PTFE resin price trajectories and blast furnace capacity utilization rates stress-tested volume assumptions across the projection horizon. The analytical framework modeled cleaning mechanism type, application severity, media technology tier, and end-user operational scale as core segmentation dimensions. CAGRs derived from regression against historical replacement cycle compression and regulatory enforcement intensity. Industry-specific forecast inputs included GB 4915 compliance timelines and F-Gas Regulation phase-down schedules.
Forecasts assume regulatory continuity in US EPA, China MEE, and EU ECHA regimes; material policy shifts would require re-modeling. Specific risks include REACH registration delays extending beyond current 12-18 month windows, PTFE resin export quota tightening, and predictive maintenance platform adoption accelerating faster than replacement cycle extension assumptions. Practitioners should keep alternative scenarios live as carbon capture integration requirements and biodegradable media certification standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Precision Gearboxes Market
Material Handling Equipment
Hoist Market
Material Handling Equipment
Precision Gearbox Machinery Market
Material Handling Equipment
Electric Single Beam Crane Market
Material Handling Equipment
Tipper Pads Market
Material Handling Equipment
Reach Stacker Market
Material Handling Equipment
Rubber Tired Gantry (RTG) Crane Market
Material Handling Equipment
Ship Loader and Unloader Market
Material Handling Equipment
Global Elevator Market
Material Handling Equipment
Europe Automated Material Handling (AMH) Market
Material Handling Equipment
Truck Loader Crane Market
Material Handling Equipment
Dust Extractors Market
Material Handling Equipment
Australia Forklift Market
Material Handling Equipment
Industrial Fasteners Market
Material Handling Equipment
Material Rack Correction Machine Market
Material Handling Equipment
Sand Washing Machine Market