
 Automatic Conveyor Market | 2026-2036
Automatic Conveyor Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Conveyor Market Analysis
The EU Machinery Directive is shifting the cost-of-entry calculus for automatic conveyor suppliers serving European manufacturing clients. Siemens AG leverages its embedded automation stack to anchor premium positioning in control-integrated conveying systems. Daifuku Co. Ltd. sustains geographic dominance across Asian airport baggage handling and intralogistics installations. Bosch Rexroth specializes in linear motion and drive technologies that differentiate its modular conveyor platforms from commodity belt suppliers.
An automatic conveyor is a mechanized material handling system comprising motorized belts, rollers, chains, or buckets driven by variable-speed motors and programmable logic controllers, engineered to transport discrete or bulk items along predetermined paths at throughput rates measured in units per minute. Its primary industrial purpose is eliminating manual material movement while synchronizing production flow with upstream and downstream equipment. Belt conveyor configurations dominate high-volume packaging lines where continuous flat surfaces accommodate irregular product geometries, while roller conveyors capture margin pools in pallet-handling warehousing applications due to their load capacity and energy efficiency at scale. Sensor technology is displacing legacy limit-switch architectures as end users demand real-time position tracking and predictive maintenance telemetry across distribution networks.
The US Occupational Safety and Health Administration enforces machine guarding standards that mandate emergency stop zones and interlocked access panels on powered conveyor systems, directly shaping R&D allocation toward safety-certified designs. Japan's Ministry of Economy, Trade and Industry promotes factory automation adoption through JIS standards alignment and smart manufacturing subsidies that accelerate conveyor-robot integration in electronics assembly. China's Ministry of Ecology and Environment enforces dual carbon goals that pressure domestic conveyor manufacturers to reduce motor energy consumption and adopt regenerative drive technologies. Stakeholders must monitor how divergent regional certification timelines affect platform standardization strategies and spare parts inventory economics.
Market Dynamics
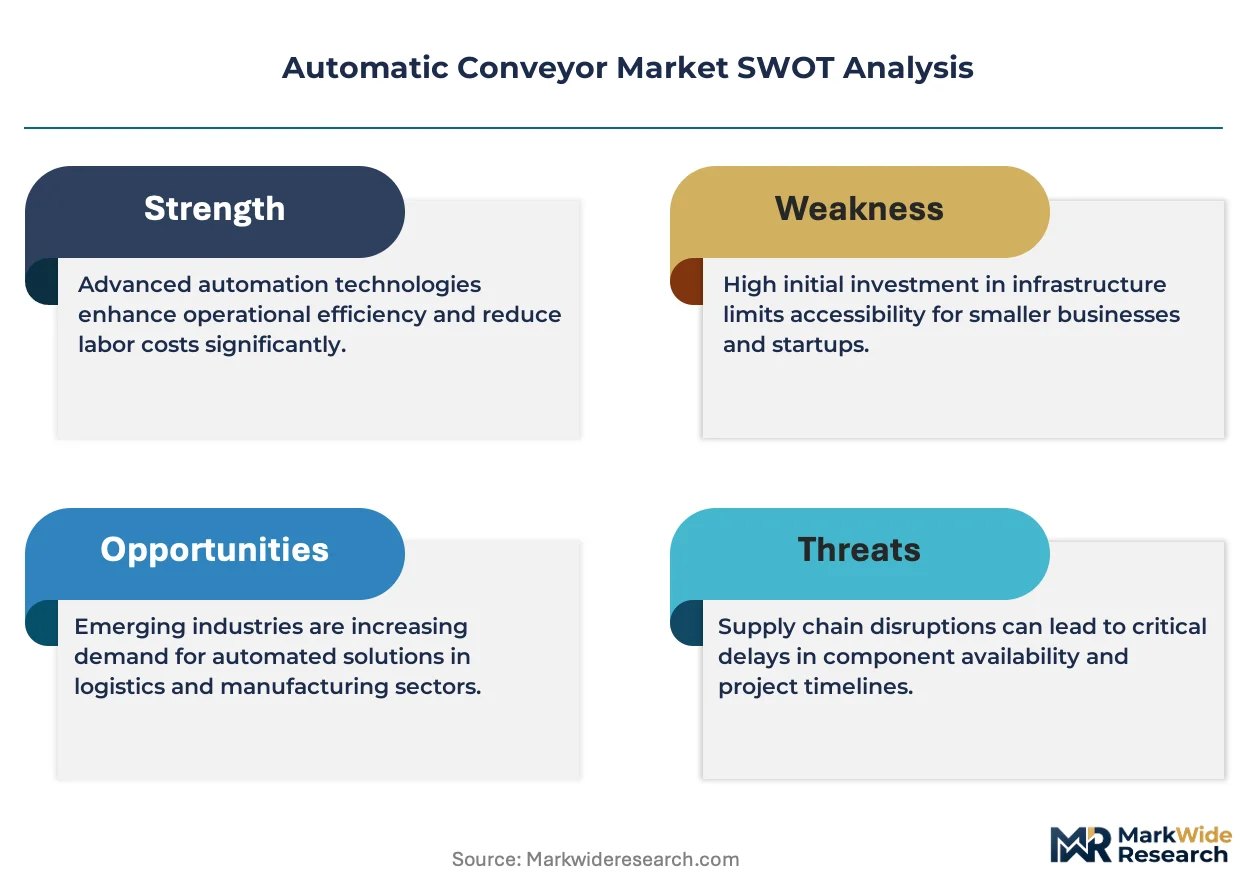
Sensor-driven predictive maintenance architectures are compressing replacement cycles for legacy belt systems while forcing incumbent suppliers to reengineer hardware-software interfaces around real-time telemetry protocols.
Growth Catalysts
- E-commerce fulfillment density:Parcel sortation hubs in the United States are retrofitting fixed-path conveyors with vision-guided diverters to handle polymorphic package geometries at throughput rates exceeding manual sorting capacity.
- OSHA machine guarding mandates:Emergency stop zone requirements and interlocked access panel standards are accelerating capital deployment toward safety-certified designs that command specification preference in food processing and automotive assembly.
- Regenerative drive adoption:China's dual carbon goals enforced by MEE are pressuring domestic manufacturers to replace conventional motors with energy-recovery systems that reduce operational expenditure in high-duty-cycle warehouse applications.
Market Restraints
- Steel and aluminum input volatility:Roller conveyor frames and modular structural components face margin compression when commodity metal prices spike, particularly affecting pallet-handling system producers with fixed-price contracts.
- Control system supplier concentration:Premium positioning in integrated automation stacks depends on captive access to PLC and servo drive ecosystems dominated by industrial automation conglomerates with proprietary communication protocols.
- Electrification substitution threat:Autonomous mobile robots with onboard conveyance are capturing intralogistics applications below certain throughput thresholds, displacing fixed-path installations in facilities with high SKU variability.
Strategic Opportunities
- India's PLI scheme for manufacturing:Production-linked incentives for electronics and automotive sectors are triggering greenfield assembly line investments where modular conveying systems can anchor turnkey automation packages.
- Convergence of AI vision and motion control:Edge-computing cameras paired with variable-frequency drives enable dynamic speed profiling that optimizes energy consumption while preventing product damage in fragile goods handling.
- EU Green Deal procurement criteria:Public sector tender rules embedding lifecycle carbon metrics create specification advantages for suppliers offering regenerative drives and recyclable belt materials in municipal distribution projects.
Industry Challenges
- Mechatronics skill scarcity:Deployment of integrated conveyor-robot cells requires technicians fluent in both mechanical alignment and PLC programming, a combination rarely found in traditional maintenance workforces.
- CE marking timeline compression:The EU Machinery Directive's evolving safety certification requirements extend validation cycles for new platform introductions, delaying revenue recognition against competitor products already in compliance.
- Legacy system integration friction:Brownfield installations must bridge proprietary fieldbus protocols from 1990s-era controllers with modern Ethernet-based architectures, inflating commissioning costs and project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Conveyor Market |
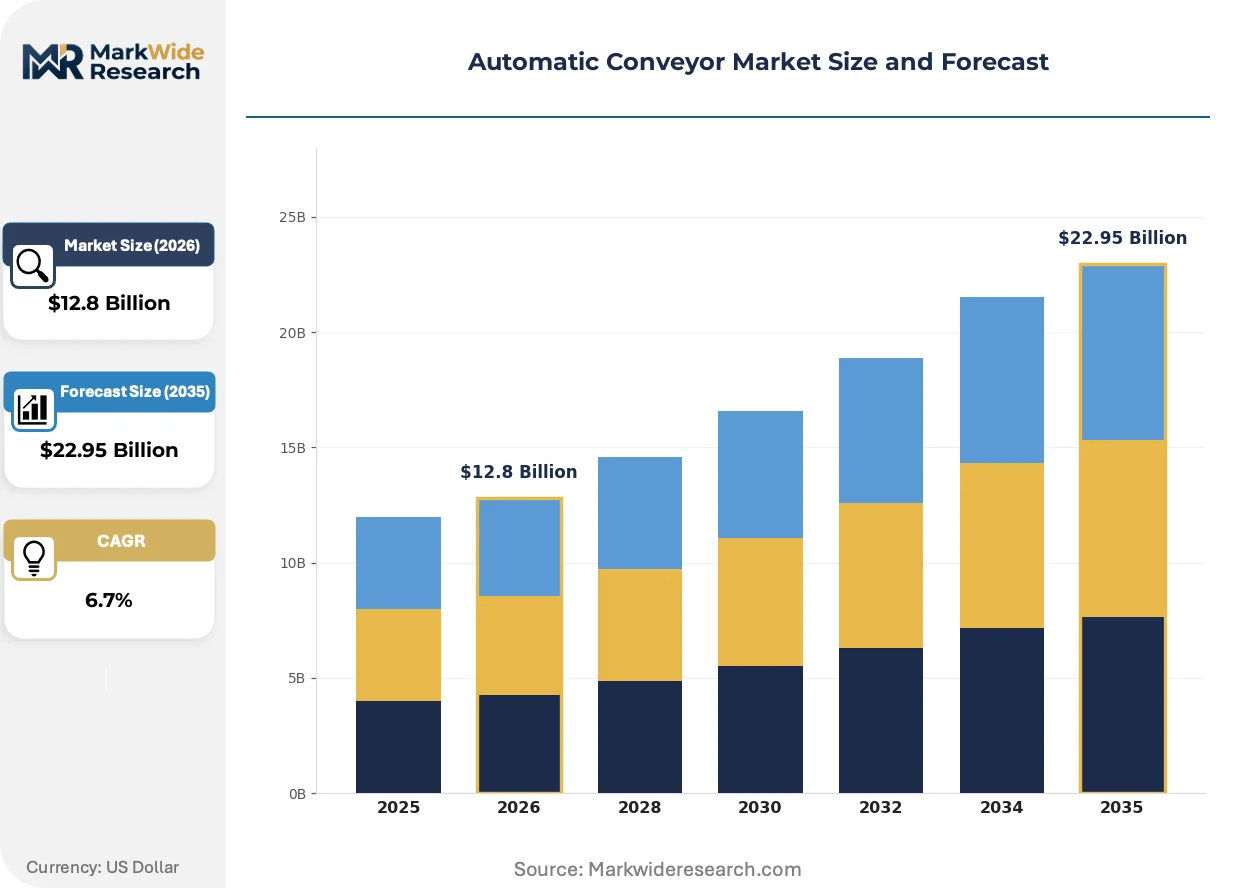
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roller Conveyor, Belt Conveyor, Bucket Conveyor, Chain Conveyor Technology: Automated Guided Vehicle, Robotics, Control Systems, Sensor Technology Application: Manufacturing, Packaging, Warehousing, Distribution End User: Consumer Goods, Food & Beverage, Pharmaceuticals, Electronics |
| Companies Covered | Siemens AG, Honeywell International Inc., Rockwell Automation Inc., Daifuku Co. Ltd., KUKA AG, FANUC Corporation, Schneider Electric SE, Mitsubishi Electric Corporation, Bosch Rexroth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Conveyor Market Emerging Trajectories
Digital thread architectures are collapsing the traditional separation between mechanical conveying hardware and upstream production planning systems, enabling synchronous material flow that tracks individual work-in-progress units through distributed manufacturing networks.
Edge-computing sensor arrays embedded in roller conveyor zones are unifying vibration monitoring, temperature telemetry, and position tracking into single hardware modules that feed cloud-based analytics platforms. Automotive OEMs in Germany's manufacturing corridor are specifying these integrated nodes for new assembly line investments. This convergence is unifying maintenance scheduling with production planning systems, compressing the organizational distance between operations and asset management functions.
Japan's METI smart manufacturing subsidies are accelerating JIS standards alignment for conveyor-robot integration in electronics assembly, creating certification pathways that reduce technical risk for system integrators. Factory automation adoption incentives now cover 30% of capital expenditure for qualifying installations. Electronics contract manufacturers in the Osaka-Kobe industrial zone are leveraging this support to replace fixed-speed belt systems with servo-driven flexible conveyors that accommodate rapid product changeovers.
Third-party logistics providers are unbundling after-sales service contracts from initial equipment procurement, purchasing maintenance labor and spare parts through separate competitive tenders rather than captive OEM service agreements. This disintermediation pressures incumbent suppliers to defend attachment rates through predictive remote diagnostics that demonstrate measurable uptime improvements. The practice is most visible in North American e-commerce fulfillment networks where facility operators prioritize operational expenditure flexibility over capital-intensive multi-year service bundles.
Automatic Conveyor Market Segmentation
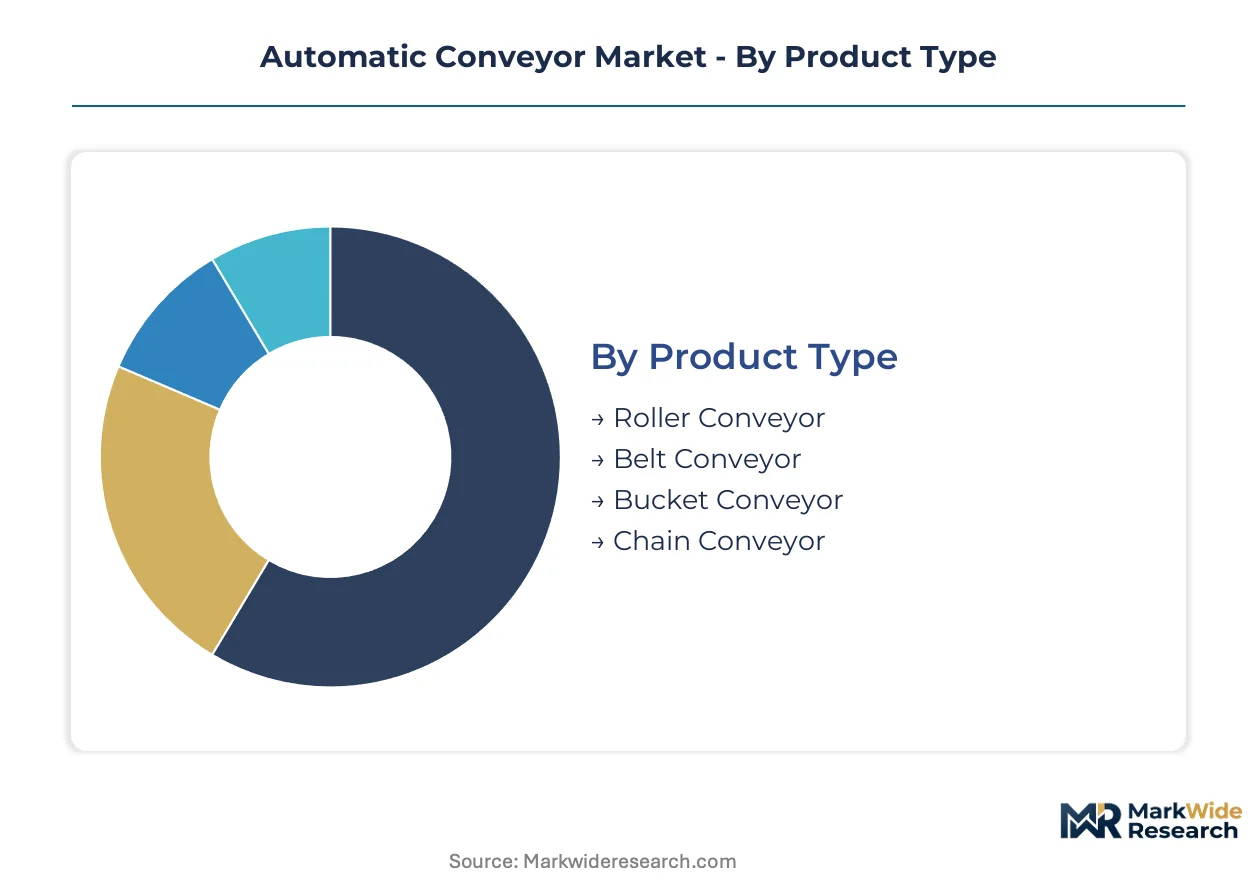
Conveyor purchasing decisions pivot on load characteristics, throughput requirements, and integration complexity with existing automation infrastructure. Each segmentation dimension reveals distinct specification patterns that suppliers must address through modular platform architectures.
Product Type:
Load capacity and surface geometry requirements dominate buyer selection between roller and belt configurations.
- Roller Conveyor:Steel or aluminum cylindrical rollers mounted on precision bearings handle palletized loads up to several thousand kilograms. German automotive OEMs in Stuttgart and Wolfsburg specify heavy-duty roller zones for powertrain assembly lines where dimensional stability under cyclic loading is non-negotiable.
- Belt Conveyor:Continuous fabric or polymer belts driven by drum motors accommodate irregular product geometries at high speeds. E-commerce fulfillment centers in the United States deploy belt systems for parcel singulation where polymorphic package dimensions exceed roller conveyor tolerance.
- Bucket Conveyor:Interconnected buckets mounted on vertical or inclined chains lift bulk materials against gravity. Grain handling facilities and mining operations specify these for vertical transport where belt incline angles would cause spillage.
- Chain Conveyor:Engineered steel chains with attachment fixtures pull loads through harsh environments. Foundry applications and automotive paint shops favor chain systems for temperature resistance and positive drive engagement.
Belt configurations lead on scale across consumer-facing logistics networks; roller systems lead on momentum in heavy manufacturing retrofits.
Technology:
Control architecture sophistication determines system price positioning and integration feasibility with upstream enterprise software.
- Automated Guided Vehicle:Battery-powered mobile platforms with onboard conveyance eliminate fixed-path infrastructure. Third-party logistics operators in North American distribution hubs deploy AGVs for high-SKU variability environments where fixed conveyor reconfiguration costs exceed mobile platform premiums.
- Robotics:Articulated arms and delta robots interfaced with conveyor zones perform pick-place, palletizing, and quality inspection. Electronics contract manufacturers in Japan's Osaka-Kobe industrial zone integrate servo-driven flexible conveyors with SCARA robots for rapid product changeovers under METI subsidy programs.
- Control Systems:Programmable logic controllers and distributed I/O modules synchronize motor drives across conveyor zones. System integrators face supplier concentration risk when specifying proprietary fieldbus protocols from dominant industrial automation conglomerates.
- Sensor Technology:Edge-computing arrays unify vibration, temperature, and position telemetry into single hardware modules. Predictive maintenance contracts now hinge on demonstrated uptime improvements from real-time condition monitoring.
Control systems anchor the largest installed base; sensor technology is climbing the fastest as aftermarket retrofit demand accelerates.
Application:
Throughput velocity and product fragility dictate conveyor specification across facility types.
- Manufacturing:Synchronous material flow systems track individual work-in-progress units through distributed production networks. Automotive assembly lines require millisecond-level coordination between conveyor zones and robotic workstations.
- Packaging:Accumulation and metering conveyors buffer product flow between filling machines and case packers. Food processing facilities specify stainless steel construction with washdown compatibility under USDA sanitation mandates.
- Warehousing:Gravity and powered roller systems optimize pallet movement density in high-bay storage environments. Energy consumption metrics increasingly influence specification as China's MEE enforces dual carbon compliance.
- Distribution:High-speed sortation conveyors with vision-guided diverters process polymorphic parcels at rates exceeding manual capacity. OSHA emergency stop zone requirements shape guard design for operator safety in high-traffic hubs.
Manufacturing commands the deepest integration complexity; distribution is gaining share fastest from e-commerce fulfillment density.
End User:
Regulatory compliance and contamination risk stratify conveyor material and surface finish requirements.
- Consumer Goods:Moderate-duty belt systems handle packaged products with standard hygiene requirements. Seasonal demand volatility drives preference for modular platforms with rapid reconfiguration capability.
- Food & Beverage:Stainless steel construction with FDA-compliant belt materials and clean-in-place accessibility. Interlocked access panels and hygienic design principles dominate specification under evolving safety certification timelines.
- Pharmaceuticals:ISO-classified cleanroom compatibility with particle generation controls and validation documentation. GMP compliance mandates traceable material certificates and serialized component tracking.
- Electronics:Electrostatic discharge protection and precision positioning for microcomponent handling. JIS standards alignment for conveyor-robot integration reduces technical risk in Japanese electronics assembly investments.
Food and beverage leads on specification stringency; electronics shows steepest expansion trajectory from factory automation subsidies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled automation engineers in Germany's automotive corridor anchor the highest-value conveyor specification activity worldwide. Mexico's maquiladora workforce supports cross-border manufacturing integration. India's factory automation technicians are scaling rapidly under production-linked incentive programs.
United States
E-commerce fulfillment density and parcel sortation hub expansion drive conveyor procurement across the Midwest and Southeast distribution corridors. OSHA machine guarding standards mandate emergency stop zones and interlocked access panels on all powered systems. Chicago and Atlanta logistics clusters are retrofitting fixed-path conveyors with vision-guided diverters to handle polymorphic package geometries.
Germany
Automotive OEM assembly line retrofits and powertrain manufacturing investments sustain premium conveyor demand. The EU Machinery Directive's evolving CE marking requirements extend validation cycles for new platform introductions. Stuttgart and Wolfsburg manufacturing corridors specify heavy-duty roller zones with millisecond-level robotic coordination for electric vehicle production lines.
China
Domestic warehouse automation and electronics contract manufacturing propel conveyor installations at scale. The Ministry of Ecology and Environment enforces dual carbon goals that pressure manufacturers to adopt regenerative drive technologies. Yangtze River Delta logistics hubs are replacing conventional motors with energy-recovery systems to reduce operational expenditure in high-duty-cycle applications.
Japan
Electronics assembly automation and conveyor-robot integration subsidies accelerate flexible conveying system adoption. METI smart manufacturing incentives cover qualifying capital expenditure for JIS standards-aligned installations. Osaka-Kobe industrial zone contract manufacturers are deploying servo-driven conveyors to accommodate rapid product changeovers in semiconductor packaging operations.
India
Electronics and automotive production-linked incentive schemes trigger greenfield assembly line investments requiring modular conveying systems. The PLI scheme for manufacturing anchors turnkey automation package demand. Maharashtra and Gujarat industrial corridors are specifying control-integrated conveyor platforms for smartphone and electric vehicle component assembly facilities.
Automatic Conveyor Market Vendor Landscape
The competitive structure tilts toward diversified industrial automation conglomerates with captive control system ecosystems. Siemens AG and Rockwell Automation Inc. anchor premium positioning through embedded PLC and servo drive portfolios that command specification preference in integrated installations. Three archetypes dominate: control-integrated system suppliers, specialized conveying equipment fabricators, and robotics-centric automation integrators. Capacity expansion in Asian manufacturing hubs and strategic partnerships between conveyor hardware vendors and third-party logistics operators represent the dominant competitive moves reshaping market access.
Within the control-integrated tier, Siemens AG and Rockwell Automation Inc. exemplify positioning that bundles conveying hardware with proprietary automation stacks. Daifuku Co. Ltd. occupies a distinct geography-focused archetype across Asian airport baggage handling and intralogistics installations. Bosch Rexroth represents the linear motion specialization vector, anchoring modular platform differentiation through drive technology integration rather than commodity belt supply. These three patterns—control ecosystem dominance, regional installation scale, and motion technology specialization—capture the strategic fault lines shaping procurement decisions.
| Leading Market Players |
|---|
| Siemens AG |
| Honeywell International Inc. |
| Rockwell Automation Inc. |
| Daifuku Co. Ltd. |
| KUKA AG |
| FANUC Corporation |
| Schneider Electric SE |
| Mitsubishi Electric Corporation |
| Bosch Rexroth |
| Others |
Supply Flow & Price Mechanics
Steel and aluminum commodity benchmarks cascade through automatic conveyor manufacturing tiers, compressing margins for roller-frame fabricators while amplifying pricing power for suppliers with captive drive-technology portfolios. The divergence between commodity-exposed fabricators and control-integrated system houses widens when metal price volatility spikes, forcing specification trade-offs between structural durability and electronics content.
Pricing Analysis
The bundled-vs-unbundled service split separates premium positioning from commodity competition. Three-tier pricing structure across premium, standard, and economy levels reflects control-system sophistication and safety-certification grade. Cost compression in economy-tier belt systems is intensifying because third-party logistics operators unbundle after-sales contracts. E-commerce fulfillment networks exhibit highest price sensitivity; pharmaceutical cleanroom installations show least.
Supply Chain Analysis
Dual-sourcing requirements from German automotive OEMs and North American parcel hubs mandate multi-supplier qualification for motors, bearings, and belt materials. Supply concentrates in China for steel frames and drive electronics, Germany for precision mechanical components, and Japan for servo motors and sensor modules. Raw material dependencies span cold-rolled steel, aluminum extrusions, and rare-earth magnet alloys. Single-source vulnerability in PLC controller ecosystems creates specification lock-in. Distribution runs through system integrators and OEM direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in automatic conveyor supply rests on regenerative drive adoption and predictive maintenance service attachment, shifting revenue mix toward software-enabled recurring streams.
For Market Incumbents: Hedge against autonomous mobile robot substitution by deepening sensor-telemetry capabilities and predictive service contracts. Incumbent suppliers should secure captive access to servo drive ecosystems through backward integration into motion control hardware. Certification investment in EU Machinery Directive compliance creates specification preference in European automotive retrofits. For New Entrants and Emerging Players: Enter via India's PLI-scheme electronics assembly corridors where greenfield facility demand outstrips established supplier presence. White-space targets include servo-driven flexible conveyors for rapid product changeovers and edge-computing sensor modules for brownfield predictive maintenance retrofits. Channel partnership with Japanese system integrators leveraging METI subsidy programs offers lowest-friction market access. For Investors and Strategic Acquirers: Asymmetric upside sits with control-integrated mid-cap specialists possessing JIS-aligned conveyor-robot integration capabilities. Long-term viability favors suppliers with demonstrated regenerative drive deployment and cloud-based predictive analytics platforms. Watch for inflection in third-party logistics operator willingness to re-bundle after-sales service contracts as uptime guarantees prove measurable.| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Drive Technology Deployment | MEE dual carbon enforcement in China creates specification mandate for energy-recovery systems. |
| Predictive Maintenance Platform Launch | Edge-computing sensor arrays feed cloud analytics that demonstrate uptime improvements for 3PL contracts. |
| EU Machinery Directive Certification Investment | CE marking compliance extends validation cycles but locks out non-compliant competitors in German automotive. |
| Conveyor-Robot Integration Partnership | METI subsidy alignment in Japan reduces technical risk for electronics assembly automation tenders. |
| Modular Platform Geographic Expansion | India PLI scheme triggers greenfield demand for turnkey conveying systems in Maharashtra industrial corridors. |
Methodological Framework
Multiple input streams — primary interviews with plant engineers and OEM procurement teams, customs and trade flow databases, SEC filings from industrial automation conglomerates, and machinery installation records — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from OSHA enforcement data, EU Machinery Directive certification registries, and METI subsidy disbursement reports. Conversations with maintenance directors at North American e-commerce fulfillment centers and system integrators in Germany's Stuttgart manufacturing corridor anchored demand-side calibration.
Cross-reference between historical installation patterns and panel input from automation procurement executives shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, control architecture sophistication, application throughput requirements, and end-user regulatory compliance tier. CAGRs were derived from regression against capital expenditure flows and automation adoption indices. Forecast inputs incorporated e-commerce fulfillment density metrics and dual carbon enforcement timelines.
Inputs from regulatory filing databases and primary stakeholder interviews were available through the study window; gaps in real-time aftermarket service contract pricing introduce uncertainty bands around revenue mix projections. Deviation in autonomous mobile robot cost-performance curves or EU Machinery Directive enforcement timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Industrial Sheaves and Pulleys Market
Material Handling Equipment
Bale Clamp Intensive Market
Material Handling Equipment
Global Metal Expansion Joints Market
Material Handling Equipment
Dynamic Compactor Market
Material Handling Equipment
Can Racks Market
Material Handling Equipment
Mobile Crane Market
Material Handling Equipment
Mobile Conveyor Market
Material Handling Equipment
Sifter Fitment Market
Material Handling Equipment
Global Loading Dock Bumpers Market
Material Handling Equipment
Industrial Parts Feeders Market
Material Handling Equipment
Silo Bin Activators Market
Material Handling Equipment
Hoist Chains Market
Material Handling Equipment
Mill Liner Market
Material Handling Equipment
Elevator Component Market
Material Handling Equipment
Selective Pallet Racking System Market
Material Handling Equipment
Hydraulic Hose Market