
 Slag Handling Machine Market | 2026-2036
Slag Handling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Slag Handling Machine Market Analysis
Direct sales channels serving steel mills is fragmenting as rental and service-contract models gain traction among mid-sized foundries. Harsco Corporation leverages its integrated service model to control aftermarket revenue streams. Tenova competes through technology leadership in hydraulic grab systems for high-temperature environments. Metso Outotec anchors its position in Nordic markets through specialization in electric-drive conveyor solutions.
Slag handling machines are heavy-duty industrial equipment engineered to transport, process, and dispose of molten or cooled metallurgical byproducts at temperatures exceeding 1,200 degrees Celsius, utilizing reinforced steel alloys and water-cooled components to prevent thermal deformation. These systems serve the essential function of maintaining continuous steel production flow while minimizing worker exposure to hazardous materials. Conveyor systems dominate capital expenditure among steel producers due to their integration into continuous casting lines, while electric technology segments attract fastest-growing interest as foundries retrofit for carbon reduction targets. Mobile deployment configurations command premium pricing in recycling plants where feedstock locations shift frequently.
EPA emissions standards and OSHA workplace safety mandates in the United States compel equipment upgrades with enhanced dust suppression and remote operation capabilities. China's MEE enforces dual carbon goals that accelerate electric-hydraulic hybrid adoption in Hebei and Shandong provinces. India's BIS certification requirements for material handling equipment create compliance barriers for unqualified imports. Stakeholders must evaluate whether regional regulatory divergence justifies modular platform designs or localized manufacturing footprints.
Market Dynamics
Steel producers face mounting pressure to decarbonize blast furnace operations while maintaining throughput, forcing capital allocation toward electric-hydraulic hybrid slag handling systems that reduce diesel dependency without sacrificing thermal load capacity.
Growth Catalysts
- CDSCO workplace safety mandates:India's pharmaceutical-grade steel producers must upgrade molten material transport protocols, creating equipment replacement cycles for compliant slag handling machinery.
- Blast furnace capacity expansion:China's Hebei Province requires automated slag removal systems to maintain continuous casting line throughput at expanded steelmaking facilities.
- Carbon reduction retrofit programs:Foundries across Nordic markets are electrifying material handling fleets to meet national emissions targets, accelerating electric-drive conveyor adoption.
Market Restraints
- Reinforced alloy input costs:Specialized chromium-molybdenum steel plates for water-cooled components face price volatility from concentrated mining output in South Africa.
- Technical thermal deformation limits:Conventional hydraulic seals fail above 1,400 degrees Celsius, constraining grab system performance in ultra-high-temperature slag applications.
- BIS certification barriers:India's material handling equipment standards create compliance friction for unqualified import sources, limiting supplier pool diversity.
Strategic Opportunities
- Service-contract penetration:Mid-sized foundries in Germany's Ruhr region are abandoning capital purchase models for integrated rental-maintenance agreements, opening recurring revenue streams.
- Recycling plant mobility requirements:Australian scrap metal processors need rapid-deployment slag handling units as feedstock locations shift between demolition sites.
- MEE dual carbon enforcement:China's Ministry of Ecology and Environment mandates accelerate electric-hydraulic hybrid adoption in Shandong Province steel clusters.
Industry Challenges
- Water-cooled system integration complexity:Retrofitting legacy blast furnace lines with closed-loop cooling infrastructure demands extended shutdown windows that compress annual output.
- Certification timeline compression:EPA emissions compliance deadlines for dust suppression upgrades force accelerated procurement cycles that strain engineering validation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slag Handling Machine Market |
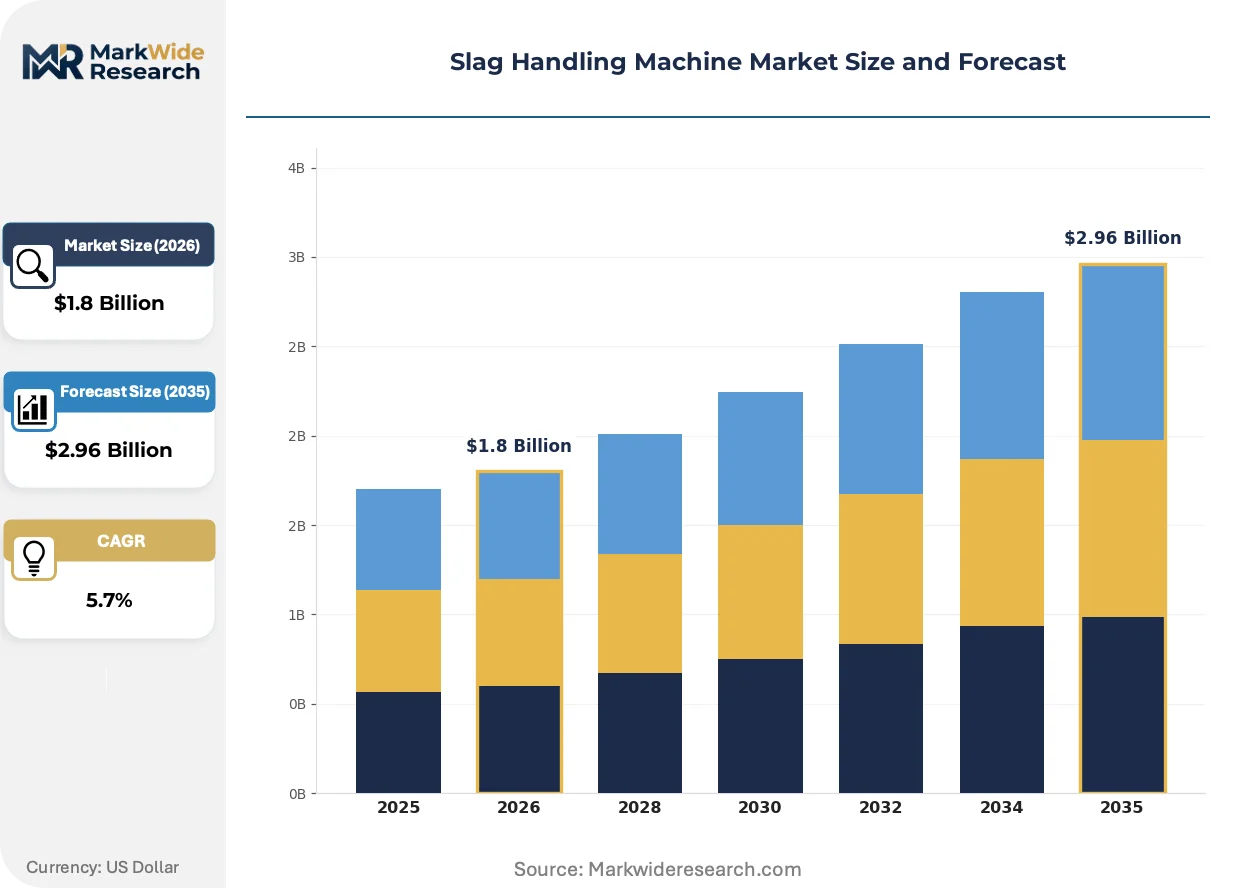
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forklift, Grab Loader, Conveyor System, Dump Truck End User: Steel Producers, Foundries, Recycling Plants, Construction Firms Deployment: Onsite, Offsite, Mobile, Fixed Technology: Hydraulic, Electric, Pneumatic, Mechanical |
| Companies Covered | Harsco Corporation, FLSmidth, Tenova, Danieli & C. Officine Meccaniche, Metso Outotec, Konecranes, BHS-Sonthofen, American Crane and Equipment Corp, Dongqi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slag Handling Machine Market Emerging Trajectories
Digital twin technology is virtualizing equipment performance before physical deployment, compressing commissioning cycles and reducing thermal failure risk in high-stakes steelmaking environments.
Sensor-integrated predictive maintenance platforms are virtualizing traditional reactive service models. Tier-one steel mills in Japan's Chubu region deploy these systems to anticipate hydraulic seal degradation before catastrophic failure. The technology is virtualizing aftermarket revenue structures, displacing scheduled maintenance contracts with usage-calibrated service pricing.
OSHA's enhanced workplace safety mandates for remote operation capabilities are forcing control system upgrades across US steel producers. Equipment must now support fully automated slag pot positioning from climate-controlled operator stations. Electric-arc furnace operators in Indiana and Ohio face the steepest compliance costs due to legacy analog control architectures.
Equipment-as-a-service contracting is displacing traditional capital expenditure patterns among European mid-market foundries. Rental and performance-based agreements now dominate procurement for mobile slag processing units in Italy's Lombardy region. This shift compresses supplier cash conversion cycles while transferring residual value risk to equipment financiers.
Slag Handling Machine Market Segmentation
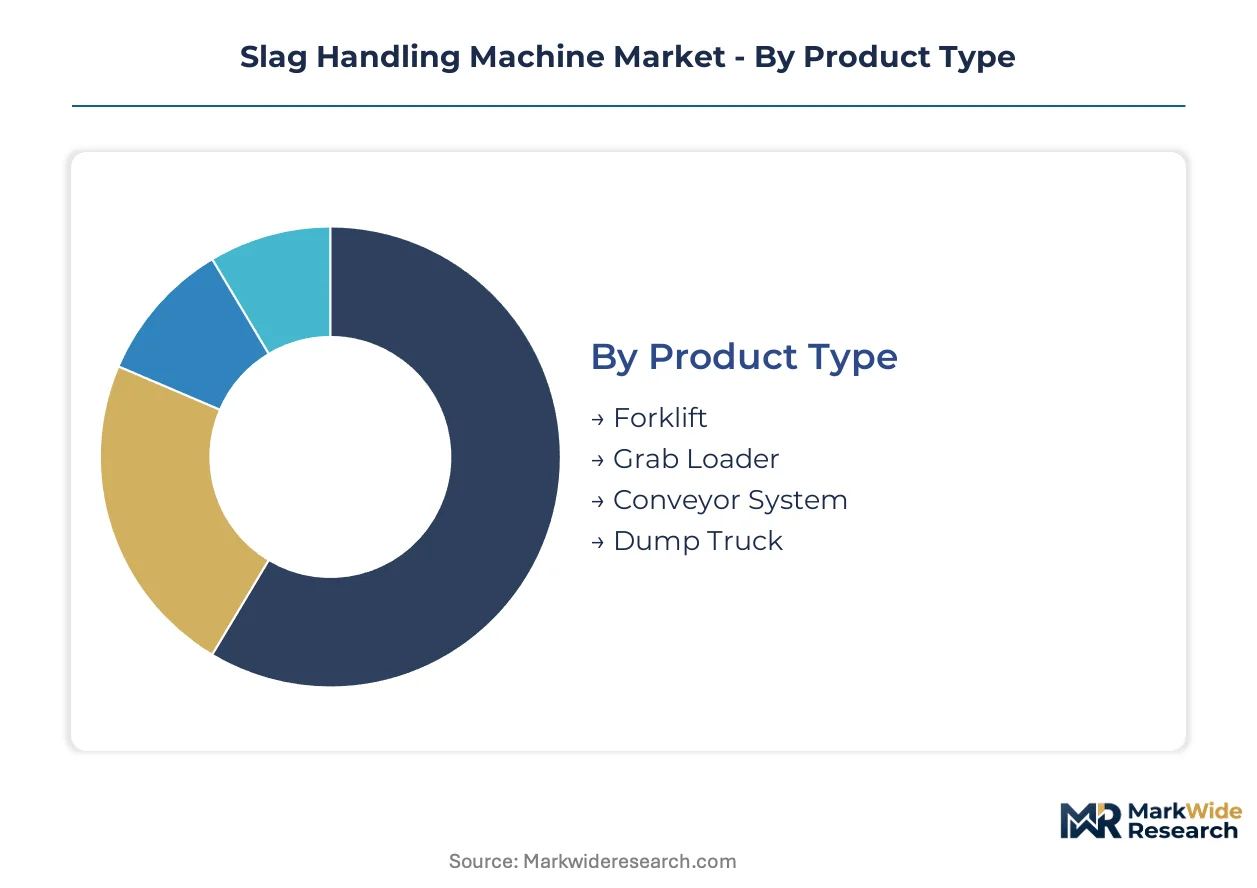
Segmentation in the slag handling machine market reveals distinct equipment specifications tied to thermal load requirements and operational mobility needs. Steel producers prioritize conveyor integration for continuous casting compatibility, while recycling operations demand modular configurations for feedstock variability.
Product Type:
Use-case spectrum spans pot transport, bulk loading, continuous discharge, and long-haul transfer across blast furnace, ladle, and slag yard operations.
- Conveyor System:Continuous belt or chain mechanisms engineered for high-volume slag transport from tapping to cooling pits. Steel producers in China's Hebei Province dominate procurement as blast furnace capacity expansion mandates uninterrupted material flow.
- Grab Loader:Articulated hydraulic grabs with water-cooled arms for direct molten slag extraction from ladles. Foundries across India's pharmaceutical-grade steel sector upgrade fleets to meet CDSCO-mandated workplace safety protocols for molten material handling.
- Forklift:Reinforced mast trucks with heat-shielded cabs for cooled slag block movement in storage yards. German Ruhr region mid-sized foundries favor rental configurations for intermittent throughput spikes.
- Dump Truck:Specialized chassis with refractory-lined beds for road transport to offsite processing facilities. Australian scrap metal processors deploy rapid-deployment units as demolition feedstock locations shift between sites.
Established volume favors Conveyor System; emerging adoption favors Grab Loader.
End User:
Customer archetypes range from integrated steelmakers with captive slag processing to third-party recyclers serving multiple metallurgical feedstock sources.
- Steel Producers:Integrated blast furnace and electric-arc furnace operators requiring 24/7 slag removal to maintain casting line continuity. Hebei and Shandong province clusters in China drive automated system adoption under MEE dual carbon enforcement.
- Recycling Plants:Independent processors converting metallurgical slag into construction aggregate and cement additives. Mobility requirements command premium pricing as feedstock locations shift between demolition and decommissioning sites.
- Foundries:Ferrous and non-ferrous casting operations with intermittent slag generation patterns. Italy's Lombardy region mid-market foundries are abandoning capital purchase models for integrated rental-maintenance agreements.
- Construction Firms:Contractors utilizing processed slag as aggregate substitute in road base and concrete applications. Secondary material procurement depends on regional availability of steelmaking byproducts.
Procurement concentration sits with Steel Producers; contract flexibility expansion favors Foundries.
Deployment:
Configuration options balance capital intensity against operational adaptability across permanent infrastructure and project-based requirements.
- Fixed:Permanent installations integrated into blast furnace basement and slag yard infrastructure. Nordic steelmakers anchor electric-drive conveyor adoption to meet national emissions targets.
- Mobile:Trailer-mounted or self-propelled units repositionable between tapping points and cooling areas. Australian scrap processors require rapid-deployment configurations for shifting demolition feedstock locations.
- Onsite:Equipment dedicated to single-facility slag management without inter-plant transfer capability. EPA emissions standards and OSHA mandates in the United States compel dust suppression upgrades for legacy installations.
- Offsite:Centralized processing hubs receiving slag from multiple generation points via road or rail transport. India's BIS certification requirements create compliance barriers for unqualified import sources serving this segment.
Capital deployment favors Fixed; retrofit flexibility favors Mobile.
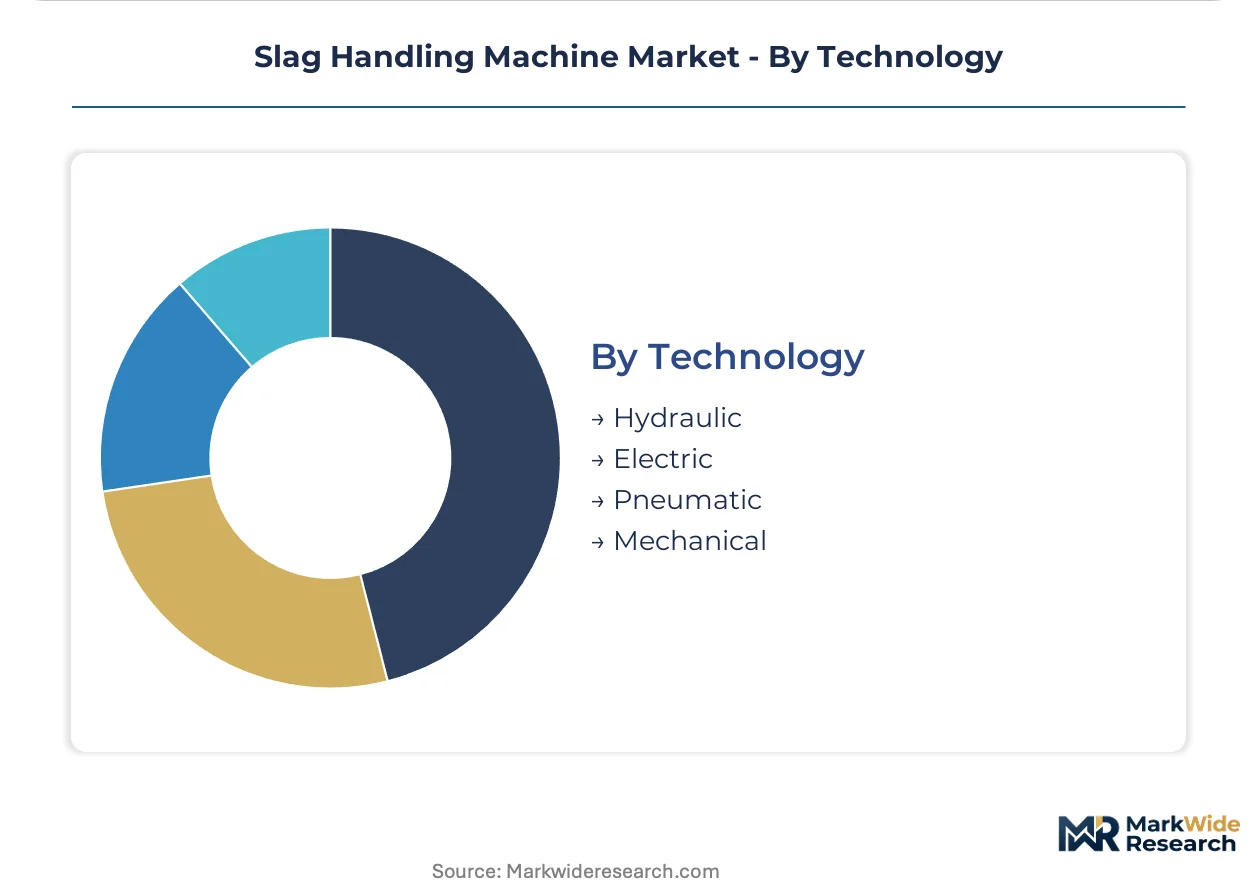
Technology:
Powertrain selection determines thermal tolerance, emissions profile, and maintenance intervals across high-temperature operating environments.
- Hydraulic:Fluid-power systems delivering high torque for grab and lift operations in 1,200-plus degree Celsius environments. Conventional seal materials face performance constraints above 1,400 degrees Celsius in ultra-high-temperature applications.
- Electric:Motor-drive configurations eliminating diesel dependency for carbon reduction compliance. Foundries across Nordic markets are electrifying material handling fleets to meet national emissions targets.
- Pneumatic:Compressed-air actuation for lighter-duty conveying and positioning tasks in secondary processing stages. Limited thermal tolerance restricts deployment to cooled slag handling.
- Mechanical:Direct mechanical linkages for simple transfer and dumping operations with minimal maintenance requirements. Cost-sensitive operators in developing markets favor this configuration for basic material movement.
Installed base concentration favors Hydraulic; steepest expansion trajectory favors Electric.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in China's Hebei Province steel clusters while Indian buyers face BIS certification premiums that inflate landed equipment costs by 12-18 percent relative to domestic procurement.
China
Blast furnace capacity expansion in Hebei and Shandong provinces drives automated slag removal procurement. MEE dual carbon enforcement mandates electric-hydraulic hybrid retrofits across steel clusters. Tangshan steelmakers deploy continuous conveyor systems to maintain casting line throughput at expanded facilities.
India
Pharmaceutical-grade steel producers upgrade molten material transport under CDSCO workplace safety protocols. BIS certification requirements for material handling equipment block unqualified import sources. Maharashtra and Gujarat foundries dominate compliant equipment replacement cycles.
United States
EPA emissions standards and OSHA remote operation mandates force dust suppression upgrades across legacy installations. Electric-arc furnace operators in Indiana and Ohio face steepest compliance costs due to analog control architectures. Great Lakes steel clusters prioritize automated slag pot positioning systems.
Germany
Ruhr region mid-sized foundries abandon capital purchase models for integrated rental-maintenance agreements. National emissions targets accelerate fleet electrification among material handling operators. North Rhine-Westphalia recycling processors command premium pricing for mobile deployment configurations.
Australia
Scrap metal processors require rapid-deployment slag handling units as demolition feedstock locations shift between sites. Western Australian mining-adjacent recyclers prioritize trailer-mounted configurations for project-based throughput. Queensland steel service centers invest in closed-loop cooling infrastructure for thermal load management.
Slag Handling Machine Market Vendor Landscape
Integrated service providers and technology specialists split the market between recurring revenue capture and equipment differentiation. Consolidation pressure intensifies as steelmakers consolidate supplier relationships to simplify compliance management across multi-site footprints. Three archetypes dominate: full-service operators bundling equipment with maintenance contracts, component specialists advancing hydraulic and electric drive systems, and regional fabricators competing on delivery speed and customization flexibility. Dominant competitive moves include geographic expansion through local assembly partnerships and backward integration into water-cooled component manufacturing.
Within the full-service tier, Harsco Corporation exemplifies integrated revenue capture through aftermarket control. Tenova occupies a position among technology-forward specialists advancing high-temperature hydraulic systems. Metso Outotec anchors Nordic market presence through electric-drive specialization. These three represent distinct strategic postures without implying specific market share or operational scale.
| Leading Market Players |
|---|
| Harsco Corporation |
| FLSmidth |
| Tenova |
| Danieli & C. Officine Meccaniche |
| Metso Outotec |
| Konecranes |
| BHS-Sonthofen |
| American Crane and Equipment Corp |
| Dongqi Group |
| Others |
Supply Flow & Price Mechanics
Chromium-molybdenum steel plate volatility from South African mining concentration determines both the premium spread for water-cooled component configurations and the geographic footprint of qualified fabricators serving blast furnace operators.
Pricing Analysis
Configured-to-order pricing for water-cooled grab systems commands substantial premiums over standard conveyor configurations due to thermal tolerance engineering and BIS certification requirements. Pricing stratifies across premium, standard, and economy tiers based on thermal load rating and after-sales service bundling. Cost compression in standard hydraulic tiers is intensifying because of electric-hydraulic hybrid substitution pressure from China's MEE enforcement. Mid-sized foundries in Germany's Ruhr region exhibit highest price sensitivity through rental-model preference, while integrated steelmakers in Hebei Province show lowest sensitivity due to throughput continuity requirements.
Supply Chain Analysis
Tariff exposure between South Africa and India dominates raw material cost planning for water-cooled component manufacturers. Specialized alloy supply concentrates in South Africa, China, and Germany, with reinforced steel plate and hydraulic seal assemblies as critical inputs. Single-source vulnerability for chromium-molybdenum feedstock creates procurement risk during mining output disruptions. Distribution runs through direct OEM channels to integrated steelmakers, with rental-service intermediaries gaining share among mid-market foundries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of thermal engineering talent capable of integrating water-cooled systems into legacy blast furnace infrastructure constrains expansion velocity for suppliers targeting retrofit opportunities.
For Market Incumbents: Entrench aftermarket control by deepening captive supply of water-cooled alloy components and securing multi-site service contracts with Hebei Province steel clusters. Electric-drive technology substitution from Nordic electrification mandates threatens hydraulic system incumbency, making certification investment in MEE-compliant hybrid platforms the critical defensive lever. For New Entrants and Emerging Players: Mobile deployment configurations for Australian scrap metal processors represent the most penetrable entry point, given rapid-deployment requirements and limited incumbent rental penetration. Italy's Lombardy region mid-market foundries offer secondary white-space through equipment-as-a-service contracting gaps. A go-to-market angle anchored to closed-loop cooling infrastructure retrofit expertise bypasses direct competition with established conveyor suppliers. For Investors and Strategic Acquirers: Regional fabricators with BIS certification capabilities and established maintenance networks in Maharashtra and Gujarat present the most attractive acquisition profile for long-term viability across the decarbonization transition window. Watch for MEE enforcement acceleration in Shandong Province as the inflection indicator for electric-hydraulic hybrid demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Component Manufacturing | Captive supply of chromium-molybdenum plates insulates margin from South African mining volatility. |
| Electric-Hydraulic Hybrid Platform Development | MEE dual carbon compliance in Hebei and Shandong provinces accelerates retrofit procurement cycles. |
| Service-Contract Model Expansion | Rental-maintenance agreements with Ruhr region foundries capture recurring revenue from capital-constrained buyers. |
| Mobile Deployment Configuration Engineering | Trailer-mounted systems address Australian scrap processor feedstock mobility requirements. |
| BIS Certification Investment | Compliance capability unlocks Maharashtra and Gujarat foundry replacement cycles blocked to unqualified imports. |
Methodological Framework
The analysis maps conveyor systems, grab loaders, forklifts, and dump trucks across fixed, mobile, onsite, and offsite deployments, each validated through maintenance directors at integrated steelmakers, plant engineers at foundries, OEM procurement teams, and aftermarket service heads. Primary fieldwork combined with secondary validation from customs trade data, SEC filings of listed industrial equipment manufacturers, blast furnace capacity expansion announcements, and national emissions target disclosures supports bottom-up and top-down triangulation.
Assumptions held fixed include regulatory enforcement timelines for MEE dual carbon goals and CDSCO workplace safety mandates, while steel production volume trajectories and alloy input cost curves were varied across the projection horizon. Segmentation dimensions modeled encompass product type, end user archetype, deployment configuration, and powertrain technology. CAGRs were derived from equipment replacement cycle analysis and capacity expansion announcements. Forecast inputs include blast furnace utilization rates and electrification retrofit program commitments.
Practitioners should monitor South African mining output disruptions, MEE enforcement acceleration, and BIS certification timeline changes for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
US and Mexico Metal Stamping Market
Material Handling Equipment
Forklift Tire Market
Material Handling Equipment
Helical Gear Market
Material Handling Equipment
Froth Flotation Equipment Market
Material Handling Equipment
Dock Levelers Market
Material Handling Equipment
Middle East Conveyor Belts Market
Material Handling Equipment
Silo Bin Activators Market
Material Handling Equipment
Copper and Aluminum Welding Bar Market
Material Handling Equipment
Industrial Static Equipment Market
Material Handling Equipment
Clinching Machines Market
Material Handling Equipment
Pneumatic Equipment Market
Material Handling Equipment
Sand Washing Machine Market
Material Handling Equipment
Firewood Processors Market
Material Handling Equipment
Vibratory Feeder Machine Market
Material Handling Equipment
Debris Loaders Market
Material Handling Equipment
Vibrating Conveyor Market