
 Heavy Loader Market | 2026-2036
Heavy Loader Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Loader Market Analytics
Telematics-enabled fleet management is restructuring how heavy loader value gets captured, shifting revenue from unit sales toward subscription-based uptime guarantees and predictive maintenance contracts. Caterpillar Inc. leverages its dealer network to anchor service revenue across North American mining operations. Komatsu Ltd. differentiates through autonomous haulage integration that extends loader-truck coordination into unified site workflows.
A heavy loader is a wheeled or tracked earthmoving machine with an operating weight exceeding 20 tonnes, engineered with articulated steering and a hydraulically activated bucket rated for bulk material handling in quarry, mine, and large-scale construction environments. Diesel configurations still dominate installed bases, yet electric variants are gaining fastest as battery energy density improvements and on-site charging infrastructure mature across European contractor fleets. GPS-guided grading and payload optimization systems concentrate margin pools in technology-augmented units rather than base mechanical platforms.
EPA Tier 4 Final, EU Stage V, and China's MEE emission enforcement are tightening particulate and NOx thresholds, forcing engine redesigns and aftermarket retrofit demand while restricting non-compliant equipment imports. ISO 50001 energy management and IEC 61508 functional safety standards further shape product development priorities for automation-ready architectures. Stakeholders must weigh electrification capex against regulatory compliance timelines and residual value risk in secondary markets.
Market Dynamics
Telematics-enabled fleet management is restructuring how heavy loader value gets captured, shifting revenue from unit sales toward subscription-based uptime guarantees and predictive maintenance contracts. This structural pivot forces manufacturers to reconfigure dealer networks and service architectures around data monetization rather than hardware margins.
Growth Catalysts
- Copper and lithium extraction targets:Mining companies in Australia and Chile are expanding fleets to meet decarbonization-driven mineral demand for electric vehicle batteries and grid infrastructure.
- EPA Tier 4 Final enforcement:US emission standards are accelerating replacement cycles for diesel-powered loaders in North American quarry operations.
- State-backed infrastructure:China's western provinces are deploying high-capacity earthmoving equipment for mineral processing and transportation corridor development.
Market Restraints
- Battery energy density limitations:Electric loader range and duty-cycle performance remain constrained by lithium-ion chemistry thresholds, delaying full electrification in open-pit mining.
- EU Stage V compliance costs:Engine redesigns and aftertreatment systems add capital intensity to European fleet procurement, compressing contractor margins.
- Specialized technician scarcity:Hybrid drivetrain and autonomous system maintenance requires skills concentrated among OEM-trained service networks, limiting third-party repair competition.
Strategic Opportunities
- Autonomous haulage integration:Unified loader-truck coordination workflows are creating differentiated value pools for technology-anchored equipment suppliers.
- Payload optimization systems:GPS-guided grading and real-time load monitoring are concentrating margins in technology-augmented units versus base mechanical platforms.
- Secondary market residual value management:ISO 50001-certified energy management and IEC 61508 functional safety compliance are emerging as value-retention criteria for auction and resale channels.
Industry Challenges
- Retrofit certification timelines:Aftermarket Tier 4 Final and Stage V engine upgrades face extended homologation periods, stranding non-compliant assets in regulated jurisdictions.
- Legacy fleet integration complexity:Telematics and autonomous coordination systems require interoperability with decades-old mechanical loaders, creating data architecture fragmentation.
- On-site charging infrastructure capex:Electric loader adoption depends on grid upgrades and fast-charging installations that mining contractors must fund before equipment delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Loader Market |
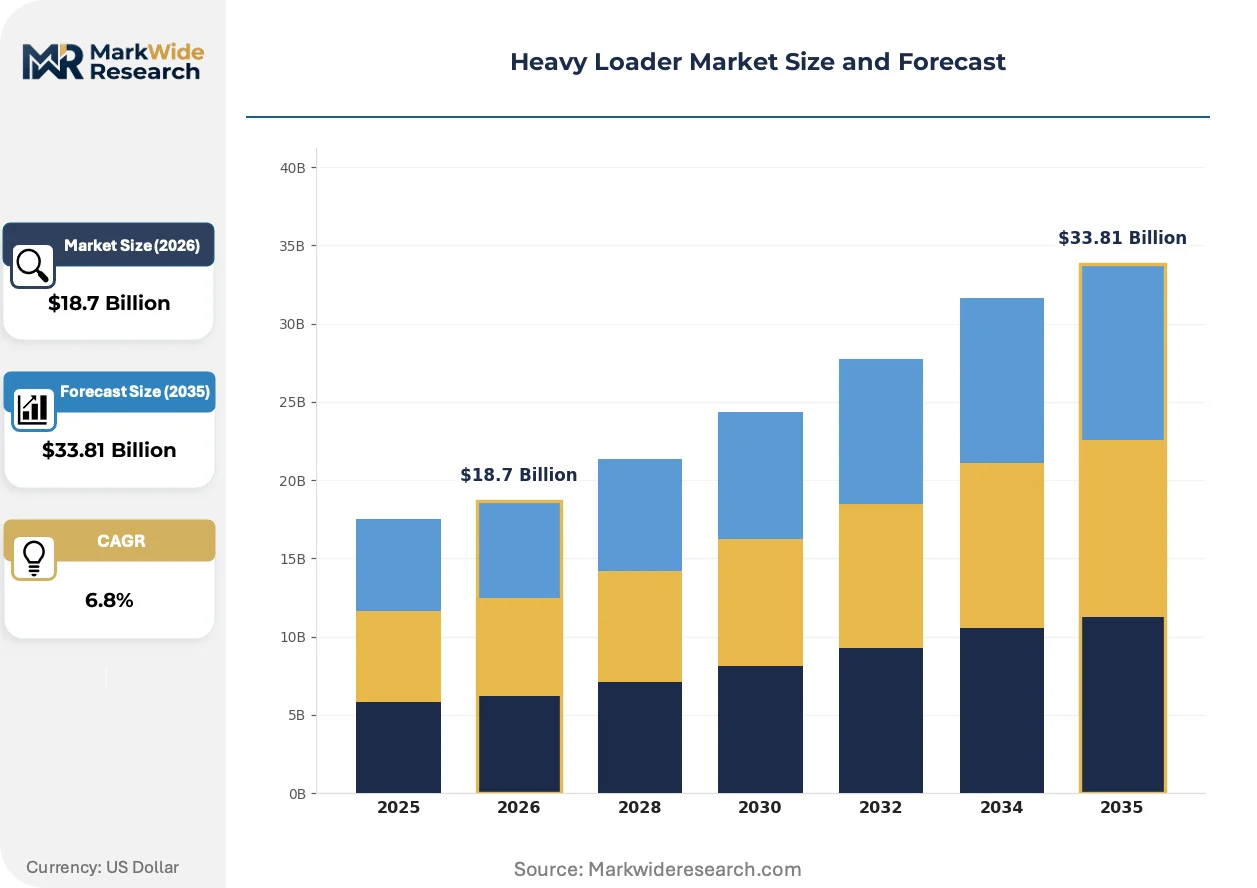
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic, Electric, Diesel, Track Application: Construction, Mining, Agriculture, Recycling End User: Contractors, Mining Companies, Farmers, Waste Management Technology: Telematics, Automation, GPS, Emission Control |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., Volvo Construction Equipment, Hitachi Construction Machinery Co., Ltd., XCMG Group, Sany Heavy Industry Co., Ltd., Liebherr Group, John Deere, HD Hyundai, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Loader Market Evolving Landscape
Electrification and automation are converging to redefine heavy loader product architectures, with battery-electric platforms serving as the physical substrate for autonomous control systems. This fusion is compressing development cycles and reshaping supplier relationships across the value chain.
Battery-electric drivetrains are integrating with high-voltage auxiliary systems to power hydraulics, climate control, and onboard electronics from a unified energy reservoir. European contractor fleets are adopting these configurations fastest where on-site solar and grid-tied charging infrastructure has matured. This integration is enabling OEMs to consolidate power electronics suppliers and reduce component count per unit.
EU Stage V and China's MEE emission enforcement are tightening particulate and NOx thresholds, forcing engine redesigns and aftermarket retrofit demand while restricting non-compliant equipment imports. Engine manufacturers must now certify aftertreatment systems across multiple regulatory regimes simultaneously. Underground mining operations in Germany and Poland are most affected, accelerating electric conversion timelines ahead of surface quarry adoption.
Subscription-based uptime guarantees are displacing traditional warranty and parts-replacement service models among large North American mining operators. Dealer networks are restructuring technician deployment and parts inventory around predictive maintenance algorithms rather than scheduled intervals. This shift is most visible in copper and iron ore operations in Arizona and Minnesota, where fleet scale justifies data infrastructure investment.
Heavy Loader Market Segmentation
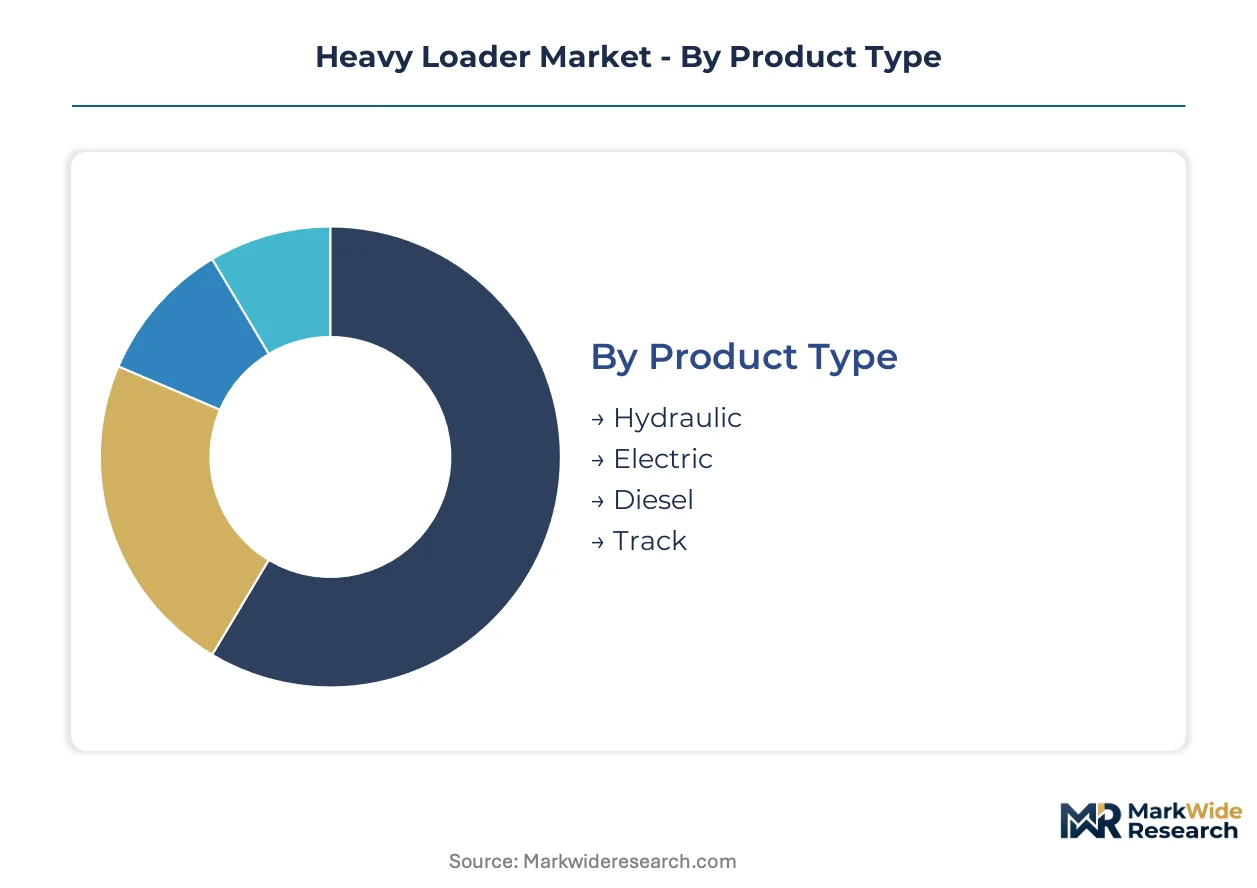
Heavy loader procurement decisions hinge on duty-cycle intensity, emission compliance timelines, and total cost of ownership calculations across fuel and technology configurations. Segment boundaries are blurring as electrified platforms absorb telematics and automation modules into unified product architectures.
Product Type:
Buyers prioritize fuel availability, infrastructure readiness, and residual value risk when selecting powertrain configurations for fleet deployment.
- Diesel:Compression-ignition engines with Tier 4 Final and Stage V aftertreatment systems dominate open-pit mining and remote construction where refueling networks are mature. Australian copper operations in Queensland and Western Australia maintain diesel dominance due to 24-hour duty cycles and limited grid access.
- Electric:Battery-electric drivetrains with high-voltage auxiliary integration are gaining share fastest in European quarry and urban demolition fleets where charging infrastructure and emission zones converge. German contractors in North Rhine-Westphalia are retrofitting depots with 350kW fast-charging to support electric loader deployment ahead of diesel phase-out deadlines.
- Hydraulic:Conventional hydrostatic transmission systems persist in specialized material handling where precise bucket control outweighs fuel efficiency targets.
- Track:Tracked undercarriage configurations serve soft-ground and steep-slope applications in forestry reclamation and pipeline construction where flotation and traction override transport speed.
Diesel leads on scale; electric leads on momentum.
Application:
Site conditions and material density dictate loader specification, with mineral extraction driving the highest capacity and durability requirements.
- Mining:High-capacity bucket configurations exceeding 15 cubic meters handle copper, iron ore, and lithium-bearing rock in Chilean Atacama and Pilbara Basin operations. Autonomous haulage integration is concentrating investment in unified loader-truck coordination systems.
- Construction:Articulated wheeled platforms with quick-attach tool systems dominate highway, dam, and commercial building earthmoving where mobility between sites matters. Chinese state-backed infrastructure corridors in Sichuan and Xinjiang are deploying heavy loaders for tunneling and embankment work.
- Agriculture:Lower-hour applications in feed handling and land clearing favor mid-size configurations with simplified maintenance protocols.
- Recycling:Reinforced guarding and specialized grapple attachments address scrap metal and construction debris sorting in European material recovery facilities.
Mining commands the largest equipment scale; construction offers the broadest geographic dispersion.
End User:
Fleet sophistication and data infrastructure maturity separate procurement patterns across customer categories.
- Mining Companies:Integrated operators with in-house maintenance capabilities and autonomous system investments concentrate demand for technology-anchored platforms with subscription-based uptime contracts.
- Contractors:Project-based rental and lease arrangements drive preference for standardized configurations with dealer service coverage across multiple jurisdictions.
- Farmers:Seasonal utilization patterns favor lower capital intensity and extended warranty terms over advanced automation features.
- Waste Management:Municipal and private operators prioritize emission compliance and noise reduction in urban proximity operations.
Mining companies set the technology frontier; contractors define volume throughput.
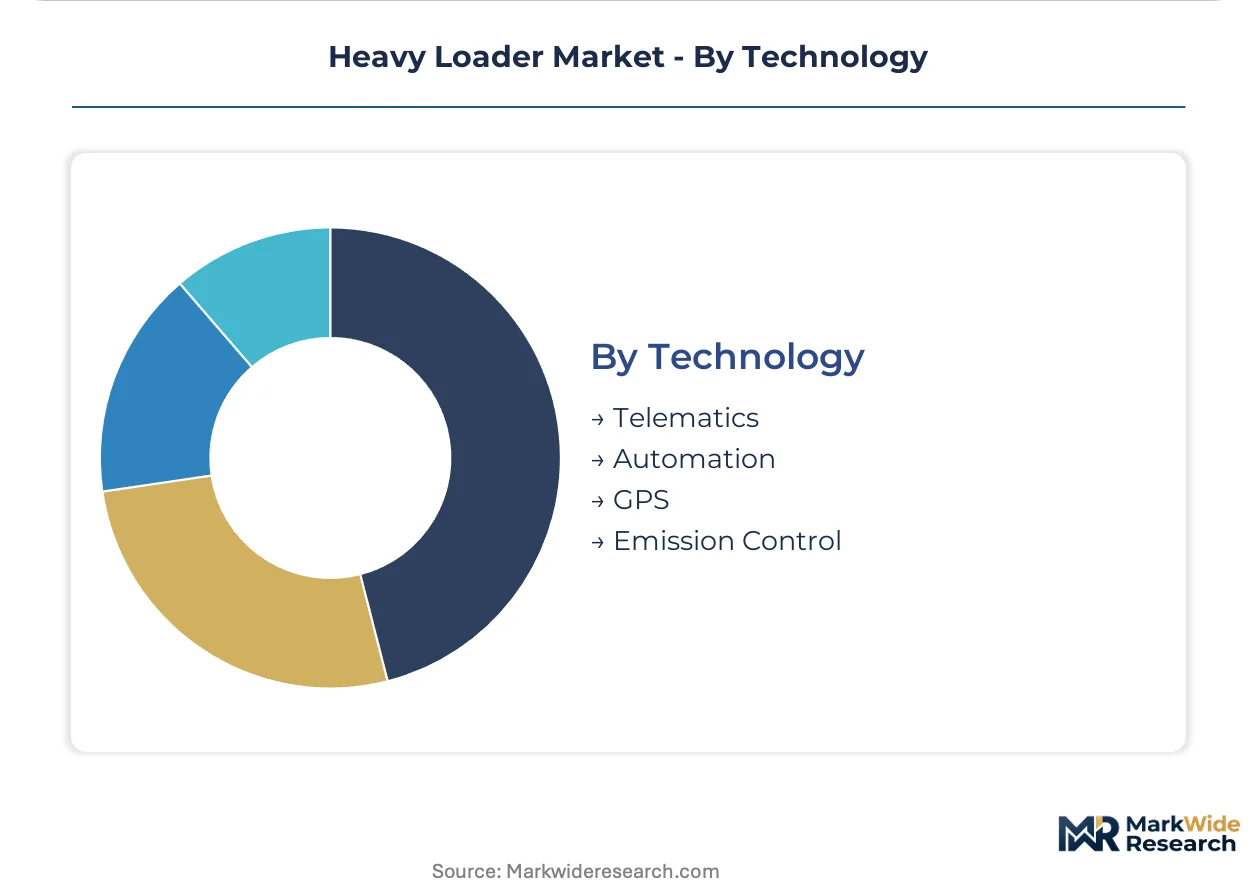
Technology:
Modular technology stacks are becoming primary differentiation vectors as mechanical performance converges across OEM platforms.
- Telematics:Cellular and satellite-connected fleet management systems enable predictive maintenance and productivity optimization. North American copper operations in Arizona are restructuring dealer relationships around real-time diagnostics and guaranteed availability contracts.
- Automation:Semi-autonomous and fully autonomous control systems integrate with haul truck fleets for unified site workflows. Komatsu's autonomous haulage networks in Australian iron ore operations are extending coordination to loading equipment.
- GPS:Satellite-guided grading and payload verification systems reduce rework and material variance in precision earthmoving applications.
- Emission Control:Selective catalytic reduction, diesel particulate filters, and exhaust gas recirculation systems address EPA, EU, and China MEE regulatory thresholds.
Telematics delivers immediate operational returns; automation promises the steepest long-term productivity gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia deploys the heaviest loader fleets for iron ore extraction, whereas Chile concentrates investment on lithium-capable configurations for Atacama operations. Mining contractors in both jurisdictions face divergent infrastructure constraints that shape equipment specification priorities.
Australia
Pilbara Basin iron ore miners operate 24-hour extraction cycles demanding maximum bucket capacity and autonomous haulage compatibility. The country's national resources regulator enforces strict mine safety standards that accelerate technology-anchored fleet replacement. Queensland's Bowen Basin coal operations are retrofitting existing diesel platforms with telematics modules to maintain compliance visibility.
Chile
State-owned Codelco and private lithium extractors in the Atacama are expanding loader fleets to meet battery-grade mineral export targets. Chile's environmental ministry enforces emission monitoring across high-altitude mining districts where engine performance degrades. Antofagasta Region contractors are trialing electric configurations for sulfuric acid plant material handling where ventilation constraints favor zero-emission equipment.
China
Western province infrastructure corridors in Sichuan and Xinjiang require high-capacity earthmoving equipment for tunneling and embankment construction. China's Ministry of Ecology and Environment enforces MEE emission standards that restrict non-compliant equipment imports and accelerate domestic electric platform development. Chengdu-based contractors are deploying state-financed loader fleets for high-speed rail extensions into Tibetan autonomous regions.
Germany
Underground mining operations in North Rhine-Westphalia face EU Stage V compliance deadlines that compress replacement cycles for diesel-powered loaders. Germany's Federal Motor Transport Authority certifies aftertreatment systems across multiple regulatory regimes simultaneously. Ruhr Valley quarry operators are installing depot fast-charging infrastructure to support electric loader deployment ahead of diesel phase-out timelines.
United States
Arizona copper operations and Minnesota iron ore miners restructure dealer relationships around predictive maintenance algorithms and guaranteed availability contracts. EPA Tier 4 Final enforcement accelerates replacement cycles for legacy diesel fleets in surface quarry operations. Phoenix-area mining contractors are consolidating fleet telematics data to negotiate subscription-based uptime guarantees with equipment distributors.
Heavy Loader Market Competitive Landscape
Top-tier vendors anchor premium technology integration, while mid-scale fabricators compete on regional service density and fleet standardization. The vendor base stratifies across three tiers: full-line autonomous-haulage integrators, regional diesel specialists, and emerging electric-platform challengers. Strategic archetypes include technology-anchored solution providers, scale-driven commodity producers, and niche application specialists. Dominant competitive moves encompass autonomous system licensing partnerships and backward integration into battery powertrain manufacturing.
Among Japanese and Swedish heavy equipment manufacturers, Komatsu Ltd. and Volvo Construction Equipment exemplify the autonomous-haulage integrator archetype through unified loader-truck coordination capabilities. Caterpillar Inc. anchors the North American premium service tier through dealer-network restructuring around data monetization. Chinese fabricators XCMG Group and Sany Heavy Industry Co., Ltd. occupy positions within the scale-driven electric-platform segment, leveraging domestic battery supply chain proximity for cost positioning.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| Volvo Construction Equipment |
| Hitachi Construction Machinery Co., Ltd. |
| XCMG Group |
| Sany Heavy Industry Co., Ltd. |
| Liebherr Group |
| John Deere |
| HD Hyundai |
| Others |
Value Network & Pricing Analysis
Battery-electric drivetrain integration is compressing power electronics costs while concentrating supplier relationships around high-voltage component specialists in China and South Korea. This technology shift simultaneously reduces per-unit manufacturing complexity and reshapes procurement leverage toward battery cell producers.
Pricing Analysis
Capacity additions in China are reshaping price floors for electric heavy loaders as domestic OEMs leverage captive battery supply chains. Three-tier pricing structure across premium autonomous-integrated, standard telematics-enabled, and economy mechanical-only levels stratifies the market. Cost compression in the standard tier is intensifying because European Stage V compliance adds aftertreatment expense without commensurate performance gains. Mining companies show least price sensitivity due to uptime guarantee contracts, while small contractors exhibit highest sensitivity to upfront capital outlay.
Supply Chain Analysis
China's MEE emission standards and domestic-content mandates are reshaping sourcing patterns, forcing foreign OEMs to localize battery pack and motor controller production. Component supply draws from China for lithium-ion cells, Germany for precision hydraulics, and Japan for autonomous control modules. Single-source vulnerability concentrates in high-density battery chemistry suppliers. Distribution runs through OEM-authorized dealer networks with parts depots positioned near Pilbara Basin, Atacama, and North Rhine-Westphalia mining clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in heavy loaders rests on electrification-driven service revenue capture and autonomous-system premium tiering. Battery cost curves and subscription-based uptime contracts shift value capture from hardware sales toward recurring service streams.
For Market Incumbents: Deepen backward integration into battery powertrain manufacturing to defend against Chinese electric-platform challengers leveraging domestic cell supply chains. Anchor dealer network restructuring around predictive maintenance data monetization to lock in mining fleet relationships. Prioritize IEC 61508 functional safety certification investment to maintain premium positioning in autonomous haulage integration.
For New Entrants and Emerging Players: Launch via equipment-as-a-service subscription models targeting mid-size contractors in European quarry operations where diesel phase-out deadlines create replacement urgency. Penetrate the German underground mining segment fastest by bundling electric loaders with depot fast-charging infrastructure deployment. Exploit technician scarcity among incumbent service networks by offering OEM-agnostic maintenance training programs.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional diesel specialists facing stranded asset risk from EPA Tier 4 Final and EU Stage V compliance deadlines. Long-term viability favors technology-anchored platforms with demonstrated autonomous haulage integration and captive battery supply arrangements. Watch for inflection in electric loader resale velocity at Ritchie Bros. and IronPlanet auctions as residual value benchmarks for secondary market confidence.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Manufacturing | Captive cell supply secures cost positioning against Chinese OEMs leveraging domestic lithium refining. |
| Autonomous Haulage System Licensing | Komatsu's unified loader-truck coordination patents create recurring royalty streams from mining fleet operators. |
| Dealer Network Data Monetization | Caterpillar's predictive maintenance subscriptions restructure parts inventory around algorithmic demand forecasting. |
| Depot Fast-Charging Infrastructure Deployment | Ruhr Valley quarry operators bundle charging capex with electric loader procurement to accelerate diesel phase-out. |
| Secondary Market Residual Value Certification | ISO 50001 energy management compliance emerges as auction pricing determinant for used equipment. |
Research Methodology
Coverage spans Australia, Chile, China, Germany, and the United States, with primary inputs from each mining jurisdiction triangulated against secondary validation. Interviews with maintenance directors at Pilbara Basin iron ore operations, procurement leads at Chilean lithium extractors, and aftermarket service heads at North American dealer networks informed demand-side assumptions. Secondary sources include EPA Tier 4 Final enforcement records, EU Stage V homologation databases, China's MEE emission standard filings, and customs data on heavy equipment trade flows. Bottom-up unit demand estimates and top-down market sizing reconvene through iterative reconciliation.
Rate-of-change decomposition separates volume growth from mix-shift effects across the projection horizon. Segmentation dimensions modeled include powertrain configuration, application intensity, end-user fleet sophistication, and technology module penetration. CAGRs derive from logistic adoption curves for electric platforms and autonomous systems, calibrated against historical diesel replacement cycles and regulatory compliance timelines. Industry-specific inputs incorporate battery energy density improvement trajectories and on-site charging infrastructure deployment schedules at European quarry operations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium price volatility and grid reliability constraints at remote mining sites. Assumptions reflect current regulatory enforcement intensity and technology cost curves, with revision triggers including accelerated diesel phase-out mandates or breakthrough solid-state battery commercialization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Shaft Shredder Market
Material Handling Equipment
Level Loader Market
Material Handling Equipment
Industrial Piggable Wye Fitting Market
Material Handling Equipment
Industrial Counterweights Market
Material Handling Equipment
Belt Scales Market
Material Handling Equipment
US and Mexico Metal Stamping Market
Material Handling Equipment
Helical Gear Market
Material Handling Equipment
Carry Deck Crane Market
Material Handling Equipment
North America Utility Locator Market
Material Handling Equipment
Global Rolling Mill Rolls Market
Material Handling Equipment
Clinching Machines Market
Material Handling Equipment
Vibrating Feed Conveyors Market
Material Handling Equipment
Air Hoist Market
Material Handling Equipment
Cherry Picker Forklift Market
Material Handling Equipment
Automated Material Handling (AMH) Market
Material Handling Equipment
US Forklift Market