
 Crate Handling Systems Market | 2026-2036
Crate Handling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Crate Handling Systems Market Outlook
Market Context
Modular system bundling is consolidating buyer preference around integrated crate handling platforms that combine conveyance, lifting, and storage functions in single footprints. ULMA Group leverages its Basque manufacturing base to dominate European food-processing installations. Laitram anchors its position through proprietary modular belt technology that sustains throughput in high-moisture environments. Dematic competes on software-integrated orchestration, extending its control over warehouse automation stacks.
Technical Definition and Segment Structure
Crate handling systems comprise electromechanical assemblies engineered to lift, convey, orient, and store standardized reusable containers with payload capacities typically spanning 25 to 50 kilograms and cycle rates calibrated to palletizer or depalletizer speeds. These systems serve primary industrial purposes in hygienic product transfer, order consolidation, and reverse logistics for returnable packaging pools. Automated crate systems capture the fastest expansion as grocery chains and e-commerce suppliers replace manual palletizing with robotic depalletizing cells. Hydraulic systems retain margin concentration in heavy-load dairy and beverage applications where pneumatic alternatives lack force density. Electric systems displace legacy pneumatic architectures in retail distribution centers seeking energy recovery and reduced compressor infrastructure.
Regulatory Environment
The EU Machinery Directive mandates conformity assessment for automated crate systems deployed in European food processing, while ISO 12100 safety standards govern risk reduction in robotic crate handling cells. OSHA lockout/tagout regulations shape maintenance protocol design for US warehousing installations, and FDA food contact material requirements constrain polymer selection in crate surfaces for pharmaceutical and nutritional applications. Stakeholders must monitor evolving CE marking scope under the EU's proposed machinery regulation revision and calibrate R&D roadmaps against anticipated energy efficiency thresholds in German Blue Angel certification.
Market Dynamics
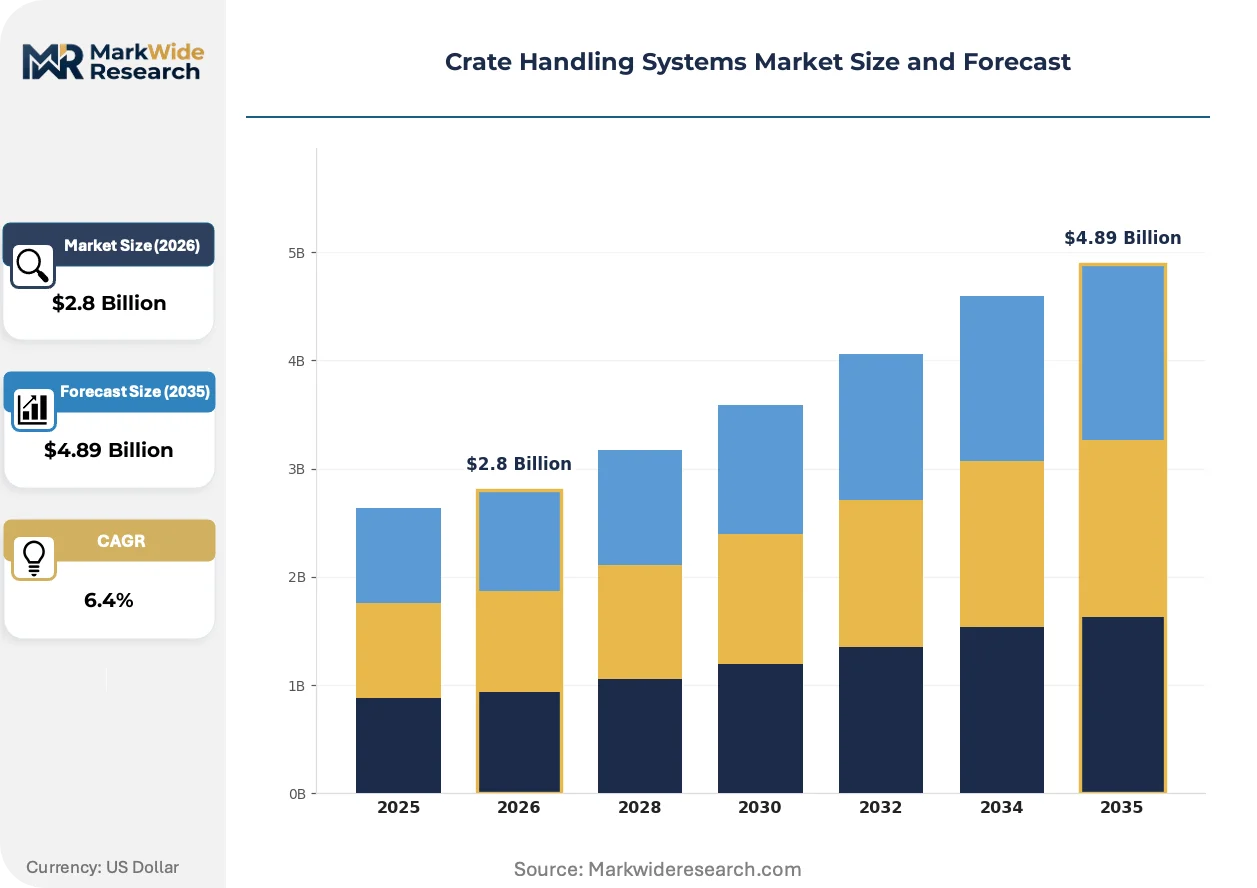
Automated crate handling infrastructure is consolidating around electromechanical architectures that eliminate pneumatic dependencies, compressing total cost of ownership and accelerating replacement cycles in high-throughput distribution environments.
Growth Catalysts
- EU Machinery Directive compliance mandates:Food processors across Germany, France, and Italy must retrofit legacy pneumatic systems with certified automated alternatives, forcing capital deployment into integrated crate handling platforms.
- E-commerce fulfillment velocity targets:Grocery chains and third-party logistics operators are replacing manual palletizing with robotic depalletizing cells to meet same-day delivery service level agreements.
- Energy recovery architectures:Electric servo-driven crate conveyors with regenerative braking are capturing preference in retail distribution centers seeking to reduce compressor infrastructure and electricity baseload.
Market Restraints
- Stainless steel input cost volatility:Hygienic crate handling systems rely on food-grade 304 and 316 stainless steel, exposing equipment margins to nickel and chromium price swings on the London Metal Exchange.
- Control system supplier concentration:Proprietary PLC and safety relay architectures from German and Japanese automation vendors create single-source dependencies for system integrators.
- Hydraulic force density ceiling:Electric linear actuators lack the force density required for heavy-load dairy applications above 50 kilograms, preserving legacy hydraulic maintenance burdens.
Strategic Opportunities
- Indian food processing infrastructure:Cold chain expansion under FSSAI modernization directives is creating first-mover advantage for crate handling vendors establishing localized assembly and service networks.
- Pharmaceutical serialization integration:EU Falsified Medicines Directive track-and-trace requirements are opening specification windows for crate systems with embedded RFID authentication and automated verification.
- Modular belt and cobot convergence:Collaborative robot arms mounted on adaptive modular conveyors are enabling mixed-SKU crate handling without fixed cell reconfiguration downtime.
Industry Challenges
- Functional safety engineer scarcity:ISO 13849 and IEC 62061 certification requirements for robotic crate cells exceed the supply of qualified safety system designers in European automation markets.
- Legacy warehouse management system integration:Proprietary communication protocols from 1990s-era WMS platforms require expensive middleware development for real-time crate tracking orchestration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crate Handling Systems Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Crate Handlers, Automated Crate Systems, Crate Lifts, Crate Storage Solutions Application: Food Processing, Retail, Warehousing, Logistics End User: Manufacturers, Distribution Centers, Grocery Stores, E-Commerce Suppliers Technology: Hydraulic Systems, Pneumatic Systems, Electric Systems, Robotics |
| Companies Covered | ULMA Group, Laitram, Crating Technologies, REB Storage Systems, Timber Creek Resource, Rentacrate, PHS Teacrate, Unifortes, Dematic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crate Handling Systems Market Strategic Shifts
Electromechanical architectures are displacing pneumatic and hydraulic alternatives across crate handling applications, while regulatory pressure on energy efficiency and food safety accelerates equipment refresh cycles.
Permanent magnet synchronous motors paired with variable frequency drives are electrifying crate conveyor segments previously served by compressed air actuators. Retail distribution centers in the Netherlands and Belgium are retrofitting pneumatic lift stations with servo-electric alternatives to capture regenerative energy and eliminate compressor maintenance. This electrification is compressing the payback period for automation investments and marginalizing pneumatic system vendors in medium-load applications.
REACH restrictions on per- and polyfluoroalkyl substances are constraining polymer selection for crate contact surfaces in pharmaceutical and nutritional applications. Equipment manufacturers must validate alternative food-grade materials against FDA 21 CFR and EFSA migration limits before European market entry. Pharmaceutical crate handling installations in Germany and Switzerland are experiencing elongated procurement timelines as material certification documentation requirements expand.
Outcome-based maintenance contracts are displacing traditional break-fix service arrangements in high-availability grocery distribution environments. System integrators are bundling predictive analytics subscriptions with crate handling installations, transferring uptime risk from operator to vendor. This service model pivot is most visible in UK and Nordic retail chains where labor cost inflation has compressed in-house maintenance staffing.
Crate Handling Systems Market Segmentation
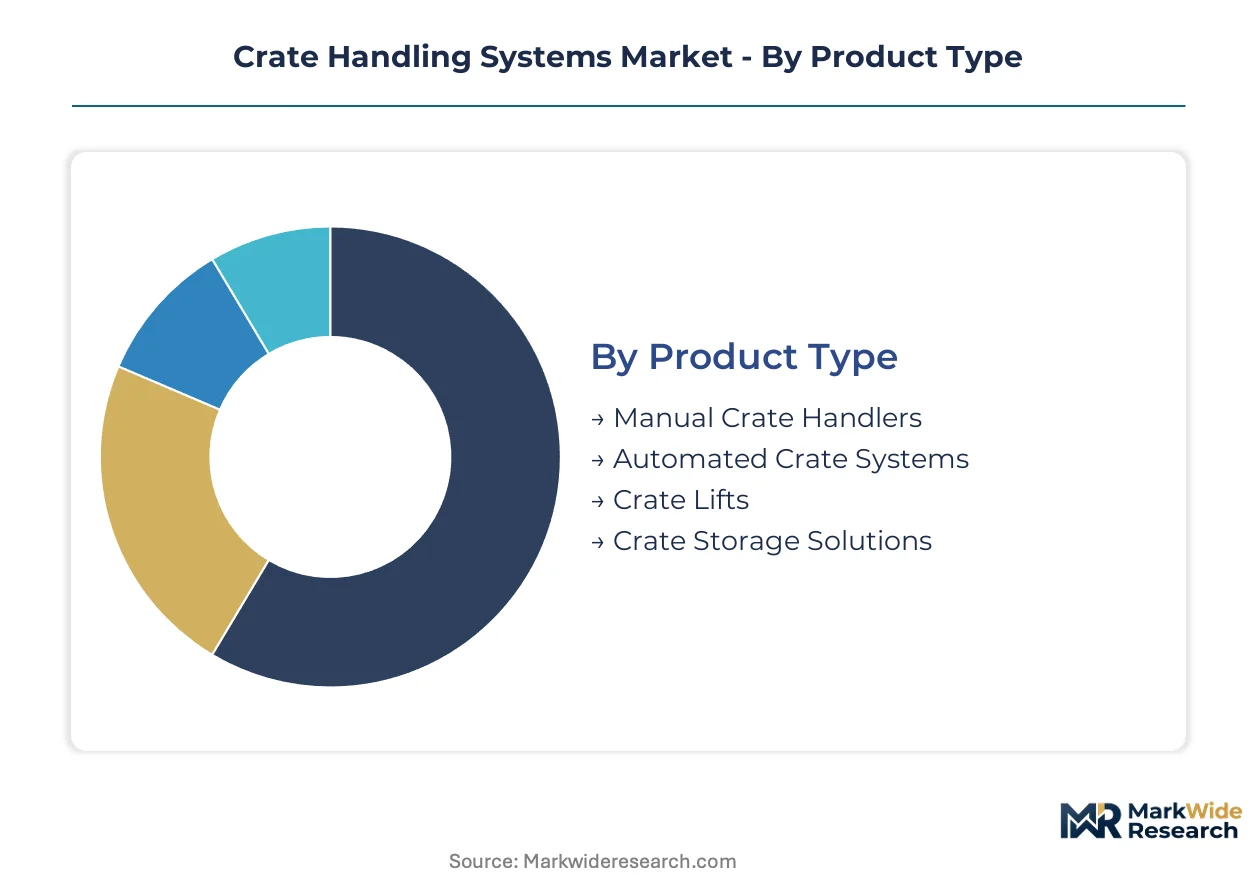
Crate handling systems fragment across four critical dimensions that determine procurement priorities and vendor selection criteria. Product type and technology choices dominate capital allocation decisions, while application context and end-user scale shape integration complexity and service requirements.
Product Type:
Buyer differentiation centers on throughput velocity requirements and labor cost exposure in their operations.
- Automated Crate Systems:Robotic depalletizing cells with vision-guided articulation handle mixed-SKU flows at cycle rates matching high-velocity e-commerce fulfillment targets. Grocery chains in Germany and the Netherlands deploy these to meet same-day delivery SLAs while compressing labor headcount.
- Crate Storage Solutions:Automated storage and retrieval systems with shuttle-based densification achieve vertical space utilization above 85% in ambient and chilled environments. Food processors in Italy prioritize these for FEFO inventory rotation compliance under EU hygiene regulations.
- Manual Crate Handlers:Ergonomic lift-assist devices with counterbalanced articulation reduce musculoskeletal injury risk in low-volume operations.
- Crate Lifts:Vertical reciprocating conveyors bridge mezzanine levels in retrofit warehouse environments where floor loading constraints prohibit pit-mounted alternatives.
Volume sits with automated crate systems; growth tilts toward crate storage solutions.
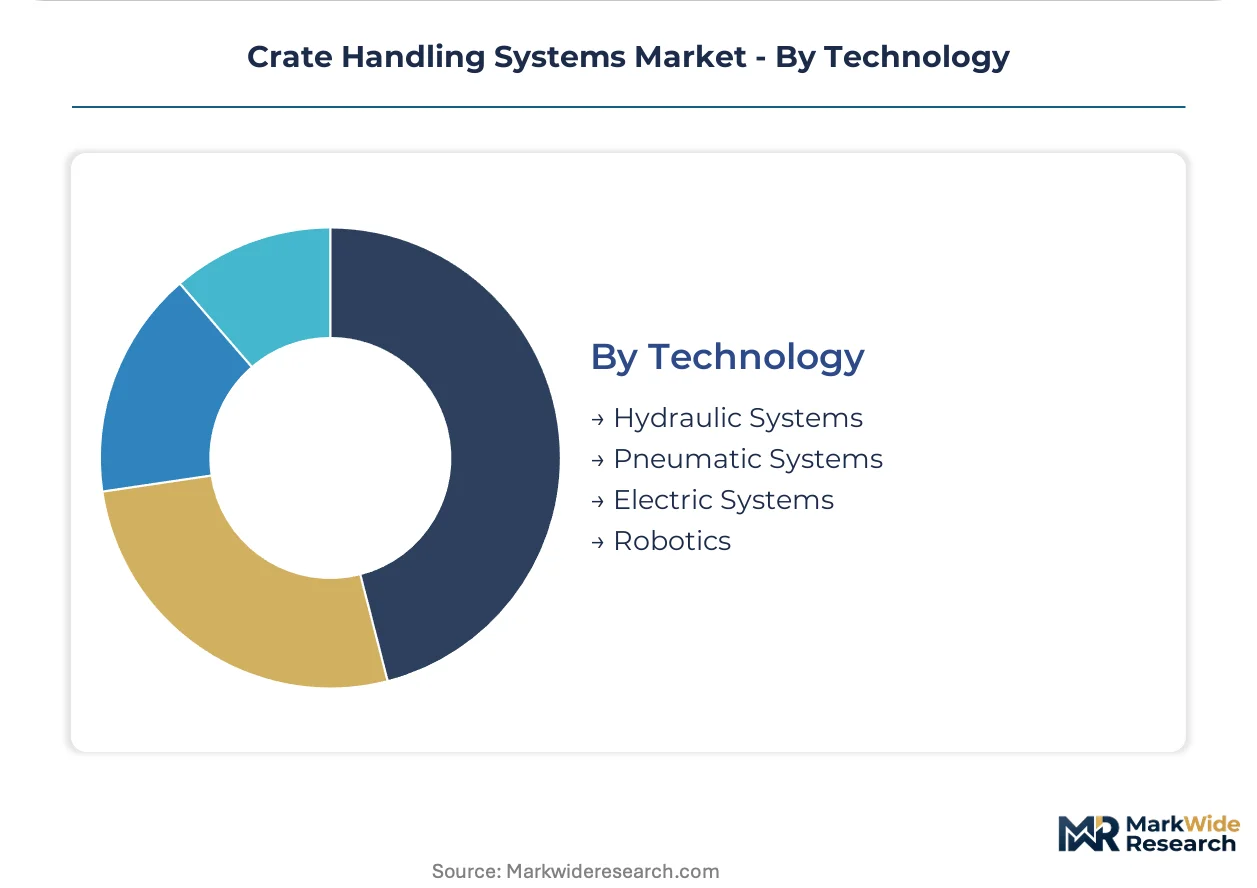
Technology:
Architecture selection hinges on force density requirements, energy recovery priorities, and maintenance staffing availability.
- Electric Systems:Permanent magnet synchronous motors with regenerative braking eliminate compressor infrastructure and capture kinetic energy during deceleration cycles. Retail distribution centers in Belgium and the Netherlands retrofit pneumatic stations with servo-electric alternatives to reduce electricity baseload.
- Robotics:Collaborative arms with adaptive grippers handle variable crate geometries without mechanical changeover. UK grocery chains deploy these for mixed-SKU order consolidation where fixed automation cannot accommodate promotional packaging variability.
- Hydraulic Systems:High-pressure accumulators deliver force density above 50 kilograms for dairy block handling where electric linear actuators remain undersized.
- Pneumatic Systems:Compressed air actuators persist in legacy installations with sunk infrastructure costs, though new procurement favors electrification.
Electric systems command the largest installed base; robotics exhibits the steepest expansion trajectory.
Application:
Hygiene certification intensity and throughput predictability separate procurement specifications across use cases.
- Food Processing:Stainless steel 316 construction with IP69K washdown ratings satisfies EU Machinery Directive and FDA food contact requirements. German meat and dairy clusters drive specification rigor around CIP compatibility and allergen segregation protocols.
- Warehousing:Modular belt conveyors with accumulation zones buffer inbound flow variability from supplier delivery windows. Third-party logistics operators in France prioritize these for multi-tenant facilities serving fragmented shipper bases.
- Retail:Compact footprint designs fit existing backroom constraints in urban grocery formats with limited dock door access.
- Logistics:High-speed diverters and merge configurations sort returnable packaging pools for reverse logistics networks.
Food processing absorbs the heaviest investment intensity; warehousing shows the fastest share gain.
End User:
Capital availability and in-house technical capability determine preference for integrated platforms versus modular point solutions.
- E-Commerce Suppliers:Automated crate handling infrastructure scales with fulfillment center footprint expansion and SKU proliferation. These buyers prioritize software-integrated orchestration with warehouse management systems for real-time inventory visibility.
- Distribution Centers:Multi-channel operators require flexible reconfiguration capabilities to accommodate seasonal demand swings and channel mix shifts.
- Manufacturers:Captive production lines favor fixed automation with dedicated tooling optimized for single-SKU throughput maximization.
- Grocery Stores:Limited capital budgets and space constraints favor manual handling equipment or compact semi-automated solutions.
E-commerce suppliers lead absolute spending; distribution centers demonstrate the most rapid technology refresh rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment production clusters in Germany and the Netherlands supply automated crate handling systems to consumption markets across Western Europe and North America. Asia-Pacific buyers rely on imported European technology for food-grade installations while building local assembly capacity.
Germany
Automotive and food processing clusters in Bavaria and Baden-Württemberg drive specification intensity for stainless steel crate handling infrastructure. The EU Machinery Directive mandates conformity assessment for automated systems deployed in meat and dairy facilities. Stuttgart-based integrators serve OEM production lines requiring IP69K washdown ratings.
United States
E-commerce fulfillment center expansion in California and Texas accelerates robotic depalletizing procurement. OSHA lockout/tagout regulations shape maintenance protocol design for warehouse installations. Chicago-area third-party logistics operators deploy electric servo-driven conveyors to eliminate compressor infrastructure.
Netherlands
Retail distribution networks in Rotterdam and Amsterdam prioritize energy recovery architectures with regenerative braking. REACH restrictions on per- and polyfluoroalkyl substances constrain polymer selection for pharmaceutical crate surfaces. Dutch grocery chains retrofit pneumatic stations with servo-electric alternatives to reduce electricity baseload.
India
Cold chain expansion under FSSAI modernization directives creates specification windows for hygienic crate handling in Maharashtra and Gujarat. The country's national food safety regulator mandates equipment certification for processed food exports. Bangalore-based cold storage operators pilot automated storage and retrieval systems for FEFO inventory rotation.
United Kingdom
Outcome-based maintenance contracts displace break-fix arrangements in high-availability grocery distribution. UK retail chains compress in-house maintenance staffing as labor cost inflation accelerates. London-area logistics operators deploy collaborative robot arms on adaptive modular conveyors for mixed-SKU handling.
Crate Handling Systems Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the crate handling systems market. The vendor base organizes into three tiers: integrated automation platforms, modular component suppliers, and regional fabrication houses. Consolidation pressures favor players with software-integrated orchestration capabilities and captive service networks. Dominant competitive moves include strategic partnerships for predictive analytics bundling and geographic expansion into Indian food processing corridors.
Within the European specialist tier, ULMA Group leverages its Basque manufacturing base to anchor food-processing installations across the continent. Laitram occupies a position exemplifying proprietary modular belt technology for high-moisture environments. Dematic represents the software-integrated orchestration archetype, extending control over warehouse automation stacks through control system integration.
| Leading Market Players |
|---|
| ULMA Group |
| Laitram |
| Crating Technologies |
| REB Storage Systems |
| Timber Creek Resource |
| Rentacrate |
| PHS Teacrate |
| Unifortes |
| Dematic |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists concentrated in Germany's Baden-Württemberg and Bavaria regions exercise disciplined pricing power through captive stainless steel fabrication capabilities and long-term service contract bundling. Their ownership structure insulates margin targets from quarterly earnings pressure while enabling selective investment in EU Machinery Directive certification that smaller competitors cannot replicate.
Pricing Analysis
Margin tightening in standard electric systems reflects nickel and chromium price volatility on the London Metal Exchange pressuring food-grade 304 and 316 stainless steel input costs. Three-tier pricing structure across premium certified, standard compliant, and economy non-washdown levels separates buyers by hygiene certification intensity and after-sales service bundling. Cost-down pressure accelerates as e-commerce fulfillment centers consolidate procurement volumes and demand outcome-based maintenance contracts. Grocery chains demonstrate highest price sensitivity due to thin operating margins, while pharmaceutical manufacturers prioritize certification tier over unit cost.
Supply Chain Analysis
CE marking and FDA food contact material qualifications gate European and North American market entry, elongating procurement timelines for polymer component sourcing. Equipment manufacturing concentrates in Germany, the Netherlands, and Italy, drawing from stainless steel mills in Spain and polymer suppliers in Belgium. Single-source vulnerability persists around proprietary PLC architectures from German and Japanese automation vendors. Distribution runs through system integrator networks with regional service footprints rather than direct OEM-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
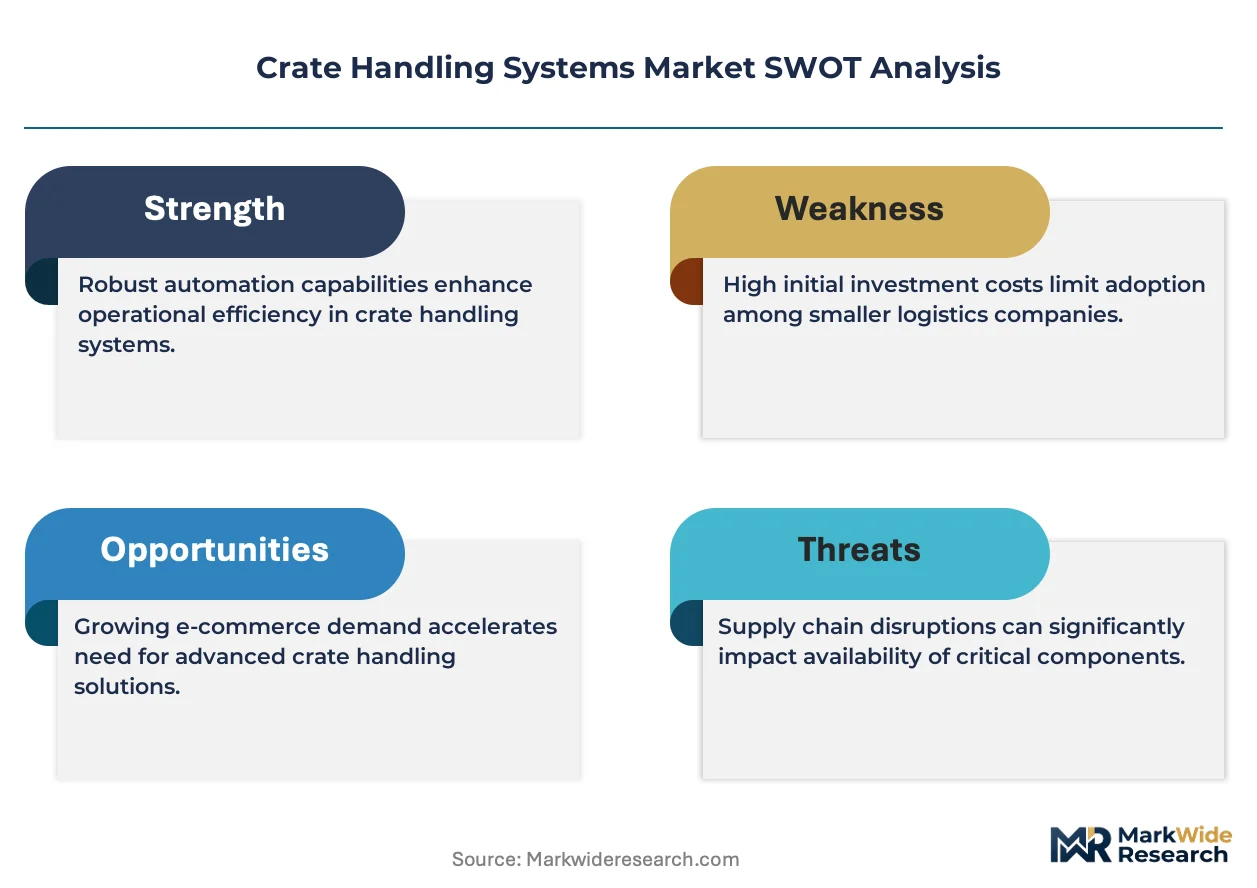
The crate handling systems market functions as a cost-of-compliance story where EU Machinery Directive conformity assessment creates a barrier-to-entry moat for players with certified automated platforms and in-house safety engineering capabilities.
For Market Incumbents: Lock in service contract renewals through predictive analytics bundling that transfers uptime risk from grocery distribution operators. Deepen backward integration into stainless steel component fabrication to defend margins against London Metal Exchange volatility. Prioritize ISO 13849 safety system certification investment to exploit functional safety engineer scarcity that constrains competitor expansion. For New Entrants and Emerging Players: Enter via Indian food processing corridors where FSSAI modernization directives create specification windows without entrenched incumbent presence. Target Maharashtra and Gujarat cold storage operators piloting automated storage and retrieval systems for FEFO inventory rotation. Lead with localized assembly and service networks rather than imported European equipment positioning. For Investors and Strategic Acquirers: Distressed-cycle entries favor modular belt technology specialists with proprietary high-moisture environment IP in the Netherlands and Belgium. Long-term viability hinges on software-integrated orchestration capabilities that extend control over warehouse automation stacks. Watch for inflection in pharmaceutical serialization integration specifications under EU Falsified Medicines Directive track-and-trace requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Fabrication | Captive 304 and 316 production insulates margins against nickel price volatility from LME swings. |
| Predictive Analytics Subscription Bundling | Outcome-based maintenance contracts transfer uptime risk from UK grocery chains to equipment vendors. |
| Indian Assembly and Service Network Expansion | FSSAI modernization directives in Maharashtra create first-mover advantage for localized production. |
| RFID Authentication Module Integration | EU Falsified Medicines Directive compliance opens pharmaceutical crate handling specification windows. |
| Collaborative Robot Arm Convergence | Cobot-mounted adaptive modular conveyors enable mixed-SKU handling without fixed cell reconfiguration downtime. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with plant engineers, maintenance directors at food processing facilities, OEM procurement teams, and aftermarket service heads validated equipment specification trends and procurement timelines. Secondary sources included EU Machinery Directive implementation reports, FDA food contact material databases, and stainless steel trade flow statistics. Bottom-up equipment shipment data and top-down industrial automation spending estimates were triangulated to calibrate market sizing.
Data-stream reconciliation across product type, technology architecture, application hygiene tier, and end-user scale dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from regression analysis against industrial capital expenditure cycles and e-commerce fulfillment center buildout trajectories. Forecast inputs incorporated EU energy efficiency threshold proposals and German Blue Angel certification roadmap indicators.
Forecast precision tightens around the base case; tail outcomes carry wider variance under nickel price volatility spikes or prolonged functional safety engineer supply constraints. Model outputs reflect assumptions around regulatory implementation timelines and automation substitution elasticity in labor markets. A model refresh is warranted upon material change in EU machinery regulation revision scope or FSSAI enforcement intensity in Indian food processing corridors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Material Handling Equipment Telematics Market
Material Handling Equipment
Pug Mill Mixers Market
Material Handling Equipment
Industrial Bag Dust Filter Market
Material Handling Equipment
Pipe Wipers Market
Material Handling Equipment
Wagon Tipplers Market
Material Handling Equipment
Trash Chute Market
Material Handling Equipment
Wire Rope Sling Market
Material Handling Equipment
Can Racks Market
Material Handling Equipment
Air Hoist Market
Material Handling Equipment
Vibrating Screen Market
Material Handling Equipment
Forklift Rental Market
Material Handling Equipment
Cable Conduit Market
Material Handling Equipment
Level Loader Market
Material Handling Equipment
Manual Lifting Mobile Light Tower Market
Material Handling Equipment
Global Conveyors Market
Material Handling Equipment
Shiplifts & Transfer Systems Market