
 Global Bucket Loader Market | 2026-2036
Global Bucket Loader Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bucket Loader Market Analysis
Buyer concentration in mining and large-scale construction is broadening as mid-tier contractors and regional rental fleets expand procurement volumes beyond traditional national accounts. Caterpillar Inc. leverages its dealer network density to sustain aftermarket revenue streams across remote extraction sites. Komatsu Ltd. anchors its position through integrated machine control and telematics platforms that reduce operator skill variance. Volvo Construction Equipment differentiates via articulated hauler-to-loader matching systems that optimize fleet fuel efficiency in quarry environments.
A bucket loader is a wheeled or tracked earthmoving machine equipped with a front-mounted hydraulic bucket for lifting, loading, and transporting loose materials such as aggregate, soil, or ore; operating weights range from compact 3-ton skid steer units to 50-ton mining-class wheel loaders with breakout forces exceeding 500 kN. The equipment serves primary material handling roles in construction site preparation, mineral extraction, agricultural bulk transfer, and municipal waste processing. Wheel loaders occupy the dominant revenue position due to their versatility across surface applications and established resale liquidity. Electric and hybrid technology segments are gaining fastest penetration in urban construction zones where emission restrictions limit diesel operation hours. Hydraulic systems remain the mature default for mining and heavy infrastructure buyers prioritizing field-service simplicity over energy efficiency gains.
The US EPA Tier 4 Final and European Stage V standards enforce particulate matter and NOx limits that elevate engine costs and filter maintenance burdens, reshaping OEM R&D allocation toward alternative powertrains. China's MEE enforces national emission zones in the Beijing-Tianjin-Hebei corridor and Yangtze River Delta that restrict older diesel equipment from project bidding, accelerating domestic replacement cycles. Stakeholders must monitor how battery energy density improvements and charging infrastructure deployment alter total cost of ownership calculations against diesel baseline economics in high-utilization applications.
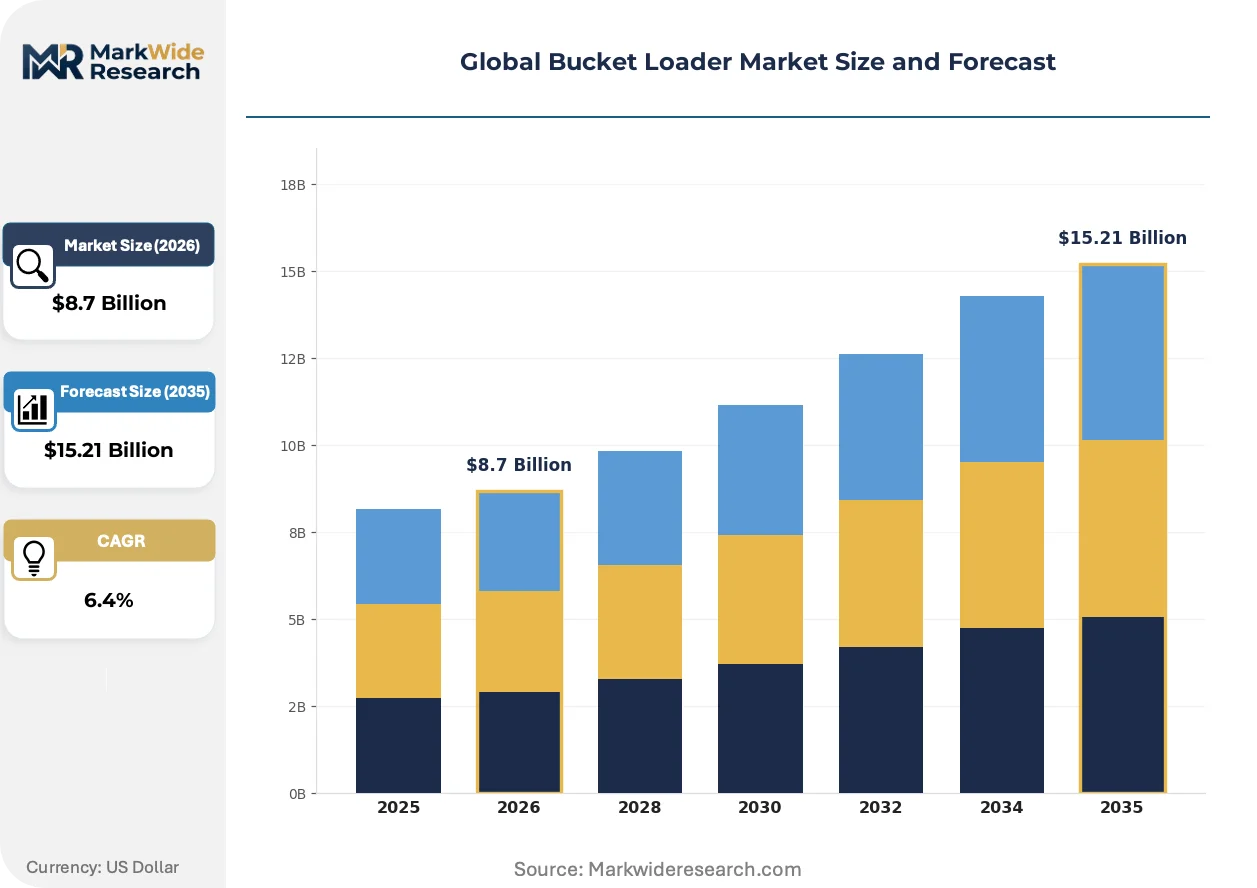
Market Dynamics
The US EPA Tier 4 Final and European Stage V emission standards are compressing diesel engine architectures while battery-hydraulic hybrids capture early adoption in urban construction zones where operating hour restrictions apply.
Growth Catalysts
- China's MEE emission zones:The Beijing-Tianjin-Hebei corridor and Yangtze River Delta restrictions accelerate replacement cycles as older diesel equipment faces project bidding exclusion.
- Underground mining depth extension:Chilean and Australian ore extraction operations drive fleet orders for high-capacity wheel loaders with breakout forces exceeding 500 kN.
- Telematics-integrated machine control:Operator skill variance reduction through real-time payload optimization and fuel monitoring expands addressable contractor segments.
Market Restraints
- High-alloy steel price volatility:Bucket and boom fabrication costs fluctuate with nickel and manganese supply disruptions from concentrated smelter regions.
- Particulate filter maintenance burden:Stage V after-treatment systems elevate total cost of ownership in high-dust mining environments where regeneration cycles interrupt production.
- Electric infrastructure gap:Battery energy density limitations and charging network absence constrain adoption in remote extraction sites beyond grid reach.
Strategic Opportunities
- India's western infrastructure corridor:State-backed highway and port projects create demand for mid-size wheel loaders in contractor fleets previously served by manual loading.
- CE marking alignment with EU Green Deal:Carbon footprint disclosure requirements favor OEMs with lifecycle emissions documentation for public procurement eligibility.
- Autonomous hauler-to-loader coordination:Convergence of machine vision and fleet management software enables unmanned shift operations in 24-hour quarry environments.
Industry Challenges
- Certification timeline compression:Multiple concurrent emission standards across export markets strain homologation resources and delay product launches.
- Hydraulic technician scarcity:Field service complexity from Tier 4 Final after-treatment integration outpaces vocational training program output in mining regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bucket Loader Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skid Steer Loaders, Wheel Loaders, Track Loaders, Mini Loaders End User: Construction, Agriculture, Mining, Waste Management Technology: Hydraulic, Electric, Fuel Powered, Hybrid Distribution Channel: Direct Sales, Dealers, Online, Retail |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., Volvo Construction Equipment, Deere & Company, JCB, Liebherr Group, Hitachi Construction Machinery, Doosan Infracore, CNH Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bucket Loader Market Emerging Trajectories
Powertrain diversification and connected fleet management are restructuring equipment economics, with alternative propulsion systems penetrating duty cycles previously dominated by diesel-hydraulic architectures.
Battery-electric wheel loaders with onboard fast-charging capability are overtaking diesel equivalents in European urban construction where Stage V zones limit engine runtime. Municipal contractors in Germany and the Netherlands now specify electric units for tunnel and demolition work. The technology is compressing maintenance intervals and reshaping residual value calculations in high-utilization rental fleets.
The EU Green Deal's embodied carbon reporting requirements through CSRD are forcing OEMs to document supply chain emissions from steel forging through end-of-life recycling. Construction equipment lessors in France and Italy now face disclosure obligations that favor suppliers with verified lifecycle data. Mining operators in Sweden and Finland are piloting carbon-accounted procurement criteria that weight manufacturing emissions alongside operating efficiency.
Mid-tier contractors are consolidating equipment purchases through regional rental fleets rather than direct OEM relationships, compressing traditional dealer service revenue models. Australia's eastern states and Canada's Prairie provinces show the fastest channel migration as project-based contractors prioritize balance sheet flexibility over ownership. Fleet management platforms that bundle maintenance, telematics, and uptime guarantees are capturing procurement decisions previously driven by unit price alone.
Global Bucket Loader Market Segmentation
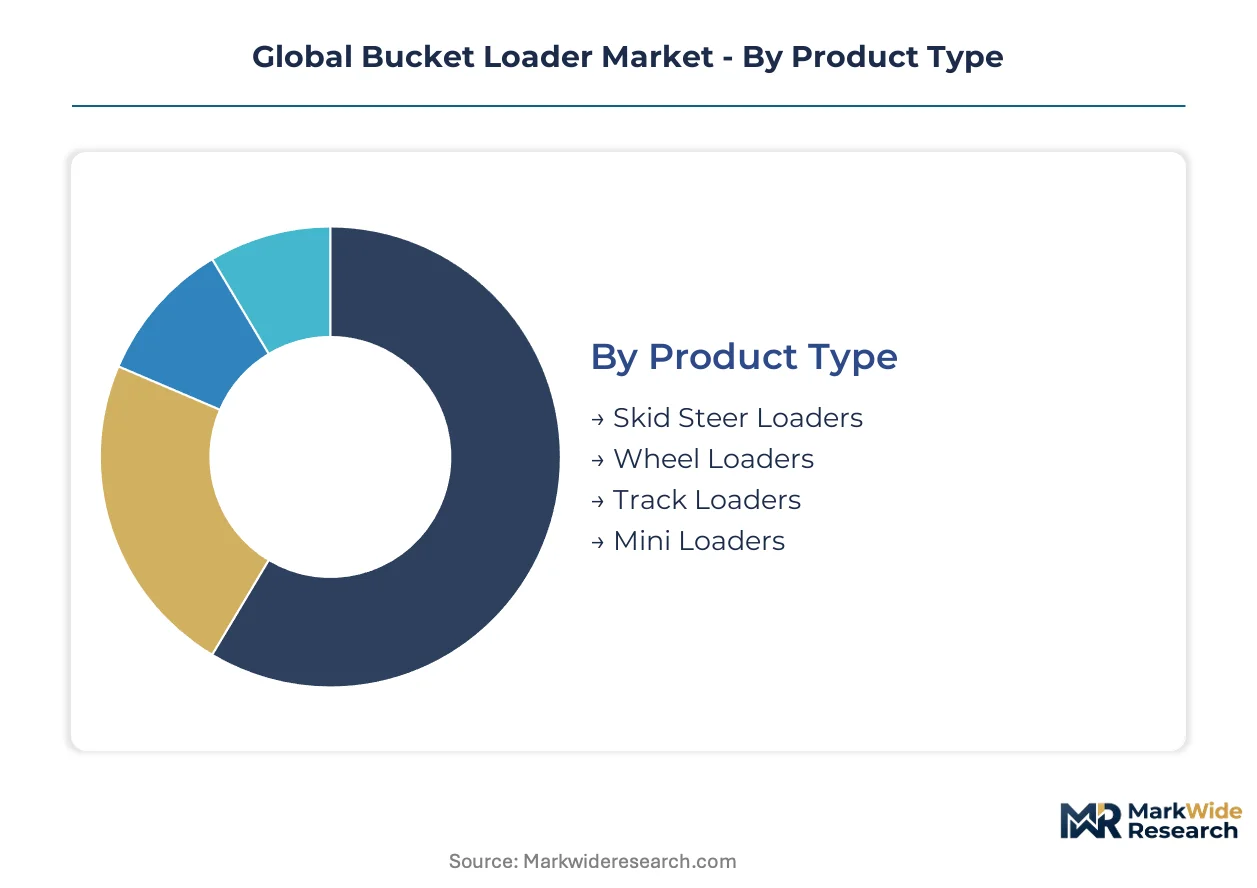
Bucket loader procurement decisions cluster around duty cycle intensity and site access constraints. Capital allocation patterns diverge sharply between mining operators seeking maximum breakout force and municipal contractors prioritizing maneuverability in confined zones.
Product Type:
Wheel loaders demand the heaviest capital commitment due to engine displacement requirements and structural reinforcement for mining-class applications. Skid steer units minimize entry costs but accelerate wear component expenditures in high-cycle rental deployments.
- Wheel Loaders:Articulated chassis designs with operating weights from 10 to 50 tons dominate surface mining and quarry operations. Chilean copper extraction sites in the Atacama Desert specify units with breakout forces exceeding 500 kN for deep ore loading. EPA Tier 4 Final compliance costs concentrate most heavily in this segment.
- Skid Steer Loaders:Compact vertical-lift and radial-lift configurations serve construction site preparation and agricultural material handling. Mid-tier contractors in India's western infrastructure corridor favor these units for balance sheet flexibility on project-based work.
- Track Loaders:Undercarriage systems distribute ground pressure below 4 psi for soft terrain access in wetland remediation and pipeline right-of-way construction.
- Mini Loaders:Sub-3-ton operating weights enable indoor demolition and landscaping applications where transport costs constrain equipment mobility.
Most installed capacity flows through wheel loaders. Expansion is steepest in mini loaders as urban emission zones restrict diesel operation hours.
End User:
Application-specific duty cycles determine maintenance interval economics and residual value trajectories. Mining operators amortize acquisition costs across continuous shift schedules while agricultural users face seasonal utilization constraints.
- Mining:24-hour extraction operations in Western Australia and Chile's Antofagasta region require load-haul-dump cycles exceeding 6,000 hours annually. Breakout force specifications above 400 kN filter supplier eligibility to established OEMs with field service density.
- Construction:Site preparation and aggregate handling in China's western provinces drive fleet turnover as state-backed infrastructure programs expand earthmoving capacity requirements.
- Agriculture:Grain handling and livestock waste management in the US Corn Belt and Brazilian Cerrado favor mid-size wheel loaders with quick-attach versatility for seasonal implements.
- Waste Management:Municipal landfill compaction and recycling material sorting in European urban centers specify sealed undercarriages and corrosion-resistant hydraulic systems.
Mining commands the highest average transaction values. Construction delivers the broadest addressable contractor base across emerging infrastructure corridors.
Technology:
Powertrain selection hinges on energy infrastructure availability and operating hour restrictions. Diesel-hydraulic architectures retain default status where grid access is limited or charging downtime disrupts production schedules.
- Hydraulic:Open-center and load-sensing hydraulic circuits remain the mature standard for mining and heavy infrastructure buyers prioritizing field-service simplicity. Technician training availability and parts commonality sustain preference in remote extraction sites.
- Electric:Battery-powered wheel loaders with onboard fast-charging capability penetrate European urban construction zones where Stage V regulations limit engine runtime. German tunnel contractors and Dutch demolition specialists now specify electric units as default.
- Fuel Powered:Diesel and compressed natural gas engines dominate applications beyond grid reach in Australian iron ore operations and Canadian oil sands development.
- Hybrid:Diesel-electric architectures capture early adoption in quarry environments where regenerative braking from downhill haul cycles offsets fuel consumption.
Hydraulic systems anchor current installed base. Electric powertrains are climbing the fastest as battery energy density improvements compress total cost of ownership gaps.
Distribution Channel:
Channel selection reflects buyer scale and service response requirements. National accounts negotiate direct OEM relationships while regional contractors consolidate through rental fleet intermediaries.
- Direct Sales:Mining houses and national construction aggregates producers negotiate frame contracts with uptime guarantees and embedded telemetry monitoring. Caterpillar's dealer network density sustains aftermarket revenue streams across remote Chilean and Australian extraction sites.
- Dealers:Authorized distribution networks provide field service coverage and residual value support for mid-tier contractors in fragmented construction markets.
- Online:Digital procurement platforms capture parts and attachment transactions previously routed through counter sales.
- Retail:Equipment rental yards and agricultural cooperatives serve small-scale users with short-term availability requirements.
Dealer networks handle the majority of unit transactions. Direct sales channels are expanding most quickly among consolidated mining operators seeking fleet standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile's mining operators expand high-capacity fleet orders as ore extraction deepens, while Australia's Western Australia iron ore belt sustains comparable procurement intensity through 24-hour extraction schedules.
United States
Construction aggregates producers in Texas and Florida drive wheel loader replacement cycles as federal infrastructure spending flows into highway expansion projects. EPA Tier 4 Final enforcement elevates engine costs and particulate filter maintenance burdens, compressing diesel architecture economics. The Permian Basin oilfield services corridor sustains demand for mid-size units in pipeline right-of-way preparation.
China
State-backed infrastructure programs in western provinces require heavy earthmoving capacity for highway and rail corridor development. MEE emission zones in the Beijing-Tianjin-Hebei corridor and Yangtze River Delta restrict older diesel equipment from project bidding, accelerating domestic replacement cycles. Sichuan-Chongqing construction clusters absorb the largest volume of new wheel loader deployments.
Germany
Municipal contractors in the Rhine-Ruhr metropolitan region specify battery-electric wheel loaders for tunnel and demolition work as Stage V zones limit engine runtime. EU Green Deal CSRD disclosure requirements through embodied carbon reporting favor OEMs with verified lifecycle emissions documentation. Bavarian quarry operators pilot autonomous hauler-to-loader coordination in 24-hour extraction environments.
Australia
Western Australia iron ore operations require load-haul-dump cycles exceeding 6,000 hours annually, filtering supplier eligibility to established OEMs with field service density. The country's national emission standards for non-road diesel engines compress fleet turnover timelines in coastal urban construction zones. Queensland coal seam gas development sustains track loader demand for soft terrain pipeline access.
India
State-backed highway and port projects in the western infrastructure corridor create demand for mid-size wheel loaders in contractor fleets previously served by manual loading. BIS certification requirements for construction equipment safety standards elevate entry barriers for imported units. Gujarat and Maharashtra industrial zones concentrate the fastest procurement growth as manufacturing capacity expands.
Global Bucket Loader Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct technology and service vectors. The vendor base clusters around three strategic archetypes: integrated mining equipment houses with global field service networks, construction machinery generalists with articulated hauler matching capabilities, and regional fabricators serving price-sensitive contractor segments. Consolidation pressures concentrate most visibly in telematics-integrated machine control platforms and battery-hydraulic hybrid architectures. Dominant competitive moves include strategic partnerships for charging infrastructure deployment and geographic expansion into India's western infrastructure corridor.
Among diversified mining equipment houses, Caterpillar Inc. and Komatsu Ltd. occupy positions defined by aftermarket density and integrated control platforms respectively. Volvo Construction Equipment exemplifies the construction machinery generalist archetype through fleet optimization systems. These three anchors sit within a broader competitive set where differentiation hinges on emission compliance timing, telematics penetration, and regional service reach rather than unit pricing alone.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| Volvo Construction Equipment |
| Deere & Company |
| JCB |
| Liebherr Group |
| Hitachi Construction Machinery |
| Doosan Infracore |
| CNH Industrial |
| Others |
Supply Flow & Price Mechanics
Battery-hydraulic hybrid powertrain adoption in European urban construction zones simultaneously elevates manufacturing complexity and concentrates sourcing leverage among specialized drivetrain suppliers. OEMs face margin compression from dual certification requirements while Tier 4 Final after-treatment integration forces cost pass-through negotiations with mining fleet operators.
Pricing Analysis
Capacity additions in China's Sichuan-Chongqing manufacturing cluster are reshaping price floors for standard wheel loader configurations. Three-tier pricing structure across premium mining-class, standard construction-grade, and economy skid steer levels stratifies by breakout force certification and telematics bundling. Cost compression in economy tiers intensifies because domestic OEMs compete aggressively on state-backed infrastructure project tenders. Municipal contractors in emission-restricted zones exhibit highest price sensitivity; Australian iron ore operators prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Ocean freight rate volatility from Asia-Pacific to Atlantic basin ports elevates landed cost uncertainty for complete machine imports. Fabrication capacity concentrates in China, Germany, and Japan, with high-alloy steel supply drawing from Australian iron ore and Chilean copper concentrate. Hydraulic pump and valve assemblies rest on German and Japanese component specialists, creating single-source vulnerability for Tier 4 Final engine-integrated systems. Distribution runs through authorized dealer networks with embedded field service capabilities in remote extraction regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on aftermarket service bundling and premium-tier electric powertrain positioning as emission zones proliferate. Telematics-integrated uptime guarantees command pricing power unavailable to transactional unit sellers.
For Market Incumbents: To counter battery-electric specialist entrants in European municipal segments, anchor dealer network density with fast-charging infrastructure partnerships and backward integration into hydraulic component remanufacturing. Prioritize certification investment for EU Green Deal CSRD lifecycle emissions documentation to defend public procurement eligibility. For New Entrants and Emerging Players: Enter via India's western infrastructure corridor where BIS certification barriers filter established OEMs and mid-tier contractors prioritize balance sheet flexibility over brand loyalty. Target rental fleet intermediaries with telematics-embedded maintenance contracts as the primary go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabricators with captive hydraulic system production and established mining field service footprints. Long-term viability centers on electric powertrain transition readiness and charging infrastructure deployment partnerships. Watch battery energy density improvement announcements from Korean and Chinese cell suppliers as the inflection signal for total cost of ownership parity against diesel baselines.| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Battery-electric wheel loader adoption in German tunnel contracts depends on site-level fast-charging deployment. |
| Telematics Platform Integration | Komatsu's payload optimization systems reduce operator skill variance across Chilean copper extraction sites. |
| Backward Integration into Hydraulics | Caterpillar's captive pump and valve production insulates margin from nickel and manganese price swings. |
| CE Marking Alignment with CSRD | EU Green Deal disclosure requirements favor OEMs with verified steel forging through recycling emissions data. |
| Regional Manufacturing Footprint | Volvo's articulated hauler-to-loader matching systems optimize fleet fuel efficiency in Australian quarry environments. |
Methodological Framework
Direct dialogue with mining maintenance directors, construction fleet procurement managers, OEM aftermarket service heads, and hydraulic component distributors grounded qualitative findings in operational reality. Secondary validation drew from EPA engine certification filings, EU Stage V homologation databases, China MEE emission zone announcements, and customs trade records for high-alloy steel imports. Bottom-up unit deployment estimates across Chile, Australia, China, Germany, and India triangulated against top-down OEM revenue segmentation.
Installed base projections and replacement cycle timing across the analysis window reflect equipment utilization intensity, emission regulation phase-in schedules, and infrastructure investment pipeline visibility. Segmentation modeling captured wheel loader, skid steer, track loader, and mini loader product categories against mining, construction, agriculture, and waste management end uses. CAGRs incorporate battery energy density improvement curves, charging infrastructure deployment rates, and diesel-electric total cost of ownership convergence assumptions.
Inputs from OEM production schedules and mining operator fleet expansion announcements were available through the study window; gaps in autonomous machine control adoption timelines introduce uncertainty bands around labor substitution scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Eye and Eye Turnbuckle Market
Material Handling Equipment
Electric Wire Rope Hoist Market
Material Handling Equipment
Outdoor Power Equipment (OPE) Market
Material Handling Equipment
Vertical Lifts Market
Material Handling Equipment
Japan Conveyor Belt Market
Material Handling Equipment
Port Equipment Market
Material Handling Equipment
Cut-To-Length Line Systems Market
Material Handling Equipment
Trash Chute Market
Material Handling Equipment
Surface Contact Wire Rope Market
Material Handling Equipment
Container Handler Market
Material Handling Equipment
Pallet Truck Market
Material Handling Equipment
Global Dewatering Equipment Market
Material Handling Equipment
Conveyor Belt Market
Material Handling Equipment
Australia Forklift Rental Market
Material Handling Equipment
Crate Handling Systems Market
Material Handling Equipment
Rolling Mill Machine Market